
 Global PVC Stabilizer Market | 2026-2036
Global PVC Stabilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Global PVC Stabilizer Market Foresight
Pharmaceutical-grade specification tiers is rotating toward the center of competitive strategy as processors face tighter migration limits in medical tubing and food-contact applications. Baerlocher GmbH leverages its backward integration into metal soap precursors to secure cost positions across European compounding channels. Adeka Corporation anchors its position through specialized liquid stabilizer formulations for high-clarity packaging films. SONGWON Industrial Group differentiates via antioxidant-stabilizer hybrid systems that reduce additive loadings in rigid profiles.
PVC stabilizers are chemical additives—typically metal soaps, organotin compounds, or organic co-stabilizers—blended at 0.5 to 5.0 parts per hundred resin to inhibit thermal degradation during PVC processing at 160 to 210 degrees Celsius, with the primary purpose of preventing hydrogen chloride evolution and color formation that would render extruded or injection-molded parts unusable. Calcium zinc stabilizers now lead volume growth as lead-based systems face phasedowns under REACH and analogous frameworks, while organic stabilizer demand is accelerating fastest in medical and potable-water segments where heavy-metal-free certification commands premium positioning. The pipes and fittings application segment sustains the largest absolute volume base, though wire and cable insulation offers superior margin pools due to electrical property specifications and longer qualification cycles.
The European Chemicals Agency enforces REACH authorization requirements that have eliminated lead-based stabilizers from most consumer-contact PVC in the European Union, while China's Ministry of Ecology and Environment implements GB standards restricting cadmium and specific phthalate co-stabilizers in domestic building products. The US EPA regulates tin-based stabilizer discharge under industrial wastewater permits, shaping formulation choices for domestic compounding operations. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation customization or universal heavy-metal-free platforms offer superior capital efficiency.
Market Dynamics
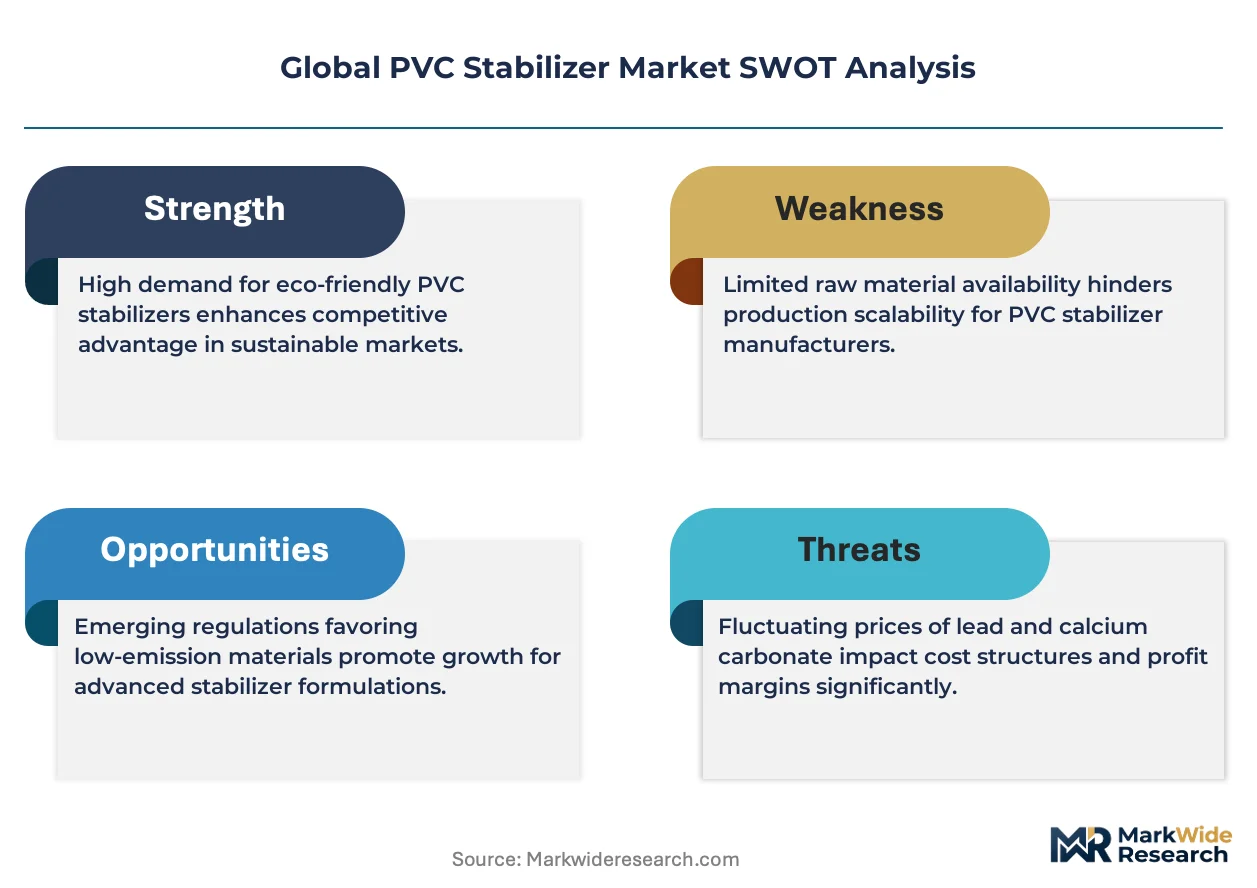
REACH authorization requirements are systematically dismantling lead-based stabilizer platforms across European compounding operations, forcing simultaneous reformulation investments and raw material qualification cycles that compress margin structures for additive suppliers.
Growth Catalysts
- Power grid modernization:Wire and cable insulation specifications are tightening across transmission infrastructure projects in China and India, pulling higher-performance calcium-zinc systems into specification.
- REACH phasedown enforcement:ECHA authorization timelines are eliminating lead-based options from consumer-contact applications, redirecting formulation R&D toward heavy-metal-free alternatives.
- Construction material expansion:PVC processing capacity for pipes and fittings is concentrating in China's eastern provinces, sustaining volume foundations for stabilizer producers with regional supply positions.
Market Restraints
- Zinc cost volatility:Fluctuations in zinc metal pricing transmit directly into calcium-zinc stabilizer cost structures, compressing compounder margins during upward cycles.
- Organotin discharge regulation:US EPA industrial wastewater permit requirements constrain tin-based stabilizer use in domestic compounding, limiting formulation flexibility for certain rigid applications.
- Technical performance gaps:Organic stabilizer systems still exhibit inferior long-term thermal stability versus metal soap alternatives in high-temperature extrusion profiles.
Strategic Opportunities
- Medical tubing certification:Heavy-metal-free stabilizer demand is accelerating in pharmaceutical-grade PVC applications where migration limits are tightening beyond current supply capacity.
- Antioxidant-stabilizer hybridization:Convergence of thermal stabilizer and antioxidant chemistries enables additive loading reduction in rigid profile extrusion, creating premium positioning.
- High-clarity packaging films:Specialized liquid stabilizer formulations for optical-grade PVC are capturing margin pools in food-contact and pharmaceutical blister pack segments.
Industry Challenges
- Formulation requalification timelines:Processor validation cycles for new stabilizer systems extend 18-24 months in wire and cable applications, slowing revenue conversion from product development investments.
- Metal soap precursor supply security:Backward integration into fatty acid and metal oxide supply chains requires capital deployment that mid-scale stabilizer producers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PVC Stabilizer Market |
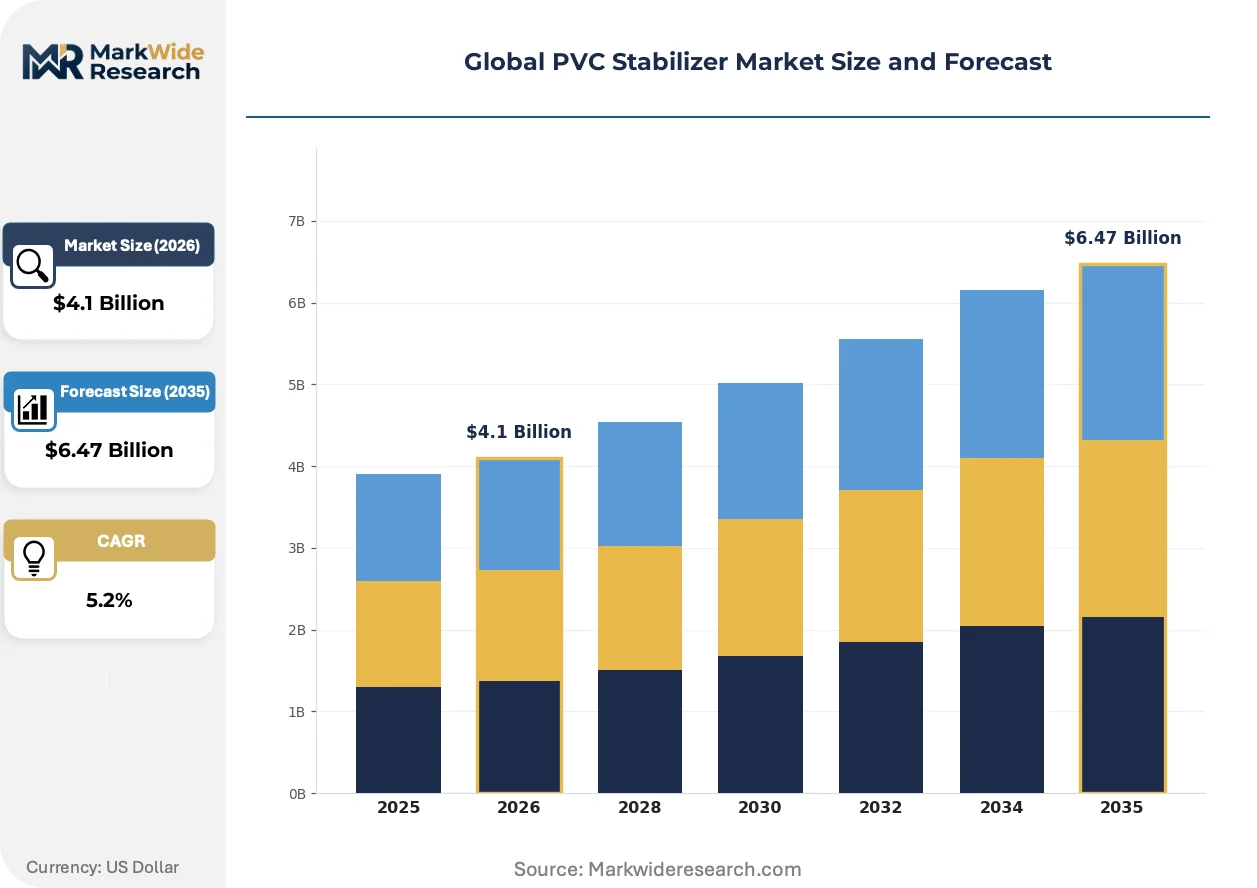
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.47 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Based, Calcium Zinc, Organic, Mixed Metal, Epoxy, Others Application: Wire & Cable, Pipes & Fittings, Profiles & Sheets, Flooring, Automotive Components, Construction Materials End User Industry: Manufacturing Plants, Assembly Units, Industrial Fabricators, Plastic Processors Form: Liquid, Powder, Granules, Paste |
| Companies Covered | SONGWON Industrial Group, PMC Group, Akdeniz Chemson, Goldstab Organics, Clariant AG, Valtris Specialty Chemicals, Adeka Corporation, KD Chem, Baerlocher GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PVC Stabilizer Market Shifts & Advancements
Formulation chemistry is pivoting toward hybrid systems that merge thermal stabilization with secondary functions, compressing additive package complexity while regulatory pressure accelerates heavy-metal elimination timelines.
Calcium-zinc complex stabilizers are decomposing the traditional separation between thermal stabilizers and lubricant packages in rigid PVC extrusion. Pipe and fitting processors in Germany and Italy are adopting these integrated systems at accelerating rates. This convergence is decomposing the historical supplier landscape where lubricant and stabilizer vendors operated as distinct procurement categories.
REACH authorization annex XIV listings have eliminated lead-based stabilizers from most European consumer-contact PVC applications. ECHA enforcement is redirecting formulation investments toward calcium-zinc and organic alternatives with qualified supply chains. Medical device and food-contact segments are responding with accelerated heavy-metal-free certification programs to maintain market access.
Specification-driven procurement is consolidating stabilizer selection authority from compounders to end-brand owners in medical and potable-water applications. Brand owners in Switzerland and the Netherlands are imposing direct stabilizer chemistry requirements that bypass traditional distributor channels. This disintermediation is most visible in pharmaceutical tubing where migration test documentation must trace to specific additive lots.
Global PVC Stabilizer Market Segmentation
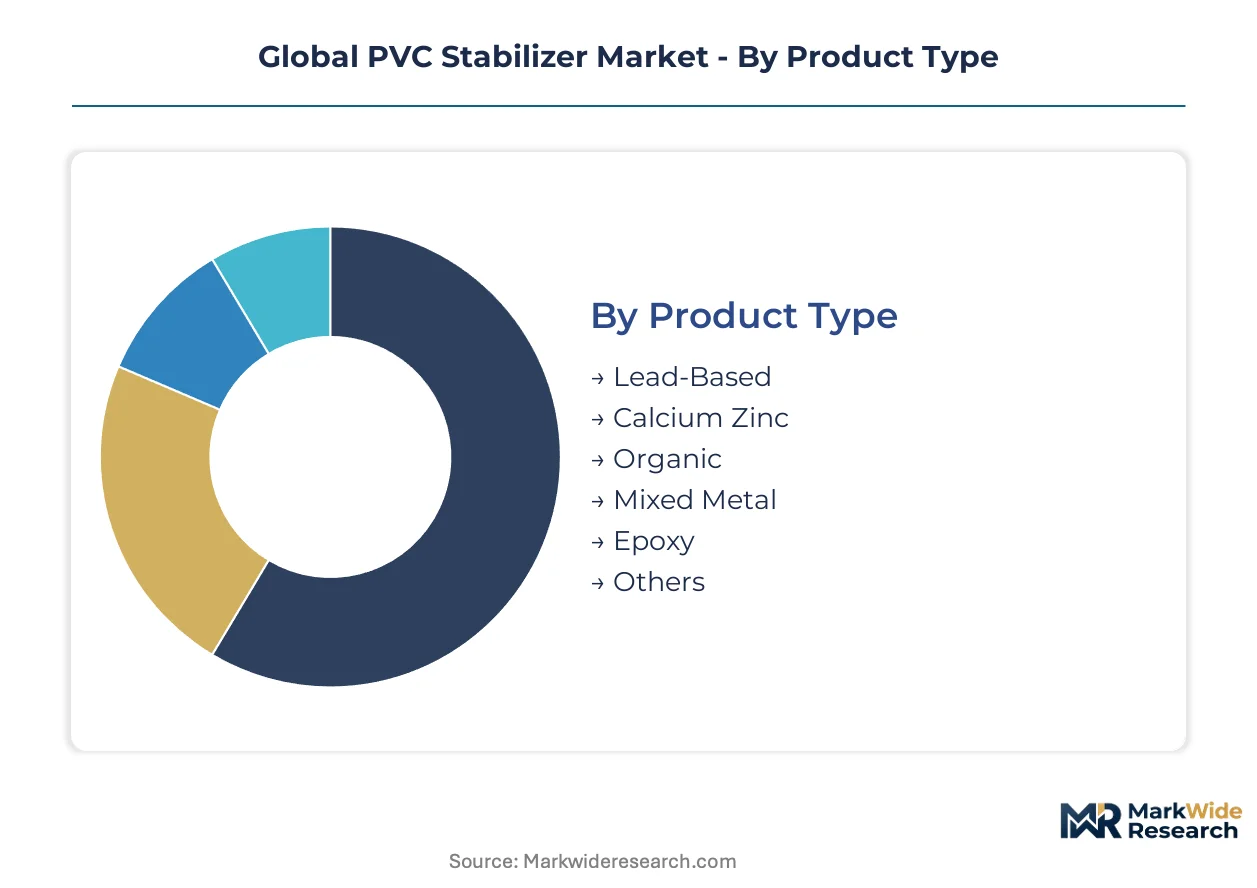
PVC stabilizer segmentation reveals distinct procurement patterns across chemistry families and processing forms. Specification requirements vary sharply between construction-grade volume applications and medical-grade certified segments.
Product Type:
Geographic spread separates domestic formulation leaders from export-dependent specialty suppliers. Lead-based systems retain residual demand in regions with phased transition timelines.
- Lead-Based:Legacy formulations incorporating lead salts and soaps still serve specific industrial PVC applications in markets with delayed regulatory implementation. Demand concentrates in regions outside REACH jurisdiction where cost sensitivity overrides heavy-metal elimination mandates.
- Calcium Zinc:Metal soap complexes combining calcium and zinc carboxylates deliver thermal stability without heavy-metal content. Volume demand clusters in China's construction sector as domestic processors convert from lead-based systems under MEE enforcement timelines.
- Organic:Heavy-metal-free stabilizers based on nitrogen-containing and phosphite chemistries command premium positioning in medical tubing.
- Mixed Metal:Barium-zinc and barium-cadmium variants serve niche rigid applications with specific cost-performance requirements.
- Epoxy:Epoxidized soybean oil and linseed oil derivatives function as co-stabilizers and plasticizers in flexible PVC.
- Others:Emerging rare earth and hydrotalcite-based systems target high-temperature extrusion profiles.
Calcium zinc commands the established base. The steepest expansion runs through organic formulations.
Application:
Cost tier differentiation separates commodity construction applications from specification-intensive electrical segments. Margin structures widen proportionally with certification burden.
- Wire & Cable:Insulation-grade stabilizers must meet electrical property specifications and extended thermal aging requirements. Demand concentrates in China's State Grid transmission projects and India's rural electrification programs, pulling higher-loading calcium-zinc systems into specification.
- Pipes & Fittings:Pressure pipe and drainage applications sustain the largest absolute volume base. Procurement clusters in China's eastern provinces where PVC processing capacity expansion continues.
- Profiles & Sheets:Window frames and siding applications require long-term weathering stability.
- Flooring:Resilient vinyl tile and sheet formulations demand specific migration characteristics for indoor air quality compliance.
- Automotive Components:Interior trim and underhood applications face OEM-specific material approval cycles.
- Construction Materials:Broad category encompassing siding, roofing membranes, and structural foams.
Pipes and fittings anchor volume foundations. Wire and cable insulation delivers superior margin capture.
End User Industry:
Customer type determines procurement authority concentration. Brand-owner specification overrides compounder selection in certified segments.
- Manufacturing Plants:Integrated PVC resin producers with captive compounding operations source stabilizers through direct supply agreements.
- Assembly Units:Component fabricators serving automotive and appliance OEMs operate on qualified supplier lists.
- Industrial Fabricators:Custom extrusion and molding operations serving construction and industrial markets.
- Plastic Processors:Independent compounders purchasing resin and additive packages for toll processing.
Manufacturing plants command the established base. The steepest expansion runs through plastic processors.
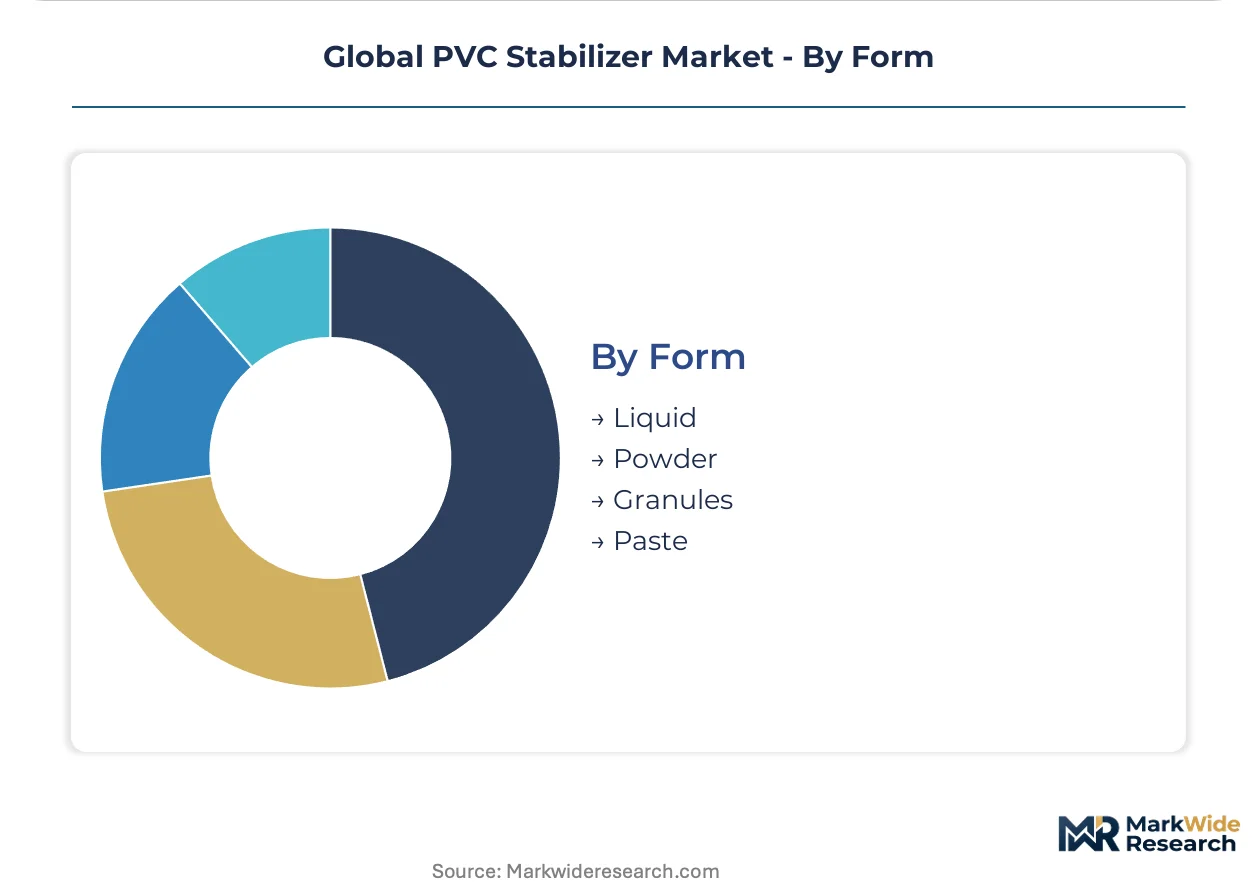
Form:
Supply concentration favors powder processing in high-volume regions while liquid formulations serve specialty film applications.
- Liquid:Pumpable stabilizer-lubricant systems enable automated dosing in continuous extrusion. Demand concentrates in high-clarity packaging film production where optical grade specifications require precise dispersion control.
- Powder:Dry blend formats dominate rigid PVC compounding. Volume procurement clusters in China's pipe and profile sector where high-speed mixing equipment is standard.
- Granules:Dust-free handling formats suit automated feeding systems in medical compounding cleanrooms.
- Paste:Pre-dispersed stabilizer systems serve plastisol applications in coating and slush molding.
Powder commands the established base. The steepest expansion runs through liquid formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics shape regional positioning across the PVC stabilizer supply base. China sustains net export surpluses in calcium-zinc formulations. European compounders source specialty organic grades through Swiss and German distributors.
China
State Grid transmission infrastructure and rural electrification programs drive wire and cable insulation demand. The Ministry of Ecology and Environment enforces GB standards restricting cadmium and phthalate co-stabilizers in building products. PVC processing capacity clusters in Jiangsu and Zhejiang provinces where pipe and profile extrusion lines operate at scale.
Germany
REACH authorization timelines eliminate lead-based stabilizers from consumer-contact applications. ECHA enforcement redirects formulation investments toward calcium-zinc and organic alternatives. Industrial compounding concentrates in North Rhine-Westphalia where pipe processors adopt integrated stabilizer-lubricant systems.
United States
Power grid modernization and data center construction pull higher-performance stabilizers into wire and cable specifications. EPA industrial wastewater permits constrain tin-based stabilizer discharge from compounding operations. Gulf Coast resin producers maintain captive additive blending capacity near Houston and Lake Charles.
India
Rural electrification programs and urban plumbing infrastructure sustain pipe and fitting demand. Bureau of Indian Standards implements migration limits for potable-water contact applications. PVC processing expands in Gujarat and Maharashtra where construction material demand concentrates.
Japan
High-clarity packaging film production for pharmaceutical blister packs drives liquid stabilizer procurement. METI guidelines shape chemical management protocols for food-contact PVC. Specialty compounding operations cluster in the Osaka-Kobe industrial corridor.
Global PVC Stabilizer Market Competitive Landscape
Concentration sits with diversified chemical conglomerates possessing backward integration into metal soap precursors. Mid-scale regional compounders occupy formulation customization niches. Strategic archetypes include integrated resin-stabilizer producers, specialty additive houses, and toll compounders serving qualified supplier lists. Capacity expansion and antioxidant-stabilizer hybridization represent dominant competitive vectors.
Within the European integrated tier, Baerlocher GmbH exemplifies metal soap precursor control. Adeka Corporation anchors the Asia-Pacific specialty vector. SONGWON Industrial Group occupies the hybrid-system positioning segment. These three entities represent distinct strategic postures without implying specific market share or revenue claims.
| Leading Market Players |
|---|
| SONGWON Industrial Group |
| PMC Group |
| Akdeniz Chemson |
| Goldstab Organics |
| Clariant AG |
| Valtris Specialty Chemicals |
| Adeka Corporation |
| KD Chem |
| Baerlocher GmbH |
| Others |
Supply & Pricing Matrix
Calcium-zinc stabilizer substitution for lead-based systems is redrawing raw material sourcing maps from Jiangsu province to the Rhine-Ruhr corridor while compressing margin structures for processors caught between zinc price volatility and REACH-mandated reformulation costs.
Pricing Analysis
Industrial OEM buyers anchor contract structures around three-tier pricing stratification across pharmaceutical-grade, electrical-grade, and construction-grade tiers. Price differentiation hinges on heavy-metal-free certification depth and volume commitment scale, with spot-market zinc oxide costs transmitting directly into calcium-zinc formulation economics. Cost compression in construction-grade segments is intensifying because Chinese pipe processors are consolidating procurement through direct mill agreements. Medical tubing compounders exhibit lowest price sensitivity due to migration-test documentation requirements and 18-24 month requalification timelines.
Supply Chain Analysis
China and Germany anchor global metal soap precursor production, with fatty acid supply chains clustering around Jiangsu and Zhejiang provinces while European compounding draws from North Rhine-Westphalia chemical parks. Stabilizer formulation rests on zinc oxide, epoxidized soybean oil, and organotin intermediates as critical inputs. Single-source vulnerability concentrates in rare earth co-stabilizer feedstock controlled by Chinese state-owned miners. Distribution runs through regional compounder networks in pipe and profile sectors, shifting toward direct brand-owner procurement in medical and potable-water applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a cyclical recovery phase driven by State Grid transmission infrastructure deployment in China, creating favorable conditions for additive suppliers with qualified heavy-metal-free platforms.
For Market Incumbents: Secure backward integration into zinc oxide and fatty acid supply chains to defend margin positions against commodity volatility. Fortify medical tubing certification portfolios before ECHA extends REACH migration limits to additional polymer categories. Prioritize antioxidant-stabilizer hybrid R&D to capture additive-loading reduction demand from rigid profile extruders.
For New Entrants and Emerging Players: Lead with specialized liquid stabilizer formulations for high-clarity pharmaceutical packaging films where Adeka Corporation's established position leaves niche white space. Target India's rural electrification wire and cable segment through Bureau of Indian Standards pre-certification partnerships with Gujarat-based compounders. Pursue toll-manufacturing arrangements with European distributors to bypass 18-24 month processor qualification cycles.
For Investors and Strategic Acquirers: The market sits at a mid-cycle expansion phase that favors specialty additive houses with medical-grade certification depth over commodity metal soap producers. Long-term viability through the next decade hinges on regulatory acceleration of heavy-metal elimination timelines across ASEAN markets. Monitor ECHA annex XIV expansion announcements as the primary inflection signal for organic stabilizer demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metal Soap Precursors | Baerlocher GmbH's captive fatty acid production secures cost positions across European calcium-zinc compounding channels. |
| Medical-Grade Certification Investment | Heavy-metal-free stabilizer documentation meets Swiss and Dutch brand-owner direct procurement requirements in pharmaceutical tubing. |
| Antioxidant-Stabilizer Hybrid Development | SONGWON Industrial Group's integrated systems reduce additive loadings in rigid PVC profiles for construction applications. |
| Regional Capacity Expansion in China | Jiangsu and Zhejiang province plant additions serve State Grid wire and cable insulation demand growth. |
| Long-Term Supply Agreements with Power Grid Developers | Direct contracts with China's State Grid and India's rural electrification programs stabilize volume foundations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade databases, SEC chemical sector filings, ECHA authorization registers, and industry association technical standards. Interviews with PVC plant managers, downstream pipe processor procurement leads, distribution channel partners, and medical device regulatory affairs directors informed demand-side validation. Bottom-up volume estimates from application-level consumption models triangulated against top-down chemical additive production data.
Segmentation dimensions modeled include stabilizer chemistry family, processing form, end-use application, and regional regulatory cluster across the analysis window. CAGRs derived from curve-fitting historical volume trajectories against projected construction and electrical infrastructure deployment schedules. Forecast inputs incorporate PVC resin capacity expansion timelines, REACH authorization phase-down calendars, and power grid investment program commitments.
Forecasts assume regulatory continuity in REACH, GB standards, and Bureau of Indian Standards regimes; material policy shifts would require re-modeling. Specific risks include zinc price volatility spikes, ECHA acceleration of organotin restrictions, and delays in India's rural electrification procurement cycles. Recalibration cycles align with material shifts in power grid investment disbursements and ECHA annex XIV listing announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Carboxylic Acids Based Esters Market
Additives
Global Polyurethane Additives Market
Additives
Nucleotide Premix Market
Additives
Global Metal Scavenging Agents Market
Additives
Inorganic Rheology Modifiers Market
Additives
Anti-Pollution Ingredients Market
Additives
United Kingdom Sodium Reduction Ingredient Market
Additives
Low Volatile Organic Compounds Coating Additives Market
Additives
Global Sodium Acetate Trihydrate Market
Additives
Global Silica-Based Matting Agents Market
Additives
Ultraviolet Light Stabilizer Market
Additives
Global Coalescing Agent Market
Additives
Antiknock Agents Market
Additives
Tamarind Gum Derivatives Market
Additives
Tragacanth Market
Additives
Polyethylene Terephthalate Additives Market