
 Sodium Stearyl Fumarate Market | 2026-2036
Sodium Stearyl Fumarate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Stearyl Fumarate Market Analytics
REACH compliance in Europe is repositioning the cost-of-entry calculus for excipient suppliers serving regulated markets. JRS Pharma leverages its vertical integration into fumaric acid supply chains to sustain cost discipline across batch production. SPI Pharma differentiates through specialized granulation capabilities that anchor its position in high-purity sodium stearyl fumarate grades. Nippon Soda dominates technical-grade supply within Asia-Pacific pharmaceutical corridors, while Standard Chem & Pharm navigates regulatory complexity across multiple pharmacopeial jurisdictions.
Sodium stearyl fumarate functions as a tablet lubricant and glidant in pharmaceutical manufacturing, typically supplied as a fine white powder with a melting point near 225°C and particle size distributions optimized for direct compression processes. The compound reduces punch adhesion and improves powder flow properties without the hydrophobic film formation associated with traditional metallic stearates. Among product type segments, granule formulations occupy the dominant volume position due to superior flow characteristics in high-speed tableting operations, while powder grades represent the fastest-expanding category as continuous manufacturing lines demand more precise dosing control. Application demand concentrates in pharmaceuticals, where margin pools deepen around USP-NF and EP-certified grades subject to stringent elemental impurity testing.
The US FDA enforces ICH Q3D elemental impurity limits that directly shape excipient sourcing decisions, while the European Medicines Agency applies REACH registration requirements that filter non-compliant suppliers from commercial channels. India's Central Drugs Standard Control Organization aligns with ICH guidelines through its own impurity testing protocols, creating a convergent regulatory baseline across major manufacturing geographies. China's National Medical Products Administration maintains distinct GB standards for pharmaceutical excipients that require separate qualification pathways for market access. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP standards, as divergence in lubricant performance specifications could force parallel product development tracks and duplicate validation investments.
Market Dynamics
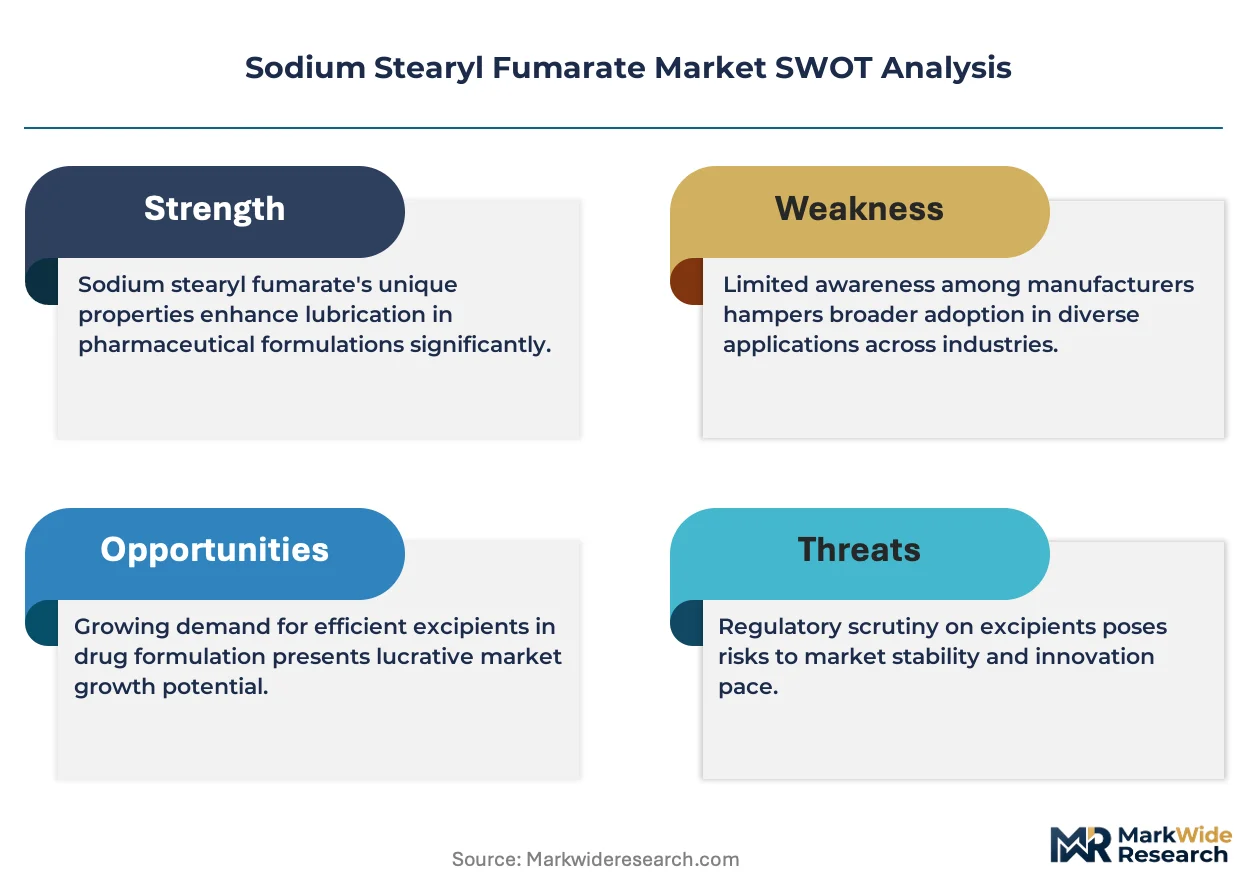
Pharmaceutical formulators are systematically replacing magnesium stearate with sodium stearyl fumarate to eliminate hydrophobic film formation on tablet surfaces, a substitution wave intensified by ICH Q3D elemental impurity scrutiny that disqualifies metallic lubricants in high-value oral solid dosage forms.
Growth Catalysts
- ICH Q3D Compliance:The FDA's elemental impurity limits force reformulation away from magnesium stearate toward non-metallic alternatives, expanding addressable demand for sodium stearyl fumarate in US generic and innovator drug portfolios.
- Continuous Manufacturing:Direct compression lines at Pfizer, Novartis, and AstraZeneca facilities demand precise powder flow control that granule-grade sodium stearyl fumarate delivers, accelerating specification upgrades across contract manufacturing organizations.
- India's API Export Engine:Domestic pharmaceutical production and export-oriented active pharmaceutical ingredient manufacturing in Hyderabad and Ahmedabad corridors drive bulk procurement of USP-NF certified excipients from integrated suppliers.
Market Restraints
- Fumaric Acid Price Volatility:Petrochemical feedstock fluctuations and agricultural diversion of maleic anhydride precursors create input cost instability that compresses margin buffers for non-integrated compounders.
- Supplier Concentration Risk:Technical-grade supply chains concentrate among three Asian chemical houses, creating single-source vulnerability for pharmaceutical buyers requiring pharmacopeial certification.
- Performance Ceiling in High-Speed Lines:Sodium stearyl fumarate's lubrication efficiency plateaus above 70,000 tablets per hour, forcing hybrid lubricant strategies that dilute pure-form adoption in the fastest compression equipment.
Strategic Opportunities
- Brazil's ANVISA Alignment:Pending harmonization with ICH Q3D guidelines creates a qualification window for pre-registered suppliers to capture share in Latin America's fastest-expanding generic market before local competitors achieve certification.
- Nutraceutical Convergence:Dietary supplement manufacturers adopting pharmaceutical-grade manufacturing standards present a greenfield application segment with lower regulatory barriers and faster qualification cycles than prescription drug channels.
- Dual-Track Pharmacopeial Strategy:Simultaneous USP-NF and EP certification investments unlock European biotech contract manufacturing demand that currently sources from regional fumarate derivative specialists.
Industry Challenges
- Analytical Method Transfer:Elemental impurity testing protocols vary between ICP-MS and XRF methodologies, forcing duplicate validation investments for suppliers serving multiple contract manufacturing organizations with divergent quality systems.
- Continuous Line Integration:Powder feeding systems designed for magnesium stearate require recalibration for sodium stearyl fumarate's distinct bulk density and electrostatic properties, extending commissioning timelines and delaying volume ramp.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Stearyl Fumarate Market |
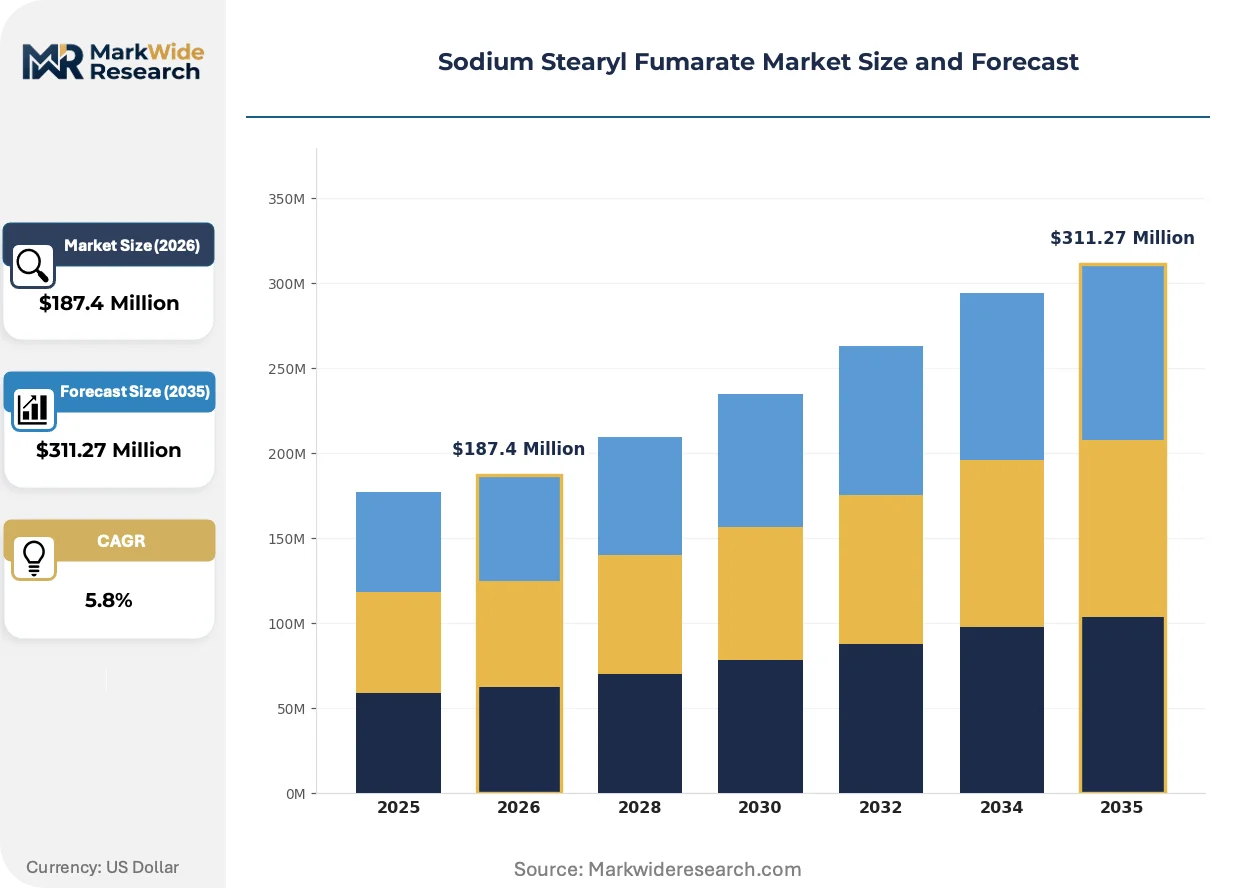
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powders, Tablets, Capsules Application: Pharmaceuticals, Cosmetics, Food Additives, Nutraceuticals End User: Pharma Companies, Cosmetic Manufacturers, Food Producers, Supplement Brands Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | Maruti Chemicals, Standard Chem & Pharm, JRS Pharma, Nippon Soda, IFF, SPI Pharma, Taizhou Tianrui Pharmaceutical, Sunhere Pharmaceutical Excipients, FMC Health & Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Stearyl Fumarate Market Evolving Landscape
Continuous manufacturing adoption is compressing batch sizes and demanding excipient grades with tighter particle size distributions, while regulatory harmonization pressures are collapsing the historical gap between pharmaceutical and technical-grade specifications.
Granule-grade sodium stearyl fumarate is overtaking traditional powder forms in high-speed tableting operations due to superior flow characteristics and reduced electrostatic adhesion. Contract manufacturing organizations in India and Ireland have completed specification switches within 18-month cycles. The technology is overtaking conventional metallic lubricants in facilities running 24-hour continuous compression campaigns where powder uniformity directly determines yield rates.
REACH registration requirements in Europe are filtering non-compliant excipient suppliers from commercial channels serving EMA-regulated drug products. The industrial consequence is a consolidation of approved supplier lists at major pharmaceutical companies, with technical-grade traders losing access to formulation development pipelines. High-purity grades subject to ECHA substance evaluation are capturing disproportionate margin pools as buyers prioritize regulatory security over unit cost.
Formulation development groups are compressing their lubricant qualification timelines from 24 months to 9 months through parallel rather than sequential stability studies. This behavioral shift disrupts traditional excipient supplier relationships built on decade-long incumbent status, creating entry points for certified alternatives. The pattern is most visible among mid-sized generic houses in India and Eastern Europe competing for limited-supply contract manufacturing slots at innovator companies.
Sodium Stearyl Fumarate Market Segmentation
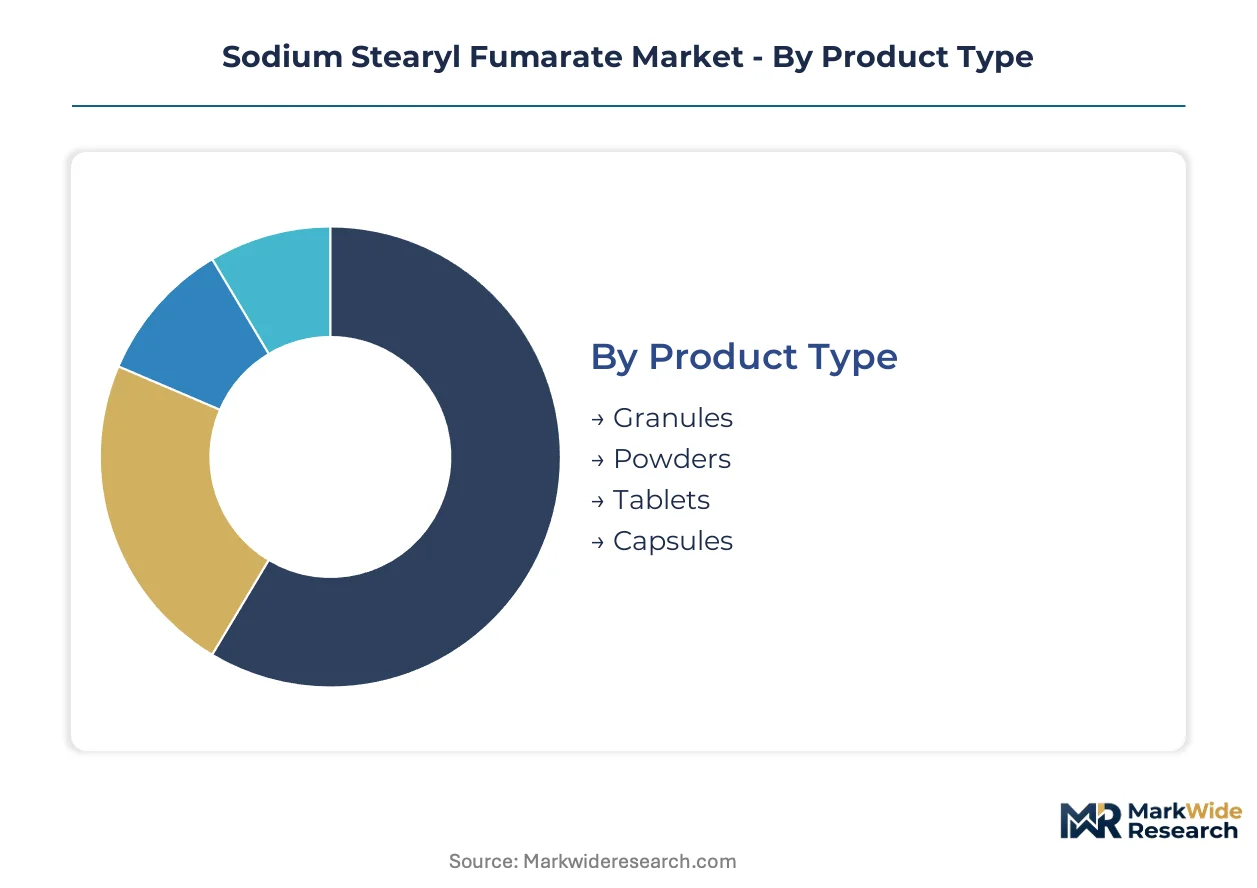
Excipient procurement patterns diverge sharply across buyer categories. Pharmaceutical formulators prioritize USP-NF certification and elemental impurity documentation, while nutraceutical and cosmetic buyers trade regulatory stringency for cost efficiency and supply flexibility.
Product Type:
Formulation requirements and manufacturing equipment dictate grade selection across buyer segments.
- Granules:Optimized particle size distributions (typically 100-500 microns) deliver superior flow characteristics in high-speed rotary tablet presses. Demand concentrates among contract manufacturing organizations in India running 24-hour continuous compression campaigns where powder uniformity directly determines yield rates.
- Powders:Fine-milled grades with sub-100 micron particle sizes enable precise dosing control in continuous manufacturing lines at Pfizer, Novartis, and AstraZeneca facilities. Powder feeding systems require recalibration for distinct bulk density and electrostatic properties, extending commissioning timelines.
- Tablets:Pre-compressed lubricant tablets simplify handling in small-batch operations and R&D environments.
- Capsules:Encapsulated grades address hygroscopicity concerns during storage and transport in tropical climates.
Volume sits with granules; growth tilts toward powders.
Application:
Regulatory burden and margin structure separate pharmaceutical demand from adjacent sectors.
- Pharmaceuticals:USP-NF and EP-certified grades subject to ICH Q3D elemental impurity testing command premium positioning. Formulators at generic houses in India and Eastern Europe compress lubricant qualification timelines from 24 months to 9 months through parallel stability studies.
- Nutraceuticals:Dietary supplement manufacturers adopting pharmaceutical-grade manufacturing standards present faster qualification cycles than prescription drug channels.
- Cosmetics:Technical-grade specifications suffice for topical formulations where lubricant function is secondary to emollient properties.
- Food Additives:FSSAI and FDA food-grade certifications apply, with demand tied to anti-caking applications in processed food manufacturing.
Pharmaceuticals capture the deepest margin pools; nutraceuticals are expanding most quickly.
End User:
Scale and integration level determine whether buyers source through distributors or direct manufacturer relationships.
- Pharma Companies:Integrated innovators and generic houses maintain approved supplier lists with 3-5 qualified sodium stearyl fumarate sources to mitigate concentration risk.
- Cosmetic Manufacturers:Regional formulators in Asia-Pacific corridors source technical grades through chemical traders with limited pharmacopeial certification.
- Food Producers:Industrial-scale processors prioritize volume pricing and consistent lot-to-lot quality over certification depth.
- Supplement Brands:Mid-tier dietary supplement companies represent a greenfield segment with lower regulatory barriers than prescription channels.
Direct procurement dominates pharma; distributor relationships anchor cosmetic and food segments.
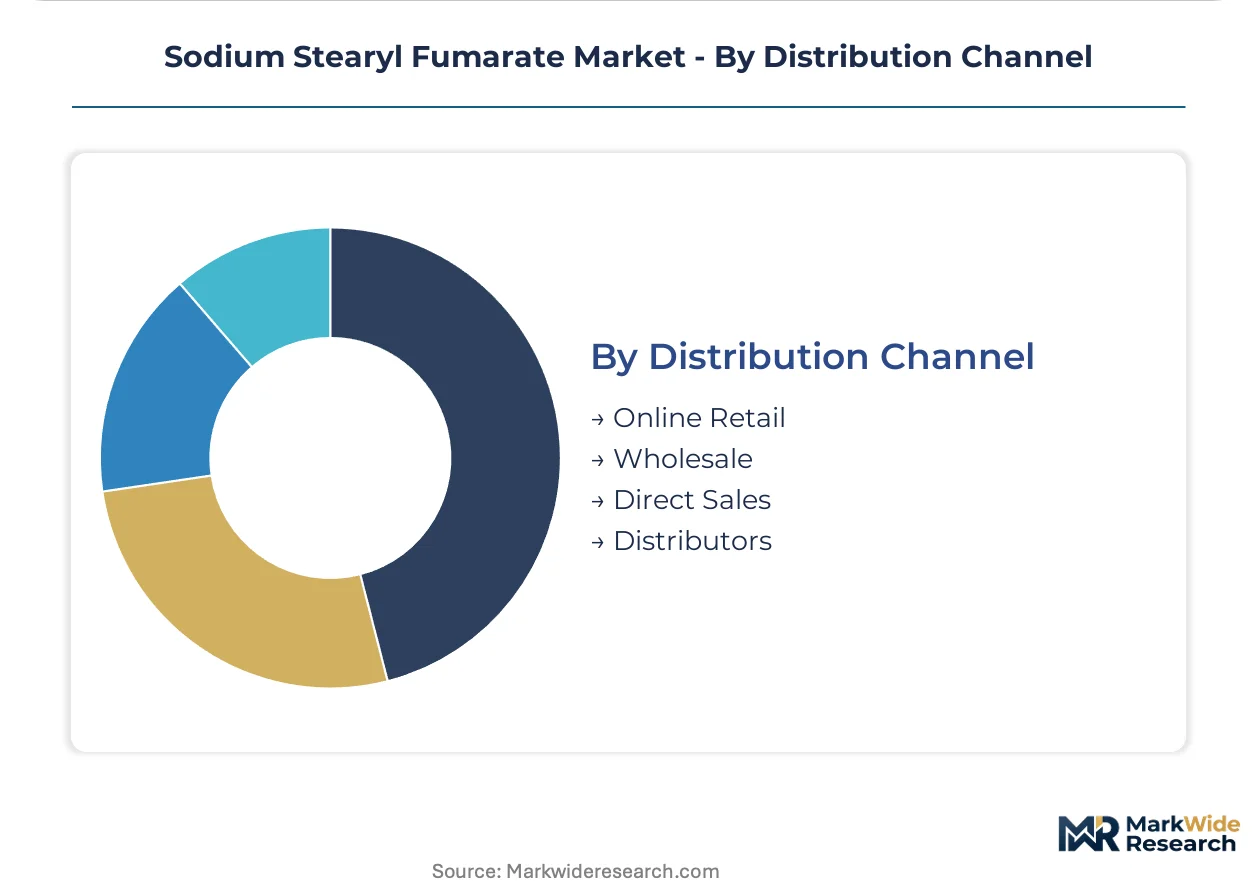
Distribution Channel:
Channel selection reflects buyer sophistication and certification requirements.
- Direct Sales:Long-term supply agreements with JRS Pharma, SPI Pharma, and Nippon Soda secure volume allocation and batch-to-batch consistency for large pharmaceutical manufacturers.
- Distributors:Regional chemical distributors serve mid-tier buyers lacking technical resources to qualify manufacturers directly.
- Wholesale:Bulk procurement channels aggregate demand from smaller nutraceutical and cosmetic formulators.
- Online Retail:E-commerce platforms facilitate sample procurement and small-volume orders for R&D laboratories and academic institutions.
Direct sales command the largest transaction values; online retail is gaining share fastest among emerging buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Hyderabad and Ahmedabad concentrate pharmaceutical excipient demand through API export manufacturing clusters. India's Pharmaceutical Park schemes and China's NMPA reform zones reshape procurement geography. Regulatory convergence around ICH Q3D standards creates qualification windows across multiple jurisdictions.
United States
Generic drug manufacturers in New Jersey and North Carolina drive USP-NF certified excipient procurement for oral solid dosage reformulation. FDA enforcement of ICH Q3D elemental impurity limits accelerates magnesium stearate substitution in high-value portfolios. The Research Triangle Park corridor hosts contract manufacturing organizations completing 18-month lubricant qualification cycles.
India
Hyderabad's Genome Valley and Ahmedabad's Changodar belt anchor bulk procurement of specialty excipients for export-oriented API production. CDSCO alignment with ICH guidelines through revised impurity testing protocols creates convergent standards with US and European markets. Domestic pharmaceutical production in these clusters demands integrated suppliers capable of pharmacopeial certification.
Germany
EMA-regulated drug manufacturers in Baden-Württemberg and North Rhine-Westphalia prioritize REACH-registered excipient sources for European market access. ECHA substance evaluation requirements filter non-compliant suppliers from approved vendor lists. The Rhine-Neckar pharmaceutical corridor concentrates formulation development activity driving high-purity grade specification.
China
NMPA maintains distinct GB standards for pharmaceutical excipients requiring separate qualification pathways from USP-NF or EP certification. Yangtze River Delta chemical manufacturers supply technical-grade material to domestic tablet producers. Shanghai and Suzhou pharmaceutical parks represent emerging demand centers as local innovators adopt international manufacturing standards.
Brazil
ANVISA's pending harmonization with ICH Q3D guidelines creates pre-registration opportunities for certified suppliers. São Paulo state's generic pharmaceutical manufacturers represent Latin America's fastest-expanding excipient demand pool. Local competitors lack certification infrastructure, opening share capture windows before regulatory alignment completes.
Sodium Stearyl Fumarate Market Competitive Landscape
German and Japanese producers anchor one tier; Indian and Chinese specialists hold volume positions in technical-grade supply. The vendor structure concentrates around three to five integrated compounders capable of pharmacopeial certification, with regional chemical traders filling gaps in uncertified segments. Strategic archetypes include backward-integrated fumaric acid producers, specialized granulation houses, and multi-jurisdictional certification specialists. Capacity expansion and dual-track pharmacopeial qualification represent dominant competitive moves.
Among established compounders, JRS Pharma exemplifies backward integration into fumaric acid supply chains, while SPI Pharma occupies a position within specialized granulation capabilities for high-purity grades. Nippon Soda represents technical-grade supply concentration within Asia-Pacific pharmaceutical corridors. These three anchors illustrate how certification depth and feedstock control separate sustainable positions from trading-dependent operations.
| Leading Market Players |
|---|
| Maruti Chemicals |
| Standard Chem & Pharm |
| JRS Pharma |
| Nippon Soda |
| IFF |
| SPI Pharma |
| Taizhou Tianrui Pharmaceutical |
| Sunhere Pharmaceutical Excipients |
| FMC Health & Nutrition |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock indices for maleic anhydride derivatives cascade through sodium stearyl fumarate supply chains, compressing margin buffers for non-integrated compounders while concentrating pricing power among backward-linked producers. Fumaric acid spot volatility feeds directly into three-tier pricing stratification across pharmacopeial certification levels.
Pricing Analysis
Short lead-time premiums of 15-25 percent separate emergency procurement from contract-scheduled deliveries in pharmaceutical-grade channels. Contract-based long-term offtake dominates volume transactions, with price differentiation anchored in USP-NF versus EP certification tiers and volume scale commitments. Cost compression in technical-grade supply is intensifying because Indian and Chinese traders compete for uncertified nutraceutical buyers. Generic houses in Eastern Europe exhibit highest price sensitivity; innovator drug portfolios at Pfizer and AstraZeneca facilities prioritize regulatory security over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with technical-grade feedstock channels concentrated among Yangtze River Delta chemical manufacturers. Supply draws from fumaric acid production in Germany, maleic anhydride processing in China, and stearyl alcohol sourcing from Southeast Asian oleochemical plants. Tariff exposure on petrochemical derivatives threatens margin stability for cross-border compounders. Distribution runs through direct manufacturer relationships for certified pharmaceutical grades, with regional chemical distributors anchoring technical-grade segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacity constraints around pharmacopeial-certified production prop pricing premiums, as only three to five integrated compounders globally maintain dual USP-NF and EP qualification. This supply bottleneck sustains margin pools for incumbent certifiers while elevating entry barriers for aspirants.
For Market Incumbents: Deepen captive fumaric acid supply through upstream chemical asset acquisition, insulating batch production from petrochemical feedstock volatility. Expand granulation capacity in Hyderabad and Ahmedabad corridors to capture India's API export engine growth. Prioritize dual-track pharmacopeial certification investments before Brazil's ANVISA completes ICH Q3D alignment, locking in pre-registration advantages.
For New Entrants and Emerging Players: Enter via nutraceutical-grade supply where FSSAI and FDA food-grade certifications present faster qualification cycles than prescription drug channels. Target dietary supplement manufacturers in North America adopting pharmaceutical-grade manufacturing standards. Lead with encapsulated grades addressing hygroscopicity concerns in tropical climates, differentiating through packaging innovation rather than certification depth.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional chemical traders in Asia-Pacific corridors facing REACH registration compliance costs. Five-to-ten year viability hinges on pharmacopeial certification infrastructure rather than technical-grade volume position. Monitor ECHA substance evaluation timelines as inflection indicator for supplier list consolidation at EMA-regulated drug manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fumaric Acid | JRS Pharma's captive supply chain insulates margin buffers from petrochemical volatility. |
| Dual-Track Pharmacopeial Certification | Simultaneous USP-NF and EP qualification unlocks European biotech contract manufacturing demand. |
| Granulation Capacity Expansion | SPI Pharma's specialized capabilities anchor high-purity grade positioning in continuous manufacturing lines. |
| Pre-Registration in Brazil | ANVISA alignment windows allow certified suppliers to capture share before local competitors achieve qualification. |
| Encapsulated Grade Development | Novel packaging formats address tropical climate hygroscopicity concerns for nutraceutical distribution. |
Research Methodology
Trade flow databases, ECHA registration filings, and CDSCO impurity testing protocols formed the secondary backbone, cross-referenced against primary interviews with pharmaceutical formulation scientists, excipient procurement managers at generic houses, regulatory affairs specialists, and contract manufacturing organization quality directors. Bottom-up volume estimates from tablet press utilization rates and top-down value projections from pharmacopeial certification premiums were reconciled through iterative triangulation.
Bottom-up modeling tracked grade-specific demand across granule and powder formulations, application segments spanning pharmaceuticals to nutraceuticals, and end-user scale tiers from integrated innovators to regional chemical traders. CAGRs were derived from elasticity-adjusted demand curves incorporating ICH Q3D compliance timelines and continuous manufacturing adoption rates. Forecast inputs included fumaric acid price trajectory assumptions and regional regulatory harmonization schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical feedstock disruption or accelerated pharmacopeial divergence between USP and ChP standards. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Acidulants Market
Additives
Defoaming Coating Additives Market
Additives
Canada Anti-Caking Market
Additives
Carboxymethyl Cellulose Market
Additives
Emulsifiers In Personal Care Market
Additives
Global Propyl Acetate Market
Additives
Glycyrrhizic Acid Glycosides Market
Additives
China Citric Acid Market
Additives
Viscosity Index Improvers Market
Additives
China Feed Additives Market
Additives
Sorbitan Esters Market
Additives
Glycol Acetate Market
Additives
Antimicrobial Ingredients Market
Additives
Antiscalants/Scale Inhibitors Market
Additives
Polyols and Sorbitols Products Market
Additives
Refinery Process Additives Market