
 North America Lubricants Market | 2026-2036
North America Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lubricants Market Analytics
Base oil production across the U.S. Gulf Coast is broadening as refiners expand Group II and Group III capacity to serve synthetic lubricant growth. ExxonMobil Corporation leverages its integrated upstream-to-blending footprint across Texas and Louisiana to secure feedstock advantage. Chevron Corporation sustains a dense distribution network that reaches both OEM factory fills and independent repair channels. Valvoline Inc. specializes in quick-lube service bay penetration, converting installed vehicle populations into recurring revenue streams.
North America lubricants are formulated mixtures of base oils and performance additives designed to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades typically spanning ISO 32 through ISO 680 for industrial applications and SAE 0W-16 through SAE 60 for automotive engines. Their primary commercial purpose centers on extending equipment life and optimizing energy efficiency across powertrain and machinery operations. Engine oil retains the largest value share within product type segmentation, though industrial lubricants command superior margins due to technical specification complexity and smaller batch production economics. Synthetic base oil categories are expanding fastest as OEMs mandate extended drain intervals and turbocharged direct-injection engines impose severe thermal stress on lubricant films.
The U.S. EPA and Environment and Climate Change Canada jointly shape lubricant demand through coordinated emissions and fuel economy regulations that reward lower-viscosity, lower-friction formulations. API SP and ILSAC GF-6 standards enforce increasingly stringent oxidation stability and deposit control, raising reformulation costs for blenders without captive additive technology. Stakeholders must monitor how California Air Resources Board tailpipe rules cascade into lubricant viscosity grade specifications across the continent.
Market Dynamics
Fleet operators across the United States and Canada are extending oil drain intervals to cut operating costs, forcing lubricant makers to reformulate toward higher-performance synthetic base stocks that withstand thermal stress over longer service cycles.
Growth Catalysts
- Extended drain interval mandates:Heavy-duty fleet operators now demand 50,000+ mile oil change cycles. This pushes blenders toward Group III and PAO base oils that resist oxidation under sustained thermal load.
- EPA Phase 3 greenhouse gas standards:The U.S. EPA's tightened fuel economy rules for model year 2027+ trucks reward lower-viscosity engine oils. OEMs now factory-fill with 5W-30 and 0W-20 grades to squeeze fractional efficiency gains.
- Great Lakes manufacturing concentration:Automotive stamping and metalworking clusters around Detroit, Cleveland, and Chicago sustain bulk demand for high-performance cutting fluids and hydraulic oils.
Market Restraints
- Group III base oil supply concentration:U.S. Gulf Coast refiners control the bulk of North American Group III capacity. Any unplanned outage at Port Arthur or Baytown facilities ripples through synthetic lubricant supply chains within weeks.
- API SP certification cost inflation:The American Petroleum Institute's latest passenger car standard demands costly bench tests for timing chain wear and low-speed pre-ignition. Smaller blenders without captive additive R&D face margin compression.
- Re-refined base oil competition:Used oil collectors in Texas and California are scaling re-refining capacity. This creates price pressure on virgin Group II feedstocks in the aftermarket segment.
Strategic Opportunities
- Canadian oil sands machinery servicing:Alberta's mining and SAGD operations run extreme-duty equipment in abrasive, cold conditions. Specialized open-gear and wire-rope lubricants for shovels and draglines command 40-60% price premiums over standard industrial grades.
- Electric vehicle thermal fluid expansion:Battery electric trucks and buses require dielectric coolants and grease for e-axles. Formulators with dielectric strength testing capability can capture factory-fill positions with emerging OEMs.
- California Low Carbon Fuel Standard credits:The state's LCFS program rewards fuel efficiency improvements. Lubricant makers can partner with fleets to document viscosity-related fuel savings and capture credit value through verified carbon intensity reductions.
Industry Challenges
- Additive chemist talent scarcity:Formulation expertise in ashless dispersants and friction modifiers concentrates among retiring specialists. Blenders struggle to replace institutional knowledge of how additive packages interact under combined thermal and shear stress.
- ILSAC GF-7 timeline compression:The next passenger car specification demands simultaneous fuel economy retention and protection for hybrid engines with frequent stop-start cycles. Development cycles of 18-24 months strain R&D resource allocation.
- Legacy ERP integration with batch tracking:Smaller blenders still run on-premises inventory systems. Migrating to cloud-based lot traceability for quality audits and recall management demands capital outlays that compete with formulation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lubricants Market |
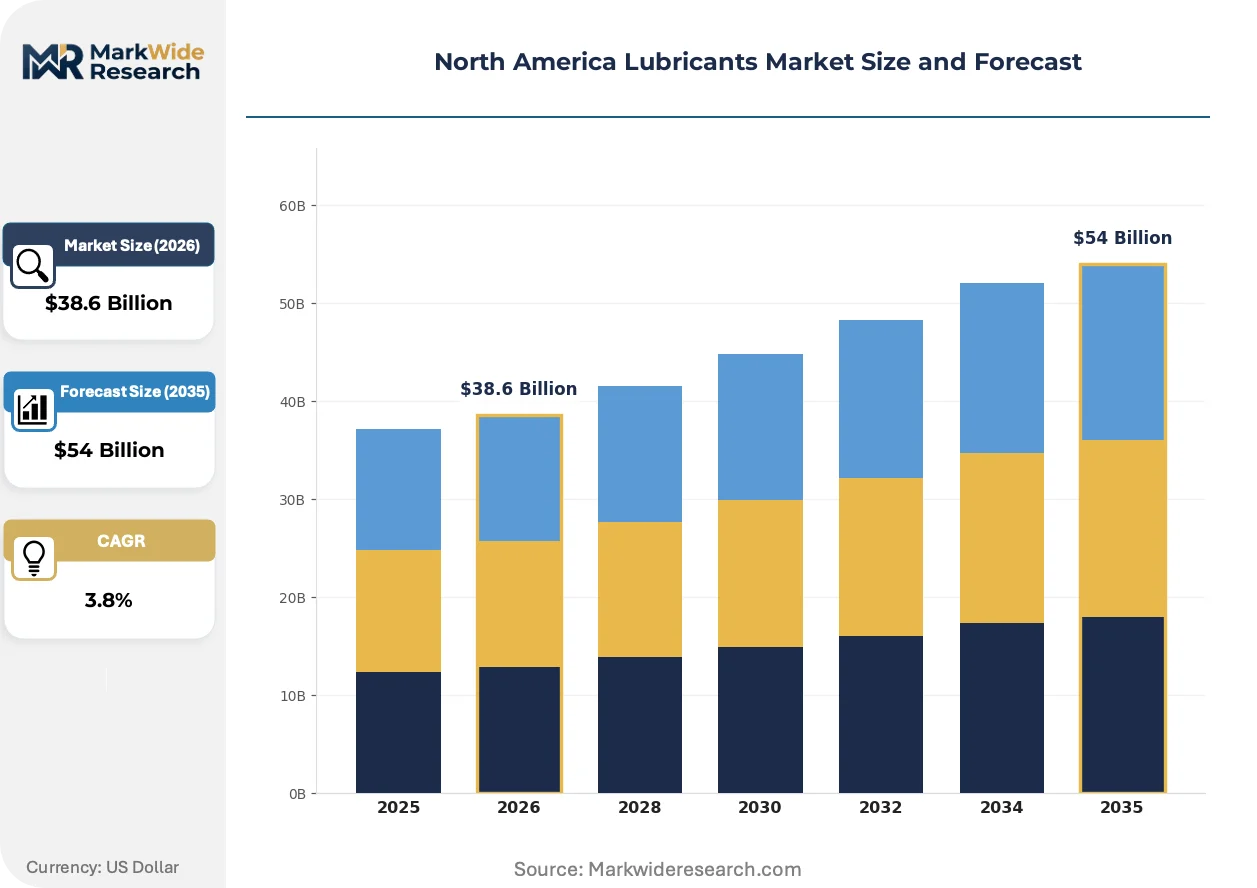
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $54 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Hydraulic Fluid, Gear Oil, Industrial Lubricants Base Oil: Mineral Oil, Synthetic Oil, Bio-based Oil, Re-refined Oil Application: Aerospace, Automotive, Marine, Manufacturing End User: OEMs, Aftermarket Providers, Retailers, Distributors |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, Shell plc, TotalEnergies SE, BP p.l.c., Phillips 66, Valvoline Inc., Fuchs Petrolub SE, Petro-Canada Lubricants, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lubricants Market Evolving Landscape
Formulation science is pivoting toward lower viscosity without sacrificing wear protection, as OEM hardware changes faster than traditional lubricant development cycles can accommodate.
Polyalkylene glycol (PAG) synthetic base stocks are rewriting the rules for compressor and refrigeration lubrication. These polymers offer inherent deposit resistance and water solubility that mineral oils cannot match. Food processing and industrial refrigeration OEMs in Wisconsin and Pennsylvania are specifying PAG-based formulations for ammonia and CO2 systems. The technology is compressing demand for traditional naphthenic refrigerator oils in new equipment installations.
The U.S. EPA's evolving criteria pollutant standards for nonroad diesel engines are tightening particulate matter limits for construction and agricultural equipment. This forces lubricant makers to optimize ash content in heavy-duty engine oils to protect exhaust aftertreatment systems. The farm equipment segment across Iowa and Nebraska is most exposed, with dealers now stocking CJ-4 and CK-4 licensed oils exclusively to avoid warranty disputes.
Fleet maintenance departments are consolidating suppliers through integrated procurement platforms that bundle lubricants with filters, coolants, and shop supplies. Independent distributors in Texas and Ohio are losing shelf space to national program contracts. The shift is most visible among Class 8 trucking fleets running dedicated routes between Dallas-Fort Worth and Chicago, where total cost of ownership models now override brand loyalty in sourcing decisions.
North America Lubricants Market Segmentation
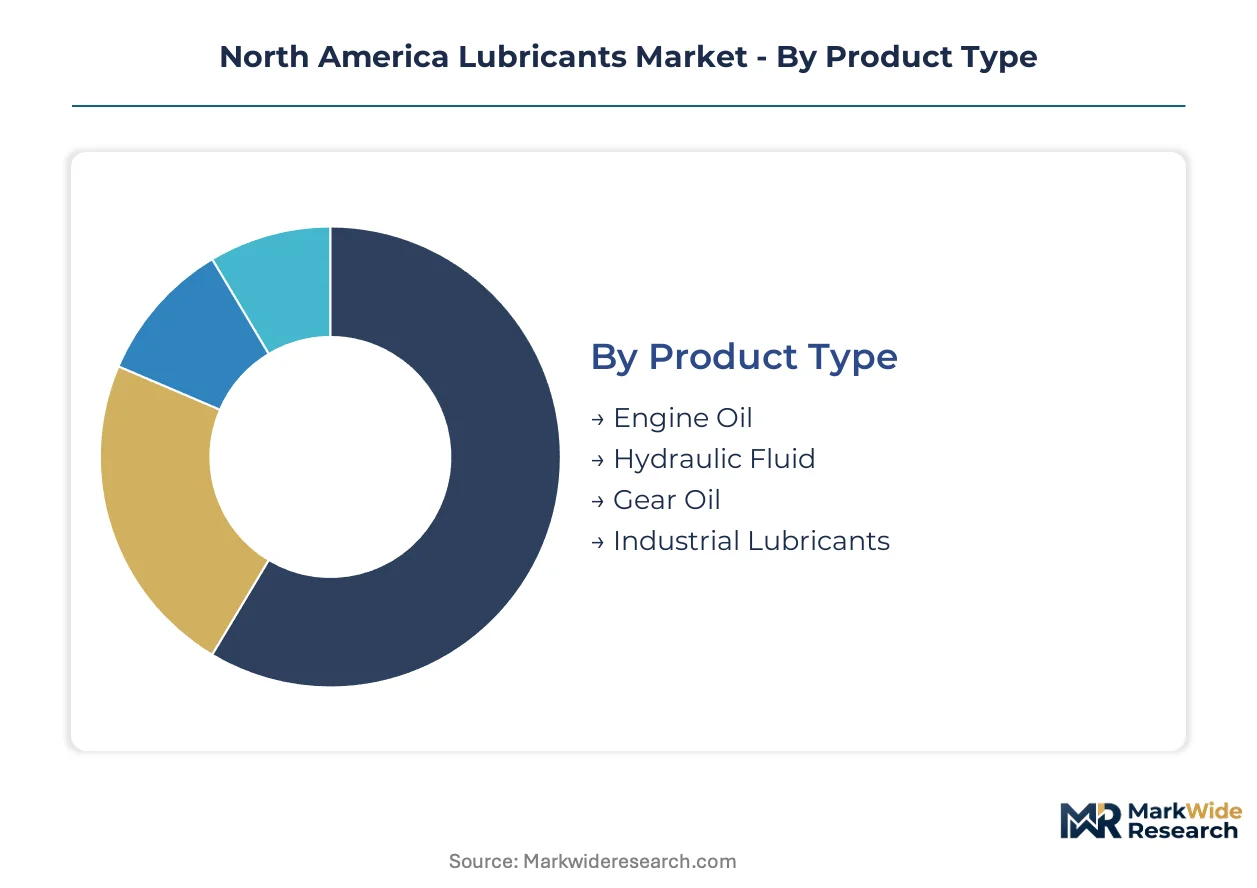
Segmentation reveals how formulation requirements diverge across powertrain technologies and industrial machinery. Each category maps distinct supply chain configurations, from captive refinery production to specialized additive blending. Understanding these splits exposes where margin pools concentrate and which specifications command technical premiums.
Product Type:
Supply concentration clusters around formulations serving high-volume automotive factory-fill contracts, with blenders optimizing production runs around OEM qualification timelines.
- Engine Oil:Formulations span SAE 0W-16 through SAE 60 viscosity grades, blending Group II/III base stocks with detergent-dispersant additive packages. Demand concentrates in Detroit's automotive corridor where Stellantis, Ford, and GM run just-in-time blending operations to match assembly line schedules. EPA Phase 3 fuel economy standards push specifications toward lower-viscosity 5W-30 and 0W-20 grades.
- Hydraulic Fluid:Anti-wear formulations with zinc dialkyldithiophosphate additives protect high-pressure piston pumps in construction and agriculture equipment. The U.S. Great Lakes manufacturing belt—Cleveland stamping presses, Chicago metal fabrication—consumes bulk volumes of ISO 32 through ISO 68 grades. Equipment OEMs like Caterpillar and Deere specify proprietary additive packages that lock in supplier relationships.
- Gear Oil:Extreme-pressure formulations with sulfur-phosphorus compounds protect hypoid differentials and manual transmissions.
- Industrial Lubricants:Cutting fluids, compressor oils, and turbine lubricants serving metalworking and power generation applications.
Today's leader: Engine Oil. Tomorrow's challenger: Industrial Lubricants.
Base Oil:
Cost tier stratification separates commodity feedstocks from performance synthetics, with price spreads reflecting refining complexity and API Group classification.
- Mineral Oil:Group I and Group II paraffinic base stocks refined from crude oil vacuum gas oil. These remain the volume foundation for conventional engine oils and industrial lubricants, with U.S. Gulf Coast refiners in Port Arthur and Baytown controlling North American supply. Price volatility tracks crude differentials and refinery utilization rates.
- Synthetic Oil:Group III hydrocracked stocks and Group IV polyalphaolefins (PAO) manufactured through severe hydroprocessing or oligomerization. Premium pricing reflects capital-intensive production and superior oxidation stability for extended drain intervals. OEMs factory-filling with 0W-20 and 5W-30 grades drive fastest volume expansion.
- Bio-based Oil:Estolide and vegetable-derived base stocks offering biodegradability for environmentally sensitive applications.
- Re-refined Oil:Vacuum-distilled and hydrotreated used oils competing with virgin Group II in aftermarket segments.
Synthetic Oil climbs fastest as OEM drain interval mandates harden. Mineral Oil defends volume leadership through fleet aftermarket demand.
Application:
Customer type fragmentation separates specification-intensive aerospace from price-sensitive marine bulk purchasing.
- Aerospace:Synthetic turbine oils meeting SAE AS5780 and MIL-PRF-23699 standards for jet engine lubrication. Formulations require thermal stability above 200°C and low coking tendency. Boeing and Airbus assembly lines in Washington state and Alabama drive factory-fill demand, with MRO facilities in Oklahoma and Arizona sustaining aftermarket volumes.
- Automotive:Passenger car and heavy-duty truck lubricants representing the largest volume pool. ILSAC GF-6 and API SP specifications govern gasoline engine oils, while API CK-4 and FA-4 cover diesel powertrains. California's LEV IV emissions rules cascade into viscosity grade requirements across the continent.
- Marine:Cylinder oils and system lubricants for two-stroke and four-stroke marine diesel engines.
- Manufacturing:Metalworking fluids, quench oils, and machinery lubricants serving discrete and process industries.
Automotive commands current revenue concentration. Aerospace offers steepest expansion trajectory through narrowbody production ramp-ups.
End User:
Geography determines channel structure, with OEM factory-fill contracts concentrating in manufacturing states and aftermarket distribution fragmenting across service bay networks.
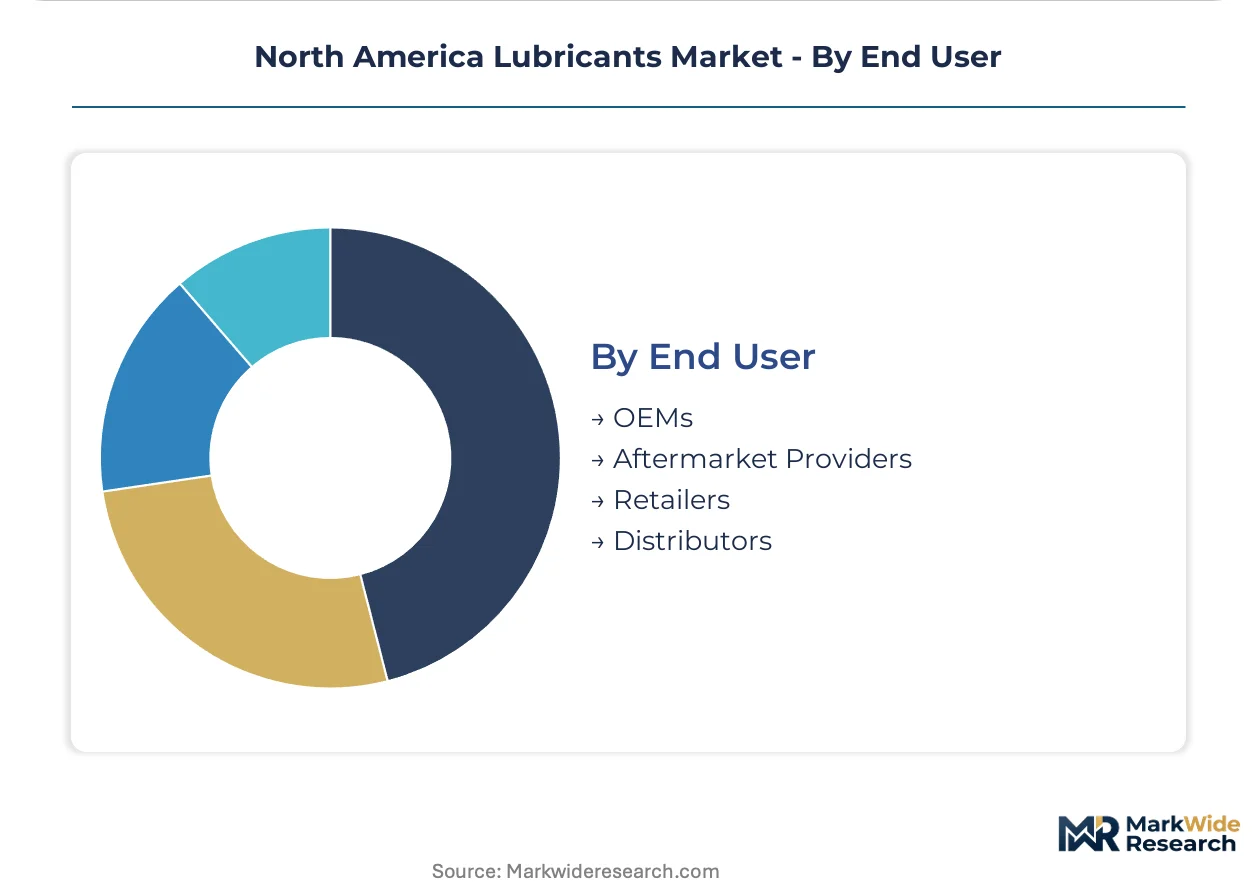
- OEMs:Original equipment manufacturers specifying factory-fill lubricants for new vehicle and machinery production. Ford's Dearborn Truck Plant, GM's Arlington Assembly, and Tesla's Austin Gigafactory run dedicated bulk blending agreements. Qualification cycles of 18-24 months create switching costs that entrench incumbent suppliers.
- Aftermarket Providers:Independent quick-lube chains, fleet maintenance shops, and dealer service departments. Valvoline Instant Oil Change and Jiffy Lube locations across Texas and Ohio convert installed vehicle populations into recurring revenue. Fleet operators extending drain intervals to 50,000+ miles compress transaction frequency but raise per-unit synthetic penetration.
- Retailers:Auto parts stores and mass merchants stocking consumer DIY quart and gallon containers.
- Distributors:Industrial supply houses and lubricant jobbers serving manufacturing accounts with bulk delivery.
OEMs anchor premium formulation development. Aftermarket Providers capture volume scale through service bay density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refiners along the U.S. Gulf Coast exploit lower environmental compliance costs versus European counterparts, drawing Group III base oil investment away from higher-regulation jurisdictions. This regulatory arbitrage concentrates synthetic feedstock capacity in Texas and Louisiana, positioning the region to supply formulation demand across the continent.
United States
Heavy-duty fleet operators in the Great Lakes corridor now mandate 50,000-mile drain intervals, forcing blenders toward Group III and PAO base stocks. The EPA's Phase 3 greenhouse gas standards for model year 2027+ trucks reward lower-viscosity 0W-20 and 5W-30 formulations. Detroit's automotive stamping cluster sustains bulk demand for high-performance metalworking fluids and hydraulic oils.
Canada
Alberta's oil sands mining and SAGD operations require extreme-duty open-gear and wire-rope lubricants for shovels and draglines operating in abrasive, sub-zero conditions. Environment and Climate Change Canada coordinates emissions regulations with the U.S. EPA, creating cross-border specification alignment for factory-fill contracts. Calgary and Edmonton serve as distribution hubs for specialized mining lubricants commanding 40-60% price premiums.
Mexico
Automotive OEMs in Nuevo León and the Bajío Region are expanding assembly capacity, drawing just-in-time blending operations from U.S. suppliers. Mexico's energy regulator CRE oversees fuel quality standards that indirectly shape lubricant additive requirements for domestic consumption. Querétaro's aerospace cluster generates specification-intensive demand for synthetic turbine oils meeting SAE AS5780 standards.
North America Lubricants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electric vehicle thermal fluid specialization and bio-based formulation niches. The market structures around three tiers: integrated oil majors with captive refinery-to-bladder footprints, independent blenders with regional distribution density, and specialized formulators serving aerospace or food-grade applications. Competitive dynamics center on backward integration into additive technology and strategic partnerships with OEMs for factory-fill qualification.
Among integrated oil majors, ExxonMobil Corporation and Chevron Corporation exemplify the upstream-captive archetype with Gulf Coast refinery positions securing Group III feedstock access. Valvoline Inc. occupies the service-bay-focused tier, converting installed vehicle populations into recurring revenue through quick-lube network penetration. These three entities represent distinct competitive vectors: feedstock security, manufacturing scale, and downstream channel control.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| Shell plc |
| TotalEnergies SE |
| BP p.l.c. |
| Phillips 66 |
| Valvoline Inc. |
| Fuchs Petrolub SE |
| Petro-Canada Lubricants |
| Others |
Value Network & Pricing Analysis
EPA Phase 3 greenhouse gas standards gate qualified supply and premium-tier pricing access for lower-viscosity synthetic formulations, with OEM factory-fill contracts commanding 15-25% markups over aftermarket equivalents. Blenders lacking Group III base oil security face margin compression as fleet operators consolidate procurement around extended-drain synthetic packages.
Pricing Analysis
Distributor margin structures stratify across three performance tiers, with synthetic Group III formulations capturing premium positioning against mineral-based economy grades. Price differentiation hinges on API SP/ILSAC GF-6 certification status and direct OEM qualification, while cost compression in the aftermarket segment intensifies as re-refined base stocks expand Texas and California capacity. Fleet operators running 50,000-mile drain intervals exhibit lowest price sensitivity; independent quick-lube channels face acute margin pressure from national program contracts.
Supply Chain Analysis
Bulk liquid freight costs from U.S. Gulf Coast refineries to Great Lakes blending facilities anchor total delivered cost structures for North American supply. Feedstock security rests on Port Arthur and Baytown Group III hydrocracker output, with additive packages sourced from specialized chemical manufacturers in the U.S. Northeast and Europe. Single-source vulnerability concentrates around unplanned refinery outages; distribution runs through regional terminal networks serving automotive OEMs in Michigan and Ohio alongside mining operations in Alberta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America lubricants function as a regulatory compounder, with EPA Phase 3 fuel economy standards hardening demand for lower-viscosity synthetic formulations across the projection horizon.
For Market Incumbents: To counter re-refined base oil price erosion in the aftermarket segment, deepen captive additive technology through R&D partnerships with friction modifier specialists, and secure long-term Group III offtake agreements with Gulf Coast refiners expanding hydrocracker capacity. For New Entrants and Emerging Players: Begin with electric vehicle thermal fluid specialization targeting dielectric coolant factory-fill positions with emerging battery-electric truck OEMs, then extend into bio-based hydraulic fluids for food processing machinery in Wisconsin and Pennsylvania. For Investors and Strategic Acquirers: Roll-up economics work for regional blenders with dense quick-lube service bay networks because fleet procurement consolidation favors last-mile distribution density over formulation scale; watch for inflection when California LCFS credit monetization pathways standardize across state borders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Technology | Captive friction modifier R&D defends margin against API SP certification cost inflation. |
| Long-term Supply Agreement with Gulf Coast Refiners | Locked Group III base oil access insulates against unplanned hydrocracker outage risk. |
| Joint Venture for EV Thermal Fluid Development | Dielectric coolant qualification with Rivian or Lucid secures factory-fill positioning. |
| Acquisition of Regional Quick-Lube Network | Dense service bay footprint in Texas or Ohio converts installed vehicles into recurring revenue. |
| Green Manufacturing Transition to Bio-based Feedstocks | Estolide base oil production captures food-grade machinery specifications in Wisconsin. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each market derived through structured interviews with lubricant blenders, fleet maintenance directors at Class 8 trucking operators, OEM procurement managers in Detroit and Arlington, and additive technology R&D directors. Secondary validation draws from U.S. EPA regulatory filings, Environment and Climate Change Canada emissions standards, API licensing databases, and customs trade data on base oil imports. Bottom-up volume estimates triangulate against top-down refinery capacity utilization data.
Rate-of-change decomposition separates volume expansion from value growth across the projection horizon, modeling segmentation dimensions including base oil grade tier, application type, and end-user channel structure. CAGRs derive from regression analysis against historical OEM factory-fill contract volumes and fleet drain interval extension trends, with specific inputs capturing EPA Phase 3 implementation pace and electric vehicle thermal fluid adoption curves.
Several conditions sit outside the modeled scope, including unanticipated refinery outages, abrupt shifts in crude oil price differentials, and regulatory delays in California LCFS credit treatment for lubricant-derived fuel savings. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Vietnam Automotive Engine Oils Market
Lubricants
Malaysia Automotive Engine Oils Market
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Saudi Arabia Lubricants Market
Lubricants
Hydro Lubricants Market
Lubricants
Global Aerospace Lubricant Market
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
Cutting Fluid Market
Lubricants
Russia Automotive Lubricants Market
Lubricants
Neat Cutting Oil Market
Lubricants
Anti-Static Oil Market
Lubricants
Africa Commercial Vehicles Lubricants Market
Lubricants
Morocco Lubricants Market
Lubricants
Global Engineered Fluids Market
Lubricants
Bangladesh Lubricants Market
Lubricants
Singapore Lubricants Market