
 North America Glycerol Market | 2026-2036
North America Glycerol Market Size, Share, and Industry Trends Forecast 2026-2036
North America Glycerol Market Insights
Buyer concentration across North American pharmaceutical and personal care formulators is broadening as mid-sized cosmetic brands and regional food manufacturers diversify their glycerol sourcing beyond traditional large-volume contracts. ADM leverages its integrated oilseed processing footprint to capture downstream glycerol value across multiple grades. Cargill, Inc. sustains supply security through biofuel co-product streams from its North American biodiesel network. BASF SE anchors its position via technical-grade specialization for industrial epoxy and polyurethane intermediates.
Glycerol, also known as propane-1,2,3-triol, constitutes a viscous, hygroscopic polyol with a molecular weight of 92.09 g/mol, derived commercially from triglyceride hydrolysis, saponification, or transesterification in biodiesel production; its three hydroxyl groups confer solubility, humectancy, and reactivity essential to formulations across food preservation, drug delivery matrices, and alkyd resin synthesis. Pharmaceutical Grade glycerol commands premium positioning due to USP-NF compliance burdens and excipient qualification protocols, while Industrial Grade volumes dominate tonnage flows into epoxy chlorohydrin and propylene glycol feedstock channels. Food Grade applications maintain stable offtake through sweetener and moisture-retention functions in processed foods, though margin compression from commodity sweetener alternatives constrains pricing power in this segment.
The FDA enforces glycerol identity and purity standards under 21 CFR regulations, while the EPA monitors biodiesel co-product pathways that supply the bulk of North American refined glycerol; together these frameworks determine which production routes achieve commercial viability and which grades qualify for human-contact applications. Health Canada and PMRA coordinate cross-border equivalency for glycerol used in veterinary pharmaceuticals and agrochemical formulations, creating dual-compliance obligations for integrated North American suppliers. Stakeholders must track evolving EPA renewable fuel obligations and state-level low-carbon fuel standards, as policy shifts in biodiesel feedstock incentives directly alter refined glycerol availability and regional pricing dynamics.
Market Dynamics
Biodiesel co-product glycerol volumes are reshaping North American supply economics as renewable fuel mandates expand refinery output, creating structural oversupply in industrial grades while pharmaceutical and food-grade purification capacity lags behind quality demand.
Growth Catalysts
- Renewable Fuel Standard (RFS):EPA mandates under 40 CFR Part 80 expand biodiesel production across US Midwest refineries, flooding downstream glycerol markets with feedstock for refined grades.
- Personal care formulators:Clean-label cosmetics brands in California and New York are substituting petroleum-derived humectants with plant-based glycerol in skincare and haircare formulations.
- Transesterification yield improvements:Continuous processing upgrades at Iowa and Illinois biodiesel facilities are raising crude glycerol purity from 80% to 92%, reducing downstream refining costs.
Market Restraints
- Crude glycerol price volatility:Soybean oil feedstock costs swing with drought cycles in Argentina and Brazil, compressing margins for US refiners locked into annual supply contracts.
- Midwest supply concentration:Seventy percent of North American refined glycerol originates within 400 miles of Des Moines, creating single-point vulnerability to regional weather or logistics disruptions.
- Propylene glycol substitution:Industrial buyers in antifreeze and de-icing applications are switching to synthetic propylene glycol when glycerol premiums exceed 15% on spot markets.
Strategic Opportunities
- Mexico pharmaceutical manufacturing:FDA-registered maquiladoras near Tijuana and Juárez lack qualified glycerol excipient suppliers, creating import substitution potential for USP-grade producers.
- Carbon capture glycerol synthesis:Emerging electrochemical reduction of CO₂ to glycerol at Texas and Alberta pilot plants could bypass agricultural feedstock constraints entirely.
- Direct-to-formulator e-commerce:Mid-sized cosmetic brands are bypassing traditional distributors through specialty chemical platforms, opening margin capture for qualified refiners.
Industry Challenges
- Pharmacopeial certification timelines:USP-NF excipient qualification requires 18-24 months of stability documentation, blocking rapid market entry for new refined glycerol entrants.
- Biofuel policy uncertainty:Congressional debates over RFS blending obligations create investment paralysis for planned glycerol purification capacity expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Glycerol Market |
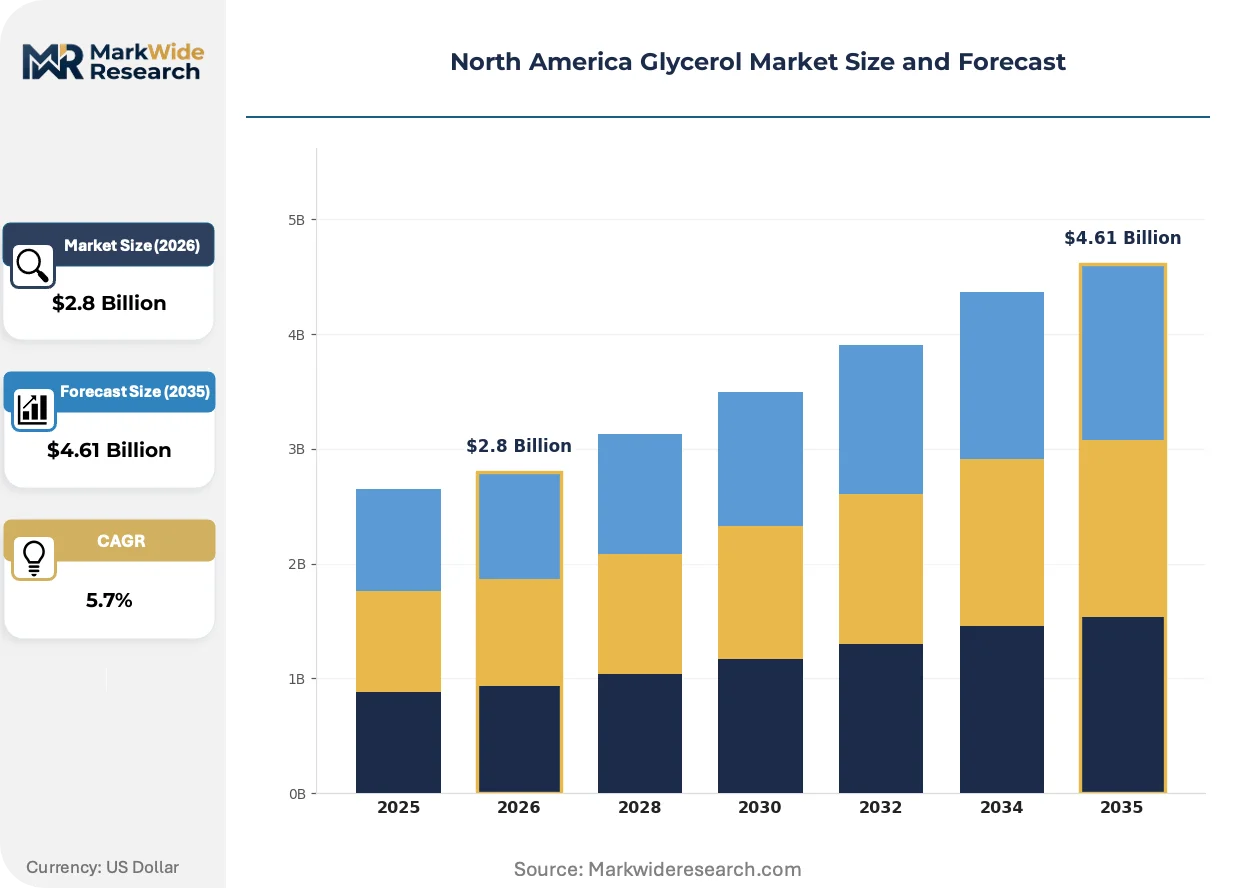
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceutical Grade, Food Grade, Industrial Grade, Cosmetic Grade Application: Food & Beverage, Pharmaceuticals, Personal Care, Industrial Processing End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Chemical Producers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | ADM, Cargill, Inc., BASF SE, Dow, Emery Oleochemicals, KLK OLEO, Oleon NV, Wilmar International Ltd., Procter & Gamble Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Glycerol Market Trends and Innovations
Digital process control and molecular purification technologies are compressing quality variance in glycerol production, while regulatory fragmentation between US and Canadian standards forces dual-track compliance investments from integrated suppliers.
Membrane filtration systems with nanofiltration and reverse osmosis stages are automating the removal of residual methanol, salts, and odor compounds from crude biodiesel glycerol. Personal care and pharmaceutical formulators in New Jersey and Ontario are specifying membrane-refined grades for 95% of new product launches. This automation is collapsing the traditional batch distillation bottleneck and enabling continuous production economics at sub-10,000-ton annual scales.
Health Canada's ICH Q3C residual solvent guidelines are diverging from USP-NF monograph limits on ethylene glycol and diethylene glycol impurities, forcing cross-border suppliers to maintain dual analytical protocols. The 2024 PMRA update for veterinary pharmaceutical excipients added glycerol-specific identification testing requirements. Canadian animal health manufacturers are responding by qualifying dedicated US-sourced glycerol streams rather than blending North American pooled supply.
Mid-sized food manufacturers are consolidating glycerol purchasing through cooperative buying groups rather than individual direct contracts with refiners. These purchasing cooperatives in the Great Lakes and Pacific Northwest regions are extracting volume-tier pricing previously reserved for multinational CPG brands. The shift is most pronounced in bakery and confectionery segments, where glycerol functions as both humectant and crystallization inhibitor in sugar-free formulations.
North America Glycerol Market Segmentation
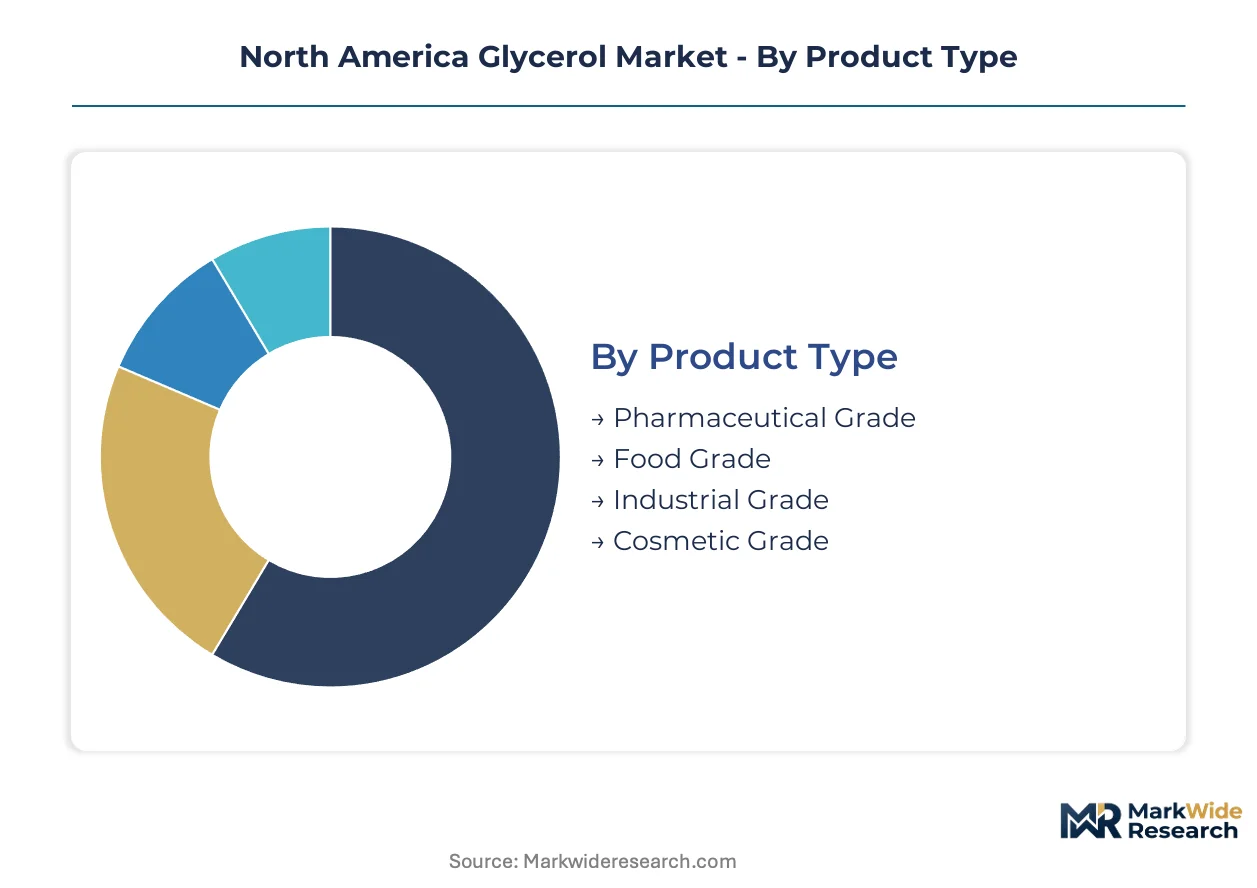
Glycerol segmentation in North America reflects divergent purity requirements and regulatory burdens across end-use sectors. Grade differentiation determines pricing architecture, with pharmaceutical and food applications commanding certification premiums while industrial volumes scale through biodiesel co-product economics.
Product Type:
Industrial Grade dominates tonnage flows, yet Pharmaceutical Grade captures disproportionate value through USP-NF compliance barriers.
- Pharmaceutical Grade:USP-NF monograph compliance mandates residual solvent limits below 0.1% for ethylene glycol and diethylene glycol. FDA 21 CFR identity standards force dedicated purification trains at Iowa and Illinois refineries. Demand concentrates in parenteral formulations and ophthalmic solutions where impurity thresholds are most stringent.
- Industrial Grade:Crude glycerol from Midwest biodiesel facilities typically assays 80-92% purity, suitable for epoxy chlorohydrin and propylene glycol feedstock synthesis. Price volatility tracks soybean oil feedstock costs from Argentina and Brazil, compressing margins for refiners locked into annual supply contracts.
- Food Grade:FEMA GRAS status and moisture-retention functionality sustain stable offtake in processed foods, though margin compression from commodity sweetener alternatives constrains pricing power.
- Cosmetic Grade:Clean-label positioning in California and New York skincare brands drives substitution of petroleum-derived humectants with plant-based glycerol certified through RSPO mass balance schemes.
Mature deployment sits with Industrial Grade. Newer deployment is concentrated in Pharmaceutical Grade as FDA tightens excipient documentation requirements.
Application:
Application segmentation tracks regulatory intensity, with human-contact uses demanding pharmacopeial documentation that industrial processing bypasses.
- Food & Beverage:Humectant and crystallization inhibitor functions in sugar-free bakery and confectionery segments sustain volume. Great Lakes and Pacific Northwest purchasing cooperatives are extracting volume-tier pricing previously reserved for multinational CPG brands.
- Pharmaceuticals:Excipient and API applications require 18-24 months of USP-NF stability documentation, blocking rapid market entry for new refined glycerol entrants. FDA-registered maquiladoras near Tijuana and Juárez lack qualified suppliers, creating import substitution potential.
- Personal Care:New Jersey and Ontario formulators specify membrane-refined grades for 95% of new product launches, automating removal of residual methanol and odor compounds through nanofiltration systems.
- Industrial Processing:Antifreeze and de-icing buyers switch to synthetic propylene glycol when glycerol premiums exceed 15% on spot markets, constraining pricing upside in seasonal demand peaks.
Volume leadership belongs to Industrial Processing. Value capture is climbing fastest in Pharmaceuticals as biosimilar and complex generic pipelines expand excipient qualification requirements.
End User:
End-user concentration varies by procurement sophistication, with pharmaceutical and chemical producers leveraging long-term contracts against spot-market exposure in food and cosmetics.
- Food Manufacturers:Mid-sized bakery and confectionery producers are consolidating purchasing through cooperative buying groups rather than individual direct contracts with refiners.
- Pharmaceutical Companies:Parenteral drug manufacturers demand dedicated supply streams with full batch traceability, forcing refiners to segregate production campaigns.
- Cosmetic Brands:Clean-label positioning drives specification of RSPO-certified glycerol, with California and New York brands bypassing traditional distributors through specialty chemical platforms.
- Chemical Producers:Epoxy and polyurethane intermediate manufacturers absorb the bulk of industrial-grade volumes, with procurement indexed to soybean oil futures to hedge feedstock volatility.
Contract discipline is most advanced with Pharmaceutical Companies. Spot-market exposure concentrates with Cosmetic Brands as direct-to-formulator e-commerce platforms fragment traditional distribution.
Distribution Channel:
Channel structure reflects order-size economics and documentation requirements, with direct sales dominating pharmaceutical qualification while distributors handle fragmented food and cosmetic accounts.
- Direct Sales:Pharmaceutical and large chemical producers negotiate annual contracts with refiners, locking in volume commitments against price caps tied to agricultural feedstock indices.
- Distributors:Regional chemical distributors aggregate demand from mid-sized food manufacturers and cosmetic formulators, maintaining inventory positions in Chicago and Houston terminals.
- Wholesalers:Bulk terminal operators in the Midwest handle industrial-grade spot transactions, with 70% of refined glycerol originating within 400 miles of Des Moines creating logistics concentration.
- Online Retail:Specialty chemical platforms enable mid-sized cosmetic brands to bypass traditional distributors, opening margin capture for qualified refiners willing to manage smaller batch sizes.
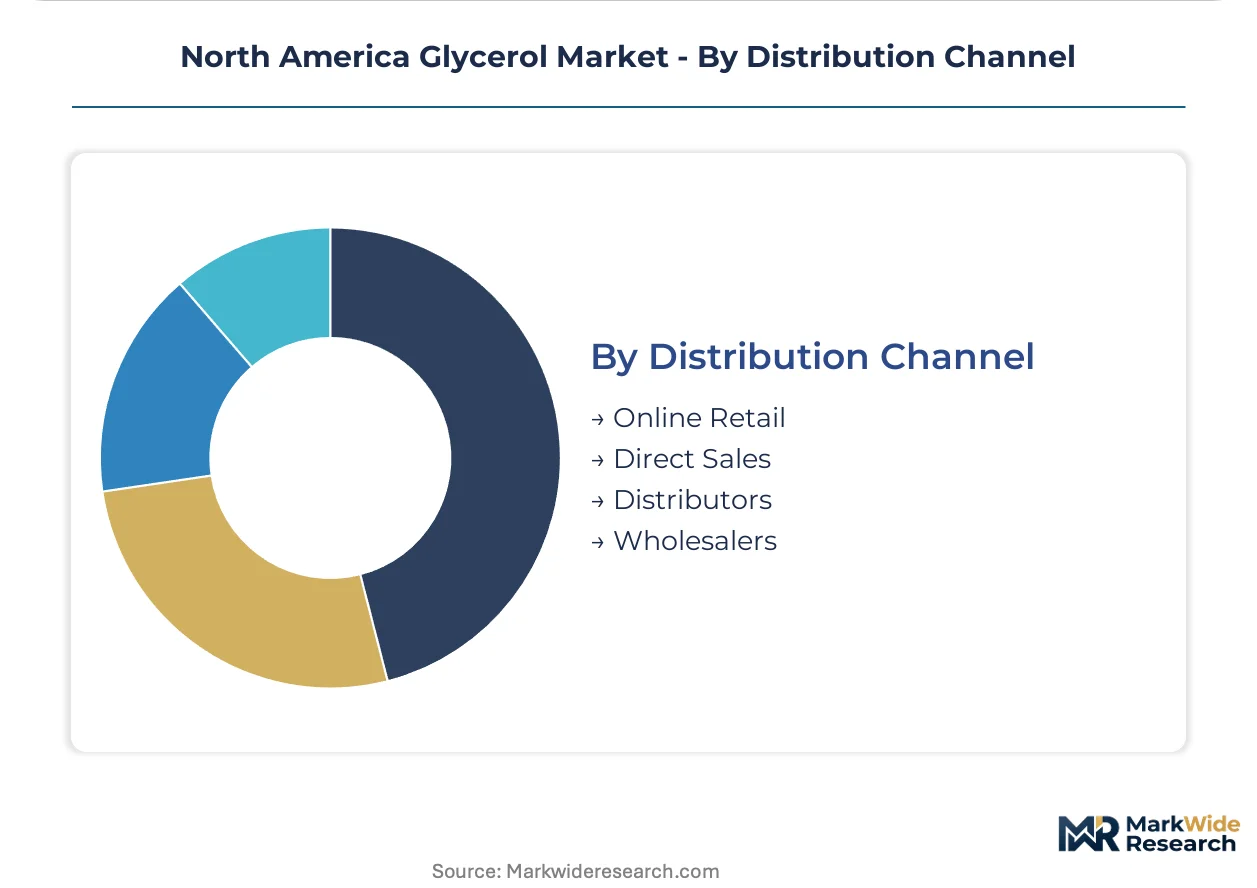
Established infrastructure sits with Distributors. Channel expansion is gaining share fastest with Online Retail as procurement digitization penetrates mid-market formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soybean crushing corridors across Iowa and Illinois anchor North American glycerol supply, with biodiesel co-product streams feeding integrated refineries throughout the Midwest.
United States
Pharmaceutical excipient demand from New Jersey and California formulators drives USP-grade purification investments. FDA 21 CFR identity standards tighten documentation burdens for parenteral drug applications. Iowa and Illinois biodiesel clusters near Des Moines process 70% of regional refined output through continuous transesterification upgrades.
Canada
Veterinary pharmaceutical manufacturers in Ontario and Quebec seek dedicated US-sourced glycerol streams after PMRA's 2024 excipient testing update. Health Canada's ICH Q3C residual solvent guidelines diverge from USP-NF limits, forcing dual analytical protocols. Toronto-area animal health producers now segregate supply chains rather than pooling North American material.
Mexico
FDA-registered maquiladoras near Tijuana and Juárez lack qualified glycerol excipient suppliers for biosimilar production. COFEPRIS alignment with US pharmacopeial standards creates compliance pathways for cross-border USP-grade imports. Baja California pharmaceutical manufacturing zones are expanding sterile formulation capacity without domestic glycerol refinement infrastructure.
California
Clean-label cosmetic brands in Los Angeles and San Diego substitute petroleum-derived humectants with RSPO-certified plant-based glycerol. CARB low-carbon fuel standards indirectly boost biodiesel output and downstream glycerol availability. Personal care formulators specify membrane-refined grades through direct specialty chemical platforms, bypassing traditional distributors.
Texas
Epoxy and polyurethane intermediate producers along the Gulf Coast absorb industrial-grade volumes indexed to soybean oil futures. Emerging electrochemical CO₂-to-glycerol pilot plants near Houston aim to bypass agricultural feedstock constraints entirely. Houston bulk terminals handle spot transactions when Midwest logistics face weather disruptions.
North America Glycerol Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue carbon-capture synthesis and membrane-refined specialty grades. The market structures around three tiers: integrated agribusiness conglomerates with captive oilseed processing, dedicated oleochemical specialists with technical-grade focus, and biodiesel operators monetizing crude glycerol streams. Competitive moves concentrate on backward integration into oilseed crushing and geographic expansion toward pharmaceutical manufacturing zones.
Among integrated agribusiness conglomerates, ADM leverages its North American oilseed footprint to capture downstream glycerol value across multiple purity grades. Cargill, Inc. sustains supply security through biofuel co-product streams. BASF SE anchors the technical-grade specialization tier for industrial epoxy and polyurethane intermediates.
| Leading Market Players |
|---|
| ADM |
| Cargill, Inc. |
| BASF SE |
| Dow |
| Emery Oleochemicals |
| KLK OLEO |
| Oleon NV |
| Wilmar International Ltd. |
| Procter & Gamble Chemicals |
| Others |
Pricing and Supply Chain Analysis
Soybean oil futures on the Chicago Board of Trade serve as the primary cost anchor for North American glycerol, cascading through biodiesel co-product economics into tiered grade premiums that separate pharmaceutical USP-NF certification from industrial feedstock volumes.
Pricing Analysis
Certificate-of-analysis bundling distinguishes pharmaceutical-grade contracts from spot industrial transactions. Three-tier pricing structure across pharmaceutical, food, and industrial grades reflects purification intensity and documentation burden. Cost compression in industrial grades is intensifying because Argentine drought cycles spike soybean oil feedstock costs. Food manufacturers in Great Lakes purchasing cooperatives exhibit highest price sensitivity, while parenteral drug manufacturers accept premium lock-ins for batch traceability.
Supply Chain Analysis
Crude glycerol supply rests on Iowa and Illinois biodiesel clusters processing Midwest soybean crush, with Canadian refiners drawing from the same Des Moines-radius concentration. Soybean oil, methanol, and catalyst chemicals constitute the core input dependencies. Single-point vulnerability to Mississippi River logistics disruptions threatens 70% of regional refined output. Distribution runs through Chicago and Houston bulk terminals aggregating spot transactions for chemical producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration automation is displacing batch distillation legacy, compressing quality variance and enabling continuous production economics at sub-10,000-ton scales.
For Market Incumbents: Deploy backward integration into oilseed crushing to secure feedstock cost control against Argentine supply volatility. Lock pharmaceutical manufacturers into dedicated supply streams with full batch traceability before CO₂-to-glycerol electrochemical pilots achieve commercial scale. Capacity expansion in New Jersey and California purification corridors reinforces excipient qualification barriers. For New Entrants and Emerging Players: COFEPRIS alignment with US pharmacopeial standards in Mexico opens a window for USP-grade import substitution at FDA-registered maquiladoras near Tijuana and Juárez. Target veterinary pharmaceutical manufacturers in Ontario and Quebec seeking segregated US-sourced streams after PMRA's excipient testing update. Direct-to-formulator e-commerce platforms offer the most penetrable go-to-market angle for mid-sized cosmetic brands bypassing traditional distributors. For Investors and Strategic Acquirers: Distressed-cycle entries favor membrane-refined specialty grade producers in Texas and Alberta with carbon-capture synthesis pilots. Five-to-ten year viability hinges on electrochemical CO₂ reduction achieving cost parity with agricultural feedstock routes. Watch EPA renewable fuel obligation debates as the inflection signal for biodiesel co-product glycerol availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | ADM and Cargill leverage captive soybean processing to stabilize feedstock costs against Argentine drought cycles. |
| Membrane Filtration Capacity Expansion | Nanofiltration and reverse osmosis systems automate impurity removal for New Jersey pharmaceutical formulators. |
| USP-NF Certification Investment | Eighteen-to-twenty-four month stability documentation blocks rapid entry, entrenching incumbent excipient positions. |
| Direct-to-Formulator E-Commerce Launch | Specialty chemical platforms enable margin capture from California clean-label cosmetic brands. |
| Cross-Border Mexico Supply Agreement | COFEPRIS-aligned imports address qualified glycerol scarcity at Tijuana and Juárez biosimilar facilities. |
Research Methodology
Document review covered FDA 21 CFR filings, EPA renewable fuel standard dockets, USP-NF monograph updates, and biodiesel production databases, complemented by interviews with Iowa refinery operations managers, New Jersey pharmaceutical formulation directors, California cosmetic brand procurement leads, and Chicago chemical distribution executives. Secondary validation drew from SEC 10-K disclosures, customs trade flow records, and Health Canada ICH Q3C guideline revisions. Bottom-up capacity modeling and top-down demand segmentation were triangulated against cross-referenced stakeholder inputs.
Historical production volume trajectories were cross-referenced against panel-based capacity expansion announcements and feedstock price elasticity assumptions across the projection horizon. Segmentation dimensions modeled include grade tier, end-use industry, and regional production hub. CAGRs were derived from fitted trend extrapolation adjusted for policy scenario variants. Industry-specific forecast inputs incorporated transesterification yield improvement curves and renewable fuel mandate compliance trajectories.
Caveats apply where EPA blending obligation debates, Mississippi River logistics disruptions, or electrochemical synthesis breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions about biodiesel co-product economics and pharmacopeial certification timelines. A small set of named triggers—policy shifts, feedstock volatility, and purification technology disruption—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Internal Olefins Market
Bulk Chemicals
Zinc Chloride Market
Bulk Chemicals
Clomiphene Citrate Market
Bulk Chemicals
Global Ammonium Phosphate Market
Bulk Chemicals
Sodium Silicate Market
Bulk Chemicals
Global Quinine Sulphate Market
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
Global Butyl Acrylate Market
Bulk Chemicals
GCC Calcium Chloride Market
Bulk Chemicals
India Chlorine Market
Bulk Chemicals
Global Ammonium Sulphate Market
Bulk Chemicals
Borates Market
Bulk Chemicals
Sodium Dichromate Market
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
Global 2-Ethylhexanoic Acid Market
Bulk Chemicals
Electronic Batio3 Powder Market