
 Global Lubricating Oil Additives Market | 2026-2036
Global Lubricating Oil Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lubricating Oil Additives Market Outlook
Modular additive bundling is hardening as the dominant procurement model, with buyers favoring pre-formulated packages over single-component sourcing to reduce blending complexity and inventory overhead. The Lubrizol Corporation leverages its integrated additive technology platforms to anchor long-term supply relationships with major lubricant blenders. BASF SE sustains competitive positioning through specialized friction modifier and antioxidant portfolios tailored to electric vehicle thermal management fluids. Infineum International Limited dominates marine and heavy-duty diesel segments through backward integration into key detergent chemistries.
Lubricating oil additives comprise chemically engineered compounds—typically organometallic complexes, polymeric dispersants, and sulfur-phosphorus anti-wear chemistries—blended at 0.1% to 30% treat rates to enhance base oil performance under thermal oxidative stress, contamination loading, and boundary lubrication regimes. Their primary purpose is to extend equipment life, reduce fuel consumption, and enable compliance with tightening emissions and efficiency standards. Viscosity index improvers represent the largest volume category due to universal deployment across multigrade engine oils, though friction modifiers command premium pricing as OEMs specify lower high-temperature high-shear formulations for fuel economy targets. Dispersants and detergents together constitute the core deposit-control backbone, with marine and industrial end users driving specification upgrades as equipment manufacturers extend warranty intervals.
The EPA regulates additive components through fuel and lubricant emissions certification pathways, while REACH mandates full substance registration and hazard communication across European supply chains. China's MEE enforces GB standards for lubricant biodegradability and heavy-metal content, creating divergent compliance costs for multinational formulators. Japan's METI coordinates with JIS standards bodies to align additive performance benchmarks with domestic automotive and precision machinery requirements. Stakeholders must monitor regulatory divergence between major economies as carbon-border adjustment mechanisms and chemical sustainability disclosures reshape formulation disclosure obligations and regional sourcing strategies.
Market Dynamics
Automotive OEMs are tightening additive specifications for extended-drain engine oils, forcing formulators to reconcile performance longevity with biodegradable chemistries under divergent regulatory regimes across the EU, China, and the United States.
Growth Catalysts
- Extended-drain specifications:OEMs in Germany and Japan now mandate 30,000-kilometer oil change intervals, requiring thermally robust dispersant and antioxidant packages that command premium treat rates.
- REACH chemical registration:Full substance disclosure mandates under ECHA frameworks are accelerating substitution toward polymeric ashless dispersants with superior environmental profiles.
- Marine cylinder lubrication:IMO 2020 sulfur caps have intensified demand for high-base-number detergent systems in two-stroke marine engines transiting Singapore and Rotterdam.
Market Restraints
- Group III+ base oil supply concentration:Middle Eastern and Korean refinery expansions have tightened feedstock availability for additive solubility, squeezing formulator margins.
- ZDDP substitution limits:Sulfur-phosphorus anti-wear chemistry faces technical boundaries in low-viscosity formulations below 0W-16, constraining wear protection in downsized turbocharged engines.
- MEE biodegradability enforcement:China's GB standards for heavy-metal content and aquatic toxicity are fragmenting formulation portfolios, raising compliance costs for multinational suppliers.
Strategic Opportunities
- Electric vehicle thermal fluids:Battery pack and e-axle cooling circuits require dielectric friction modifiers and corrosion inhibitors with thermal stability above 150°C, opening formulation white space.
- India industrial lubricant upgrade:BIS certification alignment with ISO 6743 standards is accelerating specification convergence in mining and cement sectors previously served by unadditized base stocks.
- Modular additive bundling:Pre-formulated packages reduce blender inventory complexity, creating channel power for integrated technology platforms serving mid-tier lubricant manufacturers.
Industry Challenges
- Organometallic synthesis expertise:Phosphorus pentasulfide handling and molybdenum dithiocarbamate chemistry require specialized process safety capabilities scarce outside legacy additive hubs.
- Dual-carbon compliance timelines:Chinese blenders must simultaneously satisfy MEE biodegradability deadlines and provincial carbon-intensity targets, compressing reformulation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lubricating Oil Additives Market |
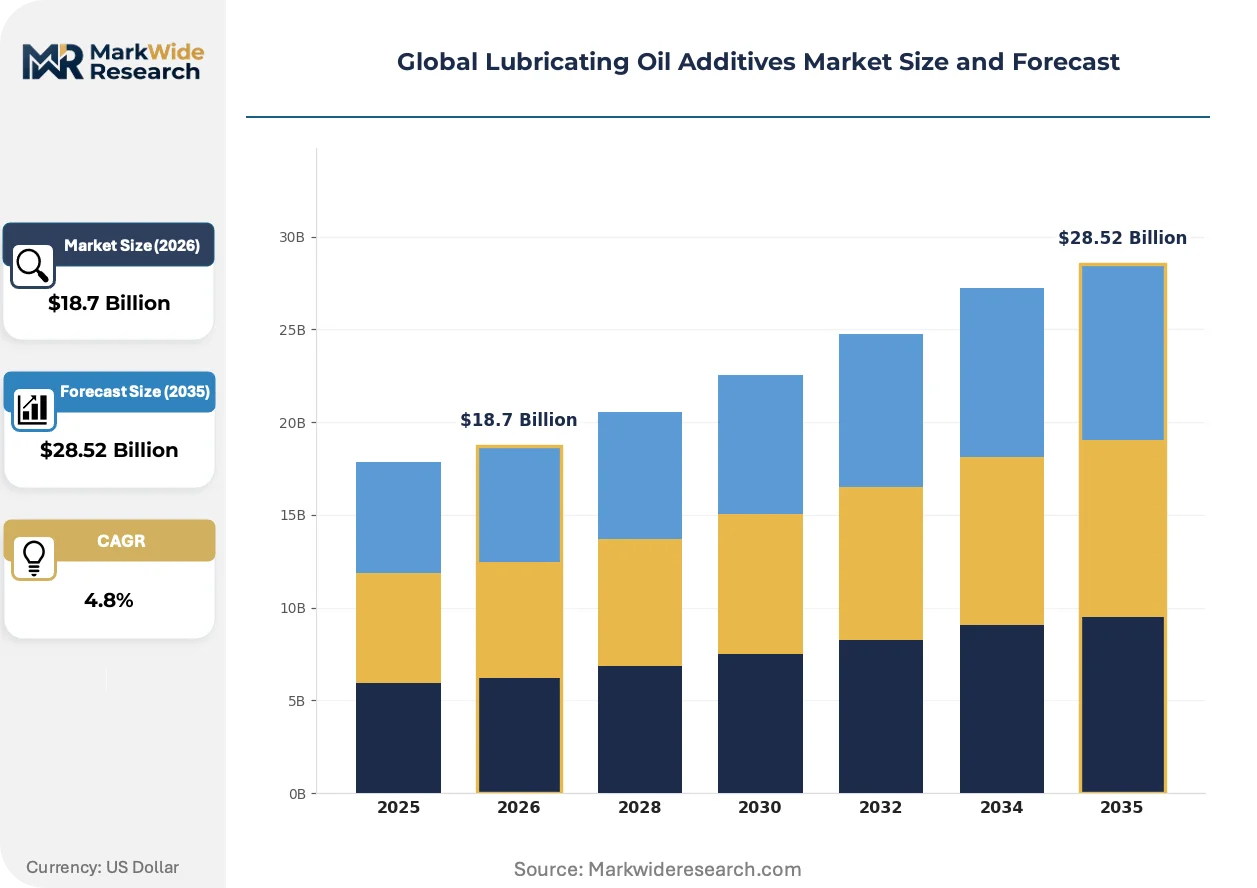
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detergents, Dispersants, Antioxidants, Friction Modifiers Functionality: Viscosity Index Improvers, Anti-Wear Agents, Corrosion Inhibitors, Seal Compatibility Agents End User: Automotive, Marine, Industrial, Aerospace Distribution Channel: Direct Sales, Distributors, Retailers, E-commerce |
| Companies Covered | The Lubrizol Corporation, Chevron Oronite Company LLC, BASF SE, Afton Chemical Corporation, Infineum International Limited, Evonik Industries AG, LANXESS AG, Croda International Plc, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lubricating Oil Additives Market Strategic Shifts
Formulation science is pivoting toward electrochemical compatibility and lifecycle transparency, with additive architectures re-engineered for thermal management fluids and sustainability disclosure requirements.
Ionic liquid friction modifiers are electrifying boundary lubrication regimes in hybrid transmission fluids. Japanese OEMs have adopted these chemistries for dual-clutch and e-CVT applications since 2022. The technology is electrifying conventional ester-based formulations out of high-torque electrified powertrains.
REACH Article 33 disclosure obligations now mandate full supply chain communication for SVHC-containing additives above 0.1% concentration. Industrial lubricant blenders face reformulation costs or substitution toward polymeric alternatives. Marine and metalworking segments in Hamburg and Antwerp are accelerating ashless hydraulic fluid development.
Specification-driven procurement now dominates additive selection, with lubricant blenders outsourcing technical validation to OEM-certified additive packages. Single-component sourcing has collapsed among mid-tier blenders in China and India. This pattern is most visible in the Sinopec and Indian Oil distribution networks, where captive additive production is displacing merchant market volumes.
Global Lubricating Oil Additives Market Segmentation
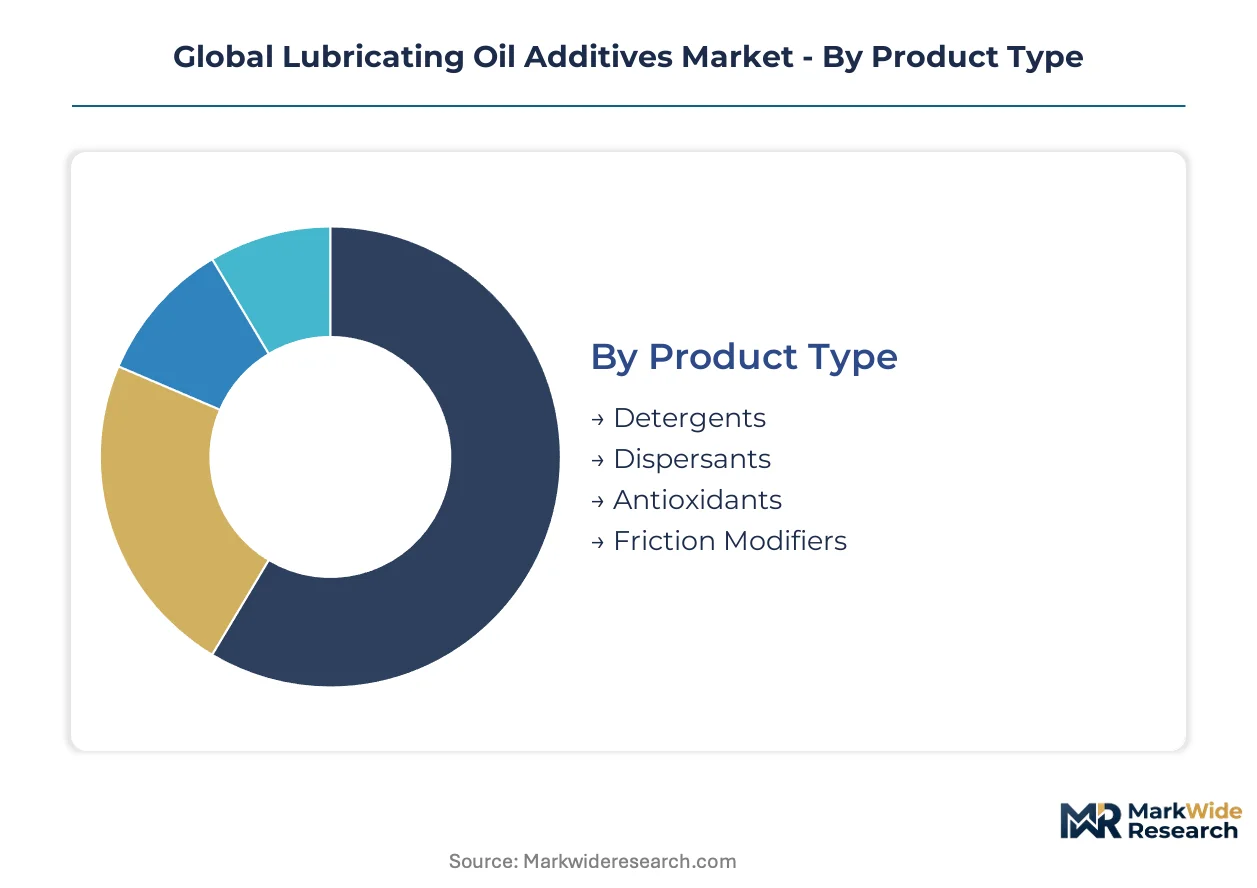
Additive selection follows specification cascades from OEM drain interval extensions and regional emissions mandates. Procurement patterns diverge sharply between integrated blenders with captive formulation capabilities and merchant-market buyers dependent on pre-packaged bundles.
Product Type:
Replacement cycles for high-performance engine oils are compressing reformulation timelines across all four chemistries, with treat rate optimization now the primary cost lever for blenders.
- Detergents:Alkaline earth metal sulfonates and phenates neutralize acidic combustion byproducts in extended-drain formulations. Marine cylinder lubrication demand concentrates in Singapore and Rotterdam as IMO sulfur caps tighten, with high-base-number systems commanding premium positioning.
- Dispersants:Polymeric ashless architectures suspend soot and oxidation products in diesel and gasoline engine oils. REACH disclosure mandates are accelerating substitution from boron-containing chemistries toward nitrogen-based alternatives in German and French formulation plants.
- Antioxidants:Hindered phenols and amines interrupt radical chain reactions under thermal oxidative stress. Treat rates are rising in Japanese OEM specifications for 30,000-kilometer service intervals.
- Friction Modifiers:Organomolybdenum compounds and fatty acid esters reduce boundary friction in fuel-economy formulations. Low-viscosity 0W-8 and 0W-12 grades for hybrid powertrains are expanding specification requirements.
Dispersants sit at the top of the volume ranking, with friction modifiers climbing the fastest as OEM fuel economy targets tighten.
Functionality:
Cost tier differentiation separates commodity viscosity modifiers from specialty chemistries commanding formulation premiums in electrified powertrains.
- Viscosity Index Improvers:Olefin copolymers and polymethacrylates enable multigrade performance across temperature extremes. Universal deployment in passenger car and heavy-duty engine oils sustains volume leadership despite margin compression from Group III+ base oil integration.
- Anti-Wear Agents:Zinc dialkyldithiophosphates form protective tribofilms on cam and bearing surfaces. Technical boundaries in ultra-low-viscosity formulations below 0W-16 are constraining substitution timelines for sulfur-phosphorus chemistries in downsized turbocharged engines from German and Korean OEMs.
- Corrosion Inhibitors:Alkylsuccinic derivatives and amine-neutralized carboxylates protect ferrous and non-ferrous metals in circulating systems. E-axle thermal management fluids for battery electric vehicles require dielectric-compatible architectures with thermal stability above 150°C.
- Seal Compatibility Agents:Esters and aromatic amines maintain elastomer integrity in automatic transmission and hydraulic systems. Japanese precision machinery specifications are tightening swell and hardness retention requirements.
Viscosity index improvers dominate absolute volume, with corrosion inhibitors gaining share fastest from electric vehicle thermal fluid proliferation.
End User:
Application-specific specification divergence creates formulation portfolio fragmentation, with marine and aerospace segments demanding certified packages unavailable through standard merchant channels.
- Automotive:Passenger car motor oils and heavy-duty diesel formulations consume the majority of detergent-dispersant-antioxidant packages. Chinese domestic blenders are expanding captive additive production to serve Sinopec and private-label distribution networks.
- Marine:Two-stroke crosshead and four-stroke trunk piston engines require high-base-number cylinder and crankcase lubricants. Singapore and Rotterdam bunkering hubs are driving specification upgrades as IMO 2020 sulfur caps intensify deposit control requirements.
- Industrial:Hydraulic, compressor, and turbine oils serve mining, cement, and steel operations. India's BIS certification alignment with ISO 6743 standards is accelerating additive penetration in sectors previously served by unadditized base stocks.
- Aerospace:Gas turbine and piston engine oils demand synthetic ester base stocks with specialized anti-wear and thermal stability packages. AS5780 and SAE standards constrain supplier qualification to a narrow set of certified formulators.
Automotive sits at the top of the volume ranking, with marine climbing the fastest from IMO regulatory stringency in Asian and European bunkering corridors.
Distribution Channel:
Customer type stratification separates multinational blenders with direct technical relationships from mid-tier manufacturers dependent on distributor inventory and formulation support.
- Direct Sales:Integrated technology platforms anchor long-term supply agreements with major lubricant blenders. Technical validation outsourcing to OEM-certified packages is collapsing single-component sourcing among scale manufacturers.
- Distributors:Regional chemical distributors serve mid-tier blenders lacking in-house formulation expertise. Inventory consolidation and pre-packaged bundles are reducing blending complexity for independent lubricant manufacturers in India and Southeast Asia.
- Retailers:Automotive aftermarket channels move packaged consumer motor oils with specified additive claims. Shelf-space competition is tightening price transparency for premium synthetic formulations.
- E-commerce:Direct-to-blender platforms are emerging for standardized additive packages in fragmented markets. China's industrial procurement digitization is accelerating merchant market access for smaller formulation operations.
Direct sales sits at the top of the volume ranking, with e-commerce climbing the fastest from procurement digitization in Asian manufacturing corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The lubricating oil additives industry traces its modern scaling to post-war industrialization in the United States and Germany, where petrochemical complexes developed organometallic synthesis capabilities for engine oil formulations. Today, additive demand concentrates in manufacturing corridors where automotive OEMs and marine bunkering hubs drive specification upgrades.
United States
Extended-drain engine oil specifications from Detroit automakers are elevating treat rates for thermally robust dispersant packages. The EPA regulates additive components through fuel and lubricant emissions certification pathways, creating compliance costs for sulfur-phosphorus chemistries. Houston and Bay Area petrochemical clusters anchor detergent and dispersant production for North American blender networks.
Germany
German OEM mandates for 30,000-kilometer oil change intervals are accelerating antioxidant and dispersant specification upgrades. REACH Article 33 disclosure obligations now mandate full supply chain communication for SVHC-containing additives above 0.1% concentration. Hamburg and Antwerp marine corridors are driving high-base-number cylinder lubricant demand as IMO sulfur caps tighten.
China
Domestic lubricant blenders are expanding captive additive production to serve Sinopec and private-label distribution networks. The MEE enforces GB standards for lubricant biodegradability and heavy-metal content, fragmenting formulation portfolios for multinational suppliers. Yangtze River Delta chemical parks are concentrating organometallic synthesis capacity for ashless dispersant production.
Japan
Japanese OEMs have adopted ionic liquid friction modifiers for dual-clutch and e-CVT applications since 2022. METI coordinates with JIS standards bodies to align additive performance benchmarks with domestic automotive and precision machinery requirements. Kanto and Nagoya industrial corridors are specializing in low-viscosity fuel-economy formulations for hybrid powertrains.
India
BIS certification alignment with ISO 6743 standards is accelerating additive penetration in mining and cement sectors previously served by unadditized base stocks. The country's national chemical regulator is tightening disclosure requirements for imported additive packages. Gujarat and Maharashtra industrial zones are attracting modular additive bundling operations for mid-tier lubricant manufacturers.
Global Lubricating Oil Additives Market Competitive Environment
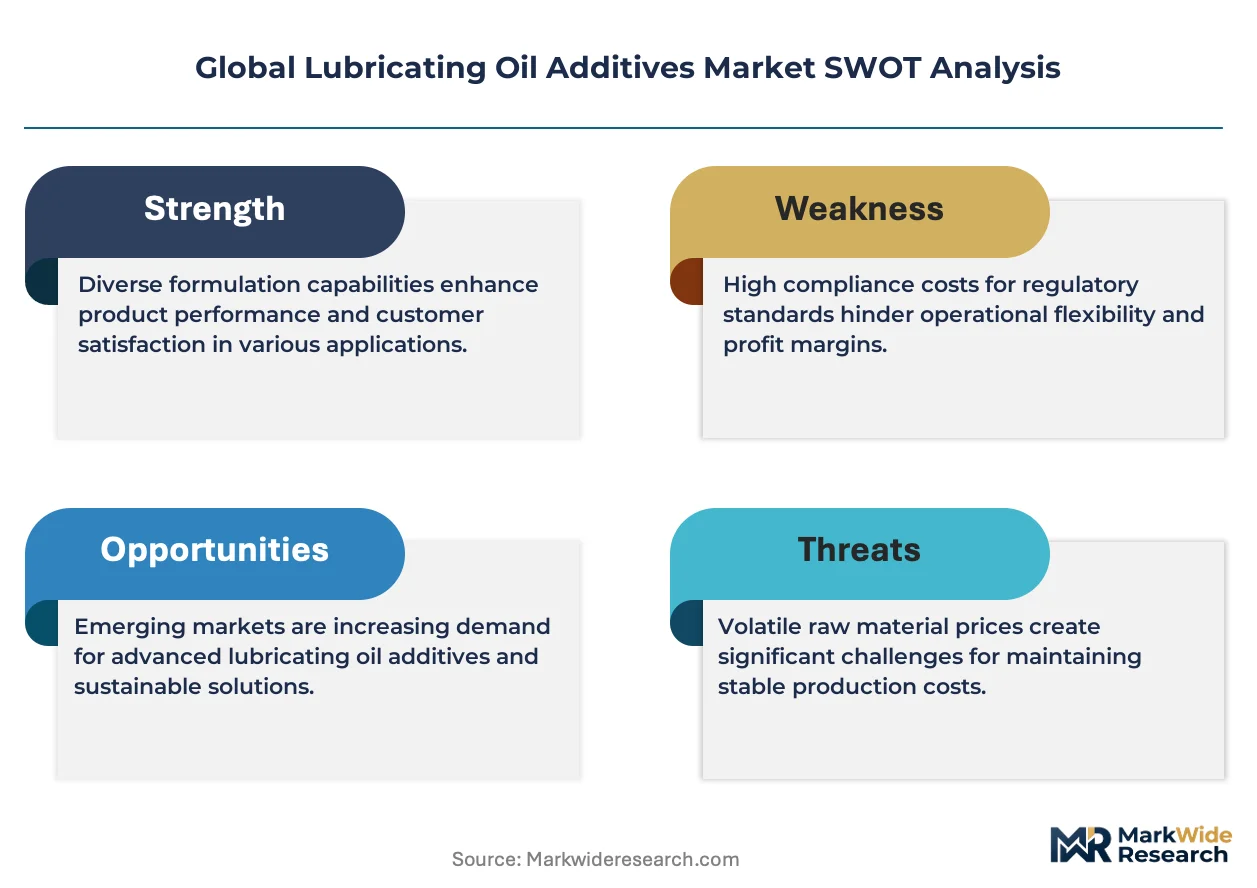
Premium-margin players sit above commodity-margin players across formulation complexity and OEM certification depth, with integrated technology platforms commanding long-term supply relationships. The vendor base stratifies into three tiers: multinational chemical conglomerates with captive additive divisions, specialized additive houses with backward integration into key chemistries, and regional formulators serving merchant markets. Two dominant competitive moves are reshaping positioning: strategic partnerships between additive suppliers and base oil refiners to secure feedstock integration, and portfolio diversification into electric vehicle thermal management fluids to capture specification white space.
Within the integrated technology tier, The Lubrizol Corporation, BASF SE, and Infineum International Limited exemplify divergent archetypes. The Lubrizol Corporation occupies a position anchored in long-term supply relationships with major lubricant blenders through modular additive bundling. BASF SE represents the specialized friction modifier and antioxidant portfolio approach tailored to emerging thermal management requirements. Infineum International Limited sits within the marine and heavy-duty diesel segment dominance archetype through upstream control into key detergent chemistries. These three entities collectively illustrate how geographic origin and corporate structure map to competitive positioning without overlapping strategic territory.
| Leading Market Players |
|---|
| The Lubrizol Corporation |
| Chevron Oronite Company LLC |
| BASF SE |
| Afton Chemical Corporation |
| Infineum International Limited |
| Evonik Industries AG |
| LANXESS AG |
| Croda International Plc |
| Clariant AG |
| Others |
Value Chain & Pricing Dynamics
Organometallic synthesis automation in Yangtze River Delta chemical parks is compressing unit economics for ashless dispersants while concentrating production among integrated technology platforms. This dual effect squeezes mid-tier formulators lacking captive phosphorus pentasulfide handling capabilities and reshapes procurement leverage across lubricant blender networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified additive packages from merchant-market bundles and unadditized base stocks. Price differentiation hinges on REACH compliance depth and treat rate optimization for extended-drain specifications. Cost compression in standard-tier friction modifiers is intensifying because Group III+ base oil integration erodes standalone VI improver margins. Mid-tier blenders in India and Southeast Asia exhibit highest price sensitivity, while German and Japanese OEMs accept premium positioning for thermally robust antioxidant systems.
Supply Chain Analysis
Spent lubricant collection and re-refining flows are creating reverse-logistics infrastructure that feeds Group II and III base stocks back into additive blending circuits. Production gravity centers on China, the United States, and Germany, with feedstock supply drawing from Middle Eastern and Korean refinery expansions. Phosphorus pentasulfide, molybdenum disulfide, and olefin copolymer imports face single-source vulnerability from legacy additive hubs. Distribution runs through direct technical relationships for multinational blenders and regional chemical distributors for mid-tier manufacturers lacking formulation expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specification convergence toward 30,000-kilometer drain intervals and IMO 2020 marine compliance is concentrating procurement among integrated technology platforms capable of full-package validation.
For Market Incumbents: To counter captive additive expansion by Chinese domestic blenders, anchor long-term supply relationships through modular bundling partnerships with Sinopec and Indian Oil distribution networks. Deepen backward integration into high-base-number detergent chemistries for marine cylinder lubrication demand in Singapore and Rotterdam bunkering corridors. For New Entrants and Emerging Players: Capture formulation white space in electric vehicle thermal management fluids, specifically dielectric friction modifiers for battery pack cooling circuits above 150°C thermal stability. India's BIS certification alignment with ISO 6743 standards offers the most penetrable entry point for modular additive bundling operations serving mid-tier lubricant manufacturers in Gujarat and Maharashtra industrial zones. For Investors and Strategic Acquirers: Valuations sit cheapest among regional formulators with merchant-market exposure to China's MEE biodegradability enforcement and fragmented compliance costs. Long-term viability favors specialized additive houses with upstream control into key chemistries and OEM certification depth across marine and heavy-duty diesel segments. Watch for inflection signals in ionic liquid friction modifier adoption rates among Japanese OEMs for hybrid transmission applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detergent Chemistries | Upstream control over high-base-number sulfonate production secures marine cylinder lubricant positioning in IMO-regulated bunkering hubs. |
| Modular Additive Bundling Partnerships | Pre-formulated packages reduce inventory complexity for mid-tier blenders in Sinopec and Indian Oil distribution networks. |
| Electric Vehicle Thermal Fluid Development | Dielectric friction modifiers for battery pack cooling address specification gaps above 150°C thermal stability thresholds. |
| REACH Article 33 Compliance Investment | Full supply chain disclosure capabilities for SVHC-containing additives above 0.1% concentration anchor German and French OEM relationships. |
| Long-term Supply Agreements with Base Oil Refiners | Feedstock integration with Middle Eastern and Korean Group III+ producers stabilizes additive solubility margins. |
Study Parameters
Bottom-up lubricant blender demand modeling reconciled against top-down additive production capacity tracking forms the analytical core of this study. Primary interviews with plant managers at detergent and dispersant synthesis facilities, procurement leads at major lubricant blenders, technical R&D directors at friction modifier specialists, and distribution channel partners in India and Southeast Asia were validated against secondary sources including customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated chemical conglomerates, and MEE enforcement records for GB standard compliance.
Input-output matrices map treat rate assumptions across viscosity grade, OEM specification tier, and regional regulatory cluster to generate volume and value outputs across the projection horizon. Segmentation dimensions include product chemistry, functionality tier, end-use application, and distribution channel structure. CAGRs were derived from regression analysis of historical specification upgrade cycles and forward projection of regulatory mandate timelines, with specific weighting for marine sulfur cap compliance and electric vehicle thermal fluid penetration curves.
Regulatory enforcement variance, feedstock availability disruptions, and specification timeline delays are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented base-case assumptions regarding OEM drain interval adoption rates and MEE biodegradability compliance deadlines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Polyurethane Additives Market
Additives
Performance Minerals Additives Market
Additives
Fuel Additives Market
Additives
Europe Feed Additives Market
Additives
Calcium Tartrate Market
Additives
Supplemental Coolant Additives Market
Additives
Alginic Acid Market
Additives
Global Matting Agents Market
Additives
Global Coalescing Agent Market
Additives
North America Citric Acid Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
North America Phosphate Esters Market
Additives
Global Sodium Acetate Trihydrate Market
Additives
Sorbitan Oleate Market
Additives
Fluid Loss Additives Market
Additives
Anti-Block Additives Market