
 United States Citric Acid Market | 2026-2036
United States Citric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
United States Citric Acid Market Intelligence
Clean-label beverage formulations are restructuring procurement patterns across the food and beverage sector. Cargill, Incorporated leverages its corn-derived feedstock network to sustain cost-competitive anhydrous citric acid output. Archer Daniels Midland Company anchors its position through integrated fermentation capacity in the Midwest. Tate & Lyle differentiates via application-specific technical service for beverage customers.
Citric acid is a tricarboxylic acid produced primarily via submerged fermentation of Aspergillus niger on carbohydrate substrates, yielding a crystalline product with purity grades exceeding 99.5% for food and pharmaceutical applications. It functions as a pH regulator, preservative, and chelating agent across industrial and consumer formulations. The anhydrous citric acid segment dominates pharmaceutical applications where moisture sensitivity dictates specification, while liquid citric acid leads in beverage manufacturing for direct dosing efficiency. Food & Beverage applications command the largest volume share, though Cleaning Agents represent the fastest-growing application as EPA Safer Choice standards drive substitution of phosphate builders.
The FDA governs citric acid under GRAS designation with purity specifications codified in 21 CFR 184.1033, while the EPA regulates downstream cleaning formulations through FIFRA and Safer Choice certification pathways. USDA organic labeling requirements further constrain feedstock sourcing for certified-clean-label supply chains. Stakeholders must monitor fermentation feedstock cost volatility and state-level packaging regulations in California and New York that affect downstream formulation economics.
Market Dynamics
Clean-label beverage procurement is compressing specification tolerance bands across the United States citric acid value chain. The FDA's GRAS affirmation process and EPA Safer Choice certification pathways are tightening purity benchmarks faster than fermentation capacity can adapt.
Growth Catalysts
- EPA Safer Choice Standards:Biodegradable cleaning agent mandates are accelerating phosphate builder substitution. Citric acid functions as the primary chelating alternative in institutional and household formulations.
- Midwestern Manufacturing Belt Concentration:Large-scale food processing clusters in Illinois, Iowa, and Nebraska anchor volume offtake. Proximity to corn feedstock networks reduces logistics friction for anhydrous grades.
- Submerged Fermentation Yield Improvements:Strain optimization of Aspergillus niger is lowering carbohydrate input requirements per ton of crystalline output. Process intensification supports cost-competitive positioning against synthetic alternatives.
Market Restraints
- Corn Feedstock Volatility:Carbohydrate substrate costs fluctuate with commodity grain markets and biofuel policy arbitrage. Price transmission lag compresses margin buffers for non-integrated producers.
- California Regulatory Layering:State-level packaging regulations and Prop 65 disclosure requirements add compliance overhead distinct from federal GRAS standards. Formulation economics shift toward documented supply chain traceability.
- Moisture Sensitivity in Pharmaceutical Grades:Anhydrous specification demands controlled-atmosphere handling infrastructure. Capital requirements for humidity-managed distribution constrain regional supplier entry.
Strategic Opportunities
- USDA Organic Certification Pathways:Clean-label supply chains require certified feedstock sourcing. Organic fermentation substrates command premium positioning in beverage and nutraceutical channels.
- Direct-to-Brewery Liquid Dosing:Craft beverage producers in Colorado and Oregon seek bulk liquid citric acid for pH adjustment bypassing dry handling. Tanker delivery models reduce labor and dust exposure.
- Bioplastics Chelating Applications:Biodegradable polymer manufacturing requires citrate-based nucleating agents. This emerging industrial segment sits outside traditional food and cleaning verticals.
Industry Challenges
- Fermentation Specialist Talent Scarcity:Industrial microbiology expertise for Aspergillus niger strain management concentrates in legacy biotechnology hubs. Rural Midwestern production sites face recruitment friction against coastal pharma and ag-biotech employers.
- GRAS Self-Affirmation Documentation Burden:FDA notification pathways require extensive safety dossiers for novel applications or modified production processes. Timeline compression pressures strain regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Citric Acid Market |
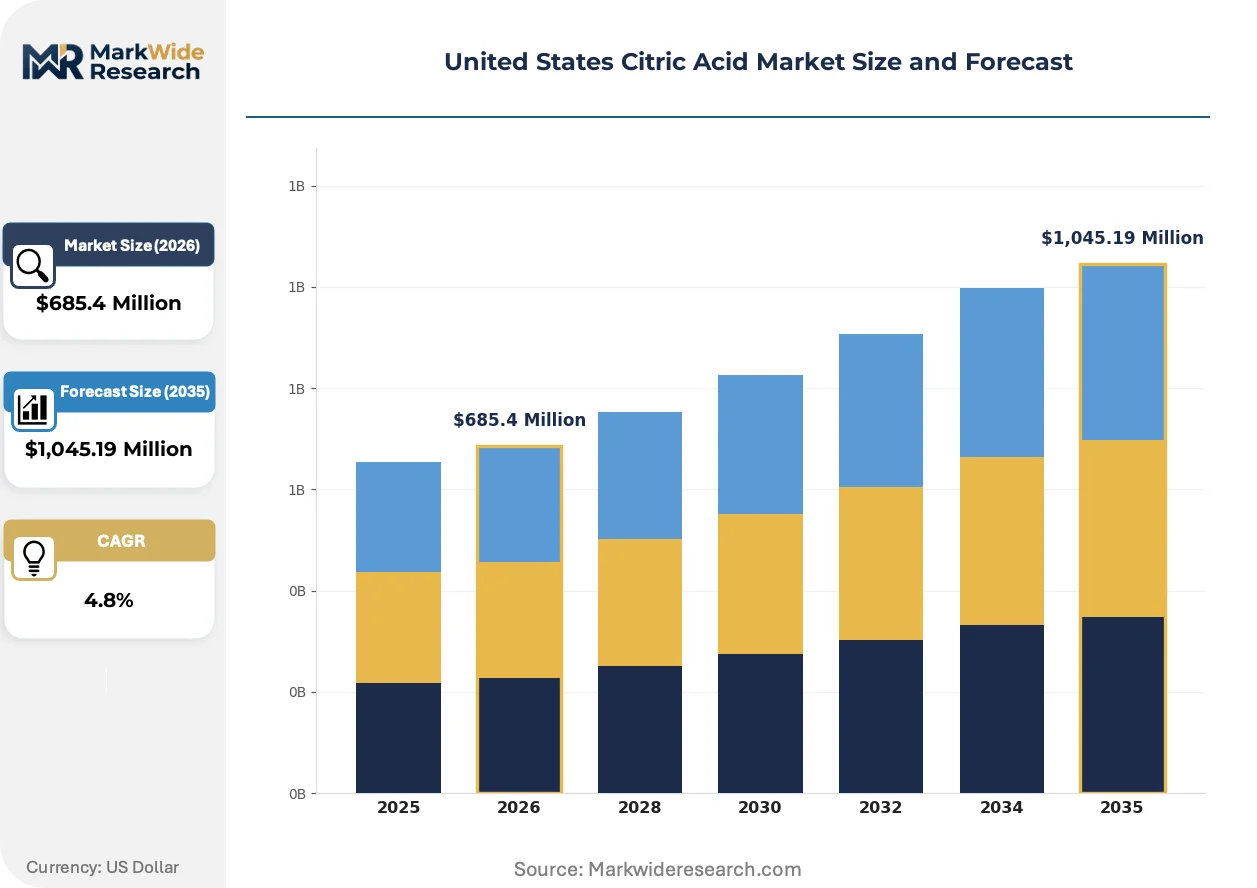
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous Citric Acid, Liquid Citric Acid, Citric Acid Monohydrate, Citric Acid Powder Application: Food & Beverage, Pharmaceuticals, Personal Care, Cleaning Agents End User: Food Manufacturers, Beverage Industry, Healthcare Providers, Cosmetic Companies Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | Mireca International, Cargill, Incorporated, Archer Daniels Midland Company, Tate & Lyle, FBC Industries, ChemPoint, Western Chemical, Geocon Products, Henwil Custom Chemicals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Citric Acid Market Strategic Shifts & Innovations
Continuous fermentation systems and membrane filtration advances are compressing batch cycle times while raising purity floors. These process innovations intersect with tightening federal and state regulatory frameworks.
Continuous fermentation technology with integrated membrane cell retention is unifying upstream productivity with downstream crystallization efficiency. Large-scale beverage manufacturers in California and Texas are piloting these systems to reduce water usage and energy intensity per ton of anhydrous output. The technology is enabling smaller footprint facilities closer to coastal demand centers, compressing traditional Midwestern supply advantages.
The EPA's Safer Choice certification program is tightening surfactant and builder specifications for institutional cleaning products. Formulators must document biodegradability profiles and aquatic toxicity thresholds that citric acid satisfies more readily than phosphate alternatives. Household and industrial cleaning segments in the Northeast and Pacific states are responding fastest, with procurement contracts now specifying Safer Choice-compliant ingredient sourcing.
Direct tanker delivery of liquid citric acid is displacing dry bulk and bagged formats among mid-sized beverage producers. This pattern compresses handling labor and dust control capital while enabling real-time pH adjustment in continuous processing lines. The shift is most visible in the Mountain West and Pacific Northwest craft brewing clusters where facility scale supports dedicated storage infrastructure.
United States Citric Acid Market Segmentation
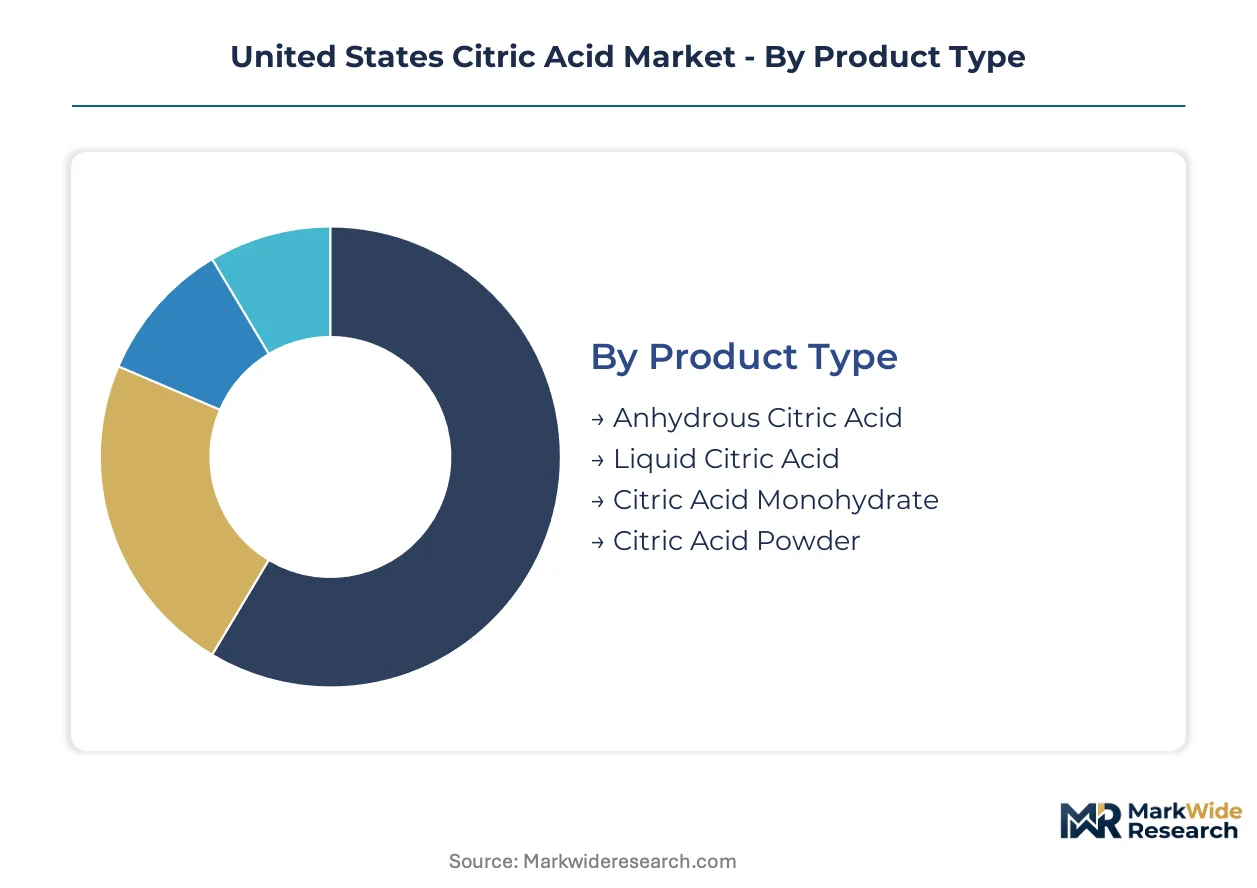
Citric acid procurement patterns diverge sharply across physical form, application chemistry, and customer operational scale. Specification tolerances and handling infrastructure requirements create distinct competitive arenas within each category.
Product Type:
Moisture sensitivity and dosing precision separate buyers across the four physical formats.
- Anhydrous Citric Acid:Crystalline form with maximum 0.5% moisture content serves pharmaceutical tablet formulations and moisture-critical food systems. California pharmaceutical manufacturers and Midwestern nutraceutical compounders anchor demand, driven by FDA 21 CFR 184.1033 purity mandates and controlled-atmosphere handling requirements that filter out smaller regional suppliers.
- Liquid Citric Acid:Aqueous solution at 50% concentration enables direct-injection pH adjustment in continuous beverage processing. Tanker-delivered volumes concentrate in Texas and Colorado craft brewing clusters where labor reduction and dust elimination justify dedicated storage infrastructure investment.
- Citric Acid Monohydrate:Single-water-molecule crystal structure balances cost and flowability for standard food preservation applications.
- Citric Acid Powder:Ground crystalline format suits small-batch dry blending operations with limited dissolution equipment.
Volume sits with anhydrous grades; growth tilts toward liquid delivery systems.
Application:
Regulatory jurisdiction and performance chemistry determine specification intensity across downstream uses.
- Food & Beverage:GRAS-affirmed citric acid functions as pH regulator, preservative, and flavor enhancer across carbonated drinks, jams, and dairy alternatives. Large-scale processors in Illinois and Iowa leverage corn-belt proximity for cost-competitive anhydrous sourcing, while California clean-label formulators drive organic-certified feedstock premiums.
- Cleaning Agents:EPA Safer Choice certification requirements position citric acid as the primary phosphate builder substitute in institutional and household formulations. Northeast and Pacific state procurement contracts now mandate documented biodegradability profiles that citrate chelating chemistry satisfies more readily than petrochemical alternatives.
- Pharmaceuticals:USP-grade material for effervescent tablets and parenteral solutions demands 99.5%+ purity with heavy metal testing protocols.
- Personal Care:Cosmetic pH adjustment and antioxidant stabilization in skincare formulations require FCC-grade certification with lower volume thresholds.
Food & Beverage commands absolute tonnage; Cleaning Agents show steepest expansion trajectory under EPA phosphate restrictions.
End User:
Scale economies and technical service requirements fragment the customer base across four operational archetypes.
- Food Manufacturers:Canned goods, confectionery, and processed dairy producers in the Midwestern manufacturing belt purchase anhydrous and monohydrate grades in bulk railcar quantities. Integrated fermentation producers like Cargill and ADM leverage captive corn feedstock networks to serve these accounts with minimal logistics friction.
- Beverage Industry:Carbonated soft drink bottlers and craft brewing operations span multinational scale to regional tanker-receipt facilities. Colorado and Oregon craft producers increasingly specify liquid citric acid for real-time pH adjustment in continuous processing lines.
- Healthcare Providers:Hospital pharmacy compounding and dialysis solution preparation requires USP-grade anhydrous material with lot-level traceability documentation.
- Cosmetic Companies:Skincare and haircare formulators in New Jersey and California purchase FCC-grade powder in drum quantities with color and odor specifications beyond food-grade standards.
Procurement concentration favors Food Manufacturers; technical service intensity peaks with Beverage Industry accounts.
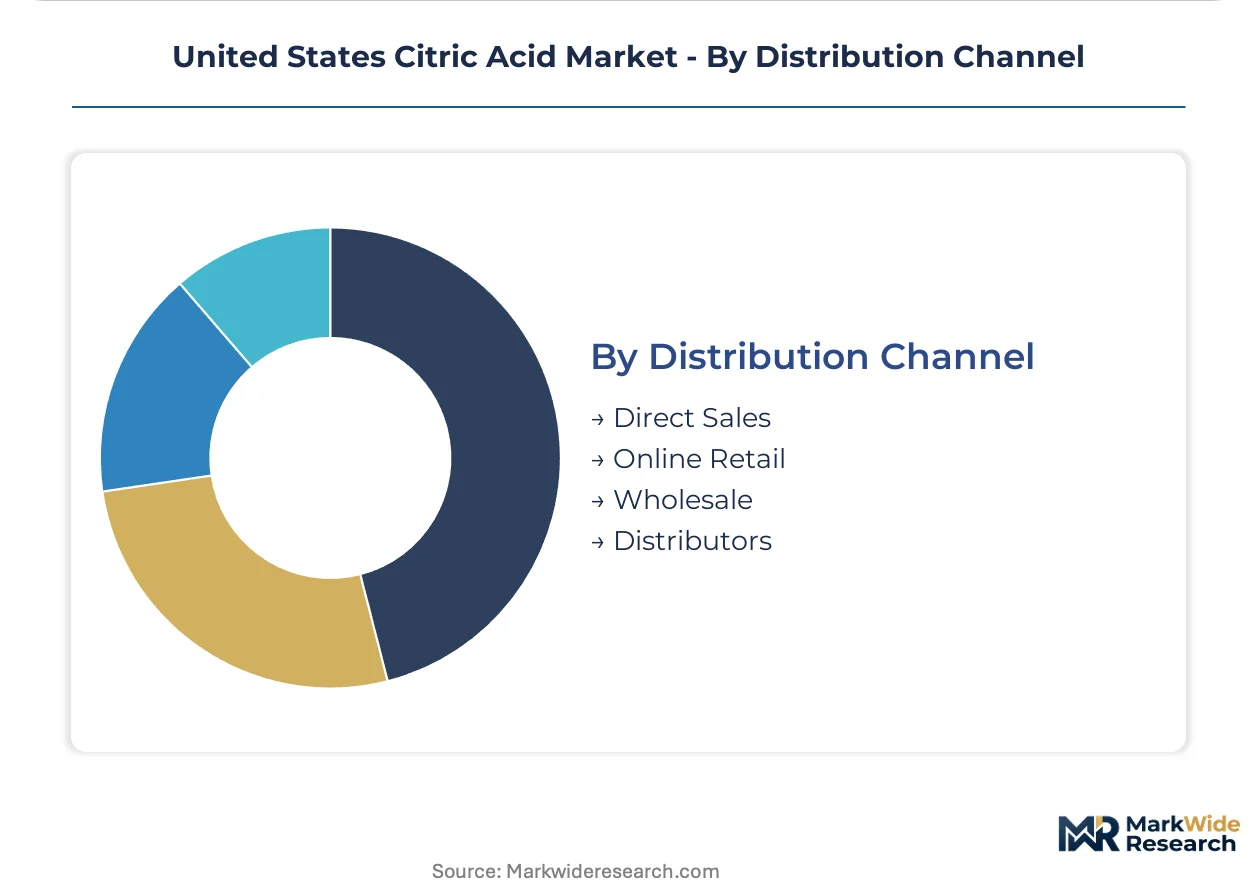
Distribution Channel:
Customer scale and formulation sensitivity dictate channel selection across the value chain.
- Direct Sales:Producer-to-manufacturer relationships dominate pharmaceutical and large food processing accounts requiring certificate of analysis documentation and dedicated technical service. ADM and Tate & Lyle field teams manage these relationships with application-specific formulation support for beverage pH optimization.
- Distributors:Regional chemical distributors warehouse anhydrous and liquid grades for mid-tier food processors and cleaning compounders requiring just-in-time replenishment across fragmented geographic footprints.
- Wholesale:Bulk break-bulk operations serve smaller food manufacturers and personal care formulators with palletized powder and drum liquid formats.
- Online Retail:E-commerce platforms capture laboratory, artisan food, and small cosmetic producer demand for packaged grades below distributor minimums.
Direct Sales capture value through technical attachment; Distributors extend geographic reach into secondary manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwestern Opportunity Zones and California Enterprise Zones concentrate citric acid demand through tax-advantaged food processing infrastructure. State-level clean-label mandates and EPA regional enforcement patterns reshape procurement geography.
California
Clean-label beverage formulators in the San Joaquin Valley drive organic-certified citric acid premiums. Prop 65 disclosure requirements and CalRecycle packaging regulations impose compliance layers beyond federal FDA GRAS standards. Los Angeles and San Diego pharmaceutical manufacturers anchor anhydrous grade demand for moisture-critical tablet formulations.
Midwest Manufacturing Belt
Illinois, Iowa, and Nebraska food processing clusters purchase bulk anhydrous grades via railcar quantities. Corn feedstock networks reduce logistics friction for integrated fermentation producers. Chicago and Des Moines serve as distribution nodes for Midwestern canned goods and confectionery manufacturers.
Texas
Continuous fermentation pilot programs in Houston and Dallas-Fort Worth compress water usage per ton of crystalline output. EPA Region 6 Safer Choice enforcement accelerates phosphate builder substitution in institutional cleaning formulations. Tanker-delivered liquid citric acid serves Gulf Coast beverage bottlers.
Colorado
Craft brewing operations in Denver and Boulder specify liquid citric acid for real-time pH adjustment. Mountain West facility scales support dedicated storage infrastructure for direct tanker delivery models. State-level environmental quality standards align with EPA Safer Choice biodegradability thresholds.
Pacific Northwest
Oregon craft beverage producers adopt liquid dosing systems bypassing dry handling labor. Washington State Department of Ecology regulations on industrial cleaning chemicals mirror EPA Safer Choice certification pathways. Portland and Seattle anchor demand for documented supply chain traceability.
United States Citric Acid Market Key Industry Players
Top-tier vendors anchor integrated fermentation capacity, while mid-tier distributors and specialty compounders fill geographic and formulation gaps. The market exhibits tiered concentration around corn-belt feedstock access and coastal technical service intensity. Strategic archetypes include captive feedstock integrators, application-specific technical service providers, and regional distribution specialists. Dominant competitive moves center on backward integration into carbohydrate substrate networks and geographic expansion toward coastal clean-label demand centers.
Among integrated agribusiness operators, Cargill, Incorporated and Archer Daniels Midland Company exemplify the captive feedstock archetype through Midwestern corn-derived fermentation networks. Tate & Lyle occupies a position emphasizing beverage application technical service. These three entities represent distinct competitive vectors: feedstock control, manufacturing scale, and customer formulation support.
| Leading Market Players |
|---|
| Mireca International |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle |
| FBC Industries |
| ChemPoint |
| Western Chemical |
| Geocon Products |
| Henwil Custom Chemicals |
| Others |
Cost & Logistics Intelligence
Midwestern food manufacturers purchasing bulk anhydrous grades via railcar offtake anchor the contract-based pricing model, with long-term agreements locking in corn-feedstock-indexed rates that buffer against commodity volatility. California clean-label formulators absorb organic-certified premiums that can exceed standard grades by substantial margins, reflecting documented supply chain traceability costs.
Pricing Analysis
Short lead-time premiums for pharmaceutical-grade anhydrous material command substantial markups over standard food-grade contracts, as moisture-controlled handling infrastructure constrains spot availability. The market operates on a three-tier pricing structure across premium, standard, and economy levels, with USP-grade certification and organic feedstock sourcing as primary price differentiation drivers. Cost compression in standard food-grade tiers is intensifying because integrated fermentation producers leverage captive corn networks. Small-batch cosmetic formulators exhibit highest price sensitivity, while pharmaceutical compounders accept premium positioning for lot-level traceability documentation.
Supply Chain Analysis
Regional distribution centers in Chicago and Des Moines operate as hub-and-spoke nodes for Midwestern manufacturing belt offtake, with tanker-delivered liquid formats bypassing traditional warehousing for coastal beverage clusters. Supply concentrates in the United States through Iowa, Illinois, and Nebraska fermentation corridors, with limited import dependency for specialty pharmaceutical grades. Corn carbohydrate substrates, Aspergillus niger strain cultures, and crystallization energy inputs constitute critical raw material dependencies. Single-source vulnerability sits with domestic corn harvest volatility amplified by biofuel policy arbitrage. Distribution runs through producer-direct railcar contracts for large processors, regional chemical distributors for mid-tier accounts, and wholesale break-bulk for fragmented personal care formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States citric acid market functions as a cost-of-compliance arena where FDA GRAS affirmation documentation and EPA Safer Choice certification pathways erect formidable barrier-to-entry moats that favor incumbent players with established regulatory affairs infrastructure.
For Market Incumbents: Deepen backward integration into certified organic feedstock networks to capture California clean-label premiums and defend against emerging fermentation technology disruptors. Expand humidity-controlled distribution infrastructure in pharmaceutical corridors to sustain anhydrous grade margins against regional supplier encroachment. Capacity addition in Texas continuous fermentation pilot zones offers geographic diversification beyond Midwestern corn-belt concentration. For New Entrants and Emerging Players: The price-point gap between premium organic-certified and economy standard-grade citric acid creates entry space for mid-tier positioning. Direct-to-brewery liquid dosing in Colorado and Oregon craft clusters represents the most penetrable white-space target, bypassing capital-intensive dry handling infrastructure. A tanker-delivery technical service model with real-time pH adjustment support offers differentiated go-to-market positioning against bulk commodity suppliers. For Investors and Strategic Acquirers: The window for entry favors fermentation technology specialists with strain optimization IP and regulatory dossier libraries. Long-term viability hinges on USDA organic certification capabilities and EPA Safer Choice formulation partnerships rather than commodity scale alone. Monitor EPA phosphate builder restriction timelines as the critical inflection signal for cleaning agent segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Feedstock | Captures California Prop 65-compliant supply chain premiums for clean-label beverage formulators. |
| Continuous Fermentation Capacity Expansion | Reduces water intensity per ton of crystalline output for EPA Region 6 Safer Choice manufacturing. |
| Direct Tanker Delivery Infrastructure | Enables real-time pH adjustment for Colorado craft brewing clusters bypassing dry handling labor. |
| USP-Grade Certification Investment | Opens pharmaceutical tablet formulation demand with FDA 21 CFR 184.1033 purity documentation. |
| Long-Term Supply Agreement with Midwestern Processors | Locks in corn-belt railcar offtake volumes against biofuel policy arbitrage volatility. |
Research Approach
Multi-period observation of corn feedstock pricing volatility, EPA Safer Choice certification adoption rates, and pharmaceutical grade purity specification evolution anchored the trend analysis, supplemented by interviews with fermentation plant managers, beverage procurement leads, cleaning compounder technical directors, and regional chemical distribution channel partners. Secondary validation drew from FDA GRAS notification databases, USDA organic certification registries, SEC 10-K filings of integrated agribusiness operators, and American Chemistry Council industrial chemical trade data. Bottom-up volume modeling across product type, application chemistry, and end-user operational scale triangulated against top-down macroeconomic demand indicators.
Input-output matrices mapped carbohydrate substrate costs through fermentation yield coefficients to crystalline output pricing tiers across the projection horizon. Segmentation dimensions modeled included physical form specification, regulatory grade tier, end-use industry vertical, and geographic production hub clustering. CAGRs were derived through exponential smoothing of historical volume trajectories adjusted for EPA phosphate restriction policy implementation curves and submerged fermentation technology adoption S-curves. Strain optimization productivity gains and membrane filtration capital expenditure cycles served as industry-specific forecast inputs.
Inputs from primary stakeholder interviews and secondary regulatory filings were available through the study window; gaps in real-time pharmaceutical inventory positioning data and proprietary strain performance metrics introduce uncertainty bands around anhydrous grade demand forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Europe Fuel Additives Market
Additives
FD and C Lakes Market
Additives
Powder Induction and Dispersion Systems Market
Additives
Chitosan Powder Market
Additives
North America Potassium Nitrate Market
Additives
Plasticizer Alcohols Market
Additives
Crystal Growth Modifier Market
Additives
2-Ethylhexyl Nitrate (2EHN) Market
Additives
Saudi Arabia Feed Additives Market
Additives
Global UV Absorbers Market
Additives
Citric Acid Market
Additives
Global Corrosion Inhibitor Market
Additives
Fuel Additives Market
Additives
North America Citric Acid Market
Additives
Silage Additives Market
Additives
Monocalcium Phosphate Market