
 Asia Pacific Plastic Additives Market | 2026-2036
Asia Pacific Plastic Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Plastic Additives Market Outlook
Automotive lightweighting is repositioning demand across the Asia Pacific Plastic Additives Market as OEMs substitute metal with engineered polymers in under-hood and structural applications. BASF SE leverages its Ludwigshafen-to-Asia technology pipeline to dominate high-heat stabilizer formulations for polyamide compounds. Songwon Industrial Co. Ltd. anchors regional supply through its Ulsan manufacturing base, sustaining cost-competitive antioxidant output for Korean and Chinese automotive tiers. Clariant specializes in halogen-free flame retardant masterbatches, differentiating its portfolio for electric vehicle battery housings across the region.
Asia Pacific plastic additives encompass chemical compounds—stabilizers, modifiers, processing aids, and flame retardants—blended at 0.1-10 wt% into polymer matrices to enhance thermal stability, mechanical performance, or regulatory compliance during extrusion, injection molding, and blow molding operations. These additives primarily extend polymer service life, enable thinner-wall designs, and satisfy fire-safety standards in transportation and electronics applications. Stabilizers command the largest value share due to their non-negotiable role in polyolefin durability, while flame retardants generate premium pricing as electric vehicle and 5G infrastructure buildouts accelerate halogen-free substitution. Impact modifiers compete on cost-efficiency in PVC construction profiles, though processing aids capture expanding margin pools in high-throughput packaging lines where cycle-time reduction justifies formulation investment.
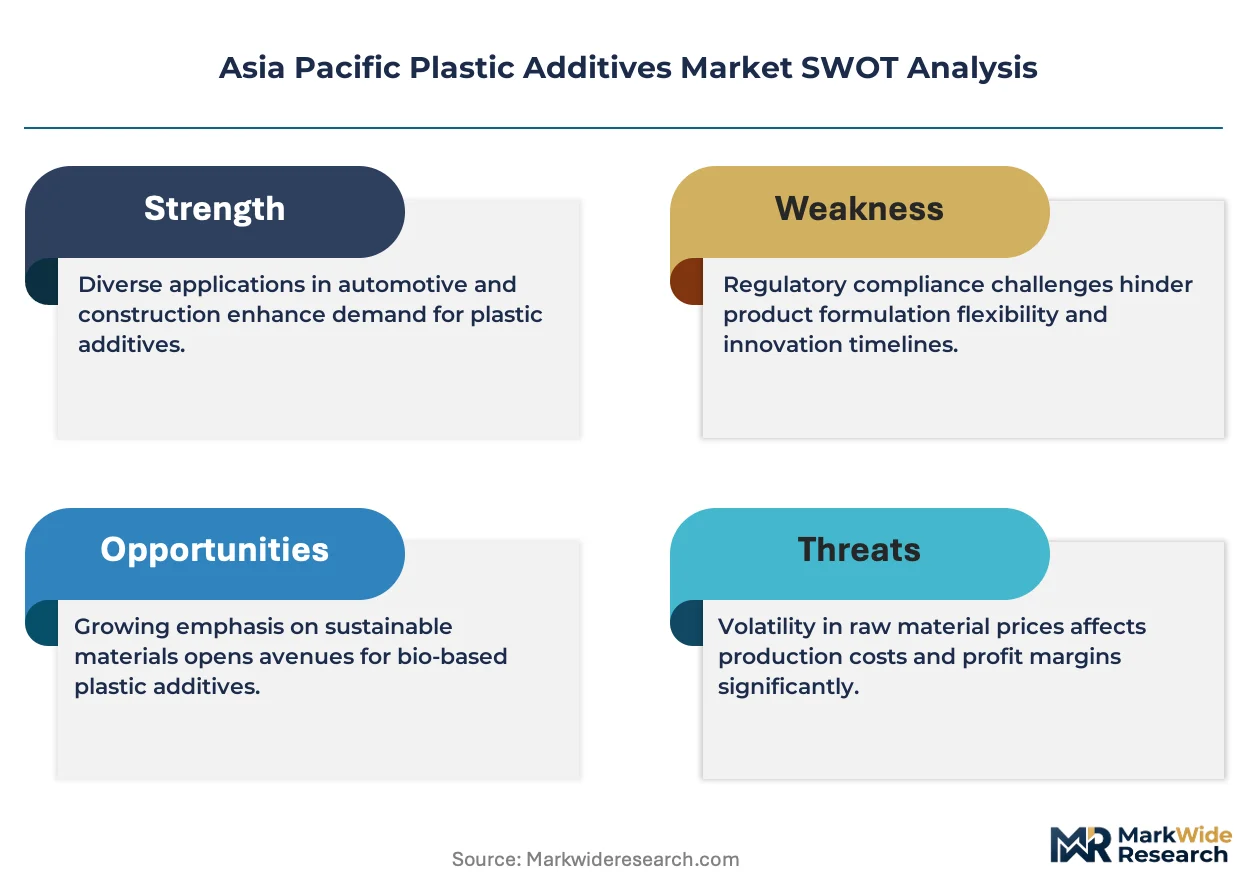
China's SAMR enforces GB standards restricting heavy metal content in plastic additives, while South Korea's MFDS aligns flame retardant classifications with evolving EU REACH substance restrictions, reshaping import eligibility and local formulation requirements. India's BIS certification mandates for construction-grade PVC additives are tightening market access for uncertified suppliers in infrastructure projects. Stakeholders must monitor regulatory divergence between China's dual carbon goals and India's PLI scheme incentives for domestic chemical manufacturing, as compliance cost asymmetries will determine competitive positioning across national boundaries.
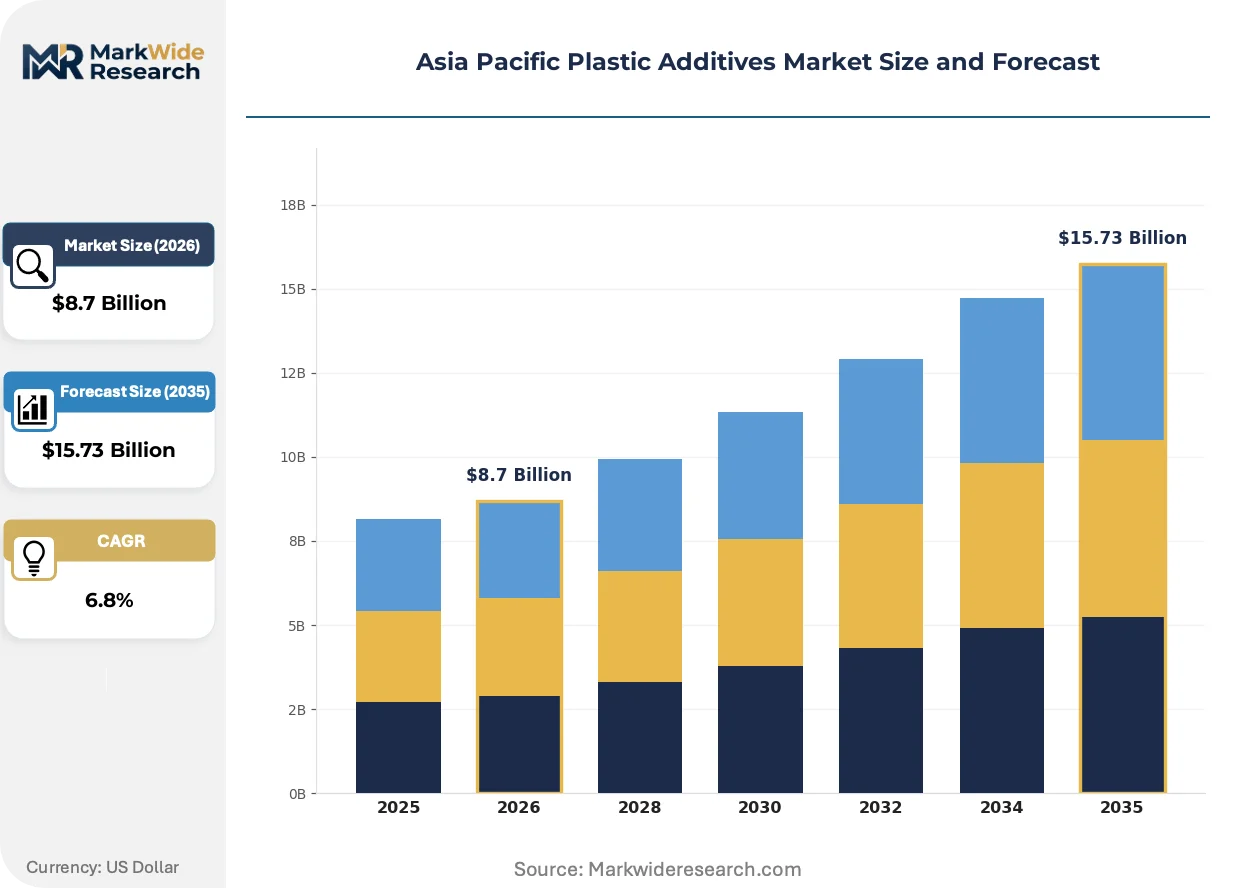
Market Dynamics
Automotive lightweighting mandates are compressing formulation cycles across Asia Pacific plastic additives, forcing compounders to certify heat-stabilized polyamide grades in under 18 months to retain OEM qualification slots.
Growth Catalysts
- China's Dual Carbon Goals:Beijing's carbon neutrality targets are accelerating demand for recyclate-compatible stabilizers in packaging and automotive applications.
- Electric Vehicle Battery Housings:Halogen-free flame retardant specifications for lithium-ion enclosures are creating specification pull across Korean and Chinese EV supply chains.
- Vietnam's Processing Zones:Polymer compounding clusters in Binh Duong and Dong Nai are expanding additive blending capacity to serve ASEAN packaging export demand.
Market Restraints
- Feedstock Volatility:Propylene and benzene derivative costs swing additive margins unpredictably for antioxidant and UV stabilizer producers.
- Korean Supply Concentration:Songwon Industrial and handful of Ulsan-based manufacturers control bulk antioxidant output, creating single-source vulnerability for Chinese compounders.
- REACH-Aligned Substitution:South Korea's MFDS restrictions on brominated flame retardants are forcing reformulation investments before local alternatives achieve cost parity.
Strategic Opportunities
- India's PLI Chemical Incentive:Production-linked incentives for specialty chemicals are drawing additive manufacturers to Gujarat's Dahej and Mundra port corridors.
- 5G Infrastructure Buildout:Low-smoke zero-halogen cable compounds for base station deployment are opening specification windows for phosphorus-based flame retardants.
- Bio-Based Plasticizers:Epoxidized soybean oil and citrate esters are penetrating medical device and food-contact films as GB standards tighten phthalate limits.
Industry Challenges
- Formulation Chemist Scarcity:Polymer-additive interaction expertise is concentrated among aging specialists in Japan's Kansai chemical belt and Shanghai's Zhangjiang science park.
- Multi-Jurisdiction Certification:Simultaneous compliance with China's GB standards, India's BIS mandates, and South Korea's K-BPR is extending product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Plastic Additives Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stabilizers, Impact Modifiers, Processing Aids, Flame Retardants Application: Packaging, Automotive, Consumer Goods, Construction End Use Industry: Electronics, Textile, Agriculture, Healthcare Form: Granules, Liquids, Powders, Masterbatches |
| Companies Covered | BASF SE, Songwon Industrial Co. Ltd., Clariant, Dow, Evonik Industries, Adeka Corporation, Baerlocher GmbH, Kaneka Corporation, Arkema Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Plastic Additives Market Strategic Shifts
Reactive extrusion techniques and halogen-free chemistry are compressing traditional additive incorporation methods across Asia Pacific compounding operations, forcing equipment and formulation investments simultaneously.
Phosphorus-nitrogen intumescent systems are overtaking brominated flame retardants in polypropylene battery housings and connector applications. Chinese EV manufacturers are specifying these systems for NEV certification compliance. The shift is overtaking legacy compounder inventories and forcing raw material procurement restructuring toward ammonium polyphosphate suppliers.
South Korea's MFDS has aligned flame retardant substance restrictions with EU REACH Annex XVII updates, prohibiting decaBDE and HBCDD in electrical enclosures from 2025. Korean cable and electronics manufacturers are reformulating halogen-free grades ahead of enforcement. Vietnamese and Thai export processors serving Korean OEMs are accelerating qualification of alternative phosphorus-based systems to maintain supply eligibility.
Compounders are consolidating procurement around full-service distributors with in-house technical service capabilities, displacing traditional trading house relationships. Japanese and Korean additive buyers now specify distributor-led formulation support for complex multi-component stabilizer packages. This pattern concentrates most visibly in China's Yangtze River Delta, where BASF and Clariant authorized distributors are capturing specification influence from independent importers.
Asia Pacific Plastic Additives Market Segmentation
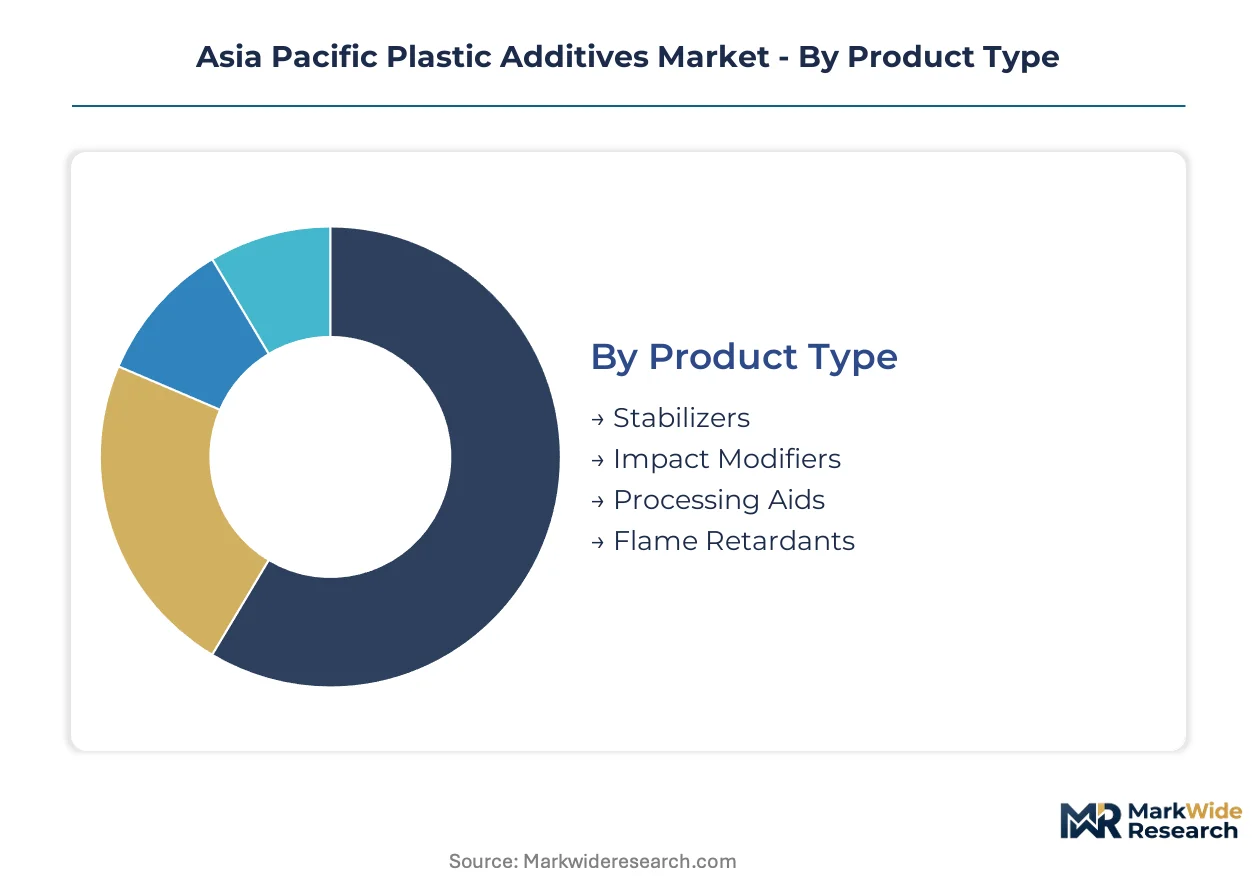
Plastic additive specifications diverge sharply across Asia Pacific manufacturing verticals, with automotive and electronics sectors driving premium stabilizer and flame retardant formulations while packaging prioritizes cost-optimized processing aids. Understanding these segment boundaries enables suppliers to align R&D spend with qualification requirements and margin pools.
Product Type:
Upgrade cycles in polymer compounding equipment are forcing additive portfolios toward higher thermal performance and regulatory compliance tiers, particularly as Chinese and Korean OEMs tighten material qualification windows.
- Stabilizers:Primary and secondary antioxidant blends protect polyolefins against thermal oxidation during processing and end-use exposure. Demand clusters in China's eastern automotive corridor where GB standards mandate extended service life for under-hood polyamide components. Heat stabilizer formulations for electric vehicle battery enclosures command premium pricing as OEMs specify 10,000+ hour aging requirements.
- Flame Retardants:Halogen-free phosphorus-nitrogen intumescent systems and mineral fillers suppress combustion in electrical enclosures and transportation applications. Korean EV manufacturers are specifying these grades for NEV certification compliance, displacing legacy brominated inventories across Busan and Ulsan supply chains. Reformulation investments are accelerating ahead of MFDS enforcement timelines.
- Impact Modifiers:Acrylic and MBS core-shell particles enhance PVC and polyolefin toughness for construction profiles and packaging films. Gujarat-Maharashtra chemical belt compounders source these for infrastructure-grade window and pipe applications.
- Processing Aids:Fluoropolymer and acrylic lubricants reduce melt fracture and die buildup in high-throughput extrusion lines. Vietnam's Binh Duong processing zones are expanding procurement of these additives to serve ASEAN packaging export demand.
Volume placements concentrate in Stabilizers; the faster expansion belongs to Flame Retardants.
Application:
Application-level differentiation tracks directly to processing temperature requirements and regulatory exposure, with automotive and electronics commanding specification authority over packaging and construction.
- Automotive:Lightweighting mandates are compressing metal-to-polymer substitution cycles across powertrain and structural components. Heat-stabilized polyamide grades for under-hood applications require 18-month qualification timelines to retain OEM supplier slots. Chinese and Korean tier suppliers are consolidating procurement around full-service distributors with in-house technical capabilities.
- Packaging:Recyclate-compatible stabilizers are gaining specification as China's dual carbon goals accelerate closed-loop material requirements. Yangtze River Delta converters are qualifying antioxidant packages that maintain clarity and mechanical properties across multiple reprocessing cycles.
- Consumer Goods:Aesthetic and tactile modifiers for appliances and personal care packaging compete on cost efficiency rather than technical performance. India's BIS certification mandates are tightening market access for uncertified additive suppliers in durable goods applications.
- Construction:PVC profile and pipe compounders in Vietnam and Thailand rely on calcium-zinc stabilizer packages to meet evolving heavy metal restrictions. Infrastructure project specifications are increasingly requiring certified additive formulations for window, siding, and conduit applications.
Automotive applications anchor value concentration; packaging delivers the steepest volume expansion trajectory.
End Use Industry:
End-use segmentation reflects diverging regulatory stringency and performance thresholds, with electronics and healthcare commanding the tightest material qualification protocols.
- Electronics:Low-smoke zero-halogen specifications for 5G base station cables and connector housings are opening specification windows for phosphorus-based flame retardants. Korean and Chinese telecom equipment manufacturers are qualifying these grades ahead of infrastructure deployment waves.
- Healthcare:Bio-based plasticizers including epoxidized soybean oil and citrate esters are penetrating medical device and food-contact films as GB standards tighten phthalate limits. Sterilization-stable stabilizer packages for polypropylene medical devices command premium positioning.
- Textile:UV stabilizers and antimicrobial additives for synthetic fiber processing compete on cost in India's Surat and Tiruppur manufacturing clusters. Technical textile applications in automotive and geotextiles specify higher-performance additive packages.
- Agriculture:UV and thermal stabilizers for greenhouse films and irrigation tubing prioritize cost efficiency and multi-season durability. Vietnam's Mekong Delta processing operations source these additives through regional distributor networks.
Electronics generates the highest specification pull; healthcare offers the most pronounced margin expansion.
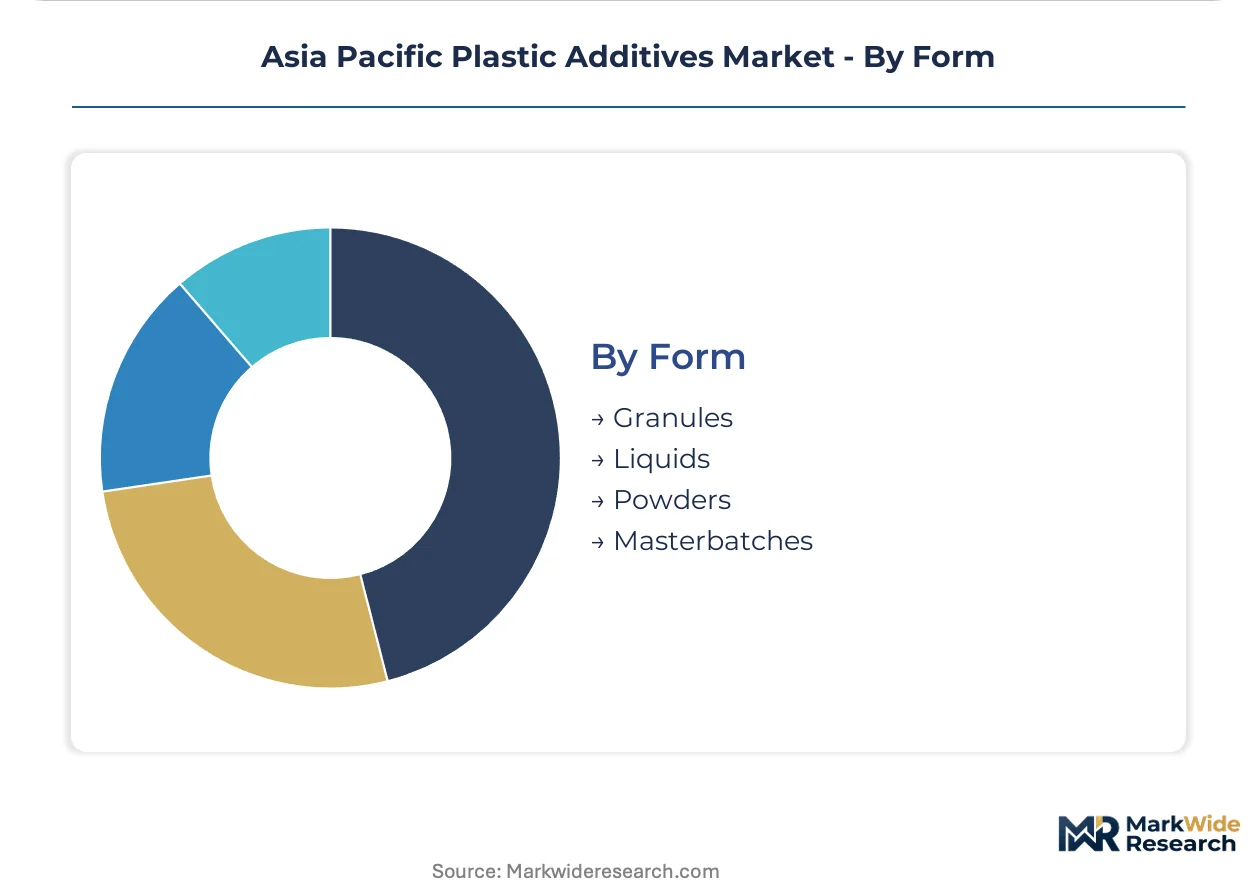
Form:
Physical form selection determines incorporation efficiency, dust exposure, and dosing precision across compounding operations, with masterbatch and liquid formats gaining share in automated processing environments.
- Masterbatches:Concentrated additive dispersions in polymer carriers enable precise dosing and reduced dust exposure in high-throughput extrusion and injection molding. Korean and Japanese compounders are consolidating procurement around distributor-led technical support for complex multi-component stabilizer packages.
- Liquids:Pumpable plasticizer and stabilizer formulations suit continuous PVC compounding and flexible film production. China's flexible packaging sector favors liquid delivery systems for rapid formulation adjustments and reduced material handling.
- Granules:Free-flowing solid additives target polyolefin and engineering polymer compounding where precise weighing and minimal segregation are critical. Automotive tier suppliers in China's Jiangsu and Zhejiang provinces specify granule formats for consistent dispersion.
- Powders:Cost-competitive dry blends serve construction-grade PVC and commodity packaging applications where dust control and automated handling are less critical. Indian and Vietnamese compounders utilize powder formats for price-sensitive infrastructure and agricultural film markets.
Masterbatch deliveries dominate value concentration; liquid formats are climbing the fastest among premium application segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor concentrates additive demand through Shanghai Free Trade Zone incentives and Yangtze River Delta polymer compounding clusters. India's PLI scheme for specialty chemicals is redirecting investment toward Gujarat's Dahej and Mundra port corridors.
China
Automotive lightweighting mandates from Shanghai-based OEMs are accelerating heat-stabilized polyamide qualification timelines to under 18 months. SAMR enforces GB standards restricting heavy metal content in plastic additives, tightening import eligibility for uncertified formulations. Yangtze River Delta compounders in Jiangsu and Zhejiang provinces are consolidating procurement around distributor-led technical support for multi-component stabilizer packages.
South Korea
EV battery housing specifications from Busan and Ulsan automotive tiers are displacing legacy brominated flame retardant inventories. MFDS aligns flame retardant classifications with EU REACH substance restrictions, prohibiting decaBDE and HBCDD in electrical enclosures from 2025. Ulsan-based manufacturers anchor regional antioxidant supply, though Chinese compounders face single-source vulnerability in bulk procurement.
India
Infrastructure-grade PVC demand from Maharashtra and Gujarat construction projects is tightening BIS certification requirements for additive suppliers. PLI scheme incentives for specialty chemicals are drawing manufacturers to Dahej and Mundra port corridors. Gujarat-Maharashtra chemical belt compounders source impact modifiers for window and pipe applications serving national infrastructure buildouts.
Vietnam
ASEAN packaging export demand is expanding additive blending capacity in Binh Duong and Dong Nai processing zones. Regional distributor networks are qualifying phosphorus-based flame retardant alternatives to maintain supply eligibility for Korean OEM export processors. Mekong Delta greenhouse film operations source UV and thermal stabilizers through Vietnam-based procurement channels.
Japan
Polymer-additive interaction expertise concentrates among specialists in Kansai chemical belt facilities near Osaka and Kyoto. METI oversight shapes technical standards for high-performance stabilizer formulations in automotive and electronics applications. Japanese compounders specify masterbatch formats with precise dosing requirements for consistent dispersion in engineering polymer processing.
Asia Pacific Plastic Additives Market Competitive Environment
Top-tier vendors anchor high-heat stabilizer and halogen-free flame retardant segments, while mid-scale compounders compete on cost-optimized processing aids and construction-grade formulations. The vendor structure stratifies across technology licensing partnerships, captive manufacturing bases, and distributor-led technical service capabilities. Strategic archetypes include integrated chemical conglomerates with Ludwigshafen-to-Asia technology pipelines, Ulsan-based regional supply anchors, and specialty masterbatch formulators. Dominant competitive moves encompass backward integration into propylene derivative supply and qualification support investments for multi-jurisdiction certification compliance.
Among Germany-based chemical conglomerates, BASF SE and Evonik Industries occupy positions exemplifying integrated technology pipeline strategies. BASF SE anchors high-performance stabilizer formulation supply through Asia-Pacific distribution networks. Songwon Industrial Co. Ltd. represents the Ulsan-based regional supply anchor archetype, sustaining cost-competitive output for Korean and Chinese automotive tiers. Clariant sits within the specialty masterbatch formulator tier, differentiating through technical service capabilities for electric vehicle battery housing applications.
| Leading Market Players |
|---|
| BASF SE |
| Songwon Industrial Co. Ltd. |
| Clariant |
| Dow |
| Evonik Industries |
| Adeka Corporation |
| Baerlocher GmbH |
| Kaneka Corporation |
| Arkema Group |
| Others |
Value Chain & Pricing Dynamics
Korean and Chinese automotive tier suppliers concentrate procurement authority through consolidated distributor relationships, anchoring contract-based long-term offtake agreements for heat-stabilized polyamide grades. This buyer concentration compresses spot-market liquidity and elevates technical service bundling as the dominant pricing model across stabilizer and flame retardant segments.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to halogen-free flame retardant masterbatches serving EV battery housing qualification deadlines, while spot inventory of commodity antioxidants trades at discounts to contract benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates certified automotive grades from construction-grade PVC additives and agricultural film compounds. Pricing pressure stems from propylene derivative cost volatility squeezing antioxidant margins. Packaging compounders in Vietnam's Binh Duong zone exhibit highest price sensitivity; Korean EV tier suppliers show least sensitivity due to specification-locked supply agreements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for heat-stabilized engineering polymers, while authorized distributor networks serve mid-tier compounders requiring formulation support. Manufacturing concentrates in China, South Korea, and India, with Ulsan-based producers anchoring regional antioxidant output. Raw material flows draw from Saudi and Singaporean propylene derivative supply, Chinese phosphorus chemical feedstocks, and Indian epoxidized soybean oil sources. Single-source vulnerability pervades Chinese compounder procurement from Korean antioxidant manufacturers. Distribution runs through Shanghai Free Trade Zone clearing facilities for Yangtze River Delta polymer clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into propylene derivative supply and captive masterbatch compounding capacity defines the vertical-integration race reshaping competitive positioning. Players are pursuing upstream control over antioxidant intermediates to defend margin structures against feedstock volatility.
For Market Incumbents: Deploy technical service capabilities as a lock-in mechanism. BASF SE and Songwon Industrial should expand distributor-led formulation support teams in China's Jiangtze River Delta to defend specification influence against emerging halogen-free flame retardant specialists. Deepen captive production of ammonium polyphosphate derivatives to reduce exposure to Chinese phosphorus chemical price swings. Certification investment in simultaneous GB standards, BIS mandates, and MFDS alignment extends product launch timelines but creates switching costs for qualified compounders. For New Entrants and Emerging Players: Launch via regional distributor partnerships targeting India's Gujarat-Maharashtra chemical belt. The PLI scheme for specialty chemicals creates the most penetrable entry corridor for antioxidant and impact modifier production. Qualify bio-based plasticizer formulations for medical device and food-contact film applications as GB standards tighten phthalate limits. Prioritize technical collaboration with Dahej port corridor infrastructure developers to secure feedstock access and customs efficiency. For Investors and Strategic Acquirers: The window for entry favors Ulsan-based regional supply anchors with established Korean automotive tier relationships. Mid-cap stabilizer formulators in Japan's Kansai chemical belt represent acquisition targets given concentrated polymer-additive expertise among aging specialists. Long-term viability hinges on recyclate-compatible formulation capabilities aligned with China's dual carbon goals. Watch MFDS enforcement timelines for decaBDE and HBCDD prohibitions as inflection indicators for phosphorus-nitrogen intumescent system demand acceleration. Periodic stress-testing of base assumptions is recommended.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Derivatives | Captive antioxidant intermediate supply insulates margins from benzene and propylene cost volatility. |
| Halogen-Free Flame Retardant Capacity Expansion | Ammonium polyphosphate production lines capture specification pull from Korean and Chinese EV manufacturers. |
| Distributor-Led Technical Service Investment | BASF-authorized distributors in Jiangsu province displace independent importers through formulation support. |
| Multi-Jurisdiction Certification Compliance | Simultaneous GB standards, BIS, and MFDS alignment extends launch timelines but locks in compounder relationships. |
| Bio-Based Plasticizer Product Line Development | Epoxidized soybean oil and citrate ester formulations penetrate medical device markets as GB phthalate limits tighten. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Asia Pacific plastic additives analysis. Primary interviews with polymer compounding plant managers, procurement leads at Korean and Chinese automotive tier suppliers, distribution channel partners in Shanghai Free Trade Zone, and technical R&D directors at Ulsan manufacturing facilities combined with secondary validation. Secondary sources encompassed Korea Petrochemical Industry Association reports, China Customs additive import statistics, SAMR GB standard enforcement disclosures, and SEC 10-K filings of listed chemical conglomerates. Bottom-up segment sizing and top-down macro reconciliation triangulated volume and value estimates.
Data-stream reconciliation across shipment volumes, capacity utilization rates, and end-use demand indicators shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry vertical, physical form factor, and regional production hub clustering. CAGRs derived from trend extrapolation of historical trade flows and elasticity-adjusted demand projections. Industry-specific forecast inputs incorporated EV battery housing specification timelines and China's dual carbon policy implementation pace.
Feedstock price volatility, regulatory enforcement delays, and automotive platform qualification cancellations are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding MFDS alignment with REACH substance restrictions and PLI scheme disbursement continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Nucleating Agents Market
Additives
Low VOC Coating Additives Market
Additives
Chemical Silage Additives Market
Additives
Global Metal Scavenging Agents Market
Additives
Liquid Thickeners Market
Additives
Triazine UV Absorber Market
Additives
Global Matting Agents Market
Additives
Rheological Additives Market
Additives
Carboxymethyl Cellulose Market
Additives
North America Potassium Nitrate Market
Additives
Epoxy Type Stabilizers Market
Additives
Grinding Aids Market
Additives
Tamarind Gum Derivatives Market
Additives
Global Acidulants Market
Additives
Supplemental Coolant Additives Market
Additives
South Africa Acidulants Market