
 North America Pharmaceutical Packaging Market | 2026-2036
North America Pharmaceutical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pharmaceutical Packaging Market Outlook
Child-resistant and senior-friendly certification tiers is reorganizing procurement priorities across North American pharmaceutical supply chains. Amcor PLC leverages its integrated film and container platforms to sustain compliance leadership in blister pack formats. Berry Global anchors high-barrier plastic solutions for moisture-sensitive oral solids. Gerresheimer AG specializes in borosilicate glass vials for injectable biologics, competing on dimensional precision and USP Type I certification.
North America pharmaceutical packaging encompasses primary, secondary, and tertiary containment systems engineered from glass, plastic, aluminum, and paper substrates to ensure product stability, patient safety, and regulatory traceability through controlled barrier properties, sterilization compatibility, and serialization-ready surfaces. Blister packs dominate unit-dose oral solid dispensing due to their compliance-enhancing calendarization and moisture barrier adaptability. Glass vials command premium positioning in parenteral applications where USP Type I hydrolytic resistance and elastomeric closure integrity prevent protein aggregation. Child-resistant packaging segments face escalating engineering complexity as CPSC protocols converge with FDA pediatric safety guidance.
FDA serialization requirements under the Drug Supply Chain Security Act, USP <1207> container closure integrity standards, and Health Canada ICH Q1A stability guidelines collectively elevate validation burdens and capital intensity for packaging converters. EPA emissions oversight on pharmaceutical manufacturing facilities indirectly constrains coating and printing process choices for secondary packaging. Stakeholders must monitor evolving USP chapters on extractables and leachables, as biologics sensitivity shifts material qualification timelines from months to years.
Market Dynamics
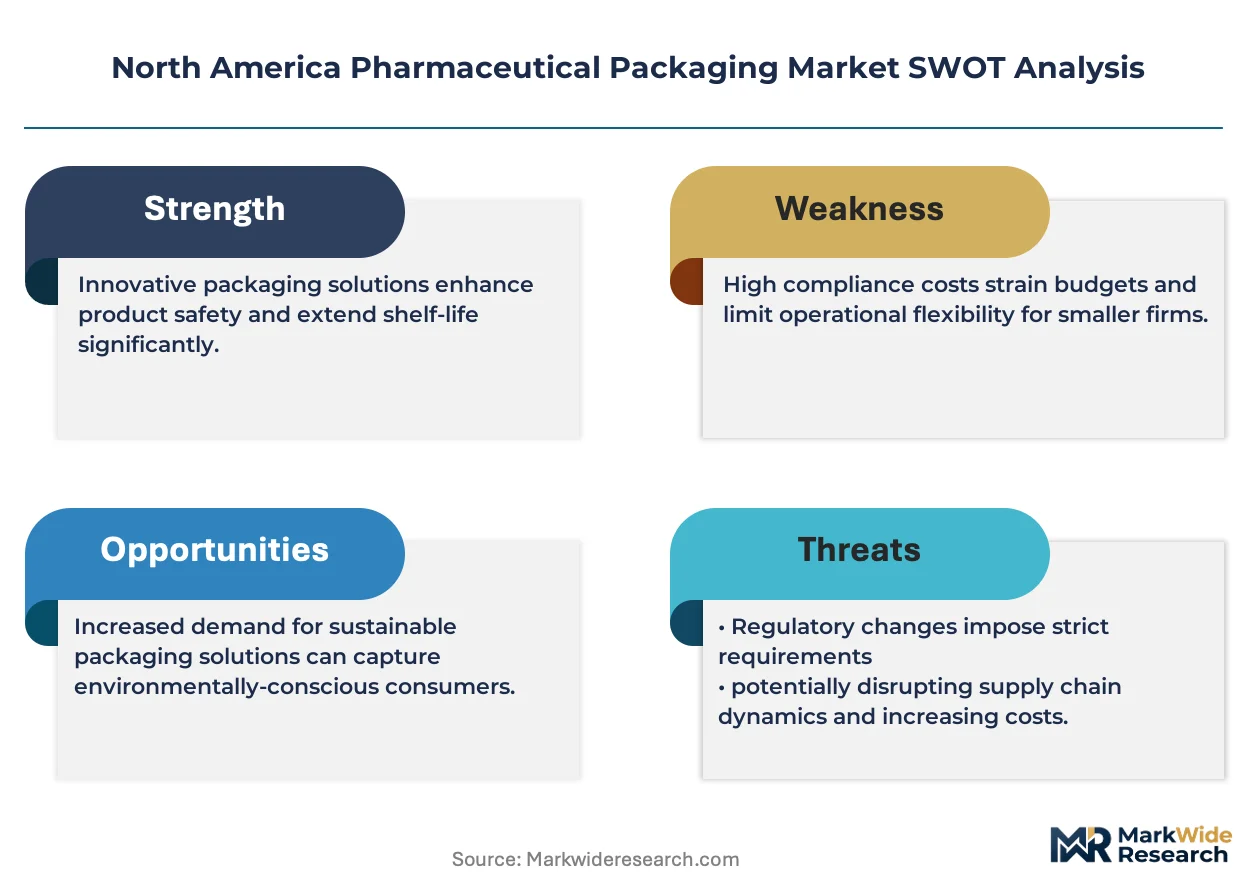
FDA serialization mandates under the Drug Supply Chain Security Act are compressing qualification timelines while biologics cold-chain requirements expand material validation burdens across North American pharmaceutical supply chains.
Growth Catalysts
- Biologics cold-chain expansion:Temperature-sensitive monoclonal antibodies and cell therapies require validated thermal packaging systems, driving demand for phase-change materials and active temperature-controlled containers across Massachusetts and New Jersey manufacturing clusters.
- USP <1207> container closure integrity:Mandatory helium leak detection and probabilistic methods for sterile barrier systems are upgrading quality infrastructure across parenteral packaging lines.
- Child-resistant compliance tiers:CPSC protocol convergence with FDA pediatric safety guidance is forcing reformulation of closure mechanisms for oral solid dose formats.
Market Restraints
- Resin supply concentration:Polypropylene and cyclic olefin polymer feedstocks for high-barrier blister films concentrate among Gulf Coast petrochemical suppliers, exposing converters to hurricane-season disruption risk.
- Glass furnace capacity constraints:Borosilicate tubing for USP Type I vials faces eighteen-month lead times as regenerative furnace rebuilds lag demand from injectable biologics.
- Extractables-leachables validation:USP <1664> chapters extending qualification timelines to multi-year horizons for elastomeric and plastic components delay new product introductions.
Strategic Opportunities
- Prefilled syringe format migration:Self-administration trends in chronic disease management are opening capacity for combination product packaging integrating device and primary container.
- Smart packaging integration:NFC-enabled blisters and temperature-logging labels converge with cloud traceability platforms to create subscription-based compliance services.
- Canadian serialization alignment:Health Canada ICH harmonization with FDA DSCSA timelines creates cross-border packaging standardization opportunities for Great Lakes distribution hubs.
Industry Challenges
- Serialization engineer scarcity:Line integration specialists capable of aggregating bottle-to-case-to-pallet data hierarchies command premium compensation in the Northeast corridor.
- Legacy equipment retrofit costs:Mechanical blister lines require camera-based vision systems and laser etching modules to meet 2024 unit-level traceability deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pharmaceutical Packaging Market |
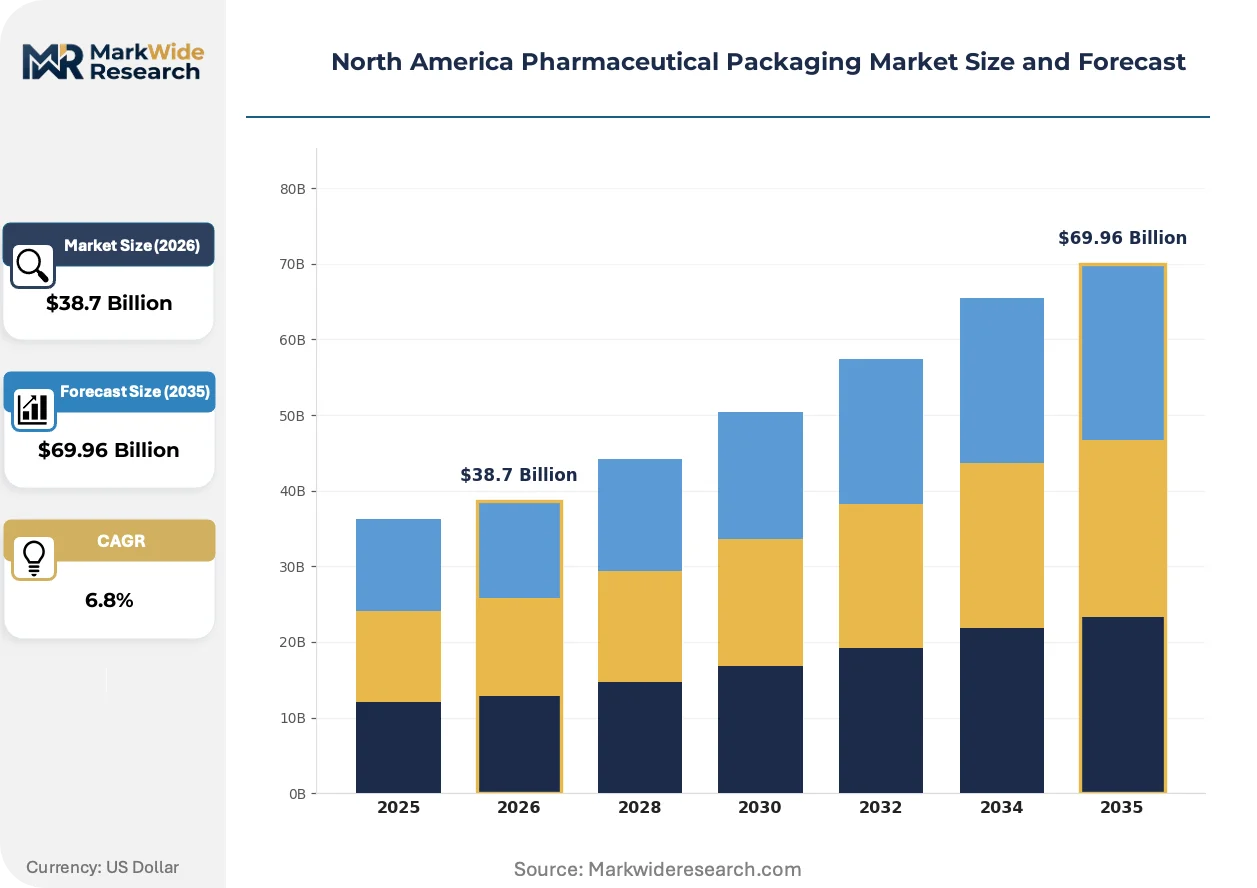
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Vials, Ampoules, Labels Material: Plastic, Glass, Aluminum, Paper End User: Pharmaceutical Companies, Contract Manufacturers, Healthcare Facilities, Research Laboratories Packaging Type: Primary Packaging, Secondary Packaging, Tertiary Packaging, Child-Resistant Packaging |
| Companies Covered | Owens-Illinois, Inc., Berry Global, Inc., Amcor PLC, Gerresheimer AG, WestRock Company, Becton Dickinson & Co., Sonoco Products Company, Schott Pharma, West Pharmaceutical Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pharmaceutical Packaging Market Strategic Shifts
Active and passive temperature-control technologies are fragmenting cold-chain packaging architectures while digital traceability layers embed compliance deeper into primary container functions.
Multilayer barrier films incorporating ethylene vinyl alcohol and polyvinylidene chloride are bifurcating moisture protection standards for oral solids. Oral oncology manufacturers in Pennsylvania and New Jersey are specifying sub-0.1 g/m²/day water vapor transmission rates for hygroscopic kinase inhibitors. This performance tier is compressing commodity blister formats into undifferentiated generics while premium structures capture chronic therapy segments.
FDA's 2023 guidance on post-approval changes management for packaging components is tightening change-control documentation for marketed products. Converters must now demonstrate equivalent performance across statistical batches rather than single-lot qualification. Parenteral glass and elastomer suppliers serving Massachusetts biologics clusters are absorbing the heaviest validation burden as ANDA holders defer material switches.
Hospital and specialty pharmacy buyers are consolidating packaging specifications across therapeutic franchises to compress supplier bases. Integrated delivery networks in Texas and California are mandating universal serialization data formats and consolidated freight programs from primary packaging vendors. This procurement consolidation is most visible in oncology and immunology verticals where formulary standardization reduces operational complexity.
North America Pharmaceutical Packaging Market Segmentation
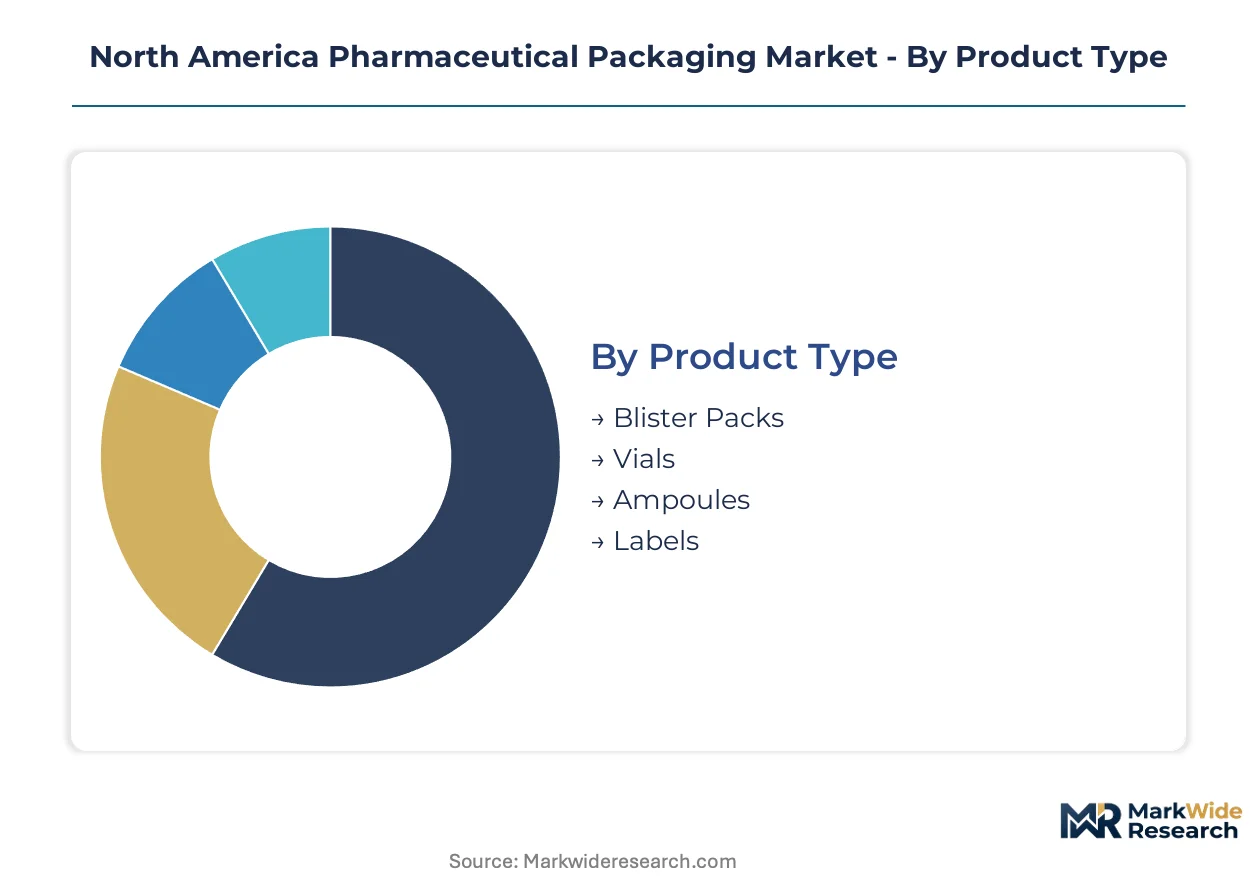
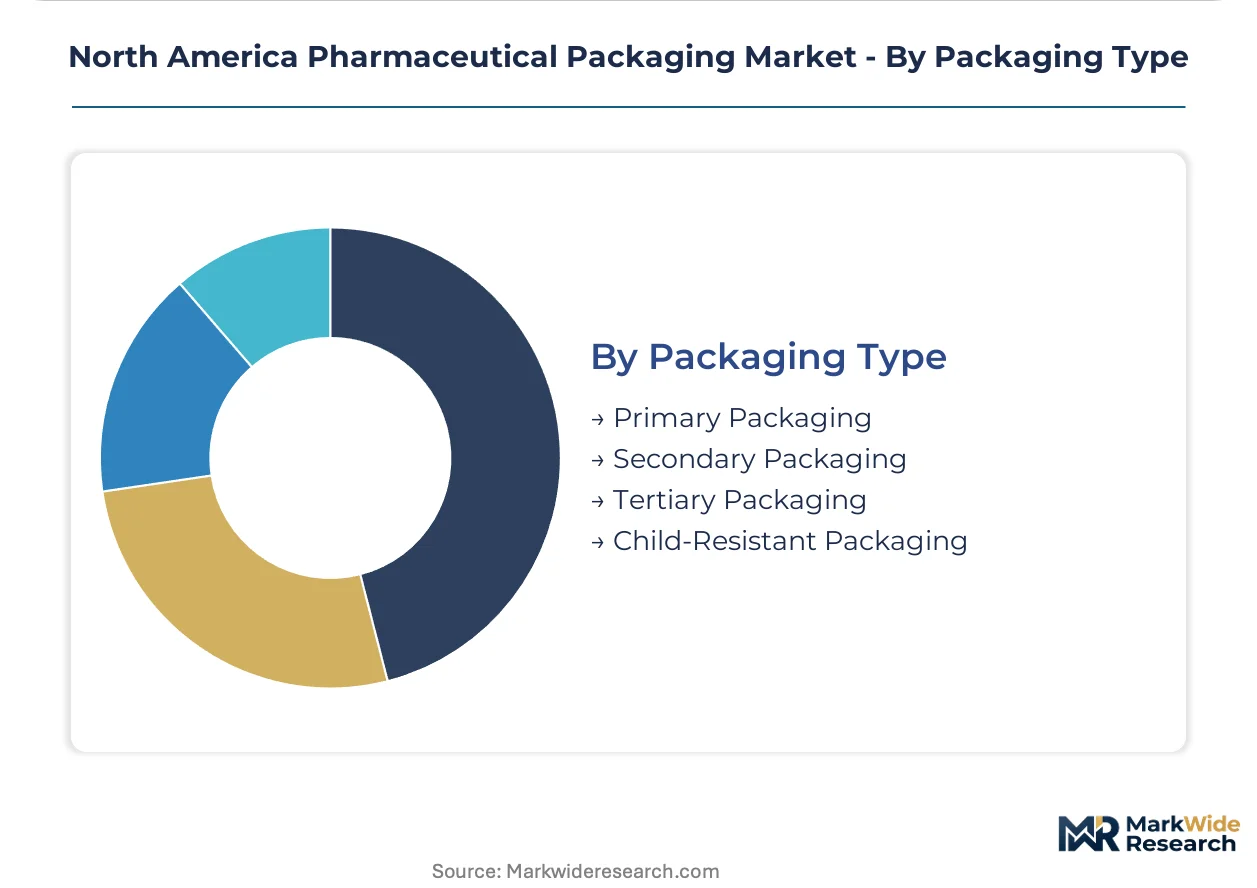
Segmentation in pharmaceutical packaging determines regulatory compliance pathways, capital allocation priorities, and supply chain partnerships. Material choices and packaging tiers carry distinct validation burdens that reshape procurement strategies across North American manufacturing clusters.
Product Type:
Channel distribution varies sharply by product type, with blister packs flowing through retail pharmacy networks while vials concentrate in hospital and specialty pharmacy procurement channels.
- Blister Packs:Multilayer barrier structures incorporating ethylene vinyl alcohol and polyvinylidene chloride films dominate oral solid dispensing. New Jersey and Pennsylvania oral oncology manufacturers specify sub-0.1 g/m²/day water vapor transmission rates for hygroscopic kinase inhibitors, compressing commodity formats into undifferentiated generics.
- Vials:Borosilicate glass containers with USP Type I hydrolytic resistance certification prevent protein aggregation in parenteral biologics. Massachusetts biologics clusters absorb eighteen-month lead times for borosilicate tubing as regenerative furnace rebuilds lag demand from injectable therapies.
- Ampoules:Single-dose glass containers for emergency and anesthetic applications require flame-sealed tips and scored neck designs for clean break opening.
- Labels:Serialization-ready substrates with tamper-evident features and temperature-indicating inks support DSCSA compliance across distribution hierarchies.
By volume, blister packs lead. By growth pace, vials are climbing the fastest.
Material:
Cost tiers separate material selection, with premium barrier polymers commanding validation premiums over commodity substrates while glass maintains position in high-stability applications.
- Plastic:Cyclic olefin polymers and polypropylene feedstocks for high-barrier blister films concentrate among Gulf Coast petrochemical suppliers, exposing converters to hurricane-season disruption risk.
- Glass:Borosilicate and soda-lime compositions serve distinct stability requirements, with Type I certification mandatory for parenteral biologics.
- Aluminum:Cold-form foil laminates provide absolute moisture and light barriers for tropical climate distribution.
- Paper:Secondary carton substrates incorporate authentication features and patient information leaflets with Braille embossing for accessibility compliance.
Plastic substrates dominate unit volumes. Glass commands the steepest expansion trajectory in value terms.
End User:
Customer type dictates packaging specification complexity, with pharmaceutical companies driving standardization while contract manufacturers absorb multi-client validation burdens.
- Pharmaceutical Companies:Integrated manufacturers in the Northeast corridor consolidate specifications across therapeutic franchises to compress supplier bases and mandate universal serialization data formats.
- Contract Manufacturers:Multi-site packaging operations serving ANDA holders defer material switches due to extended extractables-leachables qualification timelines under USP <1664> chapters.
- Healthcare Facilities:Hospital and specialty pharmacy buyers mandate consolidated freight programs and temperature-logging capabilities for cold-chain therapies.
- Research Laboratories:Clinical trial packaging requires adaptive label designs and blinded container configurations for investigational products.
Pharmaceutical companies anchor procurement volumes. Contract manufacturers are gaining share fastest as outsourcing accelerates.
Packaging Type:
Maturity gradients separate packaging tiers, with primary containers carrying the heaviest regulatory burden while tertiary systems focus on distribution efficiency.
- Primary Packaging:Direct product-contact containers face USP <1207> container closure integrity mandates requiring helium leak detection and probabilistic validation methods for sterile barrier systems.
- Secondary Packaging:Cartons and labels integrate serialization-ready surfaces with aggregation hierarchies from bottle to case to pallet.
- Tertiary Packaging:Shippers and pallets incorporate phase-change materials and active temperature-controlled containers for biologics cold-chain validation.
- Child-Resistant Packaging:CPSC protocol convergence with FDA pediatric safety guidance forces reformulation of closure mechanisms for oral solid dose formats.
Primary packaging dominates value capture. Child-resistant formats are expanding most quickly as compliance tiers tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Generic oral solid dose buyers in Mexico exhibit acute price sensitivity while biologics manufacturers in Massachusetts absorb substantial cost premiums for validated cold-chain systems. The Northeast corridor commands the steepest packaging valuations in North America.
United States
FDA serialization mandates under DSCSA compress qualification timelines for Massachusetts and New Jersey biologics clusters. USP <1207> container closure integrity standards enforce helium leak detection protocols across parenteral packaging lines. Pennsylvania oral oncology manufacturers specify sub-0.1 g/m²/day moisture barriers for kinase inhibitors.
Canada
Health Canada ICH Q1A stability guidelines harmonize with FDA timelines, creating cross-border standardization opportunities for Great Lakes distribution hubs. The national pharmaceutical regulator mandates serialization alignment with US DSCSA schedules. Ontario packaging converters serve as secondary supply sources for US biologics manufacturers seeking geographic redundancy.
Mexico
Generic pharmaceutical manufacturing concentrates in Mexico City and Querétaro, driving demand for cost-optimized blister formats with basic moisture protection. COFEPRIS regulatory convergence with FDA standards elevates export qualification requirements. Northern border states host maquiladora operations supplying secondary packaging for US distribution.
North America Pharmaceutical Packaging Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across North American pharmaceutical packaging. Consolidation pressures concentrate high-barrier film and glass vial production among integrated multinationals while regional converters capture generic oral solid dose volumes. Three archetypes dominate: integrated material-science conglomerates, specialized primary container fabricators, and diversified industrial packaging suppliers. Capacity expansion and strategic partnerships represent the dominant competitive moves as serialization deadlines compress qualification windows.
Among integrated material-science conglomerates, Amcor PLC and Berry Global occupy positions spanning film extrusion through finished container supply. Gerresheimer AG exemplifies the specialized primary container archetype with concentrated exposure to borosilicate glass and parenteral formats. These three entities represent distinct strategic postures—material integration, barrier specialization, and dimensional precision—without overlapping core competencies.
| Leading Market Players |
|---|
| Owens-Illinois, Inc. |
| Berry Global, Inc. |
| Amcor PLC |
| Gerresheimer AG |
| WestRock Company |
| Becton Dickinson & Co. |
| Sonoco Products Company |
| Schott Pharma |
| West Pharmaceutical Services, Inc. |
| Others |
Value Chain & Pricing Dynamics
Polypropylene substitution for cyclic olefin polymers in mid-tier blister films is redrawing procurement geography toward Gulf Coast petrochemical corridors while compressing margin structures for converters serving generic oral solid dose manufacturers.
Pricing Analysis
After-sales revenue from serialization validation services and cold-chain qualification consulting now drives lifetime customer value beyond unit container sales. Three-tier pricing structure across premium, standard, and economy levels separates USP Type I certified borosilicate vials from commodity soda-lime formats and basic polypropylene blisters. Price differentiation hinges on FDA certification tier and volume commitment scale. Pricing pressure stems from generic pharmaceutical buyers consolidating supplier bases across therapeutic franchises. Mexican generic manufacturers exhibit acute price sensitivity while Massachusetts biologics clusters absorb substantial cost premiums for validated cold-chain systems.
Supply Chain Analysis
Strategic stockpiling of borosilicate tubing and high-barrier resin feedstocks dominates inventory strategy as eighteen-month furnace rebuild cycles and hurricane-season disruption risks force buffer holdings. Supply concentrates in the United States, Canada, and Mexico with raw material dependencies on Gulf Coast polypropylene, Pennsylvania ethylene vinyl alcohol films, and German borosilicate glass feedstock. Single-source vulnerability pervades regenerative furnace capacity for USP Type I vials. Distribution runs through integrated delivery networks consolidating freight programs across Northeast corridor manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American pharmaceutical packaging represents an early-cycle expansion story as biologics cold-chain requirements penetrate chronic disease management and self-administration formats accelerate adoption of combination product packaging.
For Market Incumbents: Consolidate serialization engineering capabilities and helium leak detection infrastructure to defend against emerging specialized cold-chain entrants. Amcor PLC and Berry Global should deepen backward integration into film extrusion to secure polypropylene and cyclic olefin polymer feedstock access. Certification investment in USP <1207> and USP <1664> validation protocols anchors retention of Massachusetts and New Jersey biologics contracts. For New Entrants and Emerging Players: Lead with smart packaging integration targeting Texas and California integrated delivery networks mandating universal serialization data formats. The most penetrable white-space sits in NFC-enabled blisters and temperature-logging labels for oncology and immunology verticals. A subscription-based compliance service model bypasses capital-intensive furnace investments required for glass vial entry. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors specialized primary container fabricators with dimensional precision capabilities and existing USP Type I certification. Long-term viability over the next decade rests on exposure to biologics rather than generic oral solid dose commoditization. Acquisition targets should demonstrate validated cold-chain packaging systems and established relationships with Massachusetts or New Jersey manufacturing clusters. The signal to watch is Health Canada ICH harmonization progress with FDA DSCSA timelines as a cross-border standardization inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Extrusion | Captive polypropylene supply insulates converters from Gulf Coast hurricane disruption risks. |
| Smart Packaging Platform Development | NFC-enabled blisters create recurring revenue streams through cloud traceability subscriptions. |
| Cold-Chain Validation Infrastructure | Phase-change material testing capacity secures biologics contracts from Massachusetts clusters. |
| Serialization Engineering Acquisition | Line integration specialists command premium compensation in Northeast corridor talent markets. |
| Canadian Distribution Hub Expansion | Ontario facilities provide geographic redundancy for US biologics manufacturers under Health Canada alignment. |
Study Parameters
Desk research of FDA DSCSA guidance documents, USP chapter revisions, and Health Canada ICH harmonization notices preceded structured interviews with packaging converters, pharmaceutical procurement directors, and serialization engineering specialists. Secondary validation drew from EPA emissions disclosures, SEC 10-K filings of listed packaging conglomerates, and trade data on polypropylene and cyclic olefin polymer imports. Bottom-up demand modeling across dosage formats and therapeutic categories triangulated against top-down market sizing from capital expenditure announcements and capacity expansion disclosures.
Variance decomposition across material tiers, packaging types, and end-user segments shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include primary-secondary-tertiary containment hierarchy, glass-plastic-aluminum-paper material substrate, and pharmaceutical company versus contract manufacturer procurement channel. CAGRs derived from regression analysis of historical capital intensity patterns and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated USP <1207> container closure integrity adoption curves and DSCSA serialization deadline compliance rates.
The analysis sits within stated boundaries; outcomes outside sustained biologics pipeline expansion or accelerated generic consolidation would require recalibration. Forecasts reflect assumptions on regulatory timeline adherence and raw material supply continuity. Revision becomes warranted when resin supply disruption frequency or serialization engineer scarcity crosses thresholds that compress qualification windows beyond manageable operational parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceuticals Pouch Market
Pharmaceutical Packaging
Prescription Pharmacy Bags Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Middle East and Africa Ampoules Packaging Market
Pharmaceutical Packaging
Smart Pharmaceutical Packaging Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Pharmaceutical Ampoules Market
Pharmaceutical Packaging
Parenteral Drugs Packaging Market
Pharmaceutical Packaging
Pharmaceutical Labeling Market
Pharmaceutical Packaging
Global Ampoules Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Nasal Spray Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Packaging Market