
 Nasal Spray Packaging Market | 2026-2036
Nasal Spray Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Nasal Spray Packaging Market Intelligence
Pharmaceutical polymer engineering talent is unwinding capacity bottlenecks across European and North American converter networks. AptarGroup Inc. dominates precision spray pump technology through captive mold-making capabilities. Gerresheimer AG anchors glass primary packaging supply for preservative-free nasal formulations. Berry Global Inc. leverages multi-layer plastic extrusion to compete on cost at scale in over-the-counter segments.
Nasal spray packaging encompasses primary and secondary containment systems engineered to deliver metered aqueous or powder formulations through the nasal mucosa, typically incorporating crimp-sealed aluminum canisters, polyethylene terephthalate bottles, or borosilicate glass vials with elastomeric pump actuators calibrated to 50-200 microliter dose volumes. Blister packs and pump closures lead unit volume due to their dominance in allergy and decongestant portfolios, while glass vials capture premium margin pools in biologic nasal therapies requiring cold-chain stability. Plastic bottles sustain the fastest growth trajectory as generic manufacturers seek lightweight, shatter-resistant alternatives to glass for emerging market distribution.
FDA cGMP standards and EMA Annex 1 sterile manufacturing guidelines shape material selection, forcing converters toward validated blow-fill-seal lines and extractables-leachables testing protocols. ISO 15378 pharmaceutical packaging quality systems further gate market access for secondary suppliers lacking certified quality management. Stakeholders must monitor evolving USP <661> plastic packaging standards and EU MDR device classification shifts that could reclassify certain spray pumps as drug-device combination products.
Market Dynamics
Pharmaceutical converters face mounting pressure from FDA cGMP and EMA Annex 1 sterile manufacturing mandates that demand validated blow-fill-seal lines and extractables-leachables testing protocols. These requirements are compressing supplier margins while simultaneously raising entry barriers for secondary packaging vendors.
Growth Catalysts
- EMA Annex 1 sterile guidelines:European regulators now mandate closed-system processing for preservative-free nasal biologics, forcing converters toward barrier-isolation technology investments.
- India contract packaging hubs:Mumbai and Ahmedabad clusters serve multinational drug makers seeking cost-optimized nasal spray assembly for emerging market distribution.
- Metered-dose pump calibration:Precision engineering at 50-200 microliter volumes enables hormone therapy and vaccine delivery expansion into previously injectable-only indications.
Market Restraints
- Borosilicate glass supply concentration:European and Indian glass converters control premium vial supply for cold-chain biologics, creating single-source vulnerability.
- Medical-grade polymer feedstock volatility:Cyclo-olefin polymer and high-density polyethylene prices fluctuate with petrochemical indices, squeezing converter margins.
- ISO 15378 certification timelines:Pharmaceutical packaging quality system validation requires 12-18 month audit cycles, delaying market access for new entrants.
Strategic Opportunities
- Germany biologics corridor:Frankfurt-Rhine-Main cluster demands preservative-free glass primary packaging for peptide and protein nasal formulations.
- United States IRA domestic manufacturing incentives:Contract packaging reshoring creates procurement openings for blow-fill-seal plastic bottle converters.
- Smart pump-actuator convergence:Bluetooth-enabled dose-counters and NFC authentication layers create value-add differentiation in allergy medication segments.
Industry Challenges
- Polymer engineering talent scarcity:Blow-fill-seal line operation and extractables-leachables protocol design require specialized skill sets concentrated among German and Swiss technical institutes.
- Legacy aluminum canister crimping equipment:Retrofitting existing lines for ISO 15378 compliance demands capital outlays that mid-tier converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nasal Spray Packaging Market |
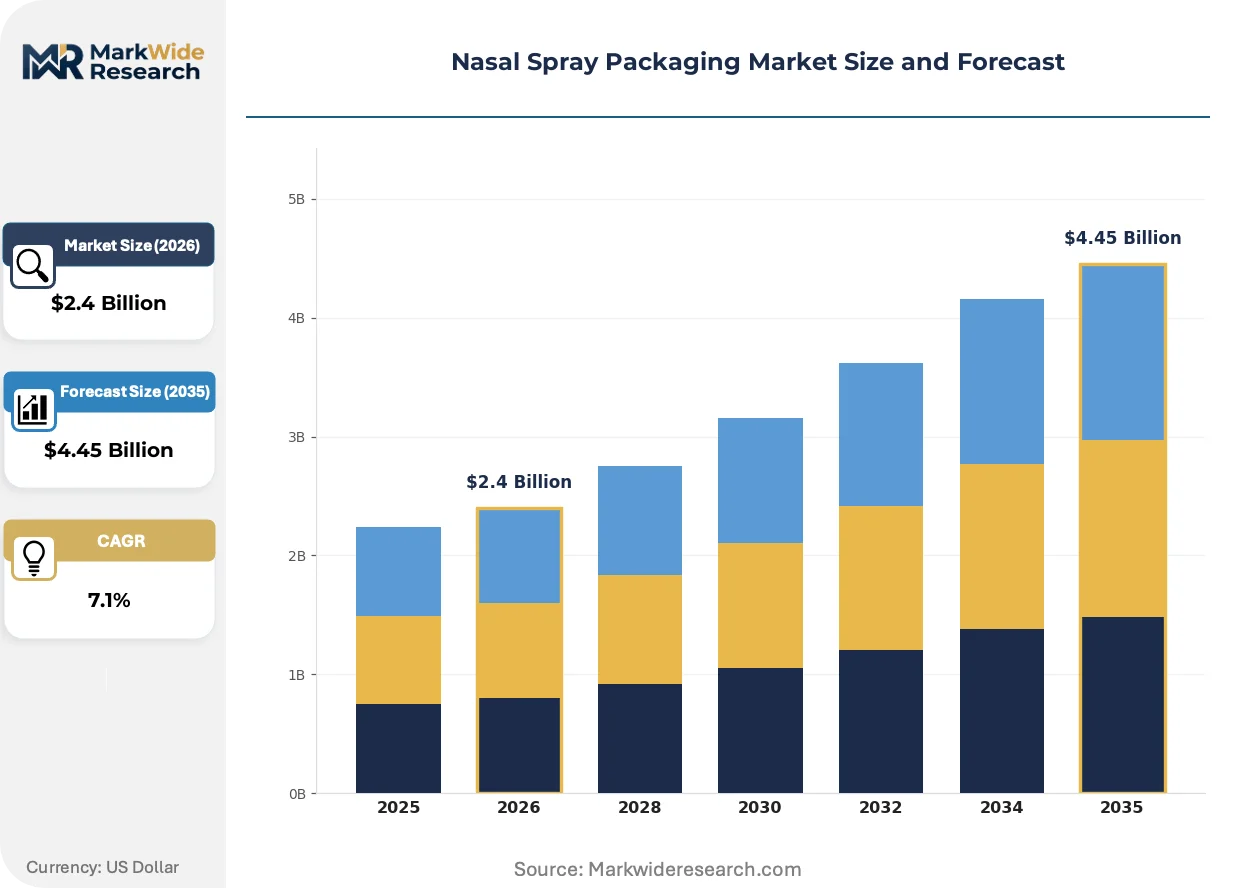
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Bottles, Vials, Pouches Material: Plastic, Glass, Aluminum, Composites Closure Type: Dropper, Spray Nozzle, Cap, Pump Distribution Channel: Pharmacies, Online Retail, Hospitals, Clinics |
| Companies Covered | Berry Global Inc., Coster Tecnologie Speciali S.p.A., AptarGroup Inc., Bormioli Pharma United States Inc., SGD Pharma, Gerresheimer AG, West Pharmaceutical Services Inc., Nolato AB, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nasal Spray Packaging Market Strategic Shifts & Innovations
Packaging technology is fragmenting along sterility-grade lines, with premium biologic applications demanding glass barrier systems while generic over-the-counter portfolios migrate toward multi-layer plastic alternatives. This divergence is compressing the middle tier of converters unable to serve both specifications.
Multi-layer plastic extrusion is bifurcating the cost-performance frontier for nasal spray primary containment. Generic manufacturers in India and the United States are adopting polyethylene terephthalate and high-density polyethylene bottles at accelerated procurement cycles. This shift is enabling lightweight, shatter-resistant distribution models for tropical and remote-market supply chains while compressing glass converter volumes in non-biologic segments.
EU MDR device classification revisions are reclassifying certain metered-dose spray pumps as drug-device combination products. Brussels regulatory interpretation is forcing pump actuator manufacturers toward notified body involvement and clinical evidence requirements. Premium hormone therapy and vaccine delivery segments face the steepest compliance ramps, with German and French packaging clusters absorbing the bulk of certification costs.
Buyer consolidation among multinational pharmaceutical manufacturers is compressing supplier negotiation cycles and unbundling after-sales technical support. Procurement teams at major allergy and decongestant portfolios now demand captive mold-making capabilities and dedicated line capacity as table stakes. This concentration is most visible in United States and Germany, where three contract packaging hubs control the majority of nasal spray volume allocation decisions.
Nasal Spray Packaging Market Segmentation
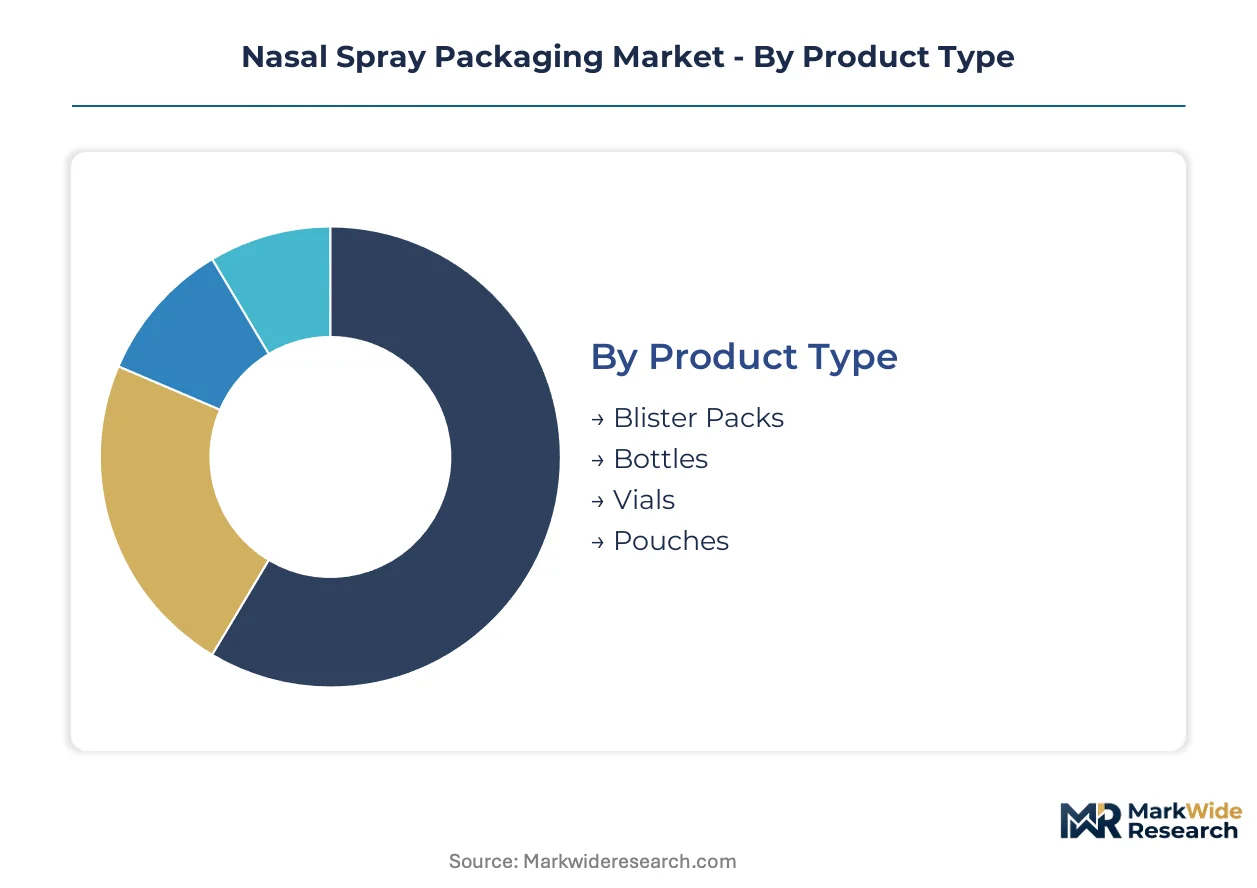
Nasal spray packaging segments fragment along sterility requirements and cost-performance trade-offs. Material selection and closure precision determine access to biologic versus generic over-the-counter markets, with regulatory compliance acting as the primary gating mechanism for supplier participation.
Product Type:
Margin pools concentrate in primary containment systems where dose precision and sterility assurance command premium positioning.
- Blister Packs:Multi-cavity aluminum-laminate or PVC structures house unit-dose nasal spray devices for allergy and decongestant portfolios. Demand clusters in United States retail pharmacy chains where child-resistant compliance and shelf visibility drive procurement specifications.
- Bottles:Polyethylene terephthalate and high-density polyethylene containers dominate high-volume generic manufacturing, with blow-fill-seal lines enabling aseptic filling without terminal sterilization. Indian contract packaging hubs in Mumbai and Ahmedabad source these most aggressively for emerging market distribution.
- Vials:Borosilicate glass primary packaging serves preservative-free biologic formulations requiring cold-chain stability.
- Pouches:Flexible laminate sachets accommodate powder nasal sprays and single-use emergency applications.
The dominant share belongs to bottles, while blister packs are closing the gap fastest.
Material:
Cost tiers separate commodity feedstocks from validated pharmaceutical-grade alternatives with extractables-leachables documentation.
- Plastic:Cyclo-olefin polymer and medical-grade polyethylene formulations enable lightweight, shatter-resistant distribution models. FDA cGMP validation requirements for blow-fill-seal processing create margin compression for converters lacking dedicated line investments.
- Glass:Borosilicate and treated soda-lime vials anchor premium biologic segments where oxygen and moisture barrier performance is non-negotiable. Frankfurt-Rhine-Main pharmaceutical clusters in Germany specify these for peptide nasal formulations.
- Aluminum:Crimp-sealed canisters with fluoropolymer internal coatings serve pressurized metered-dose applications.
- Composites:Multi-layer structures combining polymer barriers with aluminum foil laminates address niche stability requirements.
Plastic commands volume leadership, though glass maintains the steepest expansion trajectory in biologics.
Closure Type:
Application specificity determines engineering complexity and regulatory scrutiny intensity.
- Spray Nozzle:Precision-molded orifices calibrated to 50-200 microliter volumes enable hormone therapy and vaccine delivery expansion. EU MDR device classification revisions are reclassifying certain configurations as drug-device combination products, forcing notified body involvement.
- Pump:Metered-dose actuators with mechanical dose-counters dominate allergy medication portfolios. Bluetooth-enabled and NFC-authentication layers are emerging as value-add differentiators in United States retail channels.
- Dropper:Simple squeeze-bulb designs persist in pediatric and geriatric segments prioritizing ease of use over dose precision.
- Cap:Child-resistant and tamper-evident closures serve secondary safety functions across all primary containment formats.
Pump mechanisms hold the largest installed base, while spray nozzles are gaining share fastest through biologic therapy adoption.
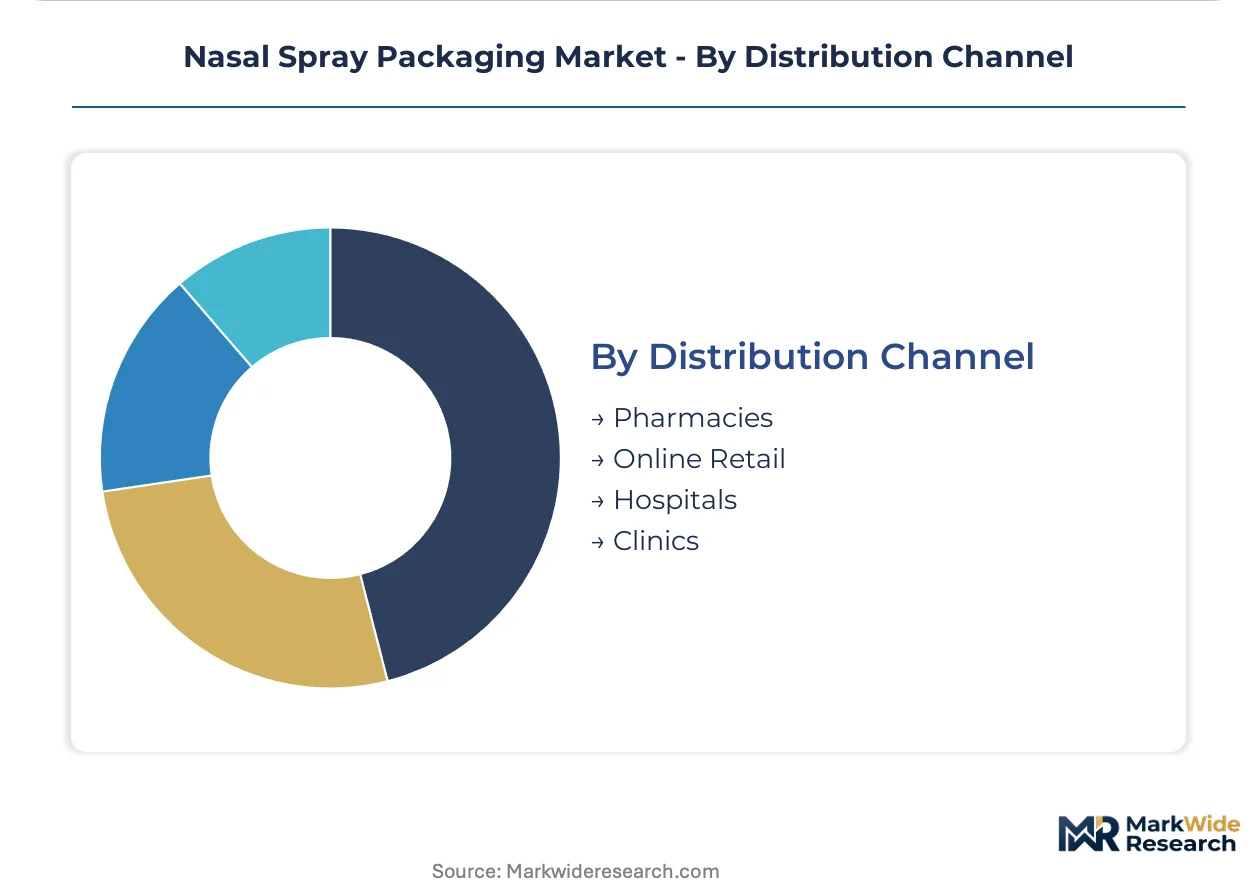
Distribution Channel:
Customer type and procurement scale shape packaging specification requirements and supplier relationship structures.
- Pharmacies:Chain and independent retail outlets drive standardized blister pack and bottle specifications with demanding shelf-life labeling requirements. United States pharmacy benefit managers influence packaging format decisions through formulary placement incentives.
- Hospitals:Institutional procurement emphasizes unit-dose packaging and barcode traceability for medication safety protocols.
- Online Retail:Direct-to-consumer channels prioritize damage-resistant secondary packaging and temperature-monitoring indicators for last-mile delivery.
- Clinics:Outpatient settings favor professional-use formats with higher dose volumes and simplified patient instruction leaflets.
Pharmacies retain the dominant position, yet online retail is climbing the fastest as direct-to-consumer biologic delivery models expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cGMP standards anchor the United States as the dominant geography, with European EMA Annex 1 sterile guidelines and India's CDSCO contract packaging clusters collectively shaping procurement flows across three continents.
United States
Pharmaceutical benefit managers drive standardized blister pack specifications through formulary placement incentives. The Inflation Reduction Act domestic manufacturing incentives are accelerating contract packaging reshoring. New Jersey and Pennsylvania packaging corridors absorb the bulk of blow-fill-seal plastic bottle converter investments.
Germany
Frankfurt-Rhine-Main pharmaceutical clusters demand preservative-free glass primary packaging for peptide nasal formulations. EMA Annex 1 sterile guidelines mandate closed-system processing investments. Bavarian and Baden-Württemberg converter networks specialize in barrier-isolation technology for biologic containment.
India
Mumbai and Ahmedabad contract packaging hubs serve multinational drug makers seeking cost-optimized nasal spray assembly. CDSCO regulations align with FDA cGMP standards for export-oriented facilities. Gujarat's pharmaceutical manufacturing zones concentrate multi-layer plastic extrusion capacity for emerging market distribution.
China
NMPA medical device classification revisions are reclassifying certain spray pumps as drug-device combination products. Yangtze River Delta packaging clusters invest in blow-fill-seal line automation. Shanghai and Jiangsu province converters supply cyclo-olefin polymer bottles for domestic hormone therapy portfolios.
France
ANSM regulatory interpretation of EU MDR device classification is forcing notified body involvement for premium pump actuators. Île-de-France pharmaceutical corridors absorb certification costs for hormone therapy segments. Lyon and Strasbourg packaging specialists focus on extractables-leachables testing protocol compliance.
Nasal Spray Packaging Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, creating a bifurcated structure where precision engineering capabilities separate premium biologic suppliers from commodity over-the-counter converters. Three archetypes dominate: captive mold-making pump specialists, glass primary packaging anchors, and multi-layer plastic extrusion scale players. Competitive moves concentrate on strategic partnerships for barrier-isolation technology access and geographic expansion into Indian contract packaging hubs.
Among North American and European packaging conglomerates, AptarGroup Inc., Gerresheimer AG, and Berry Global Inc. occupy distinct archetype positions. AptarGroup exemplifies the precision pump engineering tier through its captive manufacturing capabilities. Gerresheimer anchors glass primary packaging supply for preservative-free formulations requiring cold-chain stability. Berry Global represents the scale-driven plastic extrusion vector competing on lightweight, shatter-resistant alternatives for generic portfolios.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Coster Tecnologie Speciali S.p.A. |
| AptarGroup Inc. |
| Bormioli Pharma United States Inc. |
| SGD Pharma |
| Gerresheimer AG |
| West Pharmaceutical Services Inc. |
| Nolato AB |
| Amcor plc |
| Others |
Cost & Logistics Intelligence
Ninety-day inventory cycles for medical-grade cyclo-olefin polymer feedstock concentrate pricing power among German and Swiss converters with validated blow-fill-seal lines, while Indian contract packaging hubs exploit freight-cost arbitrage to compress margins on standard polyethylene bottle formats.
Pricing Analysis
Geographic price spreads between Frankfurt-Rhine-Main glass vial converters and Mumbai plastic bottle assemblers exceed three-to-one for comparable dose-volume specifications. Pricing stratifies across ISO 15378-certified premium tiers for biologic containment, validated standard tiers for generic prescription portfolios, and uncertified economy tiers for over-the-counter decongestants. Cost compression in the economy tier intensifies because Indian hubs are expanding blow-fill-seal capacity for emerging market export. Generic manufacturers in Gujarat exhibit the highest price sensitivity, while German peptide therapy developers accept steep premiums for borosilicate glass with extractables-leachables documentation.
Supply Chain Analysis
Germany, India, and the United States anchor pharmaceutical packaging converter networks for nasal spray primary containment. Medical-grade polymer feedstock draws from petrochemical complexes in the US Gulf Coast and Middle Eastern suppliers, while borosilicate glass production rests on European and Indian furnace operations. Single-source vulnerability concentrates in German barrier-isolation technology for preservative-free biologics. Distribution runs through multinational pharmaceutical contract packaging hubs in New Jersey, Frankfurt-Rhine-Main, and Mumbai-Ahmedabad clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart pump-actuator convergence with Bluetooth dose-counters and NFC authentication layers signals a platform-economics inflection, where packaging hardware becomes a data-capture node interoperable with pharmacy benefit manager systems and patient adherence platforms.
For Market Incumbents: Secure captive mold-making capabilities for precision 50-200 microliter spray nozzles before EU MDR device classification revisions trigger notified body bottlenecks. Deepen backward integration into medical-grade polymer compounding to offset cyclo-olefin price volatility from petrochemical indices.
For New Entrants and Emerging Players: Differentiate on extractables-leachables testing protocol compliance for preservative-free biologic segments where ISO 15378 certification scarcity creates procurement friction. Target the United States IRA domestic manufacturing incentive corridor for blow-fill-seal plastic bottle assembly reshoring opportunities.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity arbitrage play because EMA Annex 1 sterile guideline enforcement and FDA cGMP validation requirements are accelerating supplier consolidation faster than demand growth. Watch for CDSCO alignment with FDA standards in Indian export-oriented facilities as the signal for contract packaging hub maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Isolation Technology Investment | EMA Annex 1 compliance for preservative-free biologics mandates closed-system processing infrastructure in German clusters. |
| Captive Mold-Making Capability Expansion | Pump actuator precision requirements and EU MDR reclassification risks favor vertically integrated precision engineering. |
| Extractables-Leachables Protocol Certification | FDA cGMP and USP standards gate access to premium hormone therapy and vaccine delivery segments. |
| Smart Actuator Platform Development | Bluetooth-enabled dose-counters create data-layer differentiation for pharmacy benefit manager formulary placement. |
| Indian Contract Packaging Hub Scale-Up | CDSCO-aligned facilities in Mumbai-Ahmedabad serve multinational cost-optimization for emerging market distribution. |
Research Approach
Cross-validation between primary interviews with pharmaceutical packaging procurement managers, blow-fill-seal line engineers, and regulatory affairs specialists and secondary validation through FDA cGMP inspection databases, EMA Annex 1 guidance documents, and ISO 15378 certification registries anchors the qualitative findings. Bottom-up triangulation of converter capacity announcements and top-down reconciliation with pharmaceutical manufacturer procurement disclosures frame the market sizing.
Sensitivity analysis across material-grade tiers, closure precision specifications, and regional regulatory clusters shapes the analytical framework over the projection horizon. Modeled segmentation spans primary containment format, sterility assurance level, and distribution channel intensity. CAGRs derive from capacity expansion pipelines, patent expiry calendars for nasal-administered biologics, and regulatory compliance cost trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained FDA-EMA regulatory convergence and stable petrochemical feedstock pricing; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in EU MDR device classification interpretation and Indian CDSCO export facility audit outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Labeling Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Active and Intelligent Packaging in Pharmaceutical Market
Pharmaceutical Packaging
Global Ampoules Packaging Market
Pharmaceutical Packaging
Polymer Vials Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
Recycled Prescription Bag Market
Pharmaceutical Packaging
Plastic Pharma Tray Market
Pharmaceutical Packaging
Intravenous Packaging Market
Pharmaceutical Packaging
China Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Tubes Market
Pharmaceutical Packaging
Nutraceutical Packaging Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Plastic Vials and Ampoules Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Vials Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Packaging Market