
 Global Ampoules Packaging Market | 2026-2036
Global Ampoules Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ampoules Packaging Market Analysis
The ampoules packaging industry is rebalancing between premium borosilicate glass for biologics and commodity soda-lime formats for generic injectables. Gerresheimer AG leverages vertical integration from tubular glass to finished sterile packaging, sustaining cost advantages across European pharmaceutical corridors. Schott AG dominates FIOLAX borosilicate supply, while Stevanato Group differentiates through ready-to-use containment and delivery systems.
Ampoules packaging denotes small sealed vials, typically manufactured from Type I borosilicate glass or cyclic olefin polymers, designed for single-dose sterile drug containment with breakaway neck or pre-scored opening mechanisms. Glass ampoules retain dominance in parenteral applications where inertness and barrier integrity against oxygen and moisture prove critical, though plastic formats gain traction in biologics requiring reduced surface interaction. The material type dimension shows glass occupying mature, high-volume positions while composite laminates capture fastest growth in temperature-sensitive biologics; closure type segmentation reveals breakaway designs leading in emerging markets while automated open systems concentrate margin pools in automated filling lines for Western biopharma.
FDA serialization requirements under the Drug Supply Chain Security Act and EU MDR traceability mandates compel ampoule manufacturers to embed unit-level identifiers and strengthen supply chain documentation. ISO 15378 pharmaceutical packaging standards and USP <660> glass container testing protocols further constrain material selection and supplier qualification timelines. Stakeholders must monitor evolving EMA guidelines on extractables and leachables, as regulatory stringency in primary packaging increasingly determines market access and customer retention in biologics supply chains.
Market Dynamics
The ampoules packaging market is restructuring around biologics containment requirements, with cell and gene therapy scale-up forcing material selection trade-offs between borosilicate glass inertness and polymer surface compatibility.
Growth Catalysts
- EU MDR serialization mandates:Unit-level traceability requirements under the Medical Device Regulation are compelling pharmaceutical manufacturers to upgrade primary packaging specifications, expanding demand for certified ampoule suppliers capable of embedded authentication features.
- Cell therapy manufacturing:Autologous and allogeneic cell therapy production facilities are specifying Type I borosilicate ampoules for cryopreserved dose containment, creating specialized demand corridors in regenerative medicine hubs.
- German glass production corridors:Concentrated specialized glass manufacturing in Bavaria and Thuringia is shortening pharmaceutical supply chains for European biologics producers, reducing lead times for customized ampoule formats.
Market Restraints
- Borosilicate raw material concentration:High-purity silica sand and boron oxide supply concentrates among limited specialty chemical producers, exposing ampoule manufacturers to input cost volatility and qualification delays.
- FDA Drug Supply Chain Security Act compliance timelines:Serialization deadline extensions have compressed investment windows, forcing smaller ampoule converters to defer capacity upgrades or exit the pharmaceutical tier.
- Pre-filled syringe substitution:Ready-to-use delivery formats are capturing single-dose parenteral applications previously served by breakaway ampoules, particularly in oncology and autoimmune therapeutic categories.
Strategic Opportunities
- Indian pharmaceutical export manufacturing:CDSCO-aligned facilities producing for US and EU markets are localizing ampoule procurement, creating openings for domestic glass tubing conversion capacity.
- Cyclic olefin polymer-borosilicate hybrid formats:Laminated composite ampoules combining barrier performance with reduced protein adsorption are penetrating temperature-sensitive biologics segments.
- Japan PMDA Sakigake designation pathway:Accelerated approval frameworks for regenerative medicines are shortening packaging qualification cycles for ampoule suppliers with established biocompatibility dossiers.
Industry Challenges
- Extractables and leachables validation:EMA guideline evolution on elemental impurities and glass delamination is extending analytical testing timelines for new ampoule formats.
- ISO 15378 pharmaceutical packaging certification:Quality management system audits for primary packaging materials are consuming 12-18 month qualification periods, constraining supplier switching.
- Automated filling line integration:Breakaway ampoule dimensional tolerances must synchronize with high-speed depyrogenation and filling equipment, requiring joint engineering between packaging and machinery suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ampoules Packaging Market |
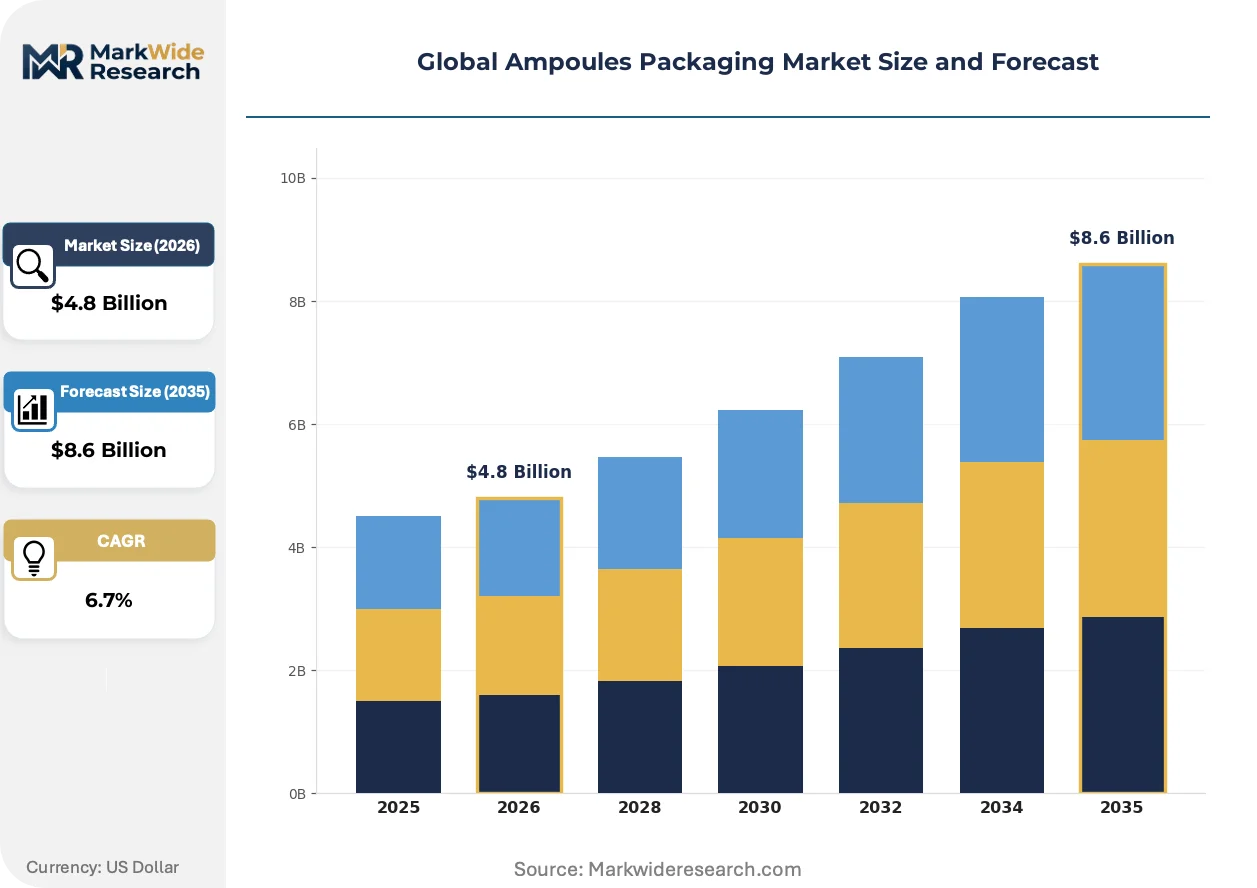
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Plastic, Composite, Others Closure Type: Breakaway, Screw Cap, Automated Open, Others End User: Pharmaceuticals, Biologics, Nutraceuticals, Cosmetics Capacity: 1ml, 5ml, 10ml, 20ml |
| Companies Covered | Gerresheimer AG, Schott AG, Stevanato Group, Amcor Group GmbH, Nipro Corporation, SGD Pharma, Adelphi Healthcare Packaging, DWK Life Sciences, Bormioli Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ampoules Packaging Market Emerging Trajectories
Digital manufacturing integration and materials science advances are compressing development cycles for specialized ampoule formats while regulatory data requirements reshape supplier qualification protocols.
Robotic vision-guided ampoule inspection is automating defect detection in high-speed production environments. Biologics contract manufacturers are deploying these systems to satisfy FDA process analytical technology expectations. The technology is automating quality assurance staffing ratios while reducing false-reject rates for cosmetic glass imperfections.
EMA guidelines on glass delamination and elemental impurities are tightening material documentation requirements for parenteral packaging. Ampoule suppliers must now submit comprehensive extractables profiles and accelerated aging data prior to commercial supply agreements. European biologics manufacturers are responding by consolidating supplier bases to those with dedicated analytical laboratories and regulatory affairs capabilities.
Pharmaceutical procurement organizations are implementing direct supplier contracting for primary packaging materials, bypassing traditional distribution intermediaries. Large molecule drug sponsors are negotiating multi-year ampoule supply agreements with embedded capacity reservation clauses. This consolidation is most visible among US-based biotech firms scaling from clinical to commercial manufacturing phases.
Global Ampoules Packaging Market Segmentation
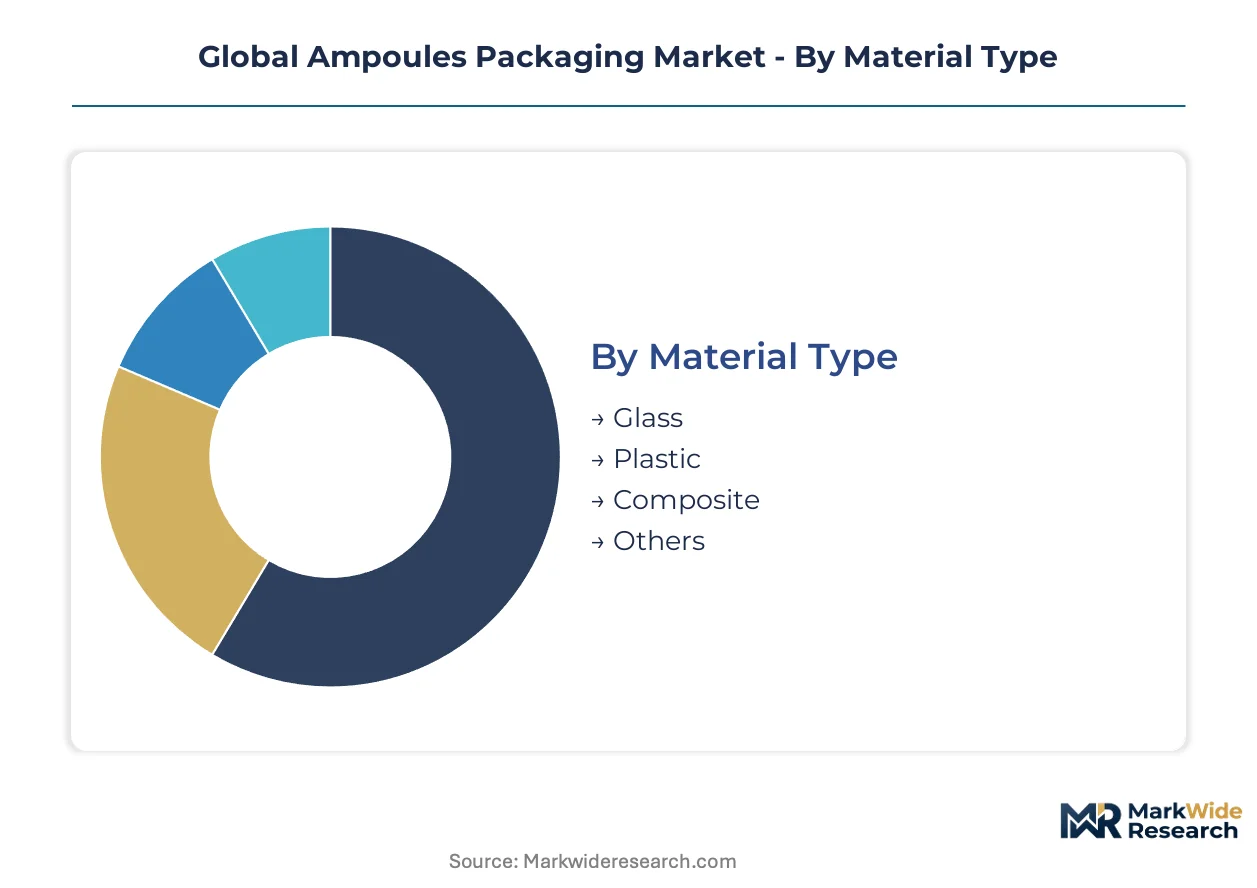
Ampoules packaging segmentation reflects divergent containment requirements across therapeutic categories. Material selection and closure mechanisms determine regulatory pathway complexity and manufacturing equipment compatibility. Capacity specifications align with dose volumes in parenteral administration protocols.
Material Type:
Upgrade cycles in pharmaceutical containment are forcing material substitution decisions as biologics manufacturers requalify primary packaging against evolving EMA extractables guidelines.
- Glass:Type I borosilicate formulations dominate parenteral applications requiring inert surfaces and oxygen barrier integrity. German production corridors supply FIOLAX-grade tubing to European biologics manufacturers facing EU MDR traceability mandates.
- Plastic:Cyclic olefin polymers reduce protein adsorption in temperature-sensitive biologics. Japanese regenerative medicine facilities specify these formats for cryopreserved cell therapies under PMDA Sakigake pathways.
- Composite:Laminated structures combining borosilicate barrier layers with polymer interfaces serve specialty applications.
- Others:Metallic and ceramic formats occupy niche diagnostic containment roles.
Glass sits at the top of the volume ranking, with Plastic climbing the fastest.
Closure Type:
Automation intensity in filling operations determines closure specification, with high-speed lines demanding dimensional precision that manual breakaway formats cannot satisfy.
- Breakaway:Pre-scored neck designs enable manual opening in clinical and emerging market settings. Indian pharmaceutical exporters specify these formats for generic injectables targeting price-sensitive procurement.
- Automated Open:Mechanized opening systems integrate with robotic filling and inspection equipment. US biotech firms scaling commercial manufacturing specify these for FDA process analytical technology compliance.
- Screw Cap:Reclosable formats serve multi-dose veterinary and diagnostic applications.
- Others:Crimp-sealed and snap-fit variants occupy specialized containment niches.
Breakaway formats retain the largest installed base, though Automated Open systems are gaining share fastest in Western biopharma corridors.
End User:
Regulatory stringency tiers separate end-use categories, with biologics demanding the most extensive supplier qualification protocols.
- Pharmaceuticals:Generic injectables and small-molecule parenterals specify standardized glass formats. CDSCO-aligned Indian manufacturers drive volume procurement for US and EU export markets.
- Biologics:Cell and gene therapies require customized ampoule geometries for cryopreserved dose containment. EMA guidelines on glass delamination force extended analytical testing timelines for these applications.
- Nutraceuticals:Dietary supplement injectables specify lower-certification packaging tiers.
- Cosmetics:Ampoule formats for professional skincare occupy premium positioning with distinct aesthetic requirements.
Pharmaceuticals command the largest volume position, while Biologics shows the steepest expansion trajectory.
Capacity:
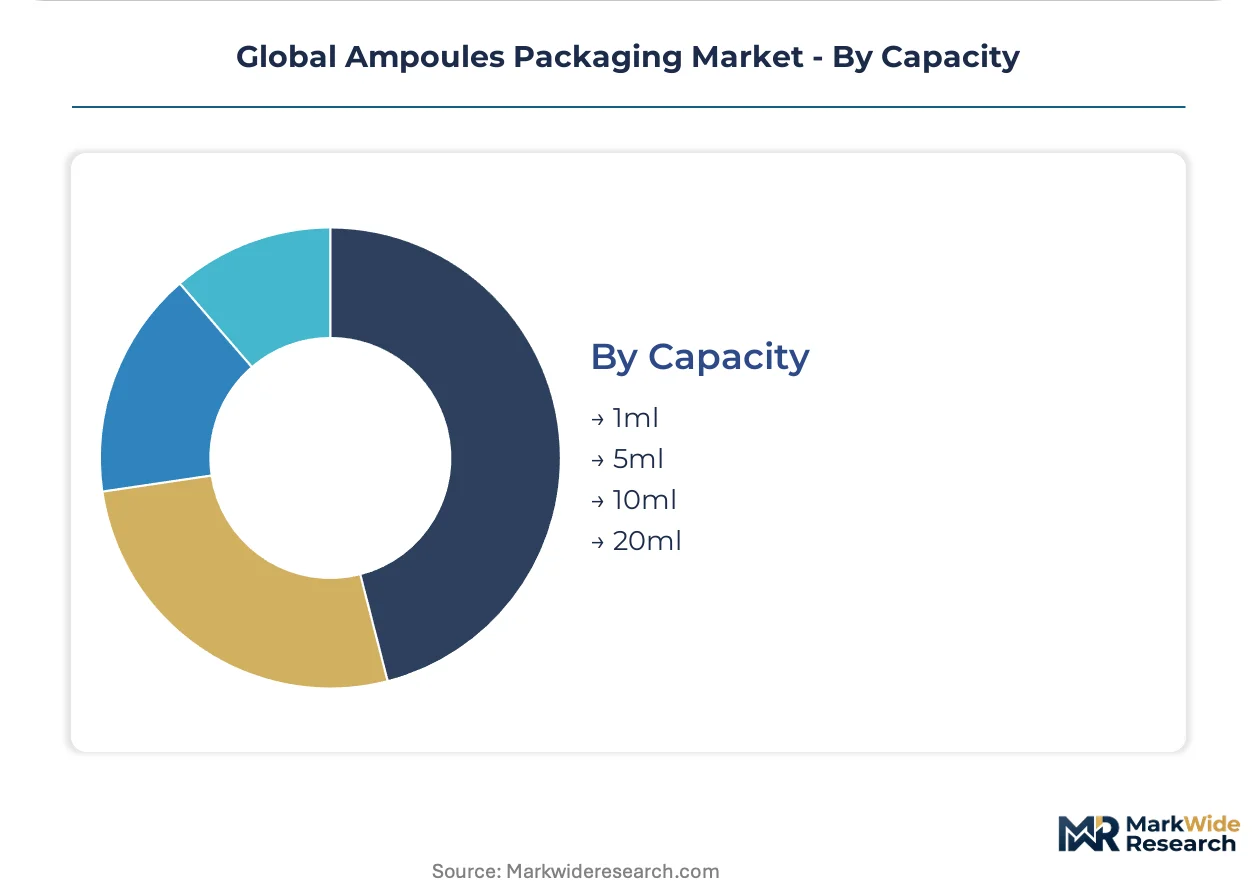
Dose volume standardization in therapeutic protocols constrains capacity selection, with oncology and vaccine applications driving 1ml and 5ml procurement.
- 1ml:Single-dose vaccine and high-potency biologic containment. Automated filling lines in Bavaria specialize in tight-tolerance production for these formats.
- 5ml:Standard antibiotic and analgesic injectable volumes. German glass corridors concentrate capacity for this specification serving European hospital procurement.
- 10ml:Multi-dose veterinary and diagnostic reagent applications.
- 20ml:Large-volume parenteral nutrition and contrast media containment.
5ml sits at the top of the volume ranking, with 1ml climbing the fastest on vaccine and cell therapy demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized glass technicians and pharmaceutical packaging engineers concentrate in southern Germany, where centuries of precision manufacturing tradition intersect with modern biologics containment demands. This workforce density anchors European supply chains for borosilicate ampoule production. Talent migration patterns from Eastern European technical universities reinforce this concentration.
Germany
Cell therapy manufacturing facilities in Bavaria and Thuringia specify FIOLAX-grade borosilicate ampoules for cryopreserved dose containment. EU MDR serialization mandates compel embedded traceability features in primary packaging. The Mainz-Wiesbaden corridor hosts specialized glass tubing conversion capacity serving European biologics producers.
United States
Biotech firms scaling from clinical to commercial manufacturing negotiate multi-year ampoule supply agreements with embedded capacity reservations. FDA Drug Supply Chain Security Act compliance timelines compress investment windows for serialization-ready formats. The Greater Boston cluster drives demand for automated open systems in high-speed filling operations.
India
CDSCO-aligned pharmaceutical exporters localize ampoule procurement for US and EU market access. Domestic glass tubing conversion capacity expands to serve generic injectables manufacturing. The Ahmedabad-Vadodara corridor concentrates breakaway ampoule production for price-sensitive emerging market procurement.
Japan
Regenerative medicine facilities under PMDA Sakigake accelerated approval pathways specify cyclic olefin polymer formats for temperature-sensitive biologics. Reduced protein adsorption requirements drive material substitution in cell therapy containment. The Kansai region hosts specialized polymer ampoule fabrication for cryopreserved dose applications.
China
NMPA traceability requirements for pharmaceutical packaging strengthen documentation standards for domestic ampoule suppliers. Local biologics manufacturers requalify primary packaging against evolving extractables guidelines. The Yangtze River Delta concentrates glass ampoule conversion capacity serving domestic vaccine producers.
Global Ampoules Packaging Market Vendor Landscape
Top-tier vendors anchor premium borosilicate supply, while mid-tier converters compete on generic injectables volume and emerging market price positioning. The vendor base stratifies across three functional tiers: integrated tubing-to-ampoule manufacturers, specialized glass converters, and polymer format specialists. Two dominant competitive moves define current positioning: backward integration into high-purity silica sand sourcing and joint engineering partnerships with automated filling equipment suppliers.
Among German-anchored integrated manufacturers, Gerresheimer AG and Schott AG exemplify the tubing-to-finished-ampoule archetype, while Stevanato Group represents the ready-to-use containment specialist tier. These three entities occupy positions spanning borosilicate supply, conversion capabilities, and regulatory dossier depth for biologics applications.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Schott AG |
| Stevanato Group |
| Amcor Group GmbH |
| Nipro Corporation |
| SGD Pharma |
| Adelphi Healthcare Packaging |
| DWK Life Sciences |
| Bormioli Pharma |
| Others |
Supply Flow & Price Mechanics
EU MDR serialization mandates and FDA DSCSA traceability requirements gate qualified supply access, compressing margins for uncertified converters while embedding authentication features commands premium-tier pricing from biologics manufacturers. Pricing stratifies across three certification tiers: ISO 15378-validated borosilicate formats for cell therapy containment, standard pharmaceutical-grade glass for generic injectables, and economy soda-lime variants for emerging market procurement.
Pricing Analysis
Service bundling separates pure component supply from integrated containment-delivery systems. Price differentiation rests on EMA extractables dossier depth and automated filling line compatibility, with certified suppliers capturing margin premiums. Cost compression in standard glass tiers intensifies as Indian pharmaceutical exporters consolidate procurement volumes. Generic injectables manufacturers exhibit highest price sensitivity; biologics sponsors prioritize regulatory dossier completeness over unit cost.
Supply Chain Analysis
Direct-to-pharma channels handle serialized formats for EU and US compliance, while distribution through regional converters serves price-sensitive emerging markets. Geographic concentration centers on Germany for FIOLAX-grade borosilicate tubing, India for breakaway format conversion, and Japan for cyclic olefin polymer fabrication. Raw material sourcing draws from high-purity silica sand deposits in Bavaria, boron oxide specialty chemical producers, and polymer resin suppliers. Single-source vulnerability in pharmaceutical-grade glass tubing creates supply risk. Distribution runs through qualified supplier networks with embedded regulatory affairs capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge from regulatory cost differentials between EU MDR compliance investments and CDSCO-aligned manufacturing in India, where serialization infrastructure lags but export volume scales.
For Market Incumbents: Anchor FIOLAX-grade supply dominance through backward integration into high-purity silica sand sourcing. Pre-filled syringe substitution threatens breakaway ampoule volumes; defend position by expanding ready-to-use containment system portfolios. Capacity reservation clauses in multi-year biologics contracts lock in revenue visibility. For New Entrants and Emerging Players: Indian CDSCO-aligned pharmaceutical exporters represent an underserved buyer archetype seeking domestic glass tubing conversion capacity. Cyclic olefin polymer-borosilicate hybrid formats for temperature-sensitive biologics offer white-space penetration. Pursue joint engineering partnerships with automated filling equipment suppliers to bypass 12-18 month ISO 15378 qualification barriers. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier glass converters because supplier consolidation under EU MDR and FDA serialization mandates is compressing viable vendor counts. Five-to-ten year viability favors targets with dedicated extractables laboratories and established biocompatibility dossiers. Monitor EMA guideline evolution on glass delamination as inflection signal for accelerated supplier switching.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Silica Sand | Captive raw material supply insulates FIOLAX-grade production from boron oxide price volatility. |
| Ready-to-Use Containment System Expansion | Pre-filled syringe substitution threatens breakaway formats; integrated delivery systems capture biologics margin pools. |
| Joint Engineering with Filling Equipment Suppliers | Automated open system dimensional tolerances require synchronized machinery development for FDA process analytical technology compliance. |
| Multi-Year Capacity Reservation Agreements | US biotech firms scaling commercial manufacturing negotiate embedded clauses securing serialized format supply. |
| Cyclic Olefin Polymer Hybrid Format Development | Laminated composite structures penetrate PMDA Sakigake-designated regenerative medicine applications in Japan. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement encompassed pharmaceutical packaging procurement directors, biologics contract manufacturing executives, regulatory affairs specialists for EMA and FDA submissions, and glass tubing conversion plant managers. Secondary validation drew from FDA Drug Supply Chain Security Act guidance documents, EMA packaging guidelines on extractables and leachables, ISO 15378 certification registries, and USP glass container testing protocols. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Comparable-period anchoring linked historical pharmaceutical packaging expenditure patterns to forward projection assumptions across the analysis window. Segmentation dimensions encompassed material type, closure mechanism, end-user regulatory tier, and capacity specification. CAGRs derived from therapeutic category growth trajectories, biologics pipeline scaling rates, and regional regulatory implementation timelines. Industry-specific inputs included cell therapy manufacturing facility buildout announcements and serialization mandate compliance deadlines.
Inputs from regulatory filing databases and pharmaceutical packaging trade associations were available through the study window; gaps in real-time capacity utilization data from private glass converters introduce uncertainty bands around short-term supply elasticity assumptions. Forecasts reflect documented assumptions regarding biologics containment demand scaling and regulatory timeline adherence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Pharmaceutical Printed Cartons Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
APAC Pharmaceutical Packaging Market
Pharmaceutical Packaging
Plastic Pharma Tray Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Pharmacy Repackaging Systems Market
Pharmaceutical Packaging
India Pharmaceutical Packaging Market
Pharmaceutical Packaging
Temperature Controlled Pharmaceutical Containers Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
United States Ampoules Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Market