
 Prescription Pharmacy Bags Market | 2026-2036
Prescription Pharmacy Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Prescription Pharmacy Bags Market Analytics
Single-source procurement for pharmaceutical packaging is rebalancing toward multi-vendor arrangements as chains seek supply resilience. WestRock Company leverages its integrated paperboard operations to secure long-term contracts with major retail dispensers. DS Smith Plc anchors its position through specialized pharmacy-grade fiber formulations that meet tamper-evident standards. Huhtamaki Oyj competes by extending its flexible packaging expertise into high-barrier plastic bag segments for temperature-sensitive scripts.
Prescription pharmacy bags are specialized containment vessels engineered from kraft paper, polyethylene, or biodegradable films, typically incorporating heat-sealed closures, opacity features, and printed compliance labeling to ensure safe medication transport from dispenser to patient. Paper-based formats sustain dominant volume share due to recyclability alignment with retail pharmacy sustainability mandates, while biodegradable alternatives register the fastest structural ascent as EU Green Deal packaging rules tighten material restrictions. Closure-type segmentation shows seal mechanisms leading in hospital pharmacy settings where contamination control is paramount, whereas drawstring configurations occupy growing share in online pharmacy logistics for consumer convenience.
FDA packaging and labeling regulations govern child-resistance and tamper-evidence requirements, while EPA guidelines constrain plastic content thresholds in disposable medical packaging. The EU F-Gas Regulation and REACH chemical standards further restrict polymer additives used in European pharmacy bag production. Stakeholders must monitor evolving state-level plastic bans in California and New York alongside emerging federal Extended Producer Responsibility frameworks to anticipate material transition costs and compliance timelines.
Market Dynamics
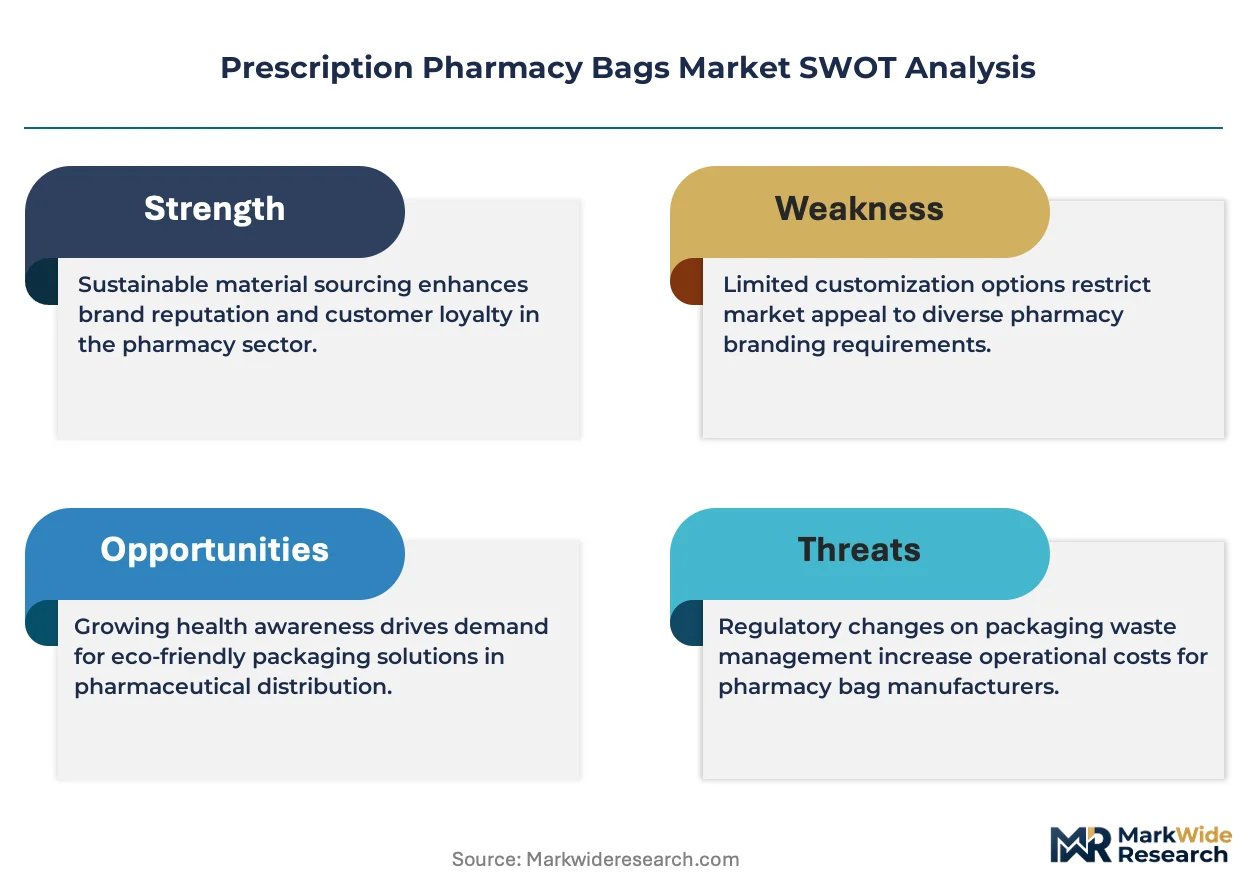
Regulatory pressure on single-use plastics is forcing material transitions across pharmacy bag supply chains faster than converter capacity can adapt. Retail dispensers face simultaneous mandates for tamper-evidence, child-resistance, and recyclability that paper-based formats struggle to satisfy without coating innovations.
Growth Catalysts
- EU Green Deal packaging rules:The Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds, accelerating demand for fiber-based alternatives with pharmacy-grade barrier properties.
- Mail-order pharmacy expansion:Temperature-sensitive biologics shipped direct-to-patient require high-barrier bag formats with integrated insulation layers, creating specification premiums.
- Child-resistant closures:ASTM D3475 testing protocols for senior-friendly yet child-resistant mechanisms are driving bag redesigns in retail pharmacy settings.
Market Restraints
- Polymer additive restrictions:REACH and F-Gas Regulation constraints on fluorinated coatings limit European converters' ability to produce grease-resistant paper bags without reformulation investments.
- Pulp supply concentration:Nordic and Canadian softwood pulp mills control specialty kraft fiber grades, exposing bag manufacturers to input cost volatility and allocation limits.
- Biodegradable performance gaps:PLA and PHA films lack the heat-seal strength and opacity of conventional polyethylene, restricting their use in light-sensitive medication packaging.
Strategic Opportunities
- India retail pharmacy modernization:Organized pharmacy chains under CDSCO oversight are replacing loose paper wrapping with standardized tamper-evident bags as the country's pharmaceutical distribution formalizes.
- QR-code traceability integration:EU MDR unique device identifier requirements create openings for printed electronics and smart labels embedded directly into bag substrates.
- Extended Producer Responsibility frameworks:California and New York state-level EPR laws incentivize closed-loop collection systems that bag manufacturers can operate as service differentiators.
Industry Challenges
- Multilayer film recycling infrastructure:Paper-plastic hybrid bags with polyethylene windows lack compatible waste streams, complicating sustainability claims and compliance documentation.
- Pharmacy automation compatibility:Bag dimensions and stiffness must align with robotic dispensing systems from vendors like ScriptPro and Parata, requiring custom tooling for each installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prescription Pharmacy Bags Market |
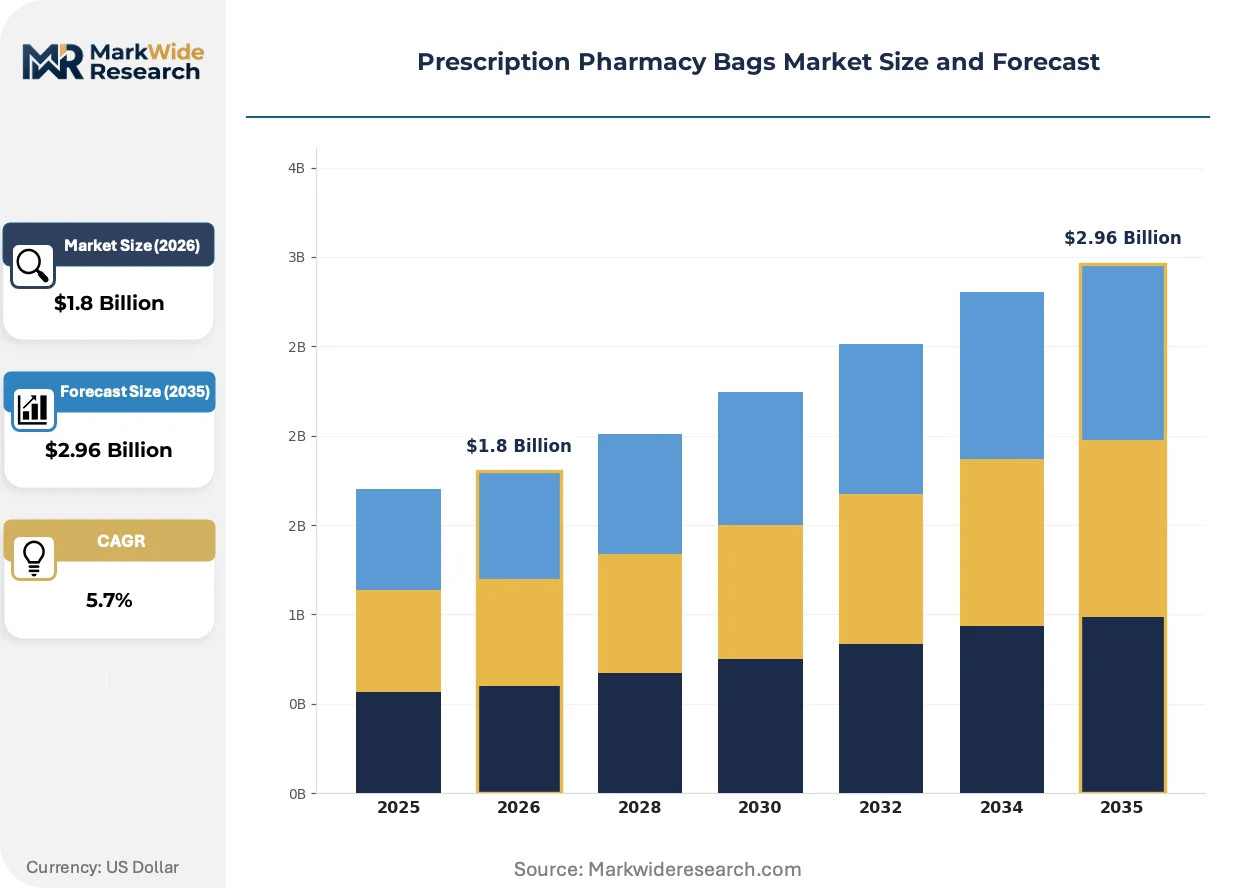
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Biodegradable, Reusable Size: Small, Medium, Large, Extra Large Closure Type: Seal, Velcro, Drawstring, Zipper End User: Retail Pharmacy, Hospital Pharmacy, Online Pharmacy, Clinics |
| Companies Covered | WestRock Company, DS Smith Plc, International Paper Company, Sealed Air Corporation, Huhtamaki Oyj, Mondi Group, Amcor Limited, Novolex, Smurfit Kappa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prescription Pharmacy Bags Market Evolving Landscape
Material science breakthroughs are compressing the performance gap between sustainable substrates and legacy plastics, while digital integration transforms bags from passive containers into active compliance tools. Three developments dominate converter R&D priorities.
Water-based barrier coatings derived from nanocellulose are overtaking fluorochemical treatments in North American pharmacy bag production. These coatings provide comparable grease and moisture resistance without per- and polyfluoroalkyl substance liabilities. WestRock and DS Smith have qualified formulations for CVS Health and Walgreens specifications, enabling full fiber recyclability through standard pulping streams.
REACH Annex XVII restrictions on intentionally added microplastics are compelling European converters to eliminate conventional plastic windows from paper pharmacy bags. The regulation forces adoption of cellulose-based transparent films or redesigned all-paper formats with die-cut viewing apertures. German and French pharmacy chains under ANSM and BfArM oversight are piloting these formats ahead of enforcement deadlines.
Hospital and long-term care facilities are consolidating vendor lists for pharmacy supplies, awarding multi-year contracts to converters who integrate inventory management software with just-in-time bag delivery. This behavior compresses switching cycles and locks out smaller competitors lacking ERP integration capabilities. The pattern is most visible in United States health system procurement, where Premier and Vizient group purchasing organizations favor sole-source arrangements with data-exchange requirements.
Prescription Pharmacy Bags Market Segmentation
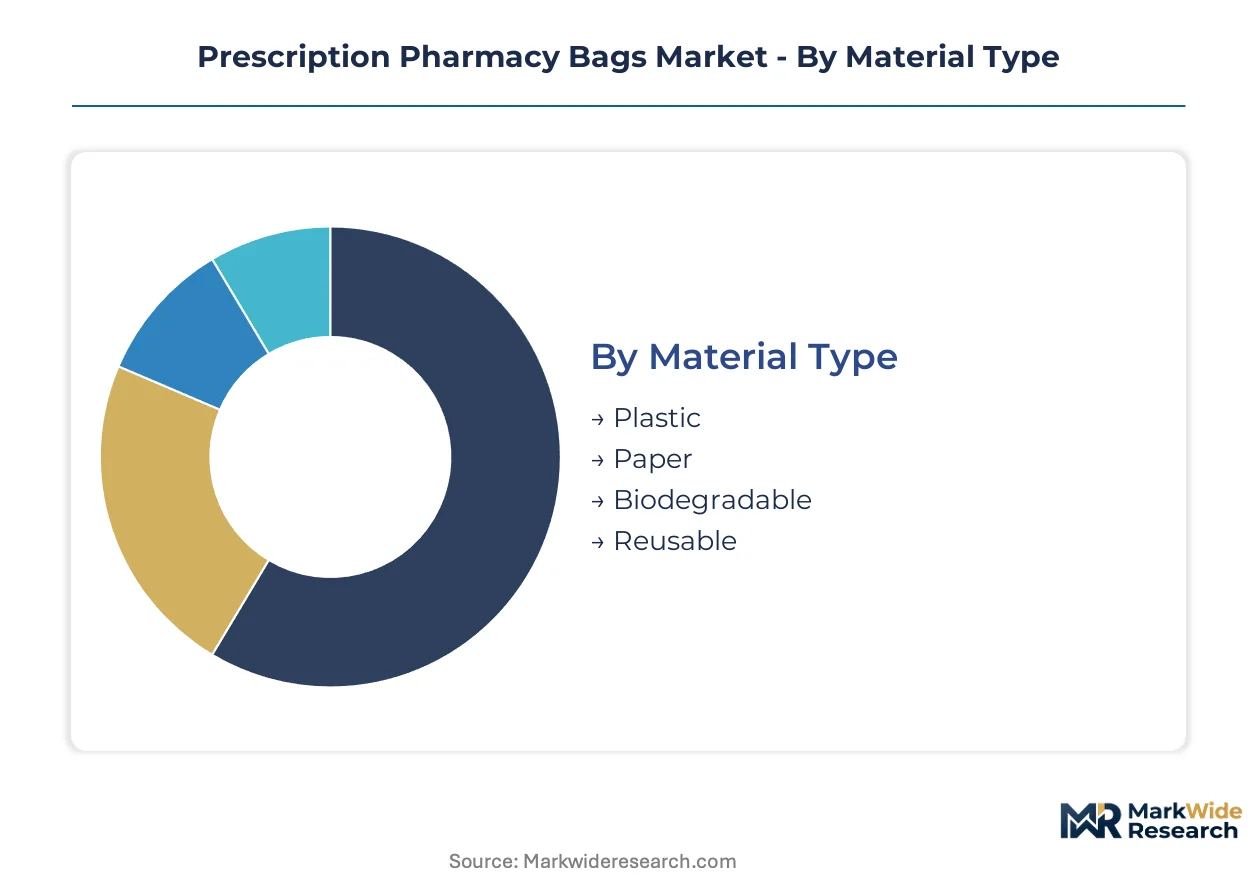
Prescription pharmacy bags serve distinct functional requirements across dispensing environments, with material specifications and closure mechanisms determining compliance eligibility and automation compatibility. Segmentation reveals how converter R&D investments and procurement priorities diverge across retail, hospital, and direct-to-patient channels.
Material Type:
Upgrade cycles in pharmacy bag procurement are accelerating as retail chains replace legacy plastic formats to meet Extended Producer Responsibility mandates and corporate sustainability targets.
- Paper:Kraft fiber constructions with water-based barrier coatings dominate CVS Health and Walgreens procurement specifications due to recyclability through standard municipal streams. Nordic softwood pulp mills supply specialty grades that satisfy FDA opacity requirements for patient privacy while enabling heat-seal compatibility with automated dispensing systems.
- Plastic:Multi-layer polyethylene and polypropylene laminates retain installed base in hospital pharmacy settings where moisture barrier performance and heat-seal integrity override sustainability preferences. REACH Annex XVII constraints on intentionally added microplastics are forcing European converters toward fluorochemical-free formulations.
- Biodegradable:PLA and PHA films from NatureWorks and Danimer Scientific formulations are gaining specification in EU member states under Packaging and Packaging Waste Regulation recycled content thresholds.
- Reusable:Woven polypropylene and silicone-coated fabric bags serve closed-loop programs at Kaiser Permanente and Veterans Affairs facilities with centralized pharmacy operations.
Volume placements concentrate in paper formats across retail chains; the faster expansion belongs to biodegradable alternatives as EU Green Deal enforcement tightens.
Size:
Cost tier differentiation in pharmacy bag procurement separates high-volume standard sizes from premium specifications for specialty medication formats.
- Small:Dimensions of 6x9 inches accommodate 30-day standard pill vials and dominate ScriptPro robotic dispensing system configurations across United States retail pharmacies.
- Medium:8x10 inch formats capture the majority of Walgreens and CVS Health volume procurement for 90-day supply scripts and combination vial-and-literature deliveries.
- Large:Expanded dimensions serve hospital discharge prescriptions with multiple vials, medical devices, and printed patient education materials in bundled configurations.
- Extra Large:Custom specifications for cold-chain biologics shipped through CVS Caremark and Express Scripts mail-order operations integrate insulated pouch inserts within outer bag structures.
Procurement volume clusters in medium formats for retail dispensing; specification premiums concentrate in extra large segments for temperature-sensitive direct-to-patient delivery.
Closure Type:
Application-specific performance requirements drive closure selection, with contamination control priorities in hospitals diverging from consumer convenience demands in e-commerce channels.
- Seal:Heat-sealed polyethylene closures provide tamper-evidence compliance for FDA-regulated dispensing and dominate hospital pharmacy specifications where sterility assurance is mandatory.
- Drawstring:Cotton and synthetic cord configurations enable rapid packing in high-volume mail-order fulfillment centers operated by Amazon Pharmacy and PillPack, with senior-friendly grip designs tested to ASTM D3475 protocols.
- Velcro:Hook-and-loop fasteners support reusable bag programs in closed-loop health system environments with patient return logistics.
- Zipper:Slider and press-to-close mechanisms serve over-the-counter transition bags at retail pharmacy front ends where child-resistance is not mandated but resealability drives consumer preference.
Seal mechanisms command volume share in institutional procurement; drawstring formats are expanding most quickly in online pharmacy logistics for packing speed optimization.
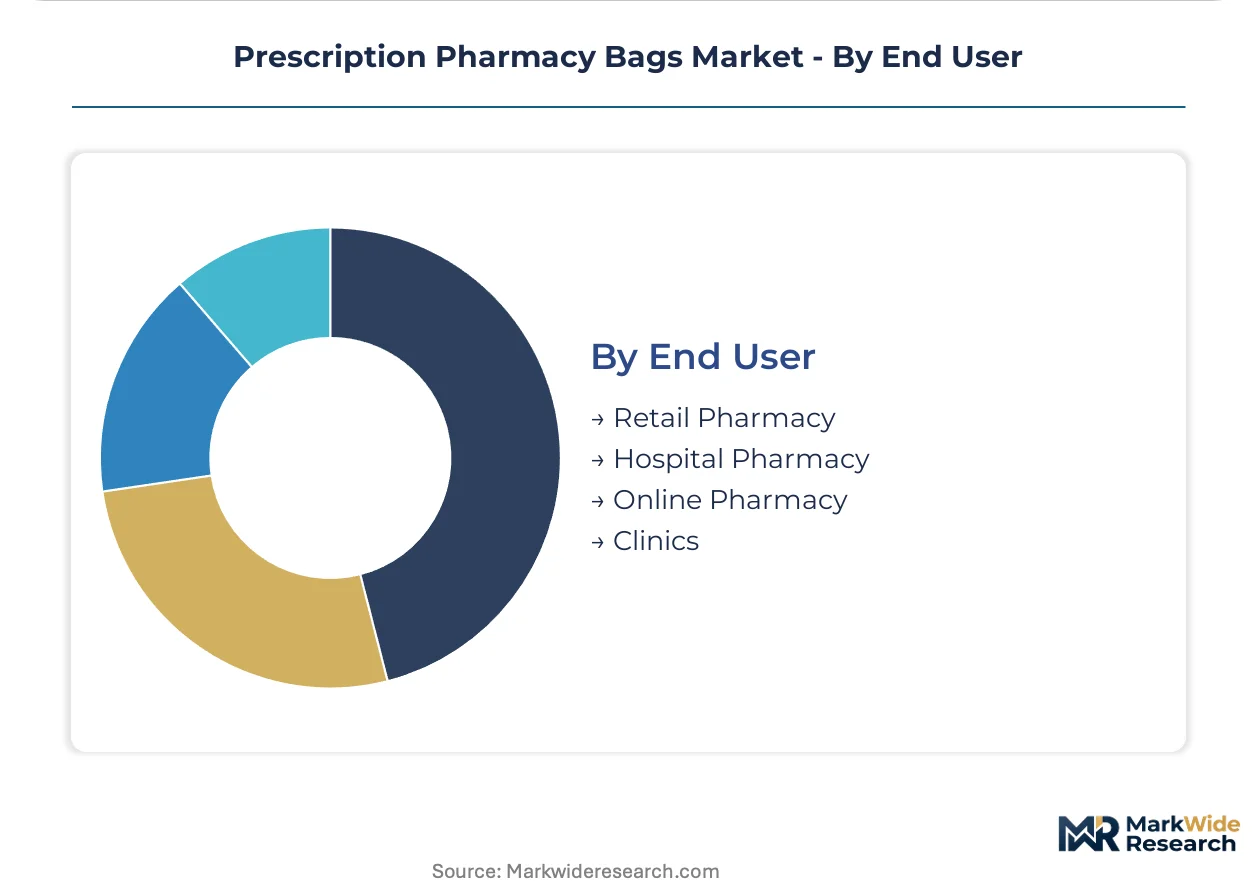
End User:
Customer-type segmentation reveals diverging specification authority, with retail chain central procurement contrasting against hospital pharmacy committee-based vendor selection.
- Retail Pharmacy:CVS Health, Walgreens Boots Alliance, and Rite Aid central procurement teams specify tamper-evident paper bags with integrated receipt pockets and branded exterior printing, driving converter volume through multi-year national agreements.
- Hospital Pharmacy:Health system pharmacy directors at HCA Healthcare and CommonSpirit Health prioritize ASTM-tested child-resistant closures and moisture barrier performance for unit-dose and discharge medication packaging.
- Online Pharmacy:Amazon Pharmacy, PillPack, and Capsule fulfillment operations require dimensionally standardized bags compatible with automated packing lines and thermal label adhesion for last-mile tracking.
- Clinics:Federally qualified health centers and urgent care chains procure lower-specification paper formats through group purchasing organizations like Premier and Vizient with price-sensitive tender processes.
Contract value concentrates in retail pharmacy chains with national scale; the steepest expansion trajectory belongs to online pharmacy segments as direct-to-patient dispensing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nordic softwood pulp mills in Sweden and Finland supply specialty kraft fiber grades that anchor pharmacy-grade paper production across developed markets. Raw material proximity to converter operations shapes regional competitive positioning and compliance cost structures.
United States
CVS Health and Walgreens Boots Alliance central procurement teams drive tamper-evident bag specifications for retail and mail-order dispensing. FDA packaging guidelines govern child-resistance and opacity requirements for patient privacy. Chicago-area converter clusters supply automated dispensing systems for ScriptPro and Parata installations across the Midwest.
Germany
Hospital pharmacy directors at Charité and university medical centers prioritize ASTM-tested closures for discharge medication bundles. REACH Annex XVII restrictions on intentionally added microplastics force elimination of conventional plastic windows from paper bags. The Rhine-Ruhr industrial corridor hosts specialized converters serving ANSM-compliant exports to France.
India
Organized pharmacy chains under CDSCO oversight are replacing loose paper wrapping with standardized tamper-evident formats as pharmaceutical distribution formalizes. State-level plastic waste management rules in Maharashtra and Gujarat accelerate fiber-based transitions. Mumbai-Pune manufacturing clusters produce pharmacy-grade bags for domestic retail and export to Southeast Asian markets.
France
ANSM oversight of hospital pharmacy procurement favors moisture-barrier paper formats with cellulose-based transparent films. EU MDR traceability requirements create demand for QR-code integrated labeling on bag substrates. The Lyon-Grenoble corridor hosts converter operations specializing in senior-friendly closure designs tested to ASTM D3475 protocols.
United Kingdom
NHS pharmacy procurement frameworks specify recyclable paper bags with water-based barrier coatings for primary care dispensing. Extended Producer Responsibility regulations incentivize closed-loop collection systems that manufacturers operate as service differentiators. Manchester-based converters supply retail chains with branded exterior printing and integrated receipt pockets.
Prescription Pharmacy Bags Market Competitive Landscape
Global majors compete with regional champions across material technology and compliance certification dimensions. The market structure concentrates around integrated paperboard producers with captive pulp supply and specialized flexible packaging converters with barrier coating expertise. Three archetypes dominate: integrated fiber producers controlling upstream kraft pulp, multilayer film specialists with pharmaceutical barrier qualifications, and regional converters with health system ERP integration capabilities. Competitive moves center on water-based coating R&D partnerships and multi-year sole-source contracts with group purchasing organizations.
Within the integrated fiber producer tier, WestRock Company and DS Smith Plc exemplify scale-driven positioning through captive paperboard operations. Huhtamaki Oyj occupies a position among flexible packaging specialists extending barrier expertise into temperature-sensitive formats. These three entities represent contrasting strategic anchors: North American integrated supply chain control, European pharmacy-grade fiber specialization, and Nordic flexible packaging technology translation.
| Leading Market Players |
|---|
| WestRock Company |
| DS Smith Plc |
| International Paper Company |
| Sealed Air Corporation |
| Huhtamaki Oyj |
| Mondi Group |
| Amcor Limited |
| Novolex |
| Smurfit Kappa Group |
| Others |
Value Network & Pricing Analysis
Retail pharmacy chain procurement offices at CVS Health, Walgreens Boots Alliance, and Rite Aid command pricing leverage through multi-year national contracts that compress converter margins into cost-plus arrangements with volume-tier rebates. These buyers unbundle after-sales services from base bag pricing, treating inventory management software and just-in-time delivery as separately negotiated service fees rather than integrated premiums.
Pricing Analysis
Warranty and service bundling separates contract structures in this market, with national retail chains negotiating comprehensive agreements that embed compliance documentation and ERP integration while smaller clinic buyers purchase bags on transactional spot terms. Three-tier pricing structure across premium, standard, and economy levels reflects FDA certification grade and automation compatibility tier, with ASTM D3475-tested child-resistant formats commanding premiums over basic opacity-compliant bags. Cost compression in standard paper formats is intensifying because Nordic pulp mills restrict specialty kraft fiber allocations, forcing converters to absorb input volatility or surrender share. Clinic procurement through group purchasing organizations exhibits highest price sensitivity, whereas mail-order pharmacy operations prioritize dimensional standardization and thermal label adhesion over unit cost.
Supply Chain Analysis
Specialty kraft fiber supply rests on Nordic softwood pulp mills in Sweden and Finland, with Canadian mills providing secondary grades for North American converter operations. Bag production draws from these pulp inputs, water-based barrier coating chemicals, and heat-seal adhesive formulations, with QR-code label substrates increasingly sourced from printed electronics specialists. Single-source vulnerability concentrates in Nordic pulp supply, where mill maintenance shutdowns and allocation limits cascade through converter order books within weeks. Distribution runs through health system group purchasing organizations like Premier and Vizient in the United States, with direct-to-pharmacy fulfillment models gaining share among online dispensers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive pulp supply and downstream ERP-enabled service layers defines competitive positioning in this market, as converters race to secure fiber access and lock in health system vendor consolidation benefits.
For Market Incumbents: Lock in long-term fiber supply agreements with Nordic and Canadian pulp mills before allocation limits tighten further, and accelerate water-based coating R&D partnerships to eliminate fluorochemical liabilities under REACH Annex XVII. Biodegradable film specialists like NatureWorks and Danimer Scientific threaten to displace polyethylene laminates in EU markets, making barrier coating certification investment the critical defensive lever. For New Entrants and Emerging Players: Begin with India retail pharmacy modernization, where CDSCO oversight is replacing loose paper wrapping with standardized tamper-evident formats and organized chains lack established converter relationships. State-level plastic waste rules in Maharashtra and Gujarat accelerate fiber-based transitions, creating specification white-space for pharmacy-grade bag producers willing to invest in regional manufacturing clusters near Mumbai-Pune. For Investors and Strategic Acquirers: The window for entry favors converters with ERP integration capabilities and health system sole-source contracts, as hospital vendor consolidation compresses switching cycles and locks out smaller competitors. Watch for EU MDR traceability enforcement deadlines as inflection indicators that will separate QR-code-enabled bag producers from legacy format converters unable to fund printed electronics integration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Kraft Pulp | Captive fiber supply from Nordic mills insulates WestRock and DS Smith from allocation volatility. |
| Water-Based Barrier Coating Certification | FDA and REACH-compliant formulations enable full recyclability claims for CVS Health and Walgreens procurement. |
| ERP Integration for Health System Contracts | Premier and Vizient sole-source arrangements require just-in-time delivery software compatibility. |
| QR-Code Traceability Embedding | EU MDR unique device identifier rules create specification premiums for printed electronics converters. |
| India Manufacturing Footprint Expansion | Mumbai-Pune clusters position suppliers for CDSCO-compliant domestic retail and Southeast Asian export. |
Research Methodology
Trade association filings from the Paperboard Packaging Council, FDA packaging guidance documents, and SEC 10-K disclosures from WestRock and DS Smith formed the secondary backbone, cross-referenced against primary interviews with retail pharmacy procurement directors, hospital pharmacy committee chairs, converter plant managers, and health system GPO contracts managers. Bottom-up and top-down triangulation validated volume estimates against pulp mill production data and pharmacy dispensing statistics.
Bottom-up modeling aggregated segment-level unit economics across material type, closure mechanism, and end-user channel, while top-down approaches calibrated aggregate market size against healthcare packaging spend ratios. The analysis window spans material transition timelines under EU Green Deal and Extended Producer Responsibility frameworks, with CAGRs derived from regression against pharmaceutical dispensing volume growth and regulatory compliance investment cycles. Forecast inputs incorporated mail-order pharmacy expansion rates and hospital automation penetration curves.
Underlying measurement precision varies by segment; retail pharmacy chain procurement data carries tighter precision than clinic and urgent care channel estimates due to concentration in disclosed national contracts. Forecasts reflect assumptions about pulp fiber allocation continuity, REACH enforcement timelines, and health system vendor consolidation momentum. A small set of regulatory triggers—California EPR implementation, EU MDR traceability deadlines, and FDA child-resistance protocol updates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Labeling Market
Pharmaceutical Packaging
Latin America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Global Temperature Controlled Packaging Solutions for Pharmaceuticals Market
Pharmaceutical Packaging
Plastic Pharma Tray Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Vials Market
Pharmaceutical Packaging
Smart Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical Secondary Packaging Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
North America Ampoules Packaging Market