
 China Pallets Market | 2026-2036
China Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
China Pallets Market Insights
Buyer concentration in China's logistics sector is shifting as third-party providers consolidate warehousing networks across provincial hubs. CHEP (China) Company leverages its pooled pallet rental model to sustain national coverage. China Merchants LOSCAM anchors its position through port-adjacent depot density. LogisALL Shanghai Co.Ltd. competes on automated sorting integration for e-commerce clients.
Pallets are load-bearing platform structures, typically measuring 1200 mm by 1000 mm for Chinese standard compatibility, manufactured through nail-assembly, injection molding, or welding processes to enable mechanized handling of goods via forklifts and conveyor systems. Wood material type retains volume leadership in domestic circulation despite plastic alternatives gaining share in pharmaceutical and cold-chain applications. Block pallets dominate export-oriented manufacturing support due to four-way entry compatibility with international container standards.
MIIT enforces GB standards for pallet dimensions and load ratings, while SAMR monitors market access compliance for recycled plastic feedstocks under circular economy directives. The central bank's green financing incentives are channeling capital toward reusable pallet pooling infrastructure. Stakeholders must weigh pooling model economics against single-use procurement as carbon accounting rules tighten.
Market Dynamics
GB/T 4995 material specification tightening is compressing domestic wood pallet supply capacity while accelerating plastic and composite substitution in pharmaceutical and cold-chain verticals across the Yangtze River Delta manufacturing corridor.
Growth Catalysts
- E-commerce fulfillment expansion:Jiangsu province fulfillment centers are scaling pallet procurement volumes to match same-day delivery infrastructure buildout.
- Green financing incentives:The central bank's reusable pooling infrastructure credits are redirecting capital from single-use procurement toward circular economy pallet models.
- Dual carbon goal alignment:Carbon accounting rule tightening under MEE directives is forcing manufacturing exporters to adopt pooled pallet systems for scope 3 emission reductions.
Market Restraints
- Recycled plastic feedstock volatility:SAMR circular economy compliance monitoring is restricting market access for non-certified recycled polymer sources, constraining domestic plastic pallet production scale.
- Wood material cost pressure:GB standards enforcement is disqualifying lower-grade timber from domestic circulation, compressing margins for nail-assembly pallet manufacturers.
- Four-way entry technical limitation:Block pallet dominance in export manufacturing creates dependency on container-standard compatibility, limiting innovation in alternative entry configurations.
Strategic Opportunities
- Automated sorting integration:E-commerce logistics providers in Shanghai and Suzhou are retrofitting warehouses with RFID-tracked pallet pools that synchronize with robotic sortation systems.
- Cold-chain pharmaceutical vertical:Plastic pallet penetration remains underdeveloped in temperature-controlled biologics distribution, creating white space for hygienic, washable alternatives to wood.
- Port-adjacent depot density:Ningbo and Shanghai container terminal proximity offers pooling operators location advantage for international shipment handoff services.
Industry Challenges
- Retrofit capex intensity:Warehouse automation integration requires simultaneous pallet pool management system deployment, straining mid-size 3PL balance sheets.
- Cross-standard compatibility:Dual circulation between domestic 1200 mm by 1000 mm GB standard and ISO 1200 mm by 800 mm export formats forces inventory duplication at manufacturing plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Pallets Market |
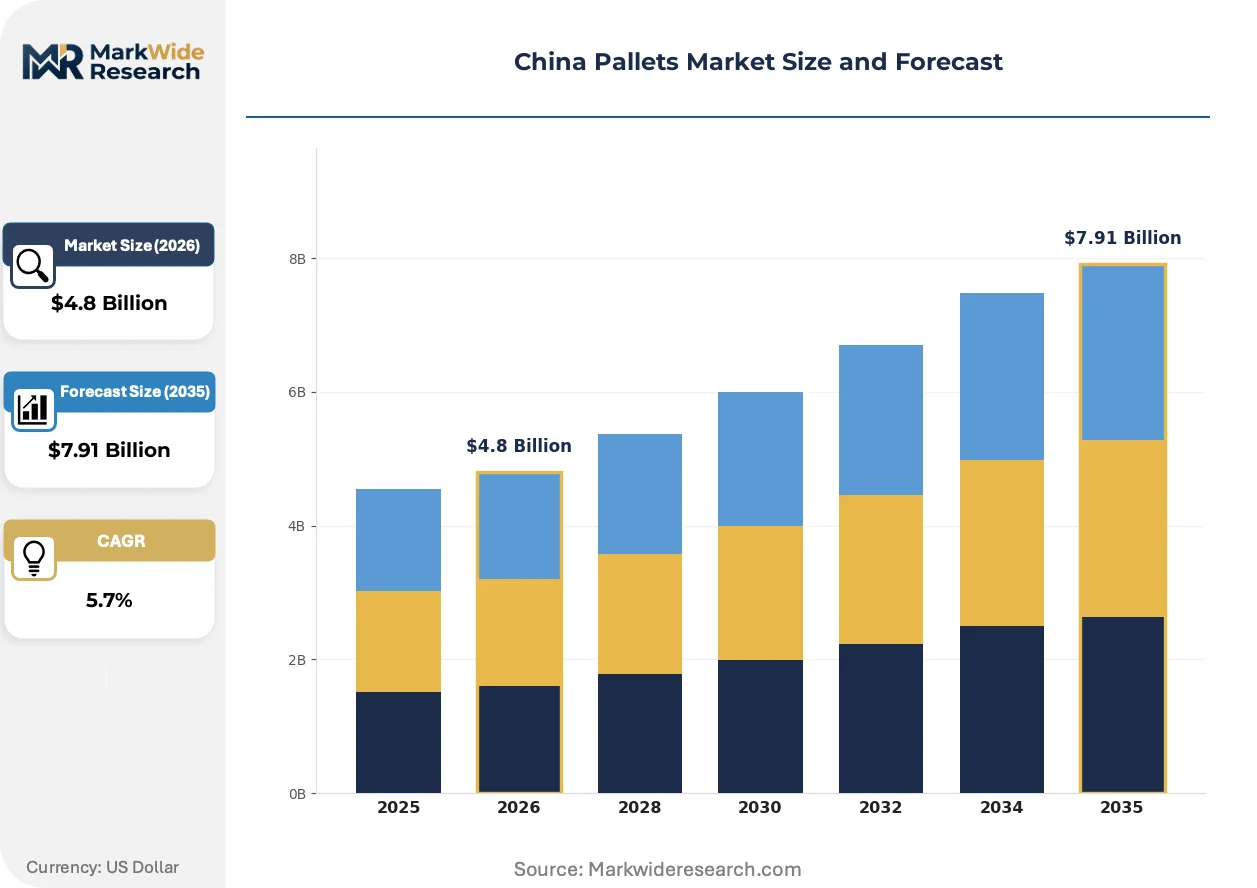
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Plastic, Metal, Paperboard, Composite Product Type: Stringer Pallets, Block Pallets, Double-Face Pallets, Four-Way Entry Pallets Application: Warehouse Storage, Transportation, Retail Display, Export Packaging, Manufacturing Support End User: Logistics Providers, E-commerce, FMCG Companies, Pharmaceutical Distributors, Electronics Manufacturers |
| Companies Covered | Shenzhen Bairuipu Technology Co Ltd, Shanghai Huayang Packaging Co Ltd, Qingdao Huili Packaging Co Ltd, China National Chemical Corporation, Yixing Huarun Plastic Co Ltd, Guangdong Liansu Group, CHEP (China) Company, China Merchants LOSCAM, LogisALL Shanghai Co.Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Pallets Market Trends and Innovations
Digital tracking convergence with circular material flows is reconfiguring how pallet assets are managed, financed, and recovered across China's logistics networks.
RFID-embedded composite pallets are modularizing asset tracking infrastructure. Pharmaceutical distributors and cold-chain operators are adopting these units fastest, replacing barcode-dependent wood alternatives. The technology is modularizing fleet management from static ownership models toward dynamic, location-aware pooling systems that compress working capital requirements.
MIIT enforcement of updated GB/T load rating specifications is disqualifying legacy nail-assembly designs from domestic circulation. Manufacturers must recertify production lines or exit the market. Pharmaceutical and food-grade applications face the steepest compliance timelines, accelerating migration toward injection-molded plastic and welded metal alternatives.
Third-party logistics buyers are consolidating warehousing networks across provincial hubs, concentrating procurement authority with fewer decision-makers. This buyer compression is displacing fragmented local pallet suppliers with national pooling operators who can guarantee unit availability across multi-node distribution footprints. The shift is most visible in Jiangsu and Zhejiang, where e-commerce fulfillment density supports pooling model unit economics.
China Pallets Market Segmentation
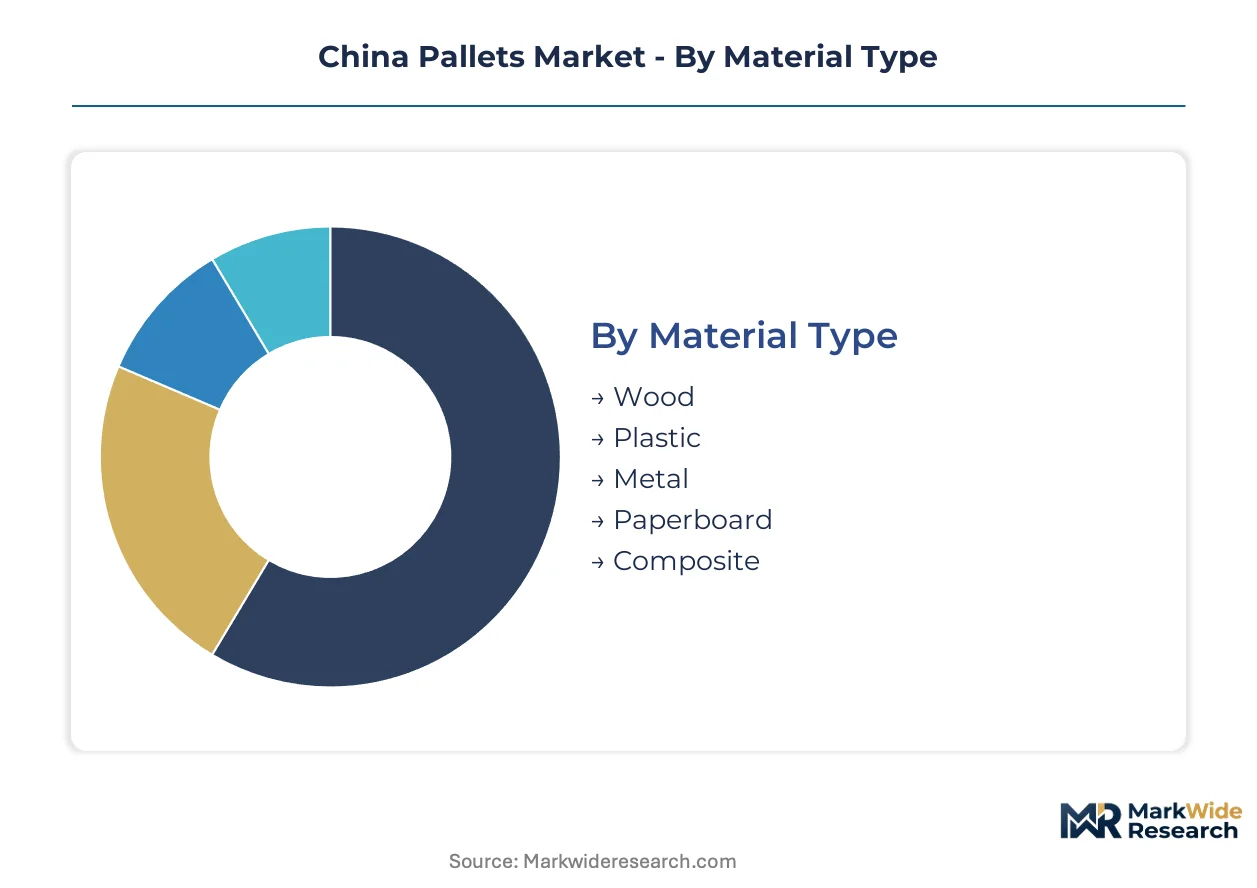
Pallet procurement decisions in China hinge on load-bearing requirements, handling automation compatibility, and circular economy compliance costs. Segment boundaries are blurring as pooled rental models and RFID tracking reshape traditional material and product hierarchies.
Material Type:
Customization intensity varies sharply across this spectrum, from commodity timber grades to engineered composites with embedded tracking chips.
- Wood:Nail-assembly softwood and hardwood platforms dominate domestic circulation under GB/T 4995 specifications. Yangtze River Delta manufacturers face margin compression as MIIT disqualifies lower-grade timber from certified supply chains.
- Plastic:Injection-molded HDPE and PP pallets are gaining fastest in pharmaceutical cold-chain and food-grade applications where washability and hygienic surfaces outweigh upfront cost premiums. SAMR circular economy directives constrain recycled feedstock availability.
- Metal:Welded steel and aluminum designs serve heavy machinery and automotive component logistics with extreme load ratings.
- Paperboard:Lightweight corrugated platforms target single-use export and air freight weight-sensitive cargo.
- Composite:Fiber-reinforced polymer and wood-plastic hybrid structures balance durability with sustainability credentials for carbon-accounting-conscious exporters.
Leading the category by volume: Wood. Expanding most quickly: Plastic.
Product Type:
Entry configuration and deck structure determine forklift compatibility and warehouse automation integration depth.
- Stringer Pallets:Two-way entry designs with parallel longitudinal supports remain cost-minimum for static warehouse storage. Jiangsu province e-commerce fulfillment centers are phasing these out in favor of four-way alternatives for robotic handling compatibility.
- Block Pallets:Four-way entry capability with nine-block base construction anchors export-oriented manufacturing support. Ningbo and Shanghai port proximity drives depot density for pooled block pallet operators serving containerized shipments.
- Double-Face Pallets:Reversible deck surfaces suit high-turnover distribution environments with bidirectional loading requirements.
- Four-Way Entry Pallets:Notched stringer or block-based designs enabling forklift access from all sides are becoming mandatory for automated sortation systems in Suzhou and Shanghai logistics hubs.
Dominant by shipment value: Block Pallets. Steepest adoption curve: Four-Way Entry Pallets.
Application:
Functional use cases stratify by handling frequency, environmental exposure, and regulatory scrutiny intensity.
- Warehouse Storage:Static racking applications prioritize load concentration and vertical space optimization over mobility features.
- Transportation:Road, rail, and intermodal movements demand impact resistance and unit load stability under dynamic stress.
- Retail Display:Point-of-sale ready platforms integrate branding surfaces and consumer-facing aesthetics for in-store merchandising.
- Export Packaging:ISPM-15 heat-treated wood or plastic alternatives satisfy cross-border phytosanitary requirements.
- Manufacturing Support:Line-side feeding and work-in-progress staging require precise dimensional tolerance for automated guided vehicle compatibility.
Highest volume application: Warehouse Storage. Fastest structural shift: Manufacturing Support.
End User:
Buyer consolidation across provincial hubs is concentrating procurement authority with fewer decision-makers per segment.
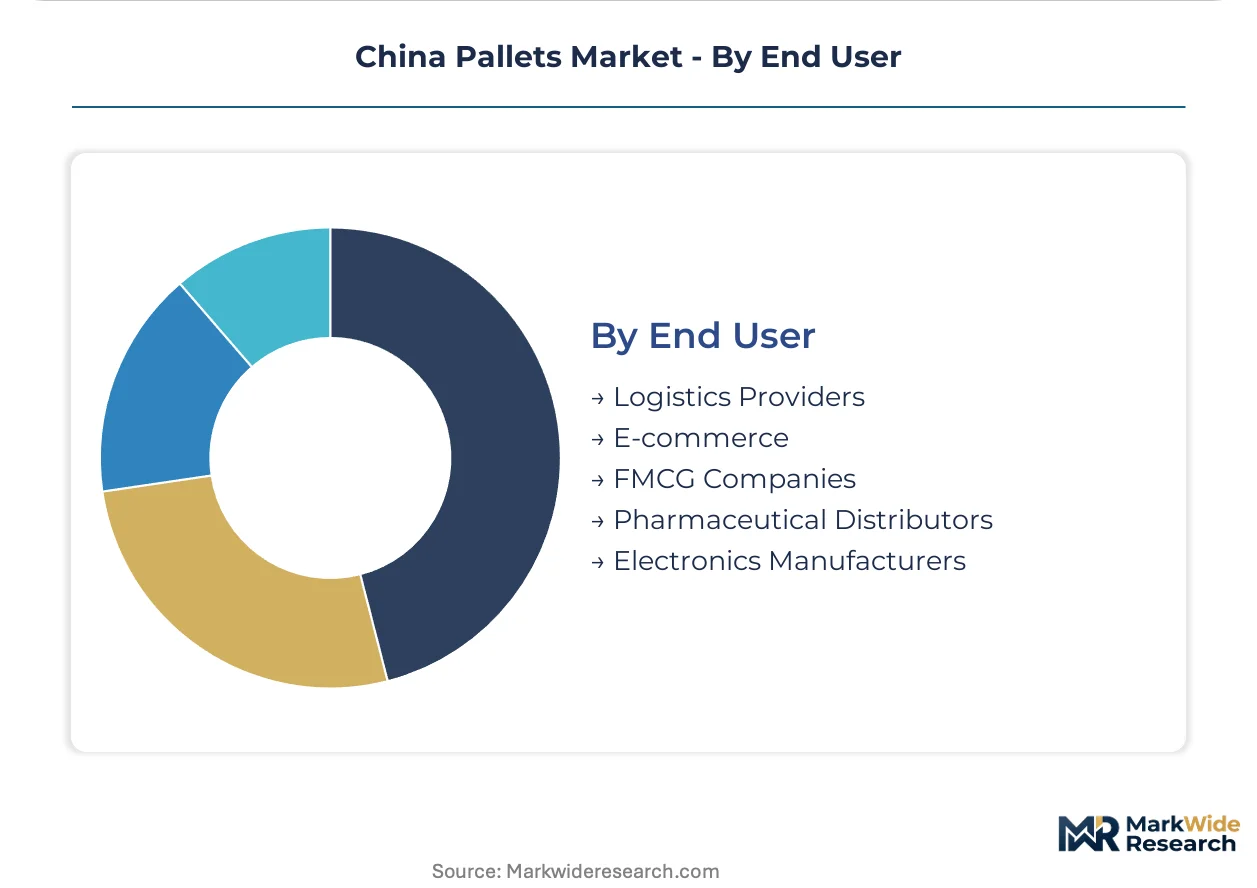
- Logistics Providers:Third-party warehousing operators in Jiangsu and Zhejiang are retrofitting networks with RFID-tracked pooled pallet systems. Balance sheet constraints delay automation integration for mid-size 3PLs.
- E-commerce:Same-day delivery infrastructure buildout in Shanghai and Suzhou fulfillment centers is scaling pallet procurement volumes fastest. Robotic sortation synchronization requirements favor standardized four-way entry designs.
- FMCG Companies:High-velocity consumer goods distribution prioritizes turnaround speed and damage minimization.
- Pharmaceutical Distributors:Temperature-controlled biologics logistics creates white space for hygienic plastic alternatives to wood in cold-chain verticals.
- Electronics Manufacturers:Precision component protection demands anti-static and contamination-controlled handling platforms.
Largest procurement base: Logistics Providers. Climbing the fastest: E-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pallet procurement concentrates in China's coastal manufacturing belts where export logistics and e-commerce fulfillment infrastructure overlap. Provincial industrial policies and port accessibility create divergent adoption patterns for pooling versus single-use models.
Yangtze River Delta
Jiangsu province fulfillment centers are scaling pallet volumes to match same-day delivery buildout. MIIT enforcement of updated GB/T load ratings is disqualifying legacy nail-assembly designs from circulation. Shanghai and Suzhou logistics hubs are retrofitting warehouses with RFID-tracked pools that synchronize with robotic sortation.
Pearl River Delta
Guangdong manufacturing exporters face MEE carbon accounting directives that favor pooled systems for scope 3 reductions. SAMR monitoring of recycled polymer feedstocks constrains domestic plastic pallet production scale. Shenzhen and Dongguan electronics clusters are driving demand for anti-static handling platforms.
Beijing-Tianjin-Hebei
Pharmaceutical distributors in the northern corridor are adopting hygienic plastic alternatives to wood for cold-chain biologics. The central bank's green financing incentives channel capital toward reusable pooling infrastructure. Tianjin port-adjacent depots offer pooling operators location advantage for international shipment handoffs.
Shandong Peninsula
Qingdao's packaging industry anchors wood pallet production despite GB standards compressing lower-grade timber supply. Dual circulation between domestic 1200 mm by 1000 mm and ISO 1200 mm by 800 mm formats forces inventory duplication at manufacturing plants. Weihai and Yantai food processors are migrating toward washable plastic for export compliance.
Sichuan-Chongqing
Western China logistics networks are consolidating warehousing authority with fewer third-party providers per provincial hub. Chongqing's inland port development is scaling containerized shipment handoff services. Chengdu e-commerce fulfillment density is approaching thresholds that support pooling model unit economics.
China Pallets Market Competitive Landscape
Yangtze River Delta producers anchor one tier; northern specialists hold port-adjacent depot density. The vendor base organizes around three strategic archetypes: national pooling operators with RFID-tracked fleet systems, regional injection-molding specialists serving pharmaceutical verticals, and commodity nail-assembly fabricators facing margin compression from GB standard tightening. Dominant competitive moves include warehouse automation integration partnerships and backward integration into recycled polymer feedstock sourcing.
Within the pooling operator tier, CHEP (China) Company and China Merchants LOSCAM exemplify national coverage models, while LogisALL Shanghai Co.Ltd. occupies a position emphasizing automated sorting integration. Among regional fabricators, Shenzhen Bairuipu Technology Co Ltd and Shanghai Huayang Packaging Co Ltd represent the plastic and packaging specialist archetypes respectively. Qingdao Huili Packaging Co Ltd anchors the Shandong-based production cluster. These named entities illustrate how competitive positioning stratifies across rental-model scale, material specialization, and geographic depot density rather than product differentiation alone.
| Leading Market Players |
|---|
| Shenzhen Bairuipu Technology Co Ltd |
| Shanghai Huayang Packaging Co Ltd |
| Qingdao Huili Packaging Co Ltd |
| China National Chemical Corporation |
| Yixing Huarun Plastic Co Ltd |
| Guangdong Liansu Group |
| CHEP (China) Company |
| China Merchants LOSCAM |
| LogisALL Shanghai Co.Ltd. |
| Others |
Pricing and Supply Chain Analysis
RFID-embedded composite pallet manufacturing is compressing unit economics for nail-assembly fabricators while concentrating procurement leverage with national pooling operators who command volume discounts across the Yangtze River Delta.
Pricing Analysis
Volume leaders in wood nail-assembly face margin compression against premium-tier plastic and composite alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects GB/T 4995 certification grade and automation compatibility. Pricing pressure stems from MIIT enforcement disqualifying lower-grade timber from circulation. E-commerce fulfillment centers show lowest price sensitivity due to automation synchronization requirements; commodity timber buyers remain most cost-conscious.
Supply Chain Analysis
Reverse-logistics flows for pooled pallet recovery anchor depot density strategies in Shanghai and Ningbo port zones. Domestic supply concentrates in Shandong, Jiangsu, and Zhejiang provinces. Production draws from certified timber plantations, virgin HDPE/PP resins, and recycled polymer feedstocks monitored by SAMR. Single-source vulnerability runs through SAMR-certified recycled plastic channels. Distribution runs through third-party logistics networks consolidating across provincial hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GB/T 4995 tightening transforms pallet procurement into a cost-of-compliance discipline where certified manufacturers build durable moats against uncertified competitors facing market exit.
For Market Incumbents: Deepen backward integration into certified timber plantations and SAMR-approved recycled polymer sourcing to lock in feedstock security against SAMR circular economy compliance volatility. Expand RFID fleet management capabilities to defend against automation-integration specialists. Fortify port-adjacent depot density in Ningbo and Shanghai as competitive barriers to regional entrants. For New Entrants and Emerging Players: Capture underpenetrated cold-chain pharmaceutical verticals in Beijing-Tianjin-Hebei where hygienic plastic alternatives to wood face minimal incumbent saturation. Target mid-size 3PLs in Sichuan-Chongqing where pooling model unit economics are approaching viability thresholds but national operators maintain limited presence. Lead with automated sorting integration partnerships as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by national pooling operators seeking regional depot density or vertical integration into certified feedstock sources. Long-term viability favors players with GB/T 4995 recertification completion and RFID fleet infrastructure deployed. Monitor MIIT enforcement intensity and SAMR recycled polymer certification expansion as inflection signals for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| GB/T 4995 Production Line Recertification | MIIT enforcement disqualifies legacy nail-assembly designs, forcing compliance investment or market exit. |
| RFID Fleet Management Deployment | Robotic sortation synchronization in Jiangsu fulfillment centers demands location-aware pallet tracking infrastructure. |
| Port-Adjacent Depot Expansion | Ningbo and Shanghai terminal proximity enables international shipment handoff services for pooled operators. |
| Recycled Polymer Feedstock Integration | SAMR circular economy directives constrain certified supply, rewarding upstream control over polymer sourcing. |
| Cold-Chain Pharmaceutical Vertical Entry | Temperature-controlled biologics distribution in northern corridors offers white space for hygienic plastic alternatives. |
Research Methodology
Multi-period observation of pallet procurement volumes, GB/T certification compliance timelines, and pooling operator depot expansion anchored the trend analysis, supplemented by interviews with logistics procurement directors, warehouse automation engineers, MIIT regulatory affairs specialists, and timber plantation certification officers. Secondary validation drew from MIIT standards documentation, SAMR circular economy directives, central bank green financing disclosures, and Yangtze River Delta industrial cluster reports. Bottom-up pallet unit demand modeling and top-down logistics infrastructure investment analysis were triangulated for convergence.
Input-output matrices mapped material type substitution elasticities, end-user consolidation patterns, and regional automation adoption curves across the analysis window. Segmentation dimensions included material type, product configuration, application function, and end-user archetype. CAGRs were derived from logistic diffusion modeling of pooling model penetration and regulatory compliance phase-in schedules. Forecast inputs incorporated e-commerce fulfillment center buildout pipelines and MIIT enforcement intensity projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAMR recycled polymer certification expansion rates and carbon accounting rule tightening under MEE directives. Forecasts reflect documented assumptions about regulatory enforcement pacing and pooling model unit economics thresholds. Practitioners should monitor MIIT inspection announcement frequency and central bank green credit allocation shifts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
North America Pallet Market
Pallets Packaging
Europe Lumber Pallet Market
Pallets Packaging
Middle East Pallets Market
Pallets Packaging
Pallet Banding Machine Market
Pallets Packaging
Pallet Slip Sheets Market
Pallets Packaging
France Pallets Market
Pallets Packaging
Pallet Wraps Market
Pallets Packaging
Pallet Displays Market
Pallets Packaging
Composite Pallet Market
Pallets Packaging
Germany Pallets Market
Pallets Packaging
Conventional Palletizers Market
Pallets Packaging
Wooden Pallets Market
Pallets Packaging
Europe Pallet Wrapping Machine Market
Pallets Packaging
Pallet Bands Market
Pallets Packaging
Pallet Shippers Market
Pallets Packaging
Pallets Market