
 Parenteral Drugs Packaging Market | 2026-2036
Parenteral Drugs Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Parenteral Drugs Packaging Market Analytics
The parenteral drugs packaging sector is rebalancing between premium containment solutions for biologics and commodity-grade glass for generic injectables. West Pharmaceutical Services anchors the high-value biologic containment segment through its elastomer and delivery system specialization. Gerresheimer AG sustains a dominant position in tubular glass vial production across European pharmaceutical corridors. Schott AG differentiates via borosilicate glass technology leadership and controlled nucleation capabilities for freeze-dried products.
Parenteral drugs packaging encompasses sterile containers and closure systems designed to maintain drug stability, prevent contamination, and enable safe administration via injection; primary materials include Type I borosilicate glass, cyclic olefin polymers, and halobutyl rubber elastomers, with functional parameters such as extractables profiles, container closure integrity, and silicone oil consistency determining suitability for sensitive biologic formulations. Vials remain the largest volume category but face margin compression from commoditization, while prefilled syringes capture expanding value pools as chronic self-injection therapies proliferate. Glass maintains structural dominance in high-value biologics due to its inertness and regulatory familiarity, though polymer syringes and composite systems are gaining traction in specific therapeutic categories where breakage risk or protein aggregation concerns drive material substitution.
The US FDA enforces stringent container closure integrity and extractables testing through its chemistry, manufacturing, and controls framework for sterile drug products, while the EU MDR imposes enhanced traceability and notified body oversight on primary packaging classified as medical devices. Germany's national pharmaceutical regulator and France's ANSM apply additional national pharmacopeial standards that exceed baseline harmonized requirements in select categories. Stakeholders must monitor evolving regulatory convergence between FDA and EMA expectations for combination product packaging, as divergence in extractables study protocols continues to complicate multi-territory filings and supplier qualification programs.
Market Dynamics
Biologics manufacturers are consolidating fill-finish capacity around prefilled syringe formats, compressing demand for conventional vials while elevating specifications for elastomeric closure systems and container closure integrity testing protocols.
Growth Catalysts
- EU MDR serialization mandates:Tighter traceability requirements for sterile injectable containers are forcing packaging upgrades across European pharmaceutical corridors, expanding demand for premium containment solutions with integrated data-matrix capabilities.
- Chronic self-injection therapies:Diabetes and autoimmune treatment protocols are migrating from clinical administration to home settings, pulling prefilled syringe volumes upward across North American and European patient populations.
- Type I borosilicate glass:Its inertness and regulatory familiarity sustain structural dominance in high-value biologics, with German glass primary packaging specialists capturing disproportionate value from mRNA and monoclonal antibody launches.
Market Restraints
- Halobutyl rubber elastomer supply concentration:Three specialized compounders control the majority of pharmaceutical-grade stoppers and plungers, creating vulnerability to input cost volatility and qualification timeline extensions.
- Silicone oil consistency limitations:Protein aggregation concerns in sensitive biologic formulations restrict polymer syringe penetration despite breakage risk advantages, preserving glass dependency in premium segments.
- FDA extractables study protocols:Divergence from EMA expectations complicates multi-territory filings, extending supplier qualification programs and delaying commercial launches for combination product developers.
Strategic Opportunities
- Cyclic olefin polymer adoption:Breakage-sensitive therapeutic categories including emergency epinephrine and travel vaccines present white space for polymer syringe penetration where protein stability concerns are less acute.
- Freeze-dried product controlled nucleation:Borosilicate vials with engineered nucleation sites enable faster lyophilization cycles, creating value capture potential for glass technology leaders serving biologics manufacturers.
- India's contract fill-finish expansion:Domestic biologics manufacturing growth and export-oriented pharmaceutical production are concentrating demand for pre-sterilized ready-to-use containers and closure systems.
Industry Challenges
- Container closure integrity testing talent scarcity:Specialized microbiology and analytical chemistry capabilities required for CCI validation are concentrated among a limited pool of qualified personnel, constraining capacity expansion timelines.
- ISO 15378 certification backlog:Primary packaging material suppliers face extended audit queues for pharmaceutical quality management system accreditation, delaying commercial qualification for new manufacturing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parenteral Drugs Packaging Market |
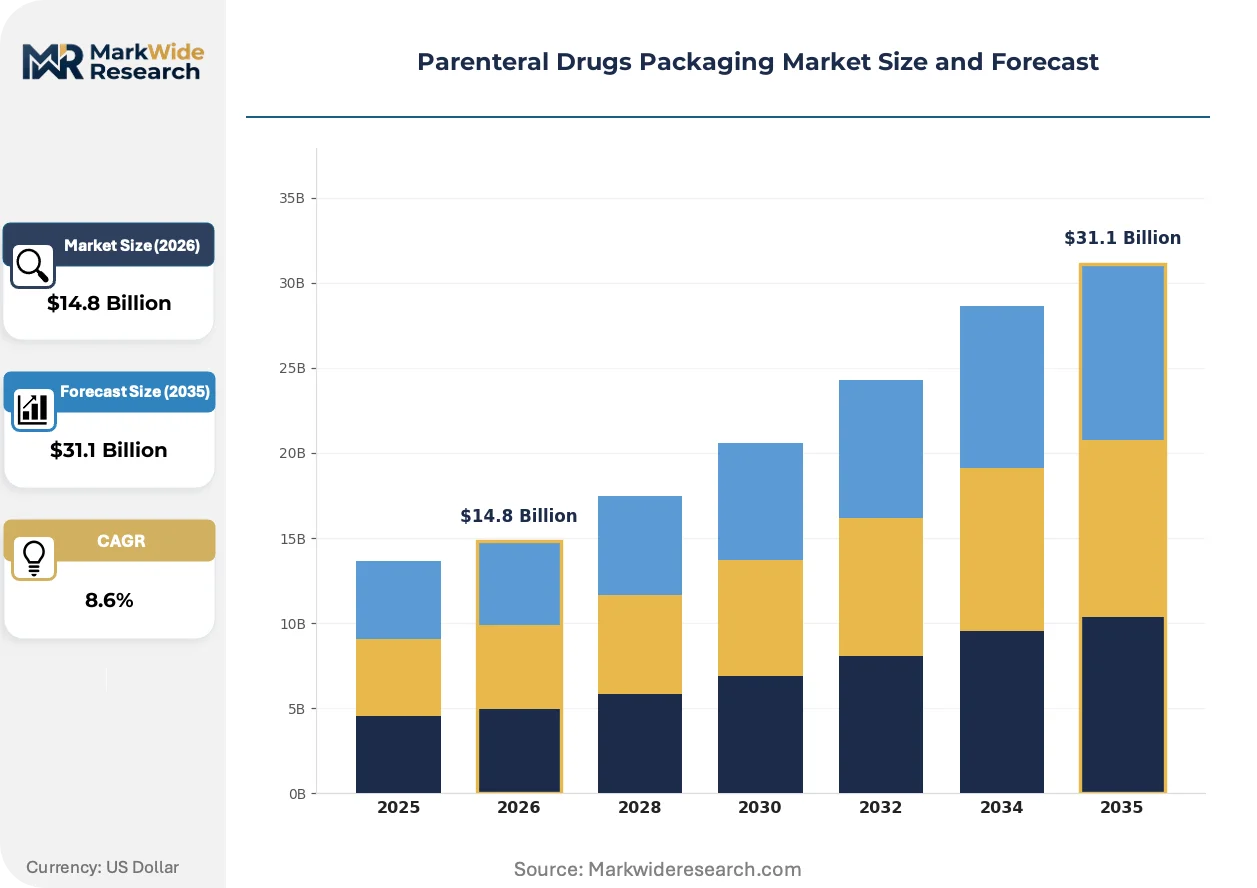
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Ampoules, Vials, Syringes, Cartridges Material: Glass, Plastic, Rubber, Composite End User: Hospitals, Clinics, Pharmaceutical Companies, Contract Manufacturers Closure Type: Seals, Stoppers, Caps, Puncture-Proof |
| Companies Covered | West Pharmaceutical Services, Amcor, Gerresheimer AG, Schott AG, Becton Dickinson and Company, AptarGroup, Nipro Corporation, Stevanato Group, SGD Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parenteral Drugs Packaging Market Evolving Landscape
Material science advances and regulatory convergence pressures are simultaneously elevating performance specifications and compressing acceptable variation margins across parenteral containment systems.
Cyclic olefin polymer syringe systems are expanding into emergency medicine and vaccine travel kits where glass breakage risk outweighs protein stability concerns. Auto-injector and pen injector manufacturers are accelerating polymer adoption for mechanical durability requirements. This material substitution is expanding into therapeutic categories previously reserved for borosilicate glass, compressing addressable volume for traditional tubular vial producers.
REACH regulatory expansions on extractables and leachables are forcing reformulation of rubber elastomer compositions and silicone oil lubricants across European supply chains. The European Chemicals Agency's substance restrictions are propagating through pharmaceutical packaging qualification programs. German and French notified bodies are applying enhanced scrutiny to medical device-classified primary packaging, extending technical documentation requirements for combination product filings.
Biologics procurement teams are consolidating supplier relationships around vertically integrated containment-delivery system providers capable of unified extractables documentation. Single-source qualification for integrated vial-stopper-seal or syringe-plunger-needle systems is displacing multi-vendor component sourcing. This consolidation pattern is most visible among mid-cap biotech developers in Massachusetts and California seeking to compress regulatory submission preparation timelines.
Parenteral Drugs Packaging Market Segmentation
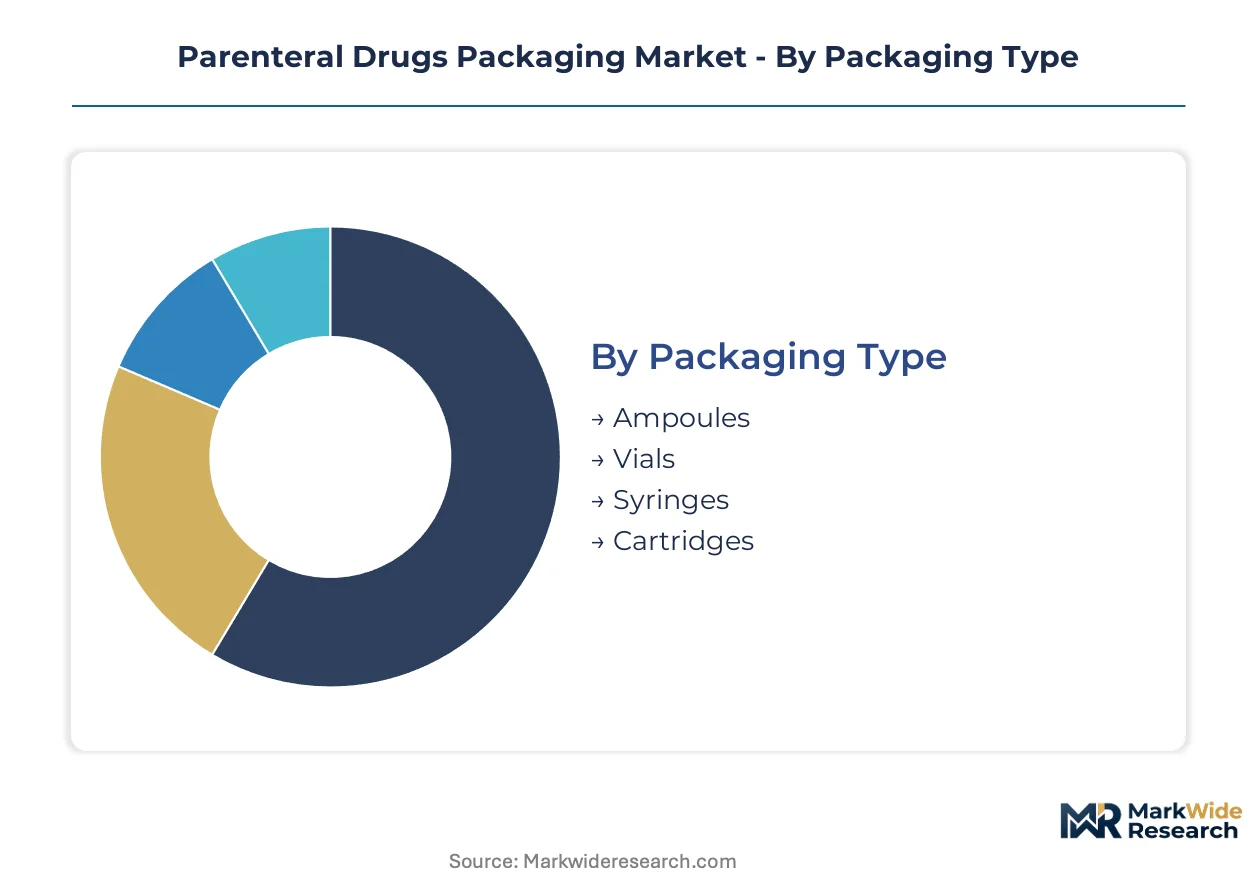
Parenteral drugs packaging segmentation reveals how regulatory complexity and therapeutic requirements fragment procurement decisions across container formats and material classes. Understanding these divides illuminates where qualification burdens concentrate and where substitution economics open white space.
Packaging Type:
ISO 15378 certification applies universally across all formats, though EU MDR medical device classification triggers additional notified body scrutiny for prefilled syringes and auto-injector cartridges compared to conventional vials.
- Vials:Tubular and molded glass configurations dominate high-volume biologics storage, with German glass primary packaging specialists capturing disproportionate share from mRNA and monoclonal antibody launches requiring Type I borosilicate inertness. Demand concentrates in fill-finish operations serving chronic disease therapies where multi-dose preservation and freeze-drying compatibility remain non-negotiable.
- Syringes:Prefilled formats are consolidating fill-finish capacity as biologics manufacturers prioritize self-administration protocols; chronic diabetes and autoimmune therapies in North American and European patient populations pull volumes upward despite silicone oil consistency limitations constraining protein-sensitive applications.
- Ampoules:Single-dose glass containers persist in emergency medicine and anesthetic applications where immediate availability outweighs multi-dose convenience; European hospital procurement maintains steady demand despite limited growth trajectory.
- Cartridges:Pen-injector compatible formats serve insulin and growth hormone therapies requiring precise dosing flexibility; polymer adoption accelerates where mechanical durability requirements override traditional glass preferences.
Vials sit at the top of the volume ranking, with syringes climbing the fastest.
Material:
Cost stratification separates premium containment from commodity-grade alternatives, with extractables testing protocols and breakage risk tolerance determining viable substitutions.
- Glass:Type I borosilicate sustains structural dominance in high-value biologics through regulatory familiarity and inertness; German and French pharmacopeial standards exceed baseline harmonized requirements, preserving premium positioning for tubular vial producers serving freeze-dried product portfolios.
- Plastic:Cyclic olefin polymers penetrate emergency epinephrine and travel vaccine kits where breakage risk outweighs protein stability concerns; auto-injector manufacturers accelerate adoption for mechanical durability requirements in home administration settings.
- Rubber:Halobutyl elastomer formulations face REACH regulatory expansions forcing composition reformulation across European supply chains; three specialized compounders control pharmaceutical-grade stopper and plunger supply, creating input cost vulnerability.
- Composite:Multi-layer barrier systems address oxygen-sensitive biologics requiring hybrid protection; limited commercial scale constrains penetration to niche high-value applications awaiting broader qualification.
Glass commands the premium tier by revenue, while plastic gains share fastest in volume-sensitive segments.
End User:
Customer procurement sophistication varies sharply, with pharmaceutical companies and contract manufacturers driving specification intensity versus institutional buyers prioritizing supply security.
- Pharmaceutical Companies:Integrated containment-delivery system procurement consolidates around vertically integrated suppliers capable of unified extractables documentation; Massachusetts and California biotech developers compress regulatory submission timelines through single-source qualification.
- Contract Manufacturers:India's domestic biologics manufacturing growth and export-oriented pharmaceutical production concentrate demand for pre-sterilized ready-to-use containers; capacity expansion timelines constrain by container closure integrity testing talent scarcity.
- Hospitals:Institutional procurement emphasizes supply continuity for critical care injectables; EU MDR serialization mandates force packaging upgrades with integrated data-matrix capabilities across European hospital networks.
- Clinics:Ambulatory administration settings prioritize prefilled convenience for routine injection protocols; chronic self-injection therapy migration from clinical to home settings compresses direct clinic procurement growth.
Pharmaceutical companies anchor the value pool, with contract manufacturers expanding most quickly in emerging supply geographies.
Closure Type:
Functional performance requirements and puncture safety regulations segment this category by therapeutic risk tolerance and administration setting.
- Stoppers:Elastomeric seals for vial containment face silicone oil consistency limitations restricting polymer syringe penetration; halobutyl rubber supply concentration creates vulnerability to qualification timeline extensions.
- Seals:Aluminum overseals for crimped vial assemblies maintain regulatory familiarity in high-value biologics; German glass primary packaging specialists integrate seal supply for streamlined customer qualification.
- Caps:Luer-lock and proprietary thread configurations serve syringe and cartridge formats; polymer adoption in auto-injectors drives mechanical specification evolution.
- Puncture-Proof:Safety-engineered closures for sharps prevention respond to OSHA and EU occupational exposure directives; hospital and clinic procurement increasingly mandates integrated protection features.
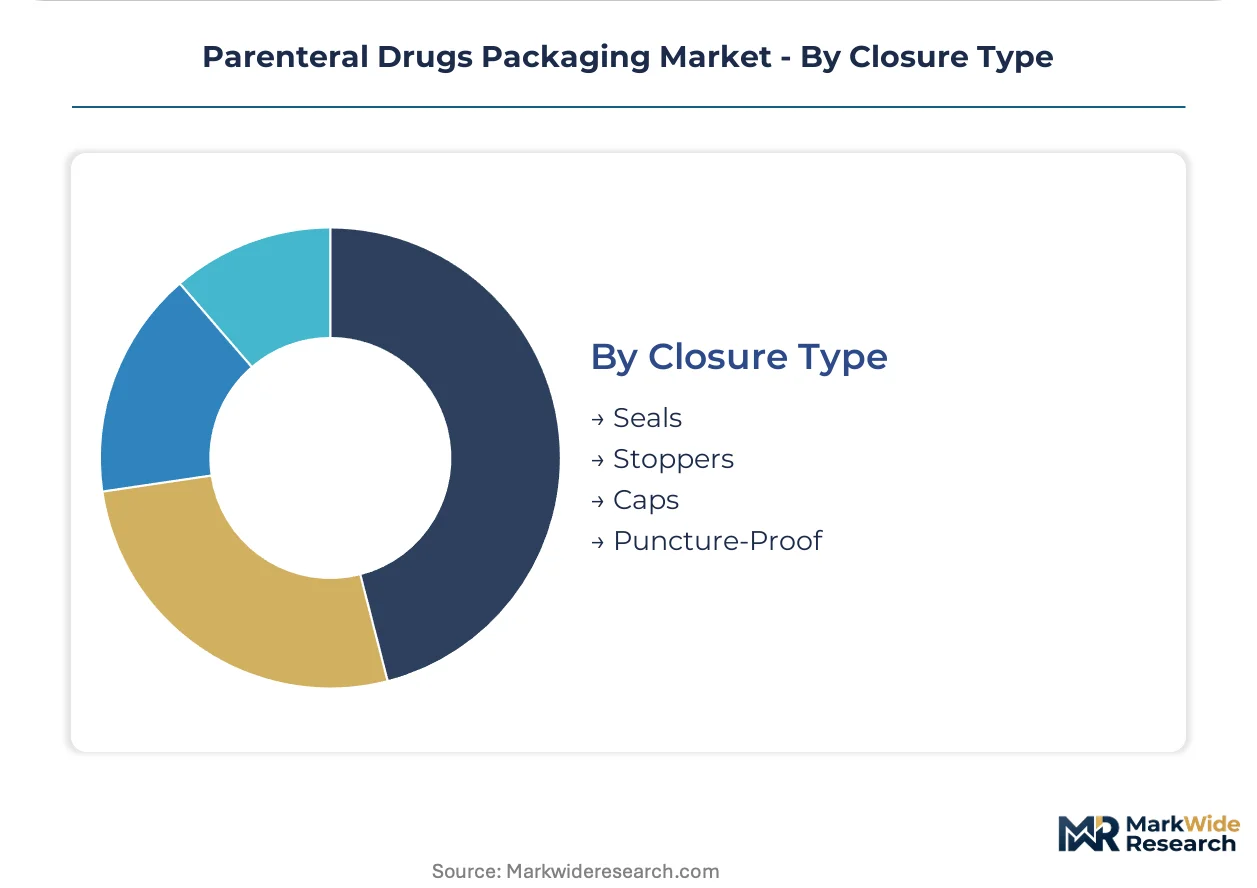
Stoppers generate the highest unit volumes, with puncture-proof closures ascending fastest on regulatory compliance tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized microbiologists and analytical chemists capable of container closure integrity validation cluster disproportionately in Germany, the United States, and Switzerland, anchoring regional capacity expansion timelines and supplier qualification programs.
United States
FDA chemistry, manufacturing, and controls enforcement for sterile drug products drives specification intensity among Massachusetts and California biotech developers. The agency's extractables study protocols diverge from EMA expectations, complicating multi-territory filings for combination product developers. Greater Boston and San Francisco Bay Area clusters concentrate demand for integrated containment-delivery systems with unified documentation.
Germany
Dense concentrations of glass primary packaging specialists and contract fill-finish providers capture disproportionate value from mRNA and monoclonal antibody launches. EU MDR serialization mandates and national pharmacopeial standards exceeding baseline harmonized requirements tighten traceability for sterile injectable containers. The Mainz and Münsterland industrial corridors anchor tubular borosilicate vial production for freeze-dried biologics.
Switzerland
Swissmedic oversight of combination product filings and medical device-classified primary packaging elevates technical documentation requirements for integrated systems. Basel and Zürich pharmaceutical corridors sustain demand for premium elastomeric closures and controlled nucleation vial technologies serving biologics manufacturers.
India
Domestic biologics manufacturing growth and export-oriented pharmaceutical production concentrate demand for pre-sterilized ready-to-use containers. CDSCO regulatory alignment with ICH guidelines accelerates qualification timelines for contract fill-finish providers. Hyderabad and Ahmedabad clusters expand ISO 15378-certified manufacturing lines for pre-filled syringe components.
China
NMPA serialization and traceability mandates for sterile injectables force packaging upgrades across domestic biologics manufacturing. The Yangtze River Delta pharmaceutical corridor concentrates demand for Type I borosilicate vials serving local monoclonal antibody developers. Shanghai and Suzhou industrial zones attract joint ventures with European glass primary packaging specialists.
Parenteral Drugs Packaging Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the containment spectrum. The market structures around three tiers: integrated system providers commanding premium pricing, specialized component fabricators serving fill-finish networks, and regional glass converters competing on scale. Two strategic archetypes dominate competitive positioning: vertically integrated containment-delivery specialists and focused tubular glass manufacturers. Capacity expansion and strategic partnerships represent the dominant competitive moves, with ISO 15378 certification backlog creating qualification bottlenecks that favor incumbents with established audit histories.
Among German-based fabricators, Gerresheimer AG and Schott AG exemplify the capital-intensive glass technology tier, with the former sustaining dominance in tubular vial production and the latter differentiating through borosilicate innovation. West Pharmaceutical Services anchors the high-value biologic containment segment through elastomer and delivery system specialization, representing the integrated system archetype that biologics procurement teams increasingly favor for unified extractables documentation.
| Leading Market Players |
|---|
| West Pharmaceutical Services |
| Amcor |
| Gerresheimer AG |
| Schott AG |
| Becton Dickinson and Company |
| AptarGroup |
| Nipro Corporation |
| Stevanato Group |
| SGD Pharma |
| Others |
Value Network & Pricing Analysis
Specialized microbiologists and analytical chemists capable of container closure integrity validation cluster disproportionately in Germany, Switzerland, and the United States, with labor-cost differentials between these hubs and emerging manufacturing corridors in India widening pricing-tier spreads across ISO 15378-certified and uncertified supply tiers.
Pricing Analysis
Bundled containment-delivery systems with unified extractables documentation command substantial premiums over unbundled component sourcing. Three-tier pricing structure across premium, standard, and economy levels separates vertically integrated system providers from specialized glass fabricators and regional converters. Pricing pressure stems from halobutyl rubber elastomer supply concentration among three compounders, compressing margins in stopper-dependent tiers. Contract manufacturers in India exhibit highest price sensitivity, while Massachusetts and California biotech developers prioritize qualification speed over unit cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by FDA chemistry, manufacturing, and controls enforcement and EU MDR notified body oversight force biologics manufacturers to qualify redundant suppliers for critical containment components. Supply concentrates in Germany for tubular borosilicate vials, the United States for elastomeric closures and delivery systems, and India for pre-sterilized ready-to-use containers. Raw material dependencies rest on Type I borosilicate glass feedstock, halobutyl rubber compounds, and pharmaceutical-grade silicone oils. Single-source vulnerability in halobutyl elastomer compounding creates structural risk. Distribution runs through direct procurement relationships between integrated system providers and biologics manufacturers, with contract fill-finish networks serving as secondary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, with EU MDR serialization mandates and REACH regulatory expansions elevating compliance costs in European corridors while CDSCO alignment with ICH guidelines accelerates qualification timelines in India.
For Market Incumbents: Acquire container closure integrity testing laboratories to capture scarce analytical chemistry talent and compress customer qualification timelines. Expand ISO 15378-certified manufacturing capacity in Hyderabad and Ahmedabad clusters to serve India's contract fill-finish expansion. Defend against cyclic olefin polymer substitution in emergency medicine by embedding controlled nucleation capabilities into borosilicate vial offerings for freeze-dried biologics. For New Entrants and Emerging Players: Contract fill-finish providers in India offer the most penetrable channel partnership opportunity, with domestic biologics manufacturing growth concentrating demand for pre-sterilized ready-to-use containers. Target emergency epinephrine and travel vaccine therapeutic categories where breakage risk outweighs protein stability concerns, enabling cyclic olefin polymer syringe penetration. Pursue go-to-market strategies emphasizing mechanical durability specifications for auto-injector manufacturers seeking polymer alternatives to glass. For Investors and Strategic Acquirers: Valuations sit cheapest among regional glass converters lacking ISO 15378 certification and vertical integration into elastomeric closure supply. Long-term viability over the next decade hinges on regulatory convergence between FDA and EMA extractables study protocols, which would compress multi-territory filing burdens and elevate unified documentation capabilities. Watch for inflection in halobutyl rubber compounder consolidation patterns, as further supply concentration would trigger forced dual-sourcing investments across biologics procurement teams.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15378 Certification Investment | Accelerates audit timelines for pharmaceutical quality management system accreditation in European and Indian manufacturing corridors. |
| Controlled Nucleation Technology Licensing | Enables faster lyophilization cycles for freeze-dried biologics manufacturers serving mRNA and monoclonal antibody portfolios. |
| Backward Integration into Halobutyl Compounding | Reduces vulnerability to input cost volatility from the three specialized pharmaceutical-grade stopper suppliers. |
| Contract Fill-Finish Partnership Expansion | Captures demand from India's domestic biologics manufacturing growth and export-oriented pharmaceutical production. |
| Unified Extractables Documentation Platform | Compresses regulatory submission preparation timelines for Massachusetts and California biotech developers. |
Research Methodology
Coverage spans the United States, Germany, Switzerland, India, and China, with primary inputs from each market combining structured interviews with regulatory affairs leads at biologics manufacturers, procurement managers at contract fill-finish providers, and technical directors at glass primary packaging specialists. Secondary validation draws from FDA chemistry manufacturing and controls guidance documents, EMA medical device classification filings, EU MDR technical documentation requirements, and CDSCO regulatory alignment circulars. Bottom-up demand modeling across container formats, material classes, and closure types triangulates against top-down market sizing from trade flow analysis and capacity announcements.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon, with analytical frameworks modeling packaging type, material tier, end-user category, and closure configuration as core segmentation dimensions. CAGRs derive from regression analysis against biologics pipeline advancement, chronic self-injection therapy penetration rates, and regulatory mandate implementation timelines. Industry-specific forecast inputs include mRNA and monoclonal antibody launch cadences, EU MDR serialization compliance deadlines, and REACH extractables study protocol evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between FDA and EMA extractables expectations, halobutyl rubber supply consolidation, and cyclic olefin polymer qualification breakthroughs in protein-sensitive applications. Deviation in EU MDR notified body capacity or ISO 15378 audit queue clearance rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
North America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Middle East and West Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Philippines Pharmaceutical Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
Pharmaceutical Tubes Market
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Global Temperature Controlled Packaging Solutions for Pharmaceuticals Market
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market