
 Asia-Pacific Pharmaceutical Plastic Packaging Market | 2026-2036
Asia-Pacific Pharmaceutical Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pharmaceutical Plastic Packaging Market Insights
Software-defined serialization and track-and-trace subscription layers is rebalancing contract economics between converters and drug makers. Amcor Group GmbH leverages its blow-fill-seal footprint across Southeast Asia to sustain multi-year supply agreements with multinational pharma firms. Gerresheimer AG anchors its position through pre-sterilized polymer syringe systems for biologics. Taisei Medical Co Ltd specializes in high-barrier multilayer films for Japan's precision-drug segment.
Asia-Pacific pharmaceutical plastic packaging comprises engineered polymer structures designed to maintain sterility, chemical stability, and tamper evidence for drug products, typically manufactured through injection blow molding, thermoforming, or multilayer extrusion with barrier coatings against moisture and oxygen ingress. Bottles and blisters occupy the largest volume positions, with bottles dominating oral medication distribution and blisters expanding fastest in dose-compliance packaging for aging populations. Polypropylene and polyethylene lead material selection for cost-sensitive oral applications, while PET gains ground in visible-dispensing containers where clarity and recyclability matter.
Japan's PMDA enforces strict leachable-extractable testing protocols that elevate qualification costs for imported packaging. India's CDSCO and China's NMPA have both aligned with ISO 15378 standards for primary packaging materials, creating dual-compliance burdens for regional suppliers. Australia's TGA maintains additional stability-study requirements that extend product validation timelines. Stakeholders must monitor evolving extended producer responsibility frameworks and polymer recycling mandates that could force material substitutions well before patent cliffs reshape drug portfolios.
Market Dynamics
Software-defined serialization layers are restructuring contract economics between converters and drug makers, forcing packaging suppliers to embed track-and-trace capabilities as standard rather than premium offerings.
Growth Catalysts
- Injectable Biologics Expansion:Pre-filled syringes and vials for monoclonal antibodies are pulling demand for cyclic olefin polymer structures across hospital networks and specialty clinics in Japan and South Korea.
- CDSCO-NMPA Alignment:India's CDSCO and China's NMPA have synchronized material traceability mandates with ISO 15378, creating unified qualification pathways that reduce dual-compliance overhead for regional suppliers.
- Maharashtra-Gujarat Concentration:India's pharmaceutical manufacturing belt is driving bulk procurement of polypropylene bottles and blister films for oral solid dosage exports to regulated markets.
Market Restraints
- Ethylene-Propylene Feedstock Volatility:Polyolefin resin costs swing with naphtha-cracker margins, compressing converter margins on standard oral-dose packaging contracts.
- PMDA Extractable-Leachable Burden:Japan's PMDA enforces extended migration testing protocols that add 12-18 months to packaging qualification timelines for imported materials.
- Glass Substitution Threat:Borosilicate and aluminosilicate glass vials retain preference for high-value biologics, limiting polymer penetration in the fastest-growing therapy segment.
Strategic Opportunities
- Vietnam-Indonesia Manufacturing Migration:Pharmaceutical contract manufacturing is shifting to lower-cost ASEAN locations, creating demand for localized blow-fill-seal capacity and regional distribution hubs.
- Extended Producer Responsibility Tailwinds:Australia's TGA and state-level frameworks are advancing polymer recycling mandates that favor PET and rPET packaging with verified circular content.
- Smart Packaging Convergence:Integration of NFC-enabled adherence sensors with multilayer barrier films is opening subscription revenue streams for packaging-as-a-service models.
Industry Challenges
- Serialization Engineering Talent Scarcity:Converters face acute shortages of software engineers capable of integrating GS1-compliant aggregation systems with legacy ERP infrastructure.
- Validation Timeline Compression:Accelerated drug approval pathways are squeezing packaging stability-study durations, forcing parallel-track qualification strategies that elevate capital risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pharmaceutical Plastic Packaging Market |
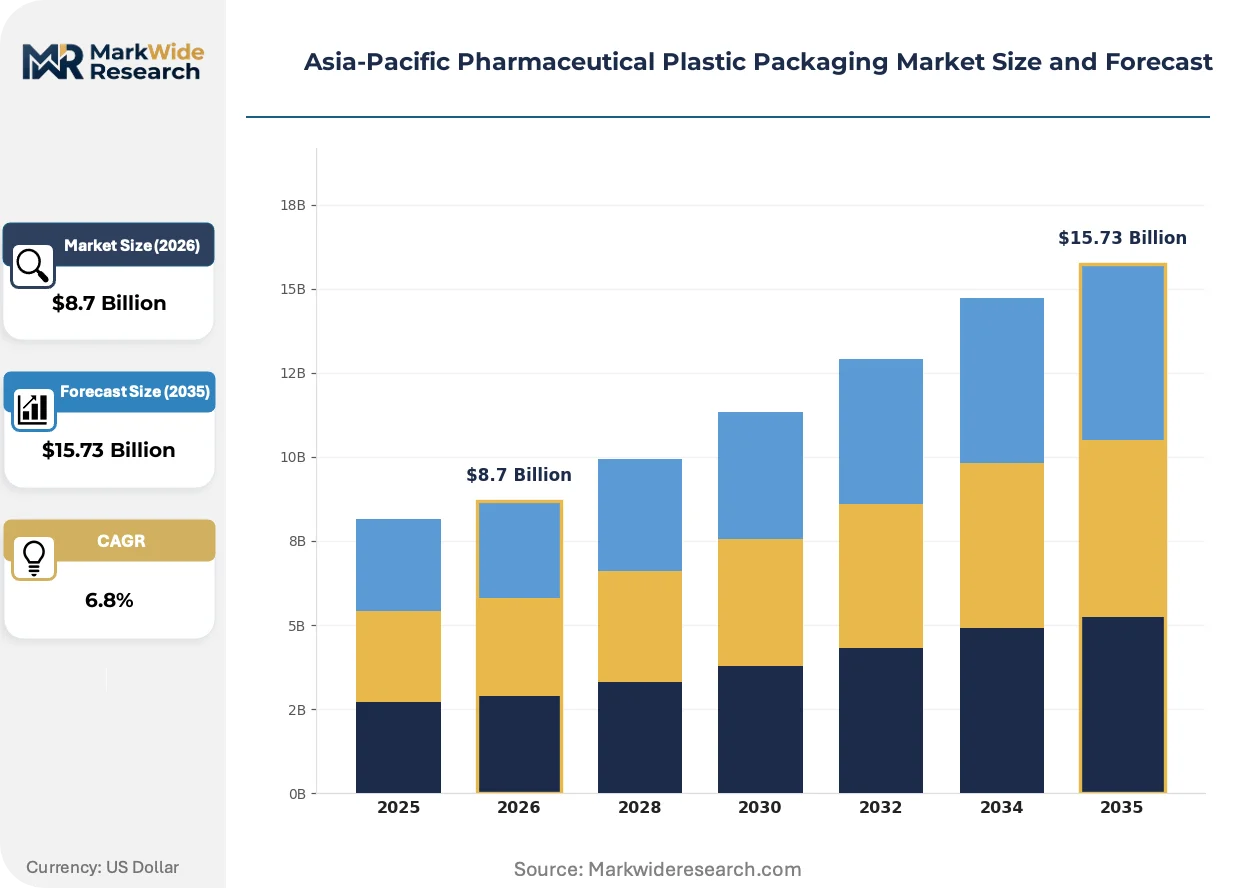
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
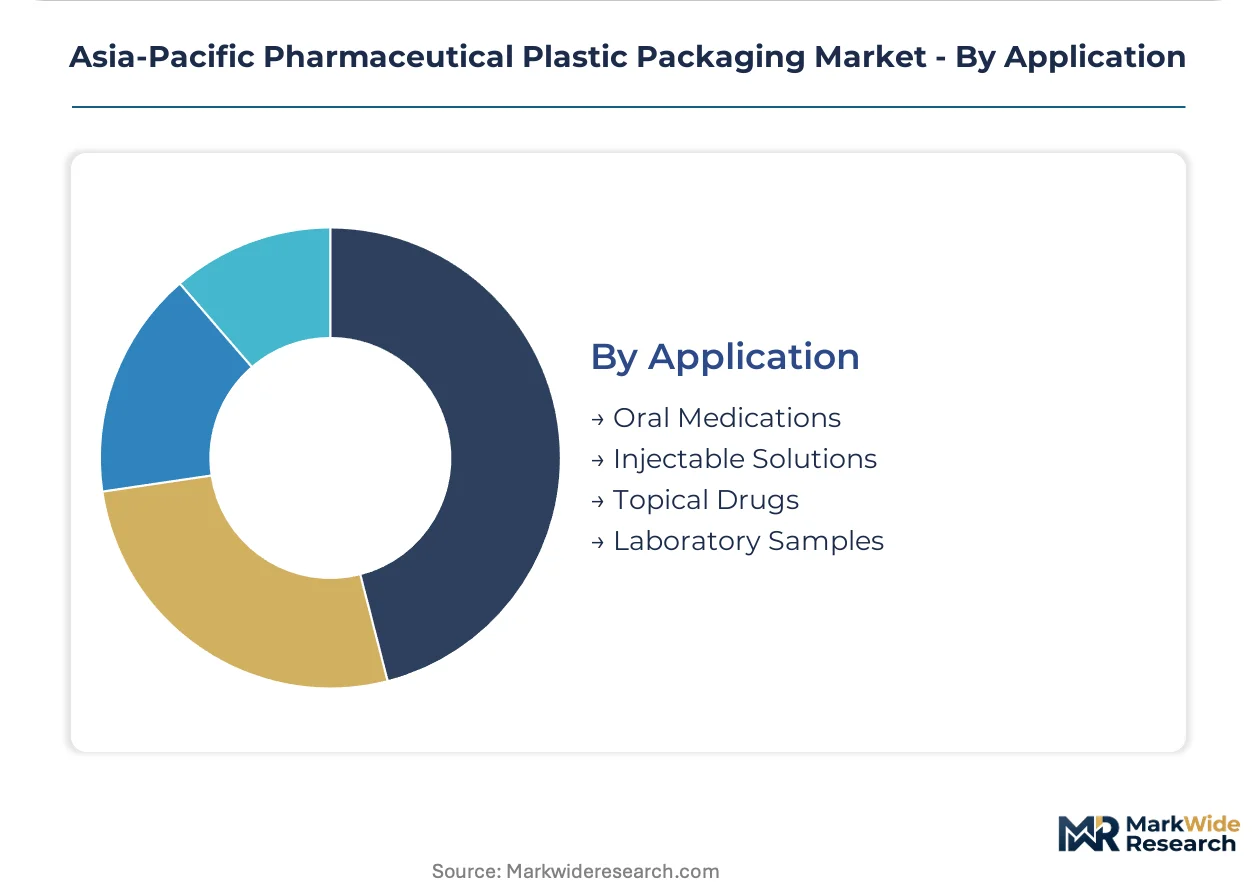
| Segmentation | Product Type: Bottles, Blisters, Sachets, Containers Material: Polyethylene, Polypropylene, Polyvinyl Chloride, PET End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutions, Distributors Application: Oral Medications, Injectable Solutions, Topical Drugs, Laboratory Samples |
| Companies Covered | AptarGroup Inc, Klockner Pentaplast Group, Amcor Group GmbH, Silgan Holdings Inc, Bormioli Pharma SpA, Gerresheimer AG, ALPLA Werke Alwin Lehner GmbH & Co KG, Taisei Medical Co Ltd, Berry Global Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pharmaceutical Plastic Packaging Market Trends and Innovations
Barrier engineering and digital integration are converging to redefine performance specifications for primary pharmaceutical packaging, with functionality now extending beyond containment into real-time supply chain visibility and patient adherence support.
Cyclic olefin copolymers (COC/COP) are electrifying the pre-filled syringe segment through glass-like clarity with polymer processability. Biologics manufacturers in Japan and South Korea are adopting these materials for protein-based injectables at pace. This electrifying shift is compressing qualification timelines for traditional glass-to-plastic conversions while elevating barrier-performance benchmarks across the category.
China's NMPA has implemented mandatory drug traceability codes linking primary packaging to patient-level dispensing records. This policy is forcing converters to retrofit extrusion and molding lines with inline printing and vision systems. Multinational pharma firms operating in China are responding by consolidating supplier bases to those with proven serialization infrastructure.
Hospital procurement consortia are consolidating purchasing power for standardized dose-compliance packaging across therapeutic categories. Group purchasing organizations in Australia's public health system are displacing fragmented clinic-level ordering with multi-year framework agreements. This concentration is most visible in Victoria and New South Wales, where centralized tenders now specify child-resistant senior-friendly (CRSF) blister formats as default.
Asia-Pacific Pharmaceutical Plastic Packaging Market Segmentation
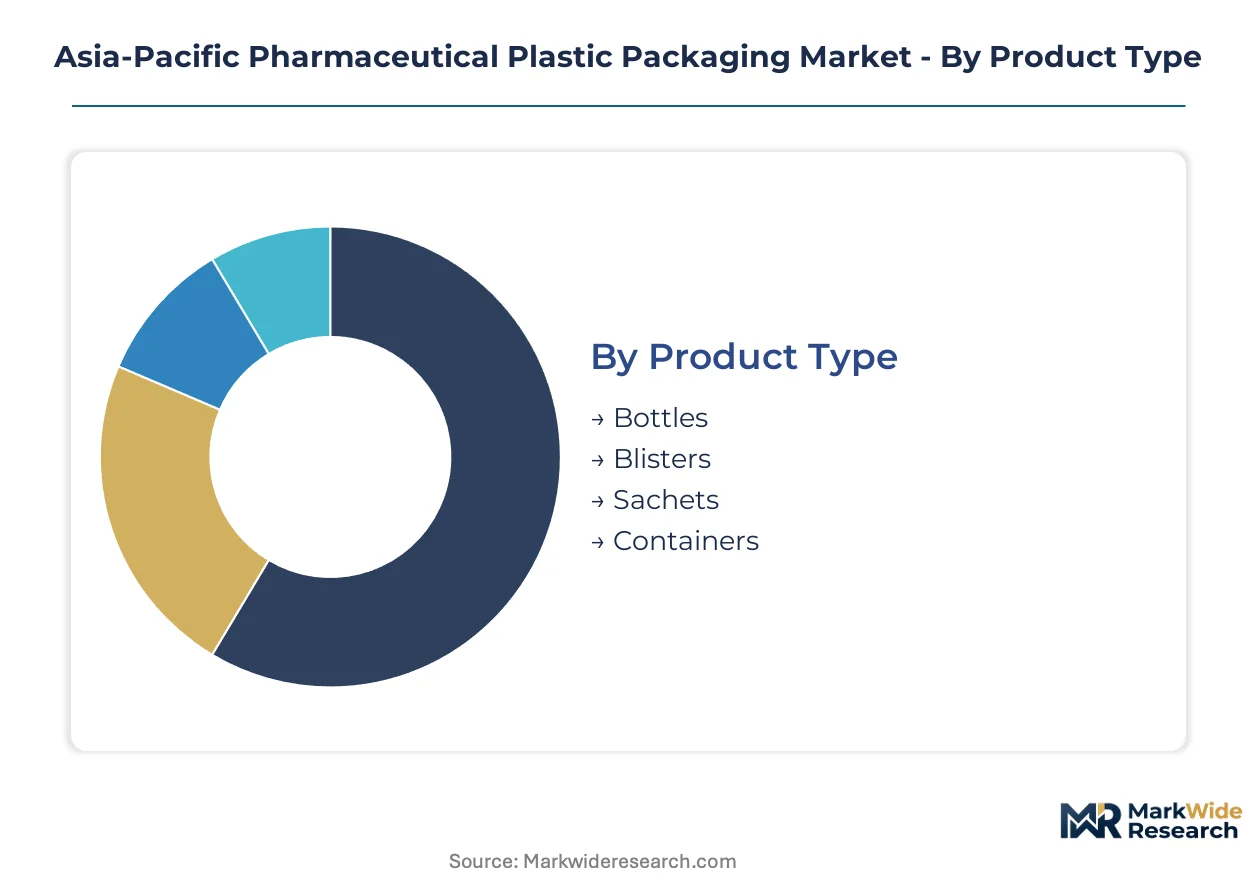
Segmentation in pharmaceutical plastic packaging reveals how converter capabilities align with drug delivery requirements across regulated markets. Material selection and format geometry determine barrier performance, while end-user procurement patterns dictate contract structure and margin distribution.
Product Type:
Standardization dominates high-volume oral formats, whereas customization concentrates in sterile delivery systems where barrier engineering varies by molecule sensitivity.
- Bottles:Polypropylene and HDPE structures with child-resistant closures dominate oral solid distribution across India's Maharashtra-Gujarat belt. CDSCO alignment with ISO 15378 has unified qualification pathways for exporters targeting regulated markets.
- Blisters:Cold-form aluminum-laminate and thermoformed PVC/PVDC multilayer films serve dose-compliance packaging for aging populations in Japan and Australia. Victoria and New South Wales hospital procurement consortia now specify CRSF formats as default.
- Sachets:Single-unit powder and granule packaging for over-the-counter segments.
- Containers:Wide-mouth jars for creams and ointments in topical applications.
Most installed capacity flows through Bottles. Expansion is steepest in Blisters.
Material:
Cost-performance tradeoffs separate commodity polyolefins from engineered polymers in sterile applications.
- Polyethylene:HDPE and LDPE grades supply cost-sensitive oral bottles across India's contract manufacturing sector. Naphtha-cracker margin volatility compresses converter margins on standard dosage contracts.
- Polypropylene:Random and impact copolymers balance clarity with chemical resistance in visible-dispensing containers. China's Jiangsu-Zhejiang corridor drives bulk procurement for export-oriented formulations.
- Polyvinyl Chloride:Plasticized and rigid PVC formulations for blister base films and medical tubing.
- PET:Virgin and rPET grades with verified circular content gain preference under Australia's advancing extended producer responsibility frameworks.
Polyethylene commands the largest installed base. PET is climbing the fastest on recyclability mandates.
End User:
Procurement concentration distinguishes multinational volume buyers from fragmented institutional purchasers.
- Pharmaceutical Companies:Integrated drug makers in Japan and South Korea specify cyclic olefin polymer syringes for monoclonal antibody portfolios. PMDA extractable-leachable protocols extend qualification timelines for imported packaging materials.
- Contract Manufacturers:CDMO migration to Vietnam and Indonesia creates demand for localized blow-fill-seal capacity and regional distribution infrastructure.
- Research Institutions:Small-batch clinical trial packaging with accelerated stability-study requirements.
- Distributors:Wholesale procurement of standardized formats for pharmacy and hospital networks.
Pharmaceutical Companies anchor current capacity utilization. Contract Manufacturers show the steepest expansion trajectory on ASEAN manufacturing migration.
Application:
Therapy format dictates barrier specification, with sterile injectables requiring the most engineered polymer structures.
- Oral Medications:Tablets and capsules in bottles and blisters dominate volume across cost-sensitive markets. China's NMPA traceability mandates force inline serialization retrofitting across extrusion and molding lines.
- Injectable Solutions:Pre-filled syringes and vials for biologics pull demand for cyclic olefin copolymers with glass-like clarity. Japan and South Korea manufacturers compress qualification timelines for glass-to-plastic conversions.
- Topical Drugs:Creams, gels, and transdermal patches in tubes and pouches.
- Laboratory Samples:Diagnostic and research specimen containment with specialized closure systems.
Oral Medications absorb the majority of installed capacity. Injectable Solutions are gaining share fastest on biologics expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing pharmaceutical packaging production across Asia-Pacific as converters seek cost-of-compliance advantages. Manufacturing migration toward ASEAN jurisdictions with streamlined qualification pathways is accelerating while established hubs defend positions through specialized barrier-engineering capabilities.
China
Jiangsu-Zhejiang corridor drives bulk procurement of polypropylene bottles and blister films for export-oriented oral solid dosage formulations. NMPA mandatory drug traceability codes now link primary packaging to patient-level dispensing records, forcing inline serialization retrofitting across extrusion lines. Suzhou and Hangzhou clusters concentrate blow-fill-seal capacity serving multinational pharma contract manufacturing.
India
Maharashtra-Gujarat pharmaceutical belt anchors domestic demand for HDPE containers and PVC blister base films targeting regulated export markets. CDSCO alignment with ISO 15378 standards has unified qualification pathways, reducing dual-compliance overhead for regional suppliers. Ahmedabad and Mumbai-Pune industrial zones host integrated converter operations supplying oral-dose packaging to European and North American drug makers.
Japan
Precision-drug packaging requirements in Tokyo-Osaka corridor elevate demand for cyclic olefin polymer syringes and high-barrier multilayer films. PMDA enforces extended leachable-extractable testing protocols that add 12-18 months to qualification timelines for imported materials. Kanto and Kansai manufacturing bases specialize in pre-sterilized polymer systems for monoclonal antibody portfolios.
South Korea
Biologics manufacturing expansion in Seoul-Incheon metro pulls demand for glass-like clarity polymers in pre-filled syringe applications. MFDS stability-study requirements compress validation timelines for glass-to-plastic conversion projects. Songdo and Osong bioclusters anchor specialized packaging qualification facilities serving domestic and regional drug makers.
Australia
Victoria and New South Wales hospital procurement consortia now specify child-resistant senior-friendly blister formats as default across therapeutic categories. TGA extended producer responsibility frameworks advance polymer recycling mandates favoring PET with verified circular content. Melbourne and Sydney distribution hubs coordinate centralized tendering for standardized dose-compliance packaging.
Asia-Pacific Pharmaceutical Plastic Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated multinationals commanding sterile delivery formats while regional converters capture oral-dose volume. Market structure tilts toward tiered consolidation: three to four global players anchor premium barrier-engineering segments, mid-scale specialists populate standard oral packaging, and fragmented local fabricators serve cost-sensitive generic markets. Dominant competitive moves include strategic partnerships for serialization infrastructure and geographic expansion into Vietnam-Indonesia manufacturing corridors.
Among Asia-Pacific-based specialists, Taisei Medical Co Ltd and Amcor Group GmbH exemplify divergent archetype positioning. Taisei Medical occupies a position within Japan's precision-drug packaging tier, representing high-barrier multilayer film specialization. Amcor Group GmbH anchors Southeast Asian blow-fill-seal capacity, exemplifying integrated multinational scale. Gerresheimer AG sits within the European-originated premium sterile systems tier, representing pre-sterilized polymer syringe capabilities for biologics applications.
| Leading Market Players |
|---|
| AptarGroup Inc |
| Klockner Pentaplast Group |
| Amcor Group GmbH |
| Silgan Holdings Inc |
| Bormioli Pharma SpA |
| Gerresheimer AG |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Taisei Medical Co Ltd |
| Berry Global Inc |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement consortia in Victoria and New South Wales specifying child-resistant senior-friendly blister formats as default are forcing converters to absorb qualification costs while standardizing output, compressing margins on legacy oral-dose contracts and accelerating tier separation between serialization-capable suppliers and commodity fabricators.
Pricing Analysis
Direct-to-pharma contract discounts dominate high-volume oral packaging agreements across India's Maharashtra-Gujarat belt. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15378-certified barrier films from basic polypropylene bottles and generic blister base materials. Cost compression in standard oral-dose segments is intensifying because naphtha-cracker margin volatility feeds resin price instability. Contract manufacturers exhibit the sharpest price sensitivity, while biologics specialists in Japan and South Korea accept premium tiers for cyclic olefin polymer syringes with extended validation support.
Supply Chain Analysis
Workforce availability constraints in Vietnam and Indonesia are slowing blow-fill-seal capacity expansion despite pharmaceutical contract manufacturing migration to these lower-cost ASEAN locations. Raw material procurement draws from Saudi ethylene feedstock, South Korean naphtha crackers, and regional polyolefin resin distributors. Single-source vulnerability concentrates in Japan's specialized cyclic olefin polymer resin supply, where PMDA qualification requirements lock converters into approved supplier lists. Distribution runs through regional distribution hubs in Singapore and Bangkok, with final-mile delivery to hospital networks and specialty clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
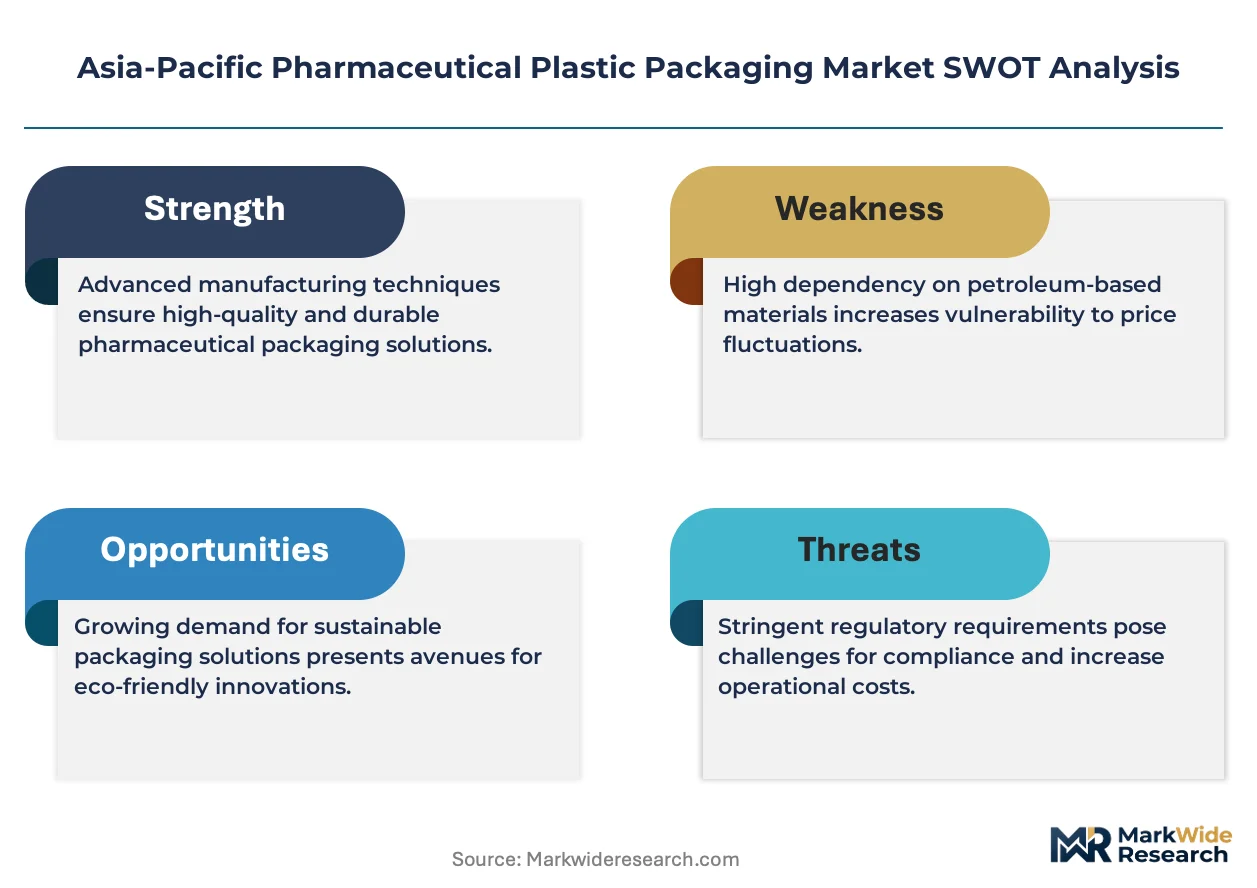
This market offers margin-expansion potential through premium-tier shifts toward pre-sterilized polymer syringes for biologics, where validation-service bundling captures value beyond commodity resin conversion.
For Market Incumbents: Hedge against glass substitution threats in high-value injectables by deepening cyclic olefin polymer qualification capabilities and securing multi-year serialization infrastructure partnerships. Anchor Southeast Asian blow-fill-seal capacity in Vietnam-Indonesia corridors ahead of contract manufacturing migration. Prioritize backward integration into barrier film coextrusion to defend margin position against resin volatility. For New Entrants and Emerging Players: Mid-scale contract manufacturers in Vietnam and Indonesia represent the most penetrable buyer archetype, as these firms lack established converter relationships and face urgent localization mandates. Target blow-fill-seal capacity gaps serving ASEAN pharmaceutical exports. Lead with rapid ISO 15378 qualification support and flexible batch-size economics rather than scale-driven unit cost claims. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized barrier-engineering converters holding PMDA-approved cyclic olefin polymer syringe capabilities, as biologics expansion in Japan and South Korea outpaces qualified supply. Acquisition candidates should demonstrate installed serialization infrastructure and regional regulatory approvals across multiple Asia-Pacific jurisdictions. Watch for CDSCO-NMPA harmonization announcements as inflection indicators for cross-border supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Infrastructure Partnership | Inline track-and-trace retrofitting satisfies China's NMPA mandatory drug traceability codes for patient-level dispensing records. |
| Cyclic Olefin Polymer Qualification | PMDA-approved glass-to-plastic conversion capabilities capture biologics syringe demand from Japan and South Korea manufacturers. |
| ASEAN Manufacturing Footprint Expansion | Localized blow-fill-seal capacity in Vietnam and Indonesia aligns with pharmaceutical contract manufacturing migration patterns. |
| Barrier Film Backward Integration | In-house coextrusion of multilayer films reduces exposure to naphtha-cracker margin volatility in polyolefin resin markets. |
| Extended Producer Responsibility Certification | Verified rPET circular content credentials satisfy Australia's TGA advancing polymer recycling mandates for hospital procurement. |
Research Methodology
Multiple input streams — converter production data, hospital procurement contract terms, and regulatory filing documentation — were reconciled through structured interviews with packaging development executives, regulatory affairs leads at multinational pharma firms, hospital procurement managers in Australia's public health system, and blow-fill-seal plant managers across Southeast Asia. Secondary validation drew from CDSCO alignment notifications, NMPA traceability code implementation records, PMDA leachable-extractable testing protocols, and customs trade data on polymer resin flows. Bottom-up capacity estimates and top-down demand aggregation were cross-checked for consistency.
Data-stream reconciliation across the projection horizon applied treatment-line segmentation by therapy format, dosage-form classification across oral and injectable categories, administration-route differentiation, and regional regulatory cluster mapping. CAGRs were derived from fitted growth curves calibrated to observed capacity expansion announcements and procurement contract durations. Forecast inputs incorporated biologics pipeline progression, serialization infrastructure deployment timelines, and extended producer responsibility framework advancement.
Underlying measurement precision varies by segment; oral-dose bottles and standard blister films carry tighter precision than emerging cyclic olefin polymer syringe categories where qualification timelines remain uncertain. Forecasts reflect assumptions regarding regulatory harmonization continuity, resin feedstock availability, and biologics manufacturing expansion trajectories. Material deviation in CDSCO-NMPA alignment enforcement, PMDA testing protocol revisions, or ASEAN manufacturing migration velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Global Biodegradable Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Packaging Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Tablet Bottle Market
Pharmaceutical Packaging
Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
APAC Pharmaceutical Packaging Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Pharmaceutical Vials Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Vials Market
Pharmaceutical Packaging
Pharmaceutical Ampoules Market
Pharmaceutical Packaging
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market
Pharmaceutical Packaging
Global Temperature Controlled Packaging Solutions for Pharmaceuticals Market
Pharmaceutical Packaging
Latin America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market
Pharmaceutical Packaging
China Pharmaceutical Contract Packaging Market