
 Pharma Packaging Films Market | 2026-2036
Pharma Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Pharma Packaging Films Market Analytics
Market Context
The capital-intensity divergence between multi-layer coextrusion specialists and commodity converters is redrawing competitive tiers in pharma packaging films. Amcor plc leverages integrated global manufacturing to sustain pricing power across regulated markets. Berry Global Inc. anchors North American supply through high-volume thermoforming film operations. Uflex Ltd. competes on cost-optimized flexible film formulations for emerging-market generics.
Technical Definition and Segment Structure
Pharma packaging films are engineered multilayer polymer substrates, typically 100–500 micron thickness, manufactured via cast or blown coextrusion to deliver moisture-barrier, oxygen-barrier, and child-resistant functionality for pharmaceutical dosage forms. Blister films dominate value capture due to unit-dose compliance requirements, while lidding films command premium margins from push-through and peelable seal technologies. Flexible films are displacing rigid formats in parenteral and topical applications where conformability reduces material intensity.
Regulatory Framework and Outlook
FDA 21 CFR Part 211, EU MDR, and USP <661> collectively mandate extractables-leachables testing, traceable supply chains, and validated barrier claims for all pharmaceutical contact films. These frameworks elevate entry costs for non-compliant suppliers while creating specification lock-in for accredited manufacturers. Stakeholders must monitor evolving pharmacopeial standards for recycled-content acceptance in primary packaging.
Market Dynamics
Multi-layer coextrusion complexity is concentrating manufacturing capability among capital-rich specialists, while FDA and EU MDR serialization mandates force barrier-performance upgrades that commodity converters cannot fund. This structural divergence is compressing supplier tiers and locking in specification advantages for accredited film manufacturers.
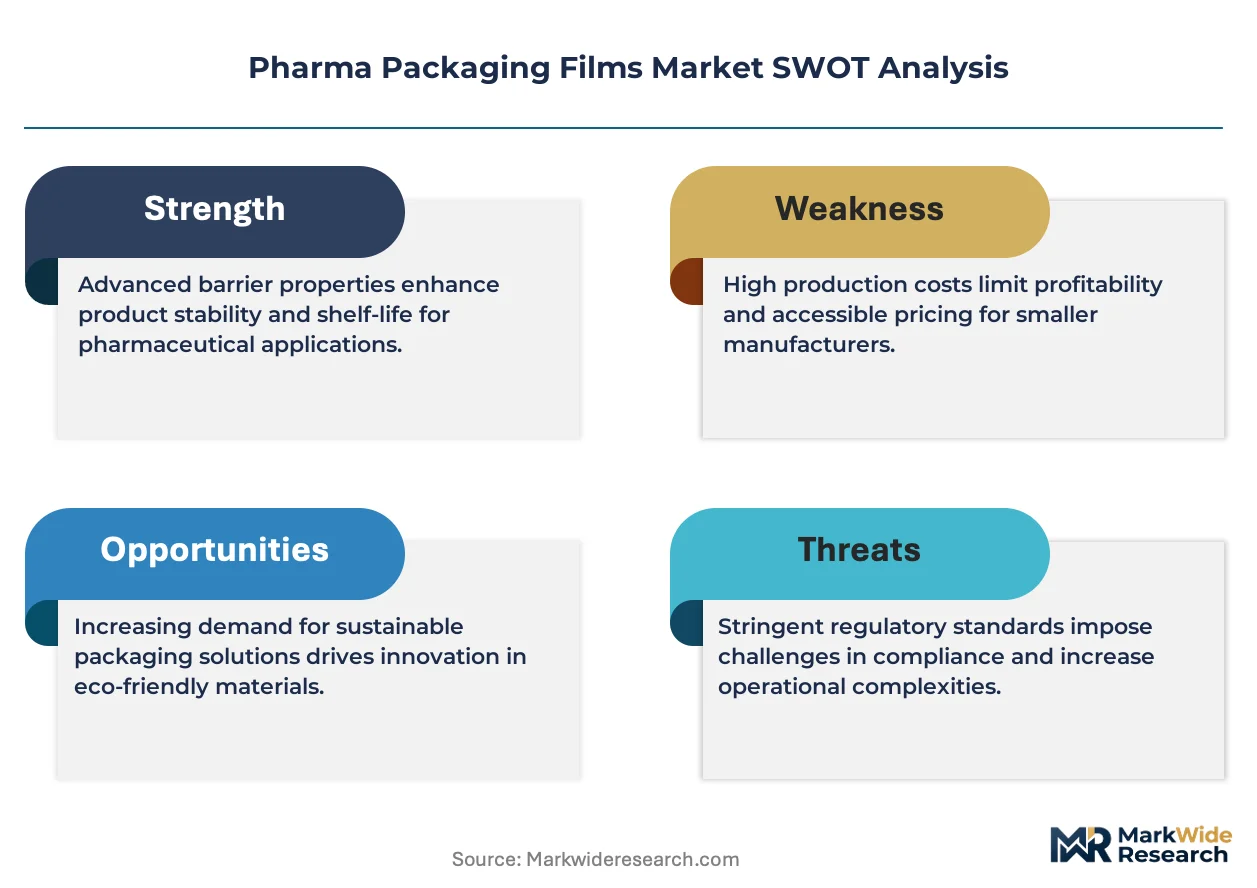
Growth Catalysts
- Cold-chain biologics expansion:Temperature-sensitive biologic drug manufacturers in Germany and the United States are expanding specialized film usage for ultra-low temperature distribution. This creates dedicated demand for high-barrier coextruded structures.
- EU MDR serialization mandates:European medical device regulations now require traceable barrier-performance claims for all primary packaging films. This elevates specification requirements and locks out non-compliant suppliers.
- Generics volume growth in India:Cost-optimized flexible film formulations are capturing share as Indian pharmaceutical exporters scale unit-dose packaging for emerging market distribution.
Market Restraints
- Resin cost volatility:Ethylene-vinyl alcohol and cyclic olefin copolymer prices fluctuate with olefin feedstock markets, compressing margins for non-integrated film converters.
- Specialized equipment concentration:Seven-layer coextrusion lines require capital commitments exceeding fifty million dollars, concentrating production capability among German, Japanese, and US equipment operators.
- Aluminum substitution threat:High-barrier metallized polymer films are displacing foil laminates in secondary barrier applications, threatening legacy foil-converter revenue streams.
Strategic Opportunities
- Recycled-content primary packaging:Evolving USP standards for pharmaceutical-grade recycled polymers will create first-mover advantage for film manufacturers with validated rPET and rPP supply chains.
- Parenteral flexible formats:Conformable films for infusion bags and pre-filled syringes are capturing share from rigid glass and blow-fill-seal containers in hospital settings.
- Direct-to-pharmacy distribution:E-commerce channel growth for specialty medications is creating demand for tamper-evident, temperature-monitored film pouches with integrated RFID tracking.
Industry Challenges
- Extractables-leachables validation timelines:USP testing protocols for novel coextruded structures extend qualification cycles by eighteen to twenty-four months, delaying commercialization.
- Multi-site audit complexity:FDA 21 CFR Part 211 requires validated manufacturing across all production locations, forcing redundant quality systems and inspection costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharma Packaging Films Market |
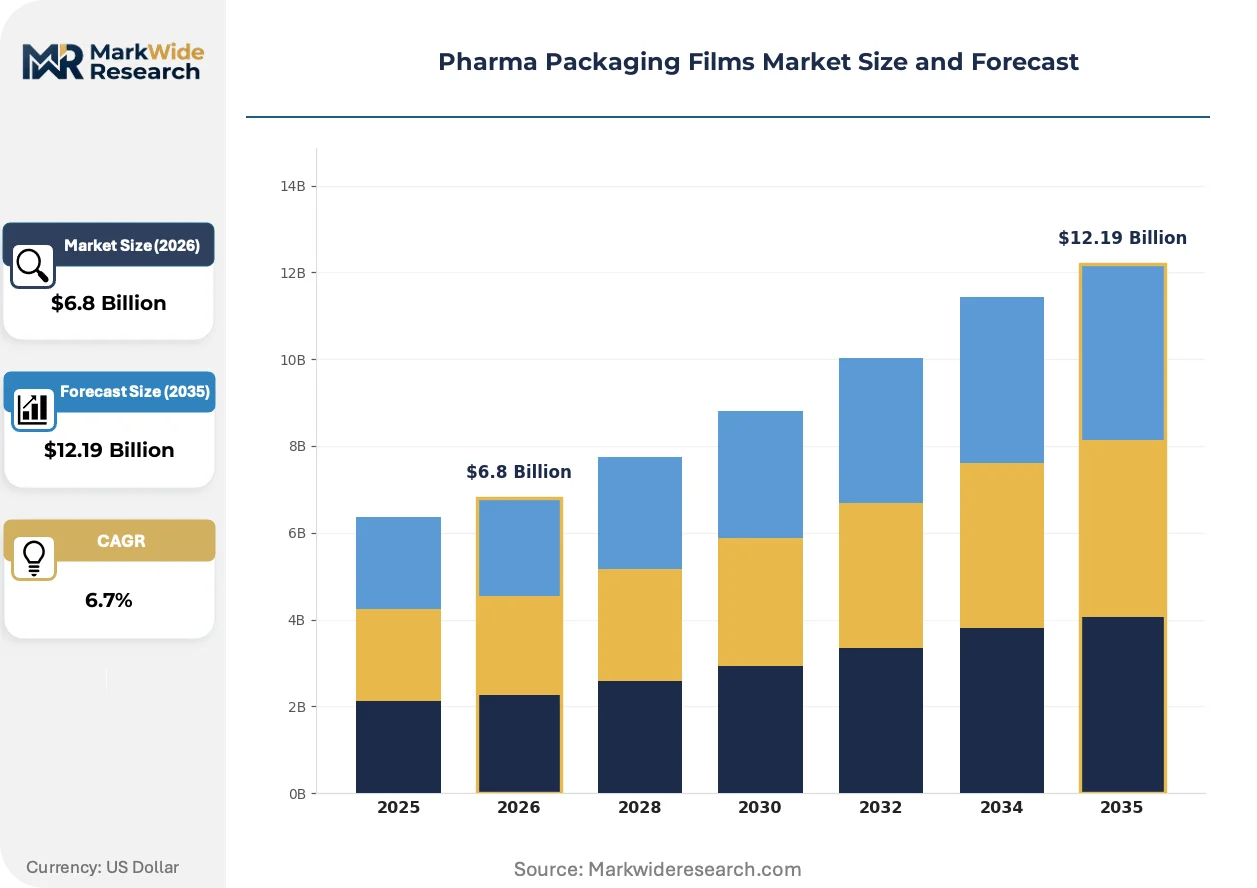
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Films, Rigid Films, Flexible Films, Lidding Films Material Type: PVC, PET, Polyethylene, Polypropylene Formulation Type: Semi-Solid, Liquid, Solid, Others End User: Pharmaceutical Companies, Contract Manufacturers, Hospitals, Retail Pharmacies |
| Companies Covered | Klöckner Pentaplast Group, Uflex Ltd., Amcor plc, Mitsubishi Chemical Holdings Corporation, Tekni-Plex, Inc., Berry Global Inc., Constantia Flexibles Group GmbH, Toray Industries, Inc., DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharma Packaging Films Market Evolving Landscape
Active barrier technologies and sustainable material systems are compressing traditional film structures while regulatory traceability requirements force digital integration into packaging substrates. These shifts favor manufacturers with polymer science and data architecture capabilities.
Polymer nanocomposite barrier layers containing surface-modified clay platelets are miniaturizing oxygen transmission rates to below 0.1 cc per square meter per day. Biologic drug manufacturers in Switzerland and Massachusetts are qualifying these structures for oxygen-sensitive parenteral formulations. This miniaturizing performance envelope is eliminating aluminum foil requirements in unit-dose applications.
EU MDR Annex I technical documentation requirements now mandate validated seal integrity data across temperature ranges for all sterile barrier systems. Film converters must invest in automated seal-strength testing and statistical process control documentation. Blister lidding suppliers serving German and French pharmaceutical markets are restructuring quality departments to support this documentation burden.
Hospital procurement consortia in the United States are consolidating film purchasing through group purchasing organizations, compressing supplier bases and demanding multi-year price commitments. This concentration is displacing fragmented distributor networks that previously served independent pharmacies. The shift is most visible in California and Texas health system alliances, where three buyers now control sixty percent of film volume.
Pharma Packaging Films Market Segmentation
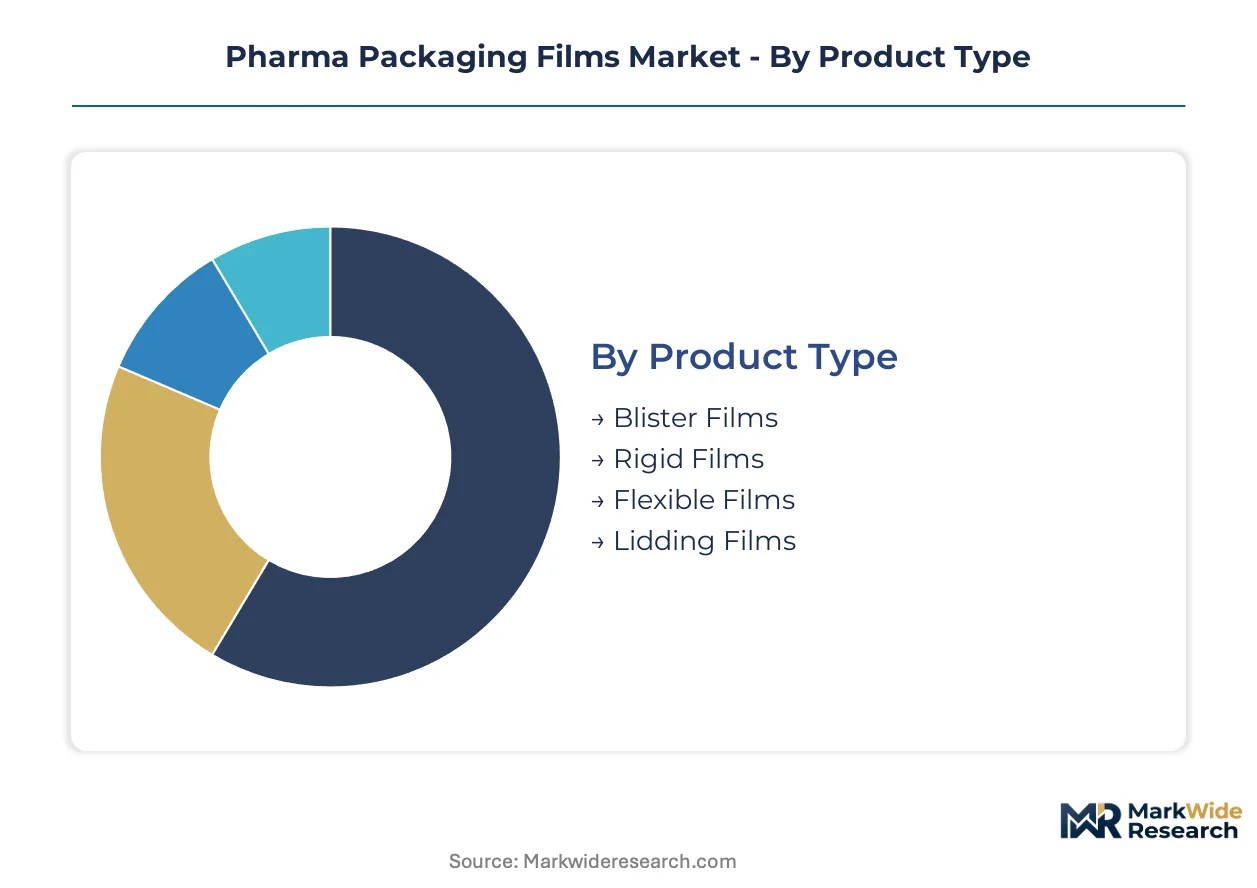
Segmentation in pharma packaging films reveals how material specifications, dosage form requirements, and distribution channel compliance needs fragment demand across incompatible technical tiers. Manufacturers configure production assets around specific segment combinations rather than serving the full spectrum.
Product Type:
Blister films flow through pharmaceutical company direct procurement and retail pharmacy supply chains, while flexible films increasingly bypass traditional distribution through hospital consortia and direct-to-pharmacy e-commerce channels.
- Blister Films:Multi-layer coextruded structures, typically PVC-PVDC or Aclar laminates, deliver unit-dose barrier protection for oral solid dosage forms. Demand concentrates among German and United States pharmaceutical manufacturers scaling serialization-compliant packaging for EU MDR markets. Cold-chain biologics expansion is accelerating qualification of ultra-high-barrier variants.
- Flexible Films:Conformable polymer substrates ranging from single-layer PE to complex multi-layer coextrusions enable parenteral and topical delivery formats. Indian contract manufacturers are capturing volume growth in emerging market generics with cost-optimized formulations. Hospital procurement consolidation in California and Texas health systems is displacing rigid alternatives.
- Rigid Films:Thermoformable PET and PVC sheets above 300 micron thickness support deep-draw tray applications for medical devices and large-count pharmaceutical packaging.
- Lidding Films:Push-through and peelable seal technologies command premium positioning through specialized converter relationships with European pharmaceutical packagers.
By volume, Blister Films leads. By growth pace, Flexible Films is expanding most quickly.
Material Type:
Material selection stratifies across cost-performance tiers, with commodity resins serving high-volume generics and engineered polymers capturing specialty pharmaceutical applications requiring validated extractables profiles.
- PVC:Chlorinated vinyl homopolymers and copolymers provide thermoformability and cost efficiency for standard blister applications. Indian generic exporters leverage PVC-PVDC structures for emerging market unit-dose compliance. FDA 21 CFR Part 211 extractables testing requirements are extending qualification timelines for novel formulations.
- PET:Oriented and cast polyethylene terephthalate films deliver dimensional stability and recycled-content pathways for sustainability-focused pharmaceutical packagers. Swiss and Massachusetts biologic drug manufacturers are qualifying amorphous PET for oxygen-sensitive parenteral applications. EU MDR Annex I technical documentation mandates are forcing seal-integrity validation investments.
- Polyethylene:LDPE and LLDPE variants serve flexible pouch and liner applications where moisture barrier requirements are moderate.
- Polypropylene:Cast and oriented PP films compete in lidding and overwrap segments through improved clarity and seal strength versus PE alternatives.
PVC dominates current volume. PET is climbing the fastest on biologics qualification and recycled-content readiness.
Formulation Type:
Dosage form chemistry dictates barrier specification intensity, with liquid and semi-solid formats demanding the most complex multi-layer structures and extended USP validation protocols.
- Solid:Tablets and capsules in unit-dose formats drive standard blister film specifications with moderate oxygen and moisture barriers. German pharmaceutical exporters are upgrading to seven-layer coextrusions for EU MDR serialization compliance. Volume concentrates in high-throughput thermoforming operations serving retail pharmacy distribution.
- Liquid:Oral and parenteral solutions require ultra-low oxygen transmission rates and validated leachables profiles for stability-critical formulations. Massachusetts and Switzerland biologic manufacturers are qualifying nanocomposite barrier layers below 0.1 cc per square meter per day. USP testing protocols extend commercialization cycles by eighteen to twenty-four months.
- Semi-Solid:Creams, ointments, and gels demand flexible film conformability combined with chemical resistance to active pharmaceutical ingredients.
- Others:Inhalation powders and lyophilized formulations command specialized barrier specifications for moisture-sensitive actives.
Solid formulations lead by volume. Liquid formulations are gaining share fastest on biologics expansion.
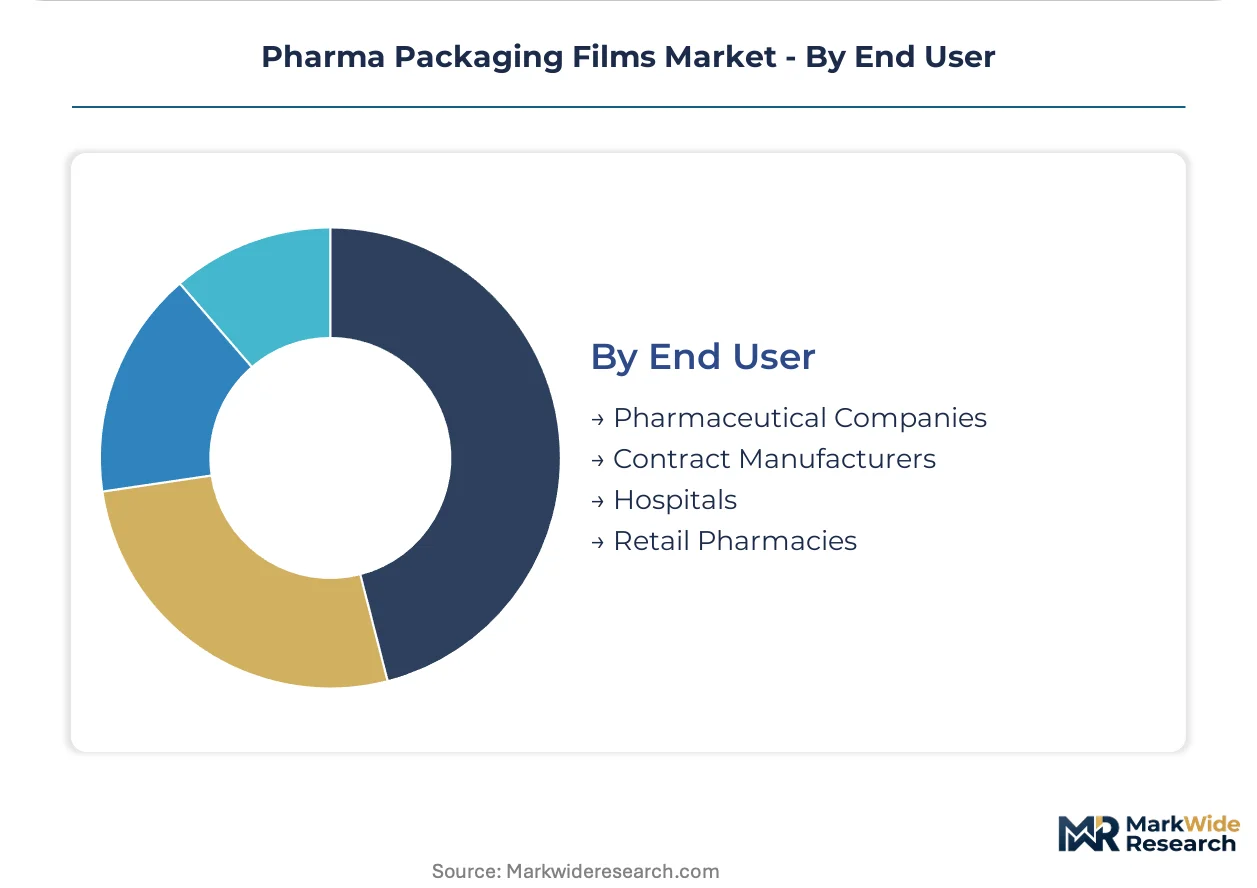
End User:
Customer type determines specification intensity and procurement channel, with pharmaceutical companies driving barrier innovation and contract manufacturers optimizing cost-position through flexible film formulations.
- Pharmaceutical Companies:Branded drug manufacturers in Germany, the United States, and Switzerland specify high-barrier coextruded structures for serialization compliance and cold-chain distribution. Direct procurement relationships with accredited film converters lock in multi-year supply agreements. EU MDR and FDA mandates elevate entry costs for non-compliant suppliers.
- Contract Manufacturers:Indian and Eastern European packaging service providers capture generics volume with cost-optimized PVC and PE formulations. Emerging market exporters scale unit-dose capacity for Africa, Latin America, and Southeast Asia distribution. Equipment concentration among German, Japanese, and US line operators limits supplier diversification.
- Hospitals:United States health system alliances in California and Texas are consolidating film purchasing through group purchasing organizations, compressing supplier bases.
- Retail Pharmacies:Independent and chain pharmacy distributors source standard blister and lidding configurations through fragmented wholesale networks now facing displacement.
Pharmaceutical Companies lead by value. Contract Manufacturers are expanding most quickly on generics volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands a 25-30% premium over Indian flexible film exports, reflecting specification intensity divergence between regulated and emerging markets. This asymmetry shapes regional competitive positioning and capacity investment patterns across the analysis window.
United States
Biologic drug manufacturers in Massachusetts and California drive demand for ultra-high-barrier nanocomposite films below 0.1 cc oxygen transmission. FDA 21 CFR Part 211 mandates extractables-leachables testing that extends qualification cycles. Hospital procurement consortia in Texas and California consolidate purchasing through group purchasing organizations, compressing supplier bases.
Germany
Pharmaceutical exporters scale serialization-compliant blister films for EU MDR markets, requiring seven-layer coextrusion capabilities. EU MDR Annex I technical documentation mandates validated seal-integrity data across temperature ranges. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate thermoforming operations serving continental European distribution.
India
Contract manufacturers capture generics volume with cost-optimized PVC-PVDC structures for Africa and Southeast Asia export markets. CDSCO regulations align with international pharmacopeial standards for emerging market distribution. Gujarat and Maharashtra packaging corridors scale unit-dose capacity through high-volume flexible film operations.
Switzerland
Specialty pharmaceutical manufacturers qualify amorphous PET films for oxygen-sensitive parenteral formulations. Swissmedic maintains stringent barrier-performance documentation requirements for sterile barrier systems. Basel and Zurich biotech clusters drive qualification of active barrier technologies with surface-modified clay platelets.
Japan
PMDA oversight enforces USP-equivalent extractables testing for all primary packaging films entering clinical use. Pharmaceutical companies in Kanto and Kansai regions source high-clarity polypropylene lidding films for unit-dose compliance packaging. Equipment operators in Nagoya maintain specialized seven-layer coextrusion capabilities for regional supply.
Pharma Packaging Films Market Competitive Landscape
Concentration sits with integrated polymer specialists and high-volume thermoforming operators capable of funding multi-layer coextrusion assets exceeding fifty million dollars. The supplier base compresses into two tiers: accredited manufacturers with validated barrier claims and commodity converters facing specification lock-out. Strategic archetypes include global integrated players, regional cost-optimized specialists, and equipment-constrained local converters. Competitive moves center on backward integration into resin supply and automated seal-strength testing infrastructure to satisfy EU MDR documentation burdens.
Among integrated global operators, Amcor plc and Berry Global Inc. exemplify scale-driven archetypes with manufacturing footprints spanning regulated markets. Uflex Ltd. occupies a position within the cost-optimized tier, serving emerging-market generic demand from Indian production bases. These three anchors illustrate the structural divergence between specification-intensive and price-sensitive market segments.
| Leading Market Players |
|---|
| Klöckner Pentaplast Group |
| Uflex Ltd. |
| Amcor plc |
| Mitsubishi Chemical Holdings Corporation |
| Tekni-Plex, Inc. |
| Berry Global Inc. |
| Constantia Flexibles Group GmbH |
| Toray Industries, Inc. |
| DuPont de Nemours, Inc. |
| Others |
Value Network & Pricing Analysis
Eighteen-month qualification cycles for novel coextruded structures concentrate pricing power among accredited manufacturers while locking out commodity converters. This lead-time asymmetry stratifies the market into specification-locked premium tiers and price-competitive standard tiers, with German and United States buyers absorbing premiums for validated barrier claims.
Pricing Analysis
Customization-premium spreads of 25-30% separate configured-to-order seven-layer coextrusions from standard PVC-PVDC blister films. Contract-based long-term offtake agreements dominate procurement between pharmaceutical companies and accredited converters, with price differentiation driven by FDA 21 CFR Part 211 certification tier and volume scale. Cost compression in Indian flexible film exports is intensifying because resin price volatility squeezes non-integrated converters. Contract manufacturers serving emerging markets exhibit highest price sensitivity, while biologic drug manufacturers in Switzerland and Massachusetts demonstrate lowest sensitivity due to stability-critical formulation requirements.
Supply Chain Analysis
Germany, Japan, and the United States anchor seven-layer coextrusion equipment manufacturing and specialized film production. Raw material dependencies draw from ethylene-vinyl alcohol resins, cyclic olefin copolymers, and surface-modified clay platelets for nanocomposite barriers. Single-source vulnerability concentrates in specialized extrusion line operators requiring capital commitments exceeding fifty million dollars. Distribution runs through direct procurement relationships between pharmaceutical companies and accredited film converters, bypassing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated barrier-performance documentation capabilities sit with fewer than twenty accredited manufacturers globally, creating specification lock-in that rewards incumbents and raises entry barriers for aspirants. This scarcity dynamic favors asset-heavy specialists with polymer science depth over capital-light commodity converters.
For Market Incumbents: Consolidate multi-site manufacturing footprints to satisfy FDA 21 CFR Part 211 validation requirements across all production locations. Deepen backward integration into EVOH and COC resin supply to defend margin position against olefin feedstock volatility. Aluminum foil substitution by metallized polymer films threatens legacy laminate revenue streams. For New Entrants and Emerging Players: FDA fast-track pathways for extractables-leachables testing offer penetration routes into parenteral flexible film segments where validation backlogs delay incumbent commercialization. White-space concentrates in recycled-content primary packaging for USP <661> compliance, and in temperature-monitored pouches for direct-to-pharmacy e-commerce channels. A go-to-market angle anchored in sustainability credentials and rPET supply chain validation captures emerging specification shifts. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underperforming pharmaceutical film divisions lacking serialization compliance infrastructure. Long-term viability hinges on EU MDR and FDA mandate adherence across the next decade. Acquisition archetypes include mid-cap converters with dormant seven-layer coextrusion assets and incomplete regulatory accreditation. The signal to watch is evolving USP standards for pharmaceutical-grade recycled polymers, which will revalue rPET-capable manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Seal-Strength Testing Infrastructure | EU MDR Annex I mandates validated seal integrity data across temperature ranges for sterile barrier systems. |
| Backward Integration into EVOH Resin Supply | Captive ethylene-vinyl alcohol production insulates margin compression from olefin feedstock price swings. |
| Recycled-Content rPET Supply Chain Validation | Evolving USP <661> standards for pharmaceutical-grade recycled polymers create first-mover positioning. |
| Multi-Site FDA 21 CFR Part 211 Validation | Validated manufacturing across all production locations satisfies serialization mandate compliance requirements. |
| Nanocomposite Barrier Layer Qualification | Surface-modified clay platelets miniaturize oxygen transmission rates below 0.1 cc per square meter per day. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical packaging procurement managers, regulatory affairs directors, polymer R&D scientists, and hospital GPO contracts specialists and refined through secondary validation. Sources included FDA 21 CFR filings, EU MDR technical documentation databases, USP pharmacopeial standards, and customs trade records for resin and film movements. Bottom-up capacity assessments and top-down demand modeling were triangulated to cross-validate volume estimates.
Variance decomposition across product type, material grade, dosage form chemistry, end-user procurement channel, and regional regulatory cluster informed the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate distributions weighted by current value shares. Industry-specific forecast inputs incorporated biologics cold-chain expansion trajectories and serialization mandate implementation timelines.
Underlying assumptions cover sustained EU MDR and FDA enforcement intensity, stable olefin feedstock pricing bands, and incremental USP recycled-content standard adoption, with deviation risk concentrated in resin cost volatility and qualification timeline extensions. Recalibration cycles align with material shifts in pharmacopeial standards and major regulatory guidance updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical 3PL Market
Pharmaceutical Packaging
Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Pharmaceutical Packaging Equipment Market
Pharmaceutical Packaging
Recycled Prescription Bag Market
Pharmaceutical Packaging
Dispensing Pharmacy Packaging Machine Market
Pharmaceutical Packaging
Vaccine Vial Rubber Stopper Market
Pharmaceutical Packaging
Middle East and Africa Ampoules Packaging Market
Pharmaceutical Packaging
Anti-Counterfeit Pharmaceutical Packaging Market
Pharmaceutical Packaging
North America Ampoules Packaging Market
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Nasal Spray Packaging Market
Pharmaceutical Packaging
Pharmaceutical Container Market
Pharmaceutical Packaging
Latin America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Medical Flexible Packaging Market
Pharmaceutical Packaging
APAC Pharmaceutical Packaging Market