
 Smart Pharmaceutical Packaging Market | 2026-2036
Smart Pharmaceutical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pharmaceutical Packaging Market Insights
Project finance for cold-chain infrastructure is reshaping competitive entry in smart pharmaceutical packaging. Amcor plc leverages polymer expertise to sustain RFID-integrated bottle programs across multiple continents. Gerresheimer AG anchors sensor-embedded glass vial production through captive manufacturing in Central Europe. West Pharmaceutical Services, Inc. differentiates via elastomer-digital combinations for injectable delivery systems.
Smart pharmaceutical packaging integrates electronic identifiers, environmental sensors, and communication modules into primary and secondary drug containers to monitor integrity, authenticate products, and capture patient-behavior data. Temperature sensors embedded in blister packs record cumulative thermal exposure through calibrated dye-migration or semiconductor architectures, enabling release decisions for biologics subject to strict cold-chain thresholds. NFC devices and RFID tags command the highest value pools within product type segments due to unit-level traceability mandates from hospital networks and pharmaceutical companies. QR codes occupy the broadest deployment base among applications for medication adherence programs, particularly in retail pharmacy chains seeking low-cost patient-engagement tools.
FDA serialization requirements under the Drug Supply Chain Security Act and EMA's evolving track-and-trace standards under the Falsified Medicines Directive compel pharmaceutical companies to embed machine-readable identifiers at the unit dose level. The EU AI Act and GDPR frameworks additionally constrain how patient-adherence data from NFC-enabled packaging may be collected, stored, and transferred across jurisdictions. Stakeholders must weigh regulatory compliance expenditures against the revenue potential of outcome-based contracting models that smart packaging data enables.
Market Dynamics
Cold-chain serialization mandates from FDA and EMA are compressing upgrade cycles for primary packaging lines. Pharmaceutical manufacturers must retrofit blister lines and vial filling stations with sensor-embedding capabilities before statutory deadlines, reallocating capex from conventional materials to electronic integration.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Unit-level traceability requirements force pharmaceutical companies to deploy machine-readable identifiers across all prescription drug containers, expanding the addressable base for NFC and RFID-integrated packaging.
- Biologics cold-chain expansion:Temperature-sensitive monoclonal antibodies and cell therapies require calibrated thermal monitoring from manufacturing through patient administration, driving sensor-embedded blister and vial adoption.
- Germany's sensor-embedded glass vial cluster:Gerresheimer and Schott AG anchor captive production capacity for injectable therapies, creating regional supply security that accelerates procurement decisions across European biologics manufacturers.
Market Restraints
- Semiconductor input volatility:NFC chips and temperature sensors depend on specialty silicon and rare-earth magnet materials subject to supply concentration in East Asian foundries, creating cost unpredictability for packaging converters.
- GDPR data-transfer friction:Patient adherence data captured by smart packaging faces cross-border storage restrictions that complicate centralized analytics platforms for multinational pharmaceutical companies.
- Legacy filling line incompatibility:Existing high-speed pharmaceutical packaging equipment lacks the mechanical tolerances and electrical interfaces required for sensor embedding, forcing complete line replacement rather than retrofit.
Strategic Opportunities
- India's domestic biologics manufacturing:CDSCO's tightening cold-chain guidelines for biosimilars create first-mover advantage for sensor-embedded packaging suppliers establishing local technical service presence.
- EU AI Act compliance services:Packaging data platforms that pre-certify patient-behavior analytics for algorithmic transparency requirements can capture premium positioning in European hospital network procurement.
- QR-NFC convergence:Hybrid authentication systems combining low-cost printed codes with encrypted short-range communication address both retail pharmacy adherence programs and high-value anti-counterfeiting needs.
Industry Challenges
- Electronics-pharma regulatory dual expertise:Packaging engineers must simultaneously satisfy FDA pharmaceutical quality standards and FCC electromagnetic emission requirements, creating talent scarcity in convergent skill domains.
- Validation timeline compression:Sensor-embedded packaging requires combined pharmaceutical stability testing and electronics reliability certification, extending qualification periods that conflict with drug launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pharmaceutical Packaging Market |
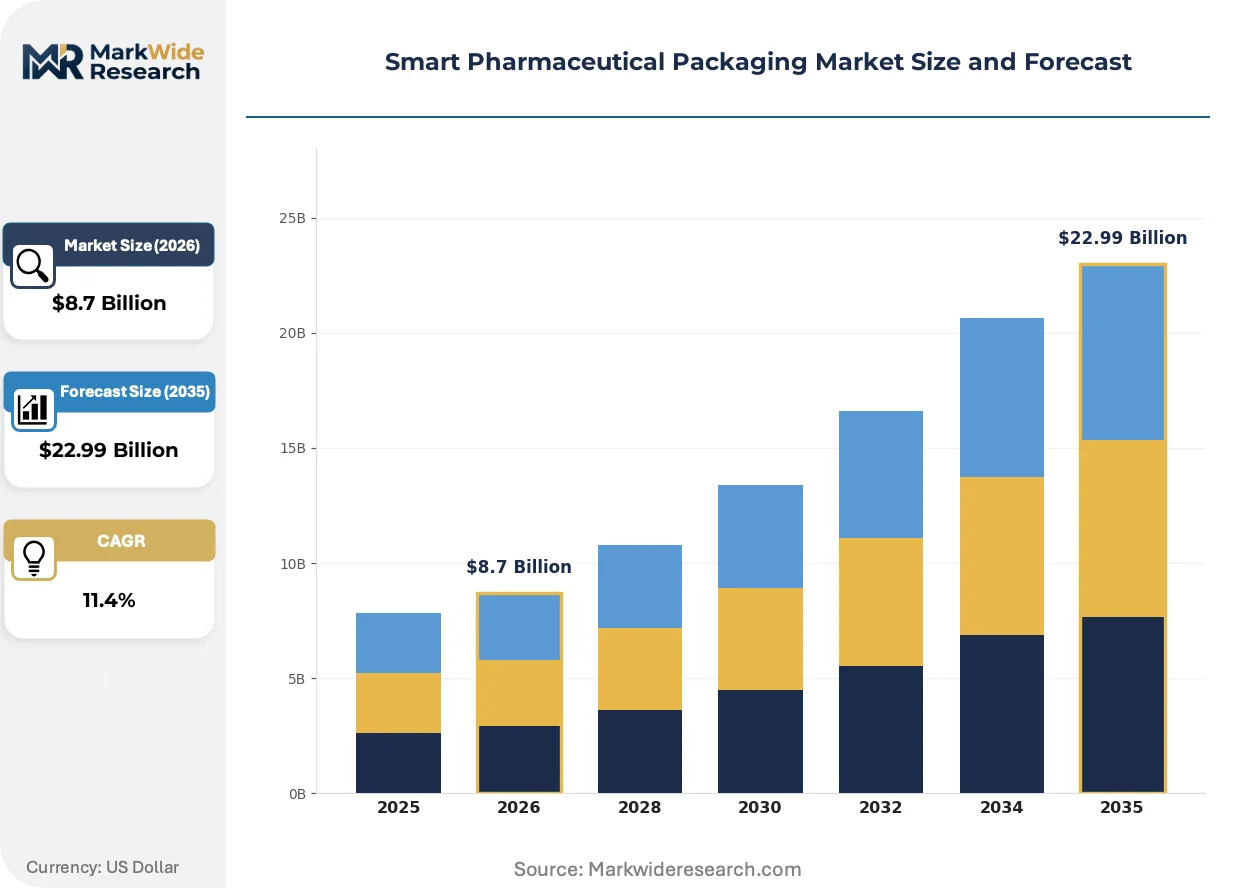
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RFID Tags, Temperature Sensors, NFC Devices, QR Codes End User: Pharmaceutical Companies, Contract Packaging Organizations, Hospitals, Retail Pharmacies Application: Medication Adherence, Supply Chain Management, Counterfeit Protection, Tracking Packaging Type: Bottles, Blister Packs, Sachets, Labels |
| Companies Covered | Amcor plc, Gerresheimer AG, Schott AG, Berry Global, AptarGroup, Inc., West Pharmaceutical Services, Inc., BASF SE, Honeywell International Inc., BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pharmaceutical Packaging Market Trends and Innovations
Printed electronics and miniaturized semiconductor architectures are collapsing the cost curve for unit-level intelligence. Packaging converters now embed functional circuitry directly onto flexible substrates, eliminating discrete component assembly and enabling form factors previously incompatible with high-speed pharmaceutical production.
Calibrated dye-migration temperature sensors are hybridizing with semiconductor architectures to create dual-mode thermal monitoring. Biologics manufacturers in Germany and Switzerland adopt these hybrid systems for international shipments where infrastructure quality varies, enabling release decisions based on cumulative exposure data rather than binary pass-fail thresholds. This hybridization compresses the price-performance gap between premium semiconductor solutions and commodity chemical indicators.
EMA's evolving Falsified Medicines Directive enforcement is mandating real-time verification connectivity for high-risk therapeutic categories. Hospital networks in France and Italy now require authentication systems capable of bidirectional communication with national medicine verification databases, forcing packaging suppliers to integrate cellular or WiFi modules alongside traditional NFC. Oncology and antiviral segments face the steepest compliance ramps.
Pharmaceutical procurement organizations are consolidating vendor relationships around full-stack smart packaging platforms. Large molecule manufacturers in the United States increasingly contract for integrated sensor hardware, cloud analytics, and regulatory documentation from single suppliers, displacing the previous multi-vendor assembly model. This consolidation concentrates purchasing power among three to four national health systems and their designated logistics partners.
Smart Pharmaceutical Packaging Market Segmentation
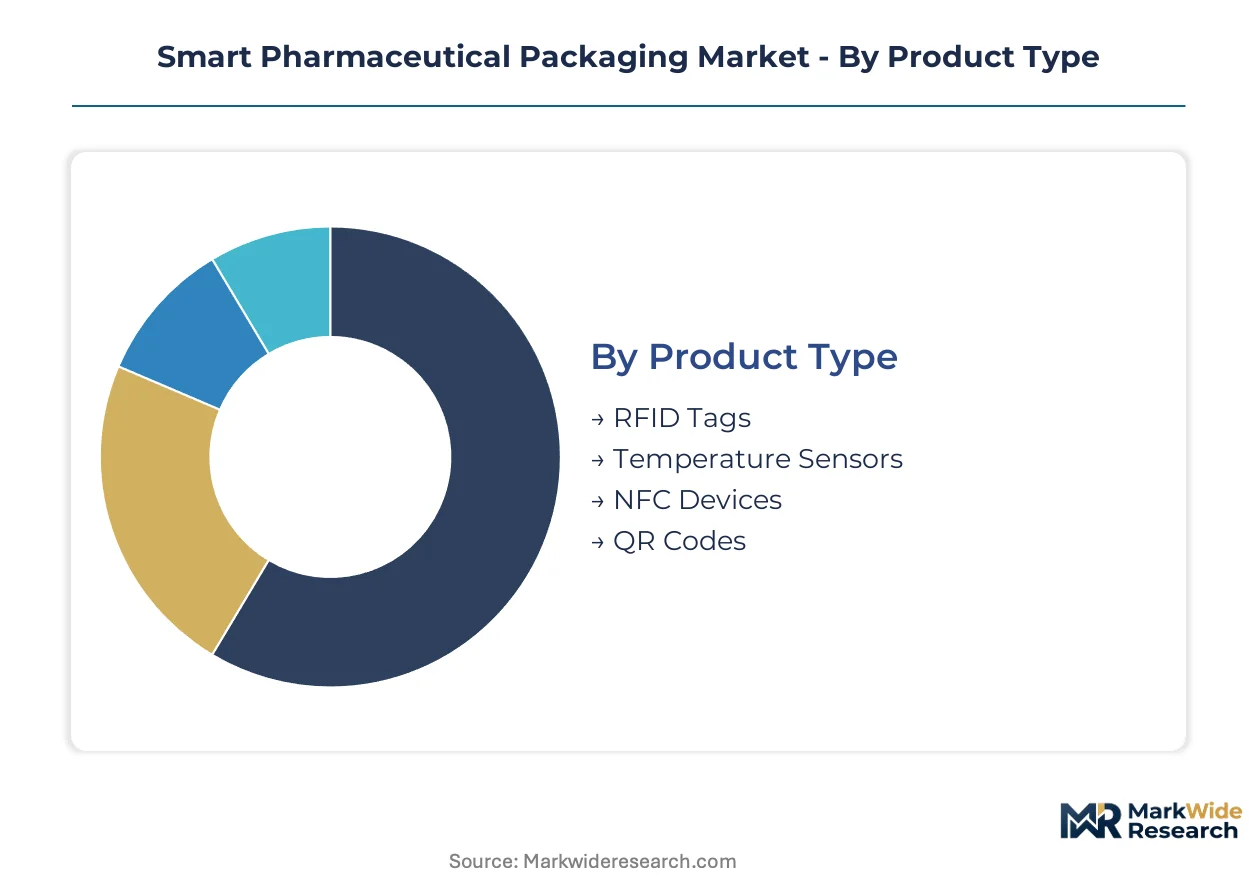
Smart pharmaceutical packaging segments diverge sharply in replacement cadence. RFID and NFC modules refresh every product generation as traceability protocols evolve, while printed QR codes and passive temperature indicators cycle slower. Understanding these velocity differences shapes inventory strategy and R&D allocation for packaging converters.
Product Type:
Cycle times stretch from months for printed codes to years for semiconductor-embedded hardware. RFID tags and NFC devices demand continuous silicon procurement hedging against foundry volatility, while dye-migration sensors and QR codes turn on printing capacity alone.
- RFID Tags:UHF and HF inlays integrate with pharmaceutical serialization systems through antenna-optimized substrates. Hospital networks in the United States mandate RFID-enabled unit-dose verification, compressing procurement cycles for acute-care injectables.
- Temperature Sensors:Calibrated dye-migration strips and semiconductor architectures record cumulative thermal exposure for biologics cold chains. German biologics manufacturers anchor demand for sensor-embedded glass vials as EMA cold-chain mandates tighten.
- NFC Devices:Encrypted near-field communication chips enable bidirectional patient engagement and authentication. France and Italy require real-time verification connectivity for high-risk therapeutic categories.
- QR Codes:Printed matrix codes provide low-cost medication adherence tracking for retail pharmacy chains. India and Brazil deploy QR-based verification for domestic generics under national traceability programs.
QR codes dominate installed base. NFC devices are where expansion concentrates.
End User:
Customer archetypes split between integrated pharmaceutical manufacturers seeking full-stack platforms and outsourced service providers assembling multi-vendor solutions. Hospital procurement centralization versus retail fragmentation creates divergent pricing power dynamics.
- Pharmaceutical Companies:Large molecule manufacturers contract for integrated sensor hardware, cloud analytics, and regulatory documentation from single suppliers. FDA Drug Supply Chain Security Act compliance drives vertical integration of packaging data platforms.
- Contract Packaging Organizations:Third-party converters retrofit legacy filling lines with sensor-embedding capabilities for multiple pharmaceutical clients. CDSCO's tightening cold-chain guidelines for Indian biosimilars accelerate technical service investments.
- Hospitals:Acute-care networks mandate unit-dose traceability for high-value oncology and antiviral therapies. EMA's evolving Falsified Medicines Directive enforcement requires bidirectional database connectivity.
- Retail Pharmacies:Chain drugstores deploy QR-based adherence programs for chronic disease management. Low-cost patient engagement tools prioritize printed codes over semiconductor solutions.
Pharmaceutical companies command premium platform pricing. Contract packaging organizations are gaining share fastest through outsourced compliance services.
Application:
Use-case maturity ranges from established supply chain serialization to emerging outcome-based contracting models. Counterfeit protection and tracking satisfy regulatory mandates, while medication adherence unlocks pharmaceutical revenue through data monetization.
- Medication Adherence:Smart packaging captures dosing behavior for pharmaceutical companies negotiating outcome-based contracts with payers. GDPR frameworks constrain cross-border data transfers for multinational adherence platforms.
- Supply Chain Management:Unit-level traceability from manufacturing through dispensing satisfies FDA and EMA serialization requirements. Cold-chain biologics drive sensor-embedded blister and vial adoption for thermal monitoring.
- Counterfeit Protection:Authentication systems verify legitimate products against falsified medicines entering distribution. EU AI Act compliance services create premium positioning for algorithmically transparent packaging data platforms.
- Tracking:Real-time location monitoring enables inventory optimization and diversion detection. Hybrid QR-NFC systems address both retail pharmacy cost constraints and high-value anti-counterfeiting needs.
Supply chain management holds the largest revenue pool. Medication adherence is climbing the fastest as outcome-based contracting expands.
Packaging Type:
Form factor selection hinges on drug delivery route, dosing frequency, and sensor integration complexity. Injectable therapies favor glass vial sensor embedding, while oral solids accommodate flexible printed electronics on blister lidding.
- Bottles:Polymer containers integrate RFID inlays and NFC modules for solid oral dosage forms. Amcor plc sustains multi-continental RFID-integrated bottle programs through polymer expertise.
- Blister Packs:Thermoformed cavities with sensor-embedded lidding dominate biologics cold-chain monitoring. Temperature-sensing blister packs accelerate procurement among North American and European biologics manufacturers.
- Sachets:Flexible single-dose pouches incorporate printed temperature indicators for tropical market distribution. Cost constraints favor dye-migration sensors over semiconductor architectures.
- Labels:Adhesive-applied smart labels retrofit conventional packaging with traceability and authentication capabilities. West Pharmaceutical Services differentiates via elastomer-digital combinations for injectable delivery systems.
Blister packs command the steepest technology premium. Labels are expanding most quickly as retrofit demand surges among legacy product lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturers in Germany and the United States anchor procurement volumes for sensor-embedded packaging, while contract packaging organizations in India and Brazil expand technical service capabilities for domestic cold-chain compliance.
Germany
Gerresheimer and Schott AG drive sensor-embedded glass vial production for injectable therapies. EMA cold-chain mandates tighten release requirements for temperature-sensitive biologics. The Rhine-Main industrial corridor concentrates captive manufacturing capacity that accelerates procurement decisions across European biologics manufacturers.
United States
Large molecule manufacturers contract for integrated sensor hardware and cloud analytics platforms. FDA Drug Supply Chain Security Act unit-level traceability requirements compress upgrade cycles for primary packaging lines. The Boston-Cambridge biotech cluster demands real-time verification connectivity for high-value oncology therapies.
India
Domestic biosimilars manufacturing expands technical service investments for sensor-embedded packaging. CDSCO tightening cold-chain guidelines create first-mover advantage for suppliers establishing local presence. The Hyderabad-Bengaluru pharmaceutical belt anchors contract packaging organization capacity for multinational biologics firms.
Switzerland
Hybrid dye-migration and semiconductor temperature sensors gain adoption for international shipments with variable infrastructure. Swissmedic enforcement of EMA serialization standards drives authentication system upgrades. The Basel-Lucerne biopharma corridor concentrates demand for calibrated thermal monitoring from manufacturing through patient administration.
France
Hospital networks mandate bidirectional communication with national medicine verification databases for high-risk therapeutic categories. ANSM enforcement of EMA Falsified Medicines Directive requires real-time verification connectivity. The Paris-Saclay healthcare cluster concentrates procurement centralization for oncology and antiviral smart packaging.
Smart Pharmaceutical Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Packaging converters with polymer expertise and glass specialists with sensor integration capabilities occupy distinct strategic positions. Three archetypes dominate: materials-science conglomerates with captive polymer supply, precision glass fabricators with semiconductor embedding competence, and elastomer-digital combination specialists for injectable delivery. Capacity expansion in Central Europe and strategic partnerships for cloud analytics platforms represent the dominant competitive moves.
Within the materials-science tier, Amcor plc exemplifies channel control through multi-continental RFID-integrated programs. Gerresheimer AG and Schott AG occupy positions as precision glass specialists anchoring sensor-embedded vial production in the Rhine-Main corridor. West Pharmaceutical Services, Inc. represents the elastomer-digital combination archetype for injectable delivery systems.
| Leading Market Players |
|---|
| Amcor plc |
| Gerresheimer AG |
| Schott AG |
| Berry Global |
| AptarGroup, Inc. |
| West Pharmaceutical Services, Inc. |
| BASF SE |
| Honeywell International Inc. |
| BD |
| Others |
Pricing and Supply Chain Analysis
Semiconductor input volatility from East Asian foundry concentration determines both tiered pricing spreads across NFC and RFID modules and the geographic shape of converter procurement networks. Packaging suppliers hedge silicon costs through long-term offtake agreements that compress margins on standard-grade sensor-embedded blister packs while preserving premium pricing for validated pharmaceutical-grade hardware.
Pricing Analysis
Cost-plus contracts with silicon indexation dominate procurement between packaging converters and pharmaceutical manufacturers. Pricing stratifies across premium, standard, and economy tiers based on FDA validation status and volume commitment scale. Cost compression in standard-grade temperature sensors is intensifying because dye-migration alternatives displace semiconductor architectures in tropical distribution markets. Retail pharmacy chains exhibit highest price sensitivity, while hospital networks purchasing oncology injectables demonstrate lowest sensitivity due to outcome-based contracting requirements.
Supply Chain Analysis
Export-control regimes limiting specialty silicon and rare-earth magnet flows constrain NFC chip availability for European and North American packaging converters. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, while glass vial sensor-embedding capacity centers in Germany and Switzerland. Raw material dependencies include specialty silicon wafers, rare-earth magnets, and pharmaceutical-grade elastomers. Single-source vulnerability in East Asian foundries creates supply disruption risk. Distribution runs through pharmaceutical contract packaging organizations and direct-to-manufacturer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart pharmaceutical packaging market is entering a cyclical recovery phase driven by FDA Drug Supply Chain Security Act compliance deadlines forcing replacement of legacy filling lines. Pharmaceutical manufacturers must accelerate procurement decisions ahead of statutory traceability mandates.
For Market Incumbents: Harden sensor-embedded glass vial supply positions through captive manufacturing expansion in Central Europe. Semiconductor embedding competence represents a defendable moat against polymer-based competitors. Capacity addition in the Rhine-Main corridor secures regional procurement decisions from EMA-regulated biologics manufacturers. Certification investment in EU AI Act-compliant data platforms captures premium positioning in French and Italian hospital networks.
For New Entrants and Emerging Players: Mid-market contract packaging organizations in India represent the most penetrable entry point for sensor-embedding technical services. CDSCO cold-chain guideline enforcement creates first-mover advantage for suppliers establishing Hyderabad-Bengaluru service presence. QR-NFC hybrid authentication systems for domestic generics offer a lower-capital go-to-market angle than full-stack semiconductor platforms.
For Investors and Strategic Acquirers: EMA Falsified Medicines Directive real-time connectivity requirements reshape the acquisition landscape toward packaging data platforms with pre-certified algorithmic transparency. Five-to-ten year viability favors converters with combined pharmaceutical stability testing and electronics reliability certification capabilities. Target acquisition archetype: elastomer-digital combination specialists for injectable delivery. The signal to watch is hospital network procurement centralization around full-stack platform vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Embedded Glass Vial Capacity Expansion | Gerresheimer and Schott AG anchor Rhine-Main production securing EMA-regulated biologics procurement. |
| EU AI Act Compliance Certification | Pre-certified patient-behavior analytics platforms capture premium positioning in French hospital networks. |
| QR-NFC Hybrid System Development | Low-cost printed codes combined with encrypted communication address retail pharmacy and anti-counterfeiting needs. |
| India Technical Service Localization | CDSCO cold-chain guidelines for biosimilars create first-mover advantage for sensor-embedding suppliers. |
| Cloud Analytics Platform Integration | Single-supplier contracts for hardware, analytics, and documentation displace multi-vendor assembly models. |
Research Methodology
A spread of perspectives from pharmaceutical packaging engineers, regulatory affairs specialists, hospital procurement managers, and biologics manufacturing executives converged on the working assumptions shaping this analysis. Primary interviews combined with secondary validation against FDA Drug Supply Chain Security Act filings, EMA Falsified Medicines Directive enforcement updates, and CDSCO cold-chain guideline releases. Bottom-up and top-down triangulation cross-checked unit-level sensor demand against pharmaceutical production capacity data.
Demand-supply balance framing anchored the forecast framework across the analysis window. Segmentation dimensions modeled include product type, end user archetype, application use case, and packaging form factor, with regional regulatory cluster as an additional pharmaceutical-specific dimension. CAGRs derived from trajectory analysis of historical adoption curves and statutory compliance deadline impacts. Forecast inputs incorporated biologics cold-chain expansion rates and serialization mandate enforcement timelines.
Stress conditions across semiconductor foundry utilization rates, rare-earth magnet export restrictions, and EMA verification connectivity requirement delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and pharmaceutical manufacturer capex allocation priorities. Cross-checking against FDA and EMA compliance deadline adherence rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
North America Pharmaceutical Vials Market
Pharmaceutical Packaging
Pharmaceutical Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Corrugated Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
Single Dose Dispensers Market
Pharmaceutical Packaging
Prescription Pharmacy Bags Market
Pharmaceutical Packaging
Global Temperature Controlled Packaging Solutions for Pharmaceuticals Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Tablets and Capsules Packaging Market
Pharmaceutical Packaging
Medical Flexible Packaging Market
Pharmaceutical Packaging
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market