
 Latin America Pharmaceutical Plastic Bottles Market | 2026-2036
Latin America Pharmaceutical Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Pharmaceutical Plastic Bottles Market Insights
Market Context
Modular packaging configurations that pair tamper-evident closures with graduated dosing inserts is recalibrating how Latin American pharmaceutical buyers evaluate total cost of ownership. Amcor Group GmbH leverages its regional film extrusion network to supply coextruded barrier structures for moisture-sensitive formulations. Gerresheimer AG anchors its position through specialized PET bottle lines serving Brazil's oncology injectables segment. Berry Global Inc. competes on scale, operating multiple blow-molding facilities that convert regional resin supply into standardized hospital-dispensing formats.
Technical Definition and Segment Structure
Latin America pharmaceutical plastic bottles are blow-molded or injection-stretch-blown containers fabricated from PE, PET, PP, or PVC resins, typically ranging from 10ml to 2L capacity, designed to meet USP light transmission and moisture vapor transmission standards for drug stability. These vessels serve as primary packaging for oral solids, liquids, and topical preparations, with functional requirements including chemical inertness, dimensional tolerance for capping automation, and compatibility with child-resistant closure systems. PET bottles dominate value capture due to their clarity, barrier performance, and recyclability profile, while PE bottles sustain volume leadership in cost-sensitive generic oral solid applications. The 100ml-500ml capacity band concentrates margin pools, as this range serves the highest-volume prescription categories across pharmacies and hospital formularies. Multi-dose packaging formats are gaining structural share where chronic disease prevalence drives recurring prescription volumes.
Regulatory Framework and Outlook
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce pharmacopeial packaging standards that mandate extractables testing, stability validation, and traceability labeling for pharmaceutical primary containers. REACH-aligned migration limits and USP Class VI biocompatibility requirements are progressively filtering into Latin American procurement specifications, particularly for export-oriented manufacturers. Stakeholders must monitor how these agencies harmonize with ICH Q3D elemental impurity guidelines, as regulatory convergence will reshape resin qualification protocols and supplier audit burdens across the region.
Market Dynamics
ANVISA's updated stability validation protocols for pharmaceutical packaging are forcing Brazilian converters to requalify resin grades and barrier structures, compressing supplier certification timelines while elevating technical barriers to market entry.
Growth Catalysts
- Chronic disease prevalence:Brazil's diabetes and hypertension patient pools are expanding multi-dose prescription volumes, driving demand for 100ml-500ml child-resistant bottles with graduated dosing features.
- COFEPRIS traceability mandates:Mexico's pharmaceutical regulator now requires serialized labeling on primary containers, accelerating investments in print-capable PET and HDPE blow-molding lines.
- Barrier-grade PET adoption:Oncology injectables manufacturers across São Paulo state are specifying coextruded structures with enhanced moisture vapor transmission resistance for humidity-sensitive formulations.
Market Restraints
- Resin import dependency:Latin American converters rely on imported barrier-grade PET and HDPE pellets, exposing margins to freight cost volatility and currency fluctuation against the US dollar.
- Extractables testing burden:ANVISA's USP-aligned extractables protocols require 12-18 month validation cycles for new resin formulations, freezing formulation flexibility for mid-tier generic manufacturers.
- Glass substitution in high-value segments:Biologics and parenteral formulations in Colombia's INVIMA-regulated hospital channels retain glass vial preference due to perceived inertness and established cold-chain compatibility.
Strategic Opportunities
- Colombia's Andean corridor:INVIMA's harmonization with ICH Q3D guidelines is opening qualification pathways for barrier-grade suppliers previously locked out by divergent national standards.
- Hospital-dispensing automation:Robotic pharmacy systems in Mexico City's public health networks are specifying dimensional-tolerant bottles with machine-readable base coding, creating premium positioning for precision blow-molders.
- Post-consumer recycled content:ANVISA's draft circular on pharmaceutical packaging sustainability is signaling future rPET acceptance, rewarding early movers with validated food-grade recycling streams.
Industry Challenges
- Validation chemist scarcity:Brazil's extractables and leachables testing capacity concentrates in São Paulo and Rio de Janeiro, creating 6-9 month queue times for regional converters seeking ANVISA approval.
- Legacy capping line incompatibility:Child-resistant closure torque specifications vary across ANVISA, COFEPRIS, and INVIMA protocols, forcing converters to maintain multiple neck finish inventories or retool frequently.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Pharmaceutical Plastic Bottles Market |
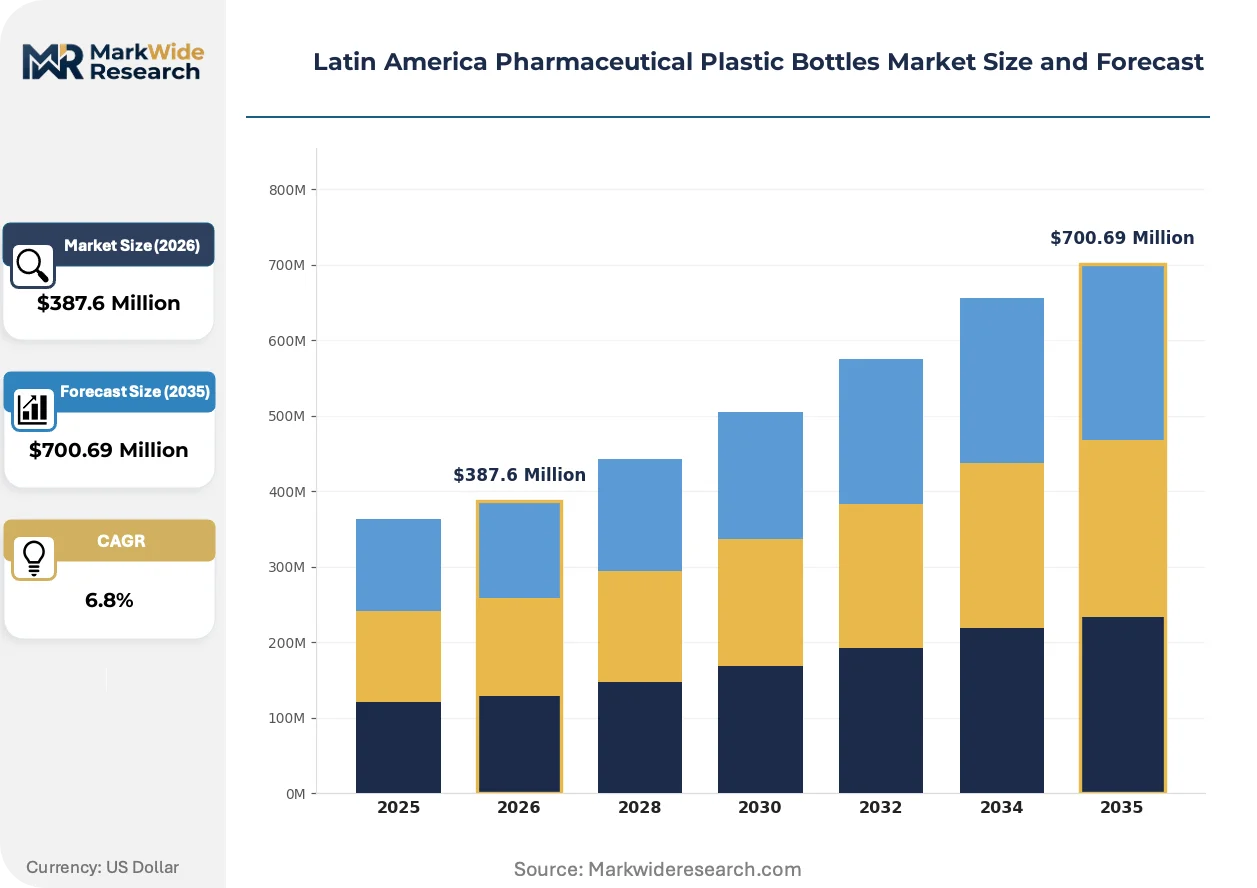
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PE Bottles, PET Bottles, PP Bottles, PVC Bottles End User: Pharmacies, Hospitals, Clinics, Research Labs Capacity: Below 100ml, 100ml-500ml, 500ml-1L, Above 1L Packaging Type: Single-use, Multi-dose, Child-resistant, Tamper-evident |
| Companies Covered | Amcor Group GmbH, Gerresheimer AG, Berry Global Inc., AptarGroup, Inc., ALPLA Werke Alwin Lehner GmbH & Co KG, Greiner Packaging International GmbH, Silgan Holdings Inc., Pretium Packaging, Bormioli Pharma S.p.a., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Pharmaceutical Plastic Bottles Market Trends and Innovations
Multi-layer coextrusion technology is redefining barrier performance expectations across Latin American pharmaceutical packaging, while regulatory convergence and automation-ready formats are reshaping buyer-specification priorities.
Coextruded PET structures with ethylene vinyl alcohol interlayers are consolidating moisture-sensitive oral solid applications previously served by desiccant-stoppered HDPE. Brazilian oncology and hormone therapy manufacturers are specifying these formats for 24-month shelf-life claims. The technology is consolidating supplier tiers by eliminating converters lacking film extrusion partnerships or in-house multilayer capability.
ANVISA's alignment with ICH Q3D elemental impurity guidelines is compelling resin suppliers to document raw material provenance and heavy metal testing protocols. This regulatory convergence is elevating audit burdens for Asian resin importers while creating qualification advantages for regional producers with traceable supply chains. Brazilian generic manufacturers are responding by consolidating supplier panels around converters with validated USP Class VI documentation.
Pharmacy chains across Mexico are consolidating procurement through centralized distribution centers, displacing direct-to-manufacturer purchasing by individual retail outlets. This channel concentration is elevating volume-scale requirements and favoring converters with multi-site blow-molding footprints capable of consistent national supply. The shift is most visible in Mexico City's metropolitan pharmacy networks, where Grupo Casa Saba and Fármacos Similares are standardizing bottle specifications across their dispensing operations.
Latin America Pharmaceutical Plastic Bottles Market Segmentation
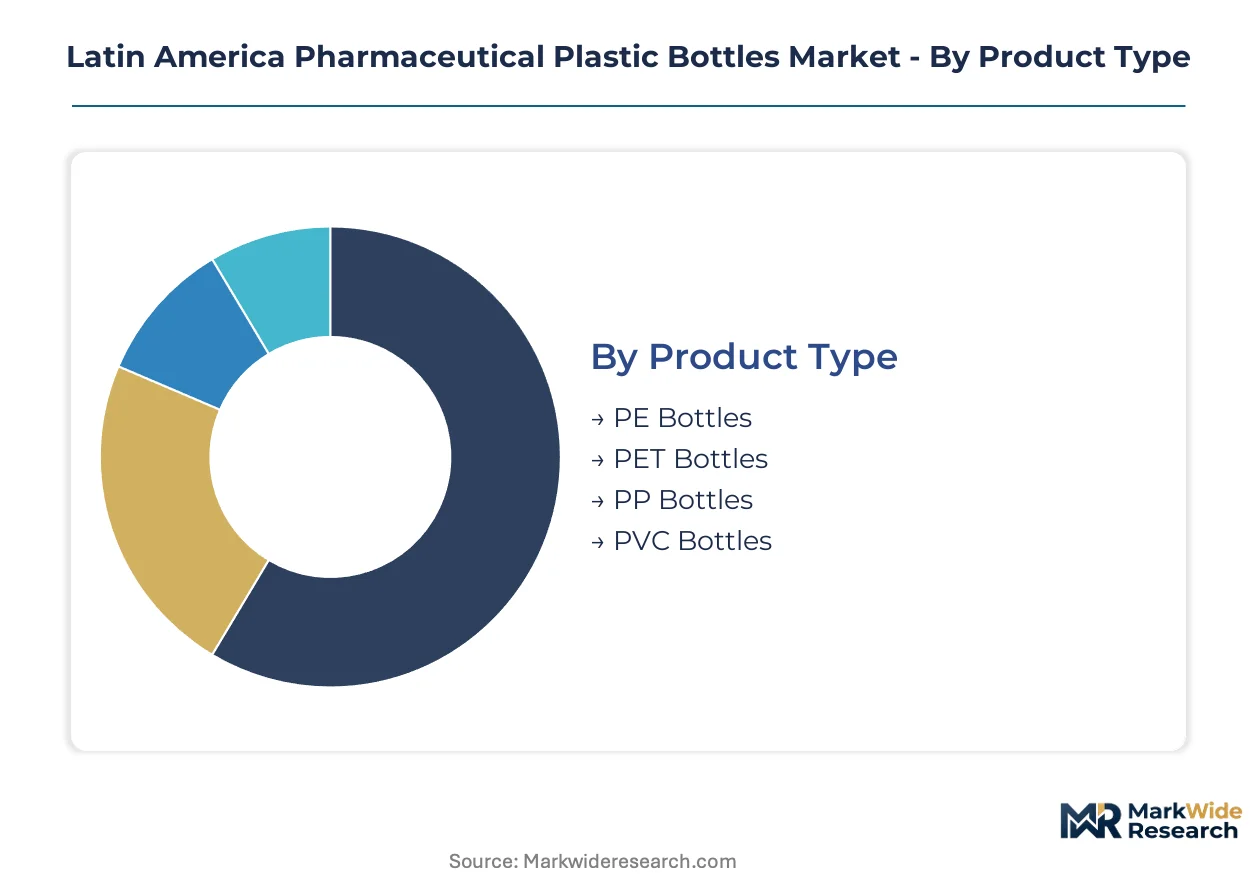
Segmentation in Latin American pharmaceutical plastic bottles reflects divergent technical requirements across resin chemistries, dispensing channels, and regulatory compliance tiers. Understanding these divisions clarifies where capital deployment yields margin protection versus volume capture.
Product Type:
Resin upgrade cycles are accelerating as ANVISA's stability protocols force requalification of legacy formulations, creating displacement windows for barrier-grade alternatives.
- PET Bottles:Injection-stretch-blown construction delivers USP-compliant light transmission limits and moisture vapor barriers. São Paulo's oncology injectables manufacturers specify coextruded PET structures for humidity-sensitive biologics, driving premium placement in hospital formularies.
- PE Bottles:Extrusion-blown HDPE and LDPE formats dominate cost-sensitive generic oral solid applications. Brazilian pharmacy chains in Minas Gerais and Rio de Janeiro states prioritize PE for high-volume chronic disease prescriptions where barrier demands remain moderate.
- PP Bottles:Polypropylene offers thermal stability for formulations requiring autoclave sterilization compatibility.
- PVC Bottles:Limited to specific topical and liquid applications where plastizer migration risks are managed through formulation controls.
Volume placements concentrate in PE Bottles; the faster expansion belongs to PET Bottles.
End User:
Channel concentration across Latin American healthcare systems is elevating procurement scale requirements and standardizing specification protocols.
- Pharmacies:Retail dispensing networks across Mexico City's metropolitan corridor are consolidating purchasing through centralized distribution centers. Fármacos Similares and Grupo Casa Saba operations specify machine-readable base coding and child-resistant closures for automated inventory management.
- Hospitals:Public health networks in São Paulo state deploy robotic pharmacy systems requiring dimensional-tolerant bottles with precise neck finish specifications. Oncology and parenteral formulation demands here sustain premium pricing for barrier-validated containers.
- Clinics:Outpatient facilities in Colombia's Andean corridor generate recurring demand for mid-capacity multi-dose formats serving chronic disease management.
- Research Labs:Clinical trial material packaging requires extractables documentation and USP Class VI biocompatibility certification.
Procurement scale tilts toward Pharmacies; technical specification intensity peaks in Hospitals.
Capacity:
Prescription volume patterns and dosing regimens dictate capacity preferences across acute versus chronic therapy categories.
- 100ml-500ml:The dominant capacity band serves Brazil's expanding diabetes and hypertension patient pools with 30-90 day multi-dose supplies. Graduated dosing inserts and child-resistant closures concentrate procurement value in this range.
- Below 100ml:Unit-dose and short-course antibiotic applications favor smaller formats. Mexican generic manufacturers specify these for COFEPRIS-traceable serialized labeling on primary containers.
- 500ml-1L:Hospital bulk dispensing and topical preparation volumes sustain regional converter specialization.
- Above 1L:Limited to institutional pharmacy compounding and veterinary pharmaceutical applications.
Margin pools concentrate in 100ml-500ml; the steepest expansion trajectory belongs to Below 100ml.
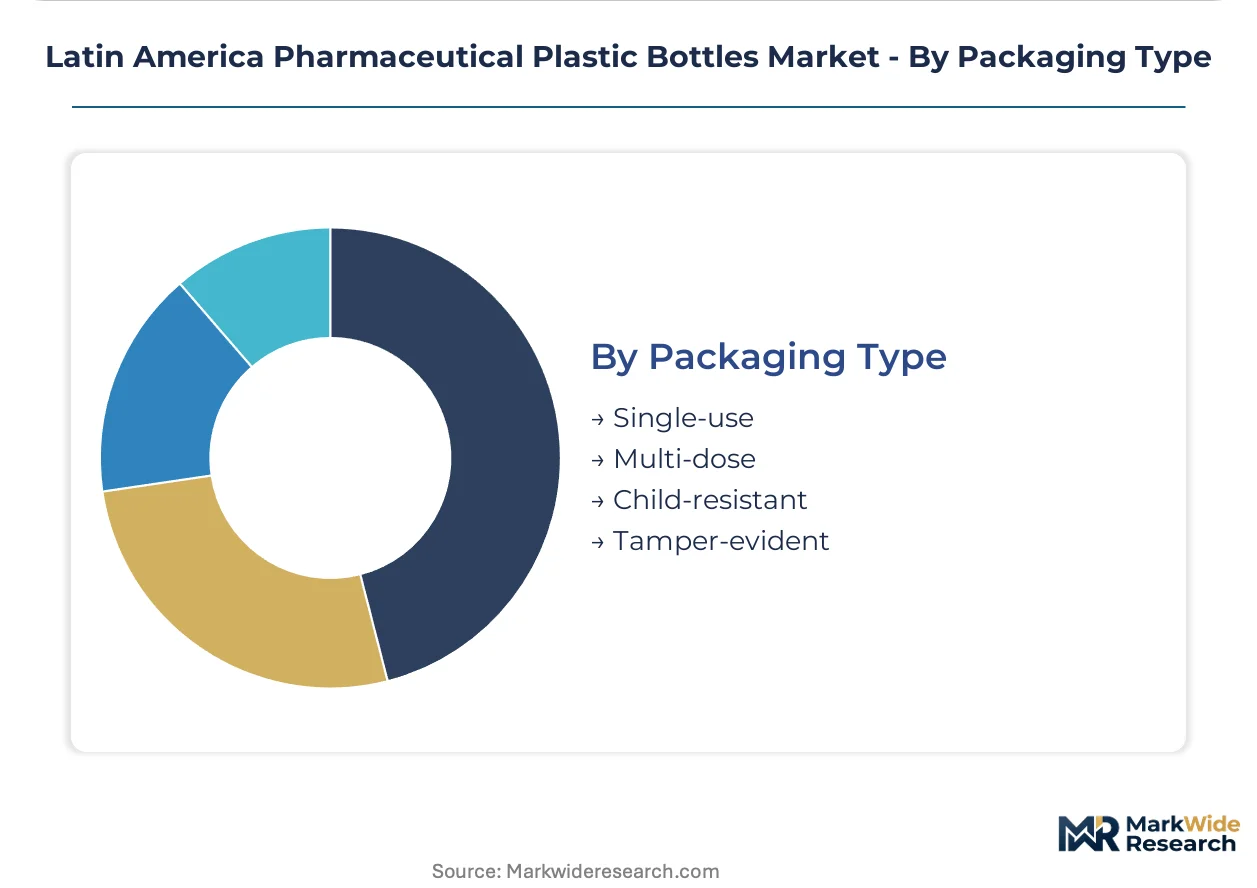
Packaging Type:
Regulatory mandates and patient safety protocols are elevating functional complexity requirements beyond basic containment.
- Multi-dose:Chronic disease prevalence across Latin America is expanding demand for containers with graduated dosing features and extended shelf-life validation. Brazilian converters pair these with desiccant-integrated closures for moisture-sensitive formulations.
- Child-resistant:ANVISA and COFEPRIS protocols mandate CR certification for oral solid dosages in household settings. Torque specification variations across national regulators force inventory complexity for regional suppliers.
- Tamper-evident:Break-ring and shrink-band closures satisfy integrity verification requirements for over-the-counter distribution.
- Single-use:Unit-dose formats serve clinical trial materials and hospital-controlled substance dispensing with full traceability.
Adoption velocity favors Multi-dose; regulatory compliance burden concentrates in Child-resistant.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Latin American pharmaceutical plastic bottle production concentrates in Brazil and Mexico, while demand spreads across Andean and Southern Cone markets that rely on imported barrier-grade resins and regional converter networks.
Brazil
São Paulo state's pharmaceutical manufacturing corridor generates concentrated demand for oncology injectables packaging and multi-dose oral solid containers. ANVISA's updated stability validation protocols compel converters to requalify PET and HDPE resin grades, extending supplier certification timelines. The Greater São Paulo industrial belt hosts the region's densest cluster of blow-molding facilities serving domestic pharma production.
Mexico
Chronic disease patient pools in Mexico City and Guadalajara metro areas expand procurement of child-resistant bottles with graduated dosing features. COFEPRIS traceability mandates now require serialized labeling on primary containers, accelerating investments in print-capable blow-molding lines. The Bajío Region's pharmaceutical manufacturing parks feed distribution networks across Central America.
Colombia
INVIMA's harmonization with ICH Q3D elemental impurity guidelines opens qualification pathways for barrier-grade suppliers previously excluded by divergent national standards. The Andean corridor's outpatient clinics generate recurring demand for mid-capacity multi-dose formats. Bogotá's pharmaceutical distribution hub concentrates procurement decision-making for regional hospital networks.
Chile
Public health system consolidation in Santiago drives standardization of hospital-dispensing bottle specifications across centralized pharmacy operations. The country's national pharmaceutical regulator enforces USP-aligned extractables testing that elevates technical barriers for imported containers. Valparaíso's port infrastructure supports resin import flows serving domestic converter operations.
Argentina
Currency volatility and import restrictions constrain access to barrier-grade PET pellets, forcing generic manufacturers toward locally sourced HDPE alternatives. Buenos Aires province maintains the country's primary pharmaceutical packaging converter base. The national pharmaceutical regulator's stability requirements lag regional harmonization trends, preserving formulation flexibility for domestic producers.
Latin America Pharmaceutical Plastic Bottles Market Competitive Landscape
The competitive structure tilts toward multinational packaging conglomerates with integrated film extrusion and blow-molding capabilities. Regional specialists occupy mid-tier positions serving generic manufacturers with standardized formats. Three archetypes dominate: integrated resin-to-container converters, specialized barrier-grade suppliers, and scale-driven hospital-dispensing producers. Capacity expansion and strategic partnerships with pharmaceutical manufacturers constitute the primary competitive moves reshaping supplier relationships.
Within the integrated converter tier, Amcor Group GmbH and Gerresheimer AG occupy positions exemplifying multinational scale advantages. Amcor leverages regional film extrusion networks to supply coextruded barrier structures, while Gerresheimer anchors specialized PET bottle lines. Berry Global Inc. represents the scale-driven archetype, operating multiple blow-molding facilities that convert regional resin supply into standardized formats. These three companies collectively illustrate how technical validation capabilities and geographic footprint determine competitive positioning across ANVISA, COFEPRIS, and INVIMA regulatory environments.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Gerresheimer AG |
| Berry Global Inc. |
| AptarGroup, Inc. |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Greiner Packaging International GmbH |
| Silgan Holdings Inc. |
| Pretium Packaging |
| Bormioli Pharma S.p.a. |
| Others |
Pricing and Supply Chain Analysis
Platts PET resin price assessments cascade through Latin American pharmaceutical packaging supply chains, compressing converter margins when US dollar-denominated feedstock costs spike against local currencies. Brazilian blow-molders absorb volatility through contract-based long-term offtake agreements with multinational resin suppliers, while Mexican converters hedge exposure via regional HDPE sourcing from Pemex petrochemical streams.
Pricing Analysis
Margin tightening in barrier-grade PET reflects ANVISA's requalification mandates and 12-18 month extractables validation timelines. Three-tier pricing structure across premium, standard, and economy levels separates coextruded oncology formats from commodity HDPE generics. Cost-down pressure on standard-grade PE accelerates because pharmacy chains consolidate procurement through centralized distribution. Generic manufacturers in Minas Gerais exhibit highest price sensitivity; São Paulo oncology injectables buyers prioritize barrier validation over unit cost.
Supply Chain Analysis
Direct-to-pharma channels handle hospital formulary demand, while distributor networks serve retail pharmacy chains across Brazil and Mexico. Resin supply concentrates in the US Gulf Coast, South Korea, and Saudi Arabia. Raw material dependencies include barrier-grade PET pellets, HDPE virgin resin, and ethylene vinyl alcohol copolymers for coextrusion. Logistics chokepoints at Santos and Veracruz ports create inventory vulnerability. Distribution runs through São Paulo-based converter clusters feeding domestic pharma manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extractables testing chemist scarcity in Brazil props pricing for validated suppliers, creating supply-constrained conditions that favor incumbents with certification capacity.
For Market Incumbents: Anchor market position through backward integration into film extrusion partnerships that secure coextruded barrier structures. Defend against Asian resin importers by accelerating USP Class VI documentation and ANVISA pre-approval. Prioritize capacity addition in São Paulo's pharmaceutical corridor to capture oncology injectables demand. For New Entrants and Emerging Players: Mid-tier generic manufacturers in Colombia's Andean corridor represent an underserved buyer archetype seeking ICH Q3D-aligned suppliers previously excluded by divergent standards. Target INVIMA qualification pathways opening post-harmonization. Pursue white-label manufacturing partnerships with Brazilian distributors lacking in-house blow-molding. For Investors and Strategic Acquirers: The window for entry favors converters with validated multilayer coextrusion capability and traceable resin supply chains. Long-term viability hinges on sustainability positioning as ANVISA signals rPET acceptance. Monitor draft circular progression as inflection indicator for recycled content premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Multilayer Coextrusion Capability Investment | Enables moisture-sensitive oncology packaging for 24-month shelf-life claims in São Paulo. |
| USP Class VI Certification Acceleration | Reduces ANVISA approval queue times and displaces non-validated Asian resin suppliers. |
| Post-Consumer rPET Validation Program | Positions early movers for ANVISA sustainability circular acceptance and premium pricing. |
| Centralized Distribution Partnership | Captures volume scale from Mexico City pharmacy chain consolidation through Fármacos Similares. |
| Extractables Testing Laboratory Acquisition | Resolves São Paulo validation chemist scarcity and compresses 6-9 month approval timelines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with blow-molding plant managers, pharmaceutical procurement leads at Grupo Casa Saba, ANVISA regulatory affairs specialists, and resin distribution channel partners. Bottom-up volume modeling triangulated against top-down value estimates derived from import-export statistics and converter capacity disclosures.
Segment-level granularity modeled resin chemistry, capacity band, end-user channel, and packaging functional type across the analysis window. CAGRs derived from regression analysis of historical production data and pharmaceutical formulation growth patterns. Forecast inputs incorporated chronic disease prevalence projections and regulatory harmonization timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ANVISA rPET circular finalization, currency volatility against the US dollar, and resin import tariff adjustments. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Middle East and Africa Ampoules Packaging Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Materials Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market