
 Braille Labels Market | 2026-2036
Braille Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Braille Labels Market Outlook
Americans with Disabilities Act Title III enforcement is decoupling compliance costs from facility size, forcing smaller retail and hospitality operators into the Braille Labels Market for the first time. APH, Inc. leverages decades of educational distribution relationships to sustain institutional contract density across North American school systems. LS&S, LLC anchors its position through specialized direct-to-consumer channels serving low-vision households with customized equipment identification solutions.
Braille labels are tactile identification substrates manufactured through embossing, thermal transfer, or screen-printing processes to produce raised-dot patterns readable by touch, typically constructed from vinyl, paper, or metal stocks with permanent or repositionable adhesive backings. Self-adhesive formats dominate volume due to retrofit compatibility with existing packaging and signage infrastructure, while thermal transfer variants capture margin pools in pharmaceutical and medical device applications requiring variable data integration. Facility signage applications lead end-user demand as healthcare systems and transit authorities upgrade wayfinding systems, with product labeling segments expanding fastest in premium consumer goods seeking inclusive design certification.
The FDA's Unique Device Identification rule and EU MDR labeling requirements shape product specifications by mandating human-readable and tactile formats on medical packaging, while Japan's METI accessibility guidelines and JIS standards dictate dot height and spacing tolerances for public infrastructure contracts. The EU Green Deal and REACH chemical restrictions increasingly filter material choices, pushing converters toward bio-based vinyl formulations and recycled paper stocks. Stakeholders must monitor divergence between FDA, EMA, and METI tactile standards when designing single-SKU global packaging programs.
Market Dynamics
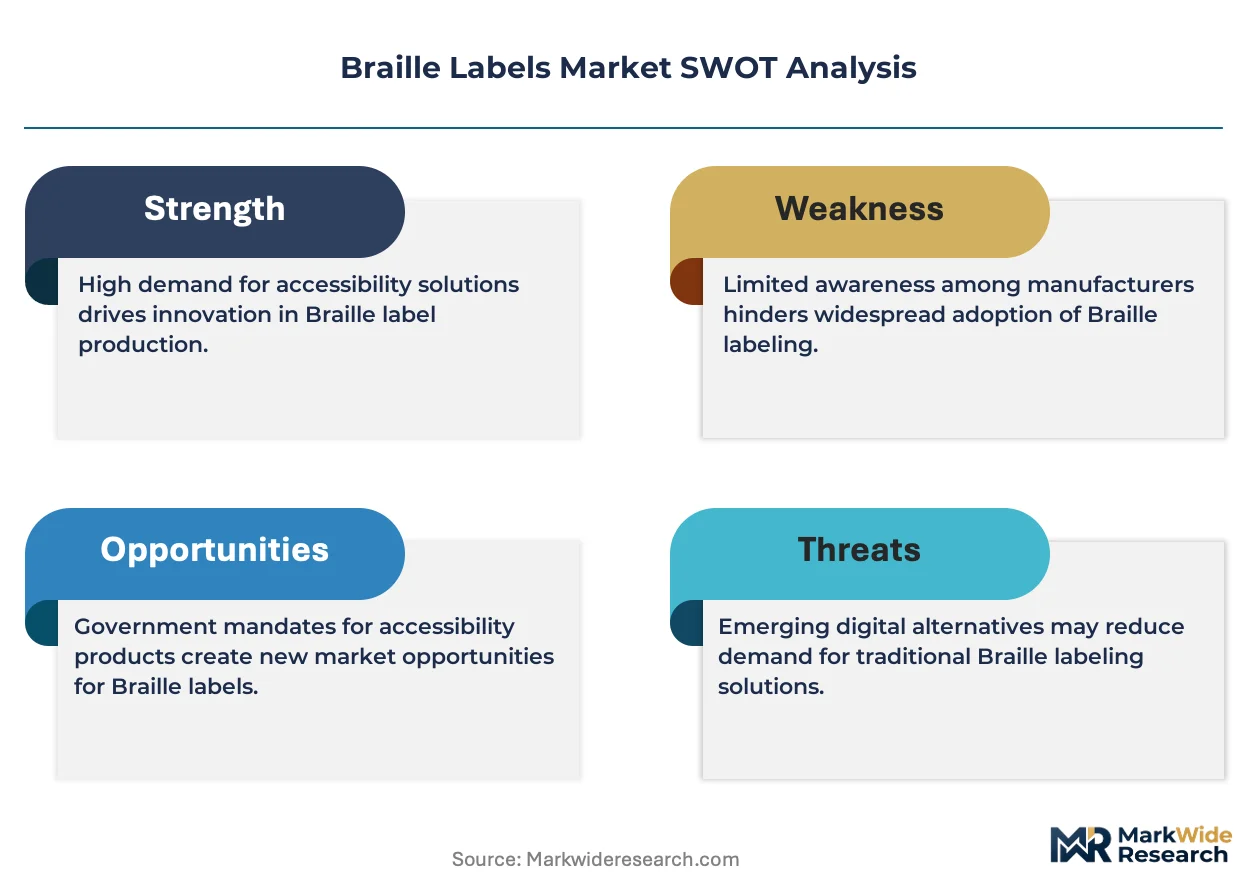
The Braille Labels Market faces a structural compression between accessibility mandates tightening across Germany, Japan, and the United States, and substrate converters racing to qualify bio-based vinyl formulations before REACH chemical restrictions harden. This regulatory-material tension is forcing simultaneous reformulation and certification investments.
Growth Catalysts
- EU MDR tactile packaging mandates:Medical device manufacturers across Germany and France must integrate Braille into primary packaging by compliance deadlines, creating dedicated demand for thermal transfer substrates capable of variable data integration.
- Japan METI transit accessibility standards:Public infrastructure contracts in Tokyo and Osaka now specify JIS-compliant dot height tolerances, pulling specification upgrades across vinyl and metal stock suppliers.
- Self-adhesive retrofit compatibility:Healthcare systems in the United States favor repositionable adhesive formats that upgrade existing wayfinding without full signage replacement, accelerating facility renovation cycles.
Market Restraints
- Petrochemical input volatility:Vinyl resin prices fluctuate with crude oil indices, squeezing converter margins on fixed-price institutional contracts.
- Specialized embossing equipment concentration:Precision dot-height machinery suppliers cluster in Southern Germany and Northern Italy, creating geographic supply risk for converters elsewhere.
- Digital audio navigation substitution:Smartphone-based wayfinding apps displace physical Braille signage in some retail environments, particularly among younger low-vision demographics.
Strategic Opportunities
- India pharmaceutical export packaging:CDSCO alignment with EU MDR tactile requirements creates first-mover advantage for converters certifying dual-compliant substrates for generic drug exporters.
- Convergence of thermal transfer and RFID encoding:Hybrid labels combining tactile readability with supply chain traceability capture premium positioning in medical device logistics.
- Direct-to-consumer equipment identification:Low-vision households seek customized Braille labels for home appliances, opening channel innovation beyond institutional procurement.
Industry Challenges
- Master engraver talent scarcity:Precision dot-pattern die production requires skills concentrated among aging craftspeople in Bavaria and Lombardy, with limited apprenticeship pipeline.
- FDA-EMA-METI standard divergence:Packaging designers face conflicting tactile height, spacing, and durability specifications when attempting single-SKU global programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Braille Labels Market |
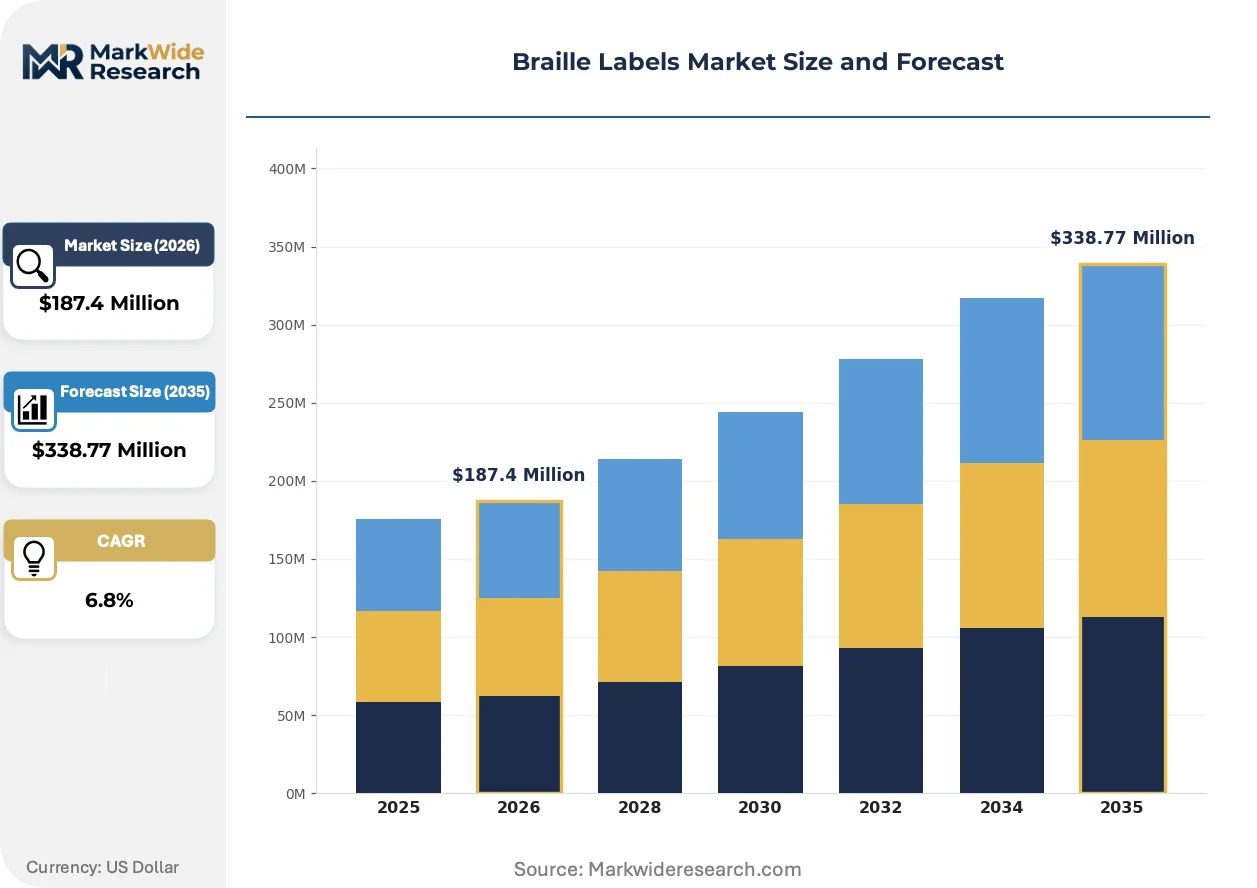
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive, Rigid, Thermal Transfer, Vinyl End User: Retail, Healthcare, Education, Hospitality Material: Plastic, Paper, Metal, Rubber Application: Equipment Identification, Facility Signage, Product Labeling, Packaging |
| Companies Covered | American Thermoform Corporation, APH, Inc., LS&S, LLC, Pia - Accessible Printing Solutions, Rath Microtech, Quantum Technology Pty Ltd, Awards USA, Aspect Labelling Limited, The Braille Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Braille Labels Market Strategic Shifts
Material science advances and regulatory harmonization pressures are actively restructuring how tactile labels are specified, produced, and procured across pharmaceutical, transit, and consumer applications.
Laser-microperforated bio-vinyl substrates are rewriting tactile label durability standards. Transit authorities in Japan and Germany adopt these materials for outdoor signage exposed to temperature cycling and UV degradation. The technology is compressing replacement cycles from five years to eight-plus while satisfying EU Green Deal material sourcing requirements.
REACH chemical restrictions and F-Gas Regulation compliance timelines are forcing substrate reformulation across European converters. Manufacturers must validate alternative plasticizers and adhesive chemistries without compromising dot-height precision or JIS durability standards. Pharmaceutical packaging lines in Germany face the tightest certification windows as MDR enforcement dates approach.
Institutional procurement through specialized accessibility distributors is fragmenting into direct specification by end-user facilities. Hospital systems in the United States and transit authorities in Japan now contract directly with converters for customized wayfinding programs, bypassing traditional educational-equipment intermediaries. This channel compression is most visible in North American healthcare renovations where ADA Title III enforcement has intensified compliance urgency.
Braille Labels Market Segmentation
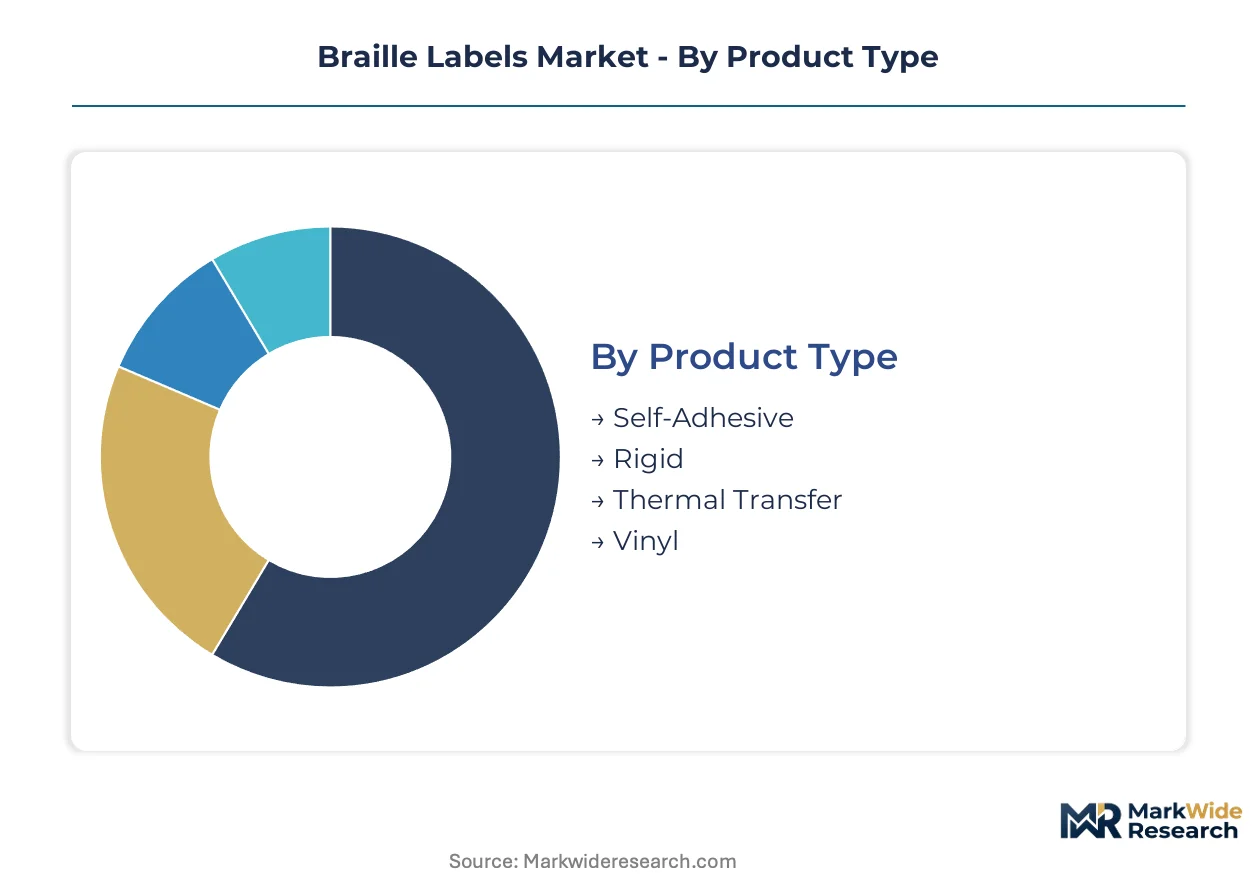
Braille label segmentation reveals distinct procurement patterns across retrofit-compatible formats versus embedded production-line solutions. Material specifications diver sharply between indoor facility applications and outdoor transit infrastructure exposed to environmental stressors.
Product Type:
Self-adhesive formats dominate retrofit installations where facilities upgrade existing signage without structural replacement, while thermal transfer and rigid variants integrate into original manufacturing workflows.
- Self-Adhesive:Pressure-sensitive backing enables rapid deployment onto existing surfaces in retail and hospitality retrofits. Demand concentrates in United States healthcare systems responding to ADA Title III enforcement timelines with minimal facility disruption.
- Thermal Transfer:Variable data integration supports pharmaceutical serialization and medical device UDI compliance. German packaging lines under EU MDR mandates specify these substrates for primary container labeling with lot-level traceability.
- Rigid:Structural substrates suit permanent wayfinding installations in transit infrastructure. JIS-compliant metal and acrylic stocks serve Tokyo Metro platform signage requiring decade-long durability cycles.
- Vinyl:Flexible, weather-resistant material dominates outdoor applications across German transit authorities and Japanese rail networks facing UV degradation and temperature cycling.
Volume placements concentrate in Self-Adhesive; the faster expansion belongs to Thermal Transfer.
End User:
Institutional procurement patterns separate facility-scale renovation contracts from product-integrated manufacturing specifications, with regulatory enforcement intensity varying by sector maturity.
- Healthcare:Hospital systems and pharmaceutical manufacturers drive specification rigor through FDA UDI and EU MDR tactile mandates. German packaging converters face compressed certification windows as enforcement deadlines approach.
- Retail:ADA Title III decoupling of compliance costs from facility size forces smaller operators into first-time tactile label procurement. Repositionable formats enable phased rollout across multi-location chains.
- Education:K-12 and university systems specify durable vinyl for classroom equipment and wayfinding. Institutional contract density sustains specialized distributors serving North American school procurement channels.
- Hospitality:Hotels and restaurants adopt self-adhesive solutions for elevator panels, room directories, and amenity signage. Enforcement visibility in United States litigation patterns accelerates compliance investment among mid-tier operators.
Contract values peak in Healthcare; Hospitality is climbing the fastest as enforcement expands.
Material:
Substrate selection balances tactile precision against environmental exposure, with regulatory chemistry restrictions increasingly filtering formulation choices across European converters.
- Plastic:Vinyl and bio-based polymer formulations dominate volume production. REACH chemical restrictions and F-Gas Regulation timelines force German converters toward alternative plasticizers without compromising dot-height precision.
- Paper:Lower-cost substrate serves indoor educational and retail applications with limited moisture exposure. Recycled content specifications rise under EU Green Deal procurement guidelines.
- Metal:Stainless steel and aluminum stocks serve high-durability transit and industrial equipment marking. JIS durability standards in Japan specify metal substrates for outdoor platform signage.
- Rubber:Elastomeric materials provide impact resistance and tactile compliance for specialized industrial and safety applications. Limited volume concentrates in equipment marking for manufacturing environments.
Procurement tonnage centers on Plastic; Metal gains share fastest in infrastructure upgrade cycles.
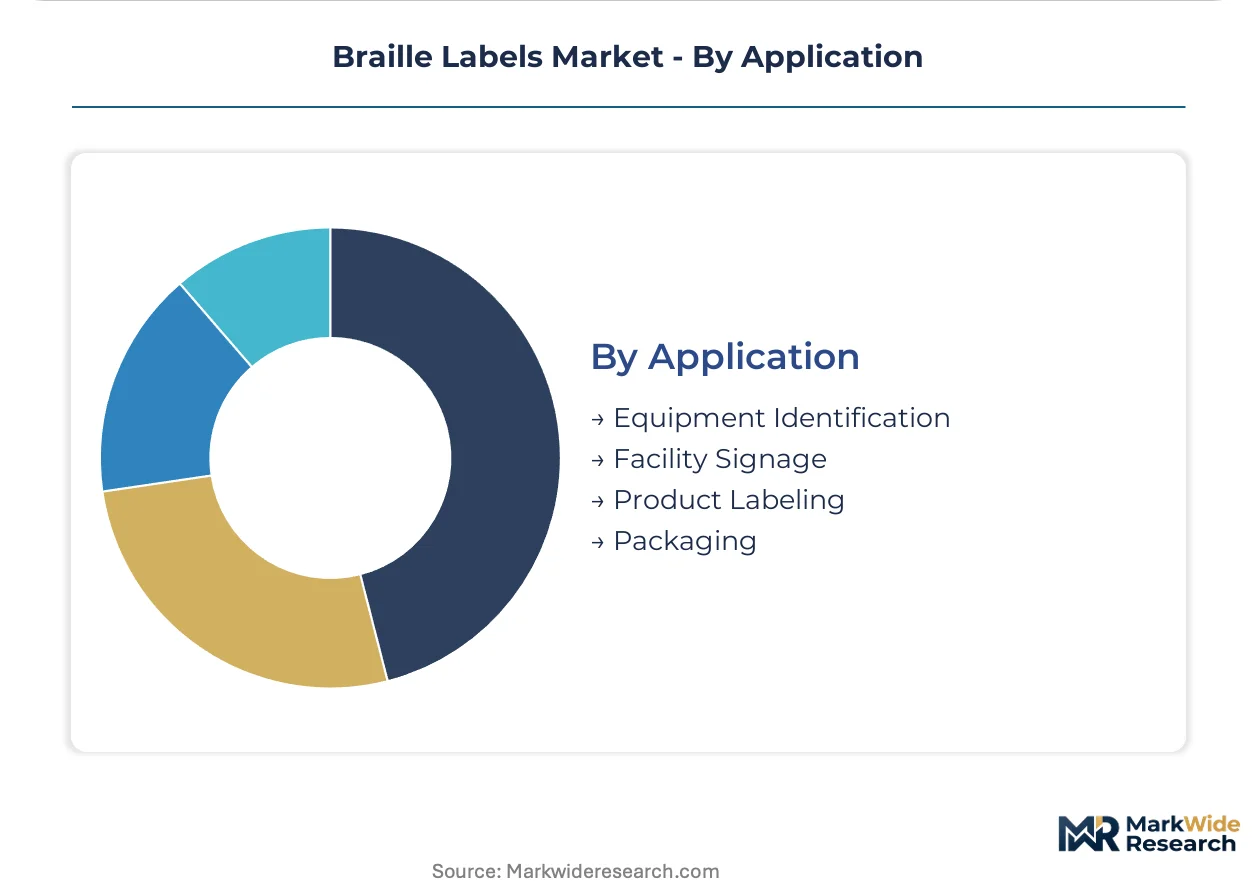
Application:
Deployment context determines specification stringency, with facility-scale wayfinding separating from product-integrated labeling in procurement workflows and compliance frameworks.
- Facility Signage:Wayfinding systems in healthcare and transit infrastructure represent the largest addressable volume. Tokyo Metro and Osaka transit authorities specify JIS-compliant dot geometries for platform and corridor installations.
- Product Labeling:Pharmaceutical and medical device packaging integrates tactile elements under FDA and EMA mandates. German manufacturers face the tightest dual-compliance certification requirements.
- Packaging:Primary and secondary container applications span consumer goods seeking inclusive design certification. Premium cosmetics and food brands adopt tactile elements for brand differentiation.
- Equipment Identification:Direct-to-consumer customization serves low-vision households labeling home appliances. Specialized channels deliver personalized formats beyond institutional procurement patterns.
Installed base concentrates in Facility Signage; Equipment Identification shows the steepest expansion trajectory as consumer channels develop.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Braille labels concentrates in Germany, Japan, and the United States, where regulatory enforcement timelines and infrastructure investment cycles create synchronized procurement waves across pharmaceutical, transit, and facility applications.
United States
ADA Title III enforcement has decoupled compliance costs from facility size, forcing smaller retail and hospitality operators into first-time tactile label procurement. FDA Unique Device Identification rules mandate human-readable and tactile formats on medical packaging. Hospital systems in Texas and Florida favor repositionable adhesive formats for rapid wayfinding upgrades without structural replacement.
Germany
Pharmaceutical packaging lines face compressed certification windows as EU MDR tactile mandates approach enforcement deadlines. REACH chemical restrictions and F-Gas Regulation compliance timelines push converters toward bio-based vinyl formulations. Precision embossing equipment suppliers cluster in Bavaria and Baden-Württemberg, creating geographic supply advantages for regional converters.
Japan
METI accessibility standards for public transit signage drive specification upgrades across vinyl and thermal transfer substrates. JIS-compliant dot height tolerances now govern Tokyo Metro and Osaka platform signage contracts. Transit authorities specify laser-microperforated bio-vinyl substrates for outdoor durability cycles exceeding eight years.
India
CDSCO alignment with EU MDR tactile requirements creates export packaging demand for generic drug manufacturers. Domestic pharmaceutical clusters in Maharashtra and Gujarat seek dual-compliant substrates for European market access. Converters certifying to both CDSCO and EMA specifications capture first-mover positioning in contract negotiations.
United Kingdom
Post-Brexit regulatory divergence complicates single-SKU packaging programs for medical device exporters. NHS procurement guidelines increasingly reference inclusive design standards for facility wayfinding. London transit authorities specify JIS-equivalent dot geometries for Underground platform renovations, pulling material imports from certified European suppliers.
Braille Labels Market Competitive Environment
German and Italian producers anchor the precision embossing equipment tier; North American specialists hold institutional distribution channels. The vendor base separates into substrate converters, specialized accessibility distributors, and direct-to-consumer equipment identification services. Three archetypes dominate: educational-equipment legacy distributors, pharmaceutical packaging specialists, and hybrid tactile-RFID integrators. Competitive moves concentrate on geographic certification expansion and bio-based material qualification ahead of REACH deadlines.
Within the educational-equipment tier, APH, Inc. and LS&S, LLC represent contrasting channel strategies. APH, Inc. occupies a position sustained through decades of institutional contract density across North American school systems. LS&S, LLC exemplifies direct-to-consumer specialization, serving low-vision households with customized formats beyond traditional procurement patterns. American Thermoform Corporation anchors the substrate conversion archetype, with geographic naming suggesting established positioning in thermal transfer and embossing processes.
| Leading Market Players |
|---|
| American Thermoform Corporation |
| APH, Inc. |
| LS&S, LLC |
| Pia - Accessible Printing Solutions |
| Rath Microtech |
| Quantum Technology Pty Ltd |
| Awards USA |
| Aspect Labelling Limited |
| The Braille Works |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between EU MDR-compliant thermal transfer substrates and commodity self-adhesive retrofits manifests in pricing spreads exceeding threefold, with supply chain configurations clustering precision embossing capacity in Southern Germany while repositionable formats source from distributed North American converters. Pharmaceutical packaging lines in Germany absorb premium pricing for variable-data integration, whereas ADA-driven facility retrofits in the United States prioritize cost-minimized vinyl solutions from regional distributors.
Pricing Analysis
Volume placements in self-adhesive retrofits trade at thin margins against fixed-price institutional contracts, while thermal transfer variants capture expanded margins through FDA UDI and EU MDR certification requirements. Price differentiation rests on JIS compliance tier and bio-based vinyl formulation grade. Cost compression in commodity vinyl intensifies because petrochemical input volatility squeezes converter margins. Smaller retail and hospitality operators in the United States exhibit highest price sensitivity; pharmaceutical manufacturers in Germany demonstrate lowest sensitivity due to regulatory non-compliance penalties.
Supply Chain Analysis
Freight cost escalation from Bavarian precision equipment clusters to Asian pharmaceutical packaging hubs is reshaping converter location decisions, with German and Italian producers anchoring master engraver talent while North American distributors control institutional procurement channels. Raw material flows draw from petrochemical complexes in Germany and Japan for vinyl resins, recycled paper stocks from Nordic suppliers, and specialty adhesives from Swiss chemical manufacturers. Single-source vulnerability concentrates in precision dot-height machinery suppliers clustered in Southern Germany. Distribution runs through specialized accessibility distributors and direct-to-consumer channels serving low-vision households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where REACH chemical restrictions and F-Gas Regulation compliance timelines force undercapitalized converters into exit or acquisition, concentrating substrate certification capabilities among scaled players with bio-based formulation pipelines.
For Market Incumbents: Hedge against digital audio navigation substitution by embedding tactile-RFID hybrid capabilities into pharmaceutical packaging lines before EU MDR enforcement deadlines compress. Capture master engraver talent through apprenticeship pipelines in Bavaria and Lombardy to defend precision die production capabilities against aging workforce attrition. Prioritize backward integration into bio-based vinyl resin supply to secure REACH-compliant raw material access ahead of formulation qualification windows. For New Entrants and Emerging Players: Direct-to-consumer equipment identification for low-vision households represents the most penetrable white-space target, with customized home appliance labeling underserved by institutional-focused incumbents. India's CDSCO-aligned pharmaceutical exporters seeking dual EMA-compliant substrates offer geographic entry with lower certification barriers than saturated German packaging lines. Pursue digital-native channel strategies bypassing traditional accessibility distributor networks. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid tactile-RFID integrators given medical device traceability convergence and supply chain digitization mandates. Long-term viability over a five-to-ten-year window favors converters with demonstrated bio-based material qualification and multi-regulatory certification capabilities. Monitor CDSCO-EMA dual-compliance certification velocity as inflection indicator for Indian pharmaceutical export packaging demand.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Vinyl Formulation Qualification | REACH chemical restrictions in Germany force substrate reformulation ahead of F-Gas Regulation deadlines. |
| Hybrid Tactile-RFID Label Development | Medical device manufacturers in Germany and the United States demand combined accessibility and traceability. |
| Master Engraver Apprenticeship Pipeline | Precision dot-pattern die production skills concentrate among aging craftspeople in Bavaria and Lombardy. |
| Direct-to-Consumer Channel Establishment | Low-vision households in the United States seek customized equipment identification beyond institutional procurement. |
| CDSCO-EMA Dual Certification Investment | Indian pharmaceutical exporters in Maharashtra and Gujarat require compliant substrates for European market access. |
Study Parameters
Independent corroboration across converter technical directors, pharmaceutical packaging procurement leads, and transit authority facilities managers underwrites the qualitative findings. Primary interviews with specialized accessibility distributors, biomedical engineers specifying hospital wayfinding systems, and regulatory affairs specialists at medical device manufacturers were combined with secondary validation. Secondary sources include FDA UDI guidance documents, EMA MDR implementation notices, METI accessibility standard filings, and customs trade data on vinyl resin flows. Bottom-up segment sizing and top-down regulatory enforcement timeline analysis were triangulated against procurement contract visibility.
Rate-of-change decomposition across product type, material formulation, end-user sector, and regional regulatory cluster shaped the analytical framework. Segmentation dimensions modeled include self-adhesive versus thermal transfer versus rigid formats, plastic versus paper versus metal substrates, healthcare versus retail versus education versus hospitality end users, and facility signage versus product labeling versus equipment identification applications. CAGRs were derived from enforcement timeline phasing and substrate replacement cycle analysis. Forecast inputs incorporated EU MDR compliance deadline clustering and Japan METI specification upgrade waves.
Revisions become necessary when regulatory enforcement timelines shift, bio-based material qualification failures emerge, or digital audio navigation substitution accelerates beyond projected rates. Forecasts reflect assumptions about certification window completion and substrate converter capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Eco-Friendly Labels Market
Labels
Integrated Labeling System Market
Labels
North America Self-Adhesive Labels Market
Labels
Stretch Sleeve Labels Market
Labels
Oxygen Indicator Labels Market
Labels
Retro-Reflective Labels Market
Labels
Hot Melt Glue Labeler Market
Labels
In-Mold Labeling (IML) Market
Labels
Stand Alone Label Applicator Market
Labels
Holographic Scratch-Off Labels Market
Labels
Stretch Sleeve and Heat Shrink Labels Market
Labels
Shipping Label Market
Labels
Die Cut Labels Market
Labels
Foam Labels Market
Labels
Global QR Code Labels Market
Labels
Primary Packaging Labels Market