
 Global Vaccine Storage and Packaging Market | 2026-2036
Global Vaccine Storage and Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vaccine Storage and Packaging Market Foresight
India's vaccine manufacturing corridor expansion is reshaping regional cold chain infrastructure priorities. Thermo Fisher Scientific leverages its laboratory equipment heritage to dominate active cooling systems for research laboratories. SCHOTT Pharma anchors pharmaceutical glass primary packaging through its polymer syringe and vial specialization. Gerresheimer competes in prefillable polymer syringes for mRNA vaccine formats requiring ultra-low temperature stability.
Vaccine storage and packaging encompasses temperature-controlled containment systems designed to maintain potency across pharmaceutical cold chains from manufacturing through last-mile administration. Thermal shippers employing phase change materials typically maintain payloads between two and eight degrees Celsius for seventy-two to ninety-six hours without external power, while cryogenic systems using liquid nitrogen vapor sustain minus seventy degrees Celsius for cell-based and mRNA formulations. Refrigerators and cold boxes lead product type revenue due to healthcare facility procurement scale, though solar-powered units represent the fastest-growing technology segment as decentralized immunization programs expand beyond grid-connected regions. Passive cooling occupies the largest technology share given its reliability in resource-limited settings, while active cooling commands premium margins in clinical trials and blood bank storage applications requiring precise temperature logging.
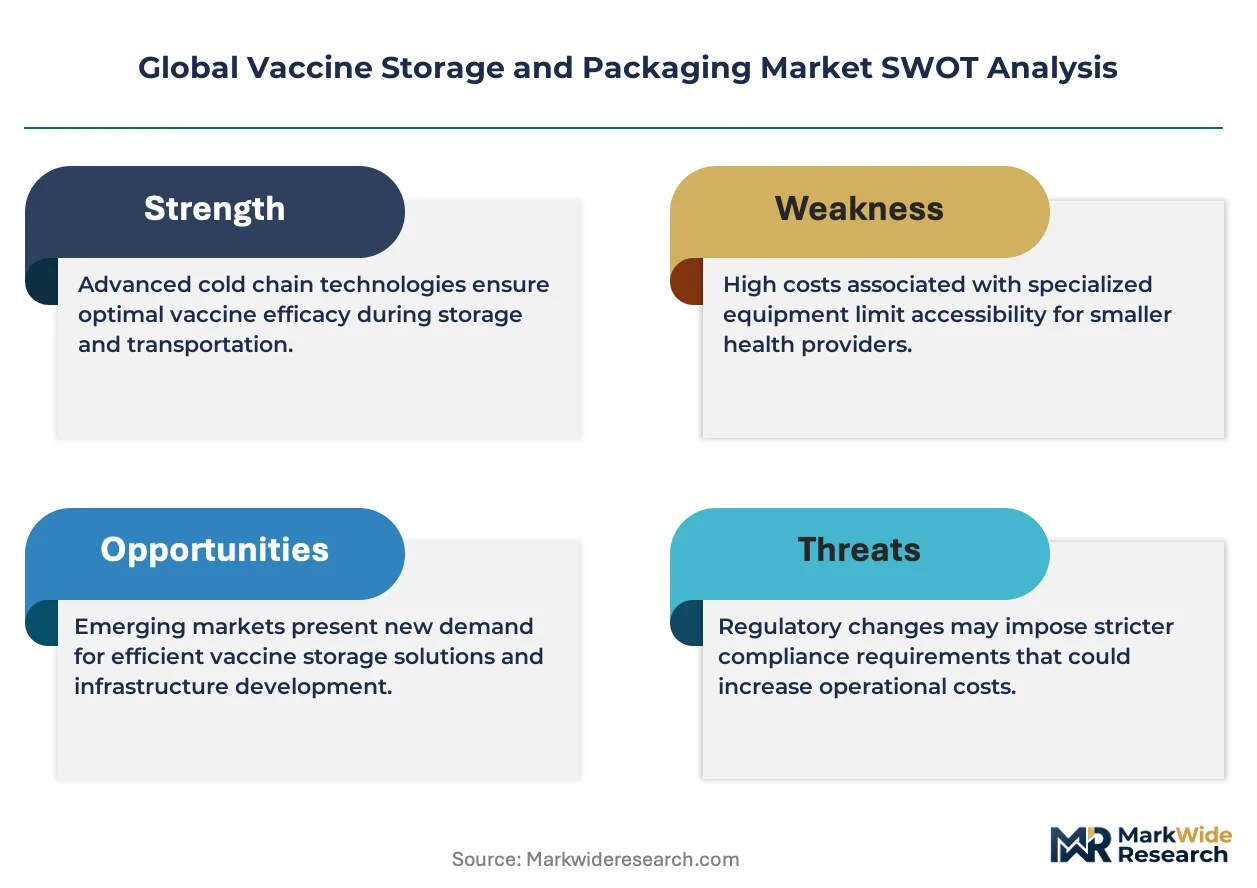
FDA's Drug Supply Chain Security Act and WHO Performance Quality and Safety prequalification framework mandate serialization and thermal validation documentation that elevates compliance costs for market entry. The EU's F-Gas Regulation progressively restricts hydrofluorocarbon refrigerants in active cooling equipment, forcing manufacturers toward natural refrigerant transitions. Stakeholders must monitor evolving pharmacopeial standards for container closure integrity as novel adjuvant and lipid nanoparticle formulations impose incompatible material requirements on legacy packaging platforms.
Market Dynamics
The WHO Performance Quality and Safety prequalification framework is compressing supplier qualification timelines while elevating thermal validation documentation requirements, forcing packaging manufacturers to restructure compliance workflows around centralized audit protocols.
Growth Catalysts
- Passive cooling technology maturation:Phase change material formulations now sustain two-to-eight-degree Celsius ranges for ninety-six hours without external power, enabling last-mile distribution in grid-deficient regions.
- India's Universal Immunization Program expansion:Government procurement of solar-powered cold boxes for rural health sub-centers is creating sustained demand for decentralized storage infrastructure.
- FDA Drug Supply Chain Security Act serialization mandates:Track-and-trace requirements for vaccine containers are driving replacement of legacy packaging with integrated data matrix solutions.
Market Restraints
- Specialized polymer feedstock concentration:Cyclic olefin polymer resin supply concentrates among three Japanese and German chemical suppliers, exposing converters to input volatility.
- EU F-Gas Regulation refrigerant restrictions:Hydrofluorocarbon phase-out timelines are forcing active cooling equipment manufacturers toward costly natural refrigerant transitions without proven service networks.
- Cryogenic infrastructure limitation:Liquid nitrogen vapor distribution for minus-seventy-degree Celsius mRNA storage remains confined to metropolitan hubs, constraining rural access.
Strategic Opportunities
- Sub-Saharan African immunization corridors:Gavi-funded cold chain investments in Nigeria, Ethiopia, and the Democratic Republic of Congo are opening procurement windows for prequalified passive cooling suppliers.
- Cell and gene therapy convergence:Autologous therapy manufacturing is repurposing vaccine cryogenic logistics infrastructure for personalized medicine distribution.
- India Production Linked Incentive scheme:Domestic vaccine manufacturing subsidies are attracting cold chain equipment assembly investments to Pune and Hyderabad industrial corridors.
Industry Challenges
- Thermal validation engineering talent scarcity:Qualified professionals capable of executing ISTA 7E and WHO PQS E003 protocols command premium compensation, constraining mid-tier manufacturer expansion.
- Multi-jurisdiction certification synchronization:Divergent FDA, EMA, and CDSCO stability study requirements force redundant testing protocols that extend product launch timelines.
- Legacy active cooling fleet retrofit complexity:Existing hospital and blood bank refrigeration infrastructure requires extensive controller and sensor upgrades to meet current data logging standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vaccine Storage and Packaging Market |
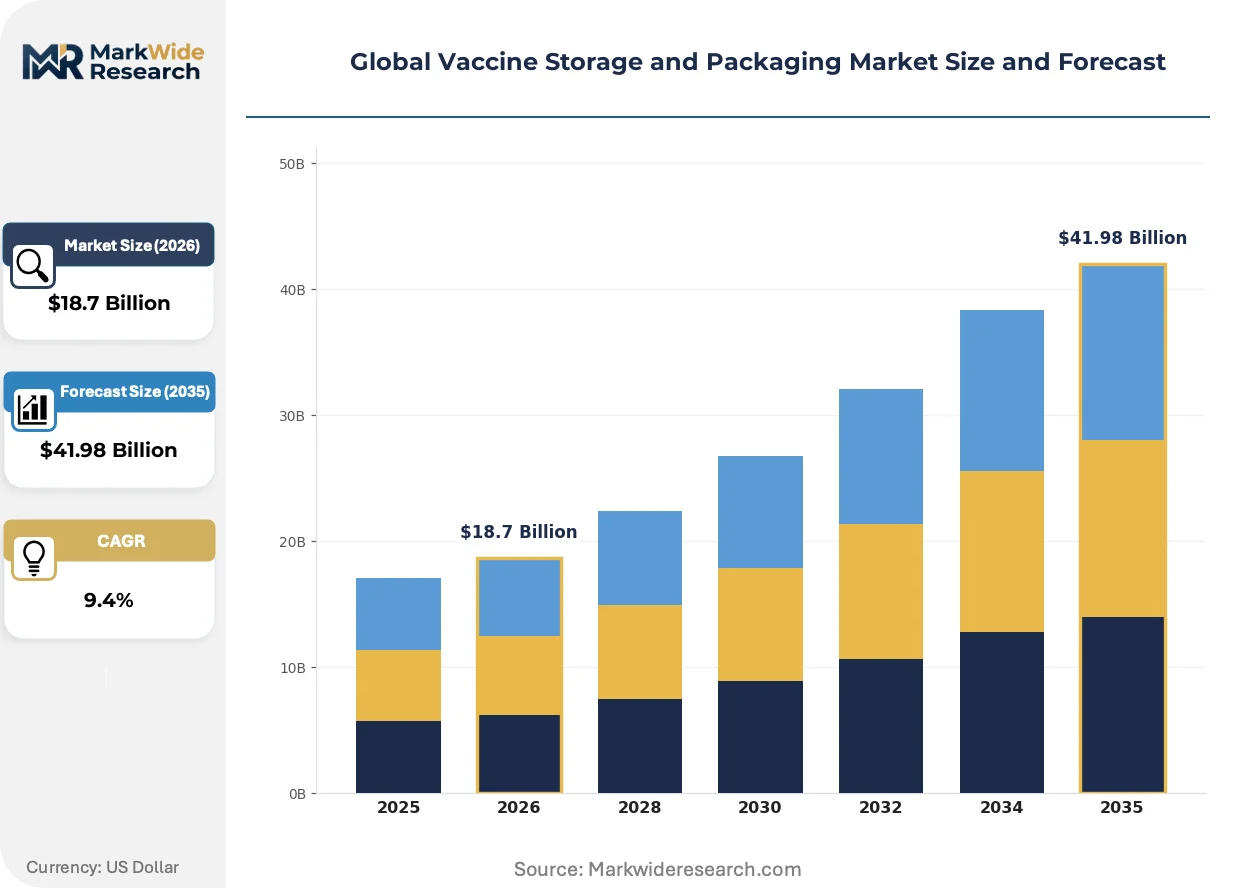
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Dry Ice Containers, Thermal Shippers, Cold Boxes, Insulated Bags Technology: Passive Cooling, Active Cooling, Phase Change Materials, Cryogenic Systems, Solar-Powered Units Application: Immunization Programs, Clinical Trials, Veterinary Vaccines, Travel Medicine, Blood Bank Storage End User: Healthcare Facilities, Research Laboratories, Vaccine Manufacturers, Public Health Organizations, Mobile Clinics |
| Companies Covered | Corning Incorporated, Gerresheimer, SCHOTT Pharma, Amcor, Thermo Fisher Scientific, DHL Group, Lineage, PHCbi, Stevanato Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vaccine Storage and Packaging Market Shifts & Advancements
Digital integration across temperature monitoring, serialization, and predictive maintenance is compressing the gap between passive reliability and active system intelligence, reshaping how cold chain performance is validated and insured.
IoT-enabled temperature loggers embedded in thermal shippers is digitizing compliance documentation for pharmaceutical distributors. Large-scale logistics providers in North America and Western Europe are mandating real-time data transmission as a procurement prerequisite. This connectivity layer is digitizing liability allocation between manufacturers, carriers, and receiving institutions.
The EU F-Gas Regulation's hydrofluorocarbon phase-down schedule is accelerating natural refrigerant adoption in active cooling equipment. Compressor manufacturers are retooling production lines for propane and carbon dioxide systems ahead of 2030 bans. Blood banks and clinical trial depots in Germany, France, and the Netherlands are piloting these transitions through accelerated replacement cycles.
Consolidated procurement by national immunization programs is displacing fragmented hospital-level purchasing in emerging markets. UNICEF and PAHO are negotiating multi-year framework agreements that bundle storage equipment with technical assistance. This aggregation is most visible across Latin American ministries of health restructuring procurement around Pan American Health Organization coordination mechanisms.
Global Vaccine Storage and Packaging Market Segmentation
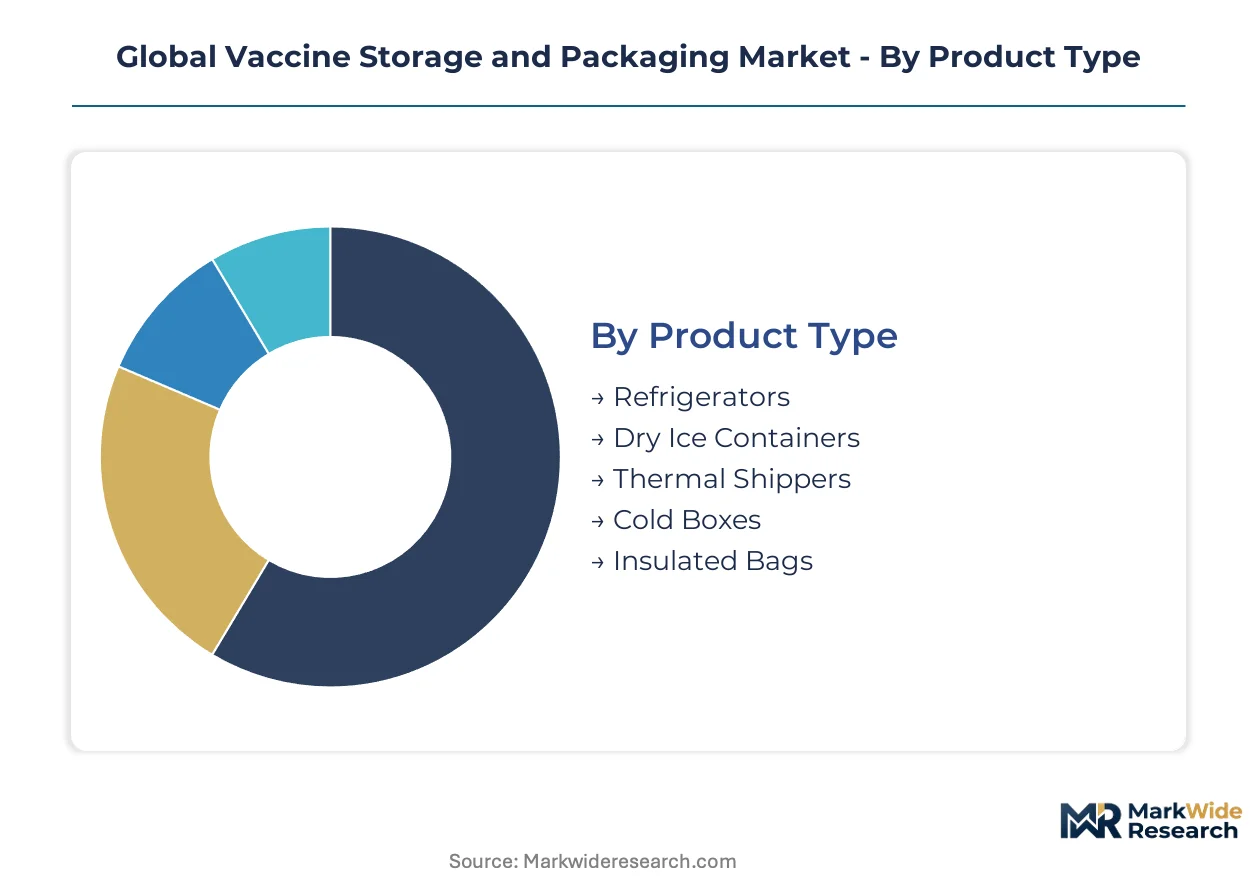
Vaccine storage and packaging segmentation reveals how equipment specifications diverge across temperature requirements, power availability, and regulatory environments. Each category carries distinct after-sales-service intensity profiles that reshape vendor profitability and customer lifetime value calculations.
Product Type:
After-sales-service intensity varies dramatically across product categories, with active cooling systems demanding continuous calibration support while passive units require minimal field intervention.
- Refrigerators:Compressor-based units with integrated data logging dominate healthcare facility procurement. India's Universal Immunization Program and Nigeria's cold chain expansion drive sustained replacement cycles for grid-connected primary health centers.
- Thermal Shippers:Insulated containers employing phase change materials maintain two-to-eight-degree Celsius stability for seventy-two to ninety-six hours. Gavi-funded last-mile distribution programs in Ethiopia and the Democratic Republic of Congo concentrate demand for validated passive transport solutions.
- Dry Ice Containers:Expanded polystyrene or polyurethane foam vessels for short-duration ultra-low temperature maintenance.
- Cold Boxes:Vaccine-grade insulated containers designed for health worker transport without external power.
- Insulated Bags:Lightweight carriers for same-day vaccine transport in urban and peri-urban settings.
Refrigerators hold the largest share; momentum sits with thermal shippers.
Technology:
Technology selection correlates directly with infrastructure maturity and electricity reliability across target deployment geographies.
- Passive Cooling:Systems relying on insulated containment and thermal mass without mechanical refrigeration. Resource-limited settings in sub-Saharan Africa and rural India favor these units for their independence from grid connectivity and minimal maintenance requirements.
- Solar-Powered Units:Photovoltaic-driven compression or absorption refrigeration with battery backup. India's off-grid health sub-centers and Indonesian archipelago immunization posts represent concentrated adoption zones as decentralized cold chain investments accelerate.
- Active Cooling:Electrically powered mechanical refrigeration with precise temperature control.
- Phase Change Materials:Engineered substances absorbing and releasing latent heat at defined temperature setpoints.
- Cryogenic Systems:Liquid nitrogen vapor or mechanical cascade refrigeration sustaining minus seventy degrees Celsius for mRNA and cell-based formulations.
Passive cooling commands the largest installed base; solar-powered units are climbing the fastest.
Application:
Application segmentation tracks how temperature requirements, batch sizes, and regulatory documentation intensity diverge across use cases.
- Immunization Programs:National and subnational public health campaigns requiring standardized equipment procurement at scale. India's Ministry of Health and Family Welfare and Brazil's Ministry of Health anchor volume through multi-year framework agreements with prequalified suppliers.
- Clinical Trials:Investigational product storage demanding continuous temperature documentation and audit trails. Contract research organizations in Germany, the United Kingdom, and the United States drive premium equipment specifications for Good Clinical Practice compliance.
- Veterinary Vaccines:Livestock and companion animal immunization with reduced regulatory stringency versus human pharmaceuticals.
- Travel Medicine:Yellow fever and typhoid vaccination services at private clinics and airport health facilities.
- Blood Bank Storage:Whole blood and component preservation with parallel temperature monitoring requirements to vaccine cold chain standards.
Immunization programs generate the largest revenue pool; clinical trials deliver the steepest expansion trajectory.
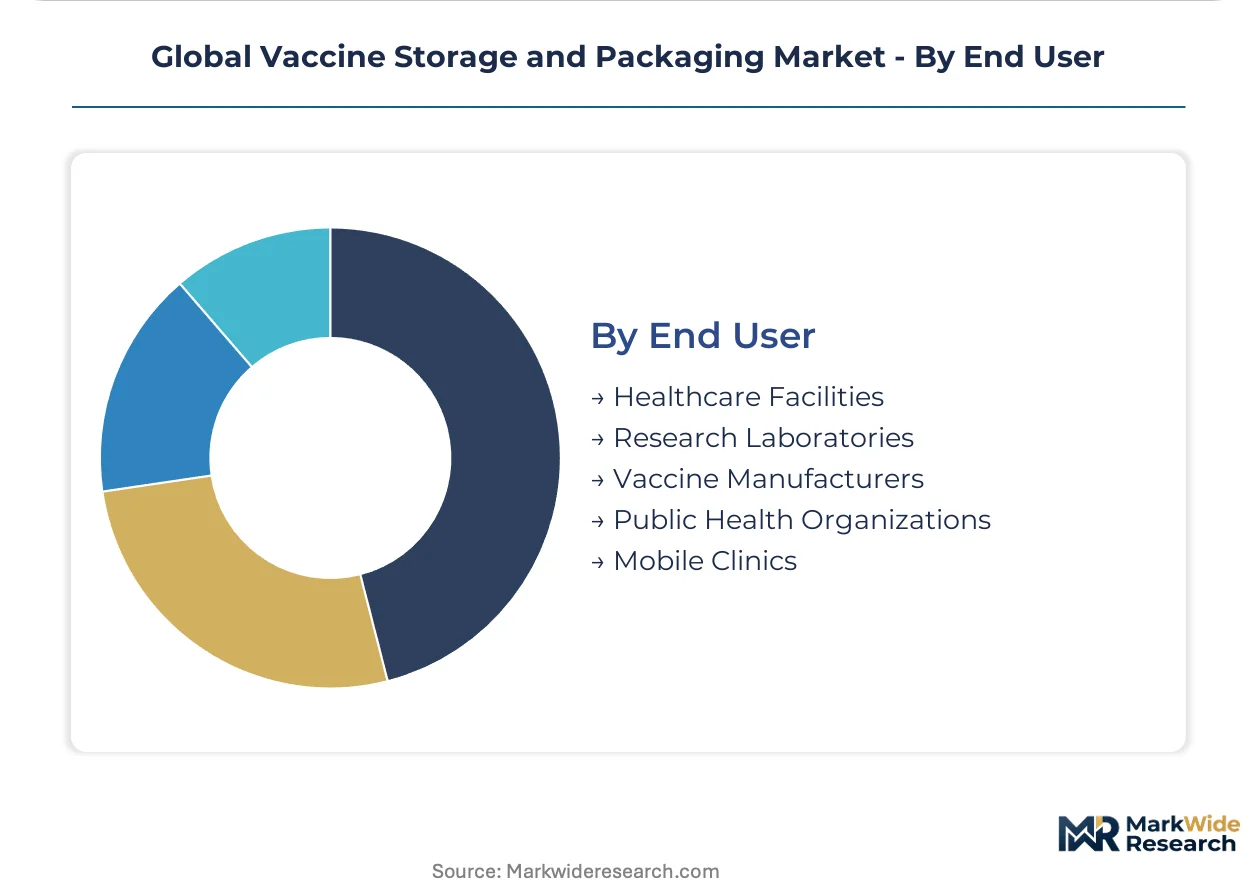
End User:
End-user categories reflect divergent procurement authority, technical sophistication, and total cost of ownership sensitivity.
- Healthcare Facilities:Hospitals, primary health centers, and clinics administering routine immunization. India's district hospitals and Nigeria's local government area cold stores concentrate equipment procurement through centralized state medical store depots.
- Vaccine Manufacturers:Serum Institute of India, Bio Farma in Indonesia, and Instituto Butantan in Brazil require validated storage for bulk antigen and finished dose inventory.
- Research Laboratories:Academic and government research institutions with specialized stability study requirements.
- Public Health Organizations:WHO, UNICEF, Gavi, and national disease control programs operating centralized procurement.
- Mobile Clinics:Outreach vaccination services requiring portable, ruggedized equipment for field deployment.
Healthcare facilities dominate installed capacity; vaccine manufacturers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cold chain corridors connecting Rotterdam's pharmaceutical port to European distribution networks, and the Delhi-Mumbai Industrial Corridor's vaccine manufacturing belt, anchor infrastructure investment across two hemispheres.
United States
FDA serialization mandates under the Drug Supply Chain Security Act are accelerating replacement of legacy vaccine packaging with track-and-trace-enabled solutions. The agency's stability study requirements for container closure integrity are elevating compliance costs for market entry. Greater Boston's biotech cluster concentrates clinical trial depot demand for precision active cooling systems.
Germany
The EU F-Gas Regulation's hydrofluorocarbon phase-down is forcing blood banks and research facilities toward natural refrigerant transitions. EMA pharmacopeial standards for novel lipid nanoparticle formulations are reshaping material compatibility requirements. The Rhine-Main region's logistics hubs are piloting IoT-enabled temperature monitoring as a procurement prerequisite.
India
CDSCO alignment with WHO Performance Quality and Safety prequalification is compressing supplier qualification timelines for domestic manufacturers. The Production Linked Incentive scheme for vaccine production is attracting cold chain equipment assembly to Pune and Hyderabad. The Universal Immunization Program's solar-powered cold box procurement sustains rural health sub-center deployment.
Brazil
ANVISA's convergence with FDA stability documentation standards is extending product launch timelines for imported packaging solutions. Pan American Health Organization consolidated procurement is restructuring ministry-level purchasing around framework agreements. São Paulo's Instituto Butantan anchors regional manufacturing demand for validated bulk antigen storage.
Japan
PMDA's stringent container closure integrity protocols for mRNA formulations are driving polymer syringe specialization among domestic suppliers. METI's dual carbon goals are accelerating natural refrigerant adoption in active cooling equipment. The Kansai region's pharmaceutical manufacturing belt concentrates demand for ultra-low temperature cryogenic infrastructure.
Global Vaccine Storage and Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and thermal engineering. The market structure bifurcates between consolidated active cooling equipment providers and fragmented passive packaging converters. Three archetypes dominate: laboratory equipment heritage players, pharmaceutical glass specialists, and logistics platform operators. Competitive moves concentrate on vertical integration into polymer resin conversion and strategic partnerships for last-mile distribution networks.
Among laboratory equipment heritage players, Thermo Fisher Scientific occupies a position exemplifying active cooling dominance for research applications. Pharmaceutical glass specialists include SCHOTT Pharma and Gerresheimer, representing the primary packaging tier where material science determines competitive positioning. These named entities anchor archetype boundaries without exhausting the competitive set.
| Leading Market Players |
|---|
| Corning Incorporated |
| Gerresheimer |
| SCHOTT Pharma |
| Amcor |
| Thermo Fisher Scientific |
| DHL Group |
| Lineage |
| PHCbi |
| Stevanato Group |
| Others |
Supply & Pricing Matrix
The Rotterdam-Frankfurt pharmaceutical corridor's freight cost volatility compresses margins for passive cooling converters while amplifying price differentiation between WHO-prequalified and non-certified equipment tiers. Supply concentration in Japanese and German cyclic olefin polymer resin producers feeds directly into packaging cost structures, forcing buyers to absorb premium markups or downgrade to standard-grade alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement frameworks. Premium tiers command substantial markups for WHO PQS E003 certification and integrated data logging, while economy segments serve resource-limited immunization programs with stripped-down passive units. Cost compression in the standard tier is intensifying because Gavi's consolidated procurement aggregates demand and squeezes converter margins. Public health organizations exhibit highest price sensitivity due to fixed budget envelopes, whereas clinical trial depots prioritize performance over unit cost.
Supply Chain Analysis
Export-control regimes on phase change material formulations and compressor technology limit flows from Germany, Japan, and the United States to certain end markets. Manufacturing draws from concentrated feedstock sources: cyclic olefin polymer resin, polyurethane foam insulation, and photovoltaic panels for solar-powered units. Single-source vulnerability in Japanese resin supply creates exposure to input disruptions. Distribution runs through UNICEF and PAHO framework agreements that aggregate national procurement and displace fragmented hospital-level purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is recovering from pandemic-era overcapacity as Gavi's replenished funding cycles and India's PLI scheme restore equipment replacement demand. This cyclical upturn favors suppliers with prequalified product portfolios and established ministry relationships.
For Market Incumbents: Entrench position through backward integration into polymer resin conversion and captive supply of phase change materials. Threat from Chinese solar-powered equipment manufacturers entering through price-aggressive bidding demands defensive certification investments in WHO PQS E003 and CDSCO alignment. Channel control via exclusive technical assistance bundling with framework agreements protects against disintermediation.
For New Entrants and Emerging Players: Sub-Saharan African immunization corridors in Nigeria, Ethiopia, and the Democratic Republic of Congo offer accessible procurement windows for prequalified passive cooling suppliers. Solar-powered cold boxes for Indonesia's archipelago health posts represent a second penetrable segment underserved by incumbent logistics networks. Go-to-market execution should anchor on Gavi application engineering support and localized assembly partnerships.
For Investors and Strategic Acquirers: Component specialists with thermal engineering IP and established ministry relationships present the most attractive acquisition profile. Long-term viability hinges on 5-10 year immunization program funding continuity rather than cyclical pandemic demand. Watch Gavi's annual funding replenishment cycles as the critical inflection signal for equipment procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO PQS Prequalification Investment | Unlocks UNICEF and Gavi procurement eligibility for passive cooling suppliers. |
| Natural Refrigerant Transition | Positions active cooling manufacturers ahead of EU F-Gas Regulation phase-down deadlines. |
| IoT-Enabled Temperature Monitoring | Meets DHL and Lineage real-time data mandates for pharmaceutical logistics contracts. |
| Domestic Assembly Investment | Captures India's PLI scheme subsidies for vaccine manufacturing corridor equipment supply. |
| Polymer Syringe Specialization | Addresses PMDA container closure integrity requirements for mRNA lipid nanoparticle formats. |
Research Methodology
The analysis maps active cooling systems, passive thermal shippers, and cryogenic infrastructure, each validated through cold chain engineers at vaccine manufacturers, procurement officers at national immunization programs, and logistics managers at pharmaceutical distributors. Primary interviews with WHO prequalification auditors and thermal validation specialists combined with secondary sources including WHO PQS equipment lists, CDSCO registration databases, and Gavi disbursement records. Bottom-up equipment procurement tracking and top-down immunization program budget analysis provided triangulation.
Assumptions held fixed include WHO prequalification standards, EU F-Gas Regulation phase-down timelines, and Gavi funding continuity across the projection horizon. Segmentation modeled product type, technology, application, and end-user dimensions alongside regional regulatory cluster variations. CAGRs derived from equipment replacement cycle analysis and immunization program expansion trajectories. Forecast inputs incorporated solar-powered unit adoption curves and natural refrigerant transition cost pass-through assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese equipment manufacturers or accelerated EU refrigerant bans would shift outcomes. Cross-checking against UNICEF's annual vaccine procurement forecasts and Gavi's country eligibility transitions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
Recycled Prescription Bag Market
Pharmaceutical Packaging
Vial Box Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Smart Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
United States Ampoules Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Packaging Market
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
Plastic Vials and Ampoules Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Pharmacy Repackaging Systems Market
Pharmaceutical Packaging
Tablet Bottle Market
Pharmaceutical Packaging
Anti-Counterfeit Pharmaceutical Packaging Market