
 United States Pharmaceutical Contract Packaging Market | 2026-2036
United States Pharmaceutical Contract Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Pharmaceutical Contract Packaging Market Intelligence
Primary packaging assembly revenue is rewriting margin allocation across the value chain as serialization and aggregation requirements absorb operational bandwidth. Catalent anchors its position through integrated clinical-to-commercial packaging campuses in North Carolina and Indiana. PCI Pharma Services leverages specialized containment infrastructure for highly potent compounds, sustaining premium pricing power in oncology packaging. Sharp Packaging competes on speed-to-market for launch quantities, differentiating through dedicated FDA-regulated facilities with flexible batch sizing.
United States pharmaceutical contract packaging encompasses outsourced fabrication, labeling, and final assembly of drug containers performed under cGMP conditions, typically involving automated blister forming, bottle filling, and cartoning operations with integrated vision inspection and electronic pedigree generation. Blister packaging dominates value contribution due to its prevalence in solid oral dose compliance regimes and child-resistant senior-friendly engineering requirements, while injectable delivery mode formats command the fastest expansion as prefilled syringe and auto-injector assemblies multiply for biologics. Pouch formats for unit-dose oral solids and shrink sleeve secondary packaging for brand protection represent mature segments where margin compression from generics demand drives consolidation among mid-tier providers.
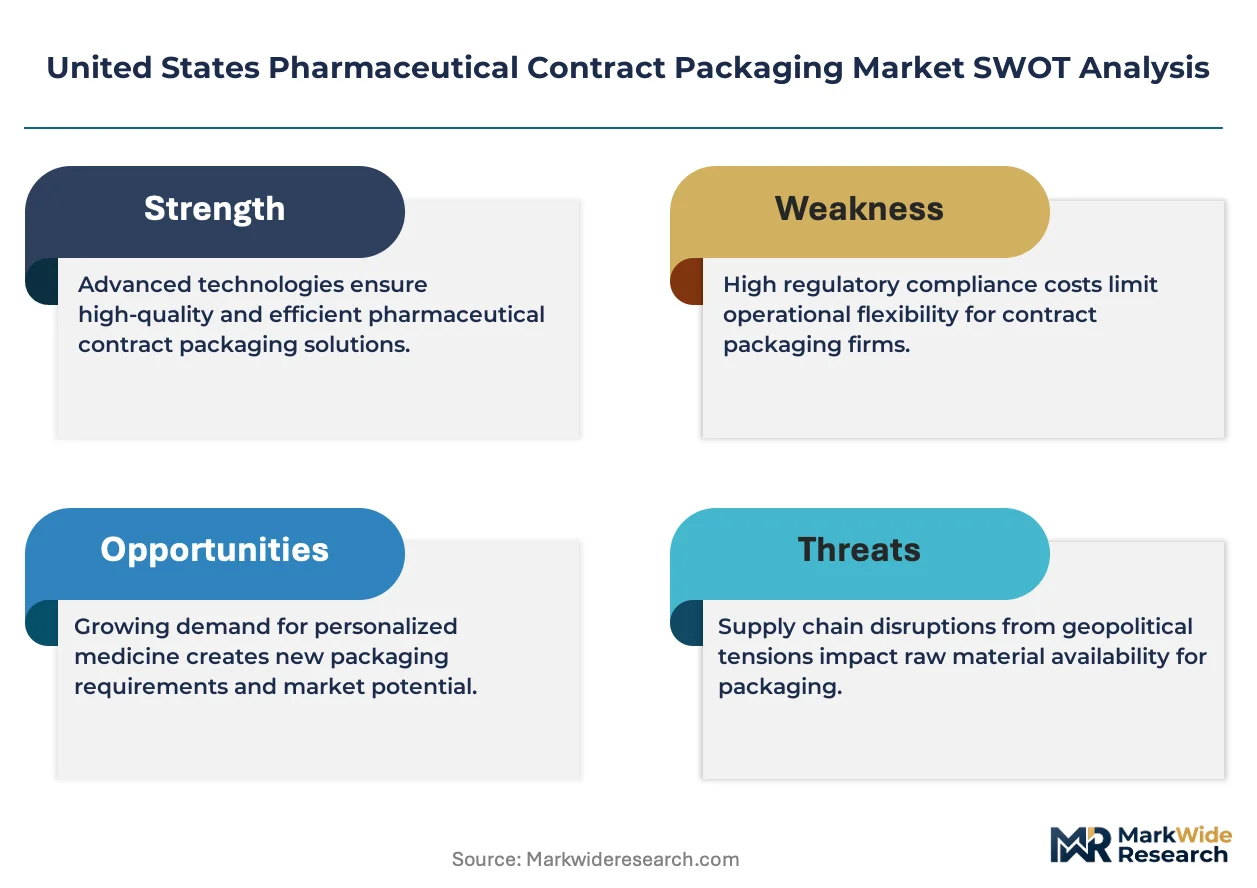
FDA's Drug Supply Chain Security Act enforcement and USP <660> glass container standards shape facility qualification timelines and equipment validation burdens, directly influencing contract packer selection criteria for sponsor companies. EPA hazardous waste regulations for pharmaceutical residuals and OSHA containment guidelines for potent compound handling further structure capital deployment decisions. Stakeholders must monitor evolving FDA guidance on advanced manufacturing technologies and state-level pharmaceutical stewardship laws that could mandate take-back program integration into packaging design specifications.
Market Dynamics
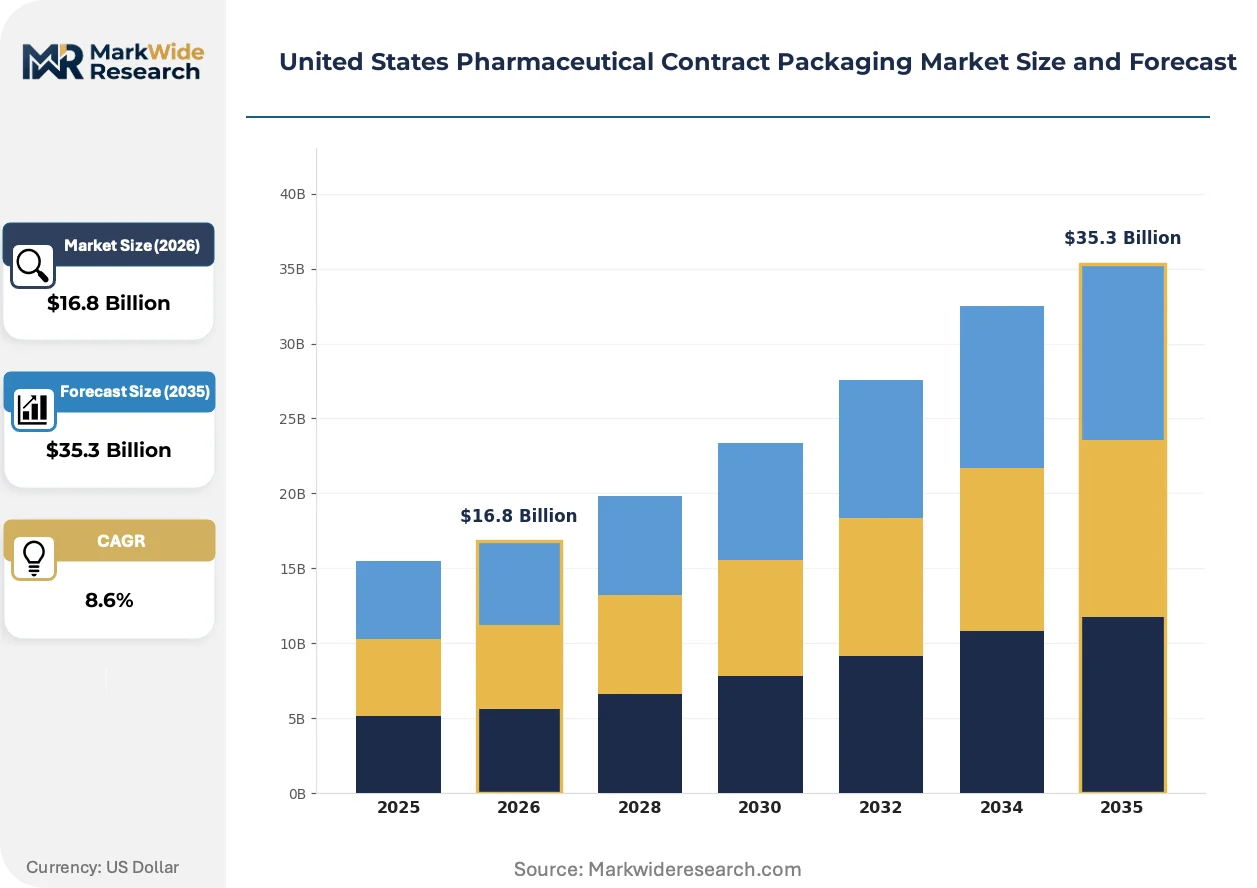
FDA serialization mandates under the Drug Supply Chain Security Act are compressing qualification timelines for contract packers while simultaneously elevating capital barriers to entry across the US pharmaceutical packaging landscape.
Growth Catalysts
- Specialty biologics proliferation:Complex therapies requiring cold-chain and sterile packaging configurations are expanding addressable contract packaging demand. Prefilled syringe and auto-injector assemblies for biologics now absorb disproportionate operational bandwidth.
- Track-and-trace infrastructure mandates:FDA DSCSA enforcement deadlines are compelling sponsor companies to outsource serialization and aggregation capabilities rather than build in-house. This regulatory pressure accelerates capital investment in automated inspection systems.
- Northeast pharmaceutical corridor concentration:Contract packers cluster near major drug development hubs spanning New Jersey, Pennsylvania, and Massachusetts, creating geographic proximity advantages that reduce logistics friction for sponsor companies.
Market Restraints
- Equipment validation burdens:USP container closure integrity standards and FDA facility qualification timelines impose extended capital deployment cycles before revenue generation begins.
- Specialized containment infrastructure scarcity:Limited domestic capacity for highly potent compound handling concentrates pricing power among providers with existing containment capabilities.
- Glass container standard compliance:Evolving USP glass quality requirements force ongoing equipment retrofits and supplier qualification costs that compress margins for mid-tier providers.
Strategic Opportunities
- Advanced manufacturing technology integration:FDA guidance on continuous manufacturing and real-time release testing creates openings for contract packers with integrated clinical-to-commercial packaging campuses.
- State-level pharmaceutical stewardship laws:Emerging take-back program mandates in California and Washington could require packaging design modifications that favor early-adopting contract packers.
- Flexible batch sizing for launch quantities:Speed-to-market demands for commercial introductions favor providers with dedicated FDA-regulated facilities capable of rapid scale transitions.
Industry Challenges
- Serialization engineering talent scarcity:Automated vision inspection and electronic pedigree generation systems require specialized validation expertise that outpaces domestic workforce development.
- Legacy MES integration friction:Sponsor company manufacturing execution systems often resist seamless data exchange with contract packer serialization platforms, creating qualification delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Pharmaceutical Contract Packaging Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $35.3 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packaging, Bottles, Pouches, Labels Delivery Mode: Oral, Injectable, Topical, Inhalation End User: Pharmaceutical Companies, Biotech Firms, Contract Providers, Research Institutions Packaging Type: Shrink Sleeves, Cartons, Sachets, Tubes |
| Companies Covered | Thermo-Pak Co., Inc., Aphena Pharma Solutions, Sonic Packaging Industries, Inc., Assemblies Unlimited, Inc., Action Pak, Inc., PCI Pharma Services, Catalent, Sharp Packaging, WestRock Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Pharmaceutical Contract Packaging Market Strategic Shifts & Innovations
Automation architectures are compressing operational bandwidth allocation while regulatory compliance technologies reshape competitive positioning across the US contract packaging value chain.
Machine vision systems integrated with automated inspection hardware are digitizing quality assurance workflows throughout primary packaging assembly operations. Specialty biologics manufacturers now demand real-time defect detection capabilities as standard qualification criteria. This technology convergence is digitizing margin allocation across the value chain by absorbing labor-intensive manual inspection processes.
FDA enforcement of Drug Supply Chain Security Act aggregation requirements is restructuring capital deployment priorities for contract packers. Sponsors now select packaging partners based on verified track-and-trace infrastructure rather than unit cost alone. Injectable delivery mode formats face the steepest compliance burden as prefilled syringe and auto-injector assemblies require unit-level serialization through case-level aggregation.
Biologics developers are compressing vendor qualification cycles from traditional eighteen-month windows to accelerated six-month evaluations. This procurement pattern shift favors contract packers with pre-validated containment infrastructure and existing FDA establishment registrations. The Northeast pharmaceutical corridor exhibits the most pronounced acceleration as Massachusetts and New Jersey-based sponsors compete for limited qualified capacity.
United States Pharmaceutical Contract Packaging Market Segmentation
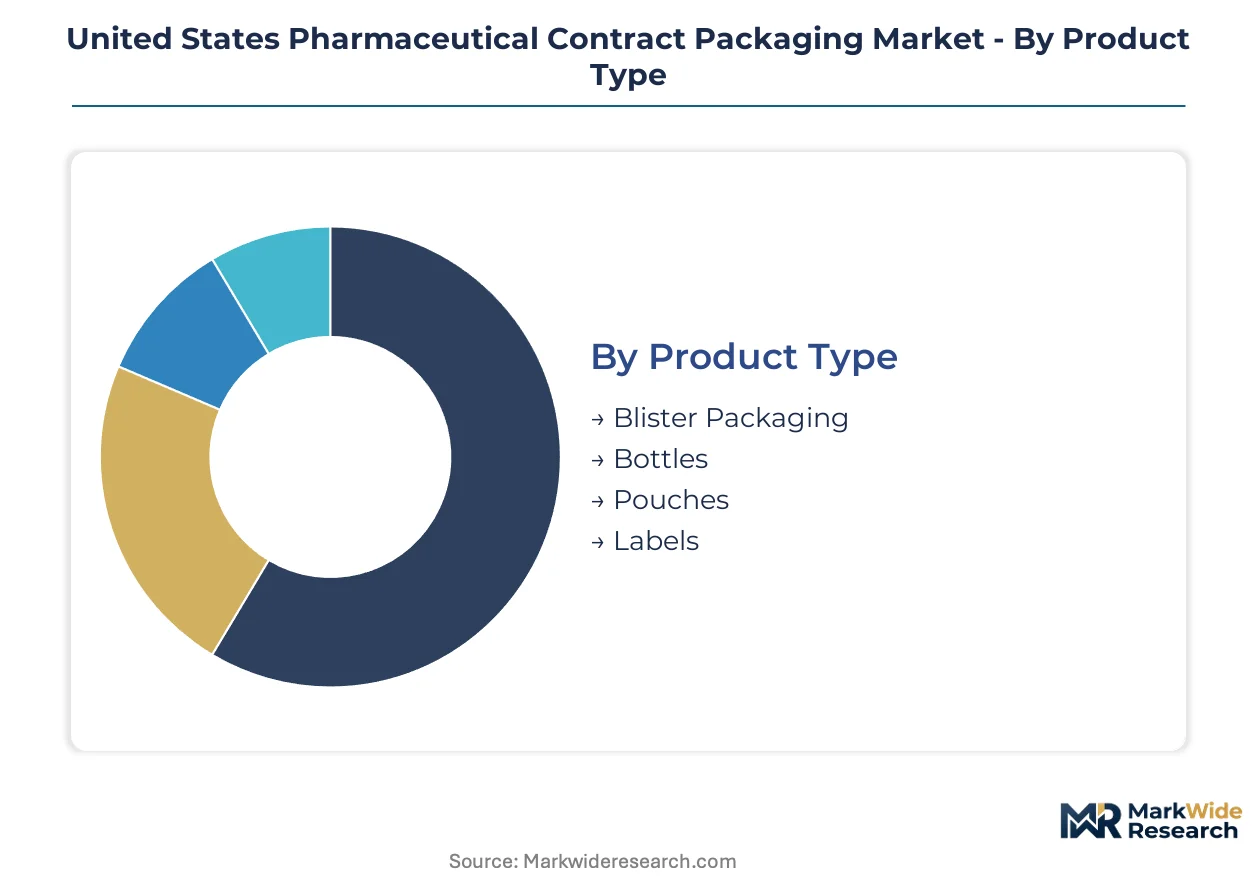
Segmentation in US pharmaceutical contract packaging reveals how regulatory compliance burdens and therapy complexity reshape vendor selection criteria. Cycle-time variation across product formats directly influences capital allocation decisions for both sponsors and packaging providers.
Product Type:
Blister packaging turns inventory fastest due to standardized solid oral dose workflows, while bottle lines require longer changeover cycles for liquid formulation compatibility.
- Blister Packaging:Automated thermoforming and cold-form foil assemblies dominate solid dose compliance regimes. Demand concentrates in New Jersey and Pennsylvania corridors where FDA-registered facilities cluster near sponsor headquarters. Child-resistant senior-friendly engineering requirements absorb disproportionate validation bandwidth.
- Bottles:HDPE and PET container systems with integrated induction sealing serve liquid and semi-solid formulations. Massachusetts-based biotech sponsors drive demand for serialized bottle-carton bundles with aggregation capabilities. USP glass quality standards force ongoing supplier qualification cycles.
- Pouches:Unit-dose strip packaging for oral solids in institutional settings.
- Labels:Pressure-sensitive and booklet formats with integrated RFID for track-and-trace compliance.
Blister packaging dominates installed base. Bottles are where expansion concentrates.
Delivery Mode:
Injectable formats command premium pricing tiers due to sterile barrier requirements, while oral delivery scales through volume efficiency.
- Injectable:Prefilled syringe and auto-injector assemblies for biologics require ISO 5 cleanroom environments and cold-chain validation. North Carolina clinical-to-commercial campuses anchor domestic capacity. FDA serialization mandates through case-level aggregation compress qualification timelines.
- Oral:Tablet and capsule packaging in blister and bottle configurations represents mature volume throughput. Indiana-based integrated facilities capture scale efficiencies for commercial launches. Generic substitution pressures compress margins.
- Topical:Cream, gel, and ointment tube and jar filling for dermatology applications.
- Inhalation:Dry powder and metered-dose device assembly with specialized containment requirements.
Oral delivery commands volume share. Injectable formats are climbing the fastest.
End User:
Biotech firms compress vendor qualification cycles most aggressively, while pharmaceutical companies maintain extended evaluation protocols for multi-site standardization.
- Biotech Firms:Massachusetts and California developers of specialty biologics demand six-month qualification windows versus traditional eighteen-month cycles. Prefilled syringe assembly capabilities rank as primary selection criteria. Limited qualified domestic capacity concentrates pricing power.
- Pharmaceutical Companies:Large sponsors in New Jersey and Pennsylvania outsource serialization infrastructure rather than build in-house DSCSA compliance systems. Multi-product portfolios favor contract packers with flexible batch sizing.
- Contract Providers:Mid-tier CDMOs seeking secondary packaging overflow capacity.
- Research Institutions:Academic medical centers with investigator-initiated trial packaging needs.
Pharmaceutical companies anchor contract volume. Biotech firms are where procurement urgency concentrates.
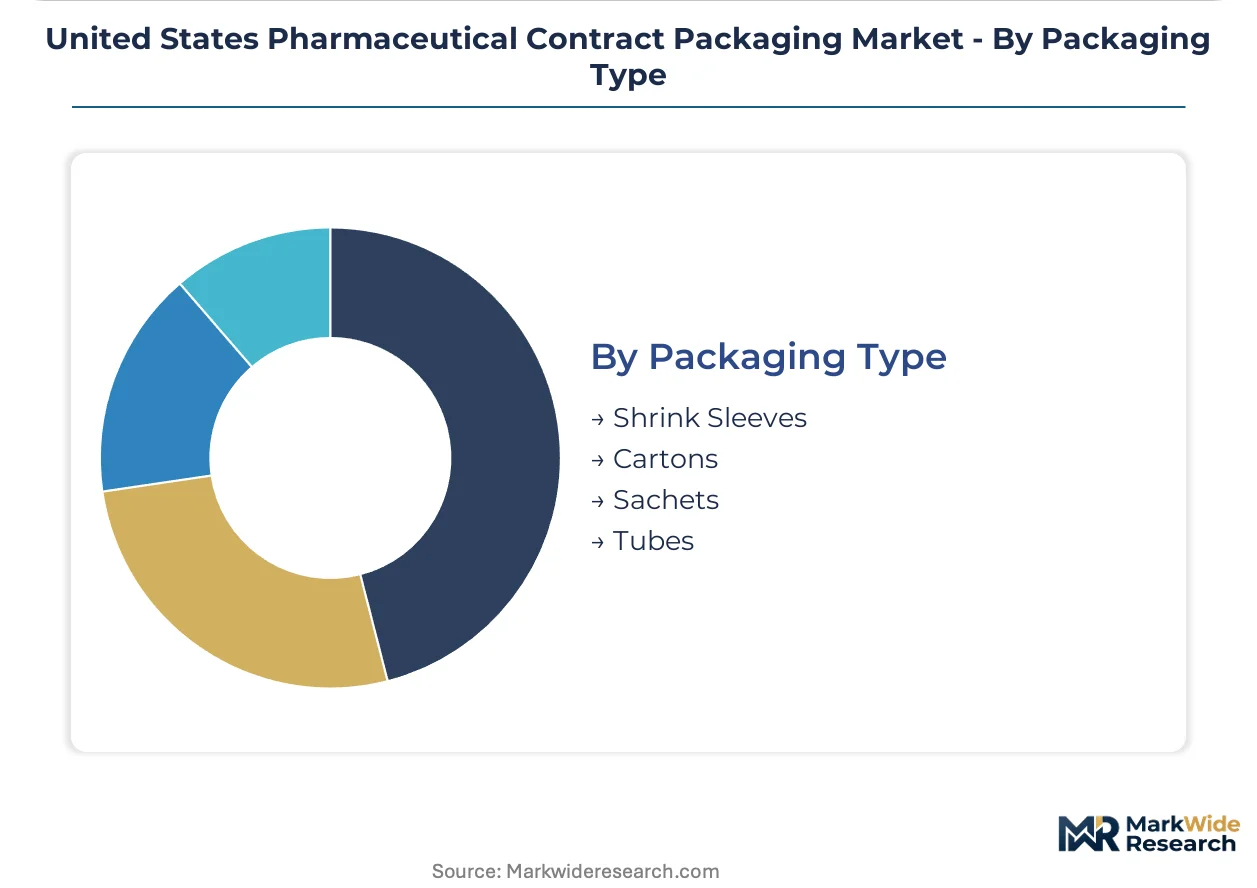
Packaging Type:
Secondary packaging formats vary in automation compatibility, with cartons integrating most seamlessly with serialization architectures.
- Cartons:Folding carton assembly with integrated leaflet insertion and tamper-evident closure serves as the standard secondary package for prescription pharmaceuticals. Northeast corridor facilities optimize for rapid launch quantity turnaround. Aggregation station integration is now mandatory for DSCSA compliance.
- Shrink Sleeves:360-degree printed film applications for brand protection and tamper evidence in OTC portfolios. California and Florida distribution hubs drive regional demand for moisture-resistant sleeve formats.
- Sachets:Single-unit flexible packaging for powder and liquid dose samples.
- Tubes:Laminate and extruded plastic containers for topical and oral care applications.
Cartons dominate secondary packaging throughput. Shrink sleeves are gaining share fastest in brand-protection applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Generic substitution pressures compress margins most severely in mature oral solid corridors, while biologics sponsors accept premium pricing for validated cold-chain infrastructure in concentrated Northeast and Midwest clusters.
Northeast Corridor
New Jersey and Massachusetts anchor the highest-value contract packaging demand as specialty biologics developers cluster near FDA headquarters and Harvard-MIT research corridors. FDA DSCSA enforcement deadlines compel sponsors to outsource serialization rather than build in-house track-and-trace systems. Catalent operates integrated clinical-to-commercial campuses in Morris County while PCI Pharma Services maintains containment infrastructure for highly potent compounds near Princeton.
Mid-Atlantic
Pennsylvania's Philadelphia suburbs concentrate bottle-filling capacity for liquid formulations serving institutional pharmacy channels. USP glass container standards force ongoing equipment retrofits among legacy facilities in Montgomery and Chester counties. Sharp Packaging competes on speed-to-market from FDA-regulated facilities in Bethlehem with flexible batch sizing for commercial launches.
Southeast
North Carolina's Research Triangle attracts biologics packaging investment through lower operating costs and proximity to growing clinical trial infrastructure. Prefilled syringe and auto-injector assembly demand from regional cell therapy developers outpaces qualified domestic capacity. Catalent anchors regional biologics packaging through integrated campuses in Research Triangle Park.
Midwest
Indiana's Indianapolis metro captures commercial-scale oral solid dose packaging for pharmaceutical companies seeking volume efficiency. Generic substitution pressures compress margins faster here than in coastal biologics corridors. Integrated facilities near Indianapolis International Airport optimize distribution reach for nationwide commercial launches.
West Coast
California's San Francisco Bay Area and San Diego clusters generate demand for specialized containment packaging from emerging biotech firms. State-level pharmaceutical stewardship laws in California could mandate take-back program integration into packaging design specifications. Limited qualified capacity concentrates pricing power among providers with existing FDA establishment registrations.
United States Pharmaceutical Contract Packaging Market Key Industry Players
Integrated clinical-to-commercial specialists and regional speed-to-market providers split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: multi-site integrated platforms with serialization infrastructure, specialized containment operators for highly potent compounds, and flexible-batch specialists for launch quantities. Dominant competitive moves include M&A to acquire validated cold-chain capacity and strategic partnerships to secure serialization engineering talent.
Within the integrated platform tier, Catalent and PCI Pharma Services exemplify archetypes that absorb disproportionate biologics demand through pre-validated infrastructure. Catalent occupies a position anchored in North Carolina and Indiana clinical-to-commercial campuses, while PCI Pharma Services represents specialized containment capabilities for oncology packaging. Sharp Packaging sits within the speed-to-market specialist tier, competing through dedicated FDA-regulated facilities with flexible batch sizing.
| Leading Market Players |
|---|
| Thermo-Pak Co., Inc. |
| Aphena Pharma Solutions |
| Sonic Packaging Industries, Inc. |
| Assemblies Unlimited, Inc. |
| Action Pak, Inc. |
| PCI Pharma Services |
| Catalent |
| Sharp Packaging |
| WestRock Company |
| Others |
Cost & Logistics Intelligence
New Jersey's pharmaceutical corridor concentrates validated serialization capacity, translating geographic scarcity into pricing power for contract packers with pre-qualified FDA establishments. Sponsors absorb 15-40% premiums for six-month qualification windows versus standard eighteen-month cycles, while mid-tier providers face margin compression from generic substitution pressures in oral solid dose segments.
Pricing Analysis
After-sales validation services and extended compliance contracts generate disproportionate lifetime value for specialized containment operators. Three-tier pricing structure across premium containment, standard serialization, and economy oral solid tiers reflects certification grade and cold-chain infrastructure investment. Pricing pressure stems from USP glass standard retrofits and DSCSA aggregation equipment depreciation. Generic pharmaceutical companies exhibit highest price sensitivity, while biotech firms prioritize speed over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced vision inspection systems and automated aggregation hardware limit equipment flows from Germany and Japan into domestic facilities. Active pharmaceutical ingredient supply draws from India, China, and Switzerland, with specialized cold-chain logistics resting on validated thermal packaging and controlled-environment trucking networks. Single-source vulnerability concentrates in ISO 5 cleanroom component fabrication. Distribution runs through sponsor-managed third-party logistics partnerships rather than contract packer-owned fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as DSCSA enforcement deadlines fragment sponsor procurement across serialization-capable specialists rather than consolidated volume players. Biologics developers' compressed qualification cycles create niche openings for mid-tier providers with pre-validated infrastructure.
For Market Incumbents: Insulate market position through backward integration into cold-chain logistics and captive serialization engineering talent development. Catalent and PCI Pharma Services anchor defensive moats through clinical-to-commercial campus density in North Carolina and Indiana. FDA establishment registration scarcity represents the priority asset to defend. Capacity expansion in Massachusetts corridor captures biotech procurement urgency. For New Entrants and Emerging Players: Mid-market pharmaceutical companies in Pennsylvania and Ohio seeking flexible batch sizing for commercial launches represent the most penetrable entry point. Containment infrastructure for highly potent compounds offers white-space pricing power given limited domestic qualified capacity. Go-to-market positioning as DSCSA compliance specialists with six-month qualification guarantees bypasses incumbent volume relationships. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because serialization mandates create durable barriers protecting specialized infrastructure investments. Acquisition targets cluster around FDA-registered facilities with existing track-and-trace validation and biologics cold-chain capabilities. The signal to watch is Massachusetts and New Jersey sponsor procurement cycle compression below twelve months, indicating capacity scarcity sufficient to sustain premium pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Infrastructure Investment | FDA DSCSA enforcement deadlines compel sponsor outsourcing rather than in-house buildouts. |
| Clinical-to-Commercial Campus Integration | Catalent's North Carolina facilities capture biologics demand through pre-validated sterile barrier capacity. |
| Containment Capability Acquisition | PCI Pharma Services' Princeton infrastructure commands oncology packaging premiums through potent compound handling. |
| Flexible Batch Sizing Specialization | Sharp Packaging's Bethlehem facilities differentiate through rapid scale transitions for commercial launches. |
| Cold-Chain Logistics Partnership | Validated thermal packaging networks reduce sponsor qualification burden for biologics distribution. |
Research Approach
Desk research of FDA establishment registrations, USP standard revision histories, and DSCSA guidance documents preceded structured interviews with drug development executives, regulatory affairs leads, contract packaging procurement managers, and serialization engineering specialists. Secondary validation drew from FDA warning letter databases, pharmaceutical trade association capacity surveys, and sponsor company outsourcing disclosure patterns. Bottom-up facility capacity estimates triangulated against top-down sponsor outsourcing spend allocation.
Assumptions around DSCSA enforcement timeline adherence, USP container closure integrity standard implementation pace, and biologics pipeline progression through clinical stages were held fixed across scenarios while varying sponsor procurement cycle compression rates and generic substitution intensity. Segmentation modeling incorporated product type, delivery mode, end-user archetype, and packaging format dimensions with regional regulatory cluster overlays. CAGRs were derived from facility investment pipeline analysis cross-referenced with sponsor outsourcing intention surveys.
Stress conditions across FDA inspection frequency escalation, glass container supplier consolidation, and serialization equipment lead time extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions with explicit scenario dependencies. Material shifts in DSCSA enforcement delay or USP standard revision scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Smart Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
Recycled Prescription Bag Market
Pharmaceutical Packaging
Latin America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Plastic Pharma Tray Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Vials Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Middle East and West Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Nutraceutical Packaging Market