
 Pharmaceutical Labeling Market | 2026-2036
Pharmaceutical Labeling Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Labeling Market Intelligence
GS1-compliant serialization specifications are reorganizing procurement priorities across pharmaceutical supply chains. Avery Dennison Corporation leverages its materials science portfolio to dominate high-performance adhesive substrates for temperature-sensitive biologics. CCL Industries Inc. sustains manufacturing scale across multiple continents, anchoring global capacity for multi-language booklet labels. Schreiner MediPharm specializes in functional label architectures that integrate RFID and NFC layers for cold-chain verification.
Pharmaceutical labeling encompasses printed, adhesive-backed substrates applied to drug containers, vials, syringes, and outer packaging to convey dosage, regulatory, traceability, and safety information; these labels typically employ facestocks such as polypropylene or polyester with permanent acrylic adhesives, manufactured through multi-layer lamination processes that must withstand sterilization, refrigeration, and chemical exposure. Pressure-sensitive labels occupy the largest volume share due to versatility across primary and secondary packaging formats, while digital printing represents the fastest-expanding technology segment as lot sizes shrink and personalization requirements intensify for clinical trial materials and orphan drug programs. Security labels command premium positioning as anti-counterfeiting layers become mandatory for high-value specialty pharmaceuticals distributed through parallel trade channels.
FDA DSCSA serialization mandates and EU Falsified Medicines Directive traceability requirements are reshaping label complexity, forcing drug manufacturers to embed unique identifiers and tamper-evident features at the unit-dose level. Health Canada and ANVISA have aligned with similar track-and-trace frameworks, expanding compliance-driven label demand across North and South American supply chains. Stakeholders must evaluate substrate-to-software integration capabilities when selecting label partners, as regulatory verification systems converge on interoperable data standards.
Market Dynamics
Serialization mandates from FDA DSCSA and EU Falsified Medicines Directive are forcing pharmaceutical manufacturers to rebuild label architectures around track-and-trace infrastructure, converting compliance spend into competitive differentiation.
Growth Catalysts
- EU Falsified Medicines Directive:Unit-dose verification requirements are expanding demand for tamper-evident and serialized labels across European distribution networks.
- Biologics cold-chain expansion:Temperature-sensitive biologics require specialized adhesive substrates that maintain integrity from -80°C to +25°C.
- Germany's pharmaceutical clusters:Heidelberg and Munich packaging hubs concentrate specialized label procurement for high-value injectables.
Market Restraints
- Adhesive raw material volatility:Acrylic polymer feedstock costs fluctuate with petrochemical markets, compressing converter margins.
- Equipment vendor concentration:Digital printing press manufacturers cluster in Western Europe and Japan, creating supply risk for label converters elsewhere.
- Legacy serialization interoperability:Incompatible data formats between early DSCSA implementations and current GS1 standards force redundant infrastructure.
Strategic Opportunities
- Brazil ANVISA alignment:Track-and-trace mandates following EU and US models create first-mover advantage for serialization-ready label suppliers.
- RFID-NFC convergence:Near-field communication layers combined with radio-frequency identification enable smartphone-based authentication for patients.
- Clinical trial personalization:Adaptive study designs require variable-data booklet labels with patient-specific dosing instructions.
Industry Challenges
- Serialization technician scarcity:Label converters struggle to hire operators proficient in both mechanical printing and cloud-based verification software.
- Multi-master data management:Pharmaceutical manufacturers must synchronize lot codes across ERP, LIMS, and label management systems with zero error tolerance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Labeling Market |
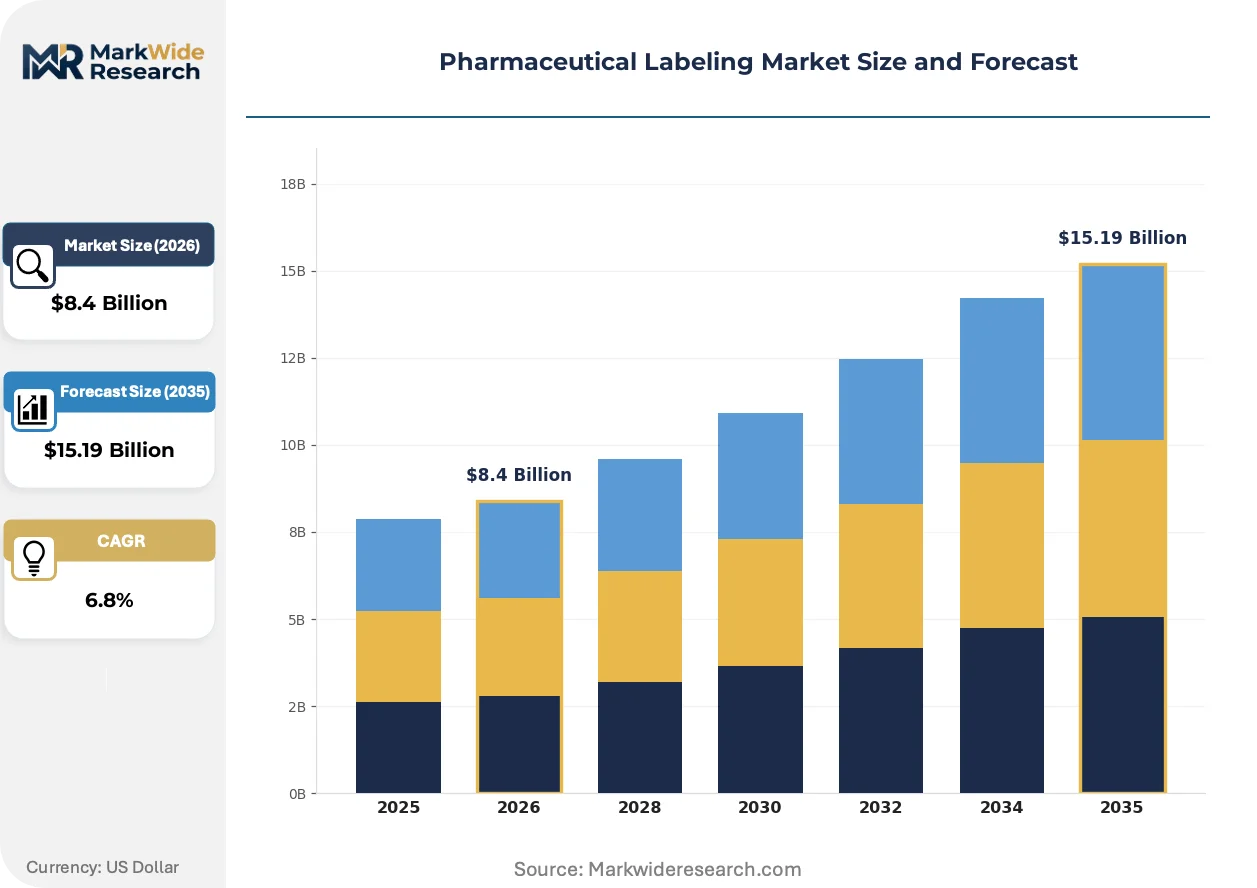
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive Labels, Shrink Sleeves, In-Mold Labels, Security Labels End User: Pharmacies, Hospitals, Drug Manufacturers, Contract Packaging Organizations Technology: Digital Printing, Flexography, Offset Printing, Lithography Application: Medication Packaging, Compliance Labeling, Product Identification, Anti-Counterfeiting |
| Companies Covered | Avery Dennison Corporation, Schreiner Group GmbH & Co. KG, CCL Industries Inc., Multi-Color Corporation, Nosco, Inc., Schreiner MediPharm, 3M Company, Zebra Technologies Corporation, UPM Adhesive Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Labeling Market Strategic Shifts & Innovations
Digital printing technologies are compressing production economics for short-run pharmaceutical labels, while regulatory mandates accelerate functional integration beyond conventional identification.
UV inkjet printing with pharmaceutical-grade low-migration inks is supplanting flexographic methods for clinical trial materials and orphan drug runs. Contract manufacturers serving Phase I-III studies adopt single-pass digital presses to eliminate plate costs and reduce changeover times from hours to minutes. This shift is compressing minimum order quantities and enabling economic production of 500-unit lots.
FDA DSCSA stabilization periods have concluded, forcing wholesale distributors to reject non-compliant shipments after verification system testing phases ended. Drug manufacturers now embed 2D Data Matrix codes with unique product identifiers at the smallest saleable unit. High-value specialty pharmaceuticals distributed through parallel trade channels face the strictest enforcement, with pedigree documentation now mandatory for reimbursement eligibility.
Biologics manufacturers now specify substrate-to-software integration capabilities as primary vendor selection criteria rather than unit pricing. Label partners must demonstrate direct API connectivity to SAP ATTP and TraceLink networks. Germany's contract packaging organizations lead this specification intensity, requiring real-time production data feeds for regulatory audit trails.
Pharmaceutical Labeling Market Segmentation
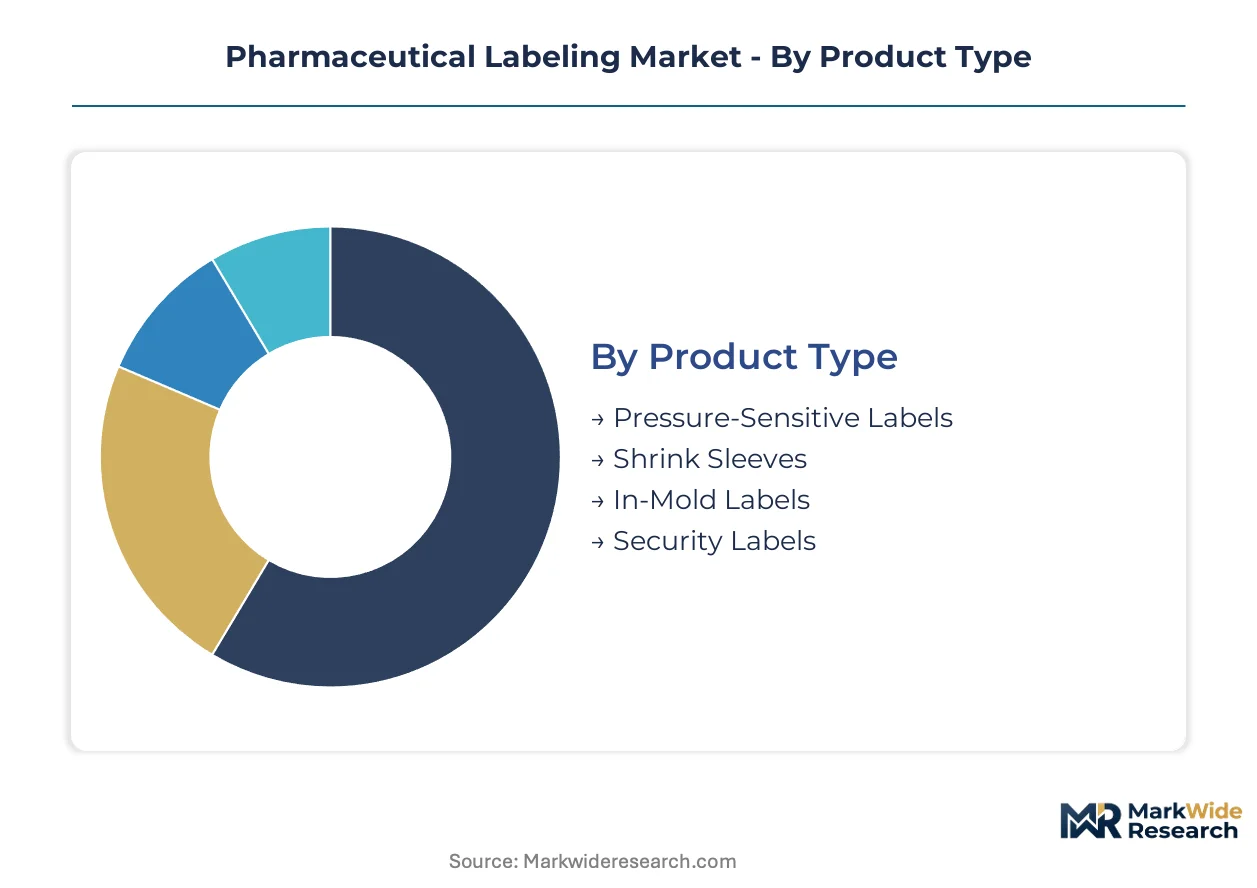
Segmentation in pharmaceutical labeling reveals how regulatory complexity and supply chain specialization fragment procurement decisions. Drug manufacturers select label formats based on serialization mandates, cold-chain requirements, and distribution channel authentication needs rather than unit cost alone.
Product Type:
Channel mix varies sharply by product type: pressure-sensitive labels flow through all distribution tiers, while security labels concentrate in parallel trade and high-value specialty channels.
- Pressure-Sensitive Labels:Multi-layer constructions of facestock, adhesive, and liner that conform to vials, syringes, and folding cartons without heat activation. Demand concentrates among German contract packaging organizations serving Heidelberg and Munich biologics clusters, driven by versatility across primary and secondary packaging formats.
- Security Labels:Tamper-evident substrates incorporating holographic foils, void patterns, or destructible adhesives for authentication at point of dispensing. Parallel trade channels in the European Union absorb the bulk of volume, compelled by EU Falsified Medicines Directive pedigree requirements for reimbursement eligibility.
- Shrink Sleeves:Heat-contractible polymer films providing 360-degree coverage for complex container geometries.
- In-Mold Labels:Polypropylene films fused directly into blow-molded pharmaceutical containers during manufacturing.
Pressure-sensitive labels dominate installed base. Security labels are where expansion concentrates.
End User:
Cost tier segmentation separates high-volume generic manufacturers from premium biologics specialists with stringent cold-chain documentation requirements.
- Drug Manufacturers:Integrated pharmaceutical companies with captive label specification authority and direct ERP-to-press connectivity demands. Serialization infrastructure investments by FDA-regulated entities and EU Falsified Medicines Directive compliance deadlines drive specification intensity.
- Contract Packaging Organizations:Third-party packagers serving multiple drug sponsors with rapid changeover requirements and multi-language booklet label expertise. German CPOs around Heidelberg and Munich anchor specialized procurement for high-value injectables with real-time audit trail obligations.
- Pharmacies:Retail and institutional dispensers requiring unit-dose verification capability at point of sale.
- Hospitals:Inpatient facilities with barcode medication administration systems and patient-specific dosing workflows.
Drug manufacturers control specification authority. Contract packaging organizations are climbing the fastest.
Technology:
Volume concentration favors flexography for long-run commercial products, while digital printing captures clinical trial and orphan drug applications with lot sizes below 10,000 units.
- Digital Printing:Variable-data inkjet and toner systems eliminating plate costs and enabling lot-size compression to 500-unit minimums. Clinical trial materials and adaptive study designs in North America and Western Europe absorb capacity, compelled by patient-specific dosing instructions and protocol amendments.
- Flexography:Rotary relief printing with photopolymer plates for high-speed production of standardized commercial labels. Established drug manufacturers with stable SKUs and annual volumes above 50 million units sustain demand.
- Offset Printing:Lithographic transfer for premium carton and insert applications requiring fine halftone reproduction.
- Lithography:Planographic methods for high-volume booklet labels with dense regulatory text.
Flexography dominates installed base. Digital printing is where expansion concentrates.
Application:
Geographic regulatory intensity determines application prioritization, with anti-counterfeiting layers mandatory in European Union and United States distribution networks.
- Anti-Counterfeiting:Multi-layer label architectures integrating 2D Data Matrix codes, RFID inlays, or NFC layers for smartphone authentication. High-value specialty pharmaceuticals in parallel trade channels absorb investment, compelled by FDA DSCSA enforcement and EU reimbursement pedigree requirements.
- Compliance Labeling:Serialized substrates with unique product identifiers, tamper-evident features, and multi-language regulatory text for market authorization. German packaging clusters specify these most intensively, driven by EMA centralized procedure requirements and export documentation complexity.
- Medication Packaging:Primary container identification with dosage, route, and stability information.
- Product Identification:Secondary packaging labels with trade name, strength, and package quantity for logistics.
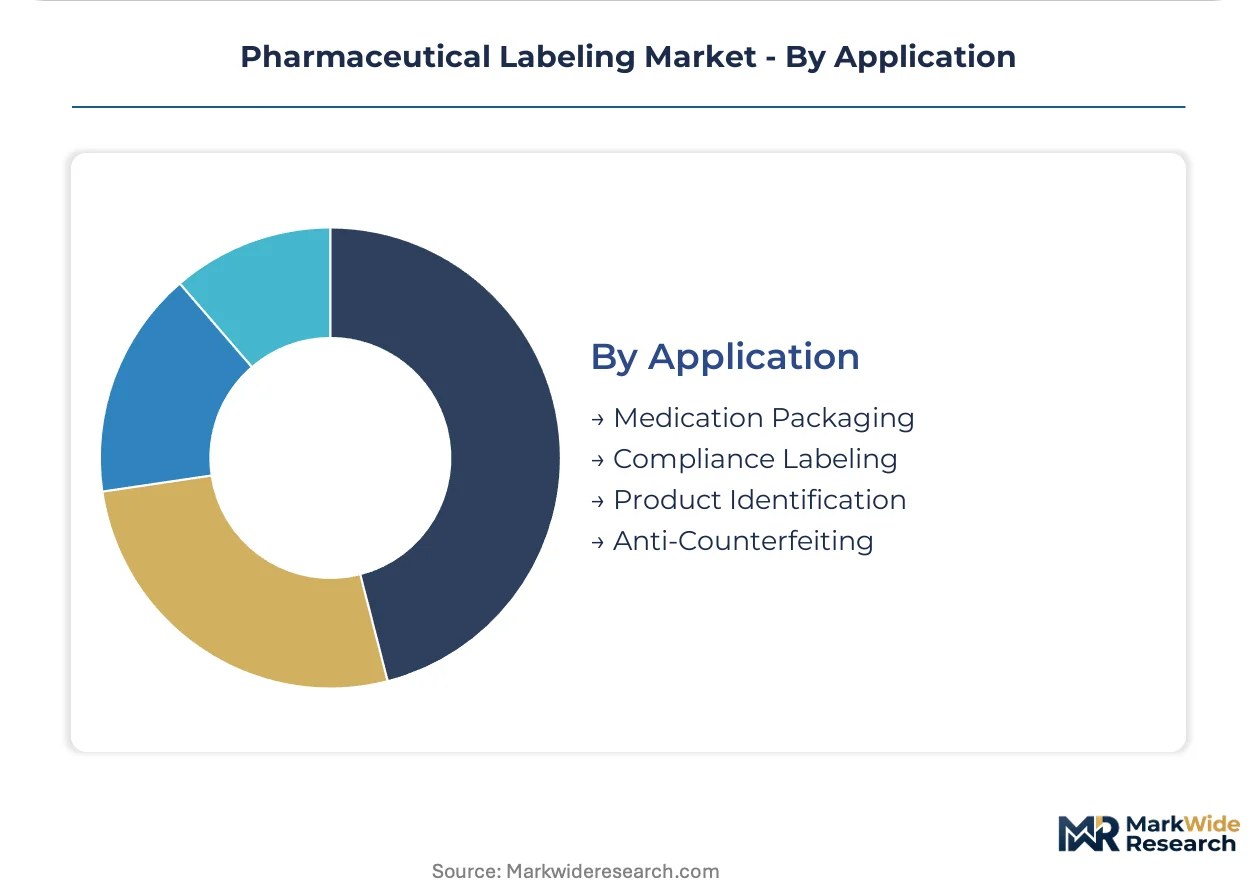
Compliance labeling dominates installed base. Anti-counterfeiting is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-heavy pharmaceutical manufacturing clusters in Germany and Switzerland drive specialized label procurement, while import-dependent markets in Brazil and India expand serialization infrastructure to align with traceability mandates. Trade flows concentrate around cold-chain biologics corridors linking European production hubs to North American and Asian distribution networks.
United States
FDA DSCSA enforcement deadlines compel wholesale distributors to reject non-compliant shipments, accelerating demand for unit-dose verification labels. The Drug Supply Chain Security Act mandates 2D Data Matrix codes at the smallest saleable unit by 2023. New Jersey and Massachusetts biopharma corridors anchor specialized procurement for high-value injectables with real-time audit trail obligations.
Germany
EMA centralized procedure requirements and export documentation complexity drive specification intensity for multi-language booklet labels. Heidelberg and Munich packaging clusters concentrate contract manufacturing for temperature-sensitive biologics requiring substrates validated from -80°C to +25°C. German contract packaging organizations lead European demand for SAP ATTP and TraceLink network integration.
Switzerland
Swissmedic regulatory alignment with EU Falsified Medicines Directive expands serialization-ready label demand for parallel trade channels. Basel's pharmaceutical headquarters density creates concentrated procurement for pedigree documentation required for reimbursement eligibility. Swiss manufacturers specify anti-counterfeiting layers combining holographic foils with tamper-evident void patterns.
Brazil
ANVISA track-and-trace mandates following EU and US models create first-mover advantage for serialization-ready label suppliers. São Paulo's pharmaceutical manufacturing corridor drives demand for GS1-compliant 2D Data Matrix integration. Brazilian distributors now require Portuguese-language pedigree documentation for high-value specialty pharmaceuticals.
India
CDSCO alignment with international traceability standards accelerates investments in smart label infrastructure for export-oriented generic manufacturers. Hyderabad and Ahmedabad pharmaceutical clusters expand digital printing capacity for clinical trial materials serving North American and European sponsors. Indian contract research organizations adopt variable-data booklet labels for adaptive study designs.
Pharmaceutical Labeling Market Key Industry Players
Listed leaders compete with private specialists across materials science and functional label architectures. The vendor base spans multi-continent converters with manufacturing scale and regional specialists with substrate-to-software integration capabilities. Three archetypes dominate: diversified materials conglomerates with adhesive science portfolios, dedicated pharmaceutical label converters with serialization expertise, and digital printing technology providers with cloud-based verification platforms. Competitive moves center on backward integration into pharmaceutical-grade adhesive production and strategic partnerships with track-and-trace software vendors.
Within the diversified materials tier, Avery Dennison Corporation and 3M Company occupy positions anchored by permanent acrylic adhesive portfolios validated for sterilization and chemical exposure. CCL Industries Inc. exemplifies the multi-continent converter archetype with manufacturing footprint spanning commercial label demand across regulatory jurisdictions. Schreiner MediPharm and Schreiner Group GmbH & Co. KG represent the functional specialization vector, with family-owned structure enabling rapid prototyping of RFID-NFC integrated architectures for cold-chain verification.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Schreiner Group GmbH & Co. KG |
| CCL Industries Inc. |
| Multi-Color Corporation |
| Nosco, Inc. |
| Schreiner MediPharm |
| 3M Company |
| Zebra Technologies Corporation |
| UPM Adhesive Materials |
| Others |
Cost & Logistics Intelligence
FDA DSCSA verification mandates and EU Falsified Medicines Directive compliance tiers gate both supplier qualification and price differentiation simultaneously, forcing drug manufacturers to pay premiums for serialization-ready substrates while disqualifying converters lacking SAP ATTP or TraceLink integration capabilities.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in pharmaceutical labeling. Price differentiation rests on certification grade — GS1-compliant serialization validation versus basic adhesive performance — and volume scale for long-run commercial products versus short-run clinical trial materials. Cost compression in standard-tier pressure-sensitive labels is intensifying because acrylic polymer feedstock costs fluctuate with petrochemical markets. Generic drug manufacturers exhibit highest price sensitivity, while biologics specialists prioritize substrate-to-software integration over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate German and Swiss contract packaging organizations serving Heidelberg, Munich, and Basel pharmaceutical clusters, while strategic stockpiling of specialized cold-chain substrates persists among North American biologics manufacturers. Geographic supply concentration centers on Germany, Switzerland, and the United States for high-performance adhesive substrates. Raw material dependencies draw from acrylic polymer feedstocks, pharmaceutical-grade release liners, and RFID inlay components. Single-source vulnerability for digital printing press manufacturers in Western Europe and Japan creates structural supply risk. Distribution runs through direct ERP-to-press integration channels rather than spot-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical labeling sits in early-cycle expansion as FDA DSCSA enforcement deadlines and EU Falsified Medicines Directive unit-dose verification requirements drive mandatory infrastructure replacement across wholesale distribution networks.
For Market Incumbents: Secure backward integration into pharmaceutical-grade adhesive production to defend margins against petrochemical feedstock volatility. Lock in multi-year serialization infrastructure contracts with German and Swiss contract packaging organizations before ANVISA mandates replicate EU compliance intensity in Brazil. Prioritize API connectivity certification for SAP ATTP and TraceLink networks as the primary competitive moat against emerging digital printing specialists. For New Entrants and Emerging Players: Anchor in Brazil's São Paulo pharmaceutical corridor where ANVISA track-and-trace mandates create first-mover advantage for serialization-ready label suppliers before incumbent converters establish local capacity. Target clinical trial personalization services with variable-data booklet label capabilities for adaptive study designs in North America. Lead with cloud-based verification platform partnerships rather than capital-intensive manufacturing scale. For Investors and Strategic Acquirers: FDA DSCSA stabilization enforcement reshapes the acquisition landscape toward converters with proven serialization infrastructure and regulatory audit trail capabilities. Five-to-ten year viability favors specialized pharmaceutical label converters over diversified materials conglomerates lacking substrate-to-software integration depth. Monitor wholesale distributor rejection rates for non-compliant shipments as the critical inflection signal for serialization infrastructure demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Production | Captive supply of pharmaceutical-grade acrylics insulates margins from petrochemical volatility affecting German and Swiss converters. |
| SAP ATTP API Certification | Direct ERP-to-press connectivity meets Heidelberg and Munich contract packaging organization requirements for real-time audit trails. |
| RFID-NFC Layer Integration | Smartphone-based patient authentication aligns with EU Falsified Medicines Directive pedigree requirements for parallel trade channels. |
| Digital Printing Platform Deployment | Single-pass UV inkjet capacity captures clinical trial and orphan drug demand with 500-unit minimum order quantities in North America. |
| Brazil Market Entry Partnership | ANVISA serialization readiness creates first-mover positioning before incumbent converters establish São Paulo manufacturing footprint. |
Research Approach
Desk research of FDA DSCSA guidance documents, EMA centralized procedure filings, and pharmaceutical trade customs data preceded structured interviews with drug development executives, regulatory affairs leads, contract packaging procurement managers, and serialization infrastructure specialists. Secondary validation drew from ClinicalTrials.gov adaptive study design filings, SEC 10-K disclosures from listed label converters, and GS1 healthcare implementation guidelines. Bottom-up demand modeling across dosage forms and administration routes triangulated against top-down pharmaceutical packaging expenditure estimates.
Variance decomposition across product type, end user, technology, and application segments structured the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by regulatory compliance intensity and cold-chain expansion rates. Treatment line positioning and regional regulatory cluster adoption curves served as industry-specific forecast inputs for biologics versus generic drug label demand divergence.
Material uncertainties — adhesive raw material cost volatility, serialization technician scarcity, and legacy infrastructure interoperability failures — sit outside the modeled envelope. Forecasts reflect assumptions regarding FDA and EMA enforcement consistency, ANVISA mandate timing alignment, and GS1 standard adoption rates across pharmaceutical supply chains. Revision becomes warranted when wholesale distributor rejection rates for non-compliant shipments cross thresholds indicating accelerated compliance infrastructure replacement cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Packaging Equipment Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Nutraceutical Packaging Market
Pharmaceutical Packaging
Parenteral Drugs Packaging Market
Pharmaceutical Packaging
Global Ampoules Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Vials Market
Pharmaceutical Packaging
Nasal Spray Packaging Market
Pharmaceutical Packaging
United States Ampoules Packaging Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
Advanced Empty Capsule Market
Pharmaceutical Packaging
Pharmaceutical Secondary Packaging Market
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
Prescription Pharmacy Bags Market
Pharmaceutical Packaging
North America Ampoules Packaging Market
Pharmaceutical Packaging
Corrugated Pharmaceutical Packaging Market