
 North America Pharmaceutical Vials Market | 2026-2036
North America Pharmaceutical Vials Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pharmaceutical Vials Market Analytics
Mexico is narrowing its cost advantage as a nearshore production base for borosilicate glass conversion, prompting contract packaging firms to reassess sourcing footprints. Gerresheimer AG leverages its multi-site North American network to sustain just-in-time delivery for parenteral drug clients. West Pharmaceutical Services differentiates through integrated containment and delivery systems that extend beyond standalone vial supply. Corning Incorporated anchors high-value pharmaceutical glass production with advanced forming technologies that reduce particle contamination risks.
Pharmaceutical vials are sealed, sterile containers manufactured from borosilicate glass or polymer resins, designed to maintain drug stability, prevent moisture ingress, and enable aseptic filling at volumes typically ranging from 2 mL to 100 mL. Their primary purpose centers on protecting injectable and biologic formulations from degradation while ensuring compatibility with automated fill-finish lines and patient-administered delivery systems. Glass vials command the dominant share of parenteral applications where inertness and barrier properties remain non-negotiable, while plastic vials gain traction in oral medication and diagnostic segments where breakage tolerance and weight reduction drive value. The injectables application generates the deepest margin pools as regulatory scrutiny around extractables and leachables intensifies qualification requirements for container materials.
FDA container closure integrity guidelines, USP Chapter 1207 on package integrity evaluation, and Health Canada ICH Q1A stability testing requirements collectively elevate barrier performance standards and documentation burdens for vial suppliers seeking market access. These frameworks compel manufacturers to invest in validated testing infrastructure and traceable supply chains, particularly for borosilicate glass sourced from limited qualified foundries. Stakeholders must monitor how evolving USP and FDA guidance on visible particulate limits and glass delamination risks reshapes material substitution timelines and supplier qualification protocols.
Market Dynamics
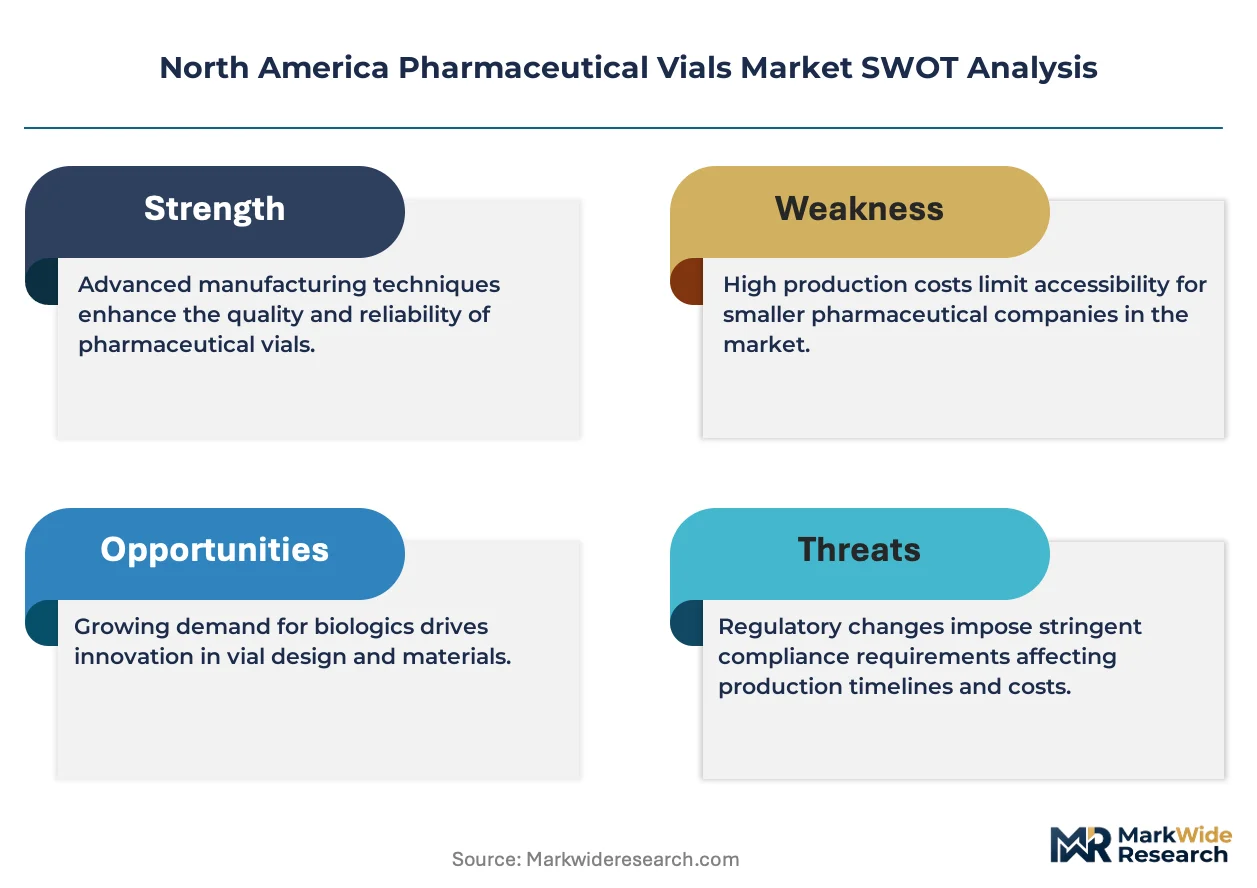
Biologics manufacturers face intensifying pressure from FDA container closure integrity standards, forcing accelerated migration toward ready-to-use formats and validated barrier technologies across parenteral packaging operations.
Growth Catalysts
- FDA Quality Standards:Tightening container closure integrity requirements under USP Chapter 1207 compel manufacturers to upgrade validation infrastructure, expanding demand for pre-qualified, ready-to-use vial systems that reduce qualification timelines.
- Northeast Pharmaceutical Corridor:Contract packaging operations concentrate in New Jersey and Massachusetts to serve adjacent biologics development hubs, creating dense demand clusters for sterile vial supply with just-in-time delivery requirements.
- Glass Delamination Risk Mitigation:Advanced borosilicate forming technologies reduce particle contamination incidents, qualifying suppliers for high-value parenteral applications where extractables and leachables scrutiny is most severe.
Market Restraints
- Qualified Foundry Concentration:Borosilicate glass sourcing depends on a limited network of validated foundries, creating supply vulnerability when any single facility faces contamination events or capacity constraints.
- Mexico Cost Erosion:Nearshore conversion economics narrow as energy and logistics costs rise, compressing the margin advantage that previously drove sourcing footprint expansion into Mexican manufacturing zones.
- Regulatory Documentation Burden:Health Canada ICH Q1A stability testing requirements and FDA traceability mandates extend supplier qualification cycles, delaying market entry for new vial formats and material innovations.
Strategic Opportunities
- Plastic Vial Expansion:Polymer resin formulations gain traction in oral medication and diagnostic segments where breakage tolerance and weight reduction outweigh barrier performance requirements of glass alternatives.
- Integrated Containment Systems:Convergence of vial supply with delivery device engineering creates value pools beyond standalone container sales, particularly for self-administered biologics in home care settings.
- Diagnostic Segment Penetration:Underdeveloped demand for polymer vials in molecular diagnostics and point-of-care testing applications offers volume growth outside traditional pharmaceutical channels.
Industry Challenges
- Automated Fill-Finish Integration:Vial dimensional tolerances must align with high-speed aseptic filling lines, requiring precision manufacturing that strains quality systems and drives rework rates.
- Particle Detection Capability Gap:Visible particulate limits under evolving USP guidance demand capital-intensive inspection infrastructure that mid-tier suppliers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pharmaceutical Vials Market |
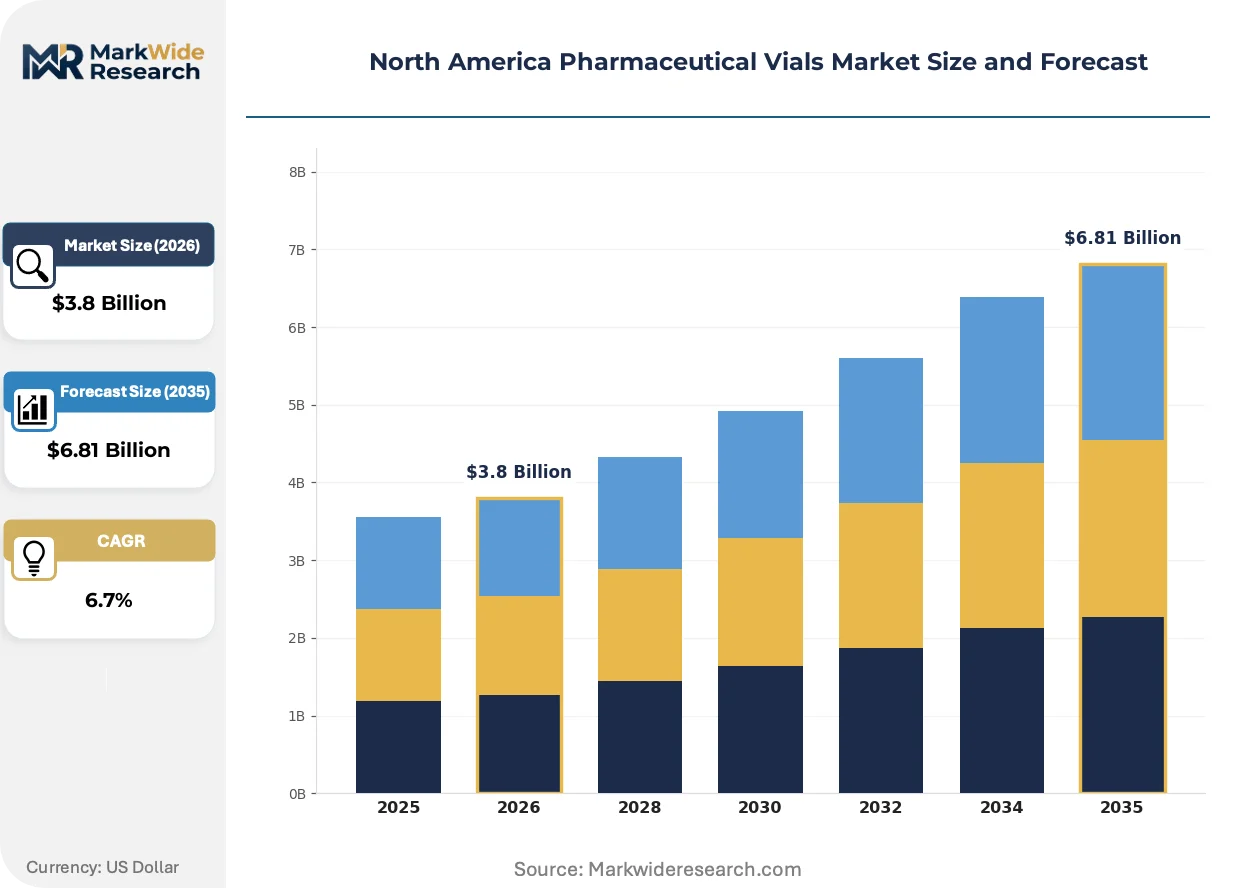
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Vials, Plastic Vials, Clear Vials, Amber Vials Material: Polypropylene, Polyethylene, Borosilicate Glass, PVC End User: Hospitals, Pharmaceutical Companies, Research Laboratories, Contract Packaging Application: Injectables, Oral Medications, Diagnostics, Veterinary Use |
| Companies Covered | Schott Pharma, Gerresheimer AG, West Pharmaceutical Services, Stevanato Group, SGD Pharma, Berlin Packaging, Pacific Vial Manufacturing Inc., Corning Incorporated, Adelphi Healthcare Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pharmaceutical Vials Market Evolving Landscape
Digital traceability and advanced forming technologies are compressing quality assurance timelines while reshaping how sterile packaging integrates with automated drug manufacturing workflows across North American production networks.
Laser-based container closure integrity testing is digitizing validation protocols for parenteral vial manufacturers. Biologics contract manufacturers adopt these systems at accelerating rates to preempt FDA inspection findings. The technology is digitizing documentation trails that previously required manual sampling, compressing batch release cycles from weeks to days.
Health Canada harmonization with FDA container closure integrity guidelines tightens cross-border compliance requirements for suppliers serving both markets. The regulatory convergence forces dual-qualified manufacturing lines and unified documentation systems. Parenteral applications face the steepest compliance costs, driving consolidation toward multi-site suppliers with established North American regulatory track records.
Consolidated procurement by large biopharma customers concentrates contract packaging decisions among fewer decision-makers with standardized technical specifications. Long-term supply agreements with integrated containment providers displace spot purchasing of standalone vials. Massachusetts and New Jersey biologics clusters exhibit the most pronounced buyer concentration, where single procurement teams manage global packaging specifications.
North America Pharmaceutical Vials Market Segmentation
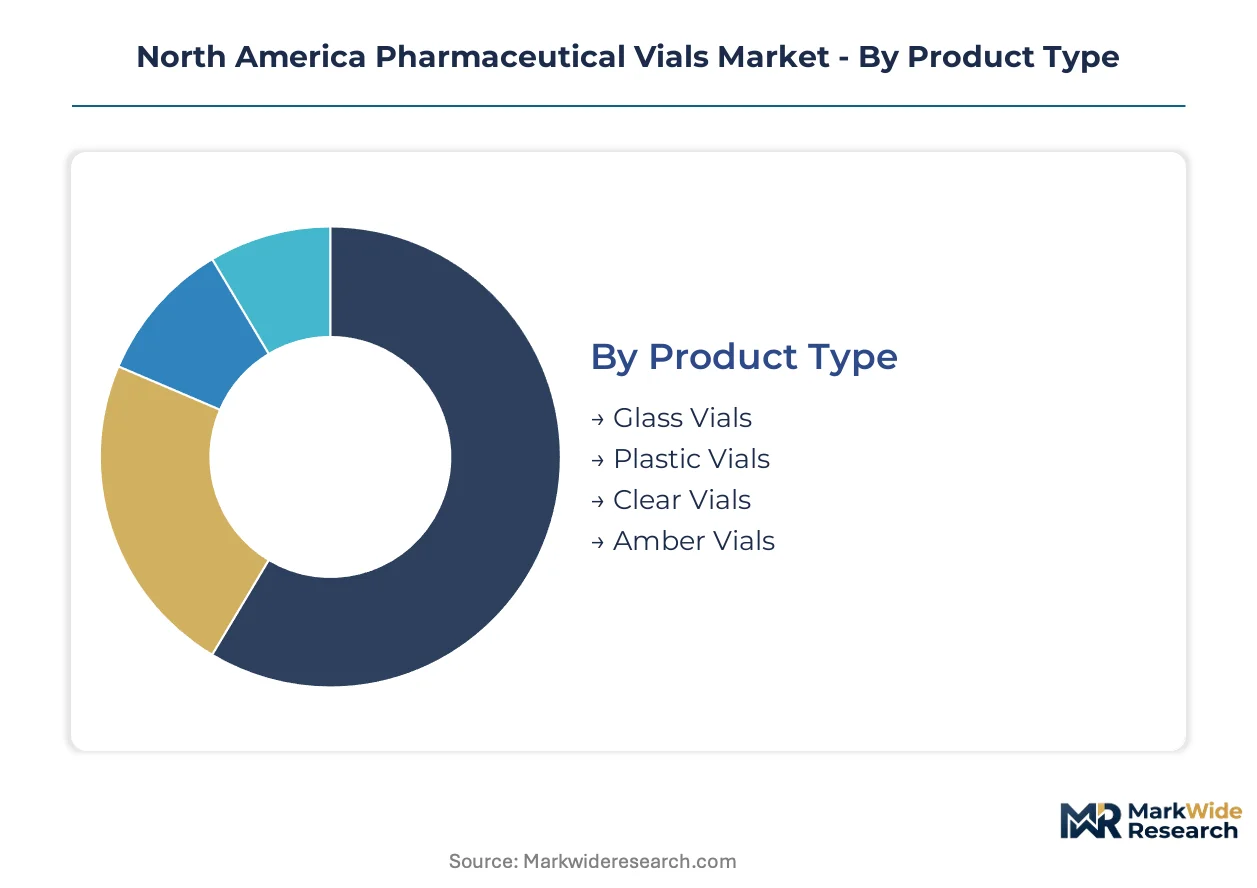
Pharmaceutical vial segmentation in North America tracks divergent technical requirements across parenteral safety standards and cost-sensitive diagnostic channels. Material selection and end-use specifications create distinct competitive arenas with incompatible qualification protocols.
Product Type:
Mature glass formats dominate high-barrier parenteral applications while polymer alternatives carve out volume in cost-driven segments.
- Glass Vials:Borosilicate construction delivers inert barrier properties essential for biologics stability and FDA container closure integrity compliance. Northeast pharmaceutical corridor manufacturers specify these for parenteral fill-finish lines where extractables scrutiny is most severe.
- Plastic Vials:Polymer resin formulations reduce breakage risk and shipping weight for oral medications and diagnostic reagents. Contract packaging operations in Mexico and the southern United States are expanding polymer conversion capacity for non-parenteral applications where barrier demands relax.
- Clear Vials:Visual inspection compatibility drives selection for protein-based injectables requiring particulate monitoring.
- Amber Vials:UV-light protection for photosensitive formulations in hospital pharmacy compounding and research settings.
Glass Vials handles the majority of throughput; Plastic Vials is the fastest mover on share.
Material:
Supply concentration in qualified borosilicate foundries contrasts with dispersed polymer resin sourcing across petrochemical networks.
- Borosilicate Glass:Schott and Corning anchor North American production with advanced forming technologies that reduce delamination risks. FDA qualification requirements limit viable suppliers to a handful of validated facilities, creating procurement bottlenecks during capacity constraints.
- Polypropylene:Injection-molded clarity and autoclavability suit diagnostic and veterinary applications where cost efficiency outweighs premium barrier performance. Polypropylene formulations from Gulf Coast resin suppliers feed contract packaging operations seeking alternatives to glass breakage liability.
- Polyethylene:Flexible squeeze designs for oral medication unit-dose packaging in retail pharmacy channels.
- PVC:Legacy use in specific diagnostic and blood collection applications with declining share due to environmental and extractables concerns.
Borosilicate Glass commands the premium tier; Polypropylene is expanding most quickly into glass-substitution opportunities.
End User:
Procurement concentration among large biopharma customers fragments the vendor landscape across integrated and spot-purchasing channels.
- Pharmaceutical Companies:Integrated containment specifications and long-term supply agreements with vial-device combination providers. Massachusetts and New Jersey biologics clusters consolidate procurement decisions among single technical teams managing global packaging standards.
- Contract Packaging:Just-in-time delivery requirements and validated sterile filling infrastructure drive supplier selection. Northeast corridor operations cluster near development hubs to compress logistics timelines for clinical trial materials and commercial launches.
- Hospitals:Unit-dose and compounding applications with fragmented purchasing through group purchasing organizations.
- Research Laboratories:Small-volume, high-SKU demand for preclinical and analytical applications.
Pharmaceutical Companies represent the deepest margin pool; Contract Packaging is gaining share fastest through outsourcing trends.
Application:
Regulatory intensity stratifies applications from validated parenteral systems to commoditized diagnostic containers.
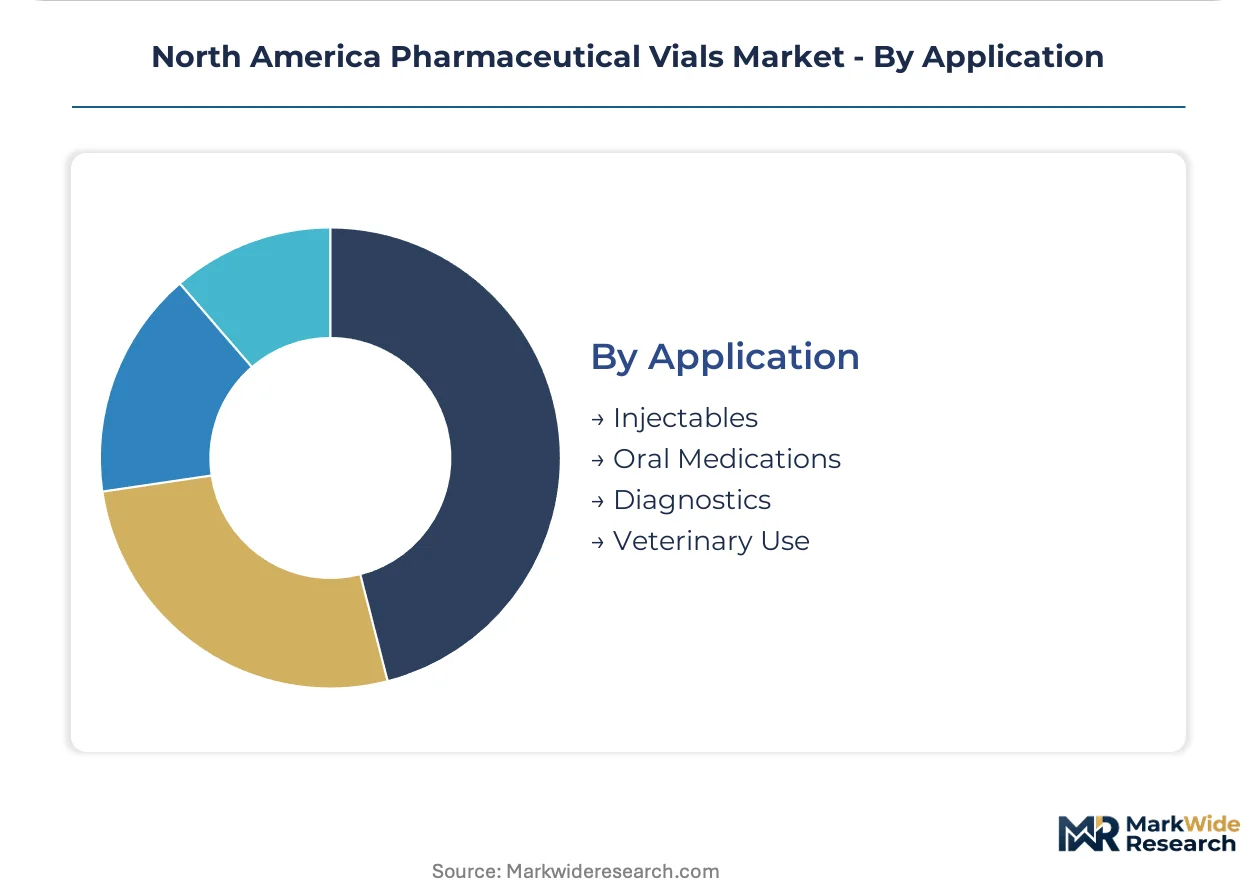
- Injectables:USP Chapter 1207 container closure integrity requirements and visible particulate limits impose capital-intensive inspection infrastructure. Biologics manufacturers in the United States specify ready-to-use formats to compress qualification timelines under tightening FDA scrutiny.
- Diagnostics:Polymer vial penetration in molecular diagnostics and point-of-care testing creates volume growth outside traditional pharmaceutical channels. Diagnostic reagent manufacturers prioritize breakage tolerance and shipping efficiency over glass barrier properties.
- Oral Medications:Unit-dose and compliance packaging for specialty pharmaceuticals with moderate barrier requirements.
- Veterinary Use:Cost-driven specifications with reduced regulatory documentation burdens compared to human pharmaceuticals.
Injectables absorbs the majority of qualification investment; Diagnostics is climbing the fastest on volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Newark-Elizabeth Marine Terminal anchors North American pharmaceutical vial distribution, handling containerized glass imports from European foundries and resin feedstocks from Gulf Coast petrochemical complexes. This infrastructure underwrites just-in-time supply chains serving the Northeast pharmaceutical corridor.
United States
FDA container closure integrity guidelines and USP Chapter 1207 requirements drive demand for pre-qualified ready-to-use vial systems among biologics manufacturers. The Northeast pharmaceutical corridor spanning New Jersey and Massachusetts concentrates contract packaging operations adjacent to major drug development hubs. Massachusetts biologics clusters consolidate procurement decisions among single technical teams managing global packaging standards.
Canada
Health Canada ICH Q1A stability testing requirements harmonize with FDA guidelines, tightening cross-border compliance for suppliers serving both markets. The country's national pharmaceutical regulator mandates unified documentation systems that extend qualification cycles. Ontario contract packaging operations near Toronto serve as secondary supply nodes for U.S. biopharma customers seeking geographic diversification.
Mexico
Rising energy and logistics costs narrow nearshore conversion economics for borosilicate glass fabrication that previously attracted contract packaging investment. The country's national pharmaceutical regulator maintains alignment with FDA traceability standards while allowing reduced documentation burdens for non-parenteral applications. Bajío Region polymer conversion facilities expand capacity for oral medication and diagnostic vial formats.
North America Pharmaceutical Vials Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a structure where consolidated procurement by large biopharma customers concentrates vendor selection among fewer decision-makers. The market exhibits tiered consolidation with multi-site suppliers holding advantage over single-facility operators. Two strategic archetypes dominate: integrated containment providers bundling vial-device combinations, and standalone glass converters competing on qualification speed. Capacity expansion and strategic partnerships constitute the primary competitive moves as suppliers seek to secure long-term supply agreements.
Within the integrated containment tier, West Pharmaceutical Services and Gerresheimer AG exemplify platform integrators extending beyond standalone vial supply into delivery system engineering. Corning Incorporated anchors high-value pharmaceutical glass production with advanced forming technologies. Schott Pharma occupies a position among validated borosilicate foundries serving parenteral applications where FDA qualification requirements limit viable supplier pools.
| Leading Market Players |
|---|
| Schott Pharma |
| Gerresheimer AG |
| West Pharmaceutical Services |
| Stevanato Group |
| SGD Pharma |
| Berlin Packaging |
| Pacific Vial Manufacturing Inc. |
| Corning Incorporated |
| Adelphi Healthcare Packaging |
| Others |
Value Network & Pricing Analysis
Undercapacity in qualified borosilicate glass foundries concentrates pricing power among validated suppliers serving FDA-regulated parenteral applications. Contract packaging operations in the Northeast pharmaceutical corridor absorb premium pricing for ready-to-use formats while Mexican conversion facilities compete on cost for non-sterile polymer alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-qualified ready-to-use glass systems from validated bulk formats and commodity polymer containers. Price differentiation hinges on certification grade against USP Chapter 1207 and container closure integrity validation depth. Pricing pressure stems from Mexico's narrowing cost advantage as energy and logistics expenses rise. Contract packaging operations exhibit highest price sensitivity for standard-tier glass, while biologics manufacturers show lowest sensitivity for premium qualified systems.
Supply Chain Analysis
Contract manufacturing concentration among Gerresheimer AG, West Pharmaceutical Services, and Corning Incorporated anchors North American sterile vial capacity. Geographic supply concentration centers on United States, Germany, and Mexico for borosilicate conversion and polymer molding. Raw material dependencies include European-sourced borosilicate glass tubing, Gulf Coast petrochemical resin feedstocks, and specialized coating chemistries. Single-source vulnerability in qualified foundry networks creates supply risk during contamination events. Distribution runs through the Port of Newark-Elizabeth Marine Terminal for just-in-time delivery to Northeast pharmaceutical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable switching costs. FDA qualification requirements and validated supply chain documentation erect barriers that protect incumbent positions.
For Market Incumbents: Harden barrier positions through backward integration into borosilicate glass forming and captive coating capabilities. Expand multi-site North American footprints to mitigate single-source foundry risk. Consolidate procurement relationships with Massachusetts and New Jersey biologics clusters through integrated containment system bundling.
For New Entrants and Emerging Players: Diagnostic polymer vials in point-of-care and molecular testing applications represent the most penetrable entry point with reduced FDA documentation burdens. Mexico-based polymer conversion for oral medication formats offers nearshore volume building. Pursue toll manufacturing partnerships with established sterilization facilities to bypass capital-intensive aseptic infrastructure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated containment providers with long-term supply agreements. Five-to-ten year viability favors multi-site suppliers with established FDA track records and validated borosilicate sourcing relationships. Monitor Health Canada-FDA regulatory harmonization progress as inflection signal for cross-border consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Site Capacity Expansion | Reduces single-source vulnerability in qualified borosilicate glass networks serving FDA-regulated parenteral clients. |
| Integrated Containment System Development | Extends value capture beyond standalone vials into combination products for self-administered biologics. |
| Diagnostic Segment Polymer Conversion | Captures volume growth in molecular diagnostics and point-of-care testing outside traditional pharmaceutical channels. |
| Laser-Based Container Closure Integrity Validation | Compresses batch release cycles from weeks to days for biologics contract manufacturers facing FDA scrutiny. |
| Long-Term Supply Agreement Consolidation | Locks in procurement relationships with concentrated biopharma buyers in Massachusetts and New Jersey clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biologics development executives, regulatory affairs leads, contract packaging operations managers, and sterile fill-finish engineers. Secondary validation drew from FDA container closure integrity guidance documents, USP Chapter 1207 technical standards, Health Canada ICH Q1A stability testing requirements, and SEC filings of publicly traded packaging suppliers. Bottom-up volume modeling triangulated against top-down market sizing across material, application, and end-user segmentation dimensions.
Calibration against historical capacity utilization rates in qualified borosilicate foundries and documented contract packaging expansion timelines anchored projection reliability. Segmentation modeling spanned product type, material chemistry, end-user archetype, and application regulatory intensity across the analysis window. CAGRs were derived from trend extrapolation of fill-finish automation adoption, biologics pipeline growth, and regulatory documentation burden trajectories. Forecast inputs incorporated FDA inspection citation patterns and visible particulate limit evolution under USP guidance.
Macroeconomic conditions sit as an overlay; deviation in energy costs, freight rates, or resin feedstock pricing would shift the trajectory of Mexico nearshore economics and polymer conversion investment. Forecasts reflect documented assumptions regarding regulatory harmonization timing and foundry qualification maintenance. Quarterly review of FDA warning letter trends, container closure integrity guidance updates, and borosilicate glass capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Materials Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Dispensing Pharmacy Packaging Machine Market
Pharmaceutical Packaging
Pharmaceutical Vials Market
Pharmaceutical Packaging
Europe Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Laboratory Consumables Primary Packaging Market
Pharmaceutical Packaging
Topical Drugs Packaging Market
Pharmaceutical Packaging
Corrugated Pharmaceutical Packaging Market
Pharmaceutical Packaging
Medical Flexible Packaging Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Active and Intelligent Packaging in Pharmaceutical Market
Pharmaceutical Packaging
China Pharmaceutical Packaging Market