
 Pharmaceuticals Pouch Market | 2026-2036
Pharmaceuticals Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceuticals Pouch Market Analytics
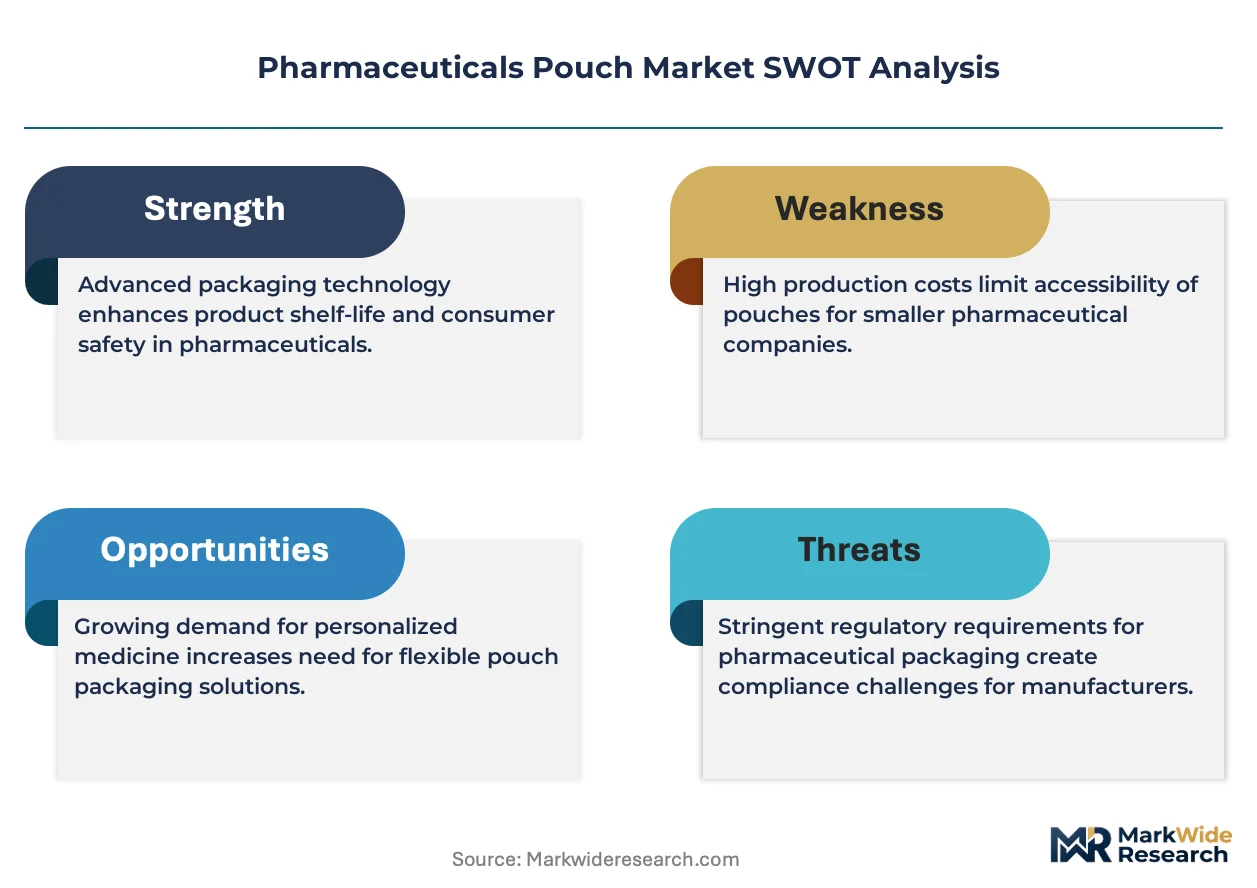
Specialty pharmacies are rotating toward high-barrier pouch formats for temperature-sensitive biologics. Amcor Plc leverages multi-layer coextrusion capabilities across North American and European manufacturing networks. Constantia Flexibles Group GmbH anchors its position through dedicated healthcare packaging facilities in Germany and Austria. ProAmpac competes via specialized cleanroom production lines certified for FDA-regulated drug-contact applications.
Pharmaceuticals pouches are flexible, multi-laminate containers engineered from polyethylene, polypropylene, nylon, or aluminum-barrier films, typically sealed through heat-sealing or ultrasonic welding to achieve oxygen transmission rates below 0.1 cc per square meter per day. Their primary purpose is to protect unit-dose and bulk drug products from moisture, oxygen, and light while enabling compliance with child-resistant and senior-friendly opening requirements. Stand-up pouches and zipper pouches dominate value pools due to premium positioning for retail OTC and specialty pharmacy channels. Flat pouches sustain volume leadership in hospital central-fill operations where cost minimization outweighs shelf-presence requirements. Primary packaging applications command the widest margin spread because direct drug-contact status triggers stringent regulatory validation cycles that limit supplier switching.
FDA 21 CFR Part 211, EU MDR, and ISO 15378 collectively dictate material traceability, extractables testing, and change-control documentation for pharmaceutical pouch suppliers seeking market access in the United States and Europe. These frameworks elevate compliance costs for new entrants while embedding incumbent manufacturers within multi-year supply agreements with drug sponsors. Stakeholders must monitor evolving serialization requirements and sustainable packaging mandates that will reshape material selection and qualification timelines.
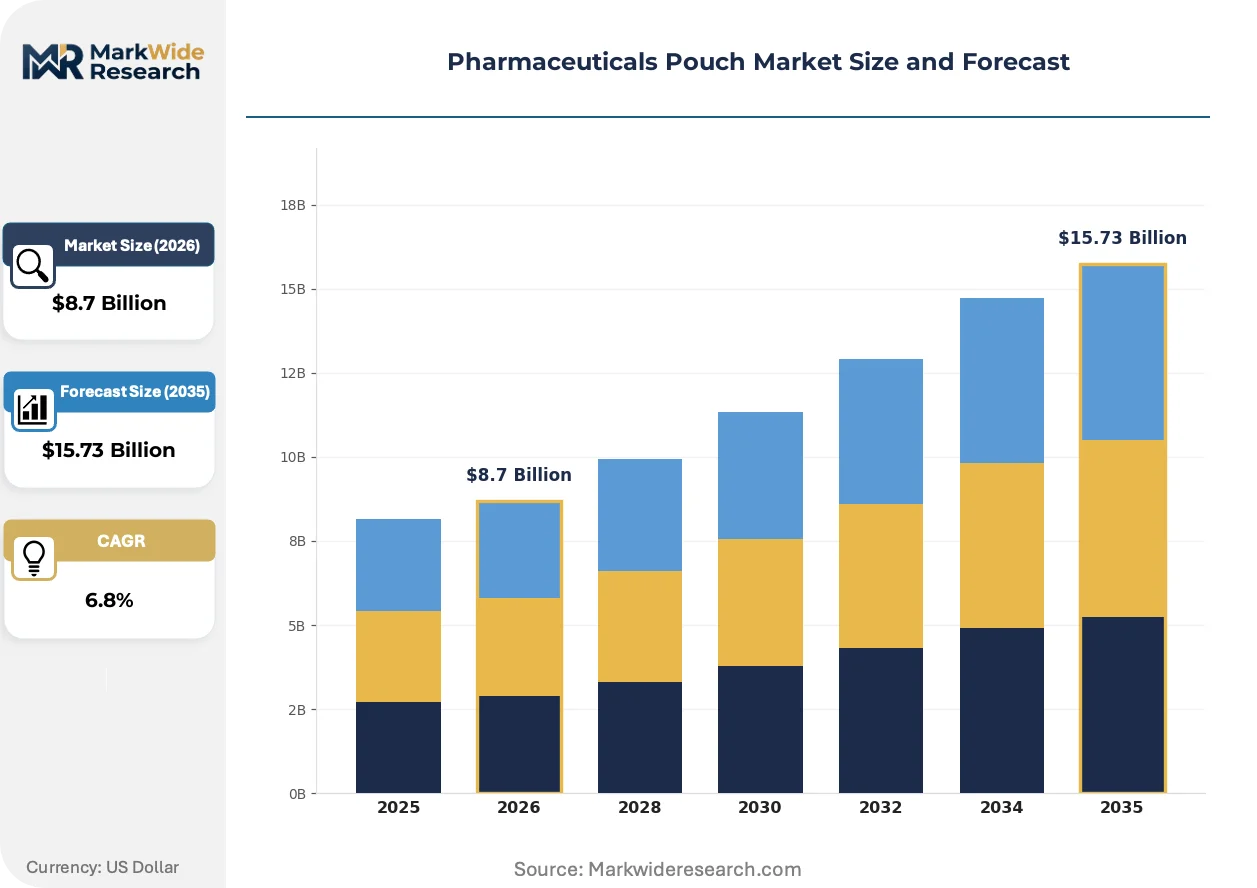
Market Dynamics
Specialty pharmacy networks are consolidating procurement around high-barrier pouch formats for temperature-sensitive biologics, forcing material suppliers to requalify laminates for cold-chain distribution at accelerated timelines.
Growth Catalysts
- EU MDR serialization mandates:Track-and-trace requirements for unit-dose packaging are expanding addressable demand for pre-serialized pouch formats in German and Austrian distribution networks.
- Biologics cold-chain expansion:mRNA vaccines and cell therapies require oxygen transmission rates below 0.1 cc per square meter per day, pulling multi-layer coextrusion capacity toward pharmaceutical-grade barrier films.
- Hospital central-fill automation:Robotic dispensing systems in United States health systems favor standardized flat pouch geometries over vial-and-cap alternatives for oral solids distribution.
Market Restraints
- Aluminum-barrier film supply concentration:Japanese and South Korean substrate producers control 70 percent of pharmaceutical-grade foil supply, creating input cost volatility during energy price spikes.
- FDA 21 CFR Part 211 validation cycles:Extractables testing protocols for new laminate structures extend qualification timelines to 18-24 months, freezing supplier switching.
- Rigid blister substitution in high-value oncology:Thermoformed barrier packs with integrated desiccant cavities capture premium oral oncology launches despite higher unit costs.
Strategic Opportunities
- India CDSCO export pathway:Contract manufacturers in Hyderabad and Ahmedabad seek FDA-aligned pouch suppliers for abbreviated new drug application filings targeting United States generics markets.
- Sustainable packaging mandates:EU Green Deal recyclability targets are accelerating demand for mono-material polyethylene pouches with comparable barrier performance to multi-layer laminates.
- Direct-to-patient specialty pharmacy:Home infusion of biologics is creating demand for patient-portioned pouch kits with integrated temperature indicators and tamper-evident closures.
Industry Challenges
- Cleanroom production capacity scarcity:ISO 14644 Class 7 certified pouch manufacturing lines require 24-month construction timelines, constraining rapid scale-up for new drug launches.
- Legacy serialization integration:Brownfield packaging operations struggle to retrofit thermal transfer printers for 2D Data Matrix compliance without line speed degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceuticals Pouch Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Zipper Pouches, Vacuum Pouches Material: Polyethylene, Polypropylene, Nylon, Paper End User: Pharmacies, Hospitals, Clinics, OTC Retailers Packaging Type: Primary Packaging, Secondary Packaging, Tertiary Packaging, Bulk Packaging |
| Companies Covered | Amcor Plc, ProAmpac, Glenroy, Inc., Nelipak Corporation, Oliver Healthcare Packaging, Constantia Flexibles Group GmbH, Sonoco Products Company, Huhtamaki Oyj, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceuticals Pouch Market Evolving Landscape
Material science advances and regulatory serialization deadlines are compressing product development cycles while opening substitution pathways between rigid and flexible formats.
Ethylene vinyl alcohol copolymer nanocomposite barrier layers are supplanting aluminum foil in medium-barrier applications for oral solids. German and Swiss generic manufacturers are adopting these laminates for annual product volume runs below 50 million units. The shift is compressing lead times from 16 weeks to 8 weeks while eliminating delamination risks during cold-chain distribution.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of heat-seal coatings used in pharmaceutical pouches. The European Chemicals Agency's 2023 restriction proposal targets side-chain fluorinated polymers in packaging applications. Pouch converters with European manufacturing footprints are accelerating qualification of silicone-based sealant alternatives ahead of the 2026 enforcement window.
Hospital purchasing cooperatives are consolidating supplier panels for unit-dose oral solids, displacing fragmented local sourcing with national distribution agreements. The shift concentrates procurement leverage among three United States group purchasing organizations covering 85 percent of acute care beds. Community hospital networks in the Midwest and Southeast are relinquishing direct supplier relationships in favor of cooperative contract pricing.
Pharmaceuticals Pouch Market Segmentation
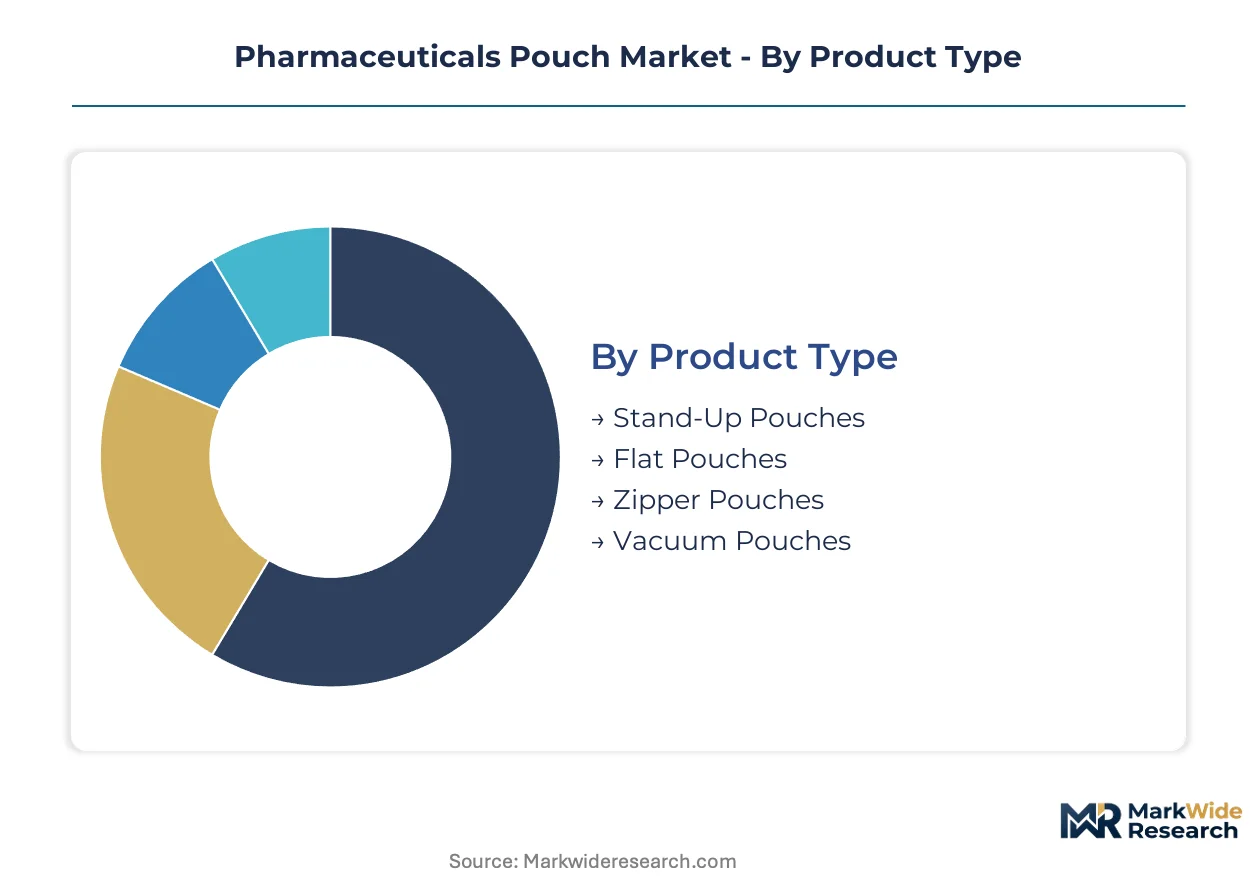
Pharmaceutical pouch segmentation reflects divergent supply chain strategies across regulated markets. Domestic production clusters serve hospital central-fill networks, while export-oriented formats target specialty pharmacy cold-chain requirements in Germany and the United States.
Product Type:
Stand-up and flat pouch formats split sharply between domestic hospital procurement and export-driven specialty pharmacy demand.
- Stand-Up Pouches:Multi-layer laminates with integrated bottom gussets enable vertical shelf presence for OTC retail channels. German and Austrian specialty pharmacies specify these formats for temperature-sensitive biologics requiring oxygen transmission rates below 0.1 cc per square meter per day.
- Flat Pouches:Heat-sealed two-dimensional geometries minimize unit cost for high-volume oral solids distribution. United States hospital central-fill automation favors standardized flat pouch dimensions over vial alternatives for robotic dispensing compatibility.
- Zipper Pouches:Reclosable interlocking profiles serve multi-dose antibiotic and pain management regimens in community pharmacy settings.
- Vacuum Pouches:Negative-pressure sealing extends stability for hygroscopic APIs in bulk API-to-contract-manufacturer shipments.
Flat pouches command the established base. The steepest expansion runs through stand-up configurations.
Material:
Material selection tracks barrier-performance tiers and regulatory qualification timelines across FDA and EU MDR jurisdictions.
- Polyethylene:Mono-material grades are gaining traction for EU Green Deal recyclability compliance. Swiss and German generic manufacturers are qualifying high-density polyethylene laminates with ethylene vinyl alcohol copolymer nanocomposite barrier layers for medium-barrier oral solids.
- Polypropylene:Cast and oriented films deliver clarity and moisture resistance for unit-dose visibility requirements. Demand concentrates in United States retail OTC channels where senior-friendly opening features are mandated.
- Nylon:Biaxially oriented polyamide layers puncture resistance for parenteral kit packaging in hospital settings.
- Paper:Fiber-based substrates with polymer barrier coatings serve sustainability-positioned OTC brands in European retail.
Polyethylene is climbing the fastest on sustainability tailwinds. Polypropylene retains the volume anchor.
End User:
End-user procurement patterns separate centralized hospital purchasing from fragmented retail pharmacy networks.
- Pharmacies:Specialty pharmacy networks in Germany and the United States are consolidating procurement around pre-serialized pouch formats for track-and-trace compliance. Cold-chain biologic distribution favors high-barrier multi-layer laminates with integrated temperature indicators.
- Hospitals:Central-fill automation in United States health systems drives standardization toward flat pouch geometries. Group purchasing organizations covering acute care beds are consolidating supplier panels to three national distribution agreements.
- Clinics:Outpatient infusion centers require patient-portioned pouch kits for take-home biologic regimens.
- OTC Retailers:Mass-market channels prioritize shelf differentiation through stand-up pouch formats with child-resistant closures.
Hospitals command the established base. The steepest expansion runs through specialty pharmacies.
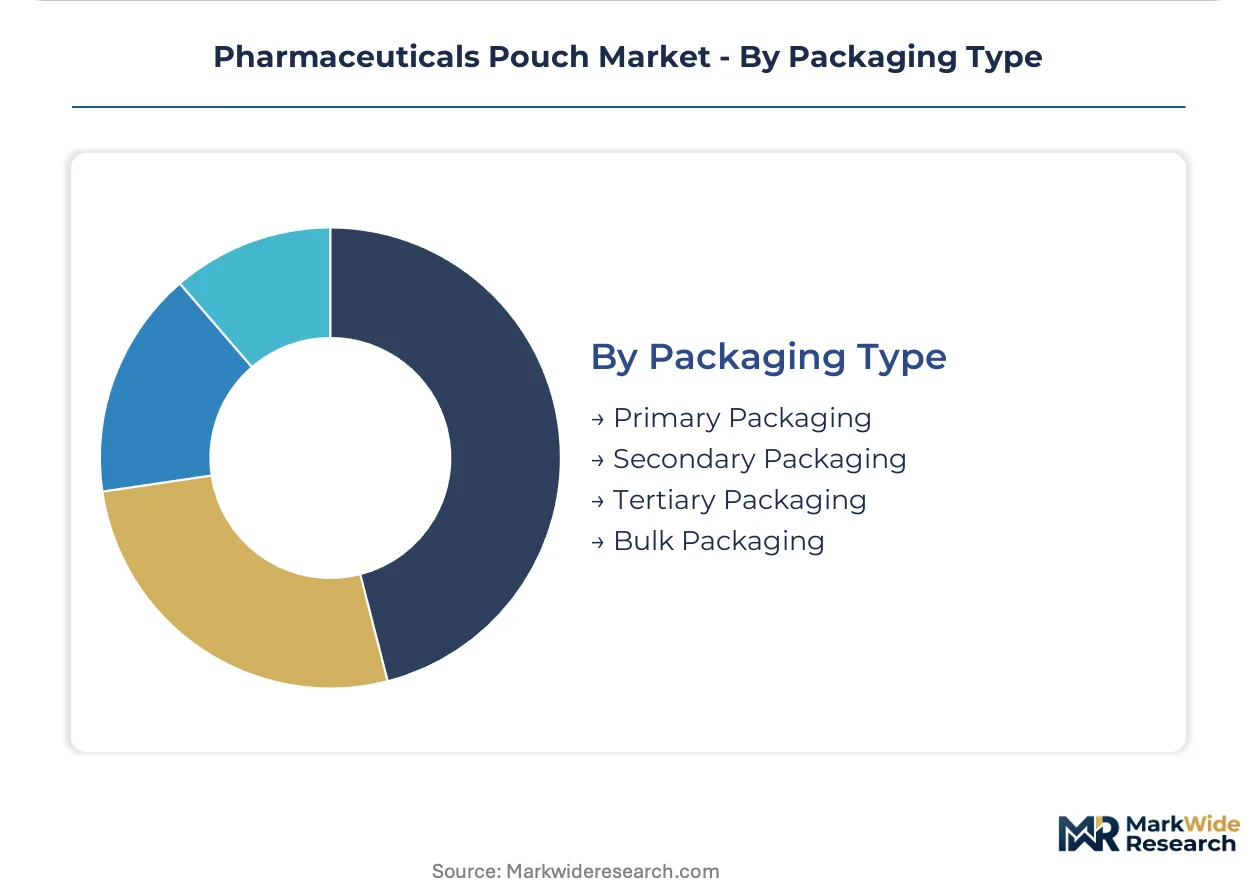
Packaging Type:
Packaging hierarchy determines regulatory validation burden and supplier switching costs across primary, secondary, and tertiary applications.
- Primary Packaging:Direct drug-contact status triggers FDA 21 CFR Part 211 and ISO 15378 validation cycles extending 18-24 months. Extractables testing protocols and change-control documentation embed incumbent manufacturers within multi-year supply agreements.
- Secondary Packaging:Outer pouches for kit assembly and labeling carry reduced qualification requirements. Demand is accelerating for pre-serialized formats in German distribution networks under EU MDR track-and-trace mandates.
- Tertiary Packaging:Shipment consolidation pouches for cold-chain distribution prioritize puncture resistance over barrier performance.
- Bulk Packaging:High-volume API storage and transfer applications favor cost-minimized polyethylene constructions.
Primary packaging commands the established base. The steepest expansion runs through secondary formats on serialization deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade pouch manufacturing clusters in Germany, the United States, and Switzerland supply cold-chain barrier films to specialty pharmacy networks worldwide. Japanese and South Korean substrate producers dominate aluminum-foil supply for high-barrier laminates.
United States
Hospital central-fill automation and specialty pharmacy biologics distribution drive demand for flat and stand-up pouch formats. FDA 21 CFR Part 211 validation cycles extending 18-24 months embed incumbent suppliers within multi-year agreements. The Research Triangle Park corridor in North Carolina hosts contract manufacturing organizations qualifying high-barrier laminates for mRNA vaccine distribution.
Germany
EU MDR serialization mandates and track-and-trace requirements expand procurement of pre-serialized pouch formats for unit-dose distribution. ECHA REACH restrictions on per- and polyfluoroalkyl substances accelerate reformulation of heat-seal coatings ahead of 2026 enforcement. The Stuttgart-Munich corridor anchors Constantia Flexibles Group GmbH healthcare packaging facilities serving Austrian and Swiss distribution networks.
Switzerland
Swissmedic regulatory alignment with EU MDR positions the country as a qualification hub for high-barrier formats targeting European specialty pharmacy channels. Generic manufacturers in Basel and Zurich adopt ethylene vinyl alcohol copolymer nanocomposite barrier layers for medium-barrier oral solids below 50 million annual units.
India
Contract manufacturers in Hyderabad and Ahmedabad seek FDA-aligned pouch suppliers for abbreviated new drug application filings targeting United States generics markets. CDSCO export pathway requirements drive qualification of ISO 15378-certified laminates. The Ahmedabad-Surat corridor concentrates pharmaceutical packaging converters serving domestic and export oral solids markets.
Japan
PMDA cold-chain stability requirements for biologics pull multi-layer coextrusion capacity toward pharmaceutical-grade barrier films with oxygen transmission rates below 0.1 cc per square meter per day. METI industrial policy supports domestic substrate production to reduce import dependency for aluminum-barrier films. The Osaka-Kobe manufacturing zone hosts specialized cleanroom pouch production for regional biologics distribution.
Pharmaceuticals Pouch Market Competitive Landscape
Concentration sits with diversified packaging conglomerates holding multi-layer coextrusion capabilities across North American and European manufacturing networks. Three strategic archetypes define competitive positioning: integrated multinational converters with healthcare-dedicated facilities, mid-cap specialists operating ISO 14644 Class 7 certified cleanroom lines, and regional substrate suppliers controlling aluminum-foil supply. Dominant competitive moves include capacity expansion in pharmaceutical-grade barrier film production and strategic partnerships with specialty pharmacy distributors for pre-serialized format qualification.
Within the integrated multinational tier, Amcor Plc and Constantia Flexibles Group GmbH exemplify archetypes leveraging geographic manufacturing footprints to serve FDA and EU MDR jurisdictions. ProAmpac occupies a position among mid-cap specialists with cleanroom production lines certified for drug-contact applications. These three anchors represent the supplier base structure: scale-driven conglomerates with healthcare verticals, European healthcare-focused converters with dedicated facilities, and North American specialists competing through regulatory certification speed.
| Leading Market Players |
|---|
| Amcor Plc |
| ProAmpac |
| Glenroy, Inc. |
| Nelipak Corporation |
| Oliver Healthcare Packaging |
| Constantia Flexibles Group GmbH |
| Sonoco Products Company |
| Huhtamaki Oyj |
| Mondi Group |
| Others |
Value Network & Pricing Analysis
Eighteen-month qualification timelines for new laminate structures concentrate pricing power among incumbent manufacturers with validated FDA 21 CFR Part 211 dossiers, while Japanese and South Korean aluminum-foil substrate producers extract premiums through supply scarcity. This lead-time asymmetry embeds multi-year contract structures that resist spot-market arbitrage and freeze supplier switching costs.
Pricing Analysis
FDA 21 CFR Part 211 dictates the pricing tier structure across pharmaceutical pouch supply, separating validated primary packaging formats from secondary applications. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and extractables testing burden, with high-barrier multi-layer laminates commanding sustained premiums. Cost compression in standard-tier polyethylene formats is intensifying because mono-material recyclability investments are spreading fixed qualification costs across narrower volume bases. Hospital group purchasing organizations exhibit the highest price sensitivity, while specialty pharmacy networks prioritize barrier performance over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate pharmaceutical-grade aluminum-foil procurement, with converters maintaining 90-120 day safety stocks against Japanese and South Korean substrate supply volatility. Raw material dependencies center on pharmaceutical-grade polyethylene, ethylene vinyl alcohol copolymers, and aluminum-barrier films. Single-source vulnerability concentrates in Japanese foil substrate production, which feeds multi-layer coextrusion lines across Germany and the United States. Distribution runs through specialty pharmacy wholesalers and hospital group purchasing organization contracts, bypassing spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rigid blister packs with integrated desiccant cavities threaten flexible pouch incumbents in high-value oral oncology launches, forcing defensive repositioning around cold-chain biologics where barrier performance advantages are most durable.
For Market Incumbents: Consolidate supply agreements with mRNA vaccine and cell therapy sponsors before 18-24 month validation cycles lock competitor access. Extend multi-layer coextrusion capacity in Germany and Austria to capture EU MDR serialization-driven demand. Backward integration into ethylene vinyl alcohol copolymer supply hedges against REACH-driven coating reformulation cost spikes. For New Entrants and Emerging Players: Differentiate on ISO 14644 Class 7 cleanroom certification speed to serve Indian CDSCO export pathways for United States generics markets. Target Hyderabad and Ahmedabad contract manufacturers seeking FDA-aligned pouch suppliers. Pursue mono-material polyethylene qualification ahead of EU Green Deal enforcement windows. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest healthcare verticals with sub-scale pharmaceutical exposure. Five-to-ten year viability hinges on serialization infrastructure deployment and sustainable material transition execution. Watch for aluminum-foil supply disruption signals as inflection indicators for premium laminate pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO 14644 Class 7 certification opens access to FDA-regulated drug-contact applications. |
| Multi-layer Coextrusion Scale-Up | Ethylene vinyl alcohol copolymer barrier layers displace aluminum foil in medium-barrier oral solids. |
| Serialization Infrastructure Deployment | EU MDR track-and-trace mandates expand addressable demand for pre-serialized pouch formats. |
| Mono-material Recyclability Qualification | EU Green Deal targets accelerate polyethylene laminate adoption for sustainability-positioned brands. |
| Specialty Pharmacy Distribution Partnerships | Direct-to-patient biologics distribution requires patient-portioned kits with temperature indicators. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs leads at pouch converters, hospital procurement managers within United States group purchasing organizations, specialty pharmacy distribution executives, and pharmaceutical packaging engineers at contract manufacturers, and refined through secondary validation against FDA 21 CFR Part 211 guidance documents, EU MDR implementation texts, ECHA REACH restriction proposals, ISO 15378 certification databases, and trade flow data from German and Austrian packaging associations. Bottom-up capacity estimates triangulated against top-down demand projections from oral solids and biologics distribution trends.
Variance decomposition across product type, material composition, end-user procurement channel, and packaging hierarchy tiers structured volume and value outputs throughout the forecast period. CAGRs were derived from segment-level growth rate convergence analysis. Cold-chain biologics expansion rates and hospital central-fill automation penetration served as pharmaceutical-specific demand drivers.
Material uncertainties — aluminum-foil supply disruption, REACH enforcement timing on fluorinated coatings, and serialization mandate deadline shifts — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and qualification timeline continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
Pharmacy Repackaging Systems Market
Pharmaceutical Packaging
Tablets and Capsules Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Materials Market
Pharmaceutical Packaging
Pharmaceutical Vials Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Glass Medicine Bottles Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Pharmaceutical Labeling Market
Pharmaceutical Packaging
United States Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Pharmaceutical Printed Cartons Market
Pharmaceutical Packaging
Active and Intelligent Packaging in Pharmaceutical Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market