
 North America Nerve Repair and Regeneration Market | 2026-2036
North America Nerve Repair and Regeneration Market Size, Share, and Industry Trends Forecast 2026-2036
North America Nerve Repair and Regeneration Market Analytics
Modular nerve graft kits bundled with intraoperative monitoring accessories is recalibrating how hospital procurement committees evaluate total procedure cost against standalone component purchasing. Axogen Corporation leverages its proprietary Avance nerve graft processing to dominate the allograft segment across ambulatory surgery centers. Integra LifeSciences Corporation sustains competitive positioning through backward integration into collagen matrix sourcing for its conduit portfolio.
Nerve repair and regeneration encompasses surgical interventions, biologic scaffolds, and electrical stimulation systems designed to restore structural continuity and functional signaling across damaged neural tissue. These technologies employ absorbable polymers, processed allografts, or implantable pulse generators to bridge lesion gaps exceeding five millimeters where spontaneous recovery proves inadequate. Neurostimulation devices capture disproportionate margin pools due to recurring electrode replacement cycles and programming service revenues. Nerve grafts compete primarily on processing quality and donor tissue traceability rather than price alone. Minimally invasive delivery modes are displacing open surgical approaches in brachial plexus and facial nerve indications.
FDA breakthrough device designations and CMS transitional pass-through payments shape reimbursement access for novel nerve repair technologies in the United States. Health Canada and the FDA coordinate on biocompatibility testing standards for collagen-derived implants, reducing redundant validation burdens for cross-border suppliers. Stakeholders must monitor evolving NICE-equivalent health technology assessments in Ontario and Quebec, where provincial formularies increasingly condition hospital procurement on demonstrated quality-adjusted life year improvements.
Market Dynamics
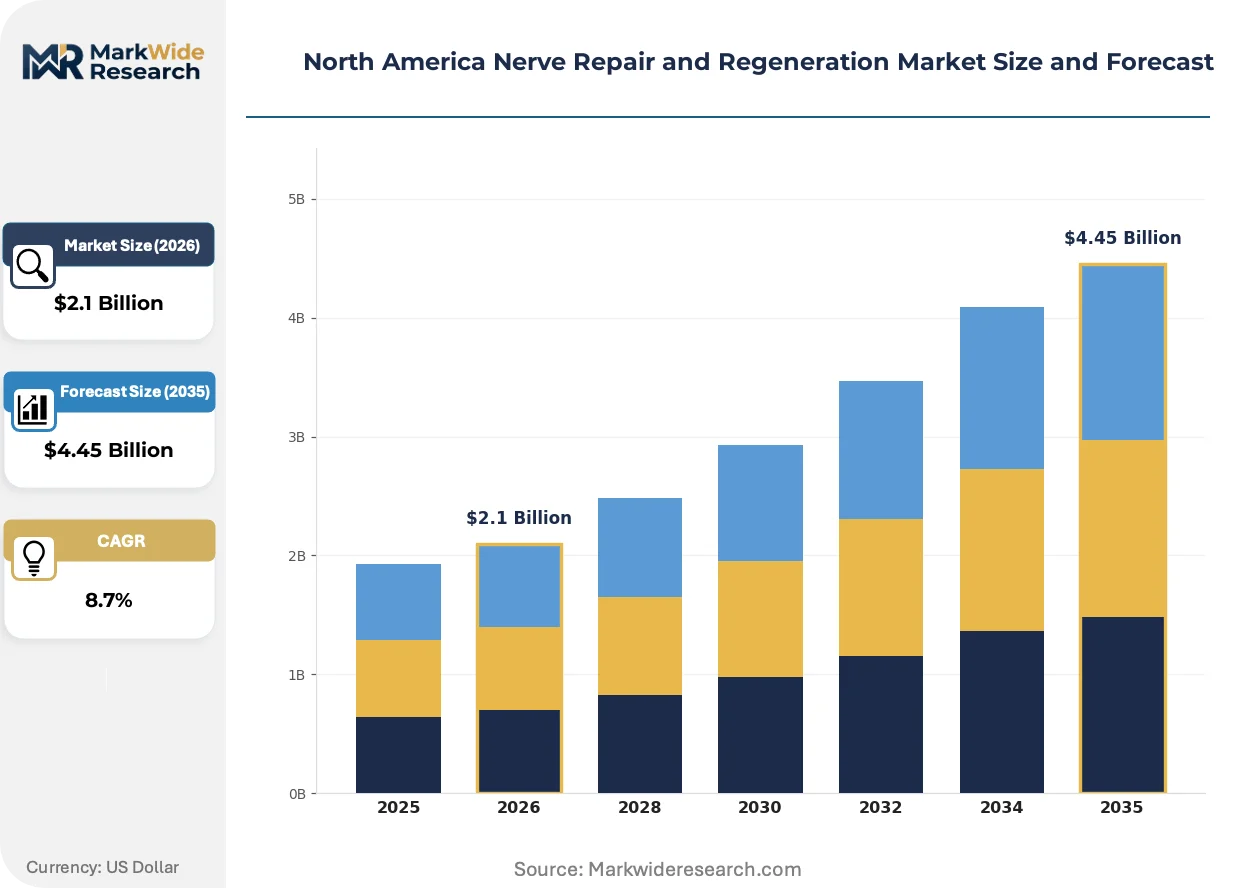
FDA breakthrough device designations are compressing clinical validation timelines for novel neurostimulation platforms while CMS transitional pass-through payments reshape hospital procurement economics for advanced nerve repair technologies across the United States.
Growth Catalysts
- CMS Transitional Pass-Through Payments:Medicare reimbursement carve-outs for novel nerve repair devices accelerate hospital adoption cycles in ambulatory surgery centers across Texas and California.
- Minimally Invasive Delivery Modes:Percutaneous nerve repair techniques are displacing open surgical approaches in brachial plexus and facial nerve indications, reducing operative morbidity and length of stay.
- Processed Allograft Quality Standards:Enhanced donor tissue traceability protocols from AATB-accredited tissue banks elevate clinical confidence in nerve graft substitution over autograft harvesting.
Market Restraints
- Collagen Matrix Input Volatility:Bovine-derived and porcine-derived collagen sourcing faces price instability from agricultural supply fluctuations and religious dietary restriction compliance costs.
- Donor Tissue Supply Concentration:Allograft processing capacity clusters among a limited cohort of AATB-accredited tissue banks, creating single-source vulnerability for nerve graft manufacturers.
- Five-Millimeter Lesion Limitation:Current biologic scaffold technologies demonstrate inconsistent efficacy bridging gaps exceeding five millimeters without adjunct neurostimulation, constraining addressable indications.
Strategic Opportunities
- Quebec and Ontario Provincial Formularies:Health technology assessment pathways in Canada's largest provinces create first-mover advantage for manufacturers demonstrating quality-adjusted life year improvements against surgical revision rates.
- Neurostimulation-AI Convergence:Closed-loop adaptive programming algorithms paired with implantable pulse generators enable personalized stimulation parameter optimization based on real-time electromyography feedback.
- Ambulatory Surgery Center Channel Expansion:Outpatient migration of peripheral nerve repair procedures creates demand for compact, disposable intraoperative monitoring systems tailored to ASC capital constraints.
Industry Challenges
- Microsurgical Fellowship Pipeline Constraints:Limited accredited peripheral nerve surgery training programs in the United States and Canada restrict qualified surgeon availability for complex brachial plexus reconstruction.
- ISO 10993 Biocompatibility Testing Bottlenecks:Extended cytotoxicity and sensitization study timelines for collagen-derived implants delay regulatory submissions to FDA and Health Canada.
- Electrode-Tissue Interface Standardization:Absence of unified impedance and charge density standards across neurostimulation platforms complicates multi-manufacturer interoperability and programming workflow integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Nerve Repair and Regeneration Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nerve Grafts, Neurostimulation Devices, Scaffolds, Conduits Therapy Area: Trauma, Peripheral Neuropathy, Spinal Cord Injury, Tumors Delivery Mode: Invasive, Non-Invasive, Minimally Invasive, Surgical End User: Hospitals, Neurology Clinics, Research Institutes, Rehabilitation Centers |
| Companies Covered | Axogen Corporation, Integra LifeSciences Corporation, Medtronic plc, Boston Scientific Corporation, Abbott Laboratories, LivaNova PLC, Stryker, Collagen Matrix, Baxter International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Nerve Repair and Regeneration Market Evolving Landscape
Neurostimulation platforms are converging with artificial intelligence to enable adaptive therapy delivery, while regulatory harmonization between FDA and Health Canada accelerates cross-border commercialization timelines for biologic scaffolds.
Bioabsorbable synthetic nerve conduits composed of polyglycolic acid and polycaprolactone copolymers are rewriting the competitive landscape for gap bridging in digital nerve repairs. Ambulatory surgery centers in California and Texas are adopting these conduits at twice the rate of traditional collagen matrices. The technology is compressing average selling prices for conduit products while expanding total addressable procedures through simplified inventory management.
FDA breakthrough device designation pathways are compressing premarket approval timelines for novel neurostimulation systems targeting peripheral nerve indications. Health Canada coordinates biocompatibility testing standards with FDA through the FDA-Health Canada Good Manufacturing Practice Mutual Recognition Agreement, reducing redundant validation burdens. Manufacturers targeting both markets are consolidating regulatory strategy functions and leveraging single-study designs for simultaneous submissions.
Hospital procurement committees are unbundling intraoperative monitoring accessories from nerve graft kit bundles and evaluating standalone component purchasing against total procedure cost metrics. This behavioral shift concentrates negotiating leverage with integrated health systems in California and Texas that operate multiple trauma centers. The transition pressures smaller ambulatory surgery centers to consolidate purchasing through group purchasing organizations to maintain comparable unit economics.
North America Nerve Repair and Regeneration Market Segmentation
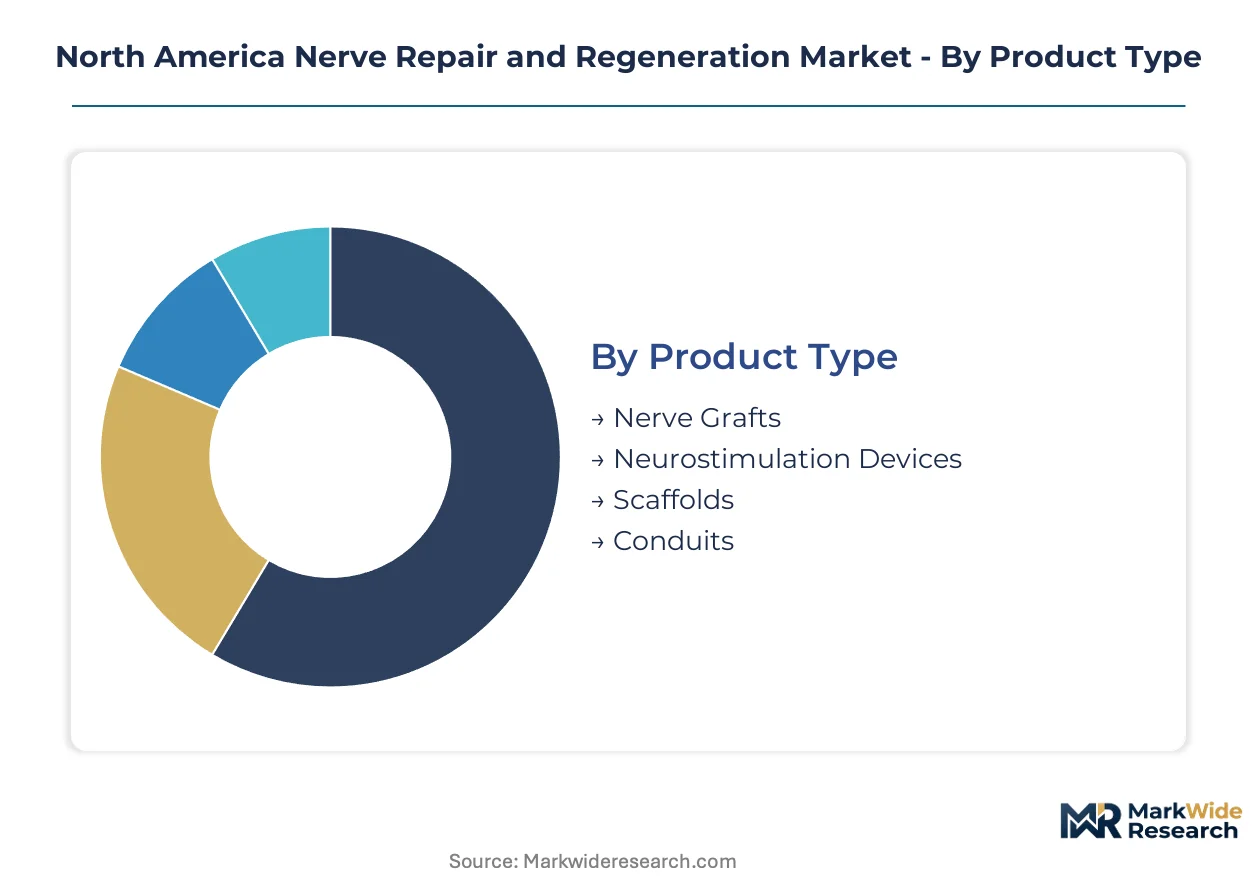
Nerve repair and regeneration technologies span distinct product architectures, therapeutic targets, and delivery modalities that determine reimbursement pathways and procurement workflows. Segmentation clarity enables manufacturers to align R&D investment with specific clinical use cases and facility capital constraints across hospital and ambulatory settings.
Product Type:
Standalone implantable systems compete with consumable biologic kits for procedural integration depth and recurring revenue potential.
- Nerve Grafts:Processed allografts and autografts bridge lesion gaps exceeding critical thresholds where spontaneous regeneration fails. Demand clusters in Texas and California trauma centers where specialized peripheral nerve surgical teams handle complex brachial plexus reconstruction volumes.
- Neurostimulation Devices:Implantable pulse generators with electrode arrays deliver electrical impulses to restore functional signaling. Recurring electrode replacement cycles and programming service revenues generate disproportionate margin pools for manufacturers serving hospital electrophysiology departments.
- Scaffolds:Biologic and synthetic matrices provide structural support for axonal regrowth across critical-size defects.
- Conduits:Hollow tubular structures guide nerve regeneration across short-gap lesions without donor site morbidity.
Nerve grafts lead volumes today; neurostimulation devices are gaining share fastest through expanded FDA breakthrough designations.
Therapy Area:
Acute traumatic indications dominate procedure volumes while chronic neuropathic conditions present longer adoption timelines due to reimbursement complexity.
- Trauma:Acute nerve transections from industrial accidents, motor vehicle collisions, and combat injuries require immediate surgical intervention. California and Texas trauma hubs generate concentrated demand for allograft and conduit products in emergency operative settings.
- Peripheral Neuropathy:Chronic nerve degeneration from diabetes, chemotherapy, and autoimmune conditions drives neurostimulation implant volumes. Medicare coverage determinations for diabetic peripheral neuropathy indications are expanding addressable patient populations in ambulatory surgery centers.
- Spinal Cord Injury:Catastrophic neural damage presents limited current surgical options but attracts experimental neurostimulation and scaffold research investment.
- Tumors:Nerve sheath tumors and oncologic resections requiring nerve sacrifice create planned surgical demand for reconstruction techniques.
Trauma leads volumes today; peripheral neuropathy is expanding most quickly through CMS coverage expansion.
Delivery Mode:
Procedural invasiveness determines facility capital requirements, anesthesia protocols, and length-of-stay economics that shape purchasing committee evaluations.
- Minimally Invasive:Percutaneous and endoscopic nerve repair techniques reduce operative morbidity and accelerate recovery timelines. Ambulatory surgery centers in California and Texas are adopting these approaches at twice the rate of traditional open procedures for digital and facial nerve indications.
- Surgical:Open operative exposure remains necessary for complex brachial plexus reconstruction and multi-nerve injury patterns. Academic medical centers maintain specialized microsurgical capabilities that sustain demand for comprehensive graft and conduit portfolios.
- Invasive:Implantable neurostimulation systems require operative placement with subsequent programming and maintenance protocols.
- Non-Invasive:External stimulation and biophysical modalities serve rehabilitation and adjunctive therapy roles without operative intervention.
Surgical approaches lead volumes today; minimally invasive techniques are climbing the fastest through ASC channel migration.
End User:
Facility type determines capital intensity tolerance, purchasing consolidation leverage, and regulatory compliance burden for device manufacturers.
- Hospitals:Integrated health systems operate centralized procurement functions that negotiate bundled pricing for nerve graft kits and intraoperative monitoring systems. Texas and California multi-hospital networks concentrate purchasing leverage through standardized formularies across trauma center networks.
- Neurology Clinics:Specialized outpatient facilities focus on diagnostic evaluation and non-surgical management, creating demand for external neurostimulation and rehabilitation protocols.
- Research Institutes:Academic and government laboratories drive preclinical validation for novel scaffold materials and neurostimulation algorithms.
- Rehabilitation Centers:Post-acute facilities manage functional recovery programming with adjunctive electrical stimulation and physical therapy modalities.
Hospitals lead volumes today; neurology clinics are expanding most quickly through outpatient procedure migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peripheral nerve repair techniques originated in military trauma centers during mid-20th century conflicts, with subsequent commercial scaling concentrated in North American academic medical centers. The current geographic distribution reflects this historical concentration alongside specialized surgical training infrastructure.
United States
California and Texas trauma hubs generate concentrated demand for allograft nerve grafts and neurostimulation implants. FDA breakthrough device designations compress premarket approval timelines for novel peripheral nerve platforms. The Texas Medical Center in Houston anchors complex brachial plexus reconstruction volumes, while Stanford and UCLA medical centers drive adoption of minimally invasive facial nerve repair techniques.
Canada
Ontario and Quebec provincial formularies condition hospital procurement on demonstrated quality-adjusted life year improvements against surgical revision rates. Health Canada coordinates biocompatibility testing standards with FDA through mutual recognition agreements, reducing redundant validation burdens for collagen-derived implants. Toronto's University Health Network and McGill University Health Centre concentrate specialized peripheral nerve surgical capacity.
Mexico
Industrial accident trauma volumes in Nuevo León and Mexico City metro areas sustain demand for nerve conduit products in emergency operative settings. The country's national pharmaceutical regulator maintains alignment with FDA biocompatibility protocols for imported collagen matrices. Guadalajara's medical device manufacturing clusters support regional distribution of processed allograft products.
North America Nerve Repair and Regeneration Market Competitive Landscape
Premium-margin players sit above commodity-margin players across neurostimulation device portfolios versus consumable biologic scaffold segments. The vendor base stratifies into three tiers: diversified medtech conglomerates with electrophysiology divisions, specialized nerve repair pure-plays with proprietary processing technologies, and regional tissue bank networks supplying raw allograft material. Consolidation pressure intensifies through strategic partnerships between neurostimulation platform developers and AI-enabled programming service providers, alongside backward integration moves by conduit manufacturers into collagen matrix sourcing.
Within the specialized nerve repair tier, Axogen Corporation exemplifies allograft processing dominance through proprietary Avance nerve graft technology. Integra LifeSciences Corporation anchors the biologic scaffold segment with captive collagen matrix supply chains. Medtronic plc represents diversified electrophysiology scale across implantable pulse generator platforms. These three entities illustrate distinct strategic archetypes: pure-play tissue processing specialization, vertical integration into raw material supply, and diversified neurostimulation device manufacturing at scale.
| Leading Market Players |
|---|
| Axogen Corporation |
| Integra LifeSciences Corporation |
| Medtronic plc |
| Boston Scientific Corporation |
| Abbott Laboratories |
| LivaNova PLC |
| Stryker |
| Collagen Matrix |
| Baxter International |
| Others |
Value Network & Pricing Analysis
Microsurgical fellowship concentration in California and Texas trauma hubs feeds directly into labor-cost differentials that separate premium-tier neurostimulation platforms from standard nerve graft kits. These regional skill premiums compress margins for commodity conduit products while sustaining pricing power for implantable pulse generators requiring specialized programming expertise.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels organizes the competitive landscape. Premium tiers capture FDA breakthrough-designated neurostimulation systems with proprietary electrode arrays; standard tiers hold processed allografts with AATB traceability certification; economy tiers absorb synthetic conduits from bioabsorbable polymer manufacturers. Cost compression in the conduit segment intensifies as ambulatory surgery centers consolidate purchasing through group purchasing organizations. Hospital procurement committees exhibit highest price sensitivity for consumable biologic scaffolds; electrophysiology departments remain least sensitive given recurring service revenue attachments.
Supply Chain Analysis
Direct-to-hospital channels handle complex neurostimulation system installations with specialized biomedical engineering support; distributor networks manage high-volume conduit and graft logistics for ambulatory surgery centers. Geographic supply concentration clusters in the United States for allograft tissue processing, Switzerland for precision electrode manufacturing, and Ireland for collagen matrix refinement. Raw material dependencies center on AATB-accredited donor tissue networks, pharmaceutical-grade polymers, and implantable-grade titanium. Single-source vulnerability pervades the allograft processing tier where AATB-accredited tissue bank capacity concentrates among limited suppliers. Distribution runs through specialized surgical device distributors with cold-chain capabilities for biologic products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where hospital procurement committees increasingly condition purchasing on demonstrated quality-adjusted life year improvements rather than unit cost alone. The demand shift toward premium specifications with FDA breakthrough designation and CMS transitional pass-through eligibility justifies this framing.
For Market Incumbents: Hedge against synthetic conduit price erosion by deepening backward integration into collagen matrix sourcing and securing captive AATB-accredited tissue bank relationships. Defensive consolidation of neurostimulation programming service capabilities protects margin pools from AI-enabled algorithm competitors. Priority rests on maintaining electrophysiology department loyalty through electrode replacement cycle lock-in. For New Entrants and Emerging Players: AI-enabled closed-loop adaptive programming algorithms offer the most penetrable technology-first wedge for neurostimulation platform disruption. White-space targets concentrate in Quebec and Ontario provincial formulary pathways where health technology assessment frameworks reward quality-adjusted life year documentation. Ambulatory surgery center channel expansion for compact intraoperative monitoring systems provides the clearest go-to-market angle against hospital-centric incumbents. For Investors and Strategic Acquirers: Diversified medtech conglomerates with electrophysiology divisions are the most active acquirer in this space, seeking AI programming capabilities to complement implantable pulse generator hardware. Long-term viability favors pure-play tissue processors with proprietary allograft technologies and demonstrated surgeon training program scale. The signal to watch is CMS coverage determination expansion for diabetic peripheral neuropathy indications as inflection indicator for neurostimulation addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates premarket approval timelines for novel peripheral nerve platforms in the United States. |
| AATB-Accredited Tissue Bank Partnership | Secures donor tissue traceability protocols that elevate clinical confidence in allograft substitution. |
| CMS Transitional Pass-Through Payment Strategy | Unlocks Medicare reimbursement carve-outs for novel devices in ambulatory surgery centers. |
| AI-Enabled Programming Service Development | Enables closed-loop adaptive stimulation parameter optimization based on real-time electromyography feedback. |
| Provincial Formulary Health Technology Assessment | Creates first-mover advantage in Ontario and Quebec through quality-adjusted life year documentation. |
Research Methodology
Direct dialogue with peripheral nerve surgeons, hospital purchasing committee members, biomedical engineers, and group purchasing organization contract managers grounded the qualitative foundation. Secondary validation drew from FDA 510(k) and PMA filings, CMS Medicare coverage determinations, AATB accreditation records, and hospital procurement database extracts. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation converged on segment-level estimates.
Bottom-up analytics tracked procedure volumes by product type, therapy area, and delivery mode across hospital and ambulatory surgery center settings. Top-down validation cross-referenced manufacturer-reported revenue segments against estimated average selling prices and replacement cycle frequencies. CAGRs emerged from regression analysis of historical adoption curves and reimbursement pathway expansion timelines. Forecast inputs incorporated CMS coverage determination pipelines, FDA breakthrough designation trajectories, and provincial formulary assessment schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to microsurgical fellowship pipeline constraints, collagen matrix input volatility, and electrode-tissue interface standardization developments. Forecasts reflect assumptions around reimbursement stability and regulatory harmonization between FDA and Health Canada. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Squamous Cell Carcinoma Treatment Market
Medical Treatment
Molluscum Contagiosum (MC) Treatment Market
Medical Treatment
North America Chronic Disease Management Market
Medical Treatment
ALAD Porphyria Treatment Market
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Postoperative Nausea and Vomiting (PONV) Management Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Lymphedema Treatment Market
Medical Treatment
US Direct Anterior Approach (Total Hip Replacement) Market
Medical Treatment
Diphtheria Treatment Market
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Disseminated Intravascular Coagulation (DIC) Treatment Market
Medical Treatment
Precocious Puberty Treatment Market
Medical Treatment
Europe Nerve Repair and Regeneration Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Tetanus Treatment Market