
 North America Electrophysiology Market | 2026-2036
North America Electrophysiology Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electrophysiology Market Outlook
Multi-source procurement of electrophysiology catheters is consolidating as health systems standardize around fewer vendor relationships to secure volume pricing and technical support integration. Medtronic leverages its integrated mapping and ablation portfolio to anchor large hospital contracts across the United States. Boston Scientific Corporation competes through specialized cryoablation technology leadership, while Abbott Laboratories sustains diagnostic catheter innovation pipelines that feed into broader lab ecosystem sales.
Electrophysiology encompasses the diagnostic and therapeutic techniques used to evaluate electrical activity in the heart and treat cardiac arrhythmias through catheter-based procedures, typically employing electrode-tipped catheters capable of recording intracardiac signals at millivolt resolution and delivering radiofrequency energy at controlled temperatures to create targeted lesions. Catheters represent the most mature product segment with established reimbursement pathways, while mapping systems capture expanding margin pools as three-dimensional electroanatomical platforms displace fluoroscopy-dependent workflows. Ablation devices incorporating pulsed field technology are gaining fastest among technology segments, though radiofrequency systems still dominate procedural volumes across hospital and cardiac clinic settings.
FDA premarket notification and premarket approval pathways govern device commercialization, while CMS reimbursement determinations directly shape hospital capital allocation toward electrophysiology suite expansion. The Medical Device Reporting regulation and subsequent FDA safety communications influence manufacturer liability exposure and product modification cycles. Stakeholders must monitor evolving CMS technology add-on payment decisions for novel ablation modalities and state-level certificate-of-need restrictions on cardiac service line expansion.
Market Dynamics
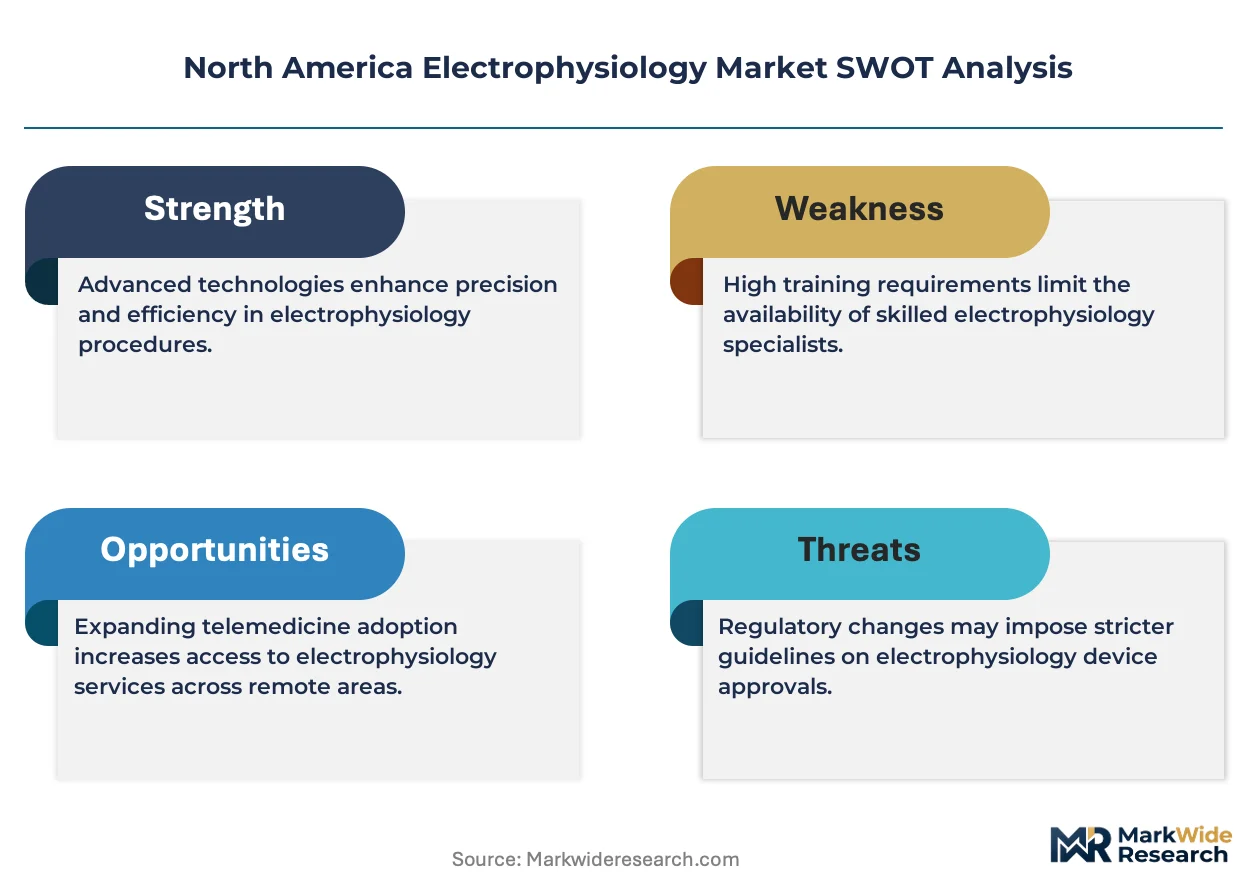
Hospital systems across the United States and Canada are consolidating vendor relationships to secure volume pricing for electrophysiology suites, compressing procurement cycles and reshaping competitive positioning among catheter and mapping system manufacturers.
Growth Catalysts
- Pulsed Field Ablation:This energy modality reduces collateral tissue damage compared to thermal approaches, accelerating adoption in high-volume cardiac centers across Texas and California.
- CMS Technology Add-On Payments:Reimbursement pathways for novel ablation devices incentivize hospital capital allocation toward electrophysiology lab expansion.
- Atrial Fibrillation Prevalence:Aging demographics in Ontario and the northeastern United States are expanding the addressable patient pool for catheter-based interventions.
Market Restraints
- Capital Equipment Intensity:Three-dimensional electroanatomical mapping systems require substantial upfront investment, limiting penetration in smaller community hospitals.
- Certificate-of-Need Restrictions:State-level CON laws in New York and Illinois constrain cardiac service line expansion regardless of underlying demand.
- Fluoroscopy Dependency:Radiation exposure concerns and imaging suite bottlenecks restrict procedural throughput in legacy catheterization laboratories.
Strategic Opportunities
- Ambulatory Surgical Centers:Regulatory clarity around site-of-service payments is enabling migration of select ablation procedures from hospital outpatient departments.
- AI-Integrated Mapping:Machine learning algorithms for arrhythmia substrate identification are converging with robotic catheter navigation platforms.
- Canadian Provincial Expansion:Underpenetrated markets in Alberta and British Columbia present whitespace for diagnostic catheter and ablation device penetration.
Industry Challenges
- Electrophysiologist Supply Constraints:Fellowship training slots have not kept pace with lab expansion, creating procedural bottlenecks in high-growth metropolitan clusters.
- FDA Premarket Approval Timelines:Novel energy modalities face extended regulatory review cycles, compressing effective patent life and delaying commercialization.
- Legacy System Interoperability:Mapping platforms from different manufacturers utilize proprietary data formats, complicating multi-vendor lab configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electrophysiology Market |
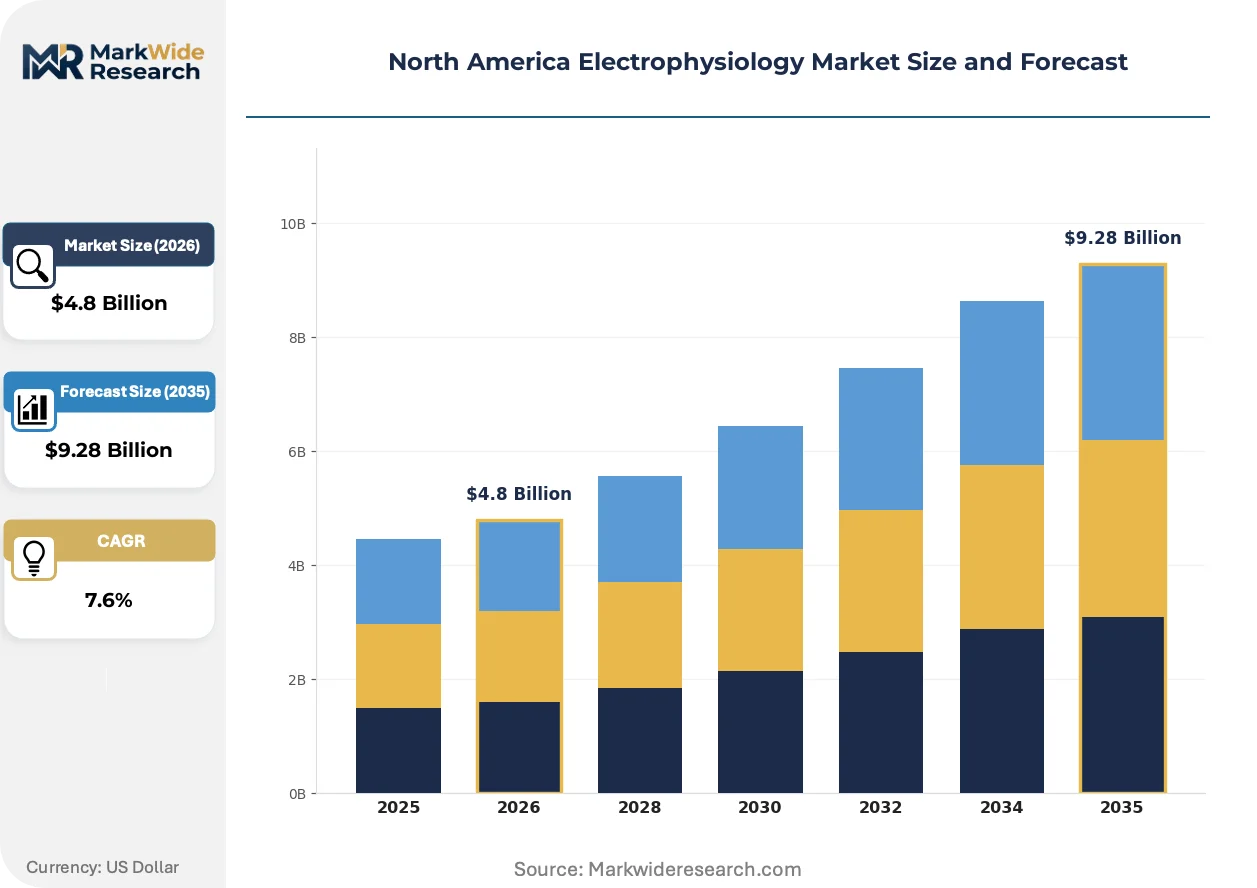
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Mapping Systems, Diagnostic Tools, Ablation Devices End User: Hospitals, Cardiac Clinics, Research Centers, Ambulatory Surgical Centers Application: Arrhythmia Treatment, Electrophysiology Studies, Cardiac Monitoring, Ablation Procedures Technology: Radiofrequency, Cryoablation, Laser, Ultrasound |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott Laboratories, BIOTRONIK, GE Healthcare, Koninklijke Philips, Johnson & Johnson Services, Inc., MicroPort Scientific Corporation, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electrophysiology Market Strategic Shifts
Pulsed field energy delivery and artificial intelligence integration are restructuring how cardiac ablation procedures are planned, executed, and reimbursed across North American healthcare systems.
Magnetically enabled catheter navigation is decentralizing the technical skill requirements for complex ablation procedures. Community hospitals in Arizona and Colorado are adopting these platforms to retain patients who previously required transfer to academic medical centers. The technology is decentralizing the geographic concentration of high-complexity electrophysiology services.
FDA premarket notification pathways for software-as-a-medical-device components are expanding regulatory scope over AI-enabled mapping algorithms. Manufacturers must now submit algorithm change control protocols for machine learning updates, extending validation timelines. Diagnostic catheter segments with embedded computational features face heightened scrutiny under this evolving framework.
Health system purchasing cooperatives are aggregating demand across multiple hospital campuses to extract pricing concessions on disposable catheter contracts. Independent cardiac clinics in Florida and Georgia are losing access to tier-one pricing, forcing consolidation into larger delivery networks. This concentration is most visible in the southeastern United States where private equity-backed cardiology platforms are acquiring community-based electrophysiology practices.
North America Electrophysiology Market Segmentation
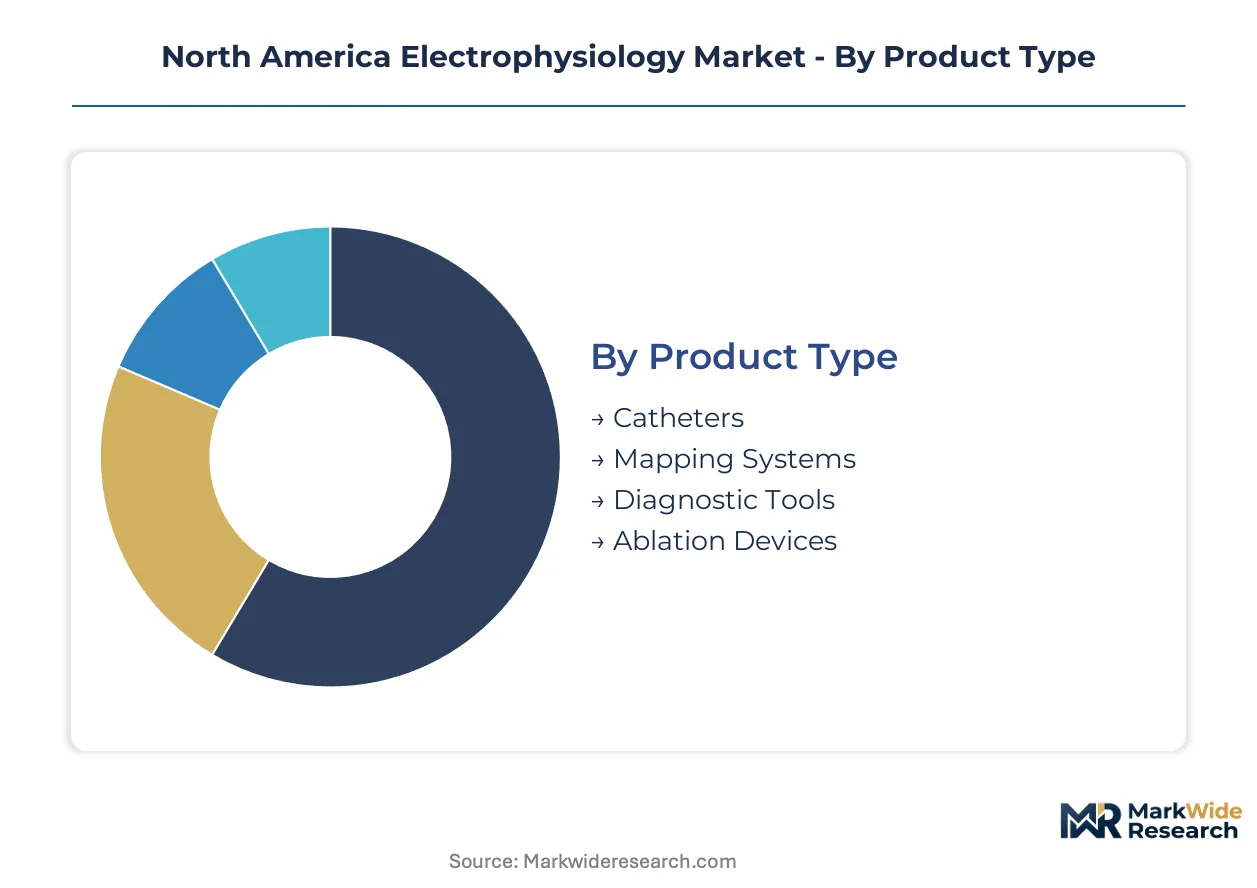
Electrophysiology market segmentation reveals divergent capital requirements across product categories. Mapping systems demand seven-figure infrastructure commitments while disposable catheters generate recurring revenue streams with minimal fixed asset deployment.
Product Type:
Capital intensity varies dramatically across this category, with imaging platforms requiring dedicated procedure rooms and disposable devices flowing through established supply chains.
- Catheters:Electrode-tipped instruments deliver radiofrequency energy and record intracardiac signals at millivolt resolution. Hospital systems in Texas and California negotiate multi-year supply agreements to secure volume pricing on these high-velocity consumables.
- Mapping Systems:Three-dimensional electroanatomical platforms displace fluoroscopy-dependent workflows through magnetic field localization. Academic medical centers in Ontario deploy these systems to anchor referral networks for complex arrhythmia cases.
- Diagnostic Tools:Signal acquisition hardware and analysis software for electrophysiology studies.
- Ablation Devices:Energy delivery systems including generators and specialized catheters for lesion creation.
Most installed capacity flows through Catheters. Expansion is steepest in Mapping Systems.
End User:
Site-of-service economics reshape procurement patterns as regulatory clarity enables procedure migration toward lower-cost settings.
- Hospitals:Integrated delivery networks maintain electrophysiology suites with full catheter and mapping system portfolios. Certificate-of-need restrictions in New York and Illinois constrain cardiac service line expansion regardless of underlying demand.
- Ambulatory Surgical Centers:Specialized facilities capture select ablation procedures previously confined to hospital outpatient departments. Arizona and Colorado clinics leverage magnetically enabled navigation to retain patients locally.
- Cardiac Clinics:Independent practices facing purchasing cooperative pressure.
- Research Centers:Academic institutions evaluating novel energy modalities.
Procedure volume concentrates in Hospitals. Site migration is accelerating fastest in Ambulatory Surgical Centers.
Application:
Clinical indication severity determines reimbursement tiering and technology selection across the care continuum.
- Ablation Procedures:Catheter-based interventions for atrial fibrillation and ventricular tachycardia utilizing thermal or pulsed field energy. High-volume cardiac centers in the northeastern United States drive demand for advanced lesion formation technologies.
- Arrhythmia Treatment:Therapeutic interventions spanning pharmacologic, device-based, and ablative approaches.
- Electrophysiology Studies:Diagnostic procedures mapping cardiac electrical conduction pathways.
- Cardiac Monitoring:Long-term rhythm surveillance through implantable and external devices.
Revenue gravity centers on Ablation Procedures. Technology evolution is most rapid in Arrhythmia Treatment.
Technology:
Energy modality selection balances lesion precision against collateral tissue risk, with newer platforms disrupting established thermal approaches.
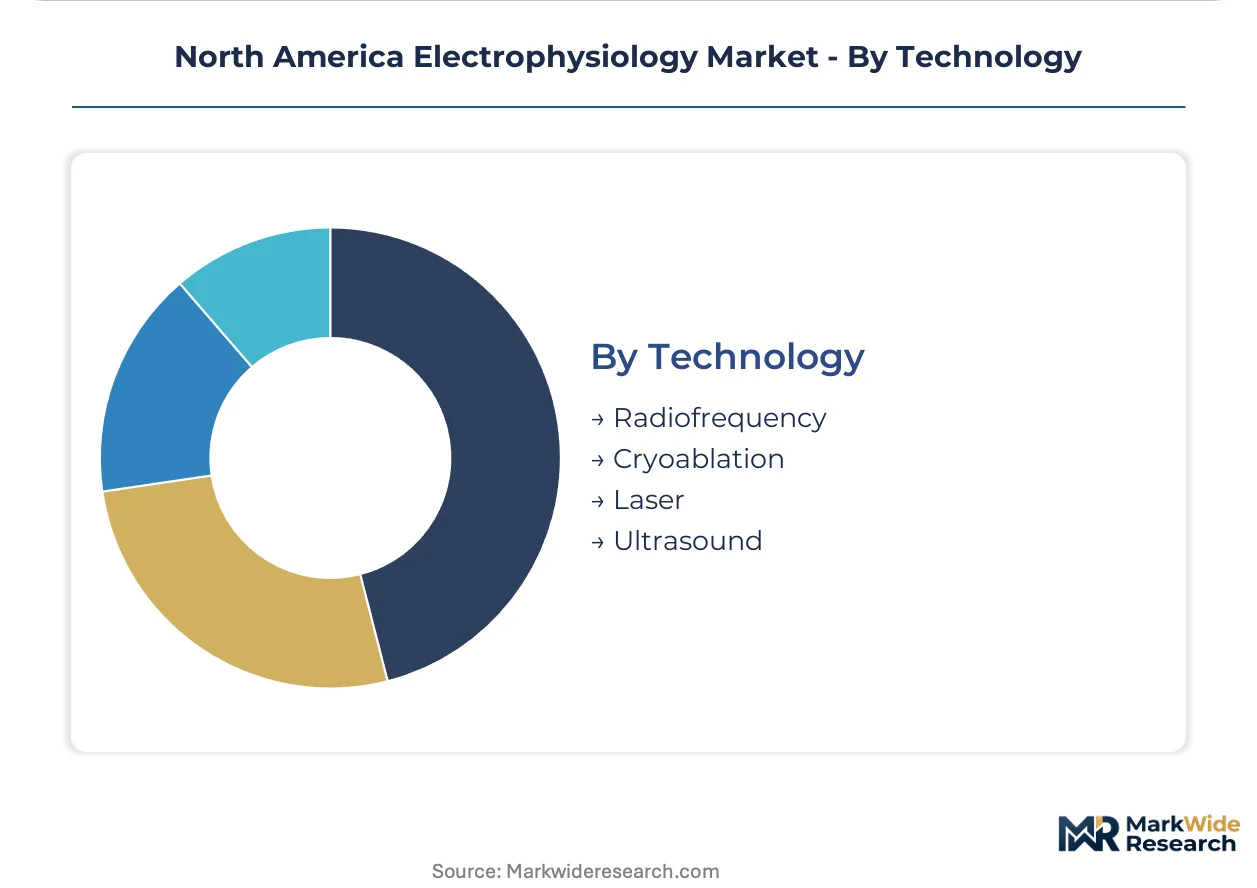
- Radiofrequency:Resistive heating at controlled temperatures creates targeted myocardial lesions. This thermal approach still dominates procedural volumes across hospital and cardiac clinic settings throughout the United States and Canada.
- Cryoablation:Nitrous oxide or argon-based cooling achieves tissue destruction through freezing. Boston Scientific Corporation anchors market position through specialized technology leadership in this modality.
- Laser:Optical energy delivery for specialized ablation applications.
- Ultrasound:Mechanical wave energy for tissue modification.
Installed base concentrates in Radiofrequency. Clinical trial activity is most intense in Cryoablation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas Medical Center corridor anchors electrophysiology demand across North America, with hospital systems in Houston and Dallas-Fort Worth expanding catheter lab capacity to capture migrating patient volumes from neighboring states.
United States
Hospital systems in California and the northeastern corridor are consolidating vendor relationships to secure volume pricing on mapping systems and disposable catheters. FDA premarket approval pathways for novel ablation devices shape manufacturer commercialization timelines and product launch sequencing. The Cleveland Clinic and Mayo Clinic anchor referral networks that drive procurement of three-dimensional electroanatomical platforms.
Canada
Provincial health authorities in Ontario and Quebec are expanding electrophysiology lab capacity to address rising atrial fibrillation caseloads among aging demographics. Health Canada regulates device commercialization through premarket notification pathways that parallel FDA frameworks but with distinct review timelines. Toronto's University Health Network and Montreal Heart Institute concentrate high-complexity procedural volume and drive mapping system adoption.
Mexico
Private hospital chains in Mexico City and Monterrey are importing electrophysiology equipment to serve affluent patient segments seeking cardiac ablation procedures. COFEPRIS, the national health regulator, governs medical device registration through established import licensing frameworks. Hospital Angeles and Hospital ABC anchor catheter lab expansion in the Mexico City metropolitan zone.
Alberta
Underpenetrated cardiac service lines in Calgary and Edmonton present whitespace for diagnostic catheter and ablation device market entry. Provincial health spending allocations through Alberta Health Services determine capital equipment procurement cycles for electrophysiology suites. The University of Alberta Hospital anchors the province's sole high-volume arrhythmia referral center.
British Columbia
Vancouver Coastal Health and Fraser Health authorities are evaluating electrophysiology lab expansion to reduce patient outflow to Seattle and Calgary. Health Canada reimbursement determinations through provincial drug and device programs shape hospital capital allocation. Vancouver General Hospital concentrates complex ablation procedural volume for the Pacific province.
North America Electrophysiology Market Competitive Environment
Global majors compete with regional champions across integrated portfolio breadth versus specialized technology depth. The vendor base organizes into three tiers: diversified medical technology conglomerates with full electrophysiology ecosystems, cardiovascular specialists with focused ablation or mapping capabilities, and imaging equipment manufacturers extending into procedural navigation. Strategic moves center on multi-year hospital system contracting and technology licensing partnerships that secure exclusive supply relationships for high-volume cardiac centers.
Among diversified medical technology conglomerates, Medtronic, Boston Scientific Corporation, and Abbott Laboratories occupy anchor positions across the integrated mapping and ablation portfolio tier. Medtronic exemplifies the full-ecosystem archetype through its combined diagnostic catheter, ablation device, and mapping system offerings. Boston Scientific Corporation represents specialized cryoablation technology leadership within the cardiovascular specialist tier. Abbott Laboratories sits within the diagnostic-to-therapeutic workflow integration archetype, sustaining innovation pipelines that feed broader lab ecosystem sales.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott Laboratories |
| BIOTRONIK |
| GE Healthcare |
| Koninklijke Philips |
| Johnson & Johnson Services, Inc. |
| MicroPort Scientific Corporation |
| Siemens Healthineers |
| Others |
Value Chain & Pricing Dynamics
Platinum group metal price indices cascade through catheter electrode manufacturing into tiered procurement contracts across North American hospital systems. Input cost volatility in conductive materials concentrates pricing power with integrated manufacturers possessing backward control over precious metal supply chains.
Pricing Analysis
Input-cost pass-through from electrode materials and polymer substrates stratifies pricing across premium, standard, and economy catheter tiers. Price differentiation hinges on FDA premarket approval tier and volume scale commitments from integrated delivery networks. Pricing pressure stems from health system purchasing cooperative aggregation forcing concession on disposable contracts. Community hospitals exhibit highest price sensitivity; academic medical centers prioritize mapping system integration over unit cost.
Supply Chain Analysis
Freight cost escalation on temperature-controlled shipments of nitrous oxide cryoablation canisters has compressed margins on cross-border Canadian distribution. Manufacturing concentrates in Costa Rica, Mexico, and Ireland for catheter assembly, with mapping system production anchored in the United States and Germany. Raw material dependencies include platinum-iridium electrodes, medical-grade polymers, and rare-earth magnetic components for navigation platforms. Single-source vulnerability in specialized magnet manufacturing creates supply chain risk. Distribution runs through GPO-negotiated contracts to hospital systems and direct-to-hospital logistics for capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American electrophysiology represents a late-cycle quality story as pulsed field ablation shifts hospital procurement toward premium energy platforms with superior safety profiles.
For Market Incumbents: Acquire cryoablation technology portfolios to defend against pulsed field substitution threatening thermal modality market share. Secure exclusive multi-year contracts with Texas and California cardiac centers to lock in mapping system installed base. Invest in FDA premarket approval pathway acceleration to preserve effective patent life against extended regulatory timelines. For New Entrants and Emerging Players: Begin with ambulatory surgical center partnerships in Arizona and Colorado where site-of-service migration creates whitespace outside hospital purchasing cooperative dominance. Target underpenetrated Canadian provincial markets in Alberta and British Columbia with diagnostic catheter bundles preceding ablation device introduction. Leverage AI-enabled mapping software-as-a-medical-device pathways to circumvent capital equipment intensity barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale catheter manufacturers possessing FDA 510(k) clearance infrastructure and untapped GPO contract access. Long-term viability favors platforms with pulsed field energy portfolios over legacy thermal dependence. Watch CMS technology add-on payment decisions as the inflection signal for novel ablation modality reimbursement traction.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Accelerated PMA timelines compress effective patent life and shape commercialization sequencing for novel energy modalities. |
| Hospital System Partnership | Exclusive supply contracts with Texas Medical Center anchors secure volume commitments and block competitor access. |
| Software Companion Development | AI-enabled mapping algorithms face expanded regulatory scope under FDA software-as-a-medical-device frameworks. |
| Reimbursement Strategy | CMS technology add-on payment applications determine hospital capital allocation toward novel ablation platform adoption. |
| CE Marking Pathway | Health Canada parallel review pathways enable synchronized North American commercialization for mapping system launches. |
Study Parameters
Direct dialogue with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded qualitative findings in procurement decision dynamics. Secondary validation drew from FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, hospital procurement records, and GPO contract disclosures. Bottom-up catheter volume estimates triangulated against top-down electrophysiology lab capacity expansion data across the analysis window.
Segment-level outputs across product type, end user, application, and technology dimensions were generated through integrated modeling of installed base replacement cycles and procedure volume growth trajectories. CAGRs were derived from regression analysis of historical reimbursement trends and capital expenditure patterns. Forecast inputs incorporated pulsed field clinical trial readouts and state-level certificate-of-need restriction changes.
Several conditions sit outside the modeled scope, including unforeseen FDA safety communications triggering product recalls and radical shifts in site-of-service regulatory clarity. Forecasts reflect assumptions about electrophysiologist training pipeline expansion and hospital consolidation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Neurostimulation Devices Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Nonablative Laser Resurfacing Devices Market
Medical Devices
Intravaginal Device Market
Medical Devices
United States Ultrasound Devices Market
Medical Devices
Coronary Angiography Devices Market
Medical Devices
Neuroendoscopy Devices Market
Medical Devices
Remote Magnetic Catheter Systems Market
Medical Devices
Ventricular Restoration Systems Market
Medical Devices
Global Gastric Balloons Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Robotics-Assisted Telesurgery Market
Medical Devices
Spain Respiratory Devices Market
Medical Devices
Global Angioplasty Balloons Market
Medical Devices
3D Printed Prosthetics Market
Medical Devices
Global Intraoral Cameras Market