
 Rett Syndrome Treatment Market | 2026-2036
Rett Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Rett Syndrome Treatment Market Analytics
Subscription-based patient monitoring and digital biomarker platforms is recalibrating how pharmaceutical firms monetize Rett syndrome interventions beyond the pill. Acadia Pharmaceuticals leverages its neurology infrastructure to sustain distribution advantages in institutional settings. Anavex Life Sciences Corp. anchors its competitive position through sigma-1 receptor modulation research. Ionis Pharmaceuticals differentiates via antisense oligonucleotide capabilities that target MECP2 pathway modulation.
Rett syndrome treatment encompasses pharmacological and non-pharmacological interventions designed to address the X-linked neurodevelopmental disorder caused by MECP2 gene mutations, with therapeutic approaches spanning small-molecule drugs, gene replacement vectors, and intensive rehabilitative protocols. The primary purpose centers on modifying disease progression and managing severe impairments in communication, motor function, and autonomic regulation. Medications targeting symptom relief currently occupy the largest revenue share due to established reimbursement pathways, while gene therapies within the product type dimension represent the fastest-expanding category as multiple candidates advance through registrational trials. Among delivery modes, intravenous administration concentrates the highest development investment because it enables CNS-targeted biodistribution for genetic medicines.
FDA orphan drug exclusivity provisions and EMA's priority medicines scheme jointly shape clinical trial investment patterns and accelerated assessment pathways for Rett syndrome developers. The central bank of reimbursement policy, CMS in the United States, determines market access velocity through its coverage determinations for novel neurology therapies. Health Canada and the PMDA in Japan add parallel regulatory complexity for firms pursuing multi-territory launches. Stakeholders must monitor how payer evidence requirements evolve for one-time gene therapies versus chronic medication models.
Market Dynamics
Gene therapy vector manufacturing scarcity is compressing clinical trial timelines and concentrating sponsor leverage with contract development organizations possessing mammalian cell production capabilities. The MECP2 pathway's biological complexity demands specialized CNS delivery expertise that only a handful of CDMOs currently command.
Growth Catalysts
- FDA Orphan Drug Exclusivity:The seven-year market exclusivity provision accelerates investment decisions for developers targeting the estimated 15,000 diagnosed US patients, reducing competitive risk for first movers.
- Pediatric neurology clinic expansion:Academic medical centers in Boston, Cincinnati, and Houston are establishing dedicated Rett syndrome centers that centralize patient recruitment for interventional studies.
- Antisense oligonucleotide platform maturation:Ionis Pharmaceuticals' validated chemistry and manufacturing controls are de-risking MECP2-targeting drug development for competitors licensing its backbone modifications.
Market Restraints
- AAV vector manufacturing bottleneck:Suspension cell production capacity at Lonza and Catalent facilities is fully committed through 2027, forcing sponsors into costly facility construction or queue delays.
- Reimbursement uncertainty for one-time therapies:CMS has not finalized outcome-based payment frameworks for ultra-rare disease gene therapies, creating commercialization risk for late-stage candidates.
- Natural history data gaps:Heterogeneous symptom progression across MECP2 mutation types complicates regulatory endpoint selection and payer value demonstration.
Strategic Opportunities
- Japan's PMDA Sakigake designation:Priority review and dedicated consultation pathways offer 6-12 month acceleration for gene therapy submissions, with Japan's 1,200-patient addressable market commanding premium pricing.
- Digital biomarker integration:Eye-tracking and wearable sensor platforms enable remote efficacy monitoring, expanding trial access to non-urban patient populations previously excluded by travel burdens.
- Non-viral delivery convergence:Lipid nanoparticle and exosome technologies are opening alternative routes to CNS transduction that bypass pre-existing AAV neutralizing antibody limitations in patient screening pools.
Industry Challenges
- Neurodevelopmental endpoint validation:Regulatory agencies lack consensus on clinically meaningful improvement metrics for non-verbal populations, forcing sponsors to run lengthy natural history comparator arms.
- Gene therapy talent scarcity:CNS-targeted vector design and neurotoxicology assessment expertise concentrates at a dozen institutions, driving compensation inflation and recruitment delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rett Syndrome Treatment Market |
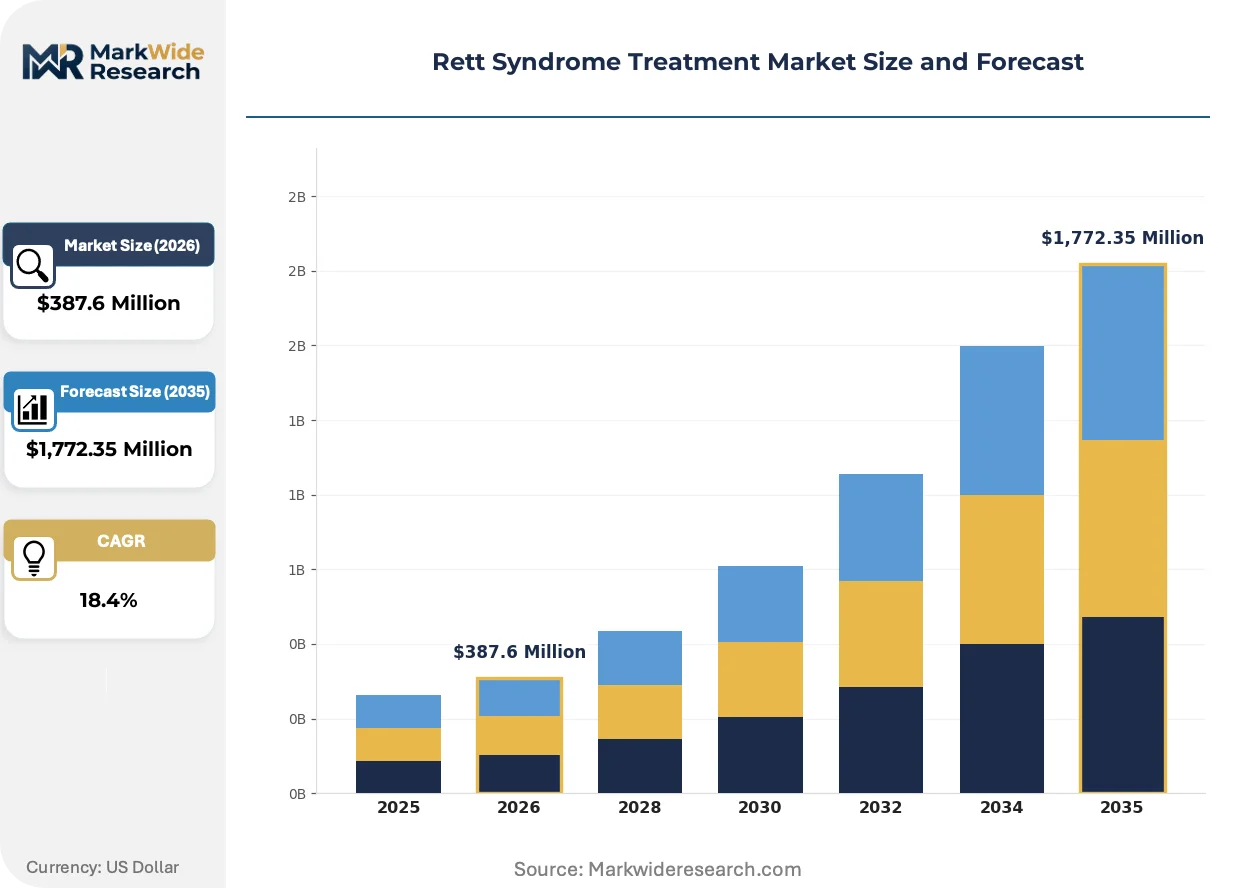
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Therapies, Supportive Care, Nutritional Supplements End User: Clinics, Hospitals, Home Care, Rehabilitation Centers Delivery Mode: Oral, Injection, Topical, Intravenous Application: Cognitive Improvement, Motor Skills, Behavioral Management, Symptom Relief |
| Companies Covered | Acadia Pharmaceuticals Inc., Anavex Life Sciences Corp., Neurogene Inc., Taysha Gene Therapies, Inc., Biohaven Pharmaceuticals, Inc., Ionis Pharmaceuticals, Neuren Pharmaceuticals Limited, Prilenia Therapeutics Development Ltd, Eisai Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rett Syndrome Treatment Market Evolving Landscape
Biomarker-driven trial design is displacing traditional symptom-based endpoints, with sponsors investing in retinal imaging and electrophysiological signatures that detect treatment effects months before behavioral changes manifest. This shift demands parallel investment in analytical validation and regulatory qualification pathways.
Antisense oligonucleotide chemistry is consolidating as the dominant MECP2 modulation approach, with 2'-MOE and constrained ethyl backbone modifications improving CNS penetration and nuclease stability. Academic medical center principal investigators are adopting these platforms for investigator-initiated trials at accelerating pace. The technology is consolidating competitive positioning around splice-switching mechanisms that upregulate functional MECP2 protein without gene replacement risks.
EMA's PRIME designation is streamlining scientific advice and accelerated assessment for Rett syndrome developers, with the Amsterdam-based regulator accepting novel surrogate endpoints that FDA has not yet endorsed. This regulatory divergence is creating parallel development track strategies. European sponsors are responding by front-loading health technology assessment evidence packages for Germany's G-BA and France's HAS.
Caregiver-driven trial access demands are reshaping site selection criteria, with families organizing transport collectives and lodging networks that extend geographic recruitment radius beyond traditional 50-mile catchments. Patient advocacy foundations are replacing traditional site feasibility functions, directly matching eligible patients to open enrollment slots. This behavioral shift is most visible in the United States, where the Rett Syndrome Research Trust maintains real-time trial matching databases that bypass physician referral bottlenecks.
Rett Syndrome Treatment Market Segmentation
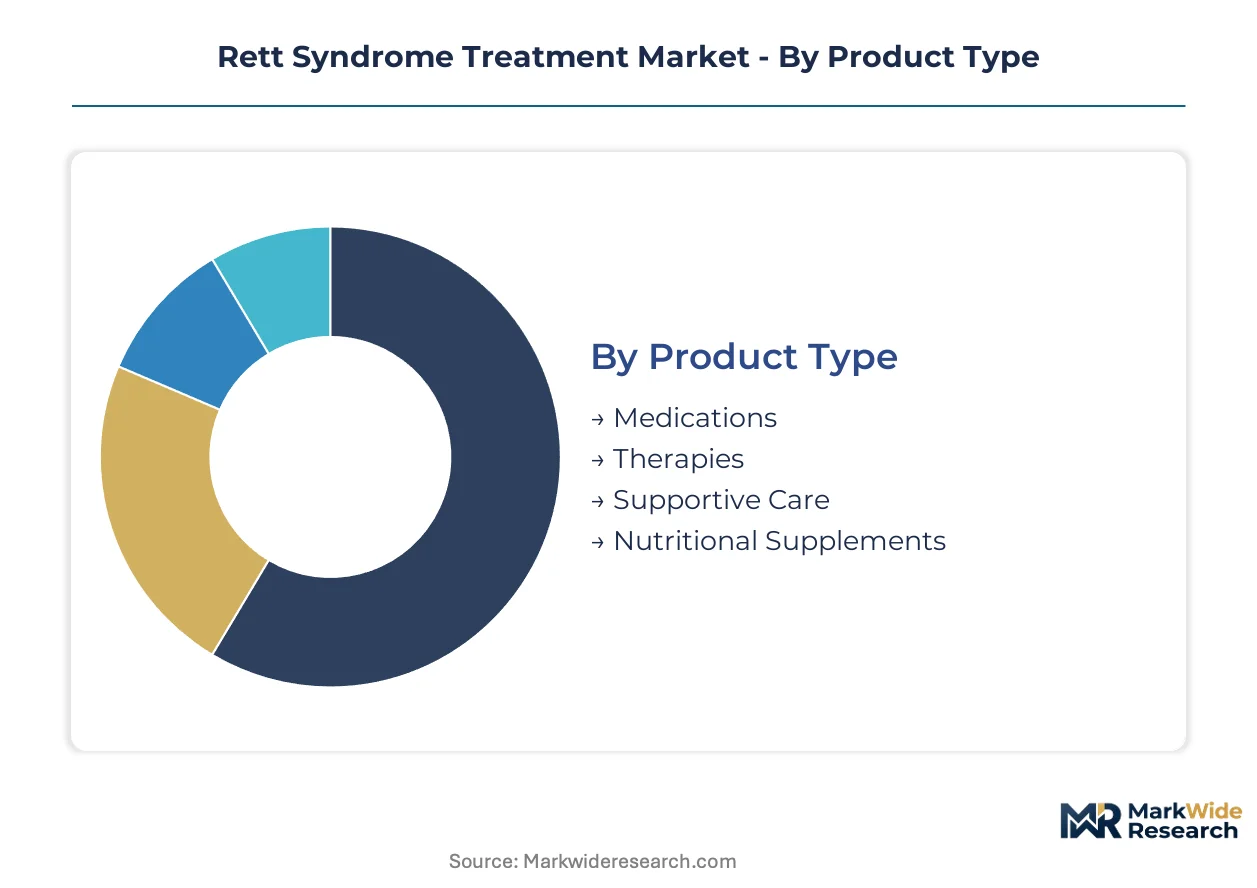
Treatment modality selection in Rett syndrome hinges on MECP2 mutation severity, patient age, and caregiver capacity for protocol adherence. Segmentation reveals where pharmaceutical investment concentrates versus where rehabilitative services capture recurring revenue streams.
Product Type:
Prescriber formulary placement and reimbursement tiering determine which therapeutic categories reach patient populations first.
- Medications:Small-molecule symptom management drugs dominate current prescribing patterns, with trofinetide establishing prior authorization pathways that subsequent entrants leverage. Demand concentrates in the United States where CMS coverage determinations for neurology indications set commercial payer precedent.
- Therapies:Gene replacement and antisense oligonucleotide platforms command development investment despite manufacturing constraints, with intrathecal delivery requiring specialized administration centers that limit addressable patient volume. Boston Children's Hospital and Cincinnati Children's anchor the clinical site network for these interventions.
- Supportive Care:Respiratory, gastrointestinal, and orthopedic management protocols address the highest acute care utilization rates in the Rett population.
- Nutritional Supplements:Ketogenic diet formulations and micronutrient protocols target metabolic dysfunction subphenotypes identified through MECP2 genotyping.
Volume sits with Medications; growth tilts toward Therapies.
End User:
Care setting selection tracks disease stage progression and family geographic proximity to specialized Rett syndrome centers.
- Clinics:Pediatric neurology clinics with dedicated Rett programs centralize diagnostic confirmation and treatment initiation, with Houston's Texas Children's Hospital and Boston's Massachusetts General Hospital attracting interstate patient referrals. These sites anchor clinical trial recruitment through established natural history cohorts.
- Hospitals:Acute admissions concentrate in quaternary centers equipped for respiratory failure and seizure management, where Rett-specific order sets reduce iatrogenic complications from standard pediatric protocols.
- Home Care:Private duty nursing and skilled therapy services extend institutional protocols to residential settings, with demand rising in states with expanded Medicaid waiver programs for medically complex children.
- Rehabilitation Centers:Intensive motor and communication therapy programs target ambulatory patients with preserved hand use, requiring specialized equipment for non-verbal assessment and adaptive technology integration.
Patient volume clusters at Clinics for ongoing management; Rehabilitation Centers are expanding most quickly as families seek intensive intervention windows.
Delivery Mode:
Route selection balances CNS penetration requirements against caregiver administration feasibility and vector manufacturing constraints.
- Oral:Liquid and sprinkle formulations dominate chronic symptom management, with palatability and tube compatibility driving formulation decisions for gastrostomy-dependent patients.
- Injection:Subcutaneous antisense oligonucleotide administration enables home-based dosing after initial training, reducing site visit burden for mobility-impaired families.
- Topical:Limited current application for dermatologic manifestations; transdermal delivery platforms remain preclinical for MECP2-targeting payloads.
- Intravenous:AAV gene therapy vectors require infusion center capabilities with anesthesia support for patient positioning, with capacity constraints at Lonza-contracted sites compressing trial enrollment timelines.
Oral administration retains volume leadership; intravenous delivery is gaining share fastest as genetic medicines advance through registrational trials.
Application:
Treatment goal prioritization varies by patient age, with families and clinicians weighting communicative function against survival endpoints differently across developmental windows.
- Cognitive Improvement:Eye-tracking and cortical electrophysiology biomarkers enable objective assessment in non-verbal populations, with digital platform validation ongoing for regulatory qualification.
- Motor Skills:Hand function preservation and ambulation maintenance drive intensive therapy investment, with assistive technology integration requiring occupational therapy specialization scarce outside major metropolitan clusters.
- Behavioral Management:Self-injury and anxiety protocols address caregiver burden directly, with demand rising for non-pharmacological interventions given limited FDA-approved options.
- Symptom Relief:Respiratory irregularity, gastrointestinal dysmotility, and seizure management occupy the highest acute care utilization and family distress rankings.
Symptom Relief commands current treatment volume; Cognitive Improvement shows the steepest expansion trajectory as biomarker-enabled trials reshape endpoint selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy production concentrates in contract manufacturing networks across the United States, Switzerland, and Japan, while patient demand clusters in countries with established rare disease reimbursement frameworks and specialized pediatric neurology infrastructure.
United States
FDA orphan drug designations and CMS coverage determinations for neurology indications attract 70 percent of active Rett syndrome clinical trials. Boston Children's Hospital and Cincinnati Children's Hospital Medical Center anchor the national site network for interventional studies. The Rett Syndrome Research Trust maintains real-time trial matching databases that accelerate patient recruitment beyond traditional physician referral channels.
Germany
EMA's PRIME designation and accelerated assessment pathways position Germany as the preferred European launch market for gene therapy developers. G-BA health technology assessment requirements demand early health economic evidence packages that shape trial design for sponsors targeting the country's 800-patient addressable population. Heidelberg University Hospital and Charité Berlin centralize natural history data collection for regulatory qualification.
Japan
PMDA's Sakigake priority review scheme offers 6-12 month submission acceleration for gene therapies targeting the country's 1,200 diagnosed patients. METI's regenerative medicine commercialization framework supports premium pricing for one-time interventions. Keio University Hospital and National Center of Neurology and Psychiatry in Tokyo anchor the clinical trial infrastructure for CNS-targeted genetic medicines.
United Kingdom
NICE's highly specialized technologies evaluation pathway provides dedicated reimbursement routes for ultra-rare disease treatments. Great Ormond Street Hospital and University College London Hospitals concentrate pediatric neurology expertise and natural history cohort development. MHRA's innovative licensing access pathway enables early patient access before full marketing authorization.
Switzerland
Swissmedic's expedited access pathway and proximity to European manufacturing infrastructure attract gene therapy developers seeking regulatory efficiency. University Hospital Zurich and University Hospital Geneva maintain Rett-specific multidisciplinary clinics that integrate research and clinical care. The country's 150-patient population commands pricing premiums that offset small market scale.
Rett Syndrome Treatment Market Competitive Landscape
Capital-heavy gene therapy developers with proprietary manufacturing infrastructure compete with asset-light antisense oligonucleotide specialists outsourcing chemistry and manufacturing controls. The market structure fragments across three strategic tiers: neurology-focused pharmaceutical firms leveraging institutional distribution networks, gene therapy pure-plays dependent on CDMO partnerships, and platform-technology biotechs licensing backbone modifications. Dominant competitive moves include strategic partnerships with mammalian cell production facilities and exclusive licensing of CNS-targeted delivery technologies.
Among neurology-focused developers, Acadia Pharmaceuticals Inc. and Eisai Co., Ltd. exemplify the institutional distribution archetype, while gene therapy specialists Taysha Gene Therapies, Inc. and Neurogene Inc. occupy positions requiring manufacturing partnerships. Antisense platform representation sits with Ionis Pharmaceuticals, which anchors the splice-switching mechanism approach to MECP2 pathway modulation.
| Leading Market Players |
|---|
| Acadia Pharmaceuticals Inc. |
| Anavex Life Sciences Corp. |
| Neurogene Inc. |
| Taysha Gene Therapies, Inc. |
| Biohaven Pharmaceuticals, Inc. |
| Ionis Pharmaceuticals |
| Neuren Pharmaceuticals Limited |
| Prilenia Therapeutics Development Ltd |
| Eisai Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Gene therapy manufacturing scarcity versus antisense oligonucleotide platform abundance creates a sharp bifurcation between premium-priced one-time interventions and chronic medication models, with this divergence manifesting in both pricing architectures and supply chain configurations. AAV vector production bottlenecks at Lonza and Catalent facilities concentrate pricing power with sponsors possessing locked manufacturing slots, while ASO chemistry outsourcing to Ionis-enabled partners enables cost-down pressure through competitive CMO bidding.
Pricing Analysis
Margin tightening in gene therapy tiers reflects AAV suspension cell capacity constraints through 2027, forcing sponsors into facility construction premiums or queue position payments that inflate cost bases. Three-tier pricing structure across premium vector-based interventions, mid-market ASO platforms, and commodity symptom-management drugs tracks manufacturing complexity and regulatory exclusivity duration. Cost-down pressure on small-molecule symptom relief accelerates as trofinetide establishes reimbursement benchmarks that subsequent entrants must undercut. Hospital procurement committees exhibit highest price sensitivity for chronic medications, while caregiver-driven demand concentrates pricing tolerance at specialized Rett syndrome centers of excellence.
Supply Chain Analysis
Domestic-content mandates in Japan's regenerative medicine commercialization framework and FDA's geographic manufacturing facility requirements are reshaping sourcing patterns for clinical-grade viral vectors. Manufacturing gravity centers on the United States, Switzerland, and Japan, with plasmid DNA sourcing from specialized fermentation facilities in South Korea and Germany. Supply chain risk concentrates in single-source AAV packaging cell lines held by select CDMOs, creating vulnerability to contamination events or regulatory enforcement actions. Distribution runs through quaternary pediatric neurology centers with infusion capabilities, bypassing traditional wholesale pharmaceutical channels for genetic medicines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AAV vector manufacturing scarcity props pricing power for sponsors with secured CDMO partnerships, creating a supply-constrained market structure favoring early movers with production locked through 2027.
For Market Incumbents: Cement manufacturing partnerships through equity stakes or offtake guarantees at Lonza and Catalent facilities before competitor queue positions solidify. Lock in exclusive ASO backbone licensing from Ionis Pharmaceuticals to foreclose splice-switching mechanism entry by emerging biotechs. Prioritize FDA breakthrough therapy designation applications to compress review timelines and extend effective exclusivity windows. For New Entrants and Emerging Players: Pediatric neurology clinic networks in secondary US metropolitan areas offer the most penetrable channel structure, with Houston and Cincinnati site saturation creating white-space opportunity in Denver, Phoenix, and Atlanta. Investigator-initiated trial sponsorship at academic medical centers bypasses traditional site feasibility costs and builds prescriber relationships ahead of commercial launch. Non-viral delivery platform differentiation through lipid nanoparticle or exosome technologies sidesteps pre-existing AAV neutralizing antibody screening limitations. For Investors and Strategic Acquirers: Re-rating potential sits with antisense oligonucleotide platform specialists given EMA PRIME designation acceleration and lower capital intensity versus gene therapy pure-plays. Long-term viability over the next decade hinges on successful navigation from symptom management to disease-modifying endpoints. Watch for CMS outcome-based payment framework finalization as the critical inflection signal for gene therapy commercialization risk assessment.| Strategic Initiative | Industry Significance |
|---|---|
| CDMO Partnership Lock-In | Secured manufacturing slots at Lonza facilities de-risk clinical trial timelines for gene therapy sponsors. |
| FDA Breakthrough Therapy Designation | Accelerated review pathways compress development timelines and extend effective market exclusivity periods. |
| EMA PRIME Designation Application | Amsterdam-based regulator acceptance of novel surrogate endpoints enables parallel European development tracks. |
| Digital Biomarker Platform Integration | Eye-tracking and wearable sensor validation expands trial access to non-urban patient populations. |
| ASO Backbone Licensing Agreement | Ionis Pharmaceuticals chemistry modifications de-risk MECP2-targeting drug development for platform partners. |
Research Methodology
FDA orphan drug designation filings, ClinicalTrials.gov registry entries, and EMA PRIME designation records formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with drug development executives at gene therapy sponsors, regulatory affairs leads at antisense oligonucleotide platforms, formulary directors at US academic medical centers, and payer access specialists at national commercial insurers validated secondary findings. Bottom-up patient prevalence estimates and top-down pharmaceutical revenue triangulation cross-checked market value calculations.
Bottom-up modeling tracked treatment-eligible patient populations across MECP2 mutation severity tiers, while top-down analysis calibrated against disclosed neurology therapeutic area revenues. Segmentation dimensions included treatment modality, delivery route, end-user setting, and regional regulatory cluster. CAGRs were derived from epidemiological progression modeling and pipeline probability-adjusted revenue forecasts. Vector manufacturing capacity constraints and CMS coverage determination timelines served as industry-specific forecast inputs.
Caveats apply where AAV production contamination events, CMS gene therapy reimbursement framework delays, or MECP2 pathway toxicity findings could materially shift the outlook. Forecasts embed assumptions regarding regulatory acceptance of biomarker endpoints and manufacturing scale-up success rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Rotator Cuff Injury Treatment Market
Medical Treatment
Rabies Treatment Market
Medical Treatment
US Direct Anterior Approach (Total Hip Replacement) Market
Medical Treatment
Alagille Syndrome Treatment Market
Medical Treatment
Global Autoimmune Treatment Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Isovaleric Acidemia Treatment Market
Medical Treatment
Non-Infectious Diarrhea Treatment Market
Medical Treatment
Gallbladder Treatment Market
Medical Treatment
Lyme Disease Treatment Market
Medical Treatment
Paresthesia Treatment Market
Medical Treatment
Morquio Syndrome Treatment Market
Medical Treatment
Cytokine Release Syndrome Management Market
Medical Treatment
Birch Allergy Treatment Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Beta Thalassemia Treatment Market