
 Precocious Puberty Treatment Market | 2026-2036
Precocious Puberty Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Precocious Puberty Treatment Market Analytics
Long-acting depot formulations is collapsing the treatment burden for families managing central precocious puberty. Pfizer Inc. leverages its manufacturing scale to sustain supply of established GnRH agonist platforms across North America and Europe. AbbVie Inc. competes through specialized pediatric endocrinology partnerships that anchor its institutional presence. Tolmar Pharmaceuticals, Inc. differentiates via advanced polymer-based delivery systems that extend dosing intervals.
Precocious puberty treatment encompasses pharmacological and surgical interventions that suppress premature activation of the hypothalamic-pituitary-gonadal axis, typically employing GnRH agonists formulated as monthly or tri-monthly depot injections to halt sex steroid production and preserve adult height potential. GnRH Agonists dominate product-type revenue due to decades of clinical validation and established reimbursement pathways, while Aromatase Inhibitors occupy a narrower niche for atypical presentations. Pediatric Clinics lead end-user channels through dedicated referral networks, though Hospitals sustain higher per-procedure margins for surgical interventions.
The FDA governs pediatric drug labeling and post-market surveillance requirements for hormonal therapies, while the EMA's pediatric investigation plans mandate age-appropriate formulation studies before market authorization in Europe. These frameworks shape development timelines and access conditions across jurisdictions. Stakeholders must monitor evolving regulatory expectations for real-world evidence generation as payers tighten criteria for treatment initiation.
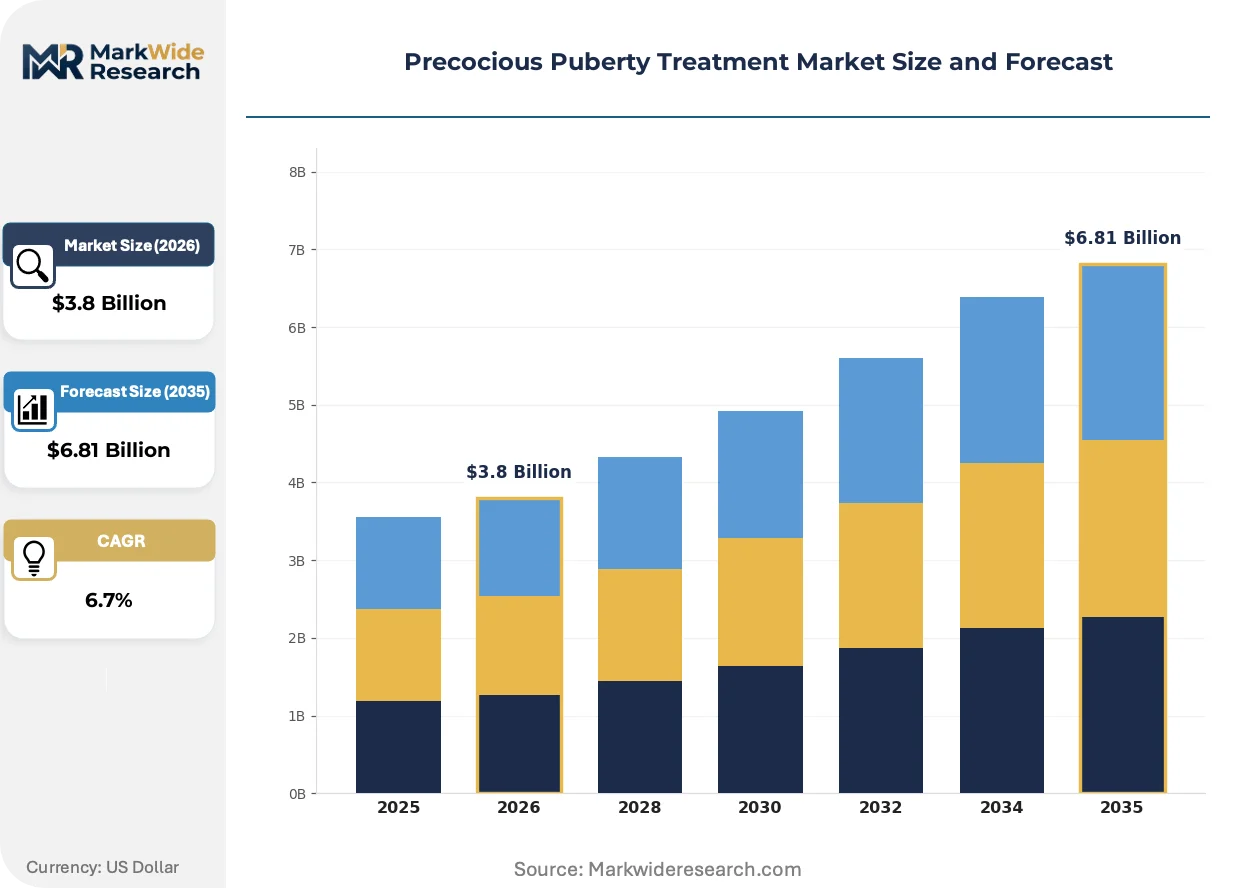
Market Dynamics
Long-acting depot formulations are collapsing the treatment burden for families managing central precocious puberty, compressing dosing intervals from monthly to tri-monthly cycles and reshaping adherence economics across pediatric endocrinology.
Growth Catalysts
- Best Pharmaceuticals for Children Act:FDA pediatric exclusivity provisions incentivize development of age-appropriate formulations, accelerating clinical trial investment in GnRH agonist delivery systems.
- Diagnostic referral networks:United States specialist access infrastructure drives treatment initiation rates through coordinated pediatric endocrinology clinic expansion.
- Polymer-based delivery systems:Advanced depot technologies extend dosing intervals, reducing family logistics burden and improving therapeutic persistence.
Market Restraints
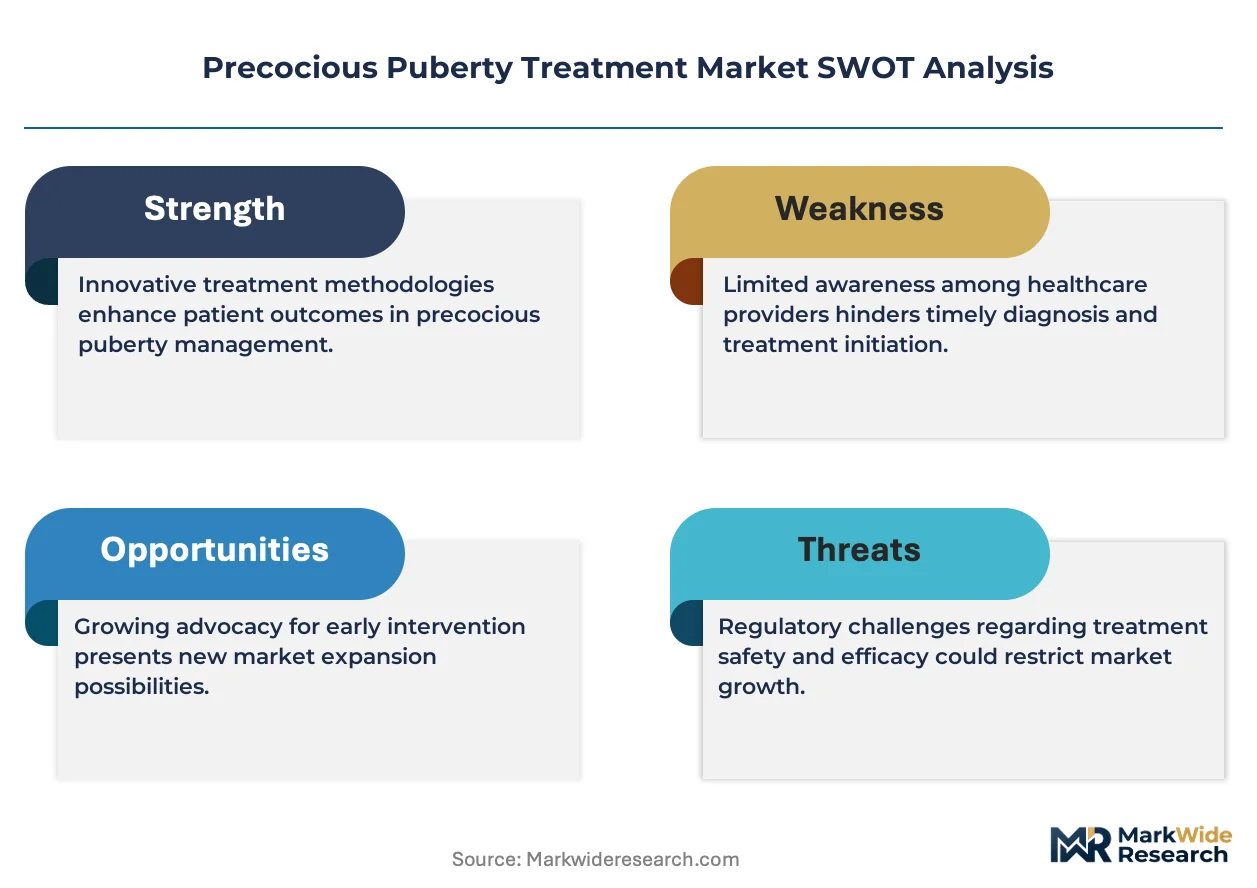
- Specialist concentration:Pediatric endocrinologist supply constraints in rural United States regions create geographic access inequities, delaying diagnosis and treatment initiation.
- Reimbursement heterogeneity:Medicaid state-level variation in GnRH agonist coverage criteria fragments patient access across United States jurisdictions.
- Surgical intervention limitations:Hypothalamic hamartoma resection carries neurosurgical risks that constrain application to pharmacologically refractory cases.
Strategic Opportunities
- EMA pediatric investigation plans:European regulatory mandates for age-appropriate formulation studies create first-mover advantage for sponsors completing PIP-compliant development programs.
- Subcutaneous implant platforms:Biodegradable implant technologies promise annual dosing intervals, opening pediatric patient segments currently lost to injection fatigue.
- Telemedicine-enabled monitoring:Remote bone age assessment and growth velocity tracking expand specialist reach into underserved United States rural markets.
Industry Challenges
- Pediatric formulation expertise:Limited pharmaceutical development talent experienced in palatable oral suspensions and child-friendly delivery systems constrains pipeline advancement.
- Real-world evidence generation:Payer demands for long-term adult height outcome data extend post-market study timelines and inflate regulatory compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precocious Puberty Treatment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GnRH Agonists, Anti-androgens, Aromatase Inhibitors, Selective Estrogen Receptor Modulators End User: Pediatric Clinics, Hospitals, Outpatient Facilities, Research Institutes Treatment Procedure: Pharmacological Intervention, Surgical Intervention, Hormonal Therapy, Monitoring Administration Route: Injectable, Oral, Transdermal, Intranasal |
| Companies Covered | Pfizer Inc., Sanofi S.A, Ferring Pharmaceuticals, AbbVie Inc., Ipsen Pharma, Tolmar Pharmaceuticals, Inc., Arbor Pharmaceuticals, Sun Pharmaceutical Industries Ltd., Endo International plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precocious Puberty Treatment Market Evolving Landscape
Formulation science and regulatory science are converging to redefine competitive advantage in pediatric hormonal therapy, with delivery mechanism innovation outpacing molecular discovery.
Implantable GnRH agonist depots are miniaturizing from matchstick-sized rods to injectable microspheres, enabling office-based administration without surgical implantation. Pediatric endocrinology clinics in major United States metropolitan areas are adopting these platforms to eliminate operating room scheduling dependencies. The technology is miniaturizing treatment logistics from multi-visit surgical procedures to single-injection outpatient encounters, compressing total cost of care.
EMA's pediatric investigation plan requirements now mandate age-appropriate pharmacokinetic studies before European market authorization, extending development timelines by 24-36 months for sponsors lacking pediatric formulation capabilities. This regulatory friction is favoring established players with dedicated pediatric development infrastructure over emerging competitors. United States sponsors are responding by front-loading PIP-compliant studies to secure simultaneous transatlantic approvals.
Family preference for reduced clinic visit frequency is displacing monthly injection schedules in favor of extended-interval depot products, even where copay differentials favor shorter-acting alternatives. United States commercial payers are recognizing this behavioral shift by tiering prior authorization criteria around adherence outcomes rather than unit cost alone. Pediatric specialty pharmacies are consolidating dispensing volume as families seek coordinated refill management for multi-month supplies.
Precocious Puberty Treatment Market Segmentation
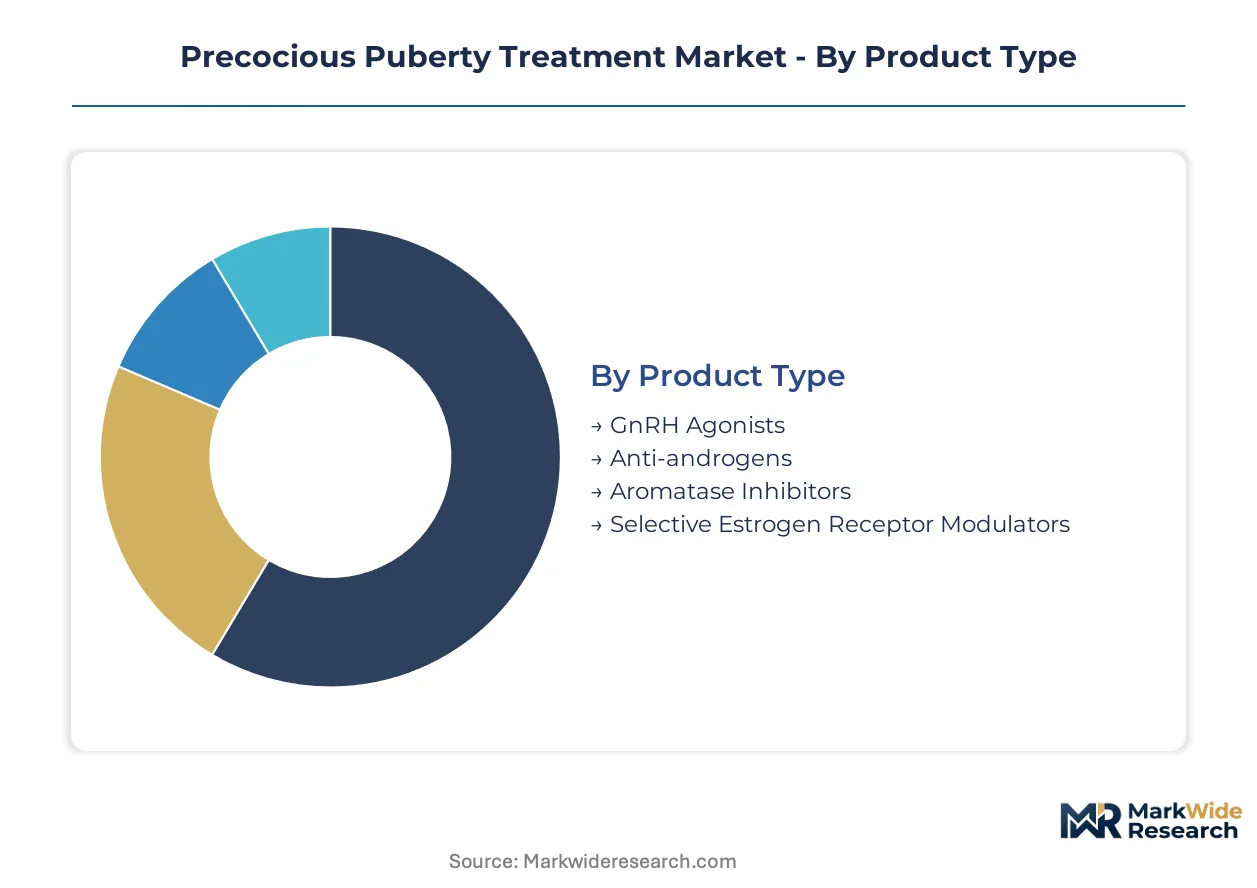
Treatment modality segmentation in precocious puberty reflects divergent reimbursement economics and patient age stratification. Formulation complexity and administration logistics determine competitive positioning across pediatric endocrinology channels.
Product Type:
Geographic demand concentration varies sharply by mechanism of action, with depot GnRH agonists dominating United States commercial reimbursement while oral alternatives gain traction in European ambulatory settings.
- GnRH Agonists:Synthetic peptide analogs of gonadotropin-releasing hormone formulated as monthly or tri-monthly depot suspensions. United States pediatric endocrinology clinics drive volume through established prior authorization pathways with commercial payers, though Medicaid state-level coverage variation fragments access.
- Anti-androgens:Steroidal and non-steroidal androgen receptor antagonists employed for peripheral precocious puberty presentations. Demand concentrates in academic medical centers managing rare congenital adrenal hyperplasia variants, where specialist diagnostic capacity determines treatment initiation rates.
- Aromatase Inhibitors:Third-generation azole derivatives blocking estrogen biosynthesis in peripheral tissues. Off-label utilization in atypical presentations limits formal reimbursement, constraining volume to self-pay and compassionate access programs.
- Selective Estrogen Receptor Modulators:Triphenylethylene derivatives modulating estrogen receptor activity in bone and pituitary tissues. McCune-Albright syndrome applications drive niche demand through specialized metabolic bone disease centers.
GnRH Agonists holds the largest share; momentum sits with Anti-androgens.
End User:
Channel economics stratify sharply by procedure intensity and reimbursement tier, with facility fees driving margin differentiation across delivery settings.
- Pediatric Clinics:Dedicated endocrinology practices with coordinated referral networks and nurse injection services. United States metropolitan markets sustain volume through subspecialist density, while rural access gaps delay diagnosis in underserved counties.
- Hospitals:Tertiary academic centers managing surgical interventions and complex comorbidities. Operating room scheduling dependencies and facility fee structures elevate per-episode costs above ambulatory alternatives.
- Outpatient Facilities:Ambulatory surgery centers and infusion clinics handling depot administration. Cost compression from site-of-service differentials is displacing hospital-based injection volume in commercial payer networks.
- Research Institutes:Clinical trial sites and academic research organizations conducting pediatric investigation plan studies. EMA-mandated age-appropriate pharmacokinetic requirements anchor European development activity in these settings.
Pediatric Clinics capture the highest volume; Hospitals retain the premium pricing tier.
Treatment Procedure:
Procedure selection follows diagnostic classification, with central versus peripheral etiology determining pharmacological versus surgical pathways.
- Pharmacological Intervention:GnRH agonist suppression of hypothalamic-pituitary-gonadal axis activation. Long-acting depot formulations are collapsing family treatment burden through extended dosing intervals.
- Surgical Intervention:Hypothalamic hamartoma resection or ovarian/testicular tumor excision. Neurosurgical risk profiles constrain application to pharmacologically refractory or organic lesion cases.
- Hormonal Therapy:Adjunctive sex steroid blockade or replacement protocols. Atypical presentation management drives utilization in academic referral centers with advanced diagnostic imaging capacity.
- Monitoring:Serial bone age assessment, growth velocity tracking, and pubertal staging. Telemedicine-enabled remote monitoring is expanding specialist reach into underserved United States rural markets.
Pharmacological Intervention dominates procedure volume; Monitoring is climbing the fastest as value-based care metrics emphasize outcome tracking.
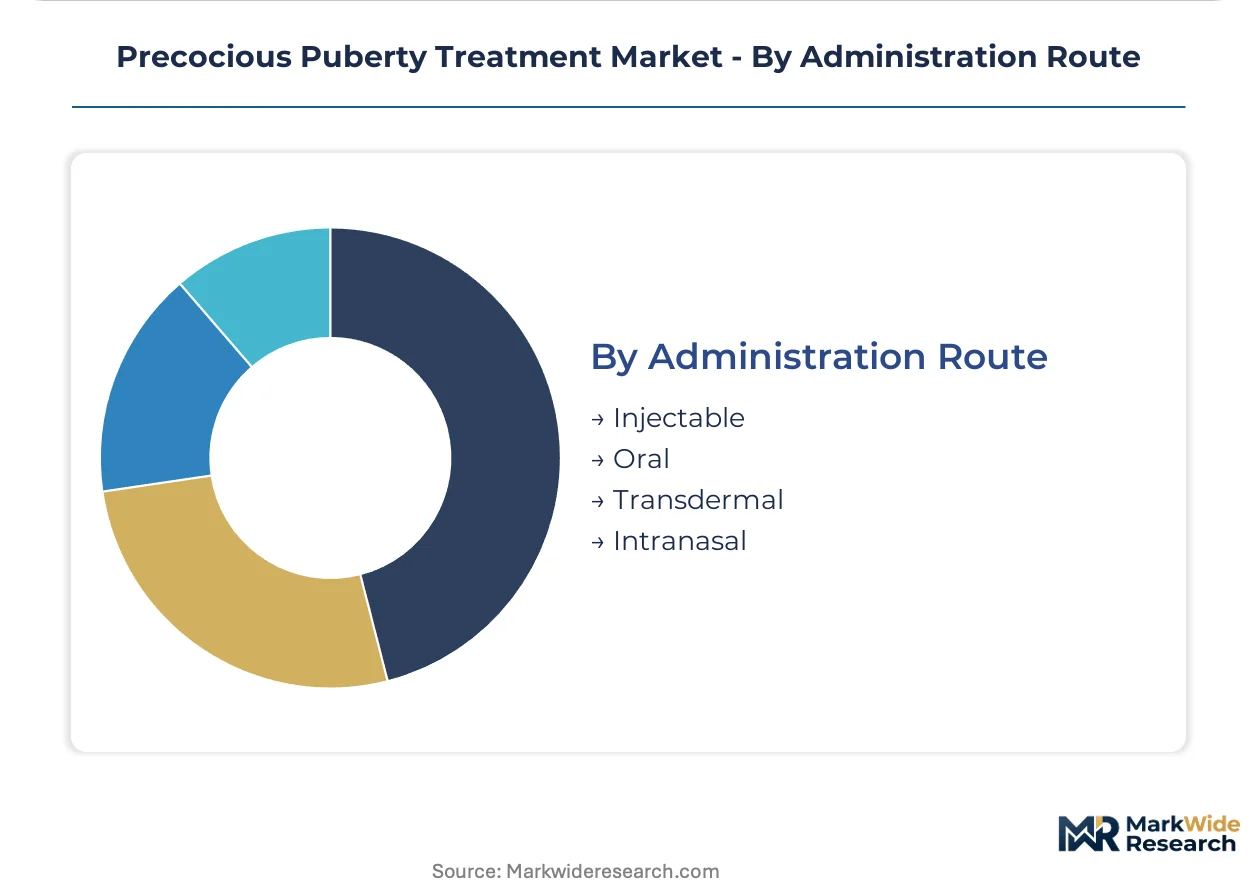
Administration Route:
Route selection reflects patient age, family preference, and formulation availability, with injection fatigue driving innovation toward alternative delivery platforms.
- Injectable:Intramuscular or subcutaneous depot suspensions and implantable rods. Polymer-based microsphere technologies are miniaturizing administration from surgical implantation to office-based injection.
- Oral:Tablet and suspension formulations for anti-androgens and aromatase inhibitors. Palatability challenges in pediatric populations constrain adherence without flavored suspension development.
- Transdermal:Patch and gel delivery systems under investigation for GnRH agonist alternatives. Skin permeation limitations in prepubertal patients have stalled commercialization.
- Intranasal:Spray formulations exploiting nasal mucosa absorption for peptide delivery. Bioavailability variability has relegated this route to investigational status.
Injectable retains absolute volume leadership; Oral formulations are gaining share fastest where palatable suspensions enter development pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for precocious puberty treatment varies sharply across markets, with United States commercial payers absorbing premium depot formulations while European ambulatory settings prioritize cost containment through oral alternatives and centralized procurement.
United States
Pediatric endocrinology referral networks in metropolitan clusters drive treatment initiation rates through coordinated specialist access. FDA pediatric exclusivity provisions under the Best Pharmaceuticals for Children Act accelerate GnRH agonist formulation development. The Boston-New York-Philadelphia corridor anchors clinical trial density for long-acting depot innovations.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia manage rare peripheral precocity presentations through centralized diagnostic hubs. EMA pediatric investigation plans mandate age-appropriate pharmacokinetic studies before market authorization, extending development timelines. Heidelberg and Berlin host the highest concentration of pediatric endocrinology research institutes conducting PIP-compliant studies.
France
ANSM oversight of hormonal therapies shapes labeling requirements for pediatric GnRH agonist indications. The Île-de-France region concentrates tertiary pediatric endocrinology capacity through Parisian hospital networks. Lyon and Marseille sustain specialized metabolic bone disease centers managing McCune-Albright syndrome applications.
Japan
PMDA pediatric drug labeling requirements align with international harmonization initiatives while maintaining domestic formulation standards. The Kanto region around Tokyo hosts the majority of pediatric subspecialist practices. Osaka's Kansai cluster advances telemedicine-enabled growth monitoring for rural patient reach.
United Kingdom
NHS England centralized procurement for GnRH agonists compresses pricing through volume-based tendering mechanisms. The Greater London pediatric endocrinology network refers complex cases to tertiary centers at Great Ormond Street and Evelina London. Manchester and Birmingham sustain regional specialist hubs addressing geographic access inequities.
Precocious Puberty Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in precocious puberty treatment, with formulation science specialists commanding premium positioning while scaled manufacturers compete on supply security and manufacturing efficiency. The market structure consolidates around established GnRH agonist platforms with decades of clinical validation, creating high barriers for molecular innovation. Three archetypes dominate: multinational pharmaceutical conglomerates with pediatric infrastructure, mid-cap specialty endocrinology players, and emerging polymer-delivery technology developers. Competitive moves center on strategic partnerships with academic medical centers for real-world evidence generation and geographic expansion through EMA pediatric investigation plan compliance.
Among multinational developers, Pfizer Inc. and AbbVie Inc. occupy positions anchored by manufacturing scale and institutional partnerships respectively, while Tolmar Pharmaceuticals, Inc. exemplifies the delivery-technology specialist archetype through polymer-based depot innovations. Sanofi S.A and Ipsen Pharma represent European-centric players navigating PIP requirements, with Ferring Pharmaceuticals occupying a mid-cap position between global scale and specialty focus. These named entities serve as structural anchors for understanding competitive dynamics without attributing specific strategic actions or market shares to individual companies.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Sanofi S.A |
| Ferring Pharmaceuticals |
| AbbVie Inc. |
| Ipsen Pharma |
| Tolmar Pharmaceuticals, Inc. |
| Arbor Pharmaceuticals |
| Sun Pharmaceutical Industries Ltd. |
| Endo International plc |
| Others |
Value Network & Pricing Analysis
FDA pediatric exclusivity provisions under the Best Pharmaceuticals for Children Act gate both supply qualification and price differentiation simultaneously, requiring sponsors to complete age-appropriate formulation studies before accessing extended market protection while enabling premium positioning for compliant depot technologies.
Pricing Analysis
After-sales service contracts for injection administration and growth monitoring drive lifetime value in this market. Three-tier pricing structure across premium depot formulations, standard monthly injections, and economy oral alternatives separates Pfizer's established GnRH agonist platforms from AbbVie's partnership-anchored offerings and Tolmar's polymer-based innovations. Cost compression in Medicaid-covered segments is intensifying because state-level coverage variation fragments prior authorization pathways. Pediatric clinics in metropolitan United States markets show least price sensitivity due to commercial payer absorption of premium formulations, while rural access gaps force families toward lower-tier alternatives.
Supply Chain Analysis
Strategic stockpiling of peptide raw materials dominates over just-in-time preferences given the specialized manufacturing requirements for GnRH agonist synthesis. Active pharmaceutical ingredient production concentrates in Switzerland, Ireland, and the United States, with formulation finishing distributed across North American and European sterile manufacturing facilities. Supply chains draw from synthetic peptide precursors, biodegradable polymer excipients, and specialized injection devices. Single-source vulnerability in polymer microsphere technology creates concentration risk for extended-interval depot products. Distribution runs through pediatric specialty pharmacies and hospital outpatient pharmacies with cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-acting depot miniaturization from surgical implantation to office-based injection disrupts treatment economics, with EMA pediatric investigation plan mandates creating regulatory friction that favors established players with dedicated pediatric infrastructure.
For Market Incumbents: Compound manufacturing scale advantages in GnRH agonist APIs with EMA PIP-compliant development programs to secure simultaneous transatlantic approvals. Defend against polymer-delivery specialists by acquiring formulation science capabilities or exclusive licensing agreements for microsphere technologies. Prioritize vertical integration into peptide synthesis to reduce dependency on Swiss and Irish API suppliers. For New Entrants and Emerging Players: Anchor in telemedicine-enabled growth monitoring for underserved United States rural markets where specialist access gaps delay diagnosis and treatment initiation. Target biodegradable implant platforms promising annual dosing intervals, a segment currently lost to injection fatigue among adolescent patients. Pursue strategic partnerships with academic medical centers for real-world evidence generation to satisfy payer demands for long-term adult height outcome data. For Investors and Strategic Acquirers: EMA pediatric investigation plan compliance reshapes the acquisition landscape by extending development timelines and inflating regulatory costs for sponsors lacking pediatric formulation capabilities. Position portfolios around 5-10 year viability windows favoring mid-cap specialty endocrinology players with existing PIP infrastructure over early-stage molecular discovery. Monitor FDA pediatric exclusivity grant rates as the signal indicating whether formulation innovation or manufacturing efficiency will command premium valuations.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Pediatric Investigation Plan Compliance | Front-loading PIP-compliant studies secures simultaneous United States and European market authorization for depot formulations. |
| Polymer-Based Microsphere Development | Miniaturization from surgical implantation to office-based injection compresses total cost of care and eliminates operating room dependencies. |
| Telemedicine-Enabled Growth Monitoring | Remote bone age assessment expands specialist reach into underserved United States rural markets with pediatric endocrinologist supply constraints. |
| Strategic Academic Medical Center Partnerships | Real-world evidence generation satisfies payer demands for long-term adult height outcome data and supports prior authorization criteria. |
| Biodegradable Implant Platform Advancement | Annual dosing intervals address injection fatigue in adolescent patient segments currently lost to treatment discontinuation. |
Research Methodology
A spread of perspectives from pediatric endocrinologists, pharmaceutical regulatory affairs leads, hospital formulary directors, and specialty pharmacy procurement managers converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA pediatric exclusivity filings, EMA pediatric investigation plan submissions, ClinicalTrials.gov registry data, and United States Medicaid formulary databases. Bottom-up patient volume estimates and top-down market sizing triangulated on segment-level figures.
Segmentation dimensions modeled span product type, end user channel, treatment procedure, administration route, and regional regulatory cluster across the projection horizon. CAGRs derived from historical growth trajectory analysis adjusted for formulation innovation cycles and reimbursement policy shifts. Forecast inputs incorporated EMA PIP completion timelines, FDA pediatric exclusivity grant patterns, and United States specialist access infrastructure expansion rates.
Decision-makers should treat outputs as directional under assumptions of stable EMA regulatory requirements and continued United States commercial payer absorption of premium depot formulations; material deviation would warrant model refresh. Revision becomes warranted when Medicaid state-level coverage criteria for GnRH agonists cross thresholds of substantial restriction or expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Iron Deficiency Anemia Treatment Market
Medical Treatment
Acupuncture Treatment Market
Medical Treatment
Tinea Pedis Treatment Market
Medical Treatment
CINV Treatment Market
Medical Treatment
Thymus Cancer Treatment Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Skin Grafts Market
Medical Treatment
Filariasis Treatment Market
Medical Treatment
Purpura Treatment Market
Medical Treatment
Lysosomal Disease Treatment Market
Medical Treatment
Mesenteric Penniculitis Treatment Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Europe Chronic Disease Management Market
Medical Treatment
North America Breast Reconstruction Market