
 North America Chronic Disease Management Market | 2026-2036
North America Chronic Disease Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Chronic Disease Management Market Insights
The gap between premium predictive-analytics platforms and commodity monitoring hardware is broadening as health systems demand outcome-linked software contracts. Epic Systems Corporation anchors its position through deep EHR integration across major hospital networks. Medtronic competes by leveraging its implantable device footprint to capture continuous physiological data streams. Koninklijke Philips N.V differentiates through bedside-to-home monitoring ecosystems that extend hardware lifecycles with subscription software layers.
Chronic disease management encompasses systematic coordination of long-term therapeutic interventions for conditions including diabetes, cardiovascular disorders, and respiratory illness through connected monitoring infrastructure, algorithmic risk stratification, and care-team workflow tools. The primary commercial purpose centers on reducing acute utilization while sustaining patient adherence through automated intervention triggers and personalized care pathways. Telehealth solutions and remote monitoring now dominate delivery mode expansion as reimbursement parity solidifies, while AI and data analytics segments capture disproportionate margin pools through predictive readmission prevention and population health stratification.
FDA digital health guidance, CMS remote therapeutic monitoring codes, and HIPAA interoperability mandates collectively reshape product requirements and market access pathways across the United States and Canada. The FDA's evolving software-as-a-medical-device framework forces vendors to validate algorithmic outputs through clinical studies, raising compliance costs for entrants. Stakeholders must monitor whether provincial health authorities in Ontario and British Columbia adopt comparable reimbursement structures to sustain cross-border platform economics.
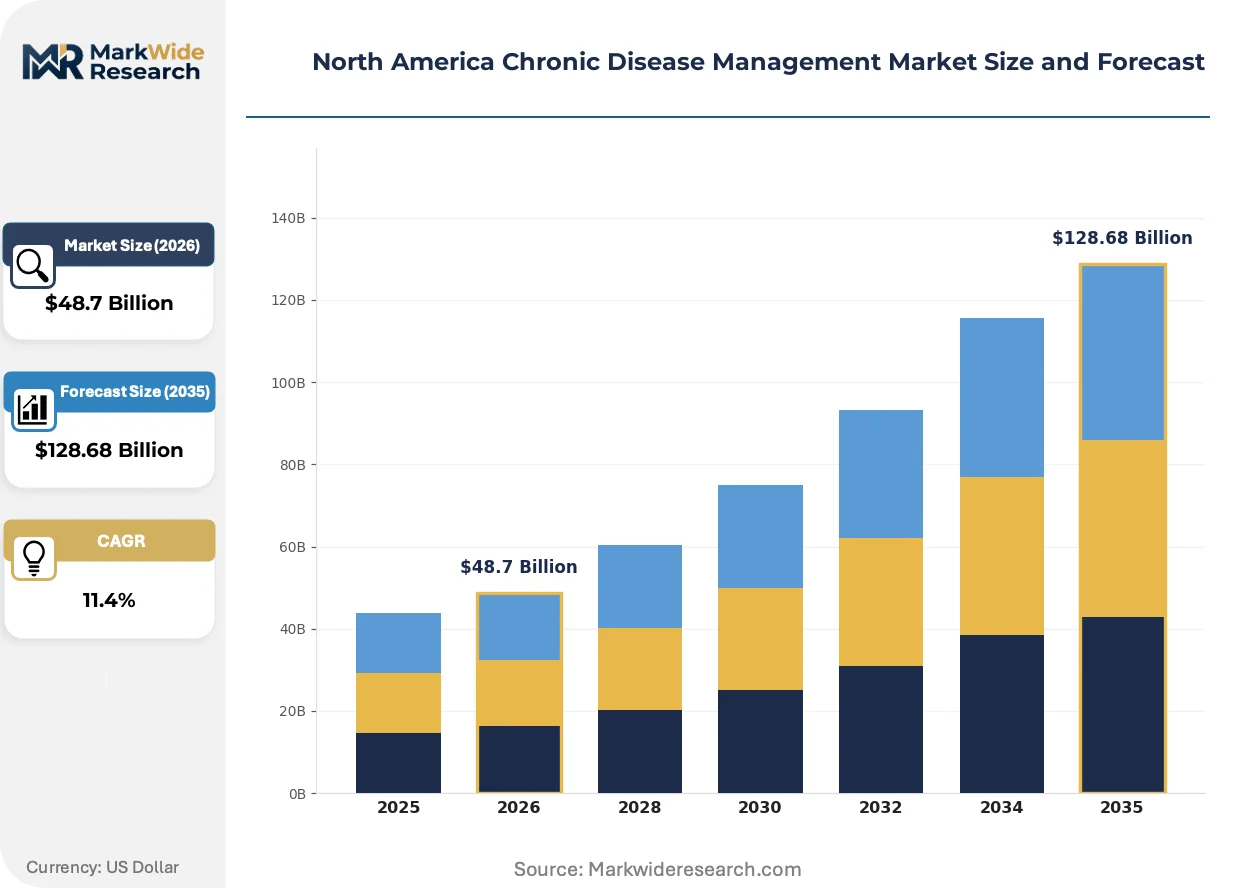
Market Dynamics
CMS reimbursement parity for remote therapeutic monitoring is compressing care delivery into home-based settings, forcing health systems to reconfigure chronic disease workflows around continuous data streams rather than episodic encounters.
Growth Catalysts
- Remote Therapeutic Monitoring Codes:CMS expansion of reimbursable service categories enables physician practices to bill for non-physiologic data collection including medication adherence and therapy response.
- Integrated Delivery Networks:Consolidation of chronic care contracts across California and Texas health systems creates captive demand pools for coordinated platform vendors.
- AI Risk Stratification:Algorithmic readmission prediction tools are absorbing emergency department diversion budgets as hospitals prioritize predictive intervention over reactive treatment.
Market Restraints
- FDA SaMD Validation Costs:The software-as-a-medical-device framework mandates clinical evidence for algorithmic outputs, elevating compliance burdens for platform entrants.
- Interoperability Fragmentation:Disconnected EHR architectures across United States hospital networks impede seamless data exchange between monitoring devices and care coordination systems.
- Workforce Density Constraints:Shortages of clinical informaticists and remote care coordinators in rural Texas and California counties limit deployment velocity of complex monitoring programs.
Strategic Opportunities
- Ontario Provincial Adoption:Comparable reimbursement structures to CMS remote monitoring codes would unlock cross-border platform economics for vendors with United States regulatory clearance.
- Behavioral Health Integration:Convergence of chronic disease management with mental health monitoring addresses comorbid depression and diabetes adherence gaps.
- Direct-to-Employer Channels:Self-insured corporations in Texas energy and California technology sectors are contracting directly for population health platforms bypassing traditional payer intermediaries.
Industry Challenges
- Legacy EHR Integration Complexity:Health systems running older Epic or Cerner instances face protracted implementation timelines for API-connected monitoring platforms.
- Clinical Workflow Redesign:Care teams require sustained training to act upon automated alert thresholds without generating alert fatigue or liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Chronic Disease Management Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Health Monitoring Devices, Wearable Sensors, Mobile Applications, Telehealth Solutions End User: Healthcare Providers, Patients, Caregivers, Wellness Programs Delivery Mode: In-Person, Remote Monitoring, Mobile Platforms, Web-Based Services Technology: IoT, Artificial Intelligence, Data Analytics, Cloud Computing |
| Companies Covered | Koninklijke Philips N.V, Epic Systems Corporation, Medtronic, WellSky, ZeOmega, Health Catalyst, Cedar Gate Technologies, Pegasystems Inc., ScienceSoft USA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Chronic Disease Management Market Trends and Innovations
Algorithmic care coordination is displacing manual case management across North American health systems, with predictive platforms now directing intervention resources before acute episodes materialize.
Continuous glucose monitoring combined with insulin dosing algorithms is absorbing pharmacy benefit budgets as integrated closed-loop systems replace multiple daily injection regimens. Endocrinology practices in Texas and California are adopting these platforms at accelerating velocity. The technology is absorbing margin from traditional blood glucose meter manufacturers while capturing recurring subscription revenue streams.
Health Canada and the FDA are converging on post-market surveillance requirements for AI-enabled diagnostic features, mandating real-world performance tracking across deployed patient populations. This regulatory alignment is elevating documentation burdens for vendors seeking dual jurisdiction approval. United States platform developers are responding by front-loading clinical validation studies to preempt Health Canada review cycles.
Value-based care contracts are restructuring procurement around total cost of care reduction rather than per-member-per-month fees. Risk-bearing entities in California's Medi-Cal managed care programs and Texas Medicaid waiver arrangements are consolidating vendor relationships. This concentration is most visible among county-level health plans seeking single-platform accountability for diabetic and cardiovascular outcomes.
North America Chronic Disease Management Market Segmentation
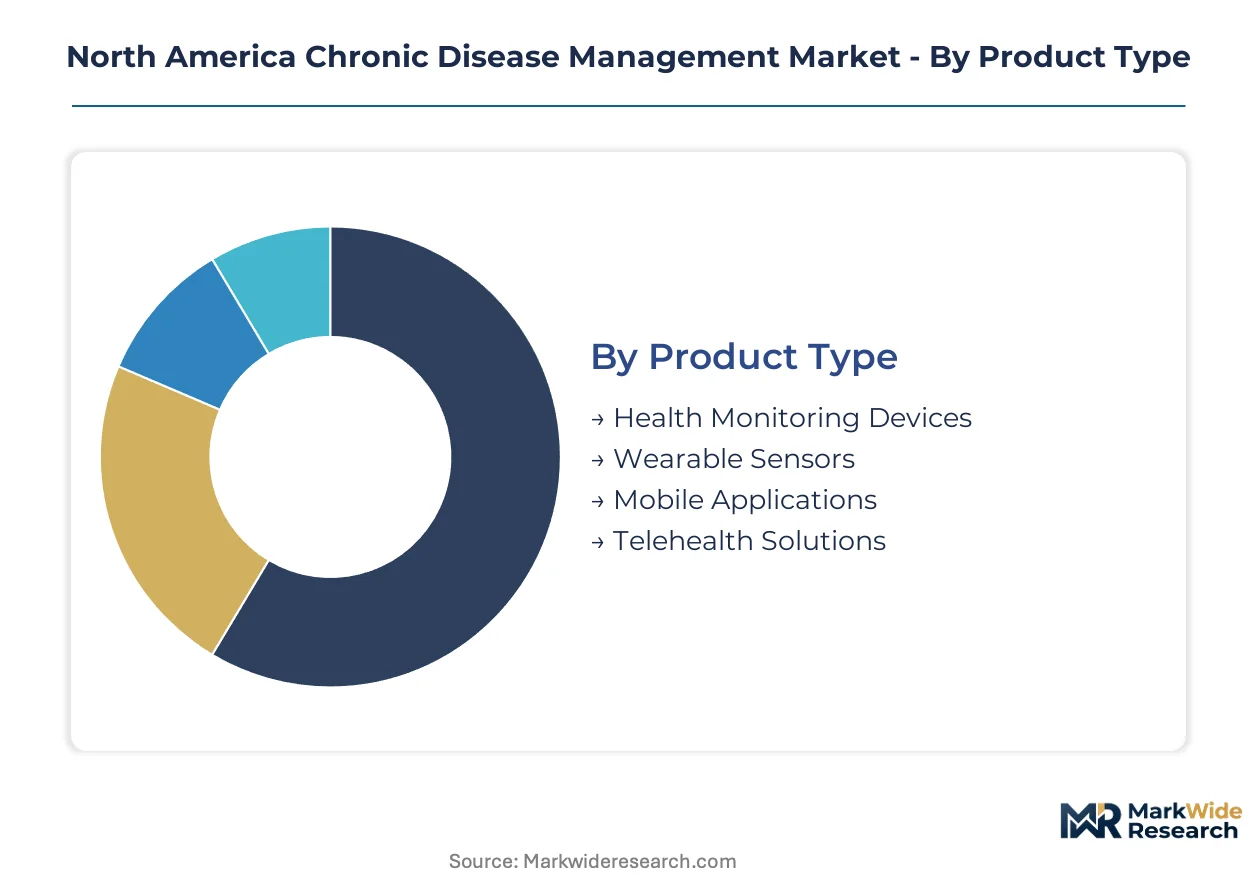
Segmentation in chronic disease management reveals how technology substitution cycles and reimbursement shifts redistribute revenue across hardware, software, and service layers. Understanding these boundaries exposes where margin pools are concentrating versus commoditizing.
Product Type:
Replacement cycles for connected hardware are shortening as CMS reimbursement codes accelerate depreciation schedules for reimburable monitoring equipment.
- Health Monitoring Devices:Stationary diagnostic equipment including blood pressure cuffs, pulse oximeters, and weight scales with cellular connectivity. Demand clusters in Texas and California integrated delivery networks where risk-bearing contracts prioritize readmission reduction metrics over device acquisition cost.
- Wearable Sensors:Continuous glucose monitors, cardiac event recorders, and activity trackers transmitting physiological data streams. California endocrinology practices are absorbing pharmacy budgets into closed-loop insulin delivery systems, compressing traditional meter manufacturer margins.
- Mobile Applications:Patient-facing adherence tools with medication reminders and symptom logging.
- Telehealth Solutions:Synchronous video consultation platforms with EHR-integrated documentation workflows.
Volume placements concentrate in Health Monitoring Devices; the faster expansion belongs to Wearable Sensors.
End User:
Procurement authority is fragmenting as direct-to-employer contracts bypass traditional payer channels in Texas energy and California technology sectors.
- Healthcare Providers:Physician practices, hospital systems, and accountable care organizations purchasing enterprise platforms. Texas Medicaid waiver arrangements and California Medi-Cal managed care programs are consolidating vendor relationships around single-platform accountability for diabetic outcomes.
- Patients:Individual consumers acquiring direct-pay monitoring tools outside reimbursement pathways. Direct-to-consumer glucose monitoring subscriptions are climbing fastest among commercially insured populations in California urban counties.
- Caregivers:Family members and home health aides utilizing delegated access dashboards.
- Wellness Programs:Employer-sponsored population health initiatives with biometric screening integration.
Revenue concentration sits with Healthcare Providers; the steepest expansion trajectory is in Patient-directed procurement.
Delivery Mode:
CMS reimbursement parity is compressing episodic encounters into continuous home-based data streams, restructuring clinical workflow design around asynchronous monitoring.
- In-Person:Traditional clinic-based consultations with point-of-care diagnostic testing. Legacy volume persists in rural Texas counties where broadband infrastructure limits remote deployment and workforce density constrains complex program rollout.
- Remote Monitoring:Continuous physiological surveillance with automated alert routing to care teams. FDA software-as-a-medical-device validation requirements are elevating compliance costs for algorithmic platforms seeking reimbursement eligibility.
- Mobile Platforms:Smartphone-native service delivery with native app distribution.
- Web-Based Services:Browser-accessible portals with multi-device synchronization.
Current volume dominance remains with In-Person encounters; Remote Monitoring is gaining share fastest as reimbursement parity solidifies.
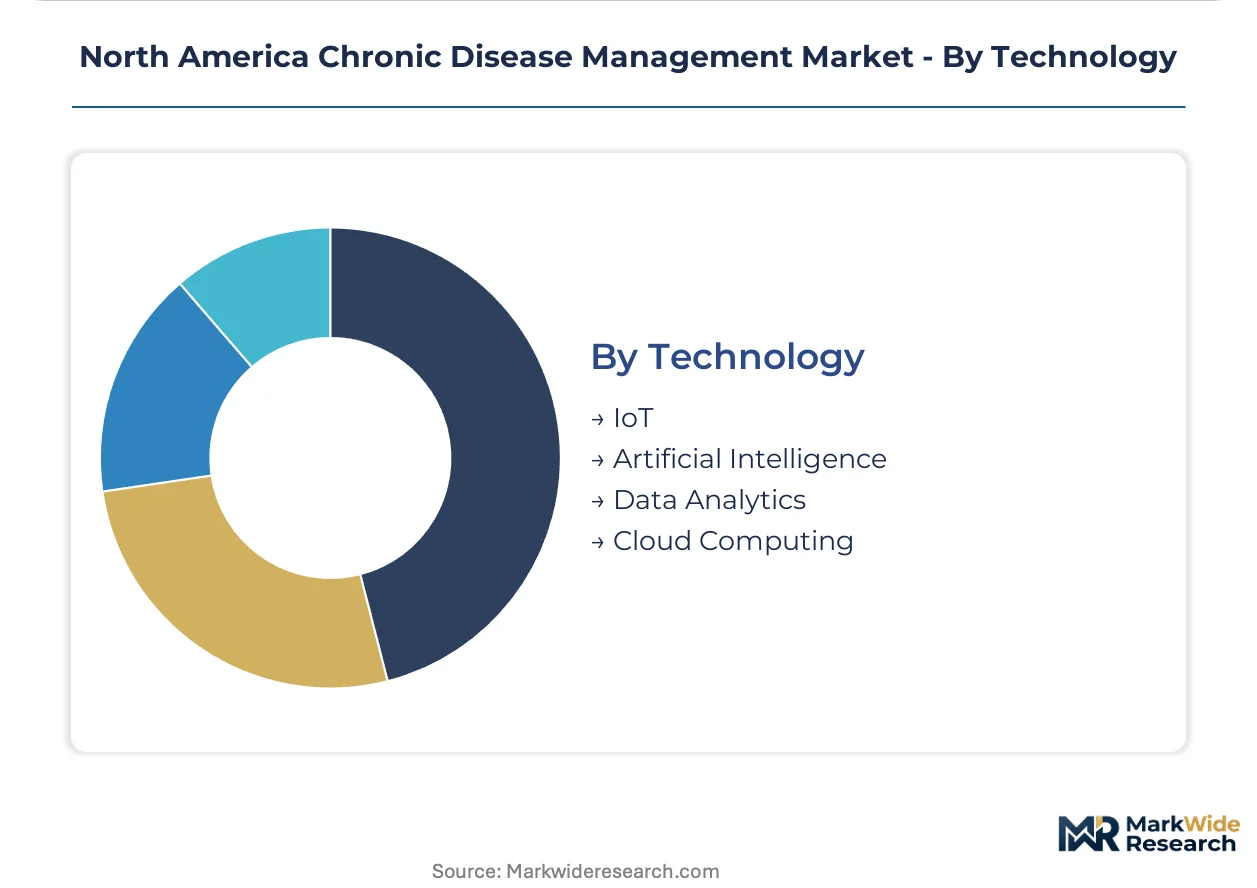
Technology:
AI and data analytics segments are capturing disproportionate margin pools through predictive readmission prevention, while hardware connectivity layers commoditize.
- IoT:Device interconnectivity protocols enabling seamless data transmission from sensors to cloud platforms. Interoperability fragmentation across United States hospital EHR architectures impedes seamless exchange between monitoring devices and care coordination systems.
- Artificial Intelligence:Algorithmic risk stratification and predictive intervention triggering. Health Canada and FDA convergence on post-market surveillance requirements mandates real-world performance tracking across deployed populations, elevating documentation burdens for dual-jurisdiction approval seekers.
- Data Analytics:Population health stratification and outcome measurement dashboards.
- Cloud Computing:Scalable infrastructure for data storage, processing, and API integration.
Margin capture concentrates in Artificial Intelligence; Cloud Computing infrastructure is expanding most quickly as health systems outsource capital-intensive platform operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors North American chronic disease management deployment through Texas Medicaid waiver networks consolidating vendor accountability for diabetic populations.
United States
California and Texas integrated delivery networks absorb the majority of platform procurement as risk-bearing Medi-Cal and Medicaid contracts consolidate around single-vendor diabetic outcomes accountability. FDA software-as-a-medical-device guidance elevates compliance costs for algorithmic platforms seeking CMS reimbursement eligibility. Houston's Texas Medical Center hosts concentrated pilot programs for continuous glucose monitoring closed-loop systems.
Canada
Ontario and British Columbia health authorities evaluate provincial reimbursement structures mirroring CMS remote therapeutic monitoring codes to sustain cross-border platform economics. Health Canada post-market surveillance requirements for AI-enabled diagnostic features mandate real-world performance tracking across deployed populations. Toronto's University Health Network pilots integrated care coordination platforms for cardiovascular risk stratification.
California
Silicon Valley technology employers and Los Angeles County health plans drive direct-to-employer contracting for population health platforms outside traditional payer channels. State-level Medi-Cal managed care procurement consolidates around total cost of care reduction metrics rather than per-member-per-month fees. San Francisco Bay Area endocrinology practices absorb pharmacy budgets into closed-loop insulin delivery subscriptions.
Texas
Energy sector self-insured employers in Houston and Dallas-Fort Worth contract directly for chronic disease platforms bypassing commercial payer intermediaries. Rural counties face deployment constraints from broadband infrastructure gaps and clinical informaticist shortages limiting complex monitoring program rollout. Austin's Dell Medical School anchors value-based care pilot programs for Medicaid diabetic populations.
Greater Boston
Academic medical centers and accountable care organizations prioritize predictive readmission prevention tools absorbing emergency department diversion budgets. Massachusetts health policy innovation creates regulatory templates for behavioral health integration with chronic disease management addressing comorbid depression and diabetes adherence gaps. Cambridge-based digital health ventures anchor FDA premarket validation studies for dual-jurisdiction Health Canada approval.
North America Chronic Disease Management Market Competitive Landscape
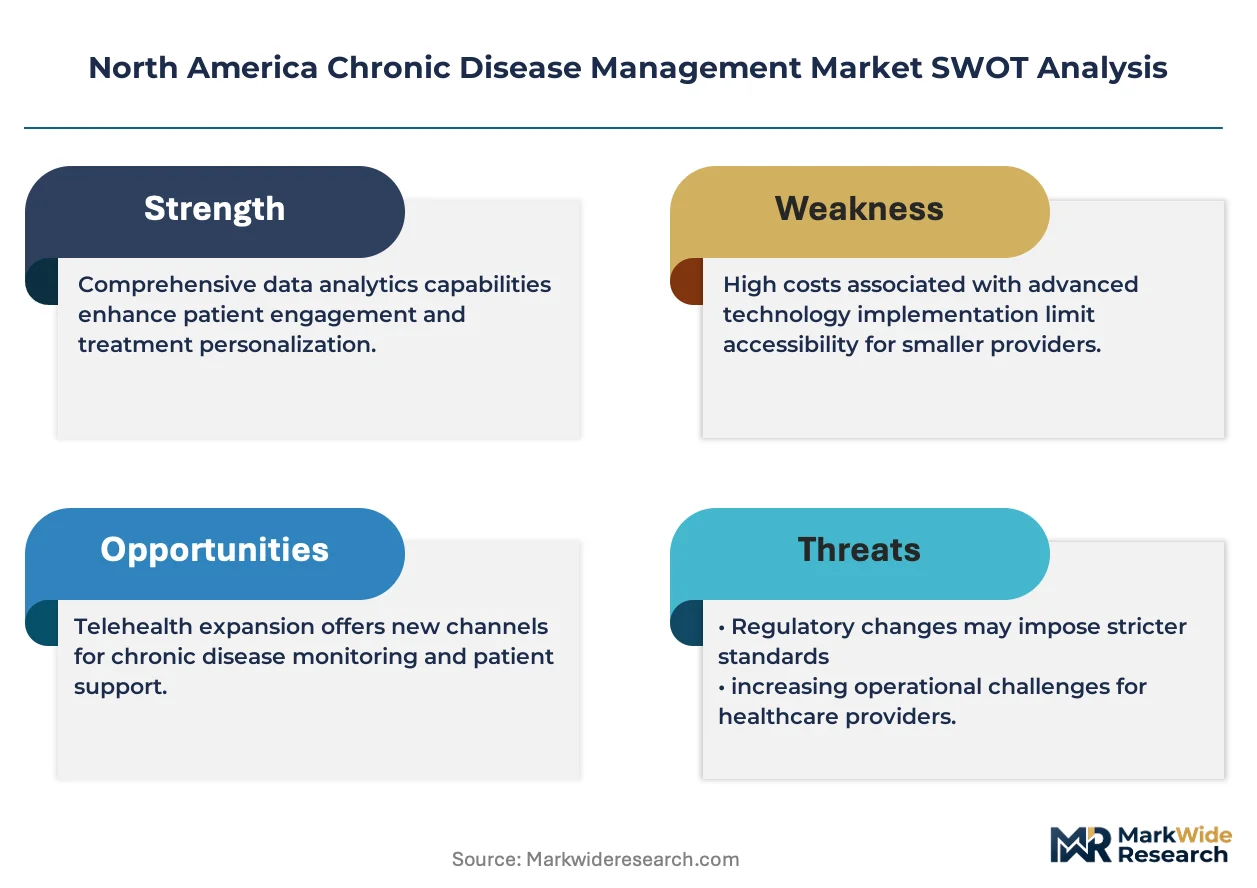
Premium-margin players sit above commodity-margin players across algorithmic risk stratification capabilities, with outcome-linked software contracts commanding pricing multiples over hardware connectivity layers. The vendor base stratifies between EHR-integrated enterprise platforms, implantable device data stream capturers, and bedside-to-home monitoring ecosystem providers. Two dominant competitive moves absorb market attention: strategic partnerships securing health system EHR integration pathways, and portfolio diversification into behavioral health convergence addressing comorbid chronic conditions.
Within the enterprise platform tier, Epic Systems Corporation and Koninklijke Philips N.V exemplify divergent archetypes—one anchoring deep hospital network EHR integration, the other extending hardware lifecycles through subscription software layers. Medtronic occupies a distinct position leveraging implantable device footprints to capture continuous physiological data streams. These three entities represent the primary competitive anchors around which mid-cap specialists and regional platform vendors coordinate partnership strategies.
| Leading Market Players |
|---|
| Koninklijke Philips N.V |
| Epic Systems Corporation |
| Medtronic |
| WellSky |
| ZeOmega |
| Health Catalyst |
| Cedar Gate Technologies |
| Pegasystems Inc. |
| ScienceSoft USA Corporation |
| Others |
Pricing and Supply Chain Analysis
Algorithmic risk stratification software is displacing commodity hardware monitoring, compressing margins on connected devices while elevating pricing power for outcome-linked SaaS platforms that bundle predictive analytics with care coordination workflows. This technology substitution simultaneously concentrates supply among FDA-validated platform developers and fragments hardware assembly across contract manufacturers competing on cellular connectivity module integration.
Pricing Analysis
Value-based contracts tied to readmission reduction metrics anchor pricing structures for enterprise chronic disease platforms, with three-tier pricing stratification across premium AI-enabled risk engines, standard monitoring dashboards, and economy device-only packages. Price differentiation rests on FDA software-as-a-medical-device certification tier and depth of Epic EHR integration, with California Medi-Cal managed care plans exhibiting highest price sensitivity due to total-cost-of-care budget constraints while Texas energy sector self-insured employers show lowest sensitivity for outcomes-guaranteed subscriptions. Cost compression in hardware tiers is intensifying as CMS reimbursement codes accelerate equipment depreciation schedules.
Supply Chain Analysis
Domestic-content requirements for federal healthcare procurement are reshaping sourcing patterns, with Buy American preferences pushing assembly toward United States-based contract manufacturers for CMS-reimbursable monitoring devices. Component supply concentrates in China for cellular connectivity modules, Taiwan for semiconductor sensors, and Mexico for final device assembly serving Texas distribution hubs. Raw material dependencies include lithium-ion cells for wearable power, medical-grade polymers for biocompatible housings, and cloud computing infrastructure for data processing. Single-source vulnerability in FDA-validated algorithm development creates supply chain risk. Distribution runs through integrated delivery network procurement committees and GPO contracts with regional hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical informaticist scarcity constrains deployment velocity for complex monitoring programs, propping pricing for outcome-linked platforms that reduce care team labor intensity. This supply bottleneck sustains margin capture for vendors with validated workflow automation.
For Market Incumbents: Lock in EHR integration pathways through exclusive API partnerships with Epic Systems and Cerner instances across California and Texas health systems, defending against emerging AI-native entrants lacking hospital network credentials. Deepen backward integration into continuous glucose monitor sensor manufacturing to capture pharmacy budget shifts from traditional meter suppliers. Prioritize Health Canada premarket validation to preempt Ontario provincial reimbursement adoption. For New Entrants and Emerging Players: Begin with behavioral health convergence modules addressing comorbid depression and diabetes adherence gaps, the most penetrable white space as California Medi-Cal plans mandate mental health integration. Target rural Texas counties with broadband-enabled asynchronous monitoring solutions bypassing clinical informaticist shortages. Pursue direct-to-employer channels in Houston energy sector bypassing commercial payer intermediaries. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by EHR-integrated platform incumbents seeking AI risk stratification capabilities, with long-term viability favoring vendors with dual FDA-Health Canada clearance and proven readmission reduction outcomes. Target acquisition archetype: mid-cap specialists with validated closed-loop insulin delivery algorithms and existing California endocrinology practice relationships. Watch Ontario provincial reimbursement structure announcements as inflection indicator for cross-border platform economics expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Validates algorithmic outputs for CMS reimbursement eligibility, locking in hospital procurement pathways. |
| Hospital System Partnership | Secures EHR integration with Epic or Cerner instances across California and Texas risk-bearing contracts. |
| Reimbursement Strategy | Aligns platform economics with expanding CMS remote therapeutic monitoring codes and Medicaid waiver structures. |
| Software Companion Development | Extends hardware lifecycles through subscription analytics layers capturing pharmacy and emergency department budgets. |
| CE Marking Pathway | Enables Health Canada premarket validation for Ontario and British Columbia provincial adoption. |
Research Methodology
Multi-period observation of CMS reimbursement code expansions, FDA software-as-a-medical-device guidance evolution, and health system platform procurement patterns anchored the trend analysis, supplemented by interviews with hospital chief medical information officers, remote care coordinators, GPO contracts managers, and digital health product executives. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare claims data, hospital procurement disclosures, and Health Canada medical device licenses. Bottom-up triangulation across vendor revenue segmentation and top-down reconciliation against health system IT spending surveys ensured methodological robustness.
Input-output matrices mapped algorithmic risk stratification adoption rates against care team labor cost savings, with segmentation dimensions spanning delivery mode, technology layer, and end-user procurement authority across the projection horizon. CAGRs derived from fitted growth curves applied to historical platform deployment velocities, with Texas Medicaid waiver network consolidation and California Medi-Cal managed care procurement cycles serving as industry-specific forecast inputs.
Underlying measurement precision varies by segment; AI and data analytics software revenue carries tighter precision than hardware device shipments due to disclosed subscription economics. Forecasts reflect documented assumptions regarding regulatory timeline adherence and reimbursement parity sustainability. Unforeseen FDA validation requirement tightening or provincial reimbursement delays in Canada could revise trajectory estimates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Burns Treatment Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Systemic Sclerosis Treatment Market
Medical Treatment
Phototherapy Treatment Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Radiotherapy Induced Oral Mucositis Treatment Market
Medical Treatment
Pelvic Organ Prolapse Repair Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Dementia Treatment Market
Medical Treatment
Global Acromegaly Treatment Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Andersen Tawil Syndrome Treatment Market
Medical Treatment
Hypogonadism Treatment Market
Medical Treatment
Facial Spasm Treatment Market
Medical Treatment
Global Sex Reassignment Surgery Market
Medical Treatment
Thymus Cancer Treatment Market