
 Intensity Modulated Radiation Therapy Market | 2026-2036
Intensity Modulated Radiation Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Intensity Modulated Radiation Therapy Market Foresight
Software-defined treatment planning and adaptive replanning subscriptions is rebalancing vendor economics toward recurring revenue streams rather than pure capital equipment sales. Varian Medical Systems leverages its cloud-based analytics platform to sustain long-term client relationships beyond hardware installation. Elekta AB anchors its European installed base through integrated service contracts covering linac uptime guarantees. Siemens Healthineers competes by bundling imaging-to-treatment workflows across its diagnostic and therapeutic portfolios.
Intensity modulated radiation therapy modulates photon beam fluence across multiple segments using inverse planning algorithms and multi-leaf collimator leaf sequences, typically delivering dose gradients of under 5 millimeters between tumor and organ-at-risk boundaries. Its primary purpose is to escalate target dose while sparing adjacent healthy tissue in anatomically complex sites. Linear accelerators retain the dominant share of product-level value given their capital intensity and replacement cycles, while arc therapy techniques capture expanding procedure volumes due to shorter beam-on times. Treatment planning systems represent the fastest-growing margin pool as vendors embed AI-driven auto-segmentation and Monte Carlo dose calculation engines.
FDA 510(k) and MDR Article 10 conformity assessments shape software validation burdens for treatment planning releases, with FDA emphasizing algorithm change control and MDR requiring clinical performance documentation under notified body scrutiny. NMPA in China and PMDA in Japan apply distinct localization testing for beam modeling algorithms, fragmenting regulatory approval timelines across major markets. Stakeholders must monitor evolving cybersecurity guidance from FDA and MDCG for networked radiotherapy systems, as connected device mandates reshape post-market surveillance obligations and vendor liability frameworks.
Market Dynamics
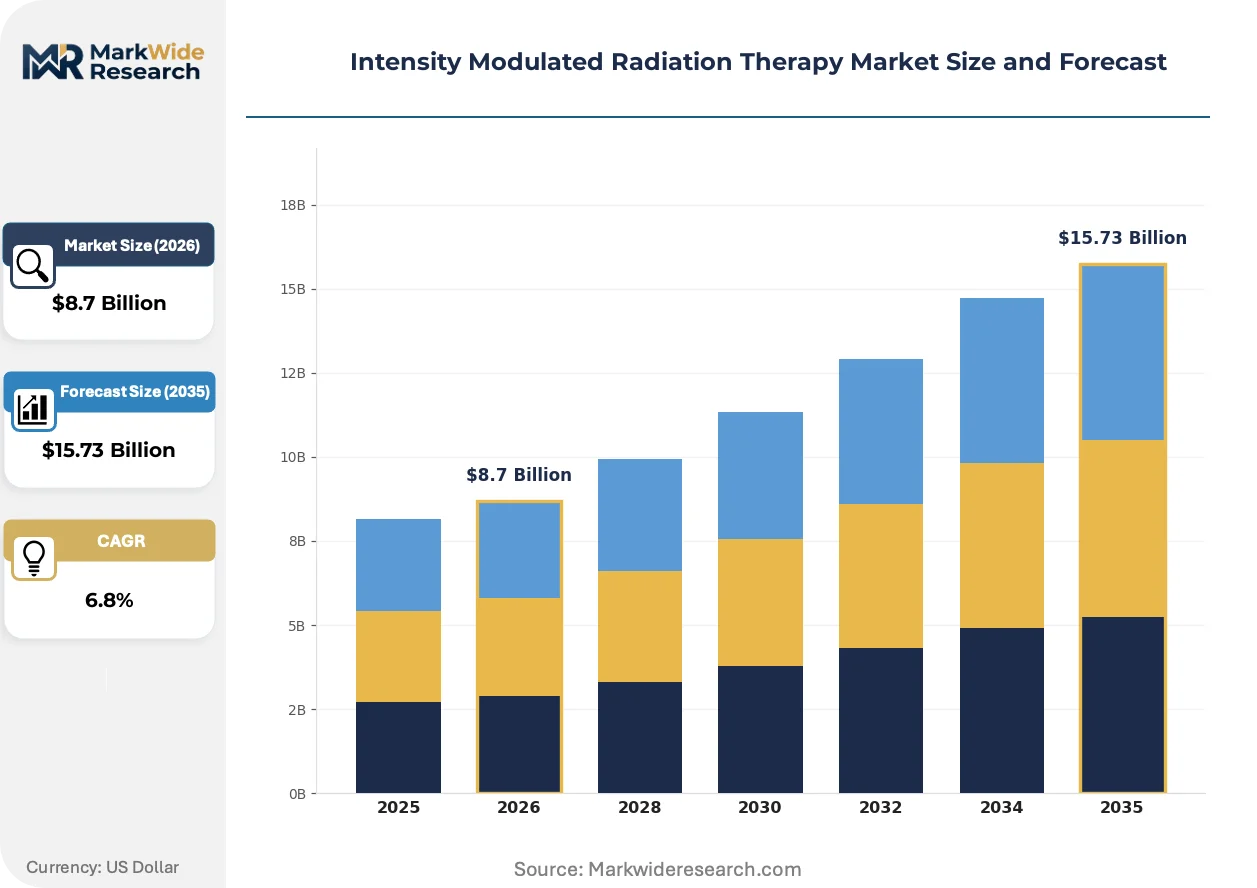
Adaptive replanning algorithms and cloud-based treatment analytics are compressing hardware replacement cycles while elongating vendor-client relationships through recurring software subscriptions. This structural shift rebalances capital equipment economics toward service-driven revenue permanence.
Growth Catalysts
- MDR Article 10 Conformity Pathways:European notified body scrutiny of clinical performance documentation accelerates adoption of validated treatment planning systems among risk-averse hospital procurement committees.
- Prostate and Head-and-Neck Oncology Protocols:Anatomically complex tumor sites with steep dose gradients drive clinical demand for beam modulation precision in major cancer treatment networks.
- Japan's Aging Demographics:PMDA-cleared systems face concentrated demand from Tokyo and Osaka metropolitan radiotherapy centers managing rising cancer incidence among elderly populations.
Market Restraints
- Tungsten and Copper Supply Concentration:Multi-leaf collimator manufacturing depends on concentrated rare metal sourcing from specific mining jurisdictions, creating input cost volatility for linac producers.
- FDA 510(k) Algorithm Change Control:Software validation burdens for inverse planning updates create regulatory friction that delays feature releases and extends development timelines.
- Proton Therapy Substitution:Bragg peak physical advantages in pediatric and ocular applications displace photon-based IMRT for specific tumor geometries despite higher facility costs.
Strategic Opportunities
- India's PLI Scheme for Medical Devices:Domestic manufacturing incentives create localization pathways for treatment planning software development and regional service hubs.
- AI-Driven Auto-Segmentation Convergence:Deep learning integration with Monte Carlo dose engines enables real-time adaptive replanning during treatment fractions.
- Subscription-Based Cloud Analytics:Remote treatment monitoring and outcomes databases replace perpetual software licenses with recurring revenue streams in North American hospital systems.
Industry Challenges
- Medical Physics Workforce Scarcity:Specialized dosimetrist training programs fail to match installation growth, creating bottlenecks for treatment plan quality assurance.
- Legacy Linac Integration Complexity:Retrofitting older linear accelerators with modern multi-leaf collimator systems requires costly mechanical engineering modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intensity Modulated Radiation Therapy Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Accelerators, Treatment Planning Systems, Imaging Systems, Accessories End User: Hospitals, Cancer Treatment Centers, Research Institutions, Clinics Technique: Static Beam Modulation, Dynamic Beam Modulation, Arc Therapy, Others Application: Prostate Cancer, Breast Cancer, Head & Neck Cancer, Lung Cancer |
| Companies Covered | Siemens Healthineers, Varian Medical Systems, Elekta AB, Accuray Incorporated, Hitachi, IBA, ViewRay Inc., RaySearch Laboratories AB, Mevion Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intensity Modulated Radiation Therapy Market Shifts & Advancements
Computational advances in beam modeling and networked device architecture are compressing treatment delivery times while elevating dose calculation precision. These developments reshape competitive positioning around software capabilities rather than hardware specifications alone.
Monte Carlo dose calculation engines are consolidating market preference among academic medical centers and high-volume cancer institutes. These algorithms replace convolution-superposition methods for heterogeneous tissue interfaces. Major treatment planning vendors embed GPU-accelerated Monte Carlo as standard configuration. This consolidation is compressing competitive differentiation around raw hardware specifications.
FDA cybersecurity guidance for networked radiotherapy systems is tightening post-market surveillance obligations for cloud-connected treatment planning platforms. The agency mandates documented vulnerability management and incident response protocols. Vendors with established quality management systems adapt faster than smaller software specialists. European MDCG guidance on connected device safety parallels these requirements.
Hospital procurement committees now unbundle after-sales service contracts from initial capital purchases. Third-party physics service organizations compete against manufacturer-integrated support agreements. This disintermediation pressures vendor margins on maintenance revenue. United States academic medical centers lead this behavioral shift toward competitive service sourcing.
Intensity Modulated Radiation Therapy Market Segmentation
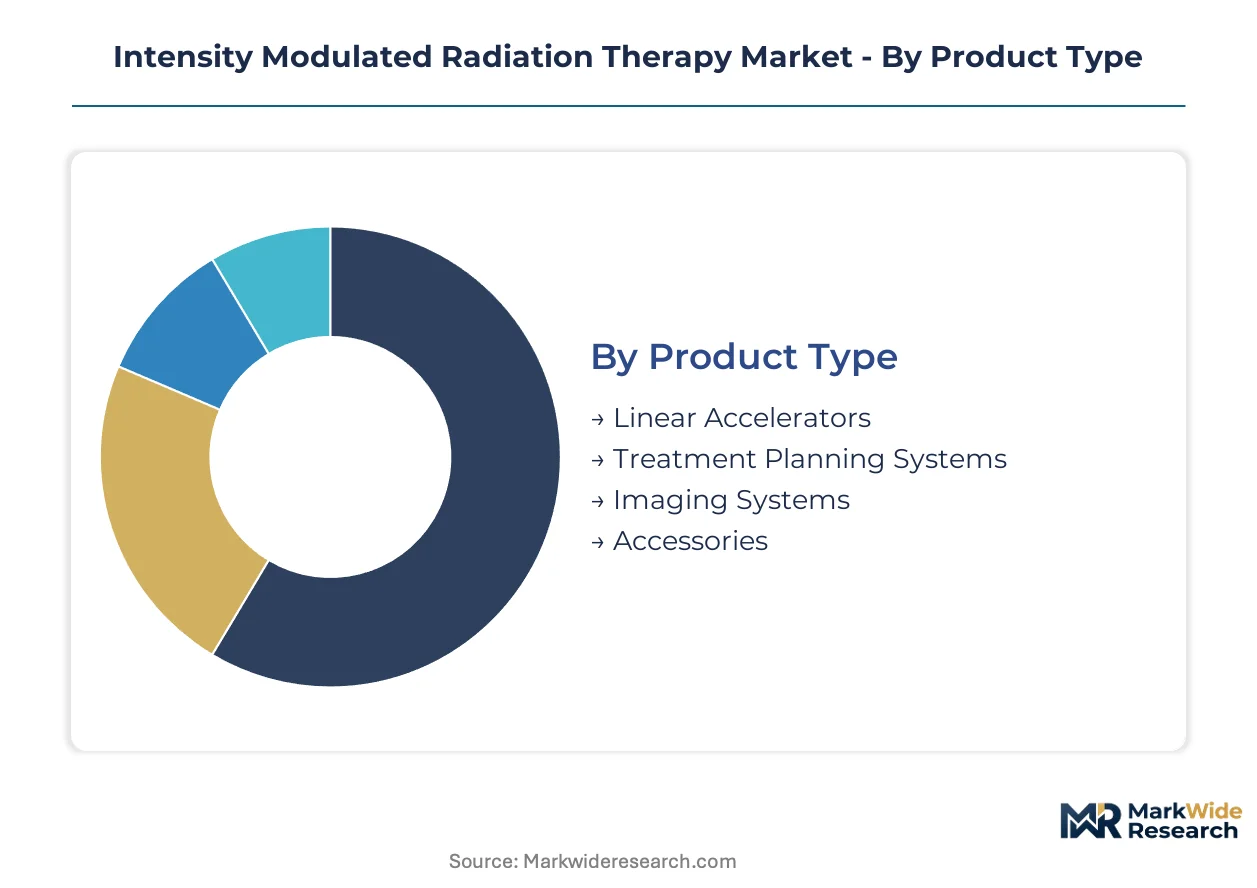
Segmentation in IMRT markets reveals how capital intensity, clinical workflow integration, and reimbursement pathways shape procurement decisions across healthcare delivery settings. Understanding these divides exposes where vendor economics concentrate and where technology substitution risks emerge.
Product Type:
Customization dominates at the treatment planning layer while hardware standardization locks in long replacement cycles across installed bases.
- Linear Accelerators:These photon delivery systems integrate multi-leaf collimator banks and flattening filter-free modes for high dose-rate delivery. Demand concentrates in Germany and Japan where hospital procurement committees prioritize uptime guarantees and service response SLAs over upfront capital differentials. Tungsten supply volatility from concentrated mining jurisdictions creates input cost pressure for MLC manufacturers.
- Treatment Planning Systems:Inverse planning software with Monte Carlo dose engines and AI-driven auto-segmentation modules commands expanding margin pools. United States academic medical centers drive adoption of cloud-connected platforms with adaptive replanning capabilities, compressing hardware replacement cycles through software-defined functionality.
- Imaging Systems:On-board kV imaging and cone-beam CT integration enables soft-tissue visualization for daily patient setup verification.
- Accessories:Immobilization devices, respiratory gating systems, and dosimetry phantoms complete treatment delivery workflows.
Most installed capacity flows through Linear Accelerators. Expansion is steepest in Treatment Planning Systems.
End User:
Procurement authority fragments across centralized hospital systems, specialized cancer networks, and distributed clinic settings with varying capital access.
- Hospitals:Integrated delivery networks in the United States leverage scale economics for multi-linac installations with shared physics support. FDA 510(k) algorithm change control requirements create compliance burdens that favor established vendors with dedicated regulatory affairs teams.
- Cancer Treatment Centers:Dedicated oncology facilities in Japan's Tokyo and Osaka metropolitan corridors concentrate procedure volumes for complex head-and-neck protocols. PMDA clearance pathways shape vendor selection criteria alongside reimbursement alignment for advanced radiotherapy techniques.
- Research Institutions:Academic medical centers validate emerging adaptive replanning algorithms and participate in clinical trials for novel fractionation schemes.
- Clinics:Community-based settings face medical physics workforce scarcity that limits treatment plan quality assurance capacity.
Revenue concentration sits with Hospitals. Patient volume growth is climbing fastest in Cancer Treatment Centers.
Technique:
Dose delivery speed and planning complexity create tiered adoption patterns across clinical sites with varying patient throughput requirements.
- Static Beam Modulation:Fixed gantry angles with segmented multi-leaf collimator positions deliver modulated fluence through step-and-shoot sequences. Legacy installations in European community hospitals retain this approach where arc therapy retrofit costs prove prohibitive.
- Arc Therapy:Continuous gantry rotation during beam delivery compresses treatment times for high-volume centers. United States prostate and lung protocols drive adoption as reimbursement frameworks reward throughput efficiency without compromising dose conformity.
- Dynamic Beam Modulation:Sliding window techniques modulate dose during constant leaf motion.
- Others:Emerging hybrid modalities combine elements of static and dynamic approaches for specialized anatomical sites.
Procedure volume concentrates in Arc Therapy. Technical migration is accelerating toward Dynamic Beam Modulation.
Application:
Anatomical complexity and organ-at-risk proximity determine where beam modulation precision commands premium positioning.
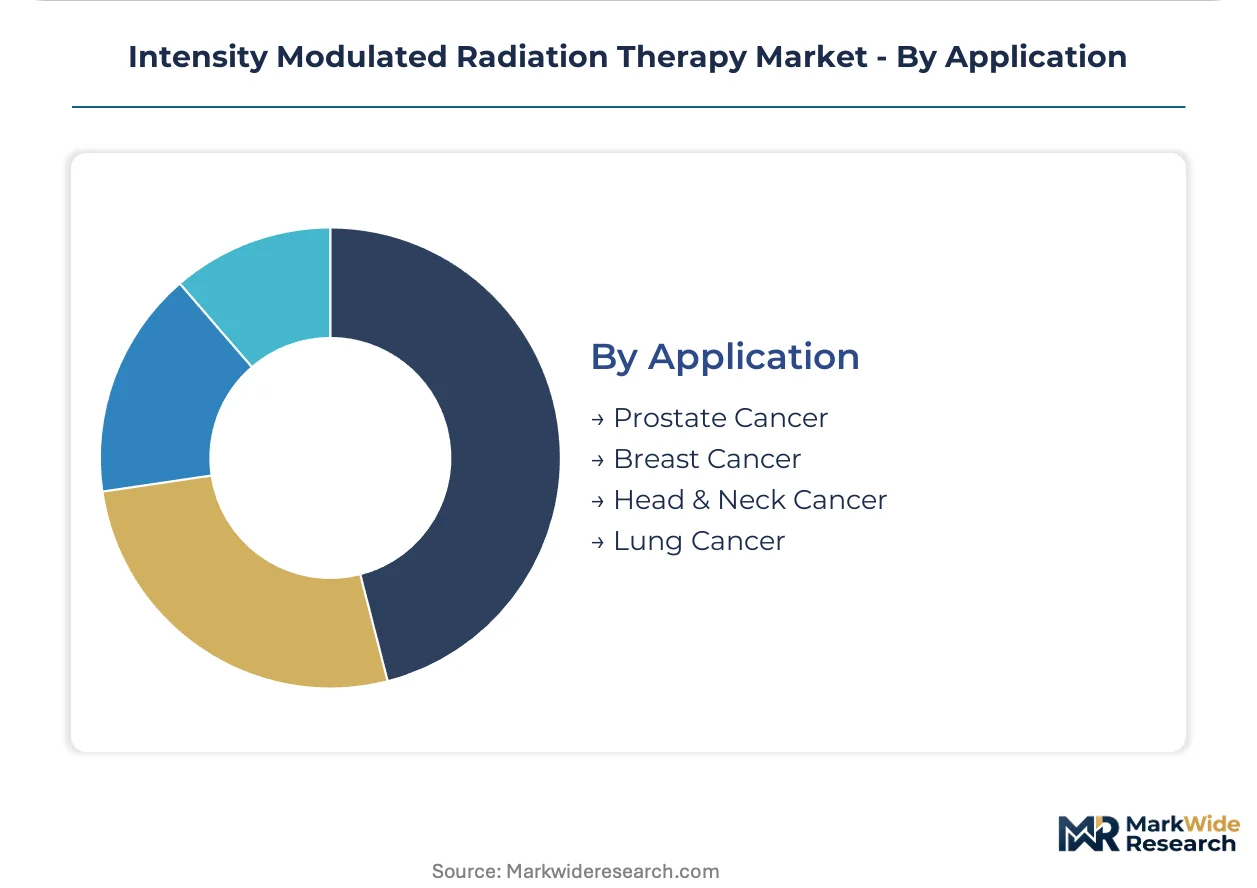
- Prostate Cancer:Favorable dose-volume histograms for rectal and bladder sparing make IMRT the standard of care in major treatment networks. United States urology-oncology protocols specify modulated techniques for intermediate and high-risk stratifications.
- Head & Neck Cancer:Steep dose gradients between tumor targets and parotid glands, optic structures, and spinal cord demand sub-5-millimeter modulation precision. German head-and-neck consortiums drive protocol standardization across university hospital networks.
- Breast Cancer:Cardiac sparing requirements for left-sided lesions motivate beam modulation adoption.
- Lung Cancer:Respiratory motion management integrates with modulation techniques for stereotactic ablative applications.
Clinical evidence density is highest in Prostate Cancer. Protocol expansion is broadening fastest in Head & Neck Cancer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the largest installed base of linear accelerators in Europe, while Japan concentrates procedure volumes in metropolitan corridors facing acute aging demographics. Regulatory frameworks in both jurisdictions prioritize clinical performance documentation and software validation standards that favor established vendors.
United States
Academic medical centers in Boston and Houston drive adoption of cloud-connected treatment planning systems with adaptive replanning capabilities. FDA 510(k) algorithm change control requirements create compliance burdens that hospital procurement committees weigh heavily in vendor selection. The Greater Boston corridor anchors validation studies for Monte Carlo dose engines serving multi-linac installations.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia standardize head-and-neck protocols requiring sub-5-millimeter modulation precision. MDR Article 10 conformity assessments accelerate procurement of validated treatment planning systems among risk-averse committees. The Munich-Stuttgart axis concentrates service engineering capacity for linac uptime guarantees.
Japan
Tokyo and Osaka metropolitan radiotherapy centers manage rising cancer incidence among elderly populations with PMDA-cleared systems. Japan's national health insurance reimbursement frameworks favor advanced radiotherapy techniques for complex tumor geometries. The Kanto region anchors the highest density of arc therapy installations per capita globally.
China
Domestic manufacturing incentives under the PLI scheme for medical devices accelerate localization of treatment planning software development. NMPA applies distinct localization testing for beam modeling algorithms that fragments approval timelines. The Yangtze River Delta corridor hosts regional service hubs serving expanding cancer center networks.
India
Private hospital chains in Maharashtra and Karnataka expand IMRT capacity for prostate and head-and-neck oncology protocols. CDSCO regulatory pathways for software-defined medical devices create entry barriers that favor vendors with dedicated local affairs teams. The Mumbai-Pune corridor concentrates medical physics training programs addressing workforce scarcity.
Intensity Modulated Radiation Therapy Market Competitive Landscape
Top-tier vendors anchor the premium equipment tier, while mid-scale specialists occupy service-intensive niches and regional fabricators compete on localization economics. The vendor base stratifies across three functional archetypes: integrated imaging-to-treatment workflow bundlers, standalone linear accelerator manufacturers, and software-centric treatment planning specialists. Competitive dynamics revolve around M&A activity consolidating imaging and therapeutic portfolios, and strategic partnerships embedding AI-driven auto-segmentation into existing installed bases.
Within the integrated systems tier, Siemens Healthineers and Varian Medical Systems exemplify divergent geographic anchoring strategies, with the former leveraging European hospital relationships and the latter sustaining North American cloud analytics platforms. Elekta AB occupies a position representing European-centric service contract economics. These three entities collectively illustrate how vendor economics rebalance toward recurring software subscriptions and uptime-guaranteed maintenance agreements rather than pure capital equipment transactions.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Varian Medical Systems |
| Elekta AB |
| Accuray Incorporated |
| Hitachi |
| IBA |
| ViewRay Inc. |
| RaySearch Laboratories AB |
| Mevion Medical Systems |
| Others |
Supply & Pricing Matrix
Tungsten price indices cascading from concentrated mining jurisdictions in Kazakhstan and Vietnam transmit directly into multi-leaf collimator manufacturing costs, stratifying linear accelerator pricing across premium service-bundled, standard equipment-only, and economy retrofit tiers. Hospital procurement committees in Germany and Japan absorb these input fluctuations through long-term uptime guarantee contracts that externalize volatility to vendor balance sheets.
Pricing Analysis
Capacity additions in China's Yangtze River Delta corridor are reshaping price floors for treatment planning software development, compressing margin structures for legacy perpetual-license vendors. Three-tier pricing structure across premium adaptive-replanning subscriptions, standard Monte Carlo-enabled packages, and economy static-beam configurations differentiates primarily by AI auto-segmentation depth and cloud connectivity. Cost compression in the economy tier is intensifying because India's PLI scheme subsidizes domestic physics service organizations competing on maintenance contracts. Community clinics in Maharashtra exhibit highest price sensitivity, while United States academic medical centers prioritize clinical performance documentation over capital differentials.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's NMPA localization testing requirements are reshaping sourcing patterns for beam modeling algorithm development and regional service engineering capacity. Tungsten and copper draws from Kazakhstan, Vietnam, and Chile; rare earth elements for MLC motors rest on Chinese processing dominance; GPU accelerators for Monte Carlo engines hinge on Taiwan semiconductor fabrication. Single-source vulnerability concentrates in Chinese rare earth processing for high-precision collimator actuators. Distribution runs through manufacturer-direct hospital system partnerships in North America, third-party physics service organizations in Europe, and regional distributor networks in South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory validation cost differentials between FDA 510(k) algorithm change control pathways and India's CDSCO software-defined device routes create geographic-arbitrage opportunities for treatment planning system vendors willing to segment development footprints.
For Market Incumbents: Lock in European installed bases through MDR Article 10 conformity assessment bundling that raises compliance barriers for emerging software specialists. Deepen backward integration into tungsten sourcing through offtake agreements with Kazakh mining operations to neutralize input cost volatility threatening MLC manufacturing margins. Prioritize GPU-accelerated Monte Carlo engine R&D to compress competitive differentiation around raw hardware specifications. For New Entrants and Emerging Players: The premium-to-economy price-point gap in adaptive replanning subscriptions creates white-space opportunity for cloud-native platforms targeting mid-tier cancer treatment centers in India's Mumbai-Pune corridor. Community hospital networks in Germany's North Rhine-Westphalia present penetrable entry points where legacy linac retrofit complexity delays incumbent software upgrades. Pursue partnership-based go-to-market models embedding AI auto-segmentation modules into existing Varian and Elekta installed bases rather than competing on hardware replacement cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with software-centric treatment planning specialists possessing FDA-cleared Monte Carlo algorithms and established cloud analytics platforms. Five-to-ten-year viability hinges on recurring revenue permanence displacing capital equipment transaction economics. Target acquisition archetypes: mid-scale European vendors with MDR-validated quality management systems and underserved Asia-Pacific service footprints. Watch PMDA clearance timeline compression for adaptive replanning algorithms as inflection indicator for Japanese market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Conformity Assessment Investment | European notified body scrutiny accelerates procurement preference for validated vendors in German hospital networks. |
| Cloud Analytics Platform Development | Remote treatment monitoring subscriptions displace perpetual licenses in United States academic medical centers. |
| AI Auto-Segmentation Integration | Deep learning modules compress planning workflow times for high-volume prostate and head-and-neck protocols. |
| Regional Service Hub Localization | India's PLI scheme enables domestic physics support capacity addressing workforce scarcity in Maharashtra clinics. |
| Tungsten Supply Agreement | Kazakh mining offtake contracts neutralize MLC input cost volatility threatening linac manufacturing margins. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with radiation oncology department heads, hospital procurement committee chairs, medical physicists, and GPO contracts managers with secondary validation against FDA 510(k) filings, PMDA approval databases, MDR notified body conformity assessments, and hospital capital expenditure disclosures. Bottom-up installed base modeling and top-down reimbursement framework analysis triangulated market sizing across product type, end user, technique, and application dimensions.
Segment-weighting approaches distributed value and volume estimates across linear accelerator hardware, treatment planning software, imaging integration modules, and accessories categories, with additional stratification by static beam modulation, arc therapy, and dynamic beam modulation techniques. CAGRs were derived from procedure volume trajectories, replacement cycle compression effects, and software subscription penetration curves over the projection horizon. Forecast inputs incorporated PMDA clearance timelines, MDR implementation compliance costs, and India's PLI scheme subsidy phase-ins.
Caveats apply where FDA cybersecurity guidance tightening, tungsten supply disruptions from Kazakh mining jurisdictions, or proton therapy substitution acceleration in pediatric applications could materially shift the outlook. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
Global Plasma Therapy Market
Medical Treatment
Lysosomal Storage Disease Treatment Market
Medical Treatment
ALAD Porphyria Treatment Market
Medical Treatment
Radiation Therapy Market
Medical Treatment
Histoplasmosis Treatment Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Cephalic Disorders Treatment Market
Medical Treatment
Cholera Treatment Market
Medical Treatment
Neglected Tropical Disease Treatment Market
Medical Treatment
Leprosy Treatment Market
Medical Treatment
Acute Migraine Treatment Market
Medical Treatment
Vulvodynia Treatment Market
Medical Treatment
Spain Hair Transplant Market