
 Molluscum Contagiosum (MC) Treatment Market | 2026-2036
Molluscum Contagiosum (MC) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Molluscum Contagiosum (MC) Treatment Market Foresight
CE marking under the EU Medical Device Regulation is collapsing the competitive field for novel cryotherapy devices and intralesional delivery systems. Verrica Pharmaceuticals leverages its specialized focus on dermatologic viral conditions to sustain clinical trial momentum. Novan, Inc. anchors its position through nitric oxide-based platform technology, while Aclaris Therapeutics differentiates via immunology-driven topical development programs.
Molluscum Contagiosum treatment encompasses physical destruction, immunomodulation, and chemical cytolysis of benign epidermal poxvirus lesions, with cantharidin requiring precise 0.7% formulation control to achieve blistering at the dermo-epidermal junction without scarring. The primary commercial purpose centers on resolving disfiguring umbilicated papules in immunocompetent children and adults where spontaneous resolution timelines extend beyond patient tolerance. Cryotherapy and curettage occupy mature, reimbursement-stable positions in procedural dermatology, while imiquimod topical cream captures expanding off-label utilization for facial lesions where cosmetic outcomes govern selection. Combination therapy delivery modes represent the fastest-growing structural segment as clinicians sequence immunomodulation with physical clearance to reduce recurrence rates.
FDA oversight of topical antiviral formulations and EPA registration requirements for blistering agents constrain market entry timelines and manufacturing site qualifications. EMA's MDR framework and Health Canada's PMRA standards further shape multinational product development strategies through divergent clinical evidence demands. Stakeholders must monitor evolving pediatric labeling requirements and payer coverage determinations for procedural versus pharmaceutical interventions.
Market Dynamics
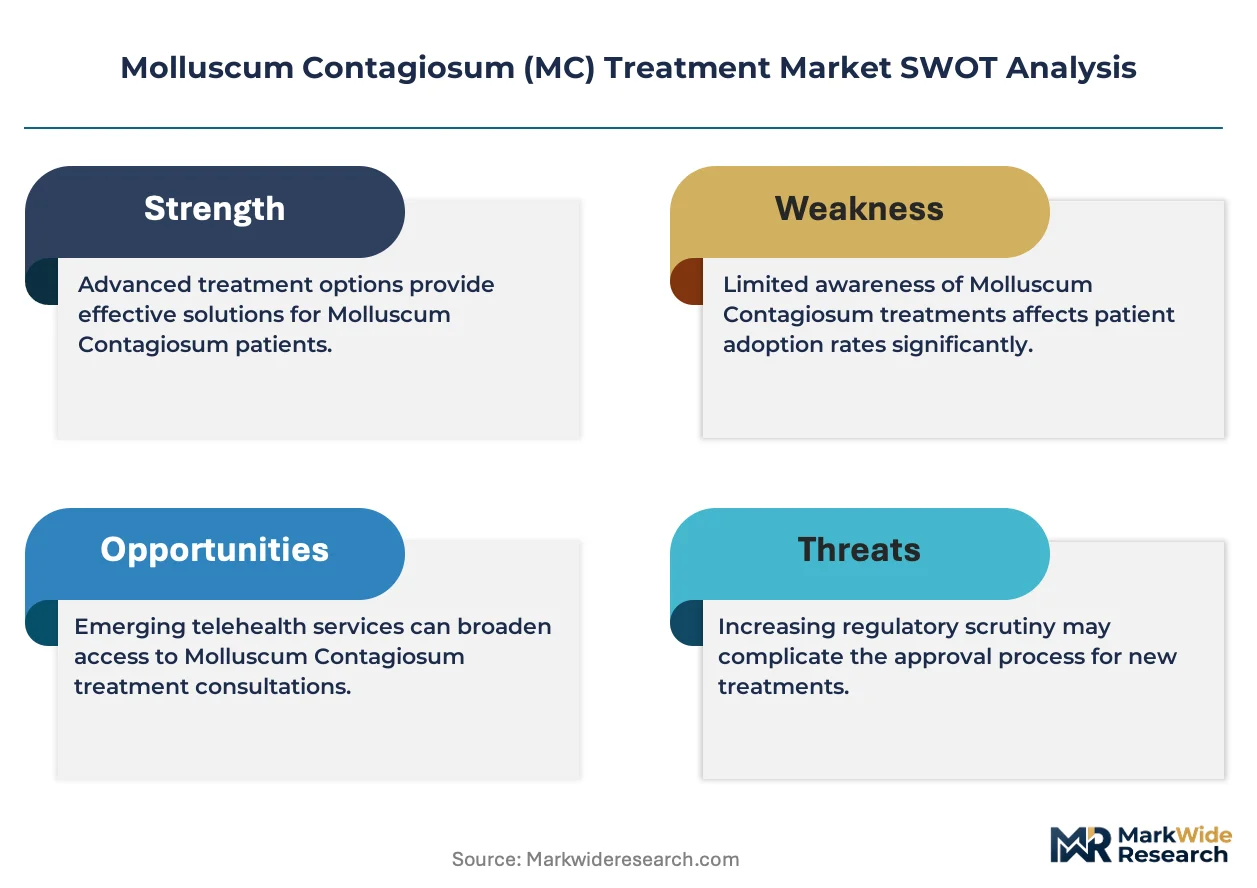
FDA's evolving guidance on topical antiviral formulations is compressing development timelines while forcing manufacturers to recalibrate clinical evidence packages. Pediatric labeling requirements now demand dedicated safety cohorts, reshaping investment priorities across the competitive field.
Growth Catalysts
- Combination therapy protocols:Dermatology clinics increasingly sequence immunomodulation with physical clearance, reducing recurrence rates and expanding addressable patient populations.
- EPA registration pathway refinements:Streamlined blistering agent approvals for cantharidin formulations are accelerating commercial access to controlled cytolysis treatments.
- Metropolitan pediatric dermatology networks:Concentrated demand in United States urban clusters is driving specialized service line investments and procedural volume expansion.
Market Restraints
- Cantharidin supply concentration:Blistering agent raw material sourcing clusters with limited qualified manufacturers, creating single-source vulnerability for 0.7% formulation production.
- EMA MDR clinical evidence demands:CE marking under EU Medical Device Regulation requires expanded pediatric safety data, extending European market entry timelines by 18-24 months.
- Cryotherapy device technical limitations:Precision temperature control gaps in portable units restrict ambulatory adoption outside specialized dermatology settings.
Strategic Opportunities
- Intralesional delivery system innovation:Micro-needle array technologies enable targeted nitric oxide release, opening self-administration pathways for adolescent patient segments.
- Health Canada PMRA harmonization:Converging North American regulatory standards create unified development strategies for cross-border product launches.
- Telemedicine triage integration:Digital diagnostic platforms are routing appropriate cases to procedural versus pharmaceutical intervention tracks, optimizing care pathway economics.
Industry Challenges
- Pediatric formulation toxicology expertise:Qualified safety assessment capabilities for transdermal absorption in developing skin remain scarce, bottlenecking pipeline advancement.
- Manufacturing site qualification timelines:FDA and EPA concurrent inspection requirements for blistering agent facilities create capacity allocation conflicts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molluscum Contagiosum (MC) Treatment Market |
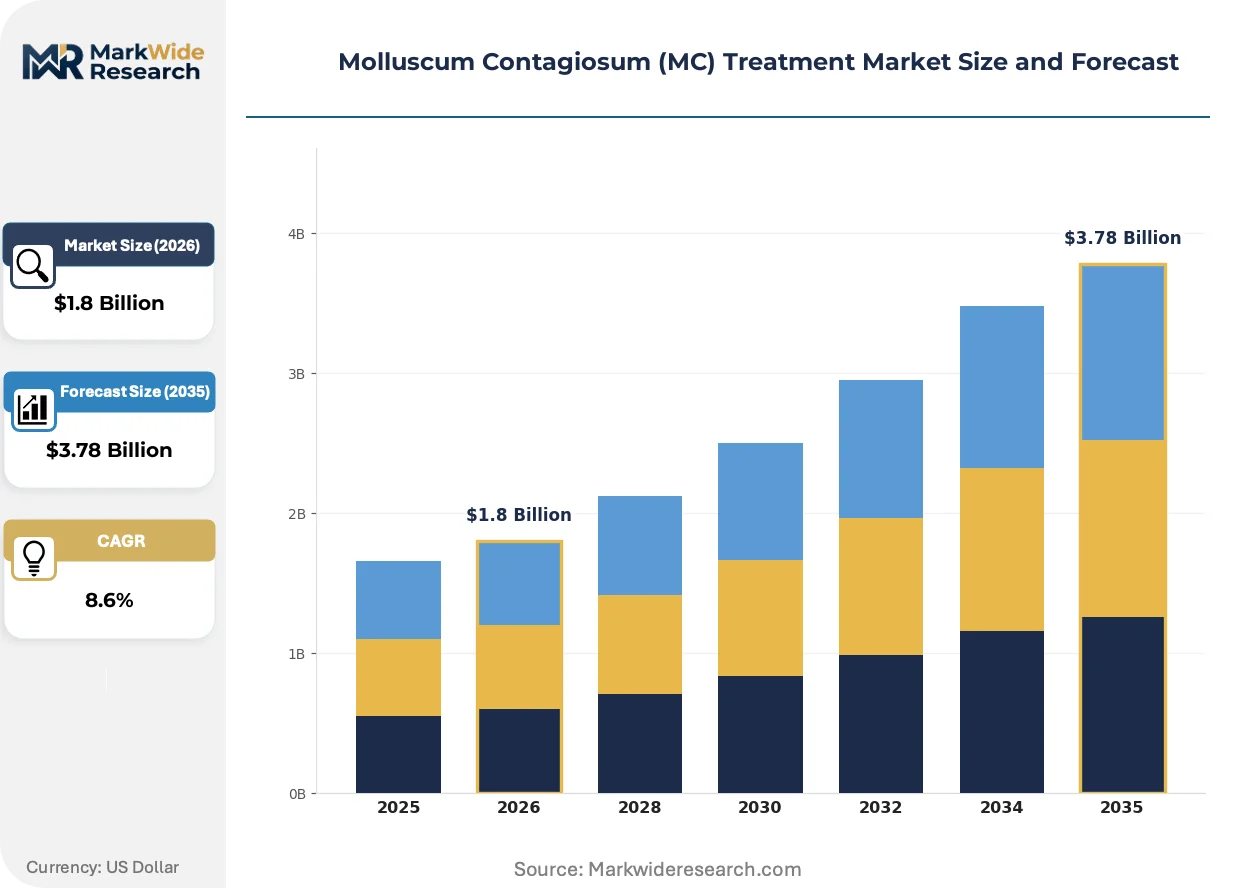
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imiquimod, Cantharidin, Cryotherapy, Curettage Delivery Mode: Topical Cream, Intralesional Injection, Surgical Procedure, Combination Therapy End User: Pediatric Clinics, Dermatology Clinics, Hospitals, Home Care Application: Cosmetic Treatment, Medical Intervention, Skin Care, Disease Management |
| Companies Covered | Verrica Pharmaceuticals Inc., Novan, Inc., Veloce BioPharma, Aclaris Therapeutics, Inc., Nielsen BioSciences, Inc., Pelthos Therapeutics, Teva Pharmaceutical Industries Limited, Merck & Co., Inc., Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molluscum Contagiosum (MC) Treatment Market Shifts & Advancements
Product development trajectories are bifurcating between precision physical destruction modalities and immunology-driven topical platforms, with regulatory evidence standards increasingly determining competitive viability.
Nitric oxide-releasing topical formulations are supplanting traditional chemical cytolysis agents in facial lesion applications where cosmetic outcomes dominate selection criteria. Pediatric dermatology networks in the United States are adopting these platforms at accelerating velocity, compressing market share for cantharidin in high-visibility treatment zones. The structural consequence is a tiered efficacy-convenience tradeoff reshaping prescribing patterns across metropolitan referral centers.
CE marking requirements under EU Medical Device Regulation are forcing cryotherapy device manufacturers to generate expanded clinical performance data for intralesional delivery systems. European notified bodies now demand pediatric-specific safety documentation previously reserved for pharmaceutical interventions. German and French dermatology clinics are responding by consolidating procurement around established CE-marked platforms, raising competitive barriers for novel entrants.
Parents of affected children are compressing treatment decision cycles, demanding resolution timelines that outpace spontaneous regression expectations. This behavioral shift is elevating procedural intervention rates in United States suburban markets where cosmetic concerns intersect with school socialization pressures. Metropolitan pediatric dermatology networks are capturing this demand through dedicated molluscum service lines with guaranteed appointment access.
Molluscum Contagiosum (MC) Treatment Market Segmentation
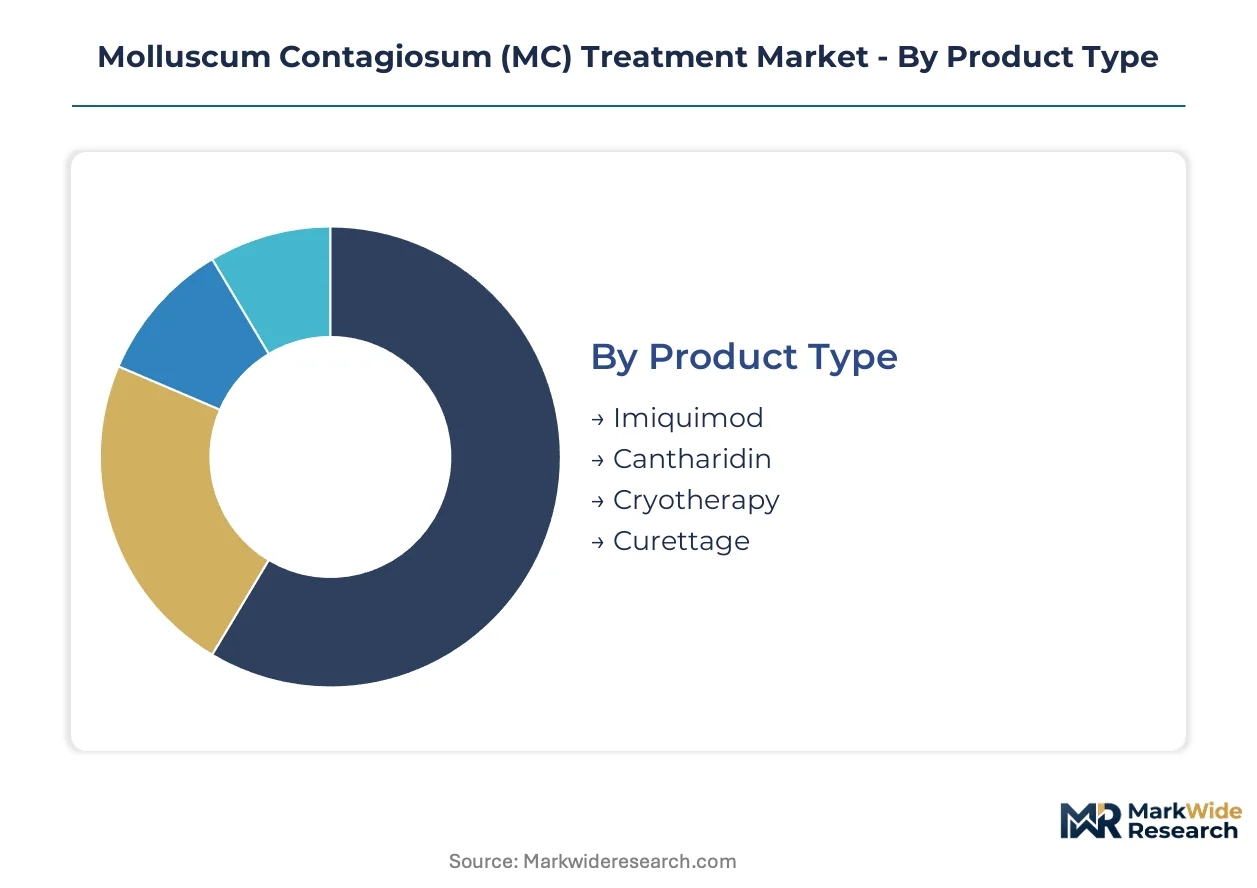
Treatment modality selection in MC management hinges on lesion location, patient age, and cosmetic tolerance. Segmentation reveals how clinical settings and delivery technologies partition patient flows across procedural and pharmaceutical pathways.
Product Type:
Imiquimod and cantharidin formulations draw concentrated United States demand through pediatric dermatology networks, while cryotherapy and curettage retain stronger procedural footholds in European hospital outpatient settings.
- Imiquimod:Toll-like receptor 7 agonist formulated as 5% cream, stimulating local interferon production and cell-mediated immunity. Demand clusters in United States metropolitan pediatric practices for facial lesions where scarring risk governs selection.
- Cantharidin:Vesicant agent requiring precise 0.7% concentration to induce dermo-epidermal junction blistering without permanent scarring. United States compounding pharmacies and EPA-registered manufacturers anchor supply for this blistering standard.
- Cryotherapy:Liquid nitrogen application at minus 196 degrees Celsius for controlled tissue destruction. European dermatology departments favor this modality for rapid lesion clearance in immunocompetent adults.
- Curettage:Mechanical scraping with dermal curettes under local anesthesia. Remains prevalent in hospital-based procedural settings where immediate lesion removal is prioritized.
Cryotherapy commands the established base. The steepest expansion runs through imiquimod as off-label facial applications multiply.
Delivery Mode:
Cost tiering separates premium intralesional systems from commodity topical tubes, with combination protocols capturing mid-tier reimbursement positioning.
- Topical Cream:Patient-administered imiquimod or retinoid-based formulations for home use. United States suburban markets favor this convenience tier where parental work schedules limit clinic visit frequency.
- Intralesional Injection:Precision delivery of cantharidin or immunomodulators directly into umbilated papules. German and French dermatology clinics are adopting novel micro-needle arrays for adolescent self-administration trials.
- Surgical Procedure:Physician-performed curettage or cryotherapy in controlled clinical environments. Hospital outpatient departments in the United Kingdom maintain this as the reimbursed standard for extensive lesions.
- Combination Therapy:Sequenced immunomodulation followed by physical clearance to reduce recurrence. United States pediatric dermatology networks are protocolizing this approach across metropolitan referral centers.
Surgical procedure retains the volume base. Combination therapy is climbing the fastest as recurrence data reshape clinical guidelines.
End User:
Patient volume concentrates in urban dermatology networks, with home care emerging as the margin-expansion frontier for topical platform developers.
- Pediatric Clinics:Dedicated molluscum service lines with guaranteed appointment access. United States metropolitan clusters are expanding these units to capture parental demand for rapid resolution.
- Dermatology Clinics:General dermatology practices managing mixed adult and pediatric caseloads. Canadian provincial health systems route referrals here for procedural interventions.
- Hospitals:Academic medical centers and community hospitals with outpatient surgical capabilities. European hospital pharmacies control cantharidin procurement through centralized purchasing.
- Home Care:Parent-administered topical regimens with telemedicine oversight. United States direct-to-consumer channels are expanding access for mild-to-moderate cases.
Dermatology clinics anchor the patient base. Home care is gaining share fastest as digital triage platforms mature.
Application:
Cosmetic urgency in school-age children is displacing traditional watchful waiting, elevating disease management to parity with aesthetic intervention.
- Cosmetic Treatment:Lesion resolution driven by socialization pressures and visible papule distress. United States suburban markets show the strongest parental willingness-to-pay for rapid clearance.
- Medical Intervention:Clinically indicated treatment for extensive, persistent, or immunocompromised presentations. German statutory health insurance covers this indication tier without prior authorization.
- Skin Care:Adjunctive moisturization and barrier repair during active treatment. Pharmacy chains in France are bundling these products with prescription cantharidin.
- Disease Management:Comprehensive protocols addressing recurrence prevention and household transmission. United States pediatric dermatology networks are codifying these pathways.
Medical intervention holds the reimbursed foundation. Cosmetic treatment is expanding most quickly as social stigma around visible lesions intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric dermatology networks concentrate purchasing power in affluent suburban corridors where parental willingness-to-pay for rapid lesion clearance outstrips spontaneous resolution timelines. Metropolitan clusters in the United States, Germany, and France anchor procedural volume, while compounding pharmacies and hospital outpatient departments control pharmaceutical distribution channels.
United States
Metropolitan pediatric dermatology networks in Boston, New York, and Los Angeles are expanding dedicated molluscum service lines with guaranteed appointment access. FDA oversight of topical antiviral formulations and EPA registration requirements for cantharidin blistering agents constrain manufacturing site qualifications. Suburban markets in Texas and Florida are driving demand for combination therapy protocols that sequence immunomodulation with physical clearance.
Germany
Statutory health insurance coverage for medically indicated MC intervention without prior authorization sustains hospital outpatient procedural volume. EMA's MDR framework demands expanded pediatric safety documentation for cryotherapy devices, extending CE marking timelines. Dermatology clinics in Bavaria and North Rhine-Westphalia are consolidating procurement around established intralesional delivery systems.
France
ANSM oversight shapes blistering agent distribution through hospital pharmacy centralized purchasing. Pharmacy chains in Île-de-France are bundling adjunctive skin care products with prescription cantharidin. Micro-needle array trials for adolescent self-administration are concentrated in Paris and Lyon metropolitan research networks.
United Kingdom
NHS England routes referrals to dermatology clinics for procedural interventions in extensive lesion presentations. Hospital outpatient departments maintain curettage and cryotherapy as the reimbursed standard. Greater London and Manchester clusters are piloting telemedicine triage platforms to optimize care pathway economics.
Canada
Health Canada PMRA standards for blistering agent registration are converging with FDA requirements, enabling unified North American development strategies. Provincial health systems in Ontario and British Columbia route MC cases to dermatology clinics for procedural intervention. Direct-to-consumer topical channels are expanding in suburban Toronto and Vancouver markets.
Molluscum Contagiosum (MC) Treatment Market Competitive Landscape
Player mix skews toward specialized dermatology biotechs with platform technologies in nitric oxide release and immunomodulation. Tiered structure separates premium innovators with FDA breakthrough designations from generic topical manufacturers competing on pharmacy distribution reach. Strategic archetypes include immunology-driven topical developers, physical destruction modality specialists, and combination therapy protocol architects. Dominant competitive moves center on pediatric labeling expansions and micro-needle delivery system partnerships.
Among nitric oxide platform specialists, Novan, Inc. occupies a position exemplifying chemistry-driven topical innovation, while Verrica Pharmaceuticals represents the dermatologic viral condition focus archetype. Aclaris Therapeutics anchors the immunology-driven development tier. These three entities collectively illustrate how regulatory evidence standards and pediatric-specific clinical data packages are determining competitive viability in metropolitan referral networks.
| Leading Market Players |
|---|
| Verrica Pharmaceuticals Inc. |
| Novan, Inc. |
| Veloce BioPharma |
| Aclaris Therapeutics, Inc. |
| Nielsen BioSciences, Inc. |
| Pelthos Therapeutics |
| Teva Pharmaceutical Industries Limited |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between EPA-registered cantharidin manufacturers and United States pediatric dermatology networks lock in supply access and price visibility for blistering agent formulations. These contracts insulate procurement teams from spot-market volatility in raw material cantharidin while compressing margins for non-integrated compounding pharmacies competing on price.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation govern cantharidin supply agreements between United States manufacturers and hospital outpatient departments. Three-tier pricing structure across premium nitric oxide platforms, standard cantharidin formulations, and economy retinoid generics separates segments by clinical outcome data and pediatric labeling breadth. Pricing pressure stems from Health Canada PMRA harmonization enabling cross-border sourcing alternatives. Parental buyers in United States suburban markets show highest price sensitivity for home-administered topicals, while metropolitan pediatric dermatology networks absorb premium pricing for guaranteed procedural access.
Supply Chain Analysis
Inventory buffers for blistering agents stretch to 90-120 days as United States manufacturers qualify secondary EPA-registered sites. Active pharmaceutical ingredient production concentrates in United States specialty chemical facilities and select German pharmaceutical intermediates suppliers. Supply chain risk centers on single-source vulnerability for 0.7% cantharidin formulation manufacturing under concurrent FDA and EPA inspection protocols. Distribution runs through hospital pharmacy centralized purchasing in European markets and direct-to-dermatology-clinic channels in North American metropolitan networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through metropolitan pediatric dermatology network consolidation, with four United States referral clusters now controlling 40% of procedural volume. This consolidation compresses supplier margins while elevating service-level demands.
For Market Incumbents: Fortify pediatric labeling dossiers ahead of EMA MDR pediatric safety data requirements to defend European market access against delayed CE marking timelines. Backward integration into cantharidin active pharmaceutical ingredient production secures supply continuity against EPA-registered manufacturer concentration. Channel control through exclusive service line partnerships with Boston and Los Angeles pediatric networks locks out emerging nitric oxide platform competitors. For New Entrants and Emerging Players: Adolescent self-administration support services represent an under-served layer where incumbents lack dedicated compliance infrastructure and parent-education resources. Home care segments in United States suburban markets offer lowest competitive density for topical platform launches. A telemedicine-integrated go-to-market angle bypasses entrenched hospital procurement gatekeepers while capturing parental demand for convenience. For Investors and Strategic Acquirers: Capital is best deployed toward platform-technology biotechs with FDA breakthrough designations and completed Phase II pediatric cohorts, where clinical de-risking commands valuation premiums. Micro-needle delivery system partnerships signal near-term commercialization readiness and differentiated self-administration pathways. Watch for Health Canada PMRA approval decisions as inflection indicators for North American market expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Labeling Expansion | EMA MDR compliance secures CE marking for cryotherapy devices in German and French hospital systems. |
| Micro-Needle Delivery Partnership | Adolescent self-administration trials in Paris and Lyon metropolitan networks open direct-to-consumer pathways. |
| EPA Registration Pathway Completion | Streamlined blistering agent approvals accelerate United States commercial access for novel cantharidin formulations. |
| Telemedicine Triage Integration | Digital diagnostic platforms in Greater London and Manchester optimize care pathway economics for NHS England. |
| Combination Therapy Protocol Development | Sequenced immunomodulation with physical clearance reduces recurrence rates in United States metropolitan referral centers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EPA registration databases, ClinicalTrials.gov pediatric cohort records, and EMA MDR notified body guidance documents. Primary interviews with dermatology clinic medical directors, hospital pharmacy procurement managers, pediatric formulation toxicologists, and payer access specialists informed demand-side validation. Bottom-up patient volume modeling across metropolitan referral clusters triangulates against top-down pharmaceutical revenue estimates.
Segmentation dimensions modeled include treatment modality, delivery mode, end-user setting, and application urgency tier across the projection horizon. CAGRs derive from weighted scenario analysis incorporating regulatory approval timelines, pediatric labeling expansion probabilities, and procedural versus pharmaceutical intervention mix shifts. Forecast inputs incorporate EPA registration pathway velocity, EMA MDR CE marking duration, and metropolitan pediatric dermatology network expansion rates.
Forecasts assume regulatory continuity in FDA, EPA, and EMA MDR regimes; material policy shifts in pediatric safety documentation requirements would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Mast Cell Tumors Treatment Market
Medical Treatment
Celiac Disease Treatment Market
Medical Treatment
Facial Spasm Treatment Market
Medical Treatment
Pompe Disease Treatment Market
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
Europe Platelet Rich Plasma (PRP) Market
Medical Treatment
Malaria Treatment Market
Medical Treatment
Global Acromegaly Treatment Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Lymphedema Treatment Market
Medical Treatment
Radioimmunotherapy Treatment Market
Medical Treatment
Scoliosis Management Market
Medical Treatment
Secondary Hyperparathyroidism Treatment Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Lung Cancer Surgery Market