
 US Direct Anterior Approach (Total Hip Replacement) Market | 2026-2036
US Direct Anterior Approach (Total Hip Replacement) Market Size, Share, and Industry Trends Forecast 2026-2036
US Direct Anterior Approach (Total Hip Replacement) Market Analytics
FDA 510(k) premarket notification requirements for novel hip implant systems is collapsing the field of qualified entrants, forcing substantial clinical evidence investments before commercialization. Stryker Corporation leverages its integrated robotics and implant portfolio to dominate high-volume hospital accounts. Zimmer Biomet sustains broad geographic coverage across independent ambulatory surgical centers. Johnson & Johnson anchors its position through DePuy Synthes-branded anterior-specific instrumentation and training infrastructure.
The direct anterior approach constitutes a total hip arthroplasty technique accessing the hip joint through the interval between the tensor fasciae latae and sartorius muscles without detaching major tendons, typically requiring a 6-10 centimeter incision and specialized retractor systems to protect the lateral femoral cutaneous nerve. Its primary purpose centers on reducing postoperative pain and accelerating early mobilization compared with posterior or lateral approaches. Uncemented implants lead volume due to biologic fixation preferences in younger, active patients seeking long-term durability. Robotic-assisted surgery technology captures disproportionate investment as health systems differentiate on precision metrics and patient-reported outcome scores. Cemented implants occupy a mature, price-sensitive niche concentrated in Medicare-dependent populations with poorer bone quality.
FDA device classification and 510(k) substantial equivalence standards govern implant approval timelines and clinical data requirements, while CMS reimbursement determinations directly shape facility willingness to adopt anterior-specific instrumentation and navigation platforms. State-level certificate-of-need regulations in jurisdictions like New York and Illinois constrain ambulatory surgical center expansion, fragmenting access to specialized anterior procedure volume. Joint Commission accreditation standards for orthopedic excellence programs increasingly incorporate anterior approach case minimums and complication benchmarks. Stakeholders must monitor whether CMS will bundle robotic navigation costs into episode-based payments or preserve separate technology add-on payments.
Market Dynamics
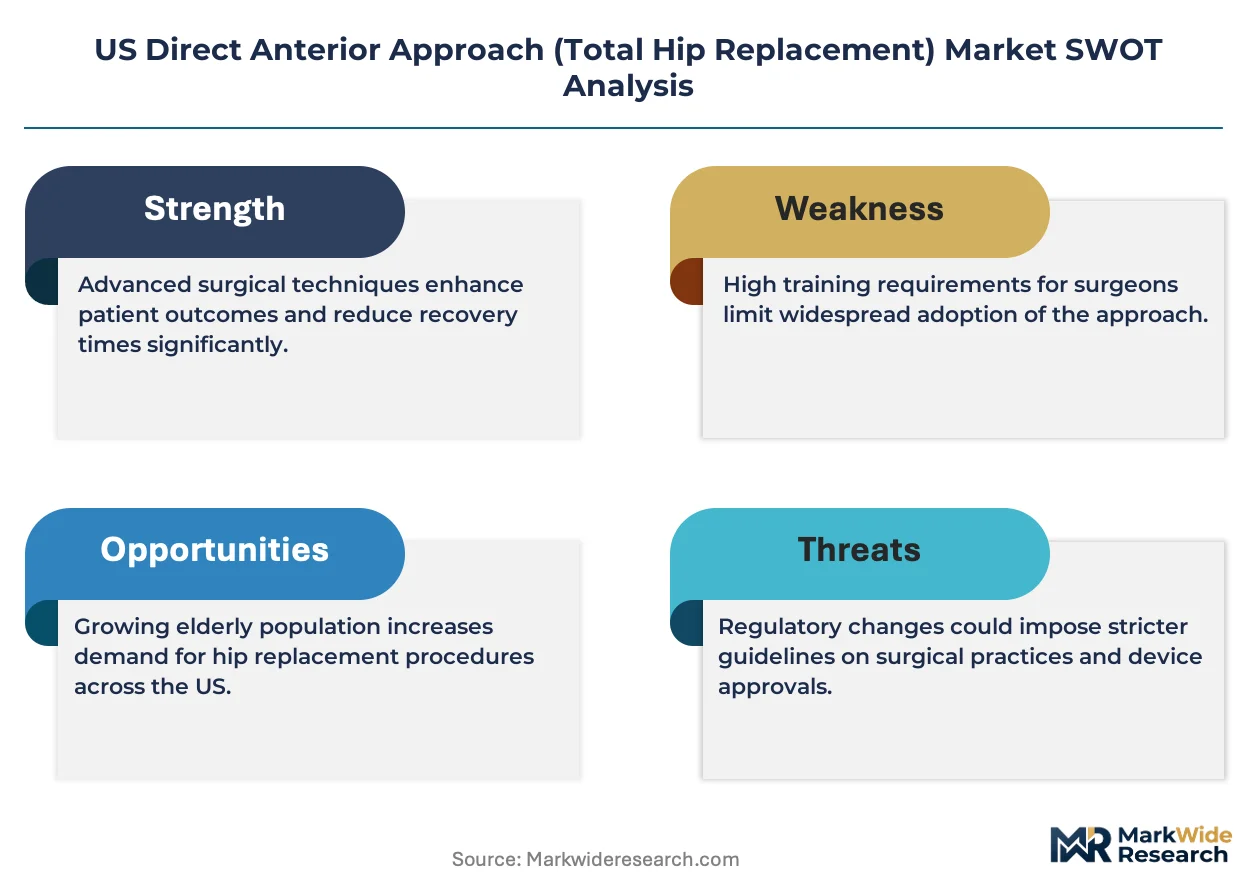
Robotic-assisted surgical platforms are compressing the learning curve for direct anterior approach procedures while CMS reimbursement ambiguity creates facility-level hesitation on capital deployment.
Growth Catalysts
- Ambulatory Surgical Center Expansion:Certificate-of-need reforms in Florida and Texas enable freestanding orthopedic facilities to capture migrating inpatient volume. These centers prioritize muscle-sparing techniques that support same-day discharge protocols.
- FDA 510(k) Pathway Efficiency:Substantial equivalence determinations for iterative implant designs accelerate commercialization timelines compared with PMA routes. Manufacturers leverage predicate device libraries to reduce premarket clinical burden.
- Southeast Health System Consolidation:Large integrated delivery networks in Georgia and North Carolina are building dedicated anterior procedure towers with standardized instrumentation contracts.
Market Restraints
- Titanium Alloy Input Volatility:Spot price fluctuations for surgical-grade titanium sponge constrain implant margin stability. Suppliers pass through raw material escalations on quarterly adjustment clauses.
- Lateral Femoral Cutaneous Nerve Injury Risk:Anatomical proximity complications generate malpractice exposure that elevates professional liability premiums for high-volume anterior surgeons.
- Certificate-of-Need Friction:New York and Illinois CON regimes block ambulatory surgical center entrants from accessing Medicare case volume in dense urban markets.
Strategic Opportunities
- Rural Hospital Robotics Partnerships:Community facilities in the Mountain West lack capital for autonomous platform acquisition. Shared-service models with regional health systems unlock case volume without full capital commitment.
- Episode-Based Payment Bundling:CMS voluntary BPCI-A programs reward anterior approach adoption through reduced length-of-stay metrics. Participants capture gainsharing on total cost-of-care reductions.
- Navigation-Implant Convergence:Preoperative CT-based planning software integration with uncemented implant positioning is reducing revision rates in varus femoral anatomy cases.
Industry Challenges
- Anterior-Specific Surgical Training Pipeline:Residency programs emphasize posterior approach proficiency. Fellowship-trained anterior specialists command compensation premiums that strain smaller practice economics.
- Robotic Platform Interoperability:Proprietary navigation ecosystems lock facilities into single-vendor implant portfolios. Health systems face switching costs when consolidating supplier contracts across multiple sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Direct Anterior Approach (Total Hip Replacement) Market |
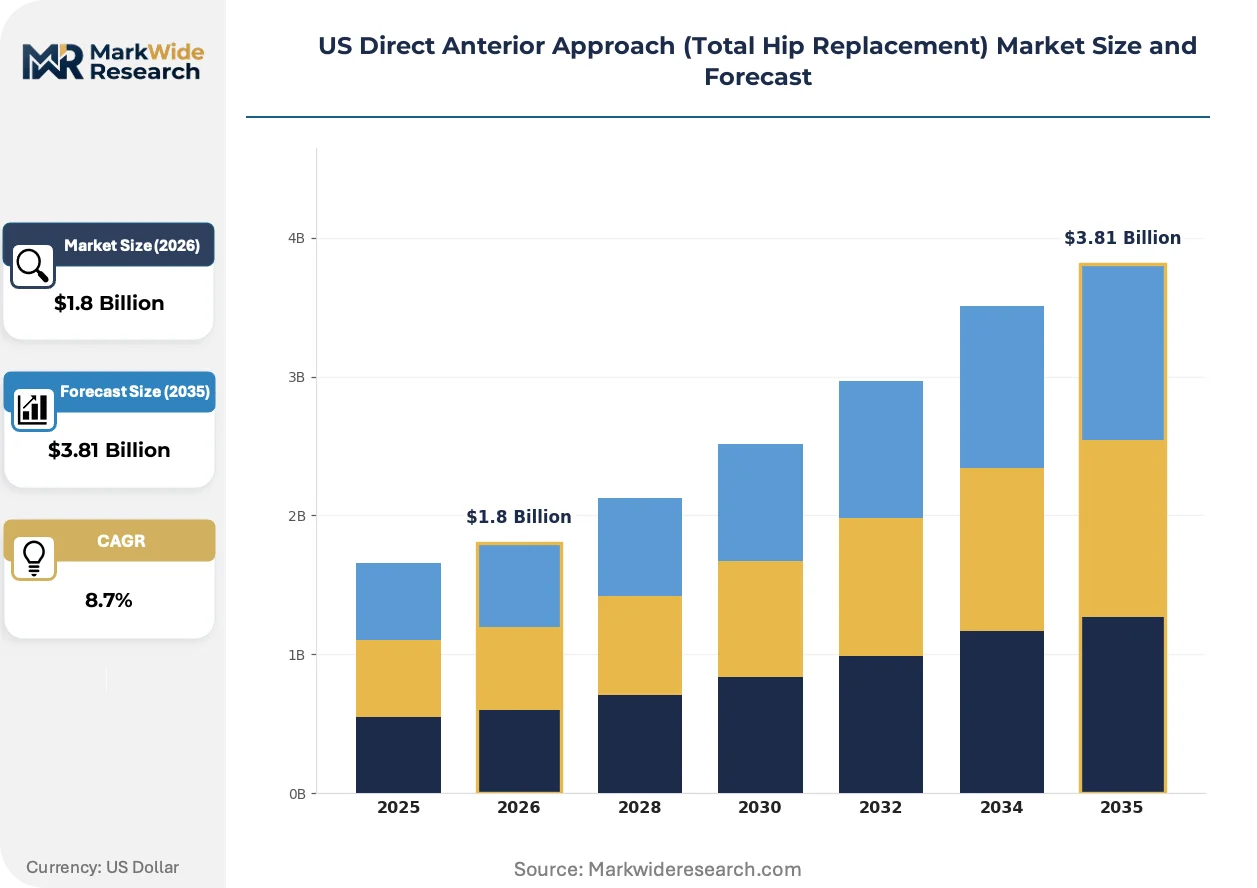
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cemented Implants, Uncemented Implants, Hybrid Implants, Resurfacing Implants End User: Hospitals, Ambulatory Surgical Centers, Rehabilitation Centers, Outpatient Clinics Technology: Robotic-Assisted Surgery, Computer Navigation, Traditional Manual Surgery, 3D Printing Device Material: Polyethylene, Titanium, Cobalt-Chromium, Ceramic |
| Companies Covered | Stryker Corporation, Zimmer Biomet, Johnson & Johnson, Smith & Nephew, OrthAlign, DePuy Synthes, Exactech, Medacta Group, Corin Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Direct Anterior Approach (Total Hip Replacement) Market Evolving Landscape
Precision instrumentation and real-time feedback systems are redefining procedural standardization while reimbursement mechanics lag technological capability.
Haptic-guided reaming systems are displacing freehand acetabular preparation in high-volume academic centers. These platforms provide torque resistance feedback that reduces component malposition rates. Community hospitals without robotics programs face referral leakage to equipped competitors.
FDA 510(k) substantial equivalence standards for robotic navigation software are tightening predicate device requirements. The agency now demands functional performance data on cup positioning accuracy. Manufacturers respond by expanding premarket clinical trial footprints across multiple US sites.
Patient-reported outcome collection is becoming a mandatory credentialing requirement for orthopedic excellence designation. The Joint Commission incorporates HOOS-JR score thresholds into accreditation surveys. Facilities without systematic PROMs infrastructure risk exclusion from narrow network contracts with large employers in the Midwest and Texas markets.
US Direct Anterior Approach (Total Hip Replacement) Market Segmentation
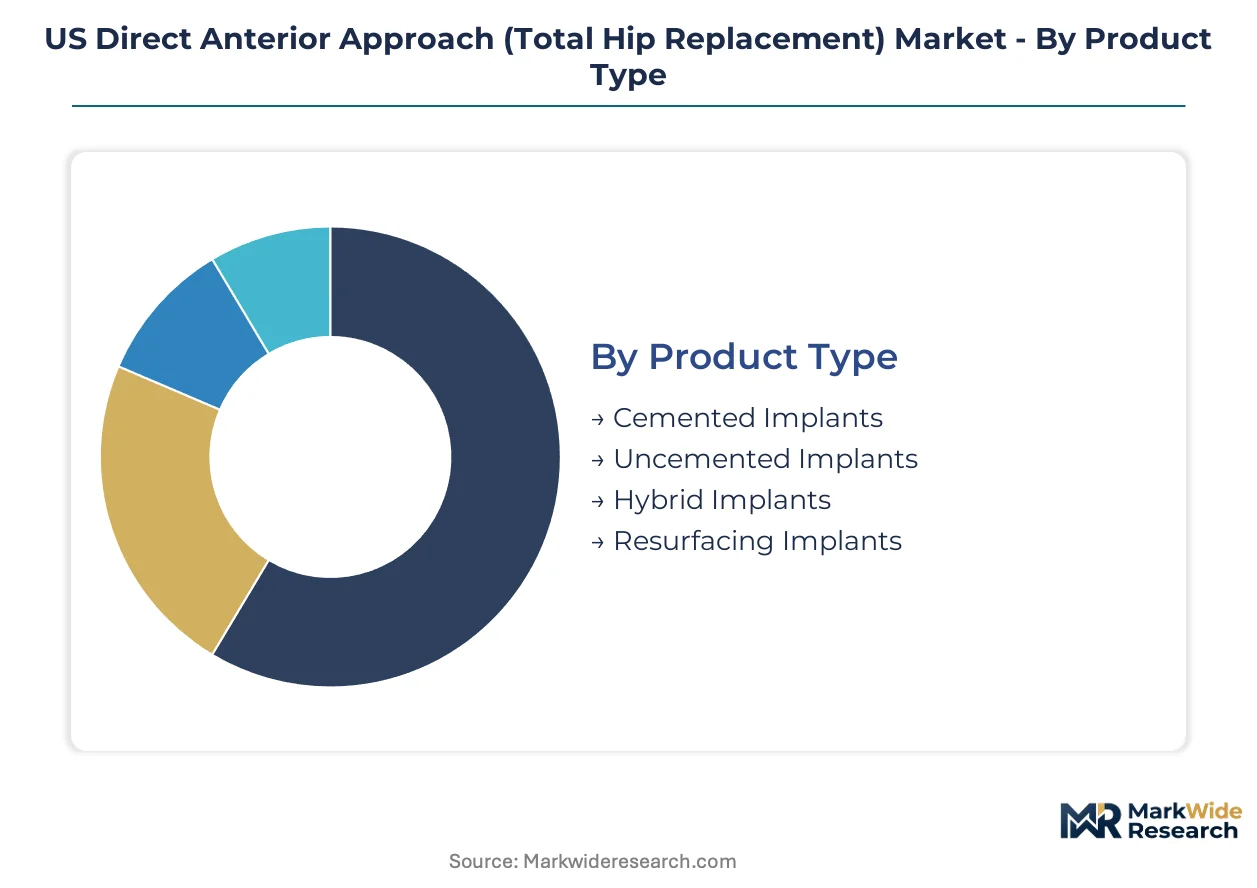
Segmentation in the US direct anterior approach market reveals how surgical technique preferences, reimbursement mechanics, and material science converge to shape procurement patterns. Each dimension carries distinct substitution pressures that manufacturers must navigate when allocating R&D and commercial resources.
Product Type:
Cemented implants face intensifying substitution pressure from biologic fixation alternatives as younger patient cohorts seek longer implant lifespans and bone-preserving options.
- Uncemented Implants:Porous-coated titanium or tantalum surfaces enable osseointegration without bone cement, reducing operative time and particulate debris generation. Demand concentrates in the Southeast where large health systems prioritize same-day discharge protocols enabled by quicker fixation stability.
- Cemented Implants:Polymethylmethacrylate fixation provides immediate mechanical stability for osteoporotic bone, serving Medicare-dependent populations with poorer bone quality. Demand clusters in the Northeast where aging demographics and dense urban hospital networks sustain mature procurement patterns.
- Hybrid Implants:Combines cemented femoral stems with uncemented acetabular components, offering tailored fixation strategies for complex anatomy cases.
- Resurfacing Implants:Conservative bone-preserving option for younger male patients with adequate femoral head bone stock, constrained by metal-on-metal bearing concerns and narrow FDA indications.
Uncemented implants anchor the volume base while robotic-assisted planning capabilities accelerate uncemented positioning accuracy gains.
End User:
Facility type determines capital intensity tolerance and case volume economics, with reimbursement differentials creating divergent technology adoption curves.
- Hospitals:Academic medical centers and community hospitals maintain robotics programs and fellowship-trained anterior specialists, capturing complex revision cases and high-acuity patients. Volume concentrates in integrated delivery networks across Georgia and North Carolina where dedicated orthopedic towers standardize anterior protocols.
- Ambulatory Surgical Centers:Freestanding facilities exploit certificate-of-need reforms in Florida and Texas to capture migrating inpatient volume, prioritizing muscle-sparing techniques that support 23-hour discharge metrics.
- Rehabilitation Centers:Post-acute settings coordinate with anterior procedure sites to leverage accelerated mobilization protocols, reducing skilled nursing facility length-of-stay.
- Outpatient Clinics:Physician-owned entities in certificate-of-need-free states perform select low-complexity cases, constrained by anesthesia and emergency backup requirements.
Hospitals retain the highest-acuity case mix while ambulatory surgical centers expand volume at the steepest rate.
Technology:
Capital deployment decisions hinge on whether precision gains translate to measurable reimbursement advantages or merely defensive market positioning.
- Robotic-Assisted Surgery:Optical tracking and haptic feedback systems enable sub-3-degree acetabular component positioning accuracy, with preoperative CT-based planning reducing outliers in varus femoral anatomy. Investment concentrates in health systems competing for narrow network contracts with large Midwest and Texas employers demanding patient-reported outcome documentation.
- Computer Navigation:Optical or electromagnetic tracking provides real-time instrument positioning without robotic arm constraints, offering intermediate precision at lower capital cost for mid-volume community hospitals.
- Traditional Manual Surgery:Freehand technique relying on mechanical guides and fluoroscopic confirmation, dominant in cost-constrained settings and rural facilities without robotics partnerships.
- 3D Printing:Patient-specific instrumentation and custom implants fabricated from preoperative imaging, emerging in complex revision cases with significant bone loss or prior deformity.
Traditional manual surgery anchors the volume base while robotic-assisted platforms capture disproportionate investment despite reimbursement ambiguity.
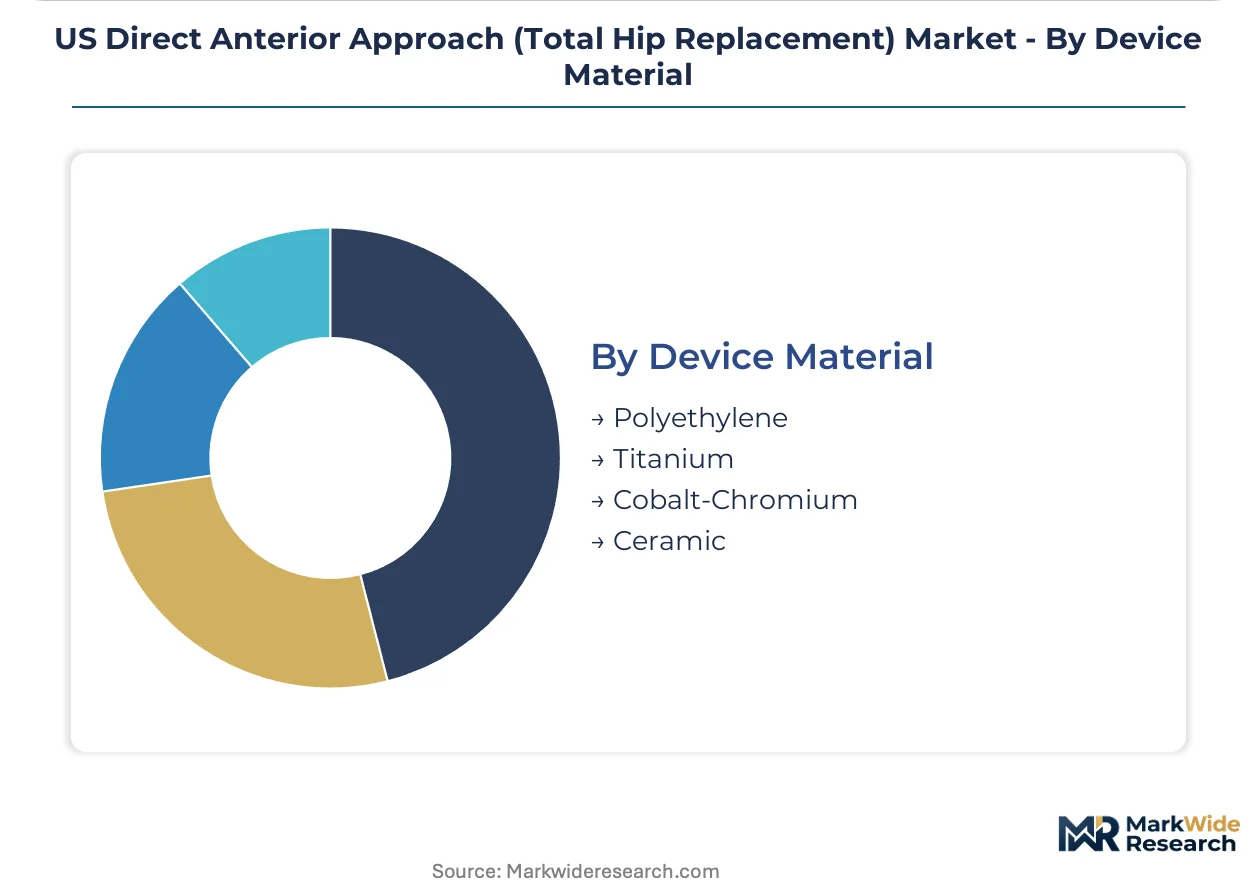
Device Material:
Material selection balances wear characteristics, biocompatibility, and supply chain concentration risks that affect implant pricing stability.
- Titanium:Surgical-grade titanium alloys dominate uncemented stem and porous coating applications, with sponge price volatility transmitted through quarterly supplier adjustment clauses. Procurement concentrates in high-volume academic centers with standardized vendor contracts.
- Ceramic:Alumina and zirconia-toughened alumina bearings deliver superior wear resistance for younger active patients, commanding premium pricing in private-pay segments.
- Polyethylene:Cross-linked ultra-high molecular weight polyethylene remains the dominant bearing surface for acetabular liners, with vitamin E stabilization extending oxidative stability.
- Cobalt-Chromium:Molybdenum-alloyed cobalt-chrome alloys provide high fatigue strength for femoral heads and metal-backed shells, though metal ion release concerns constrain bearing surface applications.
Polyethylene anchors the volume base while ceramic bearings expand most quickly in premium self-pay and commercial insurance segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certificate-of-need reforms and Medicare reimbursement differentials are redistributing direct anterior approach volume across US sub-regions, with regulatory arbitrage driving capital deployment toward states with lighter facility restrictions.
Southeast
Integrated delivery networks in Georgia and North Carolina are constructing dedicated orthopedic surgery towers with standardized anterior instrumentation contracts. Florida's CON reforms enable freestanding ASCs to capture migrating inpatient cases. Atlanta and Charlotte anchor the region's highest-volume anterior procedure clusters.
Southwest
Texas certificate-of-need elimination permits independent ambulatory facilities to expand into suburban Dallas-Fort Worth and Houston markets. Large employers in the state demand patient-reported outcome documentation for narrow network inclusion. San Antonio health systems are piloting shared-service robotics models with rural affiliates.
Midwest
Illinois maintains restrictive CON regimes that block ASC entrants from accessing Medicare volume in Chicago's dense urban core. Michigan and Ohio hospital systems compete for BPCI-A bundled payment participants seeking length-of-stay reductions. Cleveland Clinic anchors academic anterior training infrastructure.
Northeast
New York's CON friction constrains ambulatory surgical center expansion in New York City and Long Island markets. Aging demographics sustain cemented implant demand for osteoporotic populations. Boston's academic medical centers lead haptic-guided reaming adoption.
Mountain West
Community hospitals across Colorado, Utah, and Arizona lack capital for autonomous robotics acquisition. Regional health systems deploy mobile navigation units to capture rural case volume without full platform commitment. Phoenix anchors the sub-region's fastest-growing ASC development corridor.
US Direct Anterior Approach (Total Hip Replacement) Market Competitive Landscape
Listed leaders compete with private specialists across technology integration and training infrastructure dimensions. The vendor base concentrates around three tiers: diversified orthopedic conglomerates with robotics portfolios, mid-cap implant specialists with anterior-specific instrumentation, and navigation software boutiques. Strategic moves center on hospital system exclusive contracts and ASC distribution partnerships.
Within the diversified orthopedic tier, Stryker Corporation and Zimmer Biomet exemplify scale-driven platform consolidation. Johnson & Johnson occupies a position anchoring integrated instrumentation and surgeon training ecosystems. These three entities represent the dominant competitive archetypes shaping procurement patterns across hospital and ambulatory settings.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet |
| Johnson & Johnson |
| Smith & Nephew |
| OrthAlign |
| DePuy Synthes |
| Exactech |
| Medacta Group |
| Corin Group |
| Others |
Value Network & Pricing Analysis
High-volume implant manufacturing at Stryker and Zimmer Biomet facilities generates scale economies that compress per-unit fixed costs and establish price floors smaller competitors cannot match. This concentration of production capacity in the Southeast and Midwest reinforces tiered procurement contracts, where integrated delivery networks leverage volume commitments to extract preferential pricing on anterior-specific instrumentation.
Pricing Analysis
FDA 510(k) clearance tier creates the primary spread between premium robotic-integrated platforms and standard manual instrumentation. Three-tier pricing structure across premium, standard, and economy levels reflects capital intensity, software licensing, and surgeon training bundling. Price erosion runs through the manual surgery tier as ASCs in Florida and Texas pressure suppliers on 23-hour discharge metrics. Medicare-dependent hospitals exhibit highest price sensitivity; academic medical centers with robotics programs show lowest.
Supply Chain Analysis
Titanium sponge processing in the US, Japan, and China anchors surgical-grade alloy supply for uncemented implant production. Raw material dependencies center on surgical-grade titanium sponge, cross-linked polyethylene resin, and ceramic bearing blanks. Single-source vulnerability concentrates in specialized porous coating equipment where two suppliers dominate global capacity. Distribution runs through GPO-negotiated contracts with health systems, supplemented by direct ASC channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The direct anterior approach market sits in early-cycle expansion as certificate-of-need reforms in Sun Belt states accelerate ambulatory surgical center development and same-day discharge protocols.
For Market Incumbents: Shield high-volume hospital accounts from robotic-assisted competitors by embedding training infrastructure into exclusive instrumentation contracts. Deepen backward integration into titanium alloy processing to offset raw material volatility. Prioritize FDA 510(k) predicate libraries that accelerate iterative implant commercialization timelines against emerging navigation software boutiques. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks market access for novel haptic feedback systems addressing lateral femoral cutaneous nerve protection. Target rural hospital robotics partnerships in the Mountain West where shared-service models unlock case volume without full capital commitment. Lead with navigation-implant convergence value propositions in varus femoral anatomy revision cases. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among robotic platform vendors with software maintenance contracts and disposable instrument attach rates. Long-term viability favors navigation-implant convergent technologies over standalone hardware plays. Monitor CMS technology add-on payment determinations as the critical inflection signal for capital deployment willingness across health systems.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Exclusive instrumentation contracts with Georgia and North Carolina integrated delivery networks lock in anterior procedure volume. |
| FDA 510(k) Pathway Optimization | Predicate device libraries reduce premarket clinical burden and accelerate iterative implant commercialization timelines. |
| Reimbursement Strategy | CMS BPCI-A program participation captures gainsharing on length-of-stay reductions from same-day discharge protocols. |
| Software Companion Development | Preoperative CT-based planning integration with uncemented positioning reduces revision rates in complex anatomy cases. |
| ASC Distribution Partnership | Direct channel relationships with Florida and Texas freestanding facilities bypass GPO contracting friction. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CMS reimbursement determinations, hospital procurement databases, and GPO contract archives. Interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and ASC administrators informed demand-side dynamics. Bottom-up implant volume estimates triangulated against top-down health system capital expenditure disclosures.
Segmentation dimensions modeled span product type, end user facility category, technology tier, and device material composition across the projection horizon. CAGRs derive from surgical volume projections, technology penetration curves, and reimbursement scenario weighting. Forecast inputs incorporate CON regulatory reform timelines, titanium alloy price trajectories, and robotic platform installation rates.
Underlying assumptions cover sustained CMS reimbursement for anterior approach procedures, with deviation risk concentrated in technology add-on payment policy shifts. Model boundaries exclude posterior and lateral approach conversion scenarios. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Cytokine Release Syndrome Management Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Nasopharyngeal Carcinoma Treatment Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Hepatocellular Carcinoma (HCC) Treatment Market
Medical Treatment
Japan Radiotherapy Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market
Medical Treatment
Surgical Procedures Volume Market
Medical Treatment
Liver Fluke Treatment Market
Medical Treatment
Congenital Hyperinsulinism Treatment Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Bromhidrosis Disease Treatment Market
Medical Treatment
Hypogonadism Treatment Market
Medical Treatment
Goodpasture Syndrome Treatment Market
Medical Treatment
Precocious Puberty Treatment Market