
 Lymphedema Treatment Market | 2026-2036
Lymphedema Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Lymphedema Treatment Market Intelligence
Modular home-care kits bundling pneumatic devices with compression garments is rebalancing how patients and payers evaluate total cost of ownership. Tactile Medical leverages its vertically integrated manufacturing to control device-to-garment workflow. SIGVARIS GROUP anchors European distribution through specialized lymphology clinics. Bio Compression Systems differentiates via customizable pressure-calibration protocols for post-surgical protocols.
Lymphedema treatment encompasses mechanical decongestion, pharmaceutical intervention, and surgical correction of lymphatic fluid accumulation, with pneumatic compression devices typically delivering calibrated pressures between 20-60 mmHg to stimulate lymphatic return. Compression garments dominate product-type revenue due to recurring replacement cycles and insurance reimbursement structures. Home care settings represent the fastest-growing end-user segment as remote monitoring integration reduces clinic dependency. Vacuum therapy devices command premium positioning where manual drainage capacity is limited.
FDA 510(k) pathways and EMA Medical Device Regulation (MDR) classifications shape market entry timelines for pneumatic compression innovators. ISO 13485 quality management standards govern contract manufacturing relationships across the supply base. Stakeholders must monitor reimbursement code consolidation between hospital outpatient and home health categories as payer mix shifts accelerate.
Market Dynamics
Home-care migration is compressing clinical visit frequency while expanding reimbursable device categories, fundamentally restructuring how pneumatic compression systems reach lymphedema patients and how manufacturers configure service models.
Growth Catalysts
- MDR device reclassification:EMA Medical Device Regulation streamlines pneumatic compression pathway approvals across EU member states, accelerating market entry timelines for calibrated pressure systems.
- Oncology rehabilitation protocols:Post-surgical lymphedema management now integrates pneumatic devices into standard breast cancer care pathways, embedding mechanical decongestion within hospital discharge planning.
- Geriatric home-care infrastructure:Japan's aging demographic concentrates demand for remote lymphatic monitoring, with METI reimbursement codes expanding to cover telehealth-integrated compression therapy.
Market Restraints
- Silicone supply concentration:Medical-grade elastomer sourcing clusters in Southeast Asian chemical processing hubs, exposing garment manufacturers to input cost volatility and logistics disruption.
- Pressure calibration technical ceiling:Current pneumatic systems face physiological limits at sub-20 mmHg thresholds, restricting efficacy for early-stage lymphedema where manual drainage remains superior.
- Reimbursement code fragmentation:US Medicare's bifurcated hospital outpatient versus home health billing categories create administrative friction for patients transitioning between care settings.
Strategic Opportunities
- India tier-2 city penetration:Lymphology clinic networks remain underdeveloped outside Mumbai, Delhi, and Bangalore, presenting whitespace for CDSCO-registered device distributors targeting oncology centers in Ahmedabad and Pune.
- Wearable sensor convergence:Integration of bioimpedance spectroscopy with pneumatic garments enables real-time limb volume monitoring, creating subscription revenue streams beyond hardware sales.
- US IRA preventive care incentives:Inflation Reduction Act provisions expanding Medicare coverage for chronic disease management include lymphedema screening, potentially unlocking preventive device utilization.
Industry Challenges
- Lymphology specialist scarcity:Certified lymphedema therapists represent a bottleneck across Germany and Japan, constraining patient training capacity for home-based pneumatic device operation.
- ISO 13485 audit backlog:Contract manufacturers face extended certification timelines, delaying new entrant production scale-up for custom-calibration pneumatic systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lymphedema Treatment Market |
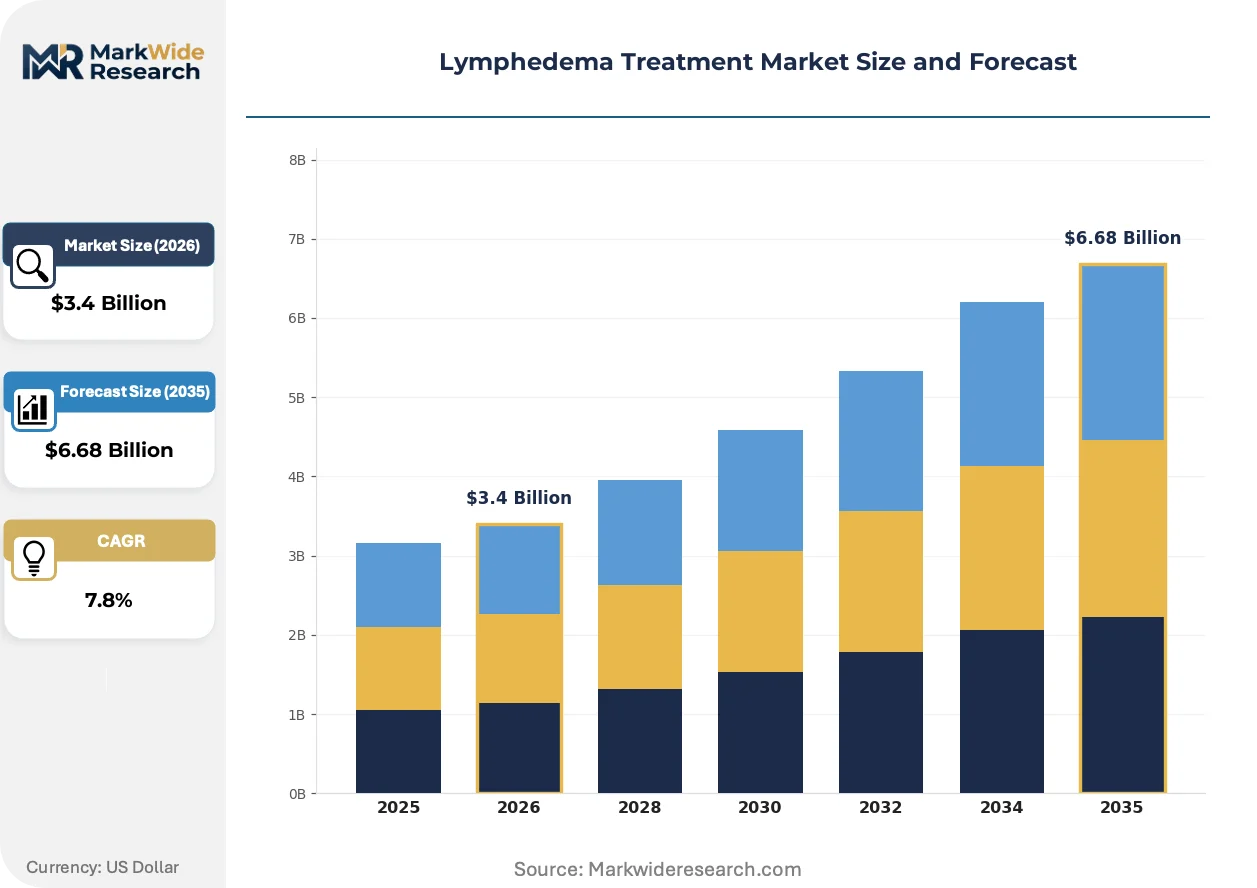
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.68 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Garments, Manual Lymphatic Drainage, Skin Care Products, Vacuum Therapy Devices Therapy Area: Post-Surgical Care, Cancer Rehabilitation, Congenital Disorders, Chronic Conditions End User: Hospitals, Outpatient Clinics, Home Care Settings, Rehabilitation Centers Delivery Mode: Direct Sales, Online Platforms, Distributors, Retail Pharmacies |
| Companies Covered | Tactile Medical, Bio Compression Systems, SIGVARIS GROUP, AIROS Medical, Lohmann & Rauscher, Essity Medical Solutions, Medi GmbH, 3M, Huntleigh Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lymphedema Treatment Market Strategic Shifts & Innovations
Digital connectivity and regulatory harmonization are converging to transform pneumatic compression from episodic clinical intervention into continuous home-based lymphatic management, with reimbursement frameworks racing to catch up to technological capability.
Smart pneumatic garments equipped with pressure-mapping arrays and cellular telemetry are decentralizing lymphedema monitoring from specialized clinics to patient residences. Home health agencies across the United States are adopting these systems at accelerating rates, substituting remote algorithmic pressure adjustment for in-person therapist visits. This shift is compressing the traditional clinic-centric service model while expanding addressable patient populations beyond urban lymphology centers.
EMA Medical Device Regulation harmonization is consolidating previously fragmented national approval pathways for pneumatic compression systems across European member states. Manufacturers now navigate a single conformity assessment procedure rather than sequential country-by-country registrations, reducing time-to-market for innovative pressure-calibration protocols. Germany's specialized lymphology clinics are leveraging this streamlining to source next-generation devices from a broader supplier base.
Patients are demanding unbundled device ownership models that separate hardware acquisition from garment replacement and remote monitoring subscriptions. US durable medical equipment suppliers are responding with financing structures that amortize pneumatic system costs while capturing recurring revenue through sensor-enabled garment refreshes. This behavioral shift is most pronounced among Medicare Advantage enrollees in Florida and Arizona, where seasonal migration patterns favor portable home-based solutions over fixed clinic relationships.
Lymphedema Treatment Market Segmentation
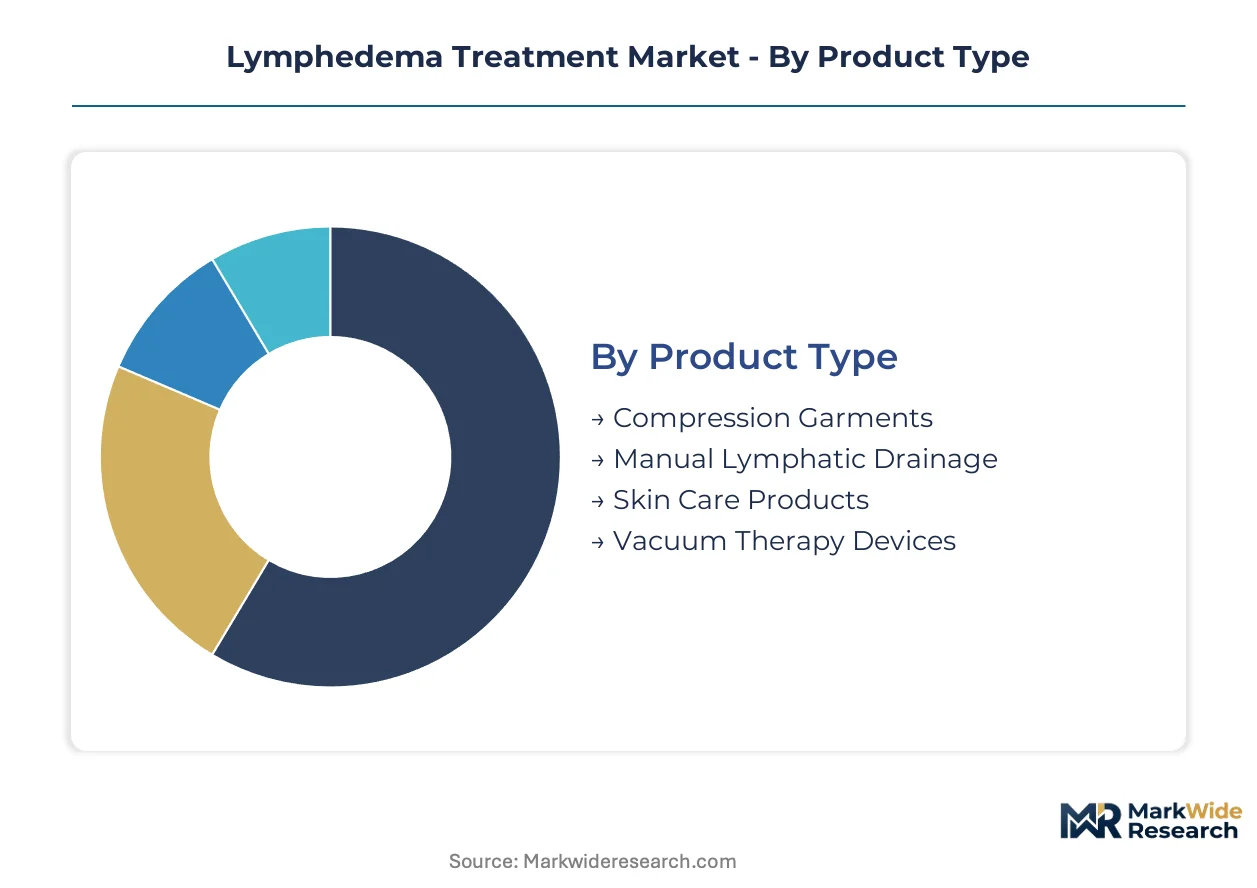
Segmentation in lymphedema treatment reveals how reimbursement structures and care setting migration reshape product demand. Patient acuity, therapy protocol standardization, and distribution economics create distinct commercial pockets across hardware, services, and consumables.
Product Type:
Cost tier differentiation separates acute intervention devices from recurring consumable revenue streams in this category.
- Compression Garments:Gradient-pressure elastic textiles deliver calibrated 20-60 mmHg containment for limb volume management. Demand concentrates in Medicare Advantage networks across Florida and Arizona where seasonal patient migration favors portable garment replacement programs over fixed clinic dependencies.
- Manual Lymphatic Drainage:Therapist-administered sequential massage protocols stimulate lymphatic vessel contractility. Certified lymphedema therapist scarcity across Germany and Japan constrains patient training capacity for home-based technique replication, preserving clinical visit revenue.
- Skin Care Products:pH-balanced emollients prevent secondary infection in compromised dermal barriers.
- Vacuum Therapy Devices:Negative-pressure intermittent compression systems command premium positioning where manual drainage capacity is limited.
Volume sits with Compression Garments; growth tilts toward Vacuum Therapy Devices.
Therapy Area:
Application maturity varies sharply between oncology-integrated protocols and orphan condition management.
- Cancer Rehabilitation:Post-surgical lymphedema management now embeds pneumatic devices into standard breast cancer discharge planning across US hospital networks. METI reimbursement codes in Japan are expanding to cover telehealth-integrated compression therapy for this population.
- Post-Surgical Care:Orthopedic and trauma-related lymphatic compromise requires acute-phase decongestion before garment transition. Demand clusters in German specialized lymphology clinics leveraging EMA MDR harmonization to source next-generation pressure-calibration devices.
- Congenital Disorders:Primary lymphedema from lymphatic malformation presents pediatric dosing challenges for pneumatic systems.
- Chronic Conditions:Long-standing venous insufficiency overlaps with secondary lymphedema in aging demographics.
Cancer Rehabilitation captures the steepest expansion trajectory as oncology protocols standardize mechanical decongestion.
End User:
Customer type determines service model configuration and regulatory pathway complexity.
- Home Care Settings:Remote monitoring integration reduces clinic dependency through cellular-enabled pneumatic garments. US durable medical equipment suppliers are adopting unbundled ownership models that separate hardware acquisition from sensor-enabled garment subscription refreshes.
- Hospitals:Acute care facilities anchor initial device prescription and patient training. FDA 510(k) pathway clearances for pneumatic compression systems are expanding reimbursable indications within hospital outpatient billing categories.
- Outpatient Clinics:Urban lymphology centers concentrate certified therapist resources for complex case management.
- Rehabilitation Centers:Skilled nursing facilities manage post-acute transition before home care handoff.
Hospitals retain volume leadership; Home Care Settings are gaining share fastest as decentralized management preferences harden.
Delivery Mode:
Supply concentration in direct sales channels contrasts with emerging platform economics.
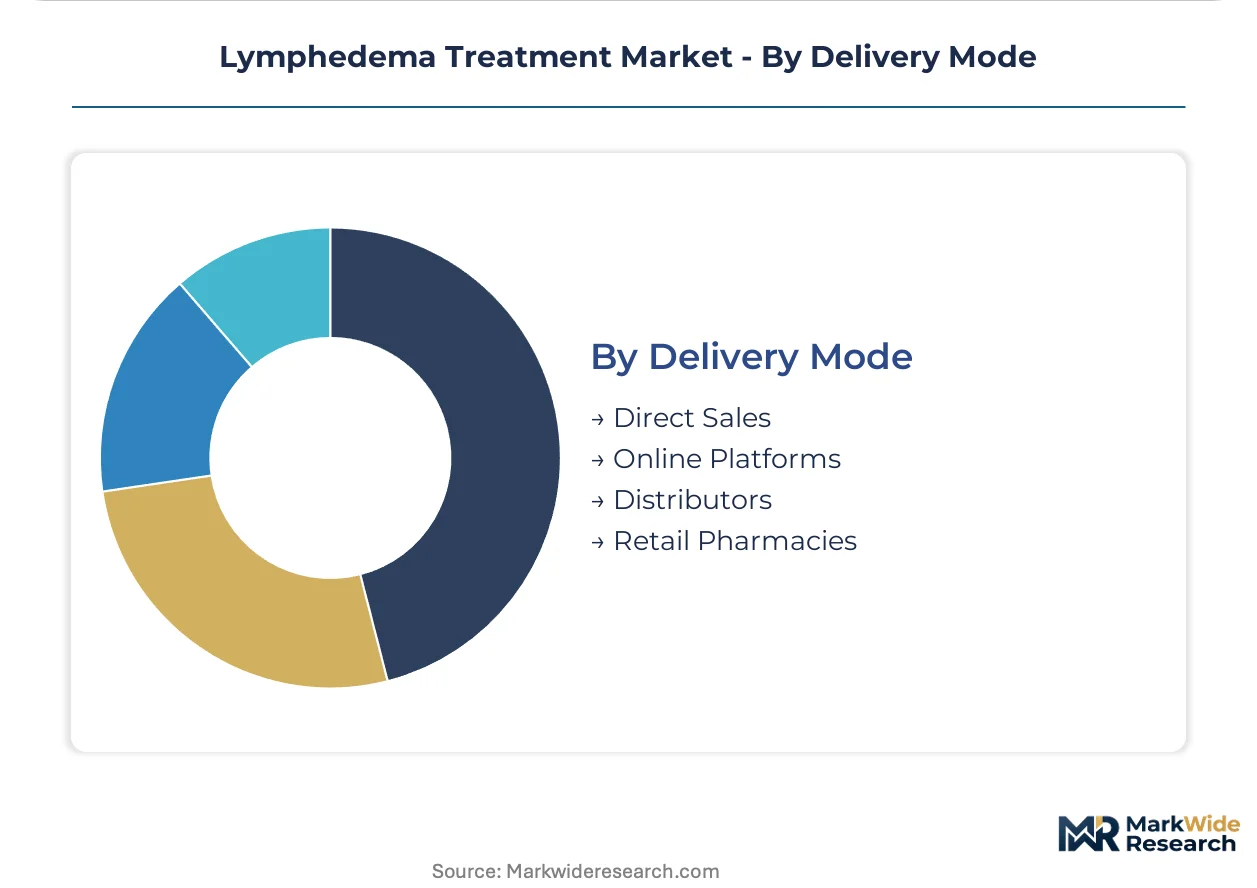
- Distributors:Specialized medical device distributors anchor European market access through relationships with German lymphology clinic networks. SIGVARIS GROUP leverages this channel structure to maintain continental coverage without direct sales force expansion.
- Direct Sales:Manufacturer-controlled account management serves high-volume hospital procurement with custom calibration protocols. Tactile Medical employs this model to capture device-to-garment workflow control through vertically integrated manufacturing.
- Online Platforms:Patient-directed garment replacement bypasses clinical gatekeepers for established therapy patients.
- Retail Pharmacies:Community access points serve compression garment replenishment for stable chronic cases.
Distributors hold current volume; Online Platforms show the sharpest upward trajectory as patient self-direction increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device production clusters in Germany and the United States while patient demand concentrates in aging economies with established oncology infrastructure. Consumption patterns diverge sharply between reimbursement-rich Western markets and emerging economies where out-of-pocket payment dominates access.
United States
Medicare Advantage networks in Florida and Arizona drive seasonal demand for portable pneumatic systems among migrating retirees. FDA 510(k) clearances for compression devices expanded reimbursable indications under hospital outpatient billing codes in 2023. The Minneapolis-St. Paul corridor anchors domestic manufacturing of calibrated pressure systems with vertically integrated garment production.
Germany
Specialized lymphology clinics in Bavaria and North Rhine-Westphalia concentrate certified therapist resources for complex case management. EMA Medical Device Regulation harmonization streamlined conformity assessments for pneumatic compression innovators entering EU markets. The SIGVARIS GROUP maintains continental distribution dominance through relationships with academic medical centers in Munich and Cologne.
Japan
METI reimbursement codes now cover telehealth-integrated compression therapy for post-surgical breast cancer patients. The aging demographic in Kanto and Kansai regions concentrates demand for remote lymphatic monitoring solutions. Tokyo-based durable medical equipment suppliers are adopting unbundled ownership models separating hardware from sensor-enabled garment subscriptions.
India
Oncology centers in Mumbai, Delhi, and Bangalore anchor current device utilization while Ahmedabad and Pune present whitespace for CDSCO-registered distributors. The Central Drugs Standard Control Organization regulates pneumatic compression systems as Class B medical devices with accelerated review pathways for post-surgical applications. Tier-2 city lymphology clinic networks remain underdeveloped, constraining patient access outside metropolitan corridors.
United Kingdom
NHS England's specialized commissioning frameworks concentrate pneumatic device prescription within tertiary lymphology centers in London and Manchester. The Medicines and Healthcare products Regulatory Agency aligns device classifications with EMA MDR standards post-Brexit, preserving market access continuity. Scotland and Wales exhibit lower therapist density, creating geographic disparities in home-care training capacity.
Lymphedema Treatment Market Key Industry Players
The competitive structure tilts toward vertically integrated specialists controlling device-to-garment workflows. Three archetypes dominate: pneumatic system manufacturers with captive textile production, European medical textile houses with compression therapy divisions, and diversified health conglomerates with wound care portfolios. Capacity expansion and geographic licensing partnerships represent the dominant competitive moves as players seek to bridge reimbursement code fragmentation between hospital and home health settings.
Among vertically integrated specialists, Tactile Medical exemplifies the archetype of domestic manufacturers controlling calibration-to-garment workflows. SIGVARIS GROUP occupies a position representing European distribution-heavy models anchored through specialized clinic relationships. Bio Compression Systems sits within the customizable-protocol tier, serving post-surgical segments where pressure calibration requirements vary by procedure type.
| Leading Market Players |
|---|
| Tactile Medical |
| Bio Compression Systems |
| SIGVARIS GROUP |
| AIROS Medical |
| Lohmann & Rauscher |
| Essity Medical Solutions |
| Medi GmbH |
| 3M |
| Huntleigh Healthcare |
| Others |
Cost & Logistics Intelligence
Medical-grade silicone elastomer flows from Southeast Asian chemical processing hubs through garment manufacturers to pneumatic device assemblers, with each tier absorbing volatility that stratifies final pricing across Medicare reimbursement categories and private-pay segments.
Pricing Analysis
Cost-down pressure on economy-tier compression garments accelerates because Southeast Asian silicone suppliers face feedstock volatility, while premium pneumatic systems maintain margin insulation through FDA-cleared calibration protocols. Three-tier pricing structure across premium, standard, and economy levels separates reimbursed hospital outpatient devices from direct-pay home care units and uninsured cash-market garments. Price differentiation rests on ISO 13485 certification status and vertical integration depth, with Medicare Advantage enrollees in migration-heavy states exhibiting highest price sensitivity and German lymphology clinics showing lowest.
Supply Chain Analysis
Dual-sourcing mandates from US durable medical equipment suppliers require qualified silicone suppliers in Thailand and Malaysia alongside backup qualification of Indian elastomer processors. Raw material dependencies center on medical-grade silicone polymers, precision pneumatic valves from Japan, and compression textile weaves from Germany. Supply chain risk concentrates in single-source vulnerability for sub-20 mmHg pressure calibration components. Distribution runs through specialized medical device distributors in Europe and direct sales forces anchoring hospital procurement in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified lymphedema therapist scarcity props pricing for training-intensive pneumatic systems, constraining supply expansion regardless of manufacturing capacity additions.
For Market Incumbents: Anchor market position by deepening backward integration into silicone textile production and securing exclusive GPO contracts with US hospital systems facing Medicare reimbursement code consolidation. Pressure from wearable sensor convergence threatens hardware-centric revenue models, making software companion development a critical defensive lever. For New Entrants and Emerging Players: Bioimpedance spectroscopy integration offers a technology-first wedge into the home care monitoring segment, where unbundled subscription models displace episodic device sales. Target India's tier-2 oncology centers in Ahmedabad and Pune through CDSCO-registered distributor partnerships, leveraging accelerated review pathways for post-surgical pneumatic applications. For Investors and Strategic Acquirers: METI reimbursement code expansion for telehealth-integrated compression therapy is the leading indicator that remote monitoring infrastructure will command premium valuations across the analysis window. Acquisition targets should prioritize vertically integrated manufacturers with captive garment production and existing FDA 510(k) clearances. Watch for consolidation signals when ISO 13485 audit backlogs begin clearing.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Medicare code consolidation between hospital outpatient and home health categories determines addressable patient populations. |
| Software Companion Development | Integration of bioimpedance spectroscopy with pneumatic garments enables recurring subscription revenue beyond hardware sales. |
| CE Marking Pathway | EMA MDR harmonization streamlines EU market entry for calibrated pressure systems across member states. |
| Hospital System Partnership | GPO contract anchoring secures initial device prescription and patient training capacity in oncology discharge protocols. |
| Backward Integration | In-house silicone textile production insulates margin from Southeast Asian feedstock volatility and logistics disruption. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across lymphedema therapists, hospital purchasing committees, biomedical engineers, and GPO contracts managers. FDA 510(k) databases, EMA MDR submission logs, CMS Medicare reimbursement schedules, and Japanese METI device registry records provided validation layers. Bottom-up patient population estimates triangulated against top-down manufacturer shipment data.
Reconciliation of device shipment streams, reimbursement claims volumes, and garment replacement cycles informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, therapy area, end user setting, and delivery mode, with regional regulatory clusters capturing FDA, EMA, METI, and CDSCO pathway differences. CAGRs derived from fitted growth curves applied to diagnosed patient prevalence and device penetration assumptions, incorporating aging demographic projections and oncology protocol standardization trends.
Several conditions sit outside the modeled scope, including novel pharmaceutical interventions displacing mechanical decongestion and radical supply chain relocation away from Southeast Asian silicone processing. Forecasts reflect assumptions about reimbursement code stability and therapist training capacity expansion. Deviation in Medicare Advantage penetration rates or EMA MDR enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Congenital Hyperinsulinism Treatment Market
Medical Treatment
Thyroid Gland Disorders Treatment Market
Medical Treatment
Factor XIII Deficiency Treatment Market
Medical Treatment
Morquio Syndrome Treatment Market
Medical Treatment
Ascites Market
Medical Treatment
Gaucher Disease Treatment Market
Medical Treatment
Europe Platelet Rich Plasma (PRP) Market
Medical Treatment
Vulvovaginal Candidiasis Treatment Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Angioedema Treatment Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Amyloidosis Treatment Market
Medical Treatment
Parathyroid Disease Treatment Market
Medical Treatment
Diphtheria Treatment Market
Medical Treatment
Anemia Treatment Market
Medical Treatment
Cleft Lip Surgery Market