
 North America Natural Gas Market | 2026-2036
North America Natural Gas Market Size, Share, and Industry Trends Forecast 2026-2036
North America Natural Gas Market Analytics
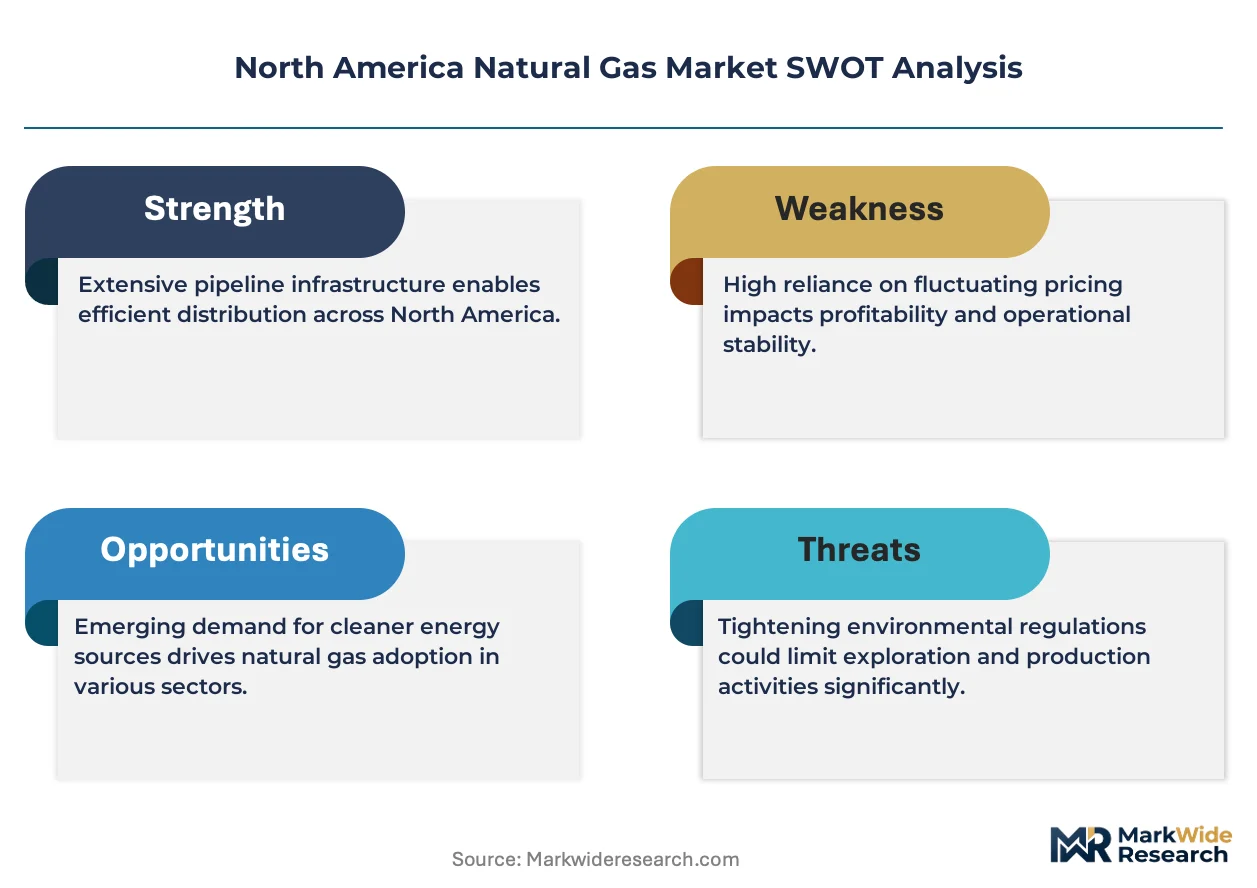
Midstream tolling margins is narrowing as long-haul pipeline contracts reprice and LNG offtake terms shift toward Henry Hub linkage. ExxonMobil Corporation leverages its Permian upstream position to anchor integrated gas-to-LNG economics. Cheniere Energy dominates Gulf Coast liquefaction capacity and sustains its lead through brownfield expansion at Corpus Christi and Sabine Pass. Williams Companies controls Appalachian takeaway routes and competes on Blue Mountain and Transco system reliability.
North America natural gas comprises methane-rich hydrocarbon mixtures extracted from conventional reservoirs, shale formations, and tight sands, with dry gas containing less than 0.1 gallon of natural gas liquids per thousand cubic feet and wet gas carrying heavier hydrocarbons like ethane and propane that require processing before pipeline injection. The commodity serves as a primary fuel for electricity generation, industrial heat, and residential heating, while also functioning as chemical feedstock for ammonia and ethylene production. LNG within the product type segment captures the fastest margin expansion as export capacity additions at Calcasieu Pass and Golden Pass come online, while power generation within the end user segment remains the largest volume sink as coal retirements accelerate across the Midwest and Southeast. Dry gas continues to dominate Appalachian and Haynesville output, though biogas is gaining policy support through EPA renewable fuel standard pathways and state-level clean heat mandates.
FERC certificate authority governs interstate pipeline construction and rate structures, while EPA methane regulations under the Inflation Reduction Act impose fees on venting and flaring above specified thresholds, forcing producers to deploy continuous monitoring technologies. OSHA process safety management standards apply to gas processing and liquefaction facilities, creating compliance costs that favor operators with scale to amortize instrumentation investments. Stakeholders must weigh EPA methane fee escalation against LNG export permit timelines as FERC environmental reviews lengthen and judicial challenges to Gulf Coast projects multiply.
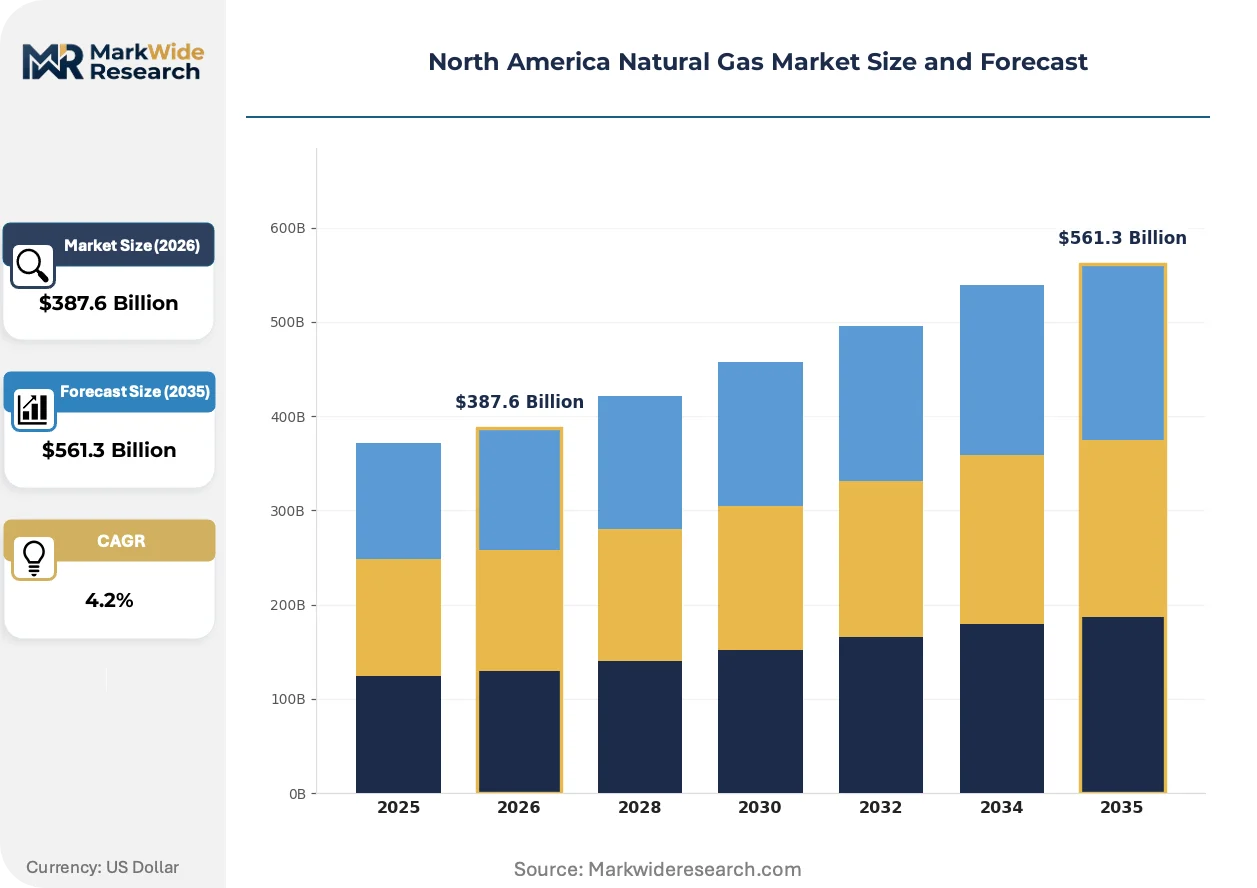
Market Dynamics
EPA methane emission standards under the Inflation Reduction Act are forcing producers to deploy continuous monitoring technologies across the value chain, compressing margins for small operators while advantaging scaled players with capital to absorb instrumentation investments.
Growth Catalysts
- Power generation retirements:Coal plant closures across the Midwest and Southeast are redirecting baseload demand toward combined-cycle gas turbines, expanding offtake volumes for pipeline operators.
- EPA methane fee structure:The Inflation Reduction Act's escalating penalties on venting and flaring above specified thresholds are accelerating leak detection and repair protocol adoption.
- Liquefaction terminal clustering:Gulf Coast export capacity additions at Calcasieu Pass and Golden Pass are anchoring Henry Hub-linked offtake contracts and pulling associated gas production from Permian and Haynesville basins.
Market Restraints
- Long-haul pipeline contract repricing:Legacy take-or-pay agreements rolling off are resetting at narrower tolling margins, compressing midstream returns on Appalachian and Permian takeaway routes.
- FERC certificate timeline elongation:Environmental review processes for interstate pipeline construction have lengthened substantially, delaying greenfield projects and trapping production in oversupplied basins.
- Electrification substitution:Residential and commercial heating electrification mandates in California and New York are eroding core demand segments for local distribution companies.
Strategic Opportunities
- Biogas pathway expansion:EPA renewable fuel standard credits and state-level clean heat mandates in California are creating offtake premiums for renewable natural gas injected into interstate pipelines.
- Brownfield liquefaction expansion:Existing Gulf Coast sites with permitted infrastructure offer faster capacity additions than greenfield developments, concentrating investment at Corpus Christi and Sabine Pass corridors.
- Continuous monitoring technology convergence:Satellite-based detection systems paired with ground-based sensors are hybridizing emissions management into integrated platforms that command premium service contracts.
Industry Challenges
- Specialized technician scarcity:Cryogenic liquefaction and gas processing facilities face acute shortages of process safety management certified operators, constraining uptime at complex plants.
- Judicial challenge velocity:Gulf Coast LNG export permits face accelerating litigation timelines, creating execution risk for offtake contracting and final investment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Natural Gas Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $561.3 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Gas, Wet Gas, Biogas, LNG End User: Power Generation, Industrial, Residential, Commercial Application: Heating, Electricity Generation, Fuel, Chemical Feedstock Distribution Channel: Pipelines, Truck, Rail, Import |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, ConocoPhillips, Chesapeake Energy, EOG Resources, Inc., Kinder Morgan, Williams Companies, Energy Transfer, Cheniere Energy, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Natural Gas Market Evolving Landscape
Digital instrumentation and emissions accountability are compressing operational tolerances across production, processing, and liquefaction stages, forcing capital redeployment toward monitoring infrastructure and away from pure volume expansion.
Continuous methane monitoring technology is hybridizing optical gas imaging with aerial LiDAR and satellite-based detection to create layered surveillance systems. Midstream operators with extensive gathering networks are deploying these platforms fastest to preempt EPA fee exposure. The structural consequence is a shift from periodic inspection to real-time emissions management, privileging technology vendors with integrated hardware-software offerings.
The Inflation Reduction Act's methane waste emissions fee imposes escalating penalties on venting and flaring volumes above facility-specific thresholds. Producers in the Permian and Bakken are consolidating operations to spread fixed compliance costs across larger throughput bases. Dry gas output from Appalachian and Haynesville formations faces the steepest fee exposure due to processing complexity and gathering line density.
Utility procurement is compressing contracting cycles as power generators seek flexibility to balance renewable intermittency. Long-term baseload gas purchase agreements are fragmenting into shorter tenors with index-linked pricing, displacing traditional fixed-price structures. This pattern concentrates in Texas and the Southeast where solar and wind capacity additions are accelerating fastest.
North America Natural Gas Market Segmentation
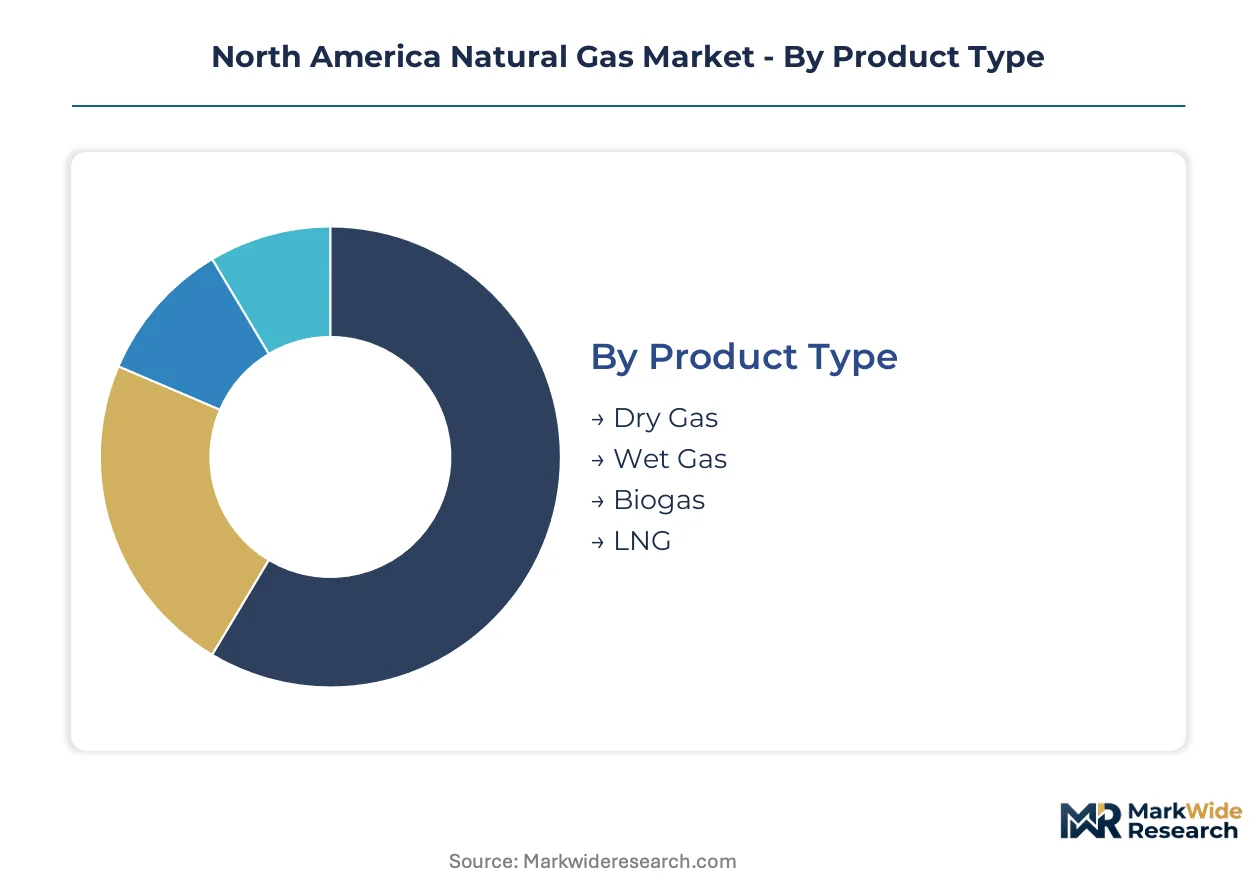
Segmentation in North American natural gas reveals how infrastructure constraints and regulatory exposure concentrate value across different product streams and delivery pathways. Understanding these divisions exposes where capital deployment faces the shortest payback periods versus stranded asset risk.
Product Type:
Cycle times vary dramatically across product types, with pipeline-ready dry gas turning over in days while liquefaction projects lock capital for years before first cargo.
- Dry Gas:Contains less than 0.1 gallon of natural gas liquids per thousand cubic feet, requiring minimal processing before interstate pipeline injection. Appalachian and Haynesville basins supply the bulk of volumes, though EPA methane fee exposure runs highest here due to gathering line density and processing complexity.
- LNG:Supercooled to minus 162 degrees Celsius for marine transport, this product commands premium pricing linked to Henry Hub benchmarks. Gulf Coast liquefaction terminals at Corpus Christi and Sabine Pass anchor capacity additions, with brownfield expansions outpacing greenfield development timelines.
- Wet Gas:Carries heavier hydrocarbons including ethane, propane, and butane that require fractionation before market delivery. Associated gas from Permian oil production supplies most wet gas volumes.
- Biogas:Methane captured from anaerobic digestion of organic waste, upgraded to pipeline quality through conditioning systems. California clean heat mandates and EPA renewable fuel standard credits support injection premiums.
Dry gas dominates installed base. LNG is where expansion concentrates.
End User:
Cost tier differentiation separates capital-intensive industrial buyers from price-sensitive residential accounts, with contract structures varying accordingly.
- Power Generation:Combined-cycle gas turbines consume the largest volume share as coal retirements accelerate across the Midwest and Southeast. Utility procurement is fragmenting into shorter tenors with index-linked pricing to balance renewable intermittency.
- Industrial:Petrochemical complexes, refineries, and ammonia plants require high-volume, high-pressure delivery with interruptible rate structures. Gulf Coast clustering near liquefaction terminals minimizes basis differentials for these buyers.
- Residential:Local distribution companies serve seasonal heating demand through city-gate delivery points. Electrification mandates in California and New York are eroding core demand segments.
- Commercial:Hotels, hospitals, and retail chains purchase through utility tariffs or retail marketers depending on scale. Cogeneration systems in urban centers are displacing standalone boiler installations.
Power generation anchors volume throughput. Industrial offtake is climbing the fastest.
Application:
Margin structure varies by application, with chemical feedstock commanding specification premiums versus commodity heating uses.
- Heating:Space and water heating in buildings represents the most seasonal demand pattern, with winter price spikes in New England and the Midwest. Heat pump electrification is displacing gas furnaces in coastal markets.
- Electricity Generation:Baseload and peaking power plants require firm delivery contracts with swing flexibility. Texas ERCOT market volatility is reshaping generator procurement toward real-time index exposure.
- Fuel:Compressed natural gas for vehicle fleets and marine bunkering competes with diesel on energy-equivalent pricing. California Low Carbon Fuel Standard credits support adoption in heavy-duty trucking.
- Chemical Feedstock:Ethane cracking for ethylene and methane reforming for ammonia require polymer-grade purity specifications. Gulf Coast petrochemical corridors concentrate demand for NGL-rich feedstocks.
Heating retains the largest installed equipment base. Chemical feedstock is where capacity additions concentrate.
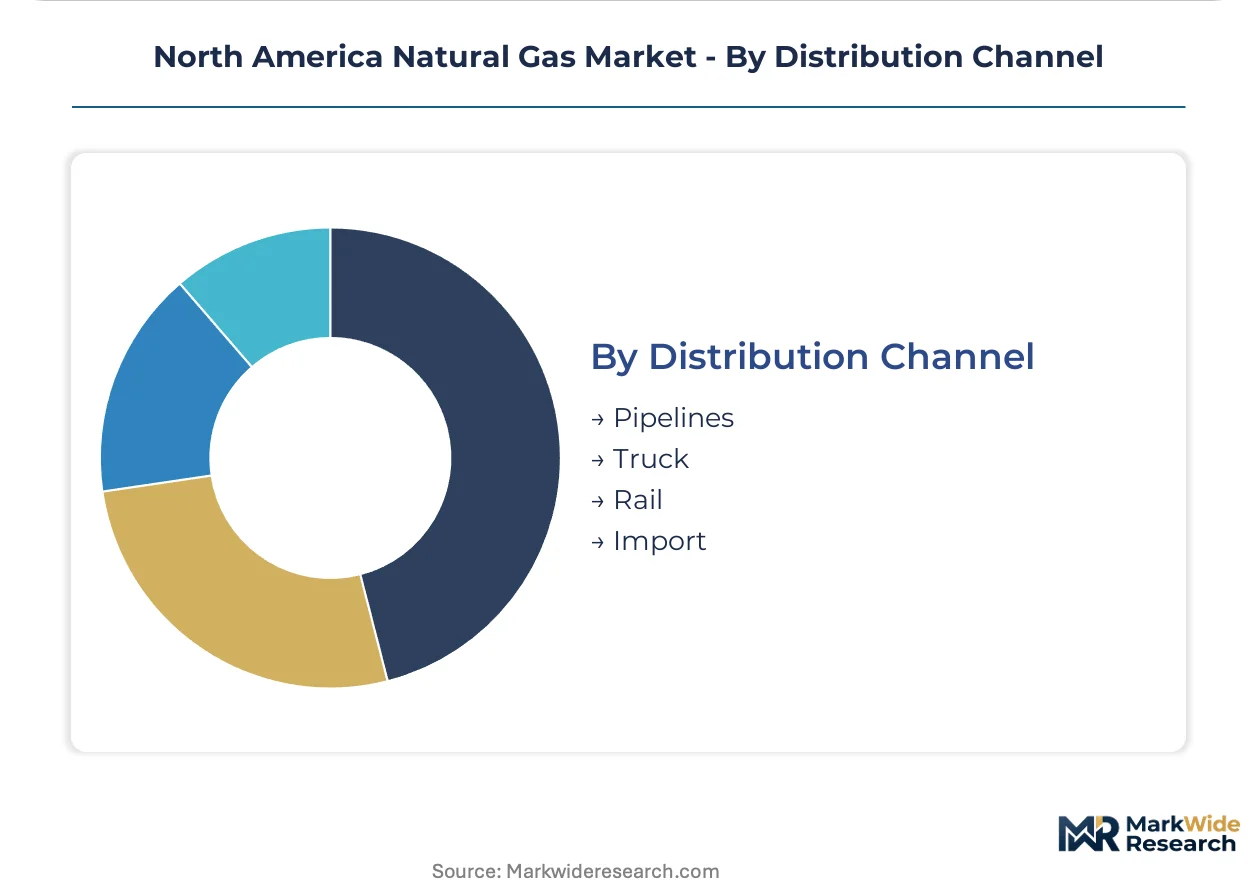
Distribution Channel:
Supply concentration dictates channel economics, with pipeline-connected basins enjoying cost advantages over truck and rail alternatives.
- Pipelines:Interstate systems governed by FERC certificate authority move over 90 percent of dry gas volumes. Legacy take-or-pay contracts repricing at narrower tolling margins are compressing midstream returns.
- Truck:Compressed natural gas tube trailers and LNG tanker trucks serve off-grid industrial sites and remote power generation. Permian and Bakken production flaring reduction is expanding virtual pipeline demand.
- Rail:Cryogenic tank cars move LNG to storage facilities beyond pipeline reach, particularly in New England and Pacific Northwest markets. Unit train economics compete with marine imports on delivered cost.
- Import:Marine LNG terminals at Everett, Cove Point, and Elba Island supplement domestic supply during winter demand peaks. Canadian pipeline imports to the Northeast are displacing some marine volumes.
Pipelines dominate installed infrastructure. Truck and rail are where logistics investment is accelerating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Texas and Louisiana show the least price sensitivity due to direct Henry Hub access, while New England utilities face acute winter volatility that amplifies cost consciousness. This demand-elasticity contrast shapes infrastructure investment patterns across the continent.
United States
Gulf Coast petrochemical complexes and LNG export terminals anchor the highest-volume demand nodes. EPA methane waste emissions fees under the Inflation Reduction Act escalate penalties on venting and flaring, forcing Permian and Bakken producers toward continuous monitoring adoption. Corpus Christi and Sabine Pass liquefaction corridors concentrate brownfield expansion activity.
Canada
Alberta oil sands operations and British Columbia LNG export projects drive western Canadian demand, while Ontario and Quebec heating markets remain seasonally price-sensitive. The country's national energy regulator governs interprovincial pipeline certificates with environmental review timelines that have lengthened substantially. Western Canadian Sedimentary Basin supply feeds both Pacific Coast LNG terminals and US Midwest markets.
Mexico
Industrial demand from northern manufacturing corridors and power generation in the Yucatán Peninsula pull US pipeline imports southward. The country's national energy regulator oversees natural gas transportation permits with terms that favor long-term capacity contracts. Burgos Basin production and marine LNG imports at Manzanillo and Altamira diversify supply beyond US interconnections.
North America Natural Gas Market Competitive Landscape
Integrated majors and pure-play midstream operators split the market between upstream-to-LNG control and tolling-fee specialization. The structure concentrates around scale advantages in liquefaction capacity and pipeline network density. Three archetypes dominate: Permian-anchored integrated gas-to-LNG players, Appalachian takeaway specialists, and Gulf Coast liquefaction tollers. Competitive moves center on brownfield terminal expansion and gathering system consolidation to spread EPA compliance costs.
Within the integrated archetype, ExxonMobil Corporation anchors Permian-to-Gulf-Coast value chain control. Cheniere Energy exemplifies pure-play liquefaction scale at Corpus Christi and Sabine Pass. Williams Companies occupies the midstream specialist tier with Appalachian and Gulf Coast gathering and transmission positioning.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| ConocoPhillips |
| Chesapeake Energy |
| EOG Resources, Inc. |
| Kinder Morgan |
| Williams Companies |
| Energy Transfer |
| Cheniere Energy |
| Others |
Value Network & Pricing Analysis
Permian Basin production concentration anchors Henry Hub pricing power and compresses basis differentials for Gulf Coast buyers. Pipeline tolling margins narrow as legacy contracts reprice, forcing midstream operators to absorb fixed costs across shrinking throughput spreads.
Pricing Analysis
Long-term offtake contracts dominate LNG export pricing, with Henry Hub linkage replacing oil-indexed structures at Corpus Christi and Sabine Pass terminals. Price differentiation rests on liquefaction capacity access and pipeline interconnectivity, with stranded Appalachian supply facing steepest discounts. Cost compression in dry gas gathering stems from EPA methane fee escalation and continuous monitoring mandates. Power generators exhibit highest price sensitivity due to renewable substitution options, while Gulf Coast petrochemical buyers show least sensitivity given direct Henry Hub access and interruptible rate structures.
Supply Chain Analysis
Tariff exposure between US and Canada on steel pipe and compressor equipment dominates midstream construction cost volatility. Supply concentrates in Texas and Louisiana for liquefaction equipment, with Germany and Japan supplying cryogenic turbomachinery. Raw material dependencies include nickel alloys for heat exchangers, specialized insulation systems, and high-pressure pipeline steel. Single-source vulnerability runs through cryogenic valve and control system vendors. Distribution runs through FERC-regulated interstate pipelines, with truck and rail serving off-grid industrial sites and New England winter peak demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward utility procurement consolidation as independent power producers merge and long-term contracting fragments into shorter tenors. This concentration among offtakers compresses supplier margins and accelerates index-linked pricing adoption.
For Market Incumbents: Entrench gathering system density in Appalachian and Haynesville corridors to spread EPA methane compliance costs across larger throughput bases. Defend liquefaction tolling margins through brownfield expansion at permitted Gulf Coast sites rather than greenfield development exposed to judicial challenge timelines. Prioritize backward integration into cryogenic maintenance capabilities to address certified technician scarcity constraining plant uptime.
For New Entrants and Emerging Players: Build out biogas upgrading and pipeline injection infrastructure in California and New York markets where clean heat mandates support renewable natural gas premiums. Target stranded associated gas in Permian and Bakken basins where flaring reduction economics create virtual pipeline opportunities. Lead with continuous monitoring technology platforms that bundle hardware-software offerings to preempt EPA fee exposure for small producers lacking capital for in-house compliance systems.
For Investors and Strategic Acquirers: Capital is best deployed toward midstream operators with FERC-regulated interstate pipeline networks and established rate base structures that amortize environmental compliance investments. Long-term viability over the coming decade hinges on positioning for LNG export demand growth while managing electrification substitution risk in residential heating segments. Watch FERC certificate timeline velocity as the critical inflection signal—elongated review periods trap production in oversupplied basins and compress regional pricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Brownfield Liquefaction Expansion | Existing Gulf Coast permits at Corpus Christi and Sabine Pass accelerate capacity additions versus greenfield timelines. |
| Continuous Monitoring Technology Deployment | Hybrid satellite-ground sensor platforms preempt EPA methane waste emissions fees and command premium service contracts. |
| Biogas Pathway Development | California clean heat mandates and EPA renewable fuel standard credits create injection premiums for upgraded landfill and agricultural methane. |
| Gathering System Consolidation | Appalachian and Haynesville network density spreads fixed EPA compliance costs across larger producer throughput bases. |
| Cryogenic Technician Pipeline Investment | Process safety management certified operator scarcity constrains liquefaction plant uptime and creates competitive moat for scaled training programs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA production databases, FERC pipeline certificate filings, EPA regulatory dockets, and IEA natural gas market reports. Interviews with utility fuel procurement officers, independent power developer planning leads, midstream gathering system operators, and LNG offtake contracting specialists were triangulated against SEC 10-K disclosures and project development announcements. Bottom-up basin-level production modeling and top-down demand sector aggregation were cross-validated to establish volume and value estimates.
Forecast inputs include power generation capacity retirement schedules, LNG export terminal construction timelines, EPA methane fee escalation trajectories, and residential electrification policy implementation rates. Segmentation dimensions span product type, end user category, application, and distribution channel, with regional regulatory framework and grid market structure as cross-cutting variables. CAGRs were derived from supply-demand balance modeling across the projection horizon, incorporating liquefaction capacity additions and pipeline takeaway constraints as binding assumptions.
Stress conditions across Henry Hub price volatility, FERC certificate approval delays, and judicial challenge success rates for Gulf Coast permits were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about coal retirement velocity, renewable intermittency patterns, and biogas policy support durability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United Kingdom LNG Market
Oil & Gas
Crude Oil Assay Testing Services Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
Methane Hydrate Extraction Market
Oil & Gas
Mud Logging Unit Market
Oil & Gas
Asia-Pacific Underground Coal Gasification Market
Oil & Gas
Europe Hydraulic Fracturing Market
Oil & Gas
Saudi Arabia Liner Hanger System Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Oilfield Services Market
Oil & Gas
Underreamers Market
Oil & Gas
Well Completion Equipment Service Market
Oil & Gas
Kazakhstan Oil and Gas Midstream Market
Oil & Gas
Marine Oil Water Separators Market
Oil & Gas
North America Drilling Completion Fluids Market