
 Well Completion Equipment Service Market | 2026-2036
Well Completion Equipment Service Market Size, Share, and Industry Trends Forecast 2026-2036
Well Completion Equipment Service Market Intelligence
Aftermarket service revenue for subsea completion systems is reconfiguring margin pools away from pure equipment sales toward long-term service contracts. Baker Hughes Company leverages its integrated turbomachinery and completion portfolio to capture recurring overhaul work. Weatherford International PLC anchors its position through proprietary expandable liner hanger technology that locks in follow-on intervention business. Halliburton Company competes by extending its digital wellbore construction platform into predictive maintenance offerings for downhole equipment.
Well completion equipment service encompasses the technical assembly, pressure testing, and sustained integrity management of downhole and subsea hardware required to bring hydrocarbon wells into production. Packers rated to 15,000 psi differential pressure and tubing hangers designed for H2S service conditions illustrate the metallurgical and sealing precision demanded in sour gas environments. Installation services dominate current revenue allocation given the capital intensity of initial well completion, while inspection and maintenance categories are expanding fastest as mature basins require more frequent intervention to sustain output. Offshore wells command premium service economics due to the logistical complexity of subsea interventions and the non-productive time costs associated with rig standby.
API specification Q1 governs manufacturing quality management for well completion equipment, while ISO 13628-4 defines design and testing protocols for subsea production control systems; both frameworks elevate barriers for non-certified entrants seeking operator approval. The US Bureau of Safety and Environmental Enforcement enforces well containment requirements that directly shape subsea blowout preventer and safety valve specifications for Gulf of Mexico operations. Stakeholders must monitor how carbon intensity disclosure obligations from the EU CSRD and evolving methane performance standards from the US EPA redirect operator procurement criteria toward lower-emission completion technologies.
Market Dynamics
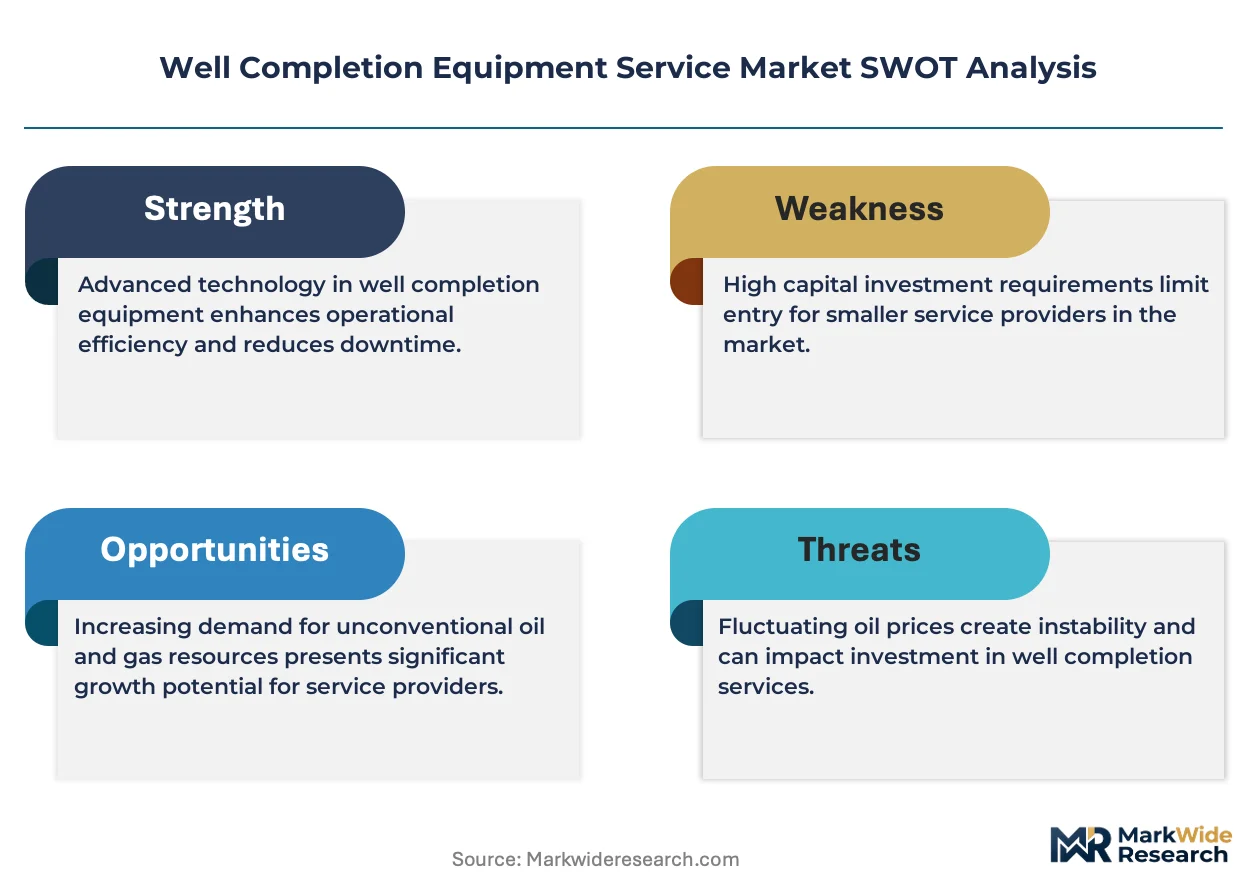
Service revenue pools are tilting toward recurring integrity management contracts as operators defer capital-intensive new well completions in favor of sustaining production from existing assets. API Q1 and ISO 13628-4 compliance thresholds are simultaneously compressing the supplier base by disqualifying uncertified competitors from tender participation.
Growth Catalysts
- Shale basin refrac intensity:Unconventional operators in the Permian and Bakken formations are accelerating re-stimulation schedules to offset base decline, pulling demand for packer redeployment and tubing hanger replacement services.
- Subsea tieback expansion:Pre-salt developments off Brazil are mandating modular completion architectures that require specialized installation vessels and post-installation pressure testing protocols.
- EPA methane performance standards:Leak detection and repair obligations for wellhead equipment are expanding the addressable market for seal integrity monitoring and fugitive emissions verification services.
Market Restraints
- Specialized alloy supply concentration:Chromium-molybdenum steel forgings for sour service packers originate from a limited set of European and Japanese mills, exposing lead times to geopolitical friction.
- Deepwater rig slot scarcity:Floating drilling unit availability constraints in the Gulf of Mexico and West Africa are compressing installation windows and deferring service revenue recognition.
- Subsea intervention vessel day rates:The capital intensity of light well intervention spreads is pricing independent service providers out of deepwater aftermarket capture.
Strategic Opportunities
- CCUS well repurposing:Depleted oil and gas reservoirs in Texas and Louisiana are converting to carbon sequestration, requiring recompletion with corrosion-resistant tubing and annular monitoring systems.
- EU CSRD carbon disclosure:Scope 3 emissions reporting mandates are redirecting operator procurement criteria toward service providers with certified lower-carbon installation methodologies.
- Predictive analytics convergence:Real-time downhole sensor data integration with digital twin platforms is enabling condition-based intervention scheduling that reduces non-productive time.
Industry Challenges
- Specialized welding certification gaps:Inconel cladding and orbital welding qualifications for subsea connectors face a shrinking qualified labor pool as veteran technicians exit the workforce.
- Legacy control system integration:Brownfield subsea installations with 1990s-era hydraulic control umbilicals resist seamless integration with electric-actuated completion components without full well workover.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Well Completion Equipment Service Market |
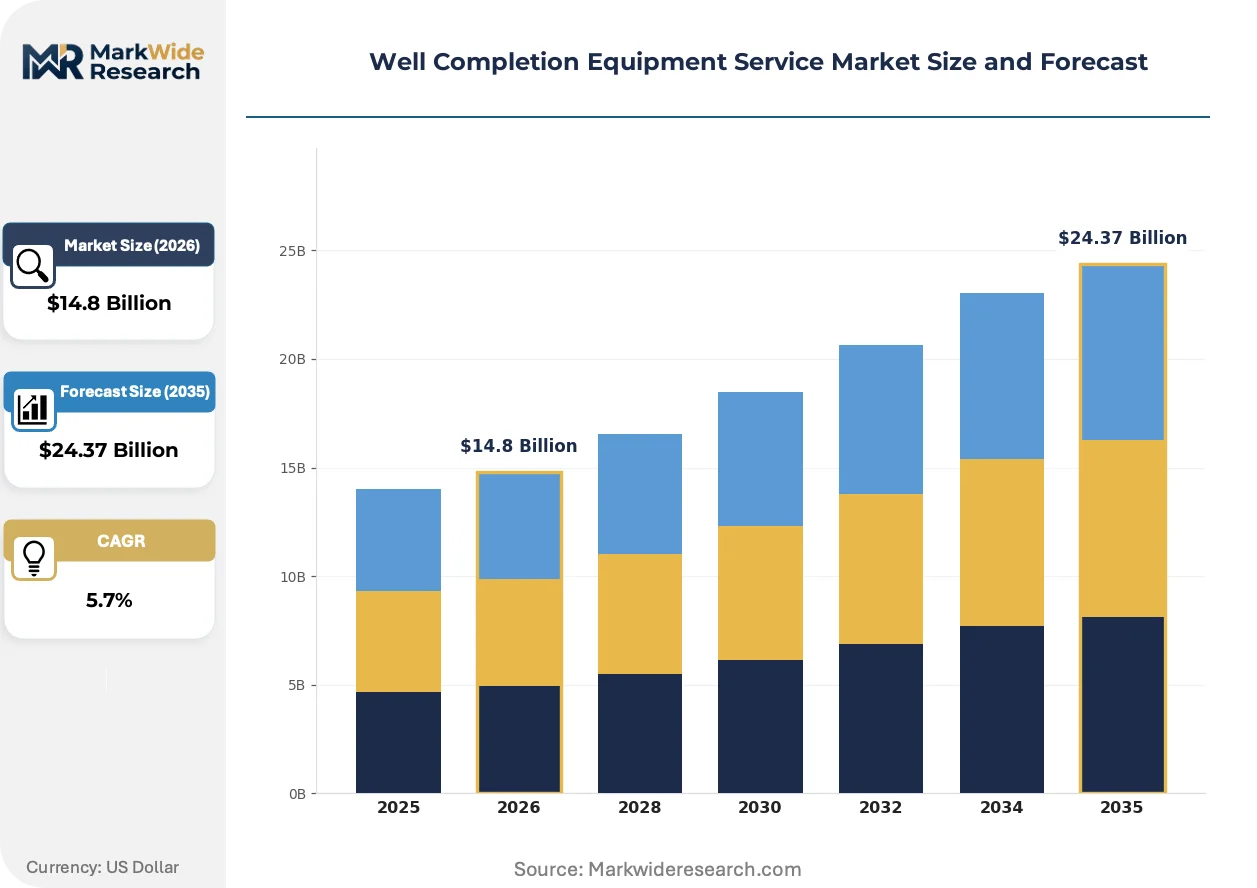
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Installation, Testing, Maintenance, Inspection, Decommissioning Application: Horizontal Wells, Vertical Wells, Offshore Wells, Unconventional Wells, Deepwater Wells Equipment Type: Packers, Tubing Hangers, Subsurface Safety Valves, Casing Accessories, Flow Control Devices End User: Exploration & Production Companies, Oilfield Service Companies, Drilling Contractors, Energy Operators |
| Companies Covered | Weatherford International PLC, Nabors Industries Ltd., Schlumberger Limited, FTS International, TechnipFMC plc, Halliburton Company, National Oilwell Varco, NCS Multistage Holdings Inc., Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Well Completion Equipment Service Market Strategic Shifts & Innovations
Digitalization of downhole diagnostics is compressing intervention cycles while metallurgical advances are extending equipment duty life in corrosive environments. These shifts are redrawing competitive advantage around data integration capabilities rather than pure hardware specification.
Intelligent completion systems with real-time zonal monitoring and autonomous choke control are migrating from deepwater showcase installations to land-based unconventional applications. Permian basin operators are piloting these systems to optimize drawdown management across stacked pay zones. The technology diffusion is compressing the premium that subsea-exclusive configurations previously commanded.
The US EPA's finalized methane emissions standards for new and modified oil and gas facilities are mandating continuous monitoring equipment at wellheads and compressor stations. Completion service contracts now increasingly bundle leak detection hardware installation with ongoing calibration and data reporting obligations. Gulf of Mexico operators are absorbing these compliance costs into front-end engineering budgets rather than treating them as discretionary add-ons.
Integrated service contracting is displacing discrete equipment procurement as the dominant commercial model for complex completions. National oil companies in Brazil and Nigeria are consolidating vendor lists around providers capable of delivering full-well lifecycle coverage from installation through abandonment. This concentration is visible in tender structures that penalize fragmented supply chains with interface risk premiums and schedule accountability gaps.
Well Completion Equipment Service Market Segmentation
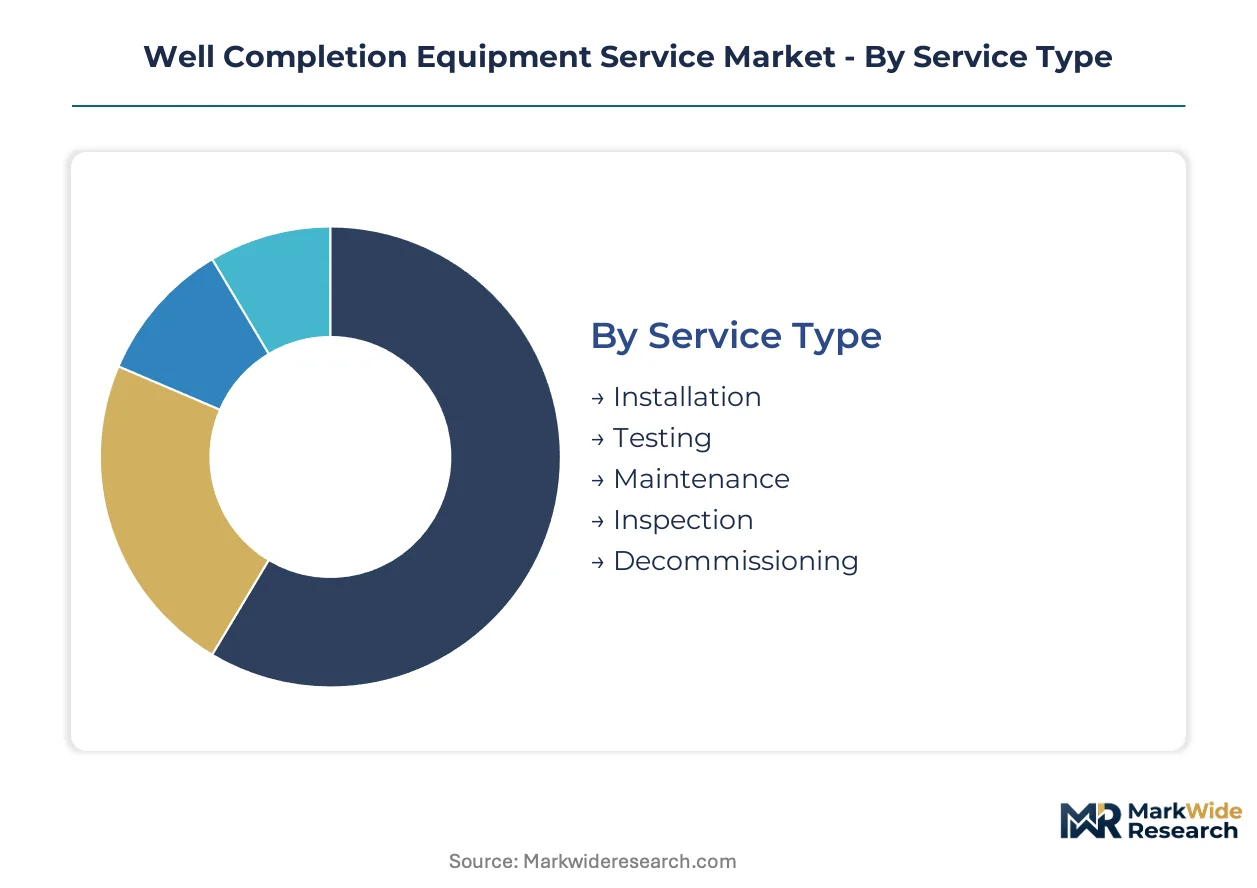
Service intensity varies dramatically across completion equipment categories, with aftermarket revenue multiples diverging based on equipment complexity and intervention accessibility. Understanding these segmentation boundaries clarifies where recurring contract value concentrates versus one-time installation economics.
Service Type:
After-sales service intensity climbs steeply from initial installation through sustained integrity management, reconfiguring margin pools toward multi-year contractual relationships.
- Installation:Capital-intensive mobilization of specialized crews and pressure testing equipment dominates current revenue allocation. Permian basin operators absorb premium day rates for simultaneous multi-well pad completions that compress surface footprint timelines.
- Testing:Hydrostatic and pneumatic validation protocols for subsea connectors demand certified third-party witnessing. Pre-salt developments off Brazil mandate post-installation pressure verification that extends revenue recognition windows.
- Maintenance:Scheduled overhaul of packer sealing elements and tubing hanger wear components generates recurring service contracts. Mature Gulf of Mexico fields require more frequent intervention cycles to sustain output.
- Inspection:Non-destructive evaluation of corrosion-resistant cladding using ultrasonic and electromagnetic methods addresses regulatory compliance obligations. EPA methane performance standards expand demand for seal integrity verification.
- Decommissioning:Well abandonment services including plug setting and conductor removal face accelerating demand as North Sea and Gulf of Mexico fields reach end-of-life.
Installation holds the largest share; momentum sits with maintenance as operators defer new well commitments.
Application:
Well architecture complexity directly scales service pricing power, with offshore configurations commanding multiples of land-based economics due to logistical constraints and non-productive time exposure.
- Horizontal Wells:Extended-reach laterals in unconventional basins require staged fracturing sleeve deployment and zonal isolation verification. Bakken operators accelerate re-stimulation schedules that pull packer redeployment demand.
- Deepwater Wells:Subsea completion architectures with subsea trees and tieback connectors concentrate procurement among integrated providers capable of full-well lifecycle coverage. Brazil's pre-salt developments mandate modular installation vessels with specialized pressure testing protocols.
- Vertical Wells:Conventional single-zone completions retain cost efficiency for conventional reservoir development. Legacy onshore fields in Texas and Louisiana convert to carbon sequestration, requiring recompletion with corrosion-resistant tubing.
- Offshore Wells:Platform-based completions face weather-dependent intervention windows that compress service revenue recognition. North Sea operators absorb premium logistics costs for helicopter-transported tooling.
- Unconventional Wells:Stacked pay zone development in Permian and Eagle Ford formations drives intelligent completion adoption with real-time zonal monitoring.
Horizontal wells dominate volume; deepwater applications capture the steepest expansion trajectory as subsea tieback activity accelerates.
Equipment Type:
Component metallurgical specifications determine aftermarket capture potential, with sour service ratings and high-pressure ratings extending replacement cycles while elevating per-intervention value.
- Packers:Mechanical and hydraulic sealing systems rated to 15,000 psi differential pressure anchor completion integrity. Chromium-molybdenum steel forgings for sour service applications face supply concentration from limited European and Japanese mill capacity.
- Tubing Hangers:Load-bearing interfaces between production tubing and wellhead assemblies require H2S-qualified metallurgy. Expandable liner hanger technology locks in follow-on intervention business through proprietary connection geometries.
- Subsurface Safety Valves:Downhole barrier devices mandated by US Bureau of Safety and Environmental Enforcement for Gulf of Mexico containment requirements. Hydraulic and electric-actuated configurations face integration challenges with legacy control umbilicals.
- Casing Accessories:Centralizers, float equipment, and stage tools support primary cementing operations. Standardized API specifications compress margin differentiation in this category.
- Flow Control Devices:Sliding sleeves and adjustable chokes enable zonal production management. Intelligent completion migration from subsea showcase installations to land-based unconventional applications compresses previous technology premiums.
Packers hold the largest share; momentum sits with flow control devices as digitalization enables autonomous reservoir management.
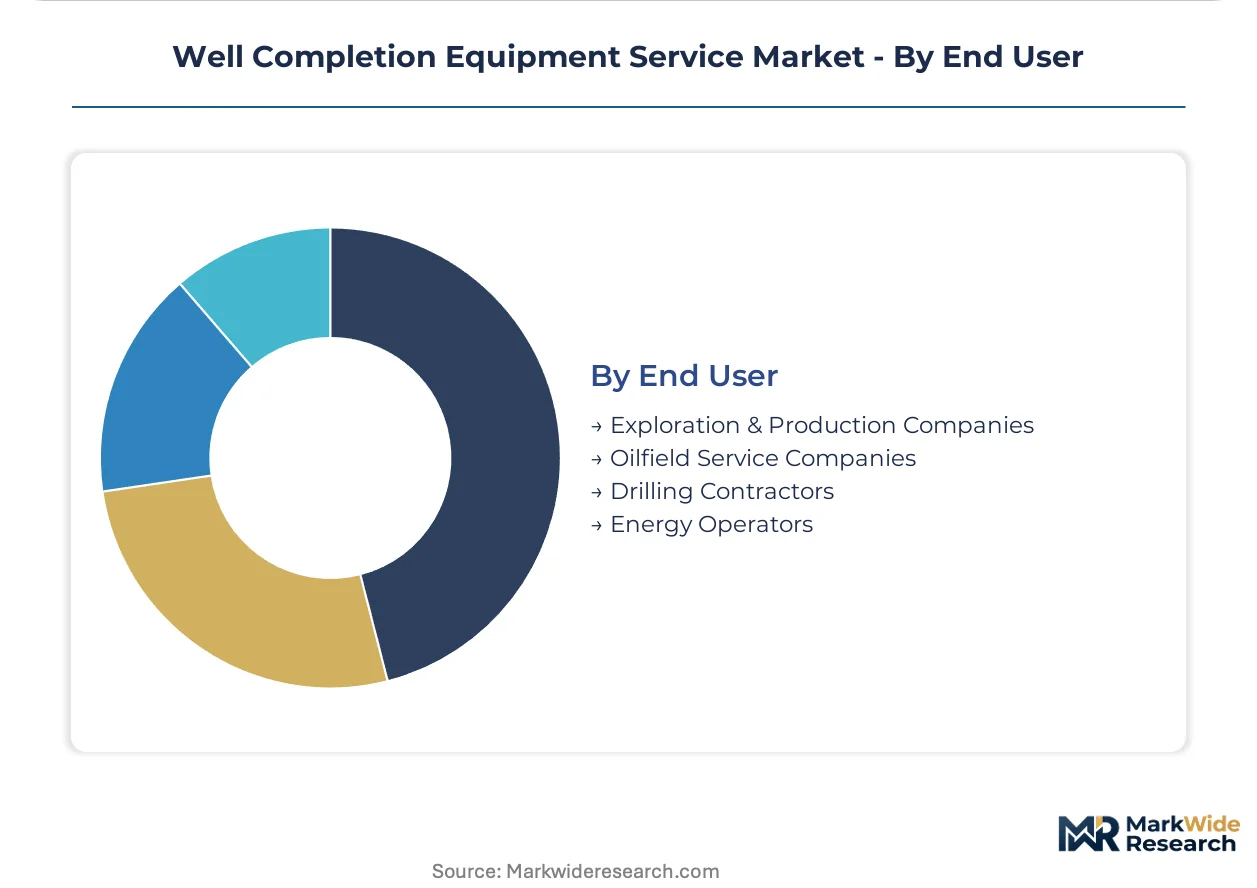
End User:
Procurement authority fragmentation across operator, service company, and drilling contractor boundaries shapes contract structure and pricing transparency.
- Exploration & Production Companies:Integrated operators with in-house engineering capabilities negotiate long-term service agreements with volume commitments. National oil companies in Nigeria consolidate vendor lists around full-well lifecycle coverage capabilities.
- Oilfield Service Companies:Equipment rental and integrated project management providers intermediate between manufacturers and field deployment. Predictive maintenance offerings for downhole equipment extend digital platform monetization.
- Drilling Contractors:Rig-based procurement of completion accessories during drilling-to-completion handover phases. Day-rate contracting structures limit capital equipment ownership in this segment.
- Energy Operators:Diversified utilities and independent power producers entering hydrocarbon production through acquisition. Carbon intensity disclosure obligations from EU CSRD redirect procurement criteria toward certified lower-carbon installation methodologies.
Exploration & Production companies hold the largest share; momentum sits with energy operators as non-traditional entrants reshape supplier qualification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in North American shale basins exhibit the highest price elasticity, squeezing service margins through competitive tendering, while deepwater operators off Brazil and West Africa absorb premium pricing due to non-productive time exposure and limited supplier alternatives.
United States
Permian and Bakken operators accelerate re-stimulation schedules that pull packer redeployment and tubing hanger replacement demand. The EPA's finalized methane emissions standards mandate continuous monitoring equipment at wellheads, expanding seal integrity verification obligations. Houston anchors the largest concentration of completion service headquarters and pressure testing facilities.
Brazil
Pre-salt developments mandate modular completion architectures requiring specialized installation vessels and post-installation pressure testing protocols. ANP regulatory frameworks enforce stringent subsea equipment qualification thresholds that compress the approved vendor list. The Campos Basin concentrates procurement authority among integrated providers capable of full-well lifecycle coverage.
Norway
North Sea decommissioning obligations accelerate well abandonment services including plug setting and conductor removal. The Norwegian Petroleum Directorate enforces stringent well integrity management requirements that sustain inspection contract demand. Stavanger clusters subsea engineering competence and intervention vessel operators serving mature field portfolios.
Saudi Arabia
Gas reservoir development programs drive demand for H2S-qualified tubing hangers and sour service packers. The Ministry of Energy's localization mandates redirect procurement toward joint ventures with domestic fabrication capacity. Dhahran concentrates Aramco's technical specification authority and supplier qualification oversight.
Australia
LNG export commitment maintenance sustains intervention scheduling across offshore Northwest Shelf assets. NOPSEMA well integrity regulations enforce subsea safety valve testing frequencies that generate recurring service contracts. Perth anchors regional procurement coordination for Timor Sea and Browse Basin developments.
Well Completion Equipment Service Market Key Industry Players
Capability concentration sits with integrated providers possessing full-well lifecycle coverage; scale advantage sits with diversified oilfield service conglomerates with global logistics networks. The supplier base compresses around three strategic archetypes: integrated turbomachinery-completion hybrids, proprietary technology specialists, and digital platform extenders. Dominant competitive moves include integrated service contracting displacing discrete equipment procurement, and predictive maintenance offerings monetizing sensor data integration.
Among US-based integrated providers, Baker Hughes Company and Halliburton Company exemplify the capability-scale hybrid archetype, while Weatherford International PLC occupies a specialist position anchored by proprietary expandable liner hanger technology. These three entities represent divergent strategic postures within a market tilting toward recurring integrity management contracts and long-term service agreements.
| Leading Market Players |
|---|
| Weatherford International PLC |
| Nabors Industries Ltd. |
| Schlumberger Limited |
| FTS International |
| TechnipFMC plc |
| Halliburton Company |
| National Oilwell Varco |
| NCS Multistage Holdings Inc. |
| Baker Hughes Company |
| Others |
Cost & Logistics Intelligence
Overcapacity in North American pressure pumping spreads is compressing day-rate realizations while simultaneously forcing equipment suppliers toward extended payment terms to preserve offtake volumes. This utilization-driven tension reshapes both procurement postures and margin structures across the completion service value chain.
Pricing Analysis
After-sales service tiers anchored by multi-year integrity management contracts now drive lifetime value capture more than initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and geographic delivery complexity. Pricing pressure stems from Permian basin operators squeezing margins through competitive tendering for pad-completion packages. Exploration and production companies exhibit the highest price elasticity, while deepwater operators off Brazil absorb premium pricing due to non-productive time exposure and limited supplier alternatives.
Supply Chain Analysis
Supplier-financing facilities with extended payment terms to 180 days have become standard for chromium-molybdenum steel forgings sourced from Japan, Germany, and Austria. Manufacturing concentration for sour-service packer metallurgy rests on limited European and Japanese mill capacity, with specialized alloy supply vulnerable to geopolitical friction. Distribution runs through Houston-based pressure testing facilities and regional service yards in Midland, Stavanger, and Singapore. Single-source vulnerability for Inconel cladding feedstock represents the dominant structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intelligent completion systems and EPA methane monitoring mandates are disrupting traditional equipment-only procurement, creating openings for integrated service providers with digital platforms and emissions-verification capabilities.
For Market Incumbents: Harden API Q1 and ISO 13628-4 certification portfolios to disqualify uncertified competitors from tender participation. Deepen backward integration into chromium-molybdenum forging supply through offtake agreements with Japanese mills. Lock in recurring revenue through predictive maintenance offerings that monetize real-time downhole sensor data.
For New Entrants and Emerging Players: CCUS well repurposing in Texas and Louisiana represents the most penetrable entry point, with depleted reservoirs requiring corrosion-resistant tubing and annular monitoring systems. Target inspection and maintenance categories in mature Gulf of Mexico fields where intervention frequency is accelerating. Pursue partnerships with established intervention vessel operators to overcome capital barriers to deepwater aftermarket capture.
For Investors and Strategic Acquirers: Capital is best deployed toward proprietary technology specialists with expandable liner hanger or autonomous flow control intellectual property. Long-term viability favors providers capable of full-well lifecycle coverage from installation through abandonment. Monitor EPA enforcement patterns on methane performance standards as the signal for accelerated procurement of seal integrity monitoring services.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contracting | Consolidates vendor lists around full-well lifecycle coverage capabilities in Brazil and Nigeria. |
| Predictive Maintenance Platform | Monetizes Baker Hughes and Halliburton digital wellbore construction platforms through sensor data integration. |
| CCUS Recompletion Capability | Captures carbon sequestration conversion demand in Texas and Louisiana depleted reservoirs. |
| Specialized Alloy Supply Security | Mitigates geopolitical exposure in chromium-molybdenum forgings from European and Japanese mills. |
| Methane Monitoring Compliance Bundle | Addresses EPA finalized standards through leak detection hardware installation with ongoing calibration obligations. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with completion engineering directors, subsea project managers, procurement leads at national oil companies, and aftermarket service heads; and secondary validation through API specification documentation, BSEE regulatory filings, ANP qualification registries, and operator tender disclosures. Bottom-up equipment shipment tallies and top-down service revenue estimates were triangulated against pressure pumping fleet utilization data and subsea tree installation records.
Forecast inputs span service type, application architecture, equipment metallurgical specification, and end-user procurement authority across the analysis window. Segmentation dimensions modeled include installation versus maintenance revenue mix, onshore versus offshore well complexity, and integrated versus discrete contracting structures. CAGRs were derived from equipment replacement cycle analysis and intervention frequency trends in mature basins. Subsea tieback project pipelines and refrac intensity schedules in Permian and Bakken formations anchored volume projections.
Macroeconomic conditions sit as an overlay; deviation in crude price realizations, floating rig day rates, or specialty steel alloy costs would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement continuity and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Swell Packers Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Asia-Pacific Underground Coal Gasification Market
Oil & Gas
Wired Drill Pipe Sales Market
Oil & Gas
Asia-Pacific Oil Country Tubular Goods Market
Oil & Gas
South America Oil and Gas Hoses and Coupling Market
Oil & Gas
Russia Drill Pipe Market
Oil & Gas
Southeast Asia Oil and Gas Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Mexico Wireline Services Market
Oil & Gas
Integrated Gas System Market