
 Underreamers Market | 2026-2036
Underreamers Market Size, Share, and Industry Trends Forecast 2026-2036
Underreamers Market Analytics
API Specification Q2 is rotating the competitive landscape by mandating quality management systems for downhole tool suppliers. Baker Hughes Company leverages its integrated drilling systems portfolio to sustain service contracts across deepwater markets. Schlumberger Limited anchors its position through proprietary expandable blade designs that dominate high-pressure wellbore applications. DRILLSTAR competes on manufacturing agility, offering rapid customization for specialty underreamer configurations in European basins.
Underreamers are mechanical downhole tools engineered to enlarge a pilot bore beyond the drill bit diameter, typically achieving expansion ratios of 1.5 to 3 times initial hole size through hydraulically or mechanically actuated blade deployment. These tools serve the primary purpose of creating adequate annular clearance for casing cementing operations in oil, gas, and geothermal wells. Fixed blade underreamers occupy mature onshore segments where standardization drives cost efficiency, while expandable blade systems capture margin pools in offshore deployments demanding precise diameter control. Retractable blade configurations lead growth in horizontal shale wells where trip-out risks necessitate tool retrieval through narrow casing IDs.
API standards, NORSOK D-002, and BSEE well control regulations collectively govern tool qualification, material traceability, and operational safety protocols across US and North Sea jurisdictions. The US EPA and OSHA frameworks further shape onshore deployment through emissions controls and worker safety mandates that influence tool selection and maintenance cycles. Stakeholders must monitor evolving certification requirements and blade material innovations to align procurement with increasingly stringent well integrity standards.
Market Dynamics
Deepwater operators are consolidating procurement around API Q2-certified suppliers, compressing vendor qualification timelines from 18 months to 9 months and forcing mid-tier manufacturers to absorb certification costs or exit high-margin offshore contracts.
Growth Catalysts
- Shale casing programs:Horizontal well designs in the US Gulf Coast require precision bore enlargement for cementing integrity, pulling demand for retractable blade systems that navigate narrow casing IDs.
- API Q2 mandates:Quality management system requirements are filtering supplier pools across North America, rewarding pre-certified incumbents with accelerated contract awards.
- Geothermal expansion:High-temperature well construction in volcanic basins is creating specifications for nickel-alloy blade materials that withstand thermal cycling beyond hydrocarbon applications.
Market Restraints
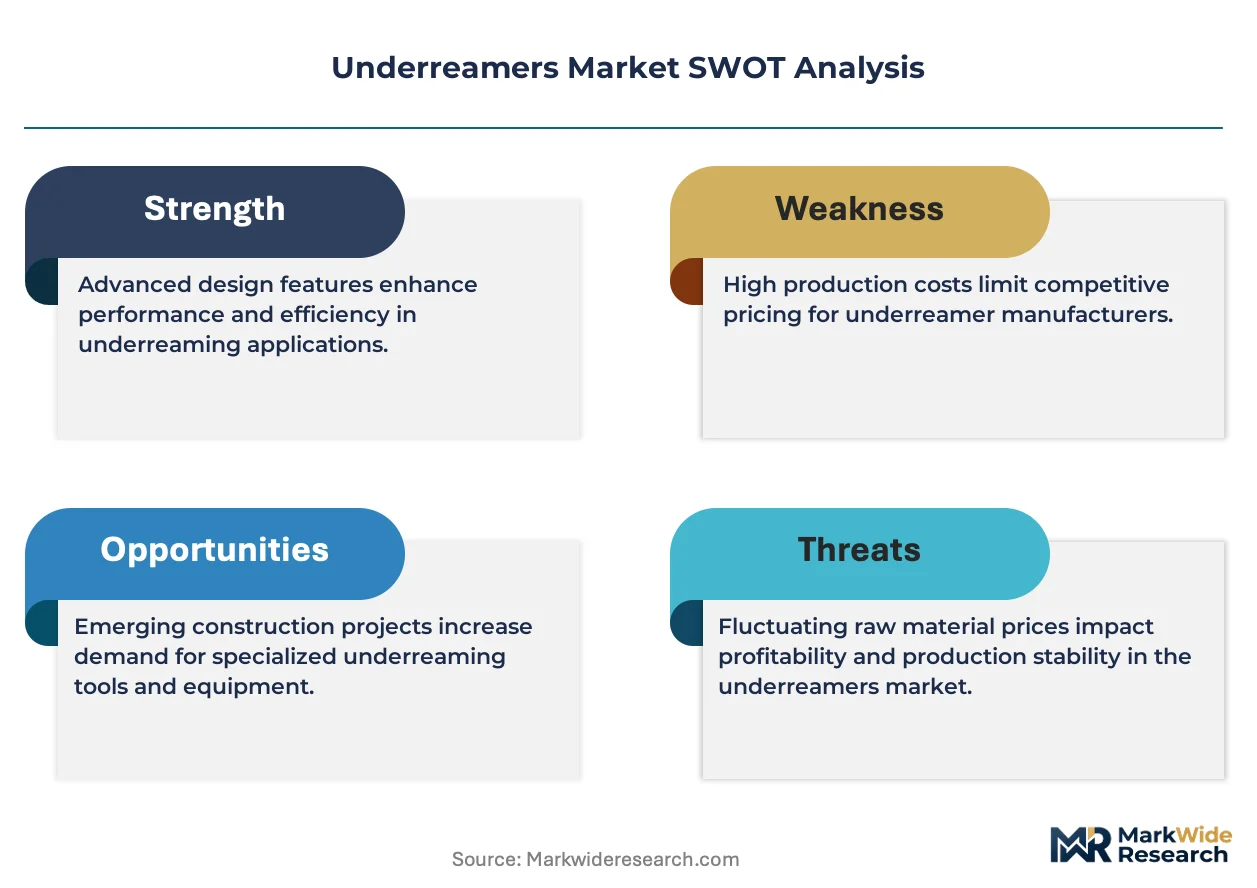
- Superalloy cost volatility:Inconel and tungsten carbide prices fluctuate with aerospace demand, squeezing margin on premium expandable systems.
- Supplier concentration:Forged cutter blocks rely on a narrow base of Pennsylvania and Ohio machine shops, creating single-source vulnerability for North American tool assemblers.
- Fixed blade commoditization:Mature onshore segments face pricing pressure from Chinese imports meeting basic API specifications without premium metallurgy.
Strategic Opportunities
- Brazil pre-salt basins:Petrobras drilling campaigns off Rio de Janeiro lack qualified local underreamer service capacity, opening import substitution partnerships for certified foreign suppliers.
- Carbon capture wells:CO2 injection formations require corrosion-resistant blade coatings, extending tool life in acidic environments beyond conventional hydrocarbon service.
- Digital blade monitoring:Real-time wear sensors integrated with rig automation systems enable predictive replacement, creating subscription revenue streams alongside hardware sales.
Industry Challenges
- API Q2 audit compression:Certification bodies face 6-month backlogs, delaying new product launches and freezing R&D budgets for unqualified applicants.
- Blade actuation integration:Hydraulic deployment mechanisms must interface with proprietary rig control systems, requiring custom engineering for each major drilling contractor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underreamers Market |
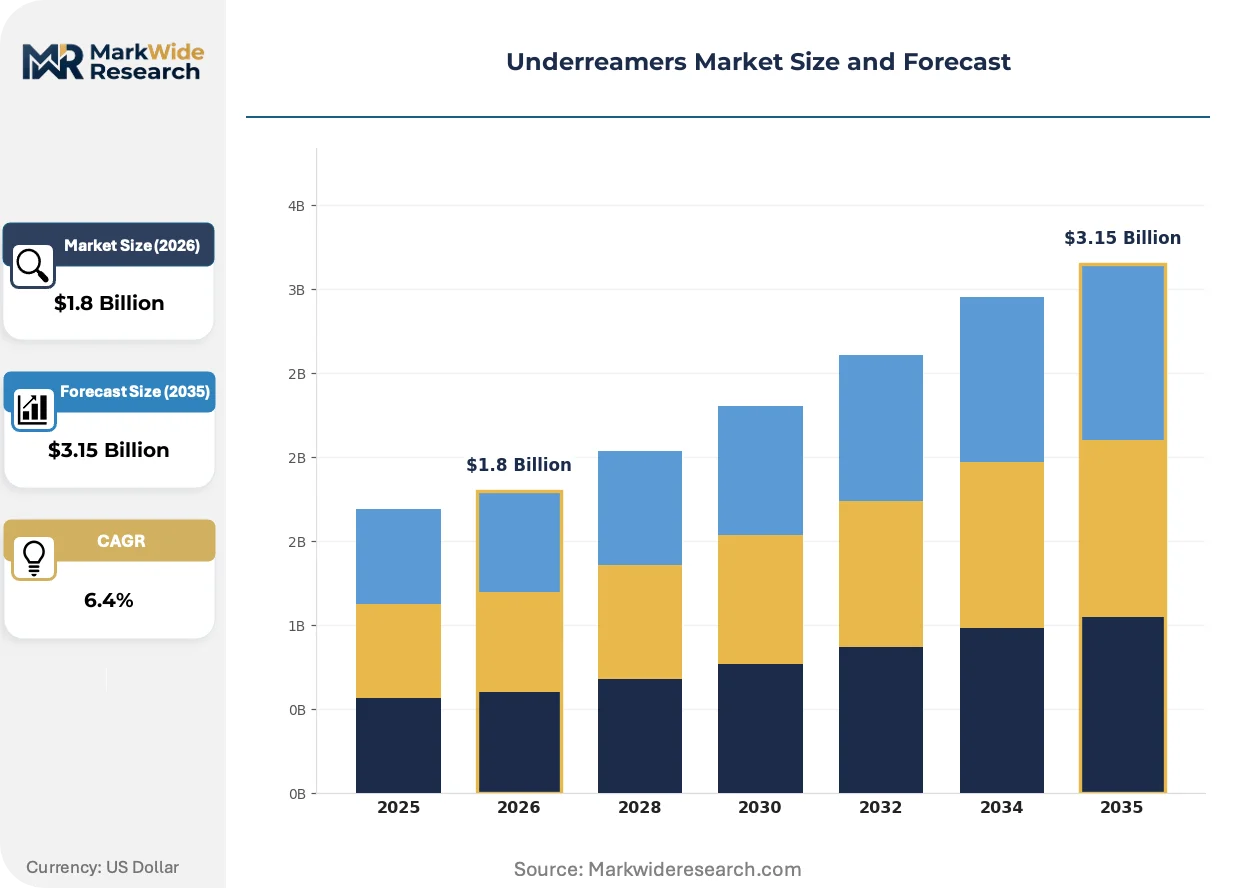
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Blade, Retractable Blade, Expandable Blade, Specialty Material: Steel, Carbide, Composite, Alloy End User: Oil & Gas, Mining, Construction, Water Well Deployment: Onshore, Offshore, Underground, Surface |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Weatherford International plc, NOV Inc., DRILLSTAR, Guizhou Gaofeng Petroleum Machinery, Tenaris S.A., Expro Group Holdings N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underreamers Market Evolving Landscape
Material science advances and regulatory tightening are converging to redefine tool performance specifications, with blade metallurgy and certification protocols emerging as primary axes of supplier differentiation.
Polycrystalline diamond compact cutters with thermally stable diamond grades are displacing conventional tungsten carbide inserts in high-abrasion formations. Operators in the Permian Basin and Bakken are specifying these cutters for 30% longer run intervals between trips. The shift is compressing aftermarket revenue for resharpening services while rewarding integrated cutter manufacturers.
BSEE well control regulations now mandate redundant blade retraction verification for subsea deployments, adding engineering validation cycles before tool qualification. Offshore contractors in the Gulf of Mexico are absorbing these compliance costs through day-rate premiums rather than capital expenditure. The rule is accelerating consolidation among subsea-focused tool shops that maintain dedicated BSEE liaison engineers.
Integrated drilling contractors are unbundling underreamer procurement from directional drilling service packages, creating direct vendor relationships previously intermediated by major service companies. Independent operators in the Eagle Ford and DJ Basin are leveraging this shift to negotiate blade specifications matched to specific formation hardness profiles. The disintermediation is most advanced in Texas and Colorado, where operator engineering staffs retain downhole tool expertise absent in larger integrated programs.
Underreamers Market Segmentation
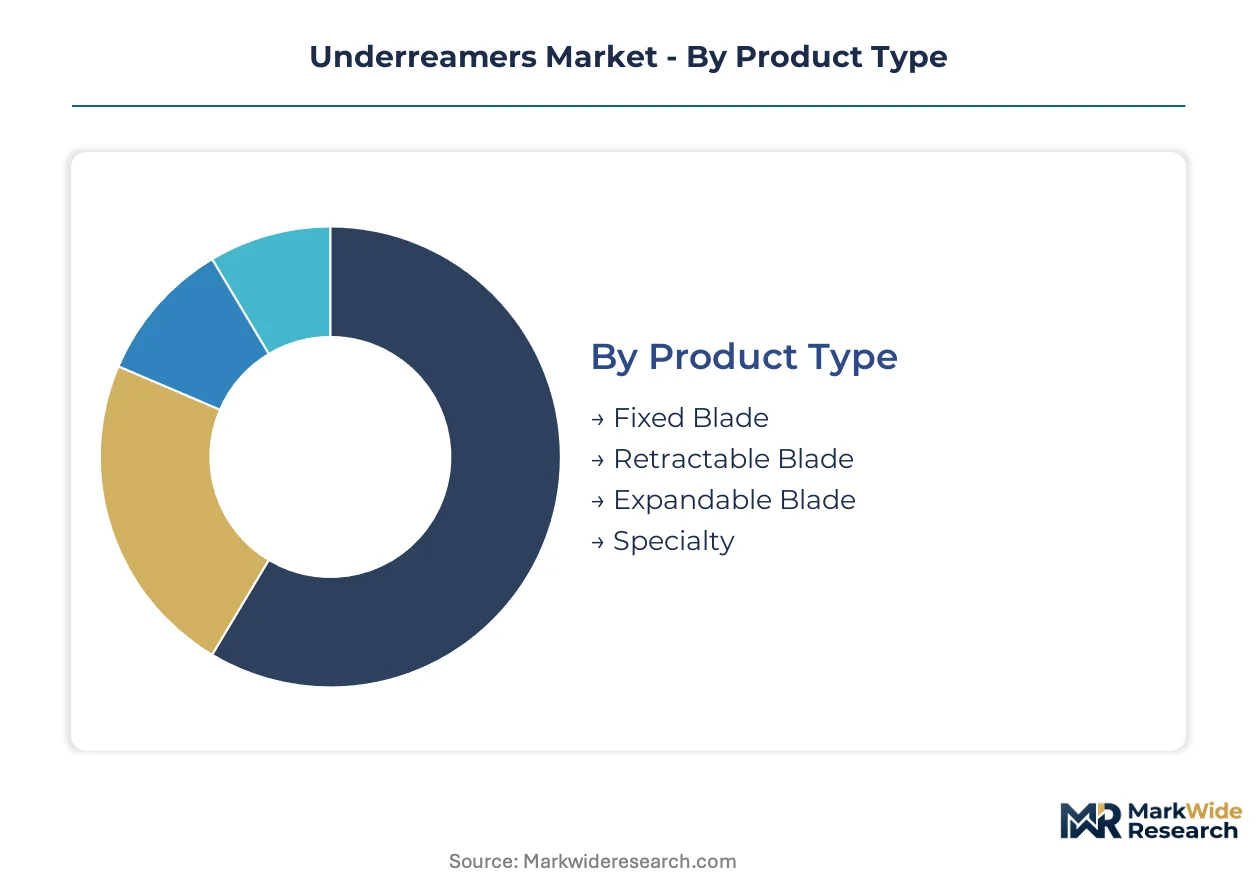
Underreamer procurement decisions hinge on formation hardness, well architecture, and regulatory jurisdiction. Each segmentation axis reveals distinct margin pools and supplier qualification barriers that reshape competitive positioning across drilling basins.
Product Type:
Expandable blade systems command the widest margin spreads in this category, driven by subsea certification requirements and precision diameter control.
- Expandable Blade:Hydraulically actuated cutter blocks deploy radially to achieve expansion ratios of 1.5 to 3 times pilot bore diameter. Gulf of Mexico operators specify these for high-pressure wellbore applications where trip-out risks demand reliable retraction mechanisms.
- Retractable Blade:Mechanically collapsible designs navigate narrow casing IDs in horizontal shale wells. US Gulf Coast casing programs pull demand for systems that maintain cementing integrity through precision bore enlargement.
- Fixed Blade:Standardized welded cutter configurations dominate mature onshore markets.
- Specialty:Custom-engineered geometries address geothermal thermal cycling and corrosive CO2 injection environments.
The dominant share belongs to expandable blade systems, while retractable blade configurations are closing the gap fastest in unconventional basins.
Material:
Material selection determines run interval economics, with superalloy grades capturing premium pricing in high-temperature deployments.
- Carbide:Tungsten carbide inserts and polycrystalline diamond compact cutters deliver abrasion resistance in Permian Basin and Bakken formations. Operators specify thermally stable diamond grades for 30% longer intervals between trips.
- Alloy:Nickel-based superalloys withstand thermal cycling beyond 300°C in volcanic geothermal basins. Inconel blade substrates command aerospace-linked pricing volatility that squeezes margin on premium expandable systems.
- Steel:Standard alloy substrates serve cost-sensitive onshore applications.
- Composite:Polymer-matrix cutters reduce weight for coiled tubing deployment.
Carbide retains volume leadership across hydrocarbon applications, though alloy grades are expanding most quickly in geothermal and carbon capture well construction.
End User:
Oil and gas operators concentrate procurement spending, while emerging verticals reshape specification requirements.
- Oil & Gas:Integrated majors and independents drive specification standards through API Q2 certification mandates. Deepwater contractors in Brazil pre-salt basins lack qualified local service capacity, opening import substitution opportunities.
- Mining:Raise bore drilling and shaft enlargement applications demand robust cutter retention in abrasive hard rock. Australian and Canadian mineral extraction operators specify reinforced blade anchors for extended run hours.
- Construction:Foundation drilling and tunnel boring applications utilize modified underreamer geometries for civil infrastructure.
- Water Well:Aquifer development programs in arid regions employ simplified fixed blade designs.
Oil and gas maintains the dominant procurement volume, with mining applications climbing the fastest as mineral extraction depths increase.
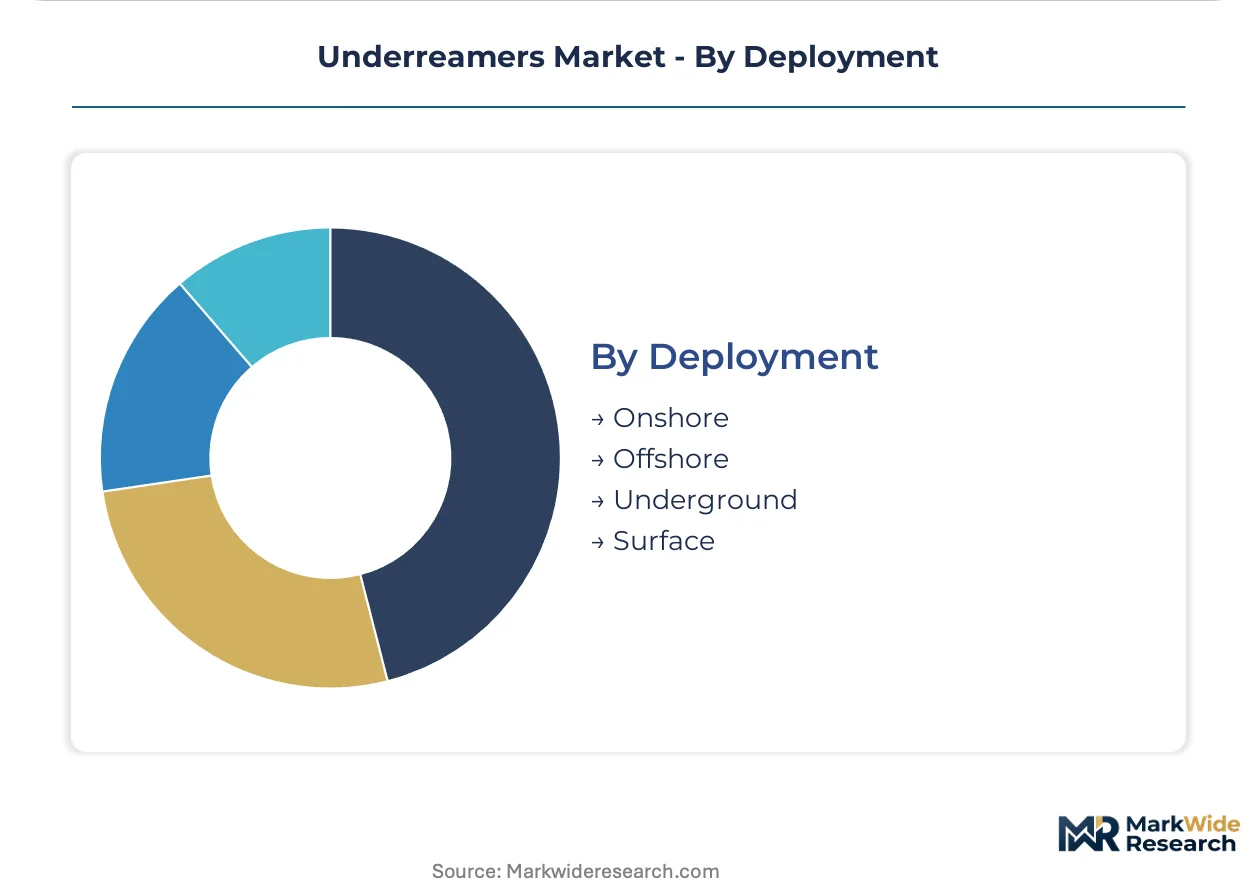
Deployment:
Offshore qualification barriers protect margin pools, while onshore commoditization pressures reshape supplier economics.
- Offshore:Subsea deployments require BSEE-mandated redundant blade retraction verification and API Q2 quality management certification. Gulf of Mexico contractors absorb compliance costs through day-rate premiums rather than capital expenditure.
- Onshore:US shale basins and Middle East conventional fields drive volume procurement of standardized systems. Chinese imports meeting basic API specifications without premium metallurgy exert pricing pressure on fixed blade segments.
- Underground:Deep mining and geothermal applications specify corrosion-resistant coatings.
- Surface:Water well and shallow construction programs utilize entry-grade tool configurations.
Offshore deployments capture the highest margin per tool, though onshore unconventional basins are gaining share fastest through horizontal well proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated drilling contractors and shale independents concentrate procurement spending in the United States Gulf Coast, while deepwater operators in Brazil and Norway drive premium-tier demand for certified subsea systems. National oil companies in the Middle East and state-backed geothermal developers in East Africa are expanding specification requirements beyond traditional hydrocarbon applications.
United States
Horizontal shale wells in the Permian Basin and Eagle Ford require retractable blade systems for precision bore enlargement through narrow casing IDs. OSHA and EPA frameworks mandate emissions controls and worker safety protocols that influence tool maintenance cycles. Houston anchors the largest cluster of API Q2-certified service providers, with Oklahoma City and Midland serving as secondary procurement hubs for independent operators.
Brazil
Petrobras drilling campaigns in the pre-salt basins off Rio de Janeiro lack qualified local underreamer service capacity, creating import substitution opportunities for certified foreign suppliers. ANP regulatory requirements align with BSEE-equivalent well control standards for subsea deployments. Macaé and Rio de Janeiro host the primary offshore service infrastructure, though blade refurbishment capabilities remain underdeveloped relative to demand scale.
Norway
Equinor and Aker BP operations in the North Sea specify NORSOK D-002 compliant tools with redundant blade retraction verification for high-pressure wellbore applications. PSA Norway enforces stricter material traceability requirements than baseline API standards. Stavanger and Bergen concentrate subsea engineering expertise, with local machine shops specializing in forged cutter blocks for premium expandable systems.
Saudi Arabia
Saudi Aramco unconventional gas programs in the Jafurah Basin are adopting expandable blade configurations previously deployed only in offshore contexts. SASO and national oil company technical specifications mandate quality management system certification aligned with API Q2. Dhahran and Jubail Industrial City host the primary manufacturing and service infrastructure, with emerging demand from NEOM geothermal exploration projects.
China
Sinopec and CNOOC deepwater campaigns in the South China Sea are accelerating procurement of hydraulically actuated systems for high-pressure formations. GB standards and MIIT regulations govern domestic tool qualification, though offshore operators increasingly specify dual-certified equipment meeting both API and NORSOK protocols. Shenzhen and Tianjin anchor manufacturing clusters, with Dalian emerging as a service hub for Bohai Bay operations.
Underreamers Market Competitive Landscape
Player mix skews toward integrated oilfield service conglomerates with captive manufacturing and certification infrastructure, compressing mid-tier vendor access to premium offshore contracts. Three archetypes dominate: full-service drilling contractors bundling underreamers within integrated service packages; specialized tool manufacturers competing on blade customization and rapid turnaround; and state-affiliated fabricators serving protected domestic markets. Consolidation through API Q2 certification absorption and strategic partnerships with forged cutter block suppliers represent the dominant competitive vectors.
Among Houston-based integrated service providers, Baker Hughes Company, Schlumberger Limited, and Halliburton Company exemplify the full-service archetype through their embedded quality management systems and established BSEE liaison capabilities. DRILLSTAR occupies a position within the specialized manufacturer tier, while Guizhou Gaofeng Petroleum Machinery represents state-affiliated fabrication capacity serving Asia-Pacific markets. These anchors illustrate how certification pre-qualification and geographic proximity to drilling basins stratify competitive access.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International plc |
| NOV Inc. |
| DRILLSTAR |
| Guizhou Gaofeng Petroleum Machinery |
| Tenaris S.A. |
| Expro Group Holdings N.V. |
| Others |
Value Network & Pricing Analysis
Polycrystalline diamond compact cutters displacing tungsten carbide inserts in Permian Basin and Bakken formations simultaneously redraws procurement geography toward integrated cutter manufacturers and compresses aftermarket resharpening revenue, forcing pricing power upstream into captive production networks.
Pricing Analysis
Cost-plus contracts with Inconel and tungsten carbide indexation dominate premium expandable blade procurement, tying day-rate premiums to aerospace-linked metal exchanges. Three-tier pricing structure across API Q2-certified premium, standard alloy, and economy fixed blade levels separates Gulf of Mexico operators from Chinese import buyers. Pricing pressure stems from fixed blade commoditization as basic API-specification imports erode margin in mature onshore segments. Independent shale operators in Texas and Colorado exhibit highest price sensitivity through unbundled procurement, while Petrobras pre-salt contractors absorb compliance premiums with least negotiation leverage.
Supply Chain Analysis
Pennsylvania and Ohio machine shops anchor forged cutter block fabrication for North American tool assemblers, while Shenzhen and Tianjin manufacturing clusters supply hydraulically actuated systems to Asia-Pacific offshore campaigns. Superalloy feedstock draws from aerospace and defense allocation pools, with nickel-based substrates tethered to thermal cycling specifications beyond hydrocarbon applications. Single-source vulnerability concentrates in Pennsylvania-Ohio cutter block forging capacity, creating chokepoint exposure for premium expandable system production. Distribution runs through Houston-anchored API Q2-certified service providers, with direct vendor relationships proliferating in Texas and Colorado independent operator markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified blade metallurgy and certification infrastructure constitute the binding constraint, with API Q2 audit backlogs and BSEE liaison engineering capacity creating scarcity premiums for pre-qualified incumbents.
For Market Incumbents: Shield offshore margin pools by embedding BSEE liaison engineers within subsea-focused tool shops, accelerating consolidation of forged cutter block suppliers in Pennsylvania and Ohio to eliminate single-source vulnerability. Absorb mid-tier manufacturers facing 18-month to 9-month qualification timeline compression to capture their R&D budgets and freeze unqualified competitor access.
For New Entrants and Emerging Players: Differentiate on rapid customization for specialty underreamer configurations in European geothermal basins and Brazilian pre-salt import substitution partnerships where certified local capacity remains underdeveloped. Target mining raise bore applications in Australia and Canada as the most penetrable vertical, leveraging reinforced blade anchor specifications absent in oil and gas procurement standards.
For Investors and Strategic Acquirers: The market sits at a certification-consolidation phase that favors vertically integrated manufacturers with captive API Q2 infrastructure and aerospace-superalloy supply relationships. Five-to-ten year viability hinges on carbon capture well corrosion-resistant coating capabilities and digital blade monitoring subscription revenue attachment. Watch for inflection when BSEE backlog clearance accelerates new product launch velocity among previously frozen R&D budgets.
| Strategic Initiative | Industry Significance |
|---|---|
| API Q2 Certification Acceleration | Compresses vendor qualification timelines from 18 months to 9 months, freezing mid-tier competitor access to Gulf of Mexico contracts. |
| Backward Integration into Forged Cutter Blocks | Eliminates Pennsylvania-Ohio machine shop single-source vulnerability for premium expandable system production. |
| Digital Blade Monitoring Platform Launch | Creates predictive replacement subscription revenue alongside hardware sales through rig automation integration. |
| Geothermal Specialty Alloy Development | Captures nickel-alloy specifications for volcanic basin thermal cycling beyond conventional hydrocarbon service. |
| Brazil Pre-salt Import Substitution Partnership | Addresses Petrobras drilling campaign demand where qualified local underreamer service capacity remains underdeveloped. |
Research Methodology
Desk research of API specification documents, BSEE well control regulations, NORSOK D-002 standards, and SEC filings from integrated oilfield service providers preceded structured interviews with drilling engineering directors, procurement managers at shale independents, subsea tool shop quality managers, and aftermarket service heads. Primary fieldwork with Houston-anchored API Q2-certified service providers and Stavanger subsea engineering clusters combined with trade data from oilfield equipment customs records and aerospace superalloy pricing indices. Bottom-up well count projections across Permian Basin, Eagle Ford, and Gulf of Mexico basins triangulated against top-down expenditure forecasts from national oil company capital programs.
Variance decomposition across product type, material grade, deployment environment, and end-user vertical dimensions structured the analytical framework throughout the projection horizon. Modeled CAGRs emerged from rig activity trajectories, blade replacement intervals, and certification penetration curves rather than extrapolated historical trends. Forecast inputs incorporated geothermal well construction specifications, carbon capture injection formation chemistry, and polycrystalline diamond compact cutter displacement rates in high-abrasion formations.
Material uncertainties — API Q2 audit body backlog resolution, Inconel price volatility from aerospace demand swings, and BSEE regulatory amendments to blade retraction verification — sit outside the modeled envelope. Forecasts reflect assumptions on certification timeline compression and superalloy supply allocation stability. Recalibration cycles align with material shifts in deepwater rig contracting activity and geothermal exploration permit issuance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Nigeria Oil and Gas Upstream Market
Oil & Gas
Well Casing Market
Oil & Gas
Brazil Wireline Logging Services Market
Oil & Gas
Central Asia Oil and Gas Market
Oil & Gas
Europe Seismic Survey Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
Vacuum Gas Oil Market
Oil & Gas
Managed Pressure Drilling Services Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
Global Fracking Fluids and Chemicals Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
United States Coiled Tubing Market
Oil & Gas
Oil and Gas Logistics Market
Oil & Gas
Pumpjack Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Egypt Natural Gas Market