
 Europe Hydraulic Fracturing Market | 2026-2036
Europe Hydraulic Fracturing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hydraulic Fracturing Market Foresight
Shale gas extraction is pivoting toward tighter reservoir formations across the North Sea rim. Halliburton leverages its pressure-pumping technology leadership to anchor deepwater fracturing campaigns in Norwegian waters. Schlumberger competes through integrated well-construction platforms that sustain complex offshore completions. Baker Hughes differentiates via digital fracturing systems that optimize proppant placement in high-stress geologies.
Hydraulic fracturing injects pressurized fluid—typically water with chemical additives and proppant—into subsurface rock formations to create conductive fractures that release hydrocarbons. Operating pressures routinely exceed 10,000 psi, with fluid viscosity controlled through cross-linked gel polymers or slickwater chemistry depending on formation permeability. Water-based technology dominates mature onshore applications where cost efficiency matters, while gel-based systems command premium positioning in high-temperature offshore wells where fracture complexity demands superior proppant suspension. Tight oil applications attract the fastest-growing investment as operators target low-permeability carbonate reservoirs in the Barents Sea region.
EU Green Deal methane regulations and REACH chemical disclosure requirements shape fracturing fluid formulations across European jurisdictions. Norway's Petroleum Safety Authority and the UK Environment Agency enforce divergent well-integrity standards that fragment equipment certification pathways. Stakeholders must monitor regulatory divergence between EU member states and non-EU North Sea producers when scaling cross-border service platforms.
Market Dynamics
EU Green Deal methane regulations are forcing a structural recalibration of fracturing fluid chemistry and well-integrity protocols across North Sea jurisdictions, creating divergent compliance cost burdens between EU member states and non-EU producers.
Growth Catalysts
- Unconventional tight gas formations:Low-permeability carbonate reservoirs in the Barents Sea region attract specialized hydraulic fracturing investment as conventional reserves deplete.
- EU Green Deal framework:Methane emission reduction mandates accelerate deployment of leak-detection technologies and closed-loop fluid systems in offshore completions.
- Norwegian offshore licensing:The country's 25th licensing round opened frontier blocks in the Norwegian Sea, stimulating demand for high-pressure deepwater fracturing services.
Market Restraints
- REACH chemical disclosure:ECHA registration requirements for fracturing fluid additives extend formulation development timelines and increase compliance expenditure.
- Proppant supply concentration:Ceramic proppant manufacturing clusters in Germany and Poland face energy cost volatility that transmits into service pricing.
- Formation damage limitations:Clay swelling in North Sea shales restricts water-based fluid applicability, forcing costlier gel-based chemistry adoption.
Strategic Opportunities
- United Kingdom shale revival:Onshore tight gas licensing moratoriums have lifted in England, opening previously suspended exploration acreage to fracturing services.
- Digital twin integration:Real-time fracture propagation modeling is converging with automated pressure control to reduce non-productive time in complex completions.
- CSRD sustainability reporting:Corporate disclosure mandates create service differentiation value for operators demonstrating methane intensity reductions.
Industry Challenges
- Pressure control engineering talent:Specialized expertise in high-temperature high-pressure well design remains concentrated among aging workforce cohorts in Aberdeen and Stavanger.
- Cross-border equipment certification:Divergent well-integrity standards between Norway's Petroleum Safety Authority and the UK Environment Agency fragment asset mobility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hydraulic Fracturing Market |
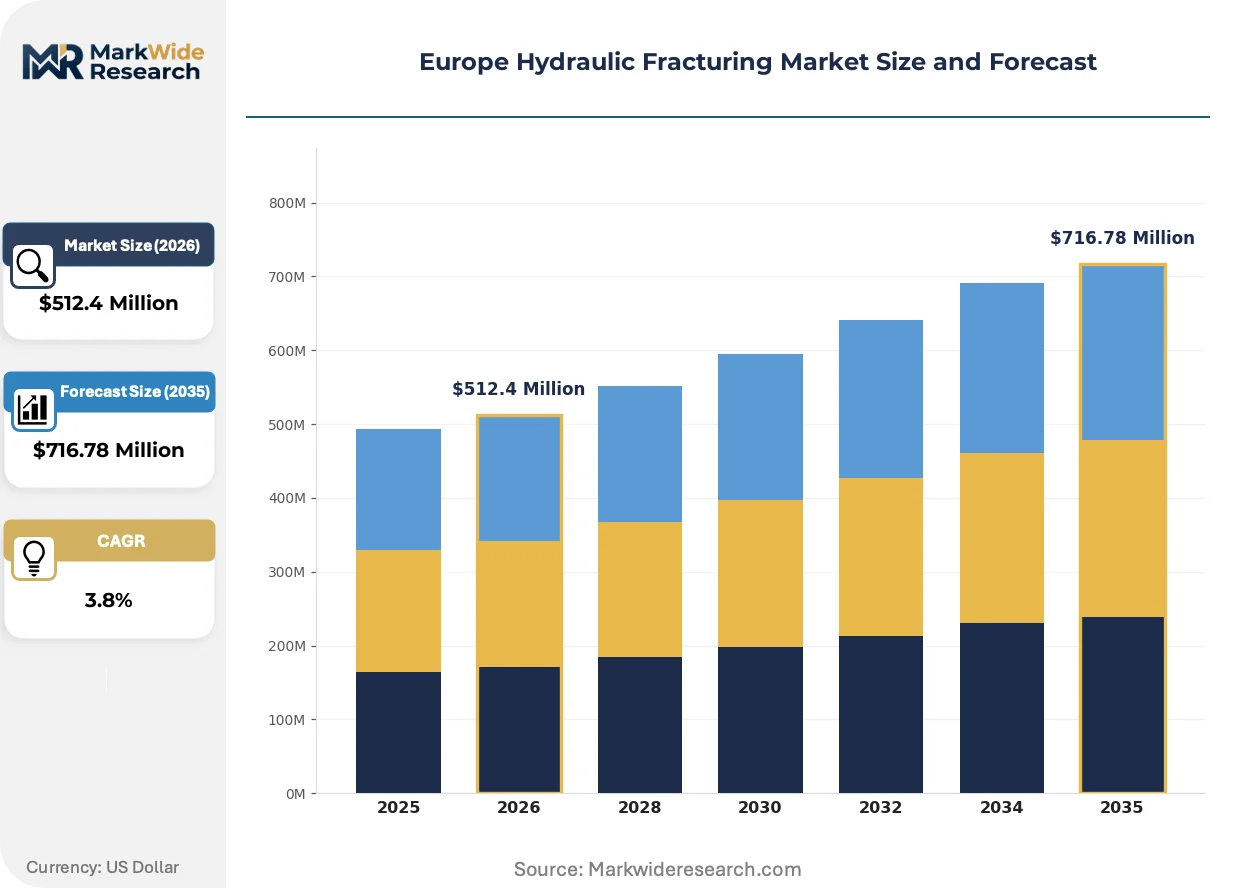
| Market Size in 2026 | $512.4 Million |
| Market Size in 2035 | $716.78 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Water-based, Gel-based, Foam-based, Hybrid End User: Oil & Gas Companies, Service Providers, Independent Producers, Government Agencies Application: Onshore, Offshore, Tight Oil, Shale Gas Deployment: Remote Sensing, Cloud-based, On-premise, Integrated Solutions |
| Companies Covered | Cuadrilla Resources Ltd, IGas Energy Plc, PJSC Rosneft Oil Company, Halliburton, Schlumberger, PAO NOVATEK, Equinor ASA, Baker Hughes, PJSC Gazprom, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hydraulic Fracturing Market Shifts & Advancements
Digitalization of fracture design and real-time downhole monitoring are compressing operational uncertainty in high-stress geologies. Service providers embed sensor networks directly into completion strings to capture pressure and temperature data during propagation.
Reservoir characterization software is converging with machine learning algorithms to optimize stage spacing and proppant loading in real time. Offshore operators in Norwegian waters deploy these integrated platforms to reduce screen-out frequency in tight chalk formations. The technology is compressing the iteration cycle between geological modeling and field execution from weeks to hours.
REACH chemical authorization procedures are tightening scrutiny of biocide and surfactant additives in fracturing fluids. ECHA's restriction proposals on per- and polyfluoroalkyl substances force reformulation of emulsion breakers and corrosion inhibitors. Fluid suppliers serving Danish and Dutch onshore projects accelerate substitution programs to maintain market access.
Integrated service contracting is displacing discrete equipment rental as the dominant procurement model in North Sea tight gas developments. Operators bundle pressure pumping, proppant supply, and flowback handling under single-provider agreements to transfer operational risk. This consolidation is most visible in UK southern North Sea campaigns where independents lack in-house fracturing expertise.
Europe Hydraulic Fracturing Market Segmentation
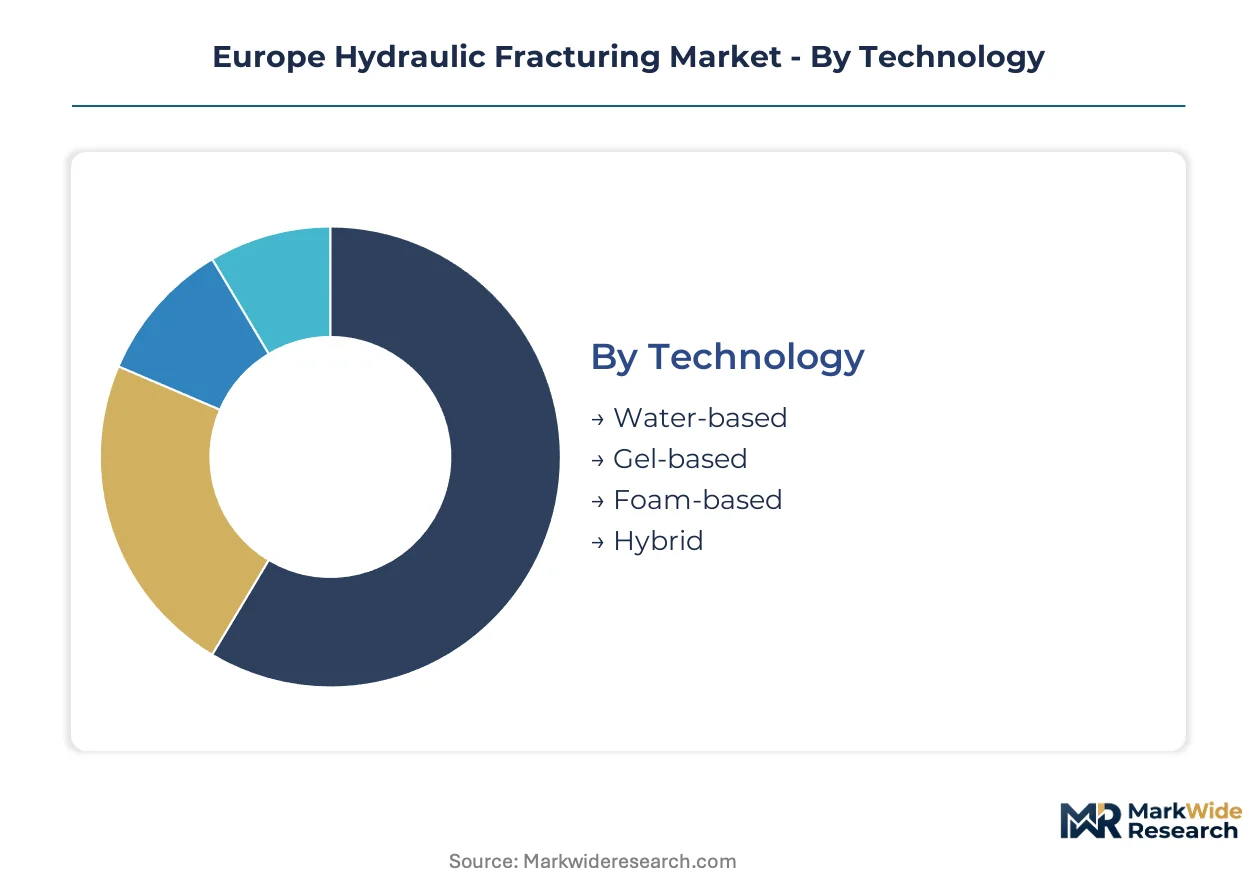
Technology and application choices in European hydraulic fracturing reflect divergent well economics across the North Sea basin. Deployment configurations increasingly favor integrated platforms that compress cycle time between geological modeling and field execution.
Technology:
Upgrade cycles in fluid chemistry accelerate as operators respond to REACH authorization pressures and high-temperature offshore requirements.
- Water-based:Slickwater formulations dominate mature onshore applications in England and Poland where cost efficiency governs procurement. Clay swelling limitations in North Sea shales restrict applicability, forcing operators toward gel alternatives in Norwegian and UK offshore campaigns.
- Gel-based:Cross-linked polymer systems command premium positioning in high-temperature offshore wells where fracture complexity demands superior proppant suspension. Norwegian deepwater operators specify these chemistries for Barents Sea tight carbonate completions.
- Foam-based:Compressed nitrogen systems reduce water footprint in water-stressed Dutch onshore concessions.
- Hybrid:Combined water-gel chemistries optimize stage economics in variable-permeability UK southern North Sea formations.
Volume placements concentrate in Water-based; the faster expansion belongs to Gel-based.
End User:
Procurement concentration varies by asset ownership structure across European jurisdictions.
- Oil & Gas Companies:Integrated majors like Equinor and Shell bundle pressure pumping under long-term framework agreements to lock in capacity for Norwegian Sea licensing rounds. Their scale permits direct negotiation of REACH-compliant fluid formulations with service providers.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes compete for integrated well-construction contracts spanning fracturing design through flowback handling. Their investment in digital twin capabilities targets operator demand for real-time fracture optimization.
- Independent Producers:UK southern North Sea independents lack in-house fracturing expertise and rely on single-provider risk-transfer agreements.
- Government Agencies:Norway's Petroleum Safety Authority and the UK Environment Agency shape procurement through divergent well-integrity certification requirements.
Contract value pools deepest with Oil & Gas Companies; Service Providers capture the steepest expansion trajectory through integrated platform adoption.
Application:
Asset maturity and regulatory exposure segment operator investment priorities.
- Onshore:England's lifted moratorium on tight gas licensing reopens previously suspended exploration acreage to fracturing services. Polish shale concessions continue limited activity despite persistent geological challenges.
- Offshore:Norwegian deepwater campaigns in the Norwegian Sea and Barents Sea drive specialized high-pressure service demand. Equinor's tight chalk developments require stage-specific proppant placement in high-stress geologies.
- Tight Oil:Low-permeability carbonate reservoirs in the Barents Sea region attract the fastest-growing investment as conventional reserves deplete.
- Shale Gas:North Sea basin unconventional exploration expands under EU methane emission regulations.
Offshore commands premium pricing; Tight Oil gains share fastest on reserve replacement economics.
Deployment:
Data architecture choices reflect operational scale and real-time decision requirements.
- Remote Sensing:Satellite-linked monitoring supports distributed North Sea platform operations where crew rotation limits physical presence.
- Cloud-based:Machine learning algorithms for stage spacing optimization run on cloud infrastructure accessible to Stavanger and Aberdeen engineering centers.
- On-premise:Cybersecurity-conscious operators maintain localized data processing for well integrity documentation subject to Petroleum Safety Authority audit.
- Integrated Solutions:Converged geological modeling and pressure control platforms compress iteration cycles from weeks to hours in Norwegian tight gas campaigns.
Integrated Solutions capture expanding contract value; Cloud-based deployment climbs fastest on CSRD sustainability reporting integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe produces minimal shale gas domestically yet consumes substantial volumes imported via pipeline and LNG, creating a persistent supply gap that offshore tight gas development in the North Sea rim seeks to narrow.
Norway
Equinor ASA drives deepwater fracturing demand through tight chalk developments in the Norwegian Sea and Barents Sea. The Norwegian Petroleum Safety Authority enforces stringent well-integrity protocols that elevate equipment certification costs. Stavanger anchors specialized service provider clusters where Halliburton and Schlumberger maintain pressure-pumping infrastructure.
United Kingdom
IGas Energy Plc and Cuadrilla Resources Ltd resumed onshore exploration after England lifted its tight gas licensing moratorium. The UK Environment Agency applies divergent chemical disclosure standards compared to EU REACH, fragmenting cross-border fluid formulation compliance. Aberdeen concentrates legacy engineering expertise for high-pressure offshore completions.
Netherlands
Water-stressed onshore concessions in Groningen and Flevoland attract foam-based fracturing systems to minimize freshwater consumption. The country's national environmental regulator imposes strict groundwater protection standards on subsurface injection operations. Rotterdam serves as the primary import hub for ceramic proppant supplies destined for North Sea campaigns.
Poland
PJSC Gazprom and domestic independents sustain limited shale activity despite persistent geological complexity in Lower Silesian basins. The country's national energy regulator oversees concession terms that favor conventional over unconventional exploration. Warsaw hosts service provider coordination centers linking Polish onshore projects to North Sea offshore expertise.
Germany
Ceramic proppant manufacturing clusters in Bavaria face energy cost volatility that transmits into North Sea service pricing. ECHA registration requirements for fracturing fluid additives extend formulation development timelines for suppliers serving German onshore pilots. Munich anchors chemical supplier R&D facilities adapting to REACH restriction proposals on per- and polyfluoroalkyl substances.
Europe Hydraulic Fracturing Market Competitive Landscape
Top-tier vendors anchor integrated service contracting, while regional independents compete on discrete equipment rental and specialized fluid formulation. The market structure concentrates around three global service conglomerates that bundle pressure pumping, proppant supply, and flowback handling under single-provider risk-transfer agreements. Two strategic archetypes dominate: technology-integrated platform providers and chemistry-specialized formulation houses. Competitive moves center on digital twin capability acquisition and REACH-compliant additive portfolio expansion.
Among US-based integrated service providers, Halliburton, Schlumberger, and Baker Hughes exemplify the technology-integrated archetype, each occupying positions that span well construction through completion optimization. These entities represent the premium-tier competitive vector where real-time fracture propagation modeling and automated pressure control differentiate contract awards. Their geographic footprints concentrate engineering resources in Aberdeen and Stavanger to capture Norwegian Sea and UK southern North Sea tight gas developments.
| Leading Market Players |
|---|
| Cuadrilla Resources Ltd |
| IGas Energy Plc |
| PJSC Rosneft Oil Company |
| Halliburton |
| Schlumberger |
| PAO NOVATEK |
| Equinor ASA |
| Baker Hughes |
| PJSC Gazprom |
| Others |
Supply & Pricing Matrix
Fluid chemistry certification tiers—REACH-authorized formulations versus transitional additive packages—create a bifurcated cost structure that separates Norwegian deepwater operators from Polish onshore independents. This divergence manifests in procurement patterns where premium gel-based systems command capacity reservations at Stavanger service hubs, while commodity slickwater blends face spot-market volatility at Groningen distribution nodes.
Pricing Analysis
Short lead-time premiums for ceramic proppant loads distinguish contract-based Norwegian campaigns from spot-market English onshore projects. Three-tier pricing structure across premium gel systems, standard water-based chemistry, and economy foam alternatives reflects divergent well-integrity certification requirements. Cost compression in water-based tiers is intensifying because German ceramic manufacturing clusters face energy input volatility. Polish independents exhibit the highest price sensitivity, while Equinor's framework agreements demonstrate minimal elasticity due to operational risk transfer priorities.
Supply Chain Analysis
Petroleum Safety Authority qualification gates restrict equipment mobility between Norwegian and UK jurisdictions, fragmenting asset utilization rates. Ceramic proppant manufacturing concentrates in Germany, Poland, and Norway, while specialized pressure-pumping fleets anchor in Aberdeen and Stavanger. Cross-linked polymer feedstocks draw from Bavarian chemical clusters, high-purity nitrogen supplies from Dutch industrial gas networks, and digital control systems from UK engineering centers. Single-source vulnerability pervades deepwater blowout preventer certification pathways. Distribution runs through Rotterdam bulk terminals for proppant, with specialized pumping equipment mobilizing via North Sea heavy-lift vessels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical authorization operates as a cost-of-compliance moat, elevating formulation development timelines and capital requirements that shield established fluid suppliers from commodity competition.
For Market Incumbents: Cement integrated service contracting dominance by acquiring digital twin capabilities that compress fracture design iteration cycles. Norwegian offshore licensing rounds present capacity reservation opportunities that lock out challengers lacking Petroleum Safety Authority certification heritage. Backward integration into ceramic proppant manufacturing mitigates German energy cost volatility transmission. For New Entrants and Emerging Players: Automated pressure control algorithms offer a technology-first wedge into UK southern North Sea independents lacking in-house fracturing expertise. White-space targets include England's revived onshore tight gas licensing and Dutch foam-based water-minimization concessions. A regulatory-specialist positioning—REACH compliance-as-a-service—opens procurement channels with mid-tier operators avoiding direct ECHA engagement. For Investors and Strategic Acquirers: Re-rating potential sits with digital-integrated service providers given CSRD sustainability reporting mandates creating disclosure differentiation value. Long-term viability favors entities with captive REACH-authorized additive portfolios and Norwegian well-integrity certification heritage. The inflection signal to monitor is UK Environment Agency convergence toward EU chemical disclosure standards, which would compress cross-border compliance fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Additive Portfolio Expansion | ECHA authorization timelines protect formulation IP from commodity competitors. |
| Digital Twin Capability Acquisition | Real-time fracture propagation modeling reduces non-productive time in Norwegian deepwater campaigns. |
| Ceramic Proppant Manufacturing Backward Integration | Captive supply of high-strength proppant insulates against German energy cost volatility. |
| Integrated Service Contracting Consolidation | Single-provider risk transfer agreements capture UK independent operator procurement. |
| Petroleum Safety Authority Certification Investment | Norwegian well-integrity standards create equipment mobility barriers against non-certified competitors. |
Research Methodology
Independent corroboration across pressure-pumping service executives, offshore drilling contractors, petroleum safety regulators, and chemical formulation specialists underwrites the qualitative findings. Primary interviews with Stavanger-based engineering directors and Aberdeen procurement leads combined with secondary validation from ECHA registration databases, Norwegian Petroleum Directorate production statistics, UK Environment Agency permit filings, and EU Green Deal methane emission monitoring protocols. Bottom-up project pipeline assessment and top-down regulatory impact modeling triangulate volume estimates.
Rate-of-change decomposition across technology adoption curves, regulatory implementation timelines, and licensing round schedules structures the forecast framework. Segmentation dimensions span fluid chemistry type, well architecture complexity, operator ownership structure, and regional regulatory cluster. CAGRs derive from capacity utilization trends in named service hubs and proppant manufacturing clusters. Forecast inputs incorporate REACH authorization pipeline status and Norwegian Sea exploration commitment levels.
Several conditions sit outside the modeled scope, including potential EU-wide fracturing moratorium legislation, breakthrough in waterless fracturing technologies, and geopolitical disruption of North Sea supply chains. Forecasts reflect assumptions regarding regulatory stability and continued offshore licensing access. A model refresh is warranted upon material change in ECHA restriction proposals targeting per- and polyfluoroalkyl substances.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Middle East Natural Gas Market
Oil & Gas
Sensors in Oil and Gas Market
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
Oil and Gas Data Management Market
Oil & Gas
Nigeria Oil and Gas Midstream Market
Oil & Gas
Cased Hole Logging Services Market
Oil & Gas
Offshore Oil and Gas Paints and Coatings Market
Oil & Gas
Global LNG Regasification Terminals Market
Oil & Gas
Coiled Tubing Services Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Desalter Market
Oil & Gas
Global Carbon Steel Tubing in Oil and Gas Lift Applications Market
Oil & Gas
Canada Oil and Gas Upstream Market