
 United Kingdom LNG Market | 2026-2036
United Kingdom LNG Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom LNG Market Analytics
A capital-intensity divergence between integrated majors and terminal operators is reorganizing competitive dynamics across the United Kingdom LNG value chain. Shell PLC leverages its global liquefaction portfolio to secure long-term supply slots into South Hook and Dragon terminals. BP p.l.c. anchors its position through equity stakes in upstream projects and direct regasification capacity at Isle of Grain. South Hook LNG Terminal Ltd. competes on throughput reliability and ship-or-pay contract structures with Qatari supply partners.
Liquefied natural gas comprises methane condensed to liquid form at minus 162 degrees Celsius, reducing volume by a factor of 600 for marine transport and enabling intercontinental energy trade. The United Kingdom relies on LNG to balance seasonal demand swings and offset declining North Sea production. Re-gasified LNG dominates volume flows through the National Grid transmission system, while small-scale LNG is gaining traction for industrial off-grid applications and marine bunkering. Power generation absorbs the largest share of regasified output, though transportation fuel demand is expanding fastest from a low base as dual-fuel truck and vessel fleets scale.
The Health and Safety Executive enforces COMAH regulations governing major hazard sites including LNG terminals, while Ofgem oversees gas market access and storage licensing under the Gas Act. The North Sea Transition Deal imposes emissions benchmarks that are reshaping terminal investment timelines and carbon capture integration requirements. Stakeholders must monitor OFTO auction outcomes and hydrogen blending trials at import facilities to assess infrastructure repurposing risk and stranded asset exposure.
Market Dynamics
The North Sea Transition Deal is forcing terminal operators to accelerate carbon capture readiness retrofits at import facilities while simultaneously managing baseload power demand from retiring coal infrastructure.
Growth Catalysts
- Power generation expansion:Baseload gas-fired plants are absorbing regasified LNG volumes as coal capacity retires under carbon pricing mechanisms. Grid balancing requirements intensify seasonal offtake patterns.
- COMAH enforcement:The Health and Safety Executive's major hazard regulations are standardizing safety protocols across terminal operations. Compliance investments are reducing incident risk and insurance premiums.
- Isle of Grain concentration:Pipeline interconnector convergence at this Kent cluster is creating infrastructure economies of scale. Regasification capacity utilization rates exceed regional averages.
Market Restraints
- Qatari supply concentration:Long-term ship-or-pay contracts with Middle Eastern producers limit sourcing flexibility. Diversification into Atlantic Basin supply remains contractually constrained.
- Carbon capture capex burden:Retrofitting post-combustion capture systems at existing terminals requires capital deployment without immediate revenue offset. Project timelines extend payback periods.
- North Sea production decline:Domestic field depletion is removing swing supply buffers. Pipeline gas shortfalls intensify import dependency during demand spikes.
Strategic Opportunities
- Small-scale LNG bunkering:Milford Haven port infrastructure can capture marine fuel switching from heavy fuel oil. Dual-fuel vessel fleet growth outpaces Mediterranean competitor ports.
- Hydrogen blending trials:Ofgem-sanctioned pilot programs at import terminals are testing pipeline compatibility. Early regulatory clearance creates first-mover positioning for repurposed assets.
- Industrial off-grid applications:Remote manufacturing clusters in Wales and Scotland lack pipeline connectivity. Cryogenic tanker delivery bypasses National Grid transmission constraints.
Industry Challenges
- Process safety engineering scarcity:COMAH-competent technical staff command premium compensation. Terminal operators compete with North Sea oil platforms for limited talent pools.
- OFTO auction timing risk:Offshore transmission owner auctions determine grid connection sequencing. Misaligned award schedules strand regasification capacity without export pathways.
- Legacy SCADA integration:Terminal control systems require cybersecurity hardening against evolving threat vectors. Operational technology upgrades disrupt continuous throughput operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom LNG Market |
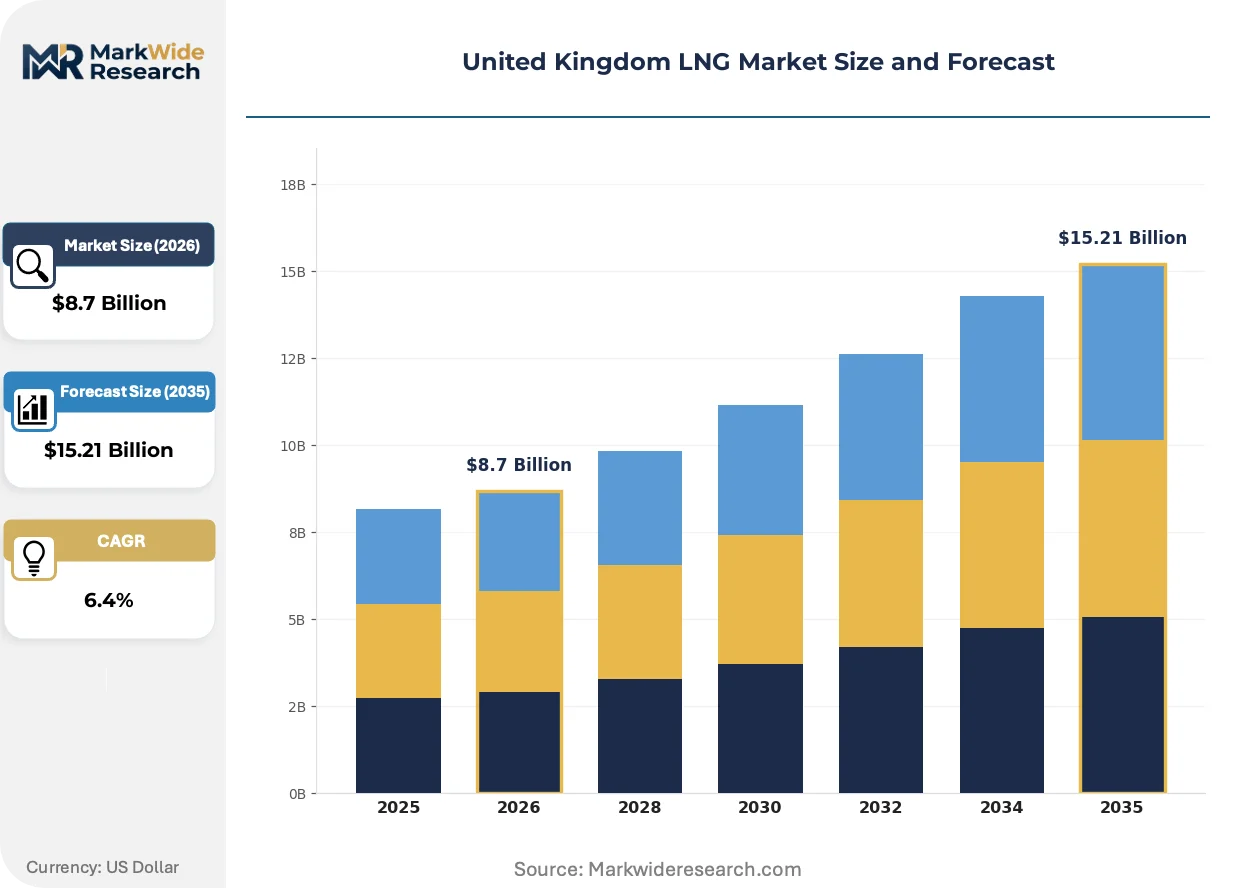
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Liquefied Natural Gas, Re-gasified LNG, Small-scale LNG, Floating LNG End User: Power Generation, Industrial, Residential, Transportation Distribution Channel: Direct Supply, Traders, Oil & Gas Companies, Brokers Application: Heating, Electricity Generation, Fuel for Vehicles, Industrial Processes |
| Companies Covered | Shell PLC, BP p.l.c., South Hook LNG Terminal Ltd., Dragon LNG, Électricité de France, TotalEnergies SE, Equinor ASA, ExxonMobil Corporation, Chevron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom LNG Market Evolving Landscape
Carbon capture integration at import terminals is reshaping capital allocation priorities, while small-scale distribution infrastructure unlocks demand segments previously excluded from pipeline economics.
Modular carbon capture technology is bifurcating terminal investment strategies between full-scale post-combustion retrofits and pilot solvent-based systems. Power generation utilities favor terminals with demonstrated capture readiness for offtake contract security. This technology split is compressing financing timelines for brownfield expansions versus greenfield developments.
The North Sea Transition Deal mandates emissions benchmarks that are compressing project approval windows for unabated gas infrastructure. Terminal operators must demonstrate carbon capture compatibility to secure planning consent. Milford Haven and Isle of Grain clusters are responding with integrated capture feasibility studies in initial development phases.
Ship-or-pay contract structures are losing ground to flexible tolling agreements as buyer credit profiles strengthen. Industrial offtakers in chemicals and ceramics sectors are negotiating interruptible supply terms against pipeline gas benchmarks. Wales and Scotland manufacturing corridors exhibit the strongest preference for demand-responsive pricing mechanisms.
United Kingdom LNG Market Segmentation
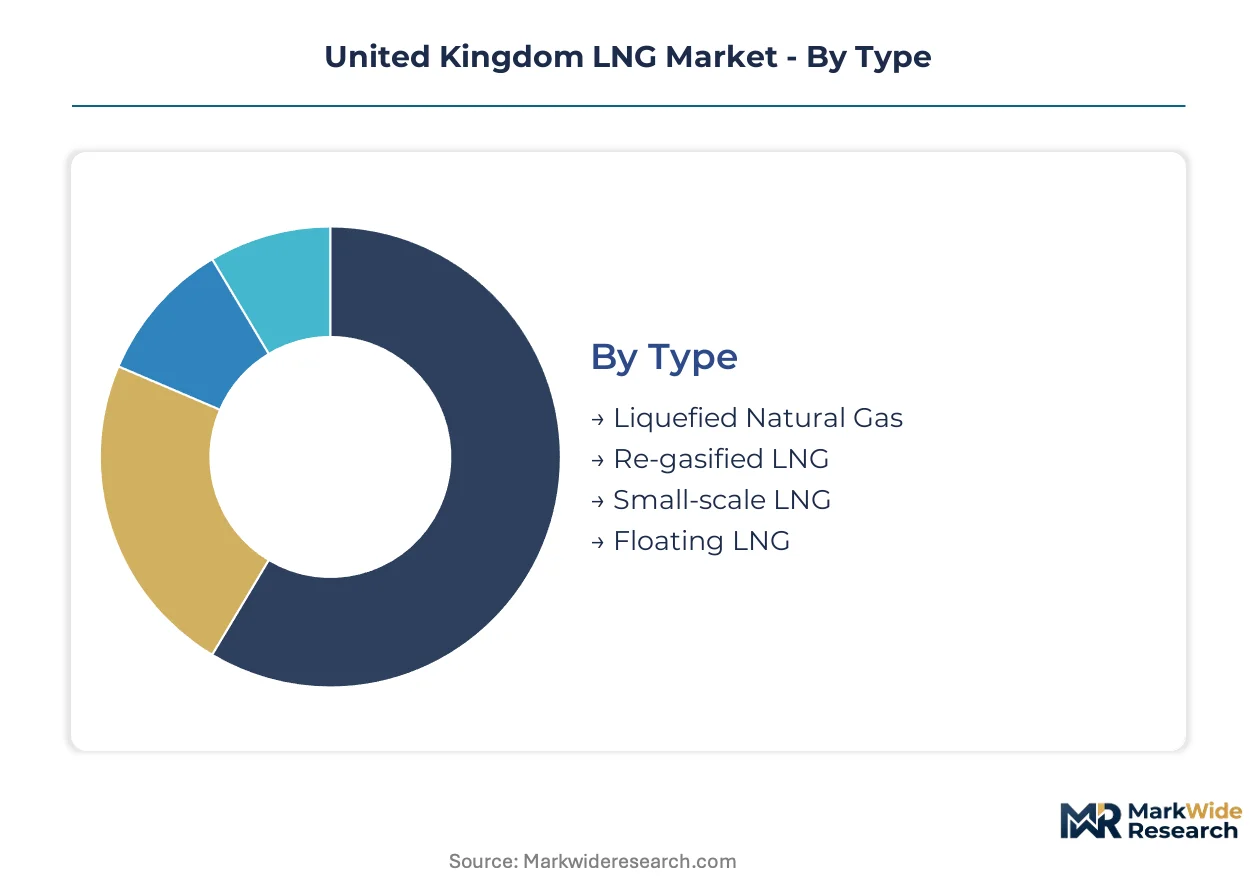
Segmentation reveals how LNG flows diverge between pipeline-connected baseload demand and distributed cryogenic delivery. Channel selection determines margin capture, with direct supply locking in utilities while traders arbitrage seasonal spreads.
Type:
Channel-mix varies sharply: re-gasified LNG flows through National Grid transmission to power utilities, while small-scale and floating LNG bypass pipeline infrastructure entirely.
- Liquefied Natural Gas:Cryogenic liquid stored at minus 162 degrees Celsius in insulated tanks at Isle of Grain and Milford Haven terminals. Demand concentrates in long-haul marine transport from Qatar and Atlantic Basin suppliers, constrained by ship-or-pay contract rigidity.
- Re-gasified LNG:Vaporized methane injected into National Grid transmission pipelines for power generation and industrial offtake. Power utilities at South Hook and Dragon terminals absorb the largest volumes as baseload coal replacement accelerates.
- Small-scale LNG:Cryogenic tanker delivery to off-grid industrial sites and marine bunkering ports. Wales manufacturing corridors and Scottish Highlands drive demand where pipeline connectivity is absent.
- Floating LNG:Offshore liquefaction and regasification vessels serving remote field developments. North Sea decommissioning timelines limit deployment scope in UK waters.
Re-gasified LNG dominates installed base. Small-scale LNG is where expansion concentrates.
End User:
Cost-tier stratification separates baseload power contracts with utility credit backing from interruptible industrial supply with higher risk premiums.
- Power Generation:Combined-cycle gas turbines at Grain and Pembroke power stations consume regasified LNG under long-term offtake agreements. Grid balancing requirements intensify seasonal demand swings as renewable penetration rises.
- Industrial:Chemicals, ceramics, and food processing facilities in Wales and Scotland purchase small-scale LNG for process heat. Interruptible contract structures prevail against pipeline gas benchmarks.
- Residential:Limited direct consumption due to National Grid distribution coverage; isolated rural properties in Scottish Highlands use tanker delivery where mains gas is unavailable.
- Transportation:Dual-fuel truck fleets and marine vessels at Milford Haven switch from heavy fuel oil. Bunkering infrastructure expansion outpaces Mediterranean competitor ports.
Power generation commands volume leadership. Transportation is climbing the fastest.
Distribution Channel:
Supply concentration around terminal clusters shapes channel power, with integrated majors controlling import capacity and independent traders capturing margin in volatile periods.
- Direct Supply:Terminal operators contract directly with power utilities and large industrials, bypassing intermediary markups. Shell and BP leverage equity terminal stakes to lock in baseload offtake.
- Traders:Independent merchants arbitrage spot-price differentials between NBP and continental hubs. Credit requirements limit participation during margin compression cycles.
- Oil & Gas Companies:Integrated majors route Qatari and Atlantic Basin supply through captive terminal slots. Long-term portfolio contracts reduce sourcing flexibility.
- Brokers:Intermediaries match fragmented industrial demand with surplus terminal capacity. Small-scale LNG growth expands matchmaking opportunities in Wales and Scotland corridors.
Direct supply dominates contracted volumes. Traders are gaining share fastest in spot-market segments.
Application:
Application mix tracks infrastructure availability, with pipeline-connected heating and power generation contrasting against vehicle fuel demand requiring dedicated bunkering networks.
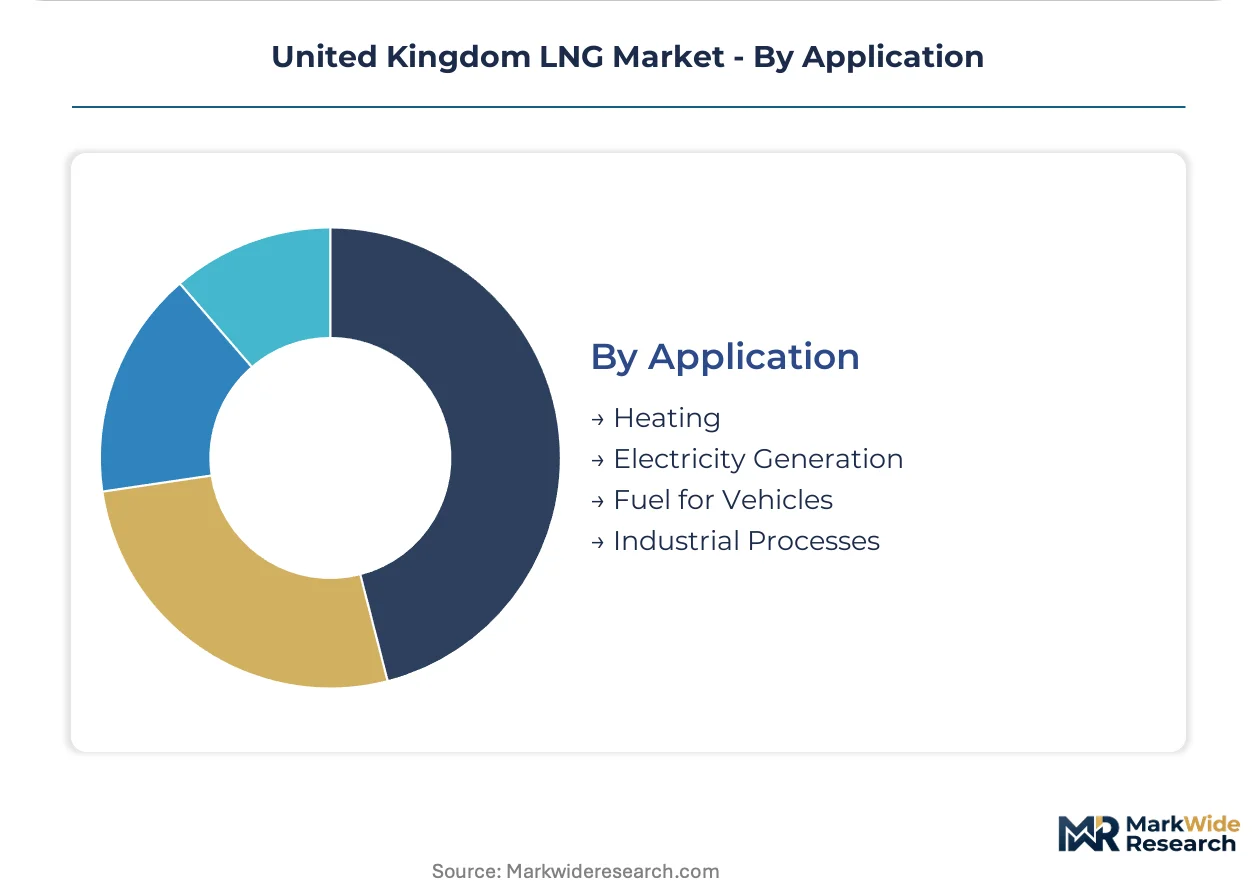
- Heating:Residential and commercial building warmth supplied through National Grid distribution networks. Seasonal demand peaks strain regasification capacity during cold snaps.
- Electricity Generation:CCGT plants at South Hook and Pembroke convert gas to power with efficiency advantages over coal. Carbon capture readiness requirements reshape terminal investment priorities.
- Fuel for Vehicles:Heavy-duty trucks and marine vessels adopt dual-fuel systems at Milford Haven. Port infrastructure investments enable fuel switching from residual fuel oil.
- Industrial Processes:High-temperature heat for ceramics, glass, and chemicals manufacturing. Cryogenic tanker delivery serves off-grid facilities in Welsh manufacturing clusters.
Electricity generation anchors demand. Fuel for vehicles shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in Wales and Scotland exhibit the highest price elasticity, interrupting offtake when NBP spreads compress, while baseload power utilities at Isle of Grain absorb volumes regardless of short-term price swings.
London and Southeast England
Power generation utilities at Grain and South Hook terminals anchor baseload demand through long-term ship-or-pay contracts. The North Sea Transition Deal imposes carbon capture readiness timelines on terminal expansions. Kent's Isle of Grain cluster concentrates regasification capacity and pipeline interconnectors serving National Grid balancing requirements.
Wales
Industrial ceramics and chemicals manufacturers in Welsh manufacturing corridors purchase small-scale LNG via cryogenic tanker delivery. Ofgem's gas market access regulations govern storage licensing and third-party terminal access. Milford Haven port infrastructure supports marine bunkering growth as dual-fuel vessel fleets expand faster than Mediterranean competitors.
Scotland
Remote highland properties and off-grid industrial facilities rely on tanker-delivered LNG where National Grid distribution is absent. The Health and Safety Executive's COMAH regulations standardize safety protocols across cryogenic storage sites. Aberdeen's energy corridor maintains process engineering talent pools despite competition from North Sea oil platforms.
North England
Pipeline-connected industrial heat users switch between regasified LNG and North Sea pipeline gas based on seasonal price differentials. The Gas Act framework governs market access and storage licensing for terminal operators. Teesside's chemicals cluster evaluates hydrogen blending trials at import facilities for future feedstock security.
United Kingdom LNG Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with upstream-backed majors controlling terminal equity and throughput slots while independent terminal operators compete on reliability metrics and flexible contract structures. Shell PLC and BP p.l.c. anchor the upper tier through captive regasification capacity and long-term supply portfolios. South Hook LNG Terminal Ltd. and Dragon LNG occupy the specialist tier with throughput-focused operating models. Competitive dynamics center on carbon capture readiness investments and small-scale distribution infrastructure expansion.
Within the integrated major tier, Shell PLC and BP p.l.c. exemplify upstream-to-terminal control strategies that lock in baseload offtake through equity stakes. South Hook LNG Terminal Ltd. represents the specialist operator archetype, competing on ship-or-pay contract execution and Qatari supply partnerships. These three companies span the vertical spectrum from liquefaction equity through regasification capacity to direct utility supply relationships.
| Leading Market Players |
|---|
| Shell PLC |
| BP p.l.c. |
| South Hook LNG Terminal Ltd. |
| Dragon LNG |
| Électricité de France |
| TotalEnergies SE |
| Equinor ASA |
| ExxonMobil Corporation |
| Chevron Corporation |
| Others |
Value Network & Pricing Analysis
Ninety-day cargo scheduling windows at Isle of Grain and Milford Haven terminals compress buyer leverage and concentrate pricing power with Qatari suppliers holding long-term ship-or-pay contracts. This lead-time rigidity anchors contract structures while spot-market volatility creates arbitrage openings for flexible offtakers.
Pricing Analysis
After-sales service revenue from terminal maintenance and carbon capture readiness upgrades now drives lifetime value capture for infrastructure operators. Contract pricing stratifies across baseload ship-or-pay commitments, interruptible industrial supply, and spot-indexed trader positions. Price differentiation rests on carbon capture certification status and terminal reliability metrics. Cost compression in spot-indexed tiers is intensifying because Atlantic Basin supply diversification is loosening Qatari grip. Industrial buyers in Welsh manufacturing corridors exhibit highest price sensitivity, while Grain power utilities absorb volumes regardless of short-term NBP swings.
Supply Chain Analysis
Inventory buffers of 15-20 days at Isle of Grain and Dragon terminals reflect just-in-time regasification scheduling against National Grid balancing requirements. Qatari liquefaction, Norwegian pipeline gas, and US Gulf Coast LNG feed UK supply. Feedstock dependencies center on methane feed gas, specialized cryogenic tanker fleets, and regasification turbine maintenance. Single-source vulnerability concentrates in Middle Eastern long-term contracts. Distribution runs through National Grid transmission to power utilities, with small-scale tanker delivery bypassing pipeline infrastructure entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom LNG market fragments around carbon capture readiness tiers and small-scale distribution infrastructure, creating niche entry points as baseload power demand splits between abated and unabated gas pathways.
For Market Incumbents: Fortify terminal equity positions through carbon capture retrofit commitments at Isle of Grain and Milford Haven, locking in baseload utility offtake before hydrogen blending trials reshape asset valuations. Shell and BP should accelerate COMAH-compliant safety engineering recruitment to preempt talent scarcity from North Sea oil platforms. Priority lever: backward integration into Atlantic Basin liquefaction equity to dilute Qatari supply concentration risk. For New Entrants and Emerging Players: Differentiate on small-scale LNG bunkering infrastructure at Milford Haven, capturing marine fuel switching ahead of Mediterranean port competitors. Target Welsh ceramics and chemicals corridors with cryogenic tanker delivery where pipeline connectivity is absent. Go-to-market angle: interruptible supply contracts with demand-responsive pricing against NBP benchmarks, bypassing ship-or-pay rigidity that constrains integrated majors. For Investors and Strategic Acquirers: Carve-out targets emerge from oil majors divesting non-core terminal equity stakes as carbon capture capex burdens reshape portfolio priorities. Long-term viability hinges on hydrogen blending compatibility and repurposing optionality across the analysis window. Acquisition archetype: specialist terminal operators with demonstrated COMAH compliance and small-scale distribution infrastructure. Signal to watch: Ofgem hydrogen pilot program approvals as stranded asset risk inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Commitment | North Sea Transition Deal mandates emissions benchmarks that compress unabated gas project timelines at import terminals. |
| Small-Scale Bunkering Infrastructure | Milford Haven port investments capture marine fuel switching from heavy fuel oil faster than Mediterranean competitors. |
| Atlantic Basin Supply Diversification | US Gulf Coast and Norwegian portfolio contracts dilute Qatari ship-or-pay concentration limiting sourcing flexibility. |
| Hydrogen Blending Pilot Participation | Ofgem-sanctioned trials at import terminals test pipeline compatibility for first-mover repurposed asset positioning. |
| COMAH Safety Engineering Investment | Health and Safety Executive enforcement standardizes protocols while talent scarcity from North Sea platforms drives premium compensation. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with terminal operations directors, utility fuel procurement managers, and Health and Safety Executive compliance officers; and secondary validation against National Grid transmission data, Ofgem storage licensing records, and North Sea Transition Deal policy documentation. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions including regasification versus small-scale delivery mode, power generation versus industrial end-use, and direct supply versus trader-mediated channel structure. CAGRs were derived from capacity utilization trajectories at Isle of Grain and Milford Haven clusters, carbon capture investment timelines, and marine bunkering infrastructure deployment schedules.
Decision-makers should treat outputs as directional under assumptions of continued North Sea production decline and sustained UK carbon pricing mechanisms; material deviation in Qatari supply reliability or hydrogen blending regulatory pace would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Chad Oil and Gas Upstream Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
Liquefied Natural Gas Market
Oil & Gas
Europe Well Intervention Market
Oil & Gas
Turkmenistan Oil and Gas Market
Oil & Gas
Global Fracking Fluids and Chemicals Market
Oil & Gas
China Oil and Gas Midstream Market
Oil & Gas
Drill Collar Market
Oil & Gas
Middle East and Africa Drill Collar Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Russian Federation Oil and Gas Downstream Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
South America LNG Bunkering Market
Oil & Gas
US Sand Control Systems Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
United States Coiled Tubing Market