
 Methane Hydrate Extraction Market | 2026-2036
Methane Hydrate Extraction Market Size, Share, and Industry Trends Forecast 2026-2036
Methane Hydrate Extraction Market Outlook
The gap between premium offshore extraction systems and commodity onshore gas alternatives is hardening as project economics diverge. Schlumberger Limited leverages its subsea technology portfolio to anchor deepwater hydrate pilot programs in frontier basins. BP p.l.c. competes through specialized simulation modeling capabilities that reduce reservoir uncertainty before capital deployment.
Methane hydrate extraction involves the controlled dissociation of ice-like crystalline structures containing methane molecules trapped within water cages, typically requiring pressure reduction below equilibrium conditions or thermal stimulation above dissociation temperatures to release gaseous fuel. Depressurization methods currently dominate operational trials due to lower energy input requirements, while thermal stimulation attracts capital in permafrost zones where surface heat sources prove technically accessible. Energy production applications command the largest share of committed investment, though carbon capture integration represents the fastest-growing segment as operators seek dual-revenue streams from hydrate-bearing formations.
The US Bureau of Ocean Energy Management and Japan's Agency for Natural Resources and Energy impose distinct permitting frameworks for offshore test drilling, with BOEM requiring extensive environmental impact statements for Alaska North Slope operations. China's Ministry of Natural Resources and Japan's METI coordinate bilateral standards for subsea monitoring protocols to prevent uncontrolled methane release during extraction trials. Stakeholders must track which regulator adopts mandatory carbon intensity thresholds first, as this will reshape project feasibility assessments across all active hydrate provinces.
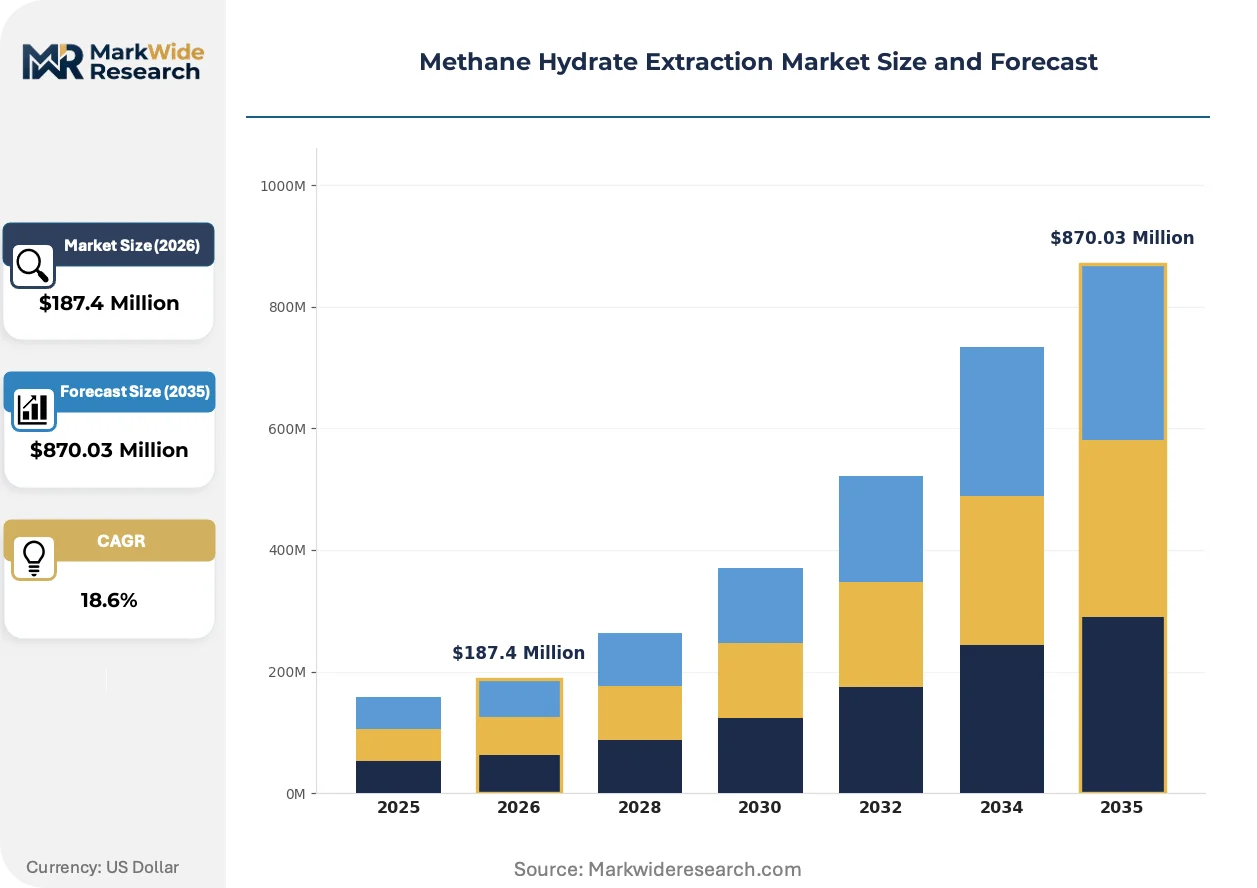
Market Dynamics
Depressurization technology maturation is compressing project breakeven thresholds across frontier hydrate basins, while Japan's METI funding mechanisms and China's Ministry of Natural Resources permitting acceleration are concentrating pilot deployment timelines in the Pacific Rim.
Growth Catalysts
- Japan's METI Research Programs:Government-backed depressurization trials in the Nankai Trough are validating commercial-scale extraction protocols and attracting private capital into subsea infrastructure partnerships.
- Carbon Capture Integration:Dual-revenue stream architectures from hydrate-bearing formations are pulling investment from energy majors seeking stranded asset monetization pathways.
- Subsea Robotics Advancement:Autonomous monitoring systems are reducing operational risk premiums and enabling sustained production testing in deepwater environments previously deemed inaccessible.
Market Restraints
- Capital Intensity Barriers:Specialized drilling vessels and subsea wellhead systems require nine-figure deployment commitments before reservoir validation, freezing out mid-cap operators.
- Permitting Friction:The US Bureau of Ocean Energy Management mandates multi-year environmental impact statements for Alaska North Slope test drilling, extending project gestation periods beyond investor patience thresholds.
- Shale Gas Substitution:Abundant conventional unconventional gas supply in North American markets is diverting R&D capital away from hydrate commercialization programs.
Strategic Opportunities
- South Korea's Unexplored Ulleung Basin:Underpenetrated deepwater acreage with confirmed hydrate deposits offers first-mover positioning for operators with proven depressurization toolkits.
- India's National Gas Hydrate Program:Ministry of Petroleum and Natural Gas production-sharing contract reforms are opening frontier blocks in the Krishna-Godavari basin to international joint ventures.
- CO2 Injection Convergence:Simultaneous methane extraction and carbon sequestration via swap technology is creating regulatory credit eligibility under emerging carbon accounting frameworks.
Industry Challenges
- Reservoir Simulation Talent Scarcity:Specialized geomechanical modeling expertise for hydrate-bearing sediments remains concentrated within a handful of academic institutions and national laboratories.
- Equipment Certification Delays:Subsea blowout preventers and wellhead assemblies lack standardized hydrate-specific testing protocols, forcing project-specific engineering reviews that extend procurement cycles.
- Legacy Infrastructure Integration:Connecting isolated hydrate production systems to existing natural gas pipeline networks requires compression and dehydration investments that erode marginal project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methane Hydrate Extraction Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Extraction Method: Depressurization, Thermal Stimulation, Gas Hydrate Dissociation, Chemical Injection Application: Energy Production, Carbon Capture, Geological Research, Marine Transportation End User: Energy Companies, Research Institutions, Government Agencies, Environmental Organizations Technology: Subsea Technology, Surface Equipment, Pipeline Infrastructure, Simulation Modeling |
| Companies Covered | Schlumberger Limited, BP p.l.c., ConocoPhillips Company, Equinor ASA, PetroChina Company Limited, Japan Petroleum Exploration Co., Ltd., INPEX Corporation, Oil and Natural Gas Corporation Ltd., ExxonMobil Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methane Hydrate Extraction Market Strategic Shifts
Extraction methodology convergence is eliminating thermal stimulation from most offshore project designs, while regulatory carbon intensity benchmarking is reshaping technology selection criteria across active hydrate provinces.
Depressurization-based dissociation systems are consolidating their dominance over thermal stimulation methods in offshore environments. Energy production operators in Japan and China are standardizing on pressure-reduction architectures that minimize energy input requirements and surface facility footprints. This technology consolidation is compressing thermal stimulation equipment vendors into niche permafrost applications where surface heat sources remain technically accessible.
China's Ministry of Natural Resources and Japan's METI are coordinating bilateral subsea monitoring standards to prevent uncontrolled methane release during extraction trials. This regulatory harmonization is forcing equipment suppliers to dual-certify sensor and valve systems against both national protocols. Frontier basin developers in the Pacific Rim are responding by pre-qualifying vendors against the stricter of the two standards to ensure cross-border project portability.
Buyer concentration around national oil companies is displacing fragmented independent operator participation in hydrate pilot programs. China's CNOOC and Japan's JOGMEC are consolidating drilling campaign procurement into multi-year framework agreements with integrated service providers. This procurement consolidation is most visible in the Nankai Trough and South China Sea, where single-source contracting is reducing vendor switching and compressing equipment pricing transparency.
Methane Hydrate Extraction Market Segmentation
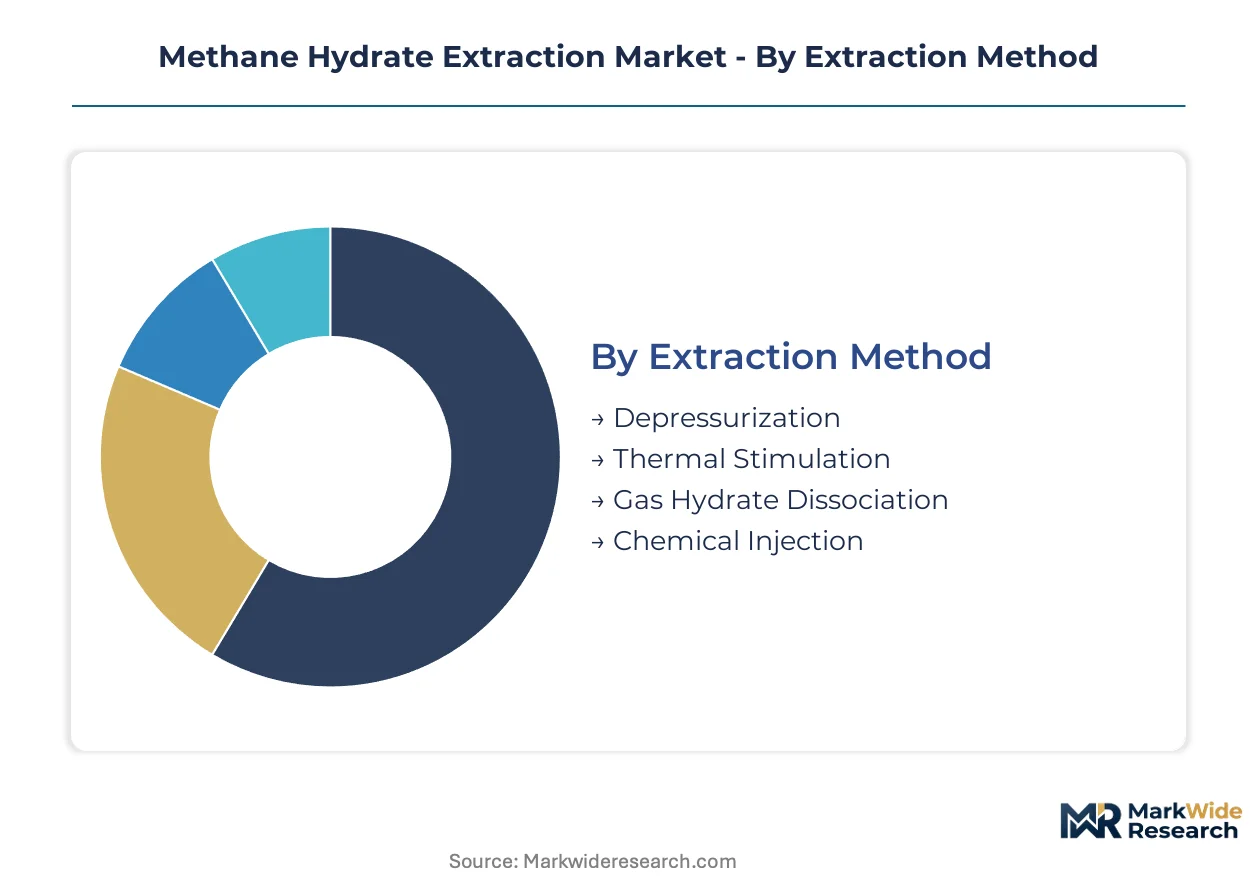
Methane hydrate extraction markets fragment across technical methodologies and deployment architectures. Each segmentation axis reveals distinct capital allocation patterns and regulatory exposure profiles.
Extraction Method:
Standardization dominates depressurization deployments while thermal stimulation retains customization requirements for permafrost-specific engineering.
- Depressurization:Pressure-reduction protocols dissociate hydrate crystals through controlled reservoir drawdown below equilibrium conditions. Japan's Nankai Trough trials concentrate demand here as METI validates commercial-scale production protocols.
- Thermal Stimulation:Surface or subsurface heat injection raises sediment temperatures above dissociation thresholds. Alaska North Slope operators favor this approach where permafrost surface infrastructure enables thermal access, though energy input costs constrain economics.
- Gas Hydrate Dissociation:Combined pressure-temperature manipulation techniques optimize recovery rates in complex reservoir geometries.
- Chemical Injection:Thermodynamic inhibitors alter hydrate stability conditions through methanol or glycol introduction.
Most installed capacity flows through Depressurization. Expansion is steepest in Gas Hydrate Dissociation as hybrid architectures gain validation.
Application:
Volume concentration sits with energy majors while margin capture shifts toward carbon accounting frameworks.
- Energy Production:Commercial methane recovery for power generation and industrial feedstock supply. China's Ministry of Natural Resources permitting acceleration in the South China Sea drives pilot deployment timelines.
- Carbon Capture:CO2 injection into hydrate-bearing formations enables simultaneous methane release and sequestration. Japan's METI research programs validate swap technology for dual-revenue stream architectures.
- Geological Research:Reservoir characterization and dissociation mechanism studies advance extraction science.
- Marine Transportation:Hydrate-derived LNG bunkering and vessel fuel supply chains.
Energy Production commands committed capital volumes. Carbon Capture climbs the fastest as carbon accounting frameworks mature.
End User:
Procurement concentration around national entities displaces fragmented private participation.
- Energy Companies:Integrated majors and national oil companies fund pilot programs through retained earnings.
- Research Institutions:University consortia and national laboratories advance dissociation science.
- Government Agencies:Japan's JOGMEC and China's CNOOC consolidate drilling campaign procurement into multi-year frameworks.
- Environmental Organizations:Monitoring and advocacy stakeholders shape permitting conditions.
Government Agencies direct most pilot funding. Energy Companies are expanding most quickly as commercialization timelines compress.
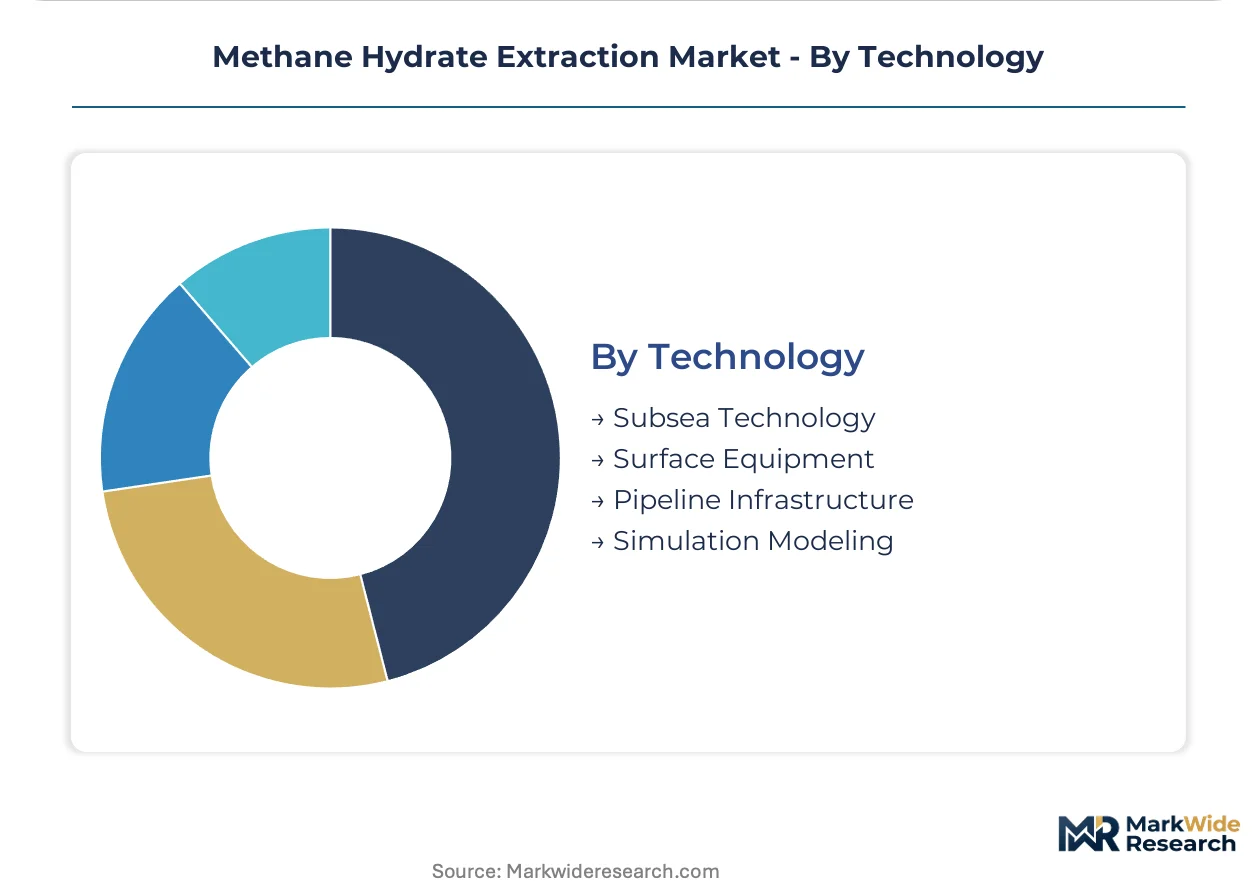
Technology:
Subsea equipment standardization lags surface infrastructure maturity.
- Subsea Technology:Autonomous monitoring systems and wellhead assemblies reduce operational risk premiums in deepwater environments.
- Surface Equipment:Compression and dehydration systems bridge hydrate production to pipeline specifications.
- Pipeline Infrastructure:Connection assets integrate isolated production systems to existing natural gas networks.
- Simulation Modeling:Geomechanical reservoir characterization reduces capital deployment uncertainty.
Surface Equipment holds the largest installed base. Subsea Technology shows the steepest expansion trajectory as frontier basins deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Geoscientists and subsea engineers cluster along Pacific Rim coastlines where hydrate-bearing sediments sit closest to population centers. National laboratories in Japan, China, and the United States anchor the technical workforce pipeline for reservoir characterization and depressurization system design.
Japan
Japan Petroleum Exploration Co., Ltd. and INPEX Corporation deploy specialized drilling units in the Nankai Trough where METI-funded research programs validate commercial-scale protocols. Japan's Agency for Natural Resources and Energy mandates continuous subsea monitoring during all extraction trials. Tokyo-Yokohama corridor houses the primary engineering consortium coordinating bilateral standards with Chinese regulators.
China
CNOOC accelerates pilot deployment in the South China Sea as the Ministry of Natural Resources streamlines permitting timelines for frontier blocks. China's Ministry of Natural Resources coordinates bilateral monitoring standards with Japan to prevent uncontrolled methane release. Shenzhen-Guangzhou industrial cluster manufactures autonomous subsea monitoring systems for Pacific Rim deployment.
United States
ConocoPhillips Company and ExxonMobil Corporation advance Alaska North Slope thermal stimulation trials where permafrost surface infrastructure enables heat access. The US Bureau of Ocean Energy Management requires multi-year environmental impact statements for offshore test drilling. Houston-Gulf Coast corridor concentrates subsea equipment engineering talent and specialized drilling vessel operations.
India
Oil and Natural Gas Corporation Ltd. evaluates Krishna-Godavari basin blocks as the Ministry of Petroleum and Natural Gas reforms production-sharing contracts for international joint ventures. India's National Gas Hydrate Program funds reservoir characterization studies across eastern offshore acreage. Mumbai-Pune industrial corridor supplies simulation modeling expertise for geomechanical sediment analysis.
South Korea
Research institutions survey the Ulleung Basin where confirmed hydrate deposits remain underpenetrated by commercial extraction trials. South Korea's Ministry of Trade, Industry and Energy funds deepwater robotics development for autonomous monitoring applications. Busan-Ulsan shipbuilding cluster fabricates specialized drilling vessel components for frontier basin deployment.
Methane Hydrate Extraction Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the methane hydrate extraction landscape. Integrated energy majors and national oil companies dominate committed capital deployment, while specialized service providers supply subsea technology and simulation modeling capabilities. Three archetypes define competitive positioning: reservoir characterization specialists, subsea equipment fabricators, and integrated pilot program operators. Capacity expansion through multi-year framework agreements and technology licensing partnerships constitute the dominant competitive moves as procurement consolidates around national entities.
Among integrated energy majors, Schlumberger Limited exemplifies the subsea technology archetype through its deepwater pilot program anchoring, while BP p.l.c. occupies a position representing specialized simulation modeling capabilities that reduce reservoir uncertainty. Japan Petroleum Exploration Co., Ltd. and INPEX Corporation sit within the national champion tier, leveraging METI research funding to validate extraction protocols in the Nankai Trough. PetroChina Company Limited anchors the state-backed operator archetype, consolidating drilling campaign procurement across South China Sea frontier blocks.
| Leading Market Players |
|---|
| Schlumberger Limited |
| BP p.l.c. |
| ConocoPhillips Company |
| Equinor ASA |
| PetroChina Company Limited |
| Japan Petroleum Exploration Co., Ltd. |
| INPEX Corporation |
| Oil and Natural Gas Corporation Ltd. |
| ExxonMobil Corporation |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed national oil companies and METI-funded research consortia anchor capital deployment across Pacific Rim hydrate provinces, concentrating procurement leverage and compressing vendor margins through multi-year framework agreements. This ownership pattern tightens pricing discipline on subsea equipment suppliers while rewarding integrated service providers with volume commitments that lock out mid-cap competitors.
Pricing Analysis
Bundled pilot-program contracts dominate over unbundled component sales, with Japan's JOGMEC and China's CNOOC preferring single-source procurement that wraps drilling vessels, wellhead systems, and monitoring equipment into unified project pricing. Price differentiation hinges on depressurization technology maturity and subsea robotics integration depth, with frontier basin premiums attaching to autonomous monitoring capabilities. Cost compression in surface equipment tiers is intensifying because fabrication capacity expansion in China's Shenzhen-Guangzhou cluster is eroding margin buffers. Government agencies exhibit lowest price sensitivity given sovereign funding guarantees, while private energy companies face capital discipline that elevates sensitivity to unit-economics thresholds.
Supply Chain Analysis
Specialized subsea equipment supply rests on Japanese precision engineering houses, South Korean shipbuilding clusters, and U.S. Gulf Coast drilling vessel operators. Critical inputs include high-pressure blowout preventers, autonomous underwater vehicle systems, and geomechanical simulation software licenses. Single-source vulnerability concentrates in subsea wellhead assemblies where hydrate-specific testing protocols remain project-specific rather than standardized. Distribution runs through national procurement frameworks that bypass traditional oilfield service channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The methane hydrate extraction market reads as a late-cycle quality story where capital allocation favors operators with validated depressurization protocols and integrated carbon capture positioning. Demand is shifting toward premium specifications for autonomous subsea monitoring systems that reduce operational risk premiums in deepwater environments.
For Market Incumbents: To counter margin compression from procurement consolidation around national entities, deepen backward integration into subsea robotics manufacturing and secure dual-certification against Japan METI and China Ministry of Natural Resources monitoring standards. Anchor capacity in the Nankai Trough through multi-year framework agreements that preempt competitor access to METI research funding streams. For New Entrants and Emerging Players: Launch via technology licensing partnerships targeting India's Krishna-Godavari basin where production-sharing contract reforms are opening frontier blocks to international joint ventures. The Ulleung Basin offers most penetrable geography given confirmed hydrate deposits and absence of incumbent drilling campaigns. Lead with CO2 injection swap technology to capture regulatory credit eligibility under emerging carbon accounting frameworks. For Investors and Strategic Acquirers: Valuations sit cheapest among reservoir simulation specialists with hydrate-specific geomechanical modeling expertise concentrated within academic spin-outs and national laboratory partnerships. Long-term viability frames around commercial-scale production validation within a five-to-ten year window rather than near-term cash flow generation. Watch Japan's Agency for Natural Resources and Energy for mandatory carbon intensity threshold adoption as the inflection signal that would reshape project feasibility assessments across all active hydrate provinces.| Strategic Initiative | Industry Significance |
|---|---|
| Depressurization Technology Licensing | Japan METI validation protocols create transferable asset value across Pacific Rim frontier basins. |
| Subsea Robotics Manufacturing Scale-Up | Shenzhen-Guangzhou industrial cluster enables cost positioning against Japanese precision competitors. |
| Carbon Capture Integration Partnership | Dual-revenue stream architectures from CO2 injection swap technology attract sovereign-backed capital. |
| Reservoir Simulation Talent Acquisition | Geomechanical modeling scarcity concentrates value capture within specialized academic partnerships. |
| Multi-Year Framework Agreement Consolidation | JOGMEC and CNOOC procurement patterns favor integrated service providers with cross-border certification. |
Study Parameters
Multiple input streams — executive interviews with subsea engineering directors, regulatory affairs leads at Japan's METI and China's Ministry of Natural Resources, and procurement officers at national oil companies — were reconciled against secondary validation from BOEM environmental impact filings, Japan Agency for Natural Resources and Energy permitting databases, and IEA unconventional gas technology roadmaps. Bottom-up project pipeline assessment and top-down sovereign funding allocation analysis were triangulated to anchor volume estimates.
Historical deployment patterns across the Nankai Trough and South China Sea pilot programs were cross-referenced against expert panel input on commercialization timeline compression. Segmentation dimensions modeled span extraction methodology, application type, and end-user procurement archetype, with regional regulatory framework clusters as an industry-specific overlay. CAGRs were derived from funding commitment trajectories and technology maturation curves rather than simple extrapolation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under uncontrolled methane release incidents or abrupt shale gas price collapses that divert R&D capital. A small set of triggers — mandatory carbon intensity thresholds, equipment certification protocol standardization, and thermal stimulation cost breakthroughs — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Land Drilling Rig Market
Oil & Gas
Chad Oil and Gas Upstream Market
Oil & Gas
South America Intelligent Pigging Market
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
Crude Oil Carriers Market
Oil & Gas
Europe Seismic Services Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Oil and Gas Logistics Market
Oil & Gas
North America Frac Sand Market
Oil & Gas
Asphaltene Inhibitors Market
Oil & Gas
North America Seismic Services Market
Oil & Gas
Oil & Gas Defoaming Separator Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
United States Artificial Lift Systems Market
Oil & Gas
Nigeria Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Security Services Market