
 Saudi Arabia Liner Hanger System Market | 2026-2036
Saudi Arabia Liner Hanger System Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Liner Hanger System Market Analytics
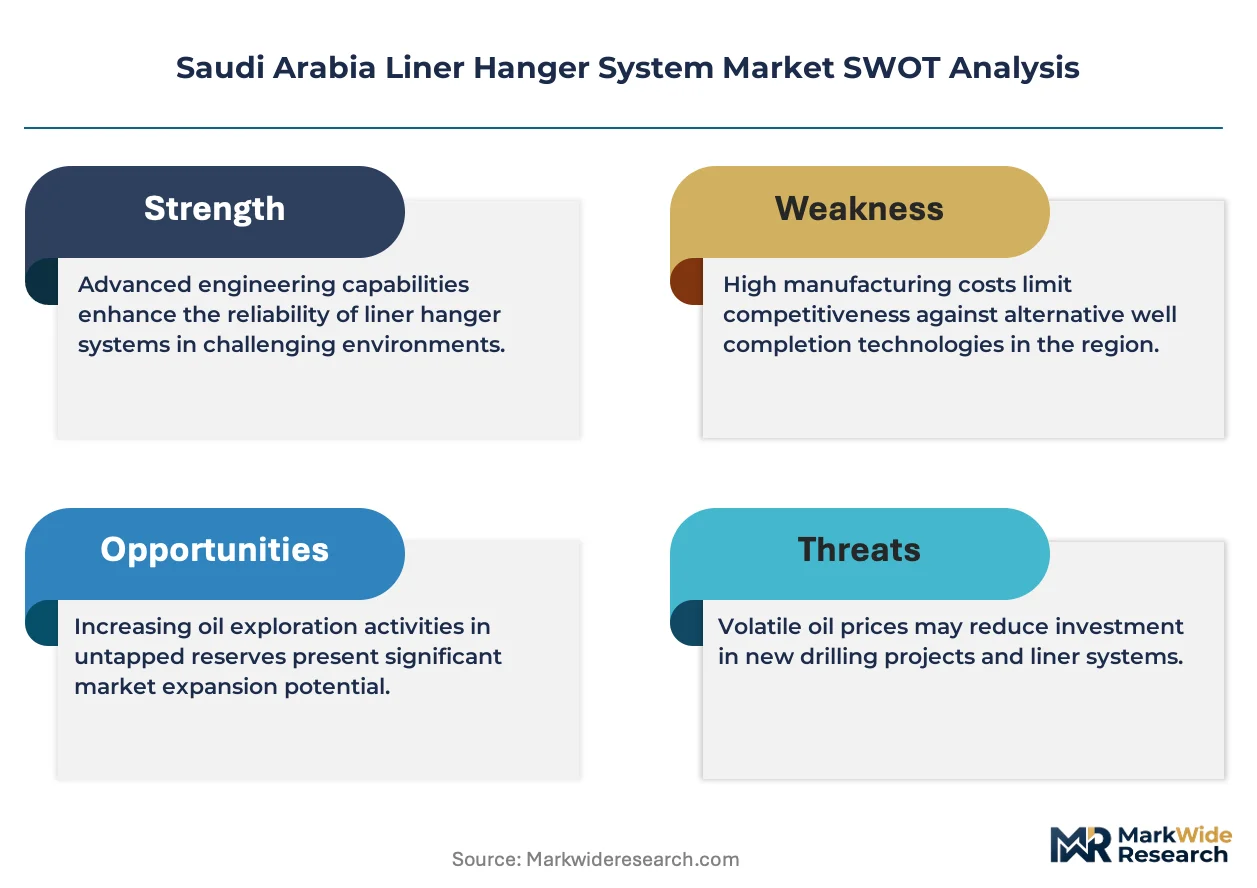
SFDA technical standards for downhole equipment is broadening the cost-of-entry calculus for new suppliers entering the Saudi market. Baker Hughes Company leverages its integrated manufacturing footprint to sustain pricing power across mechanical and hydraulic product lines. Halliburton Company anchors its position through deep relationships with national oil company procurement channels. Weatherford International plc differentiates via specialized offshore installation capabilities tailored to Arabian Gulf conditions.
A liner hanger system is a mechanical or hydraulic downhole tool that suspends and seals casing or liner strings within a wellbore, typically rated for pressures exceeding 10,000 psi and temperatures above 150°C, enabling zonal isolation and wellbore integrity during completion and production operations. Mechanical liner hangers retain dominant share due to proven reliability in high-pressure Saudi carbonate reservoirs, while hydraulic systems capture expanding share in extended-reach offshore wells where setting precision reduces non-productive time. Well completion applications generate the deepest margin pools as operators prioritize gas-tight seal integrity in sour service environments.
SFDA and SASO frameworks enforce material traceability and pressure-equipment conformity, compelling vendors to maintain accredited quality management systems for market access. The Saudi Aramco engineering standard SAES and international API specifications create layered compliance requirements that filter out uncertified competitors. Stakeholders must monitor evolving in-country value mandates and localization thresholds that will reshape supplier qualification criteria and sourcing strategies.
Market Dynamics
SFDA material certification mandates and Saudi Aramco's offshore expansion are compressing supplier qualification timelines while elevating technical performance thresholds for downhole pressure equipment.
Growth Catalysts
- Offshore drilling intensification:Saudi Aramco's Arabian Gulf campaigns require premium liner hanger assemblies rated for high-pressure sour service, pulling advanced hydraulic systems into development plans.
- SFDA technical standards:The Saudi Food and Drug Authority's downhole equipment protocols are filtering uncertified competitors, concentrating procurement among accredited quality management system holders.
- Eastern Province field density:Ghawar and Safaniya reservoir complexes anchor installation activity, creating sustained demand pull for gas-tight mechanical liner hanger configurations.
Market Restraints
- Alloy steel input volatility:Specialty metallurgy for high-temperature hangers faces price pressure from nickel and chromium supply concentration in limited smelter geographies.
- SASO conformity assessment costs:The Saudi Standards, Metrology and Quality Organization's pressure-equipment certification imposes multi-year compliance timelines that freeze marginal suppliers out of qualification pipelines.
- Mechanical hanger lock-in:Proven reliability in carbonate reservoirs creates switching friction against hydraulic alternatives despite their precision advantages in extended-reach wells.
Strategic Opportunities
- Red Sea unconventional testing:Frontier basin appraisal programs will trial liner hanger systems in HPHT conditions distinct from Eastern Province carbonate profiles.
- In-country value mandates:Localization thresholds in Saudi Aramco procurement are forcing joint venture structures that transfer assembly capability to domestic manufacturing zones.
- Digital twin integration:Real-time downhole monitoring convergence with hanger system design is enabling predictive maintenance contracts that unbundle hardware from service revenue.
Industry Challenges
- API-SAES dual compliance:Layered conformance to American Petroleum Institute specifications and Saudi Aramco engineering standards stretches engineering validation cycles.
- Specialized installation crews:Offshore hanger running in Arabian Gulf conditions demands certified personnel pools that outstrip current training program throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Liner Hanger System Market |
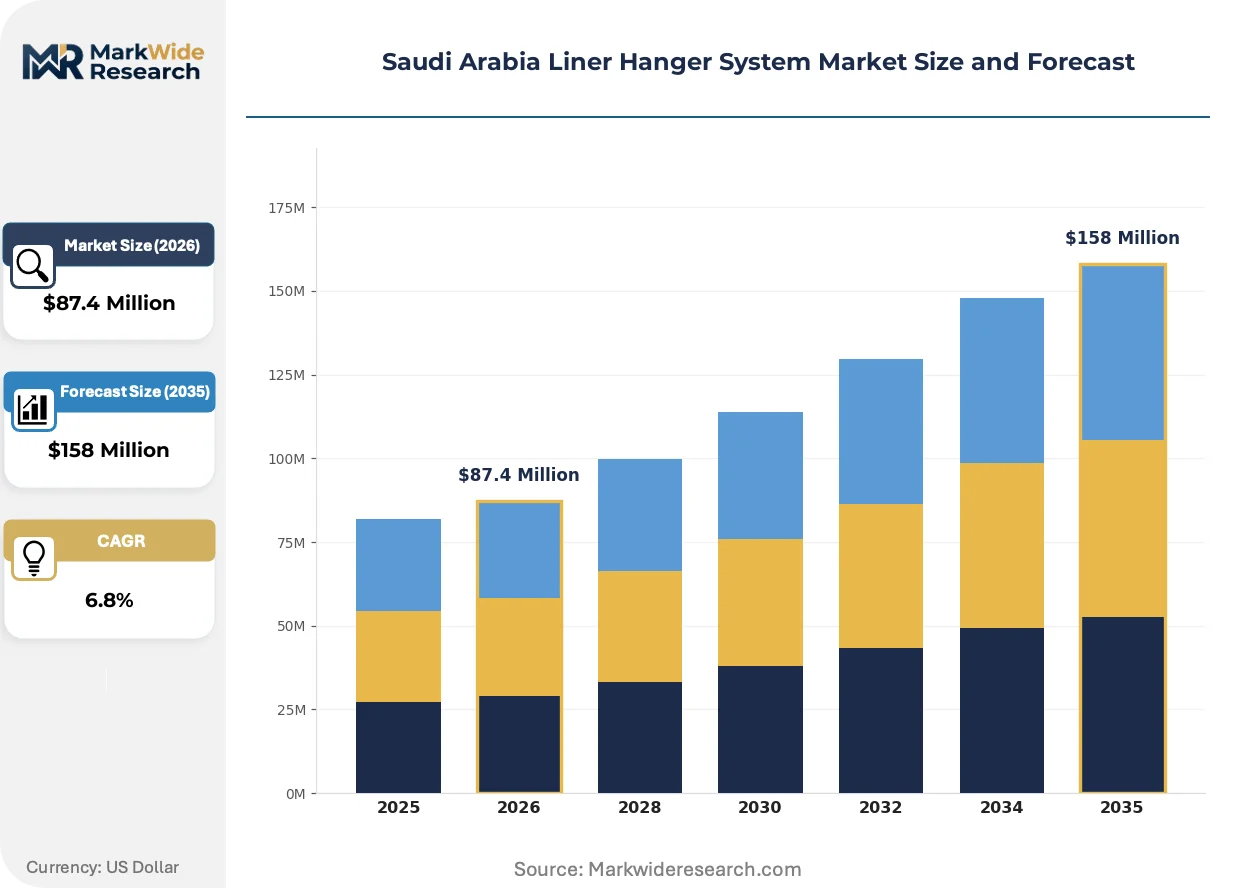
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Hydraulic, Electric, Composite Installation Type: Onshore, Offshore, Subsea, Surface End User: Oil & Gas, Water Well, Geothermal, Mining Application: Well Completion, Drilling, Production, Intervention |
| Companies Covered | Weatherford International plc, NOV Inc., Halliburton Company, SCM Daleel, Allamon Tool Company Inc., Schlumberger Limited, National-Oilwell Varco, Inc, Tianjin Elegant Technology, Baker Hughes Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Liner Hanger System Market Evolving Landscape
Material traceability requirements and precision-setting technologies are restructuring how liner hanger systems are engineered, certified, and deployed in Saudi Arabia's high-pressure reservoirs.
Intelligent liner hanger systems incorporating fiber-optic sensing are converging with automated well construction platforms. Saudi Aramco's offshore drilling units are piloting these configurations in Safaniya field extensions. The convergence is compressing non-productive time during liner installation while generating continuous wellbore integrity data streams.
SFDA and SASO frameworks are tightening material traceability mandates for pressure-containing downhole equipment. Manufacturers must now maintain accredited quality management systems with batch-level documentation. Well completion applications face the steepest compliance burden, as sour service ratings require enhanced metallurgical certification.
Service contract unbundling is separating hardware procurement from installation and maintenance obligations. National oil company procurement channels are fragmenting vendor relationships across specialized service providers. This pattern concentrates most visibly in offshore campaigns where precision-running capabilities command premium positioning independent of equipment sourcing.
Saudi Arabia Liner Hanger System Market Segmentation
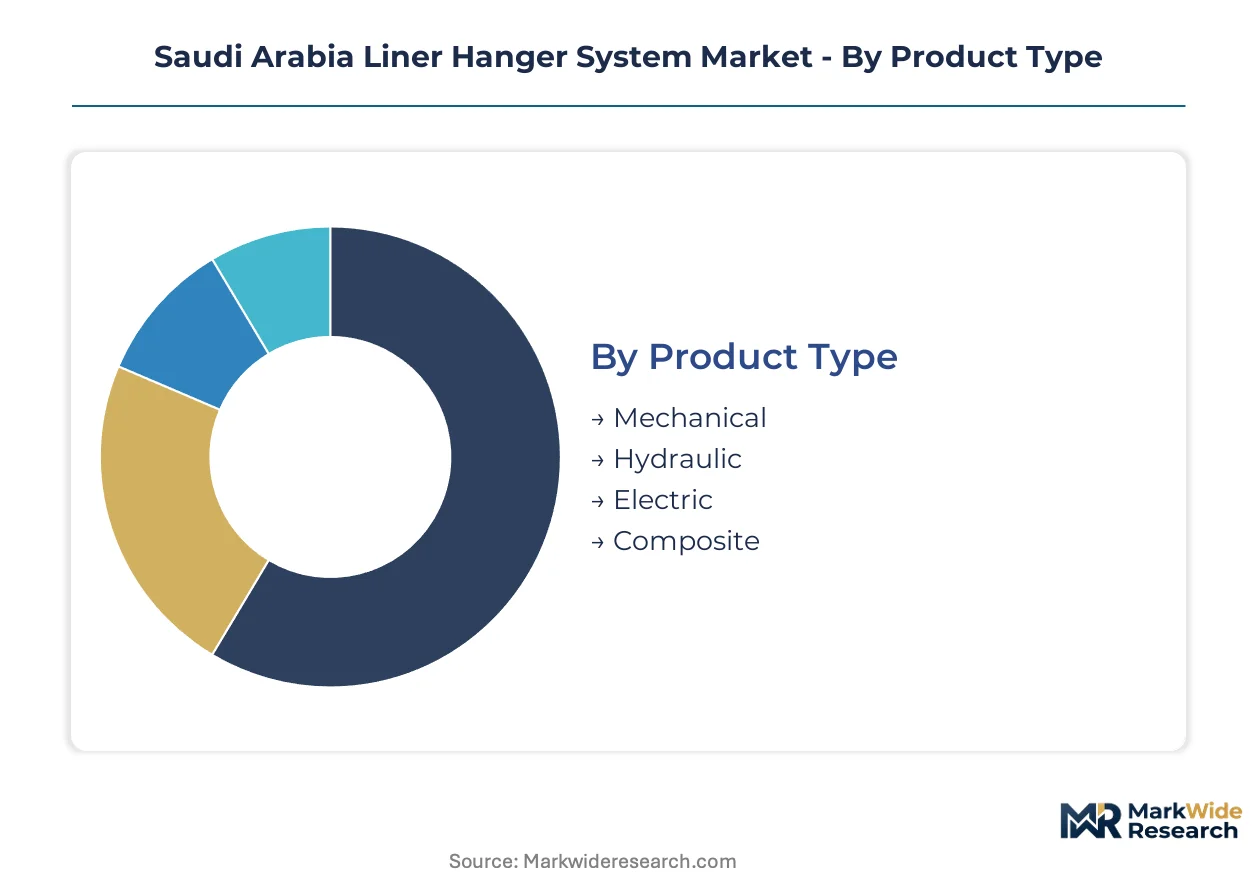
Liner hanger system procurement in Saudi Arabia fragments across pressure rating requirements, reservoir depth profiles, and installation environment complexity. Each segmentation dimension carries distinct compliance burdens and margin structures that reshape vendor positioning.
Product Type:
Mechanical systems anchor volume demand through proven reliability, while hydraulic configurations capture premium positioning in precision-critical applications.
- Mechanical:Spring-loaded slips and cone assemblies activate through pipe rotation or weight-set mechanisms rated for pressures exceeding 10,000 psi. Ghawar and Safaniya field operators specify these for carbonate reservoir completions where gas-tight seal integrity overrides setting precision requirements.
- Hydraulic:Pressure-actuated setting tools enable remote deployment in extended-reach laterals where mechanical manipulation risks casing damage. Saudi Aramco's Arabian Gulf offshore campaigns pull these into development plans for sour service environments demanding exact landing depth control.
- Electric:Surface-controlled electromechanical actuation eliminates hydraulic fluid compatibility concerns in HPHT wellbores.
- Composite:Non-metallic structural elements reduce weight for mobilization efficiency in remote desert drilling locations.
Today's leader: Mechanical. Tomorrow's challenger: Hydraulic.
Installation Type:
Onshore deployment dominates unit economics through field density advantages, yet offshore specifications concentrate the deepest margin pools.
- Onshore:Eastern Province drilling corridors enable rapid rig-to-well logistics chains that compress mobilization costs for standard mechanical hanger configurations.
- Offshore:Arabian Gulf platform and jack-up operations require corrosion-resistant metallurgy and precision-running crews certified for marine crane operations. These installations face the steepest SFDA material traceability mandates given pressure-equipment failure consequences.
- Subsea:Mudline suspension systems rated for seabed pressures anchor frontier Red Sea appraisal programs.
- Surface:Conventional wellhead-integrated hangers serve shallow conventional development in established producing regions.
Onshore installations generate volume scale. Offshore specifications command pricing power.
End User:
National oil company procurement channels concentrate demand concentration, while emerging segments reshape qualification requirements.
- Oil & Gas:Saudi Aramco's engineering standards SAES layer atop API specifications to filter supplier pools. Well completion teams prioritize gas-tight seal verification in sour service carbonate reservoirs.
- Water Well:Municipal groundwater extraction programs specify lower-pressure mechanical hangers with simplified metallurgical certification.
- Geothermal:Temperature-rated elastomer and metal seal combinations face emerging trial applications in the Kingdom's renewable energy diversification.
- Mining:Mineral exploration boreholes deploy stripped-down hanger configurations without production-grade pressure ratings.
Hydrocarbon extraction anchors revenue concentration. Geothermal applications present qualification pathway expansion.
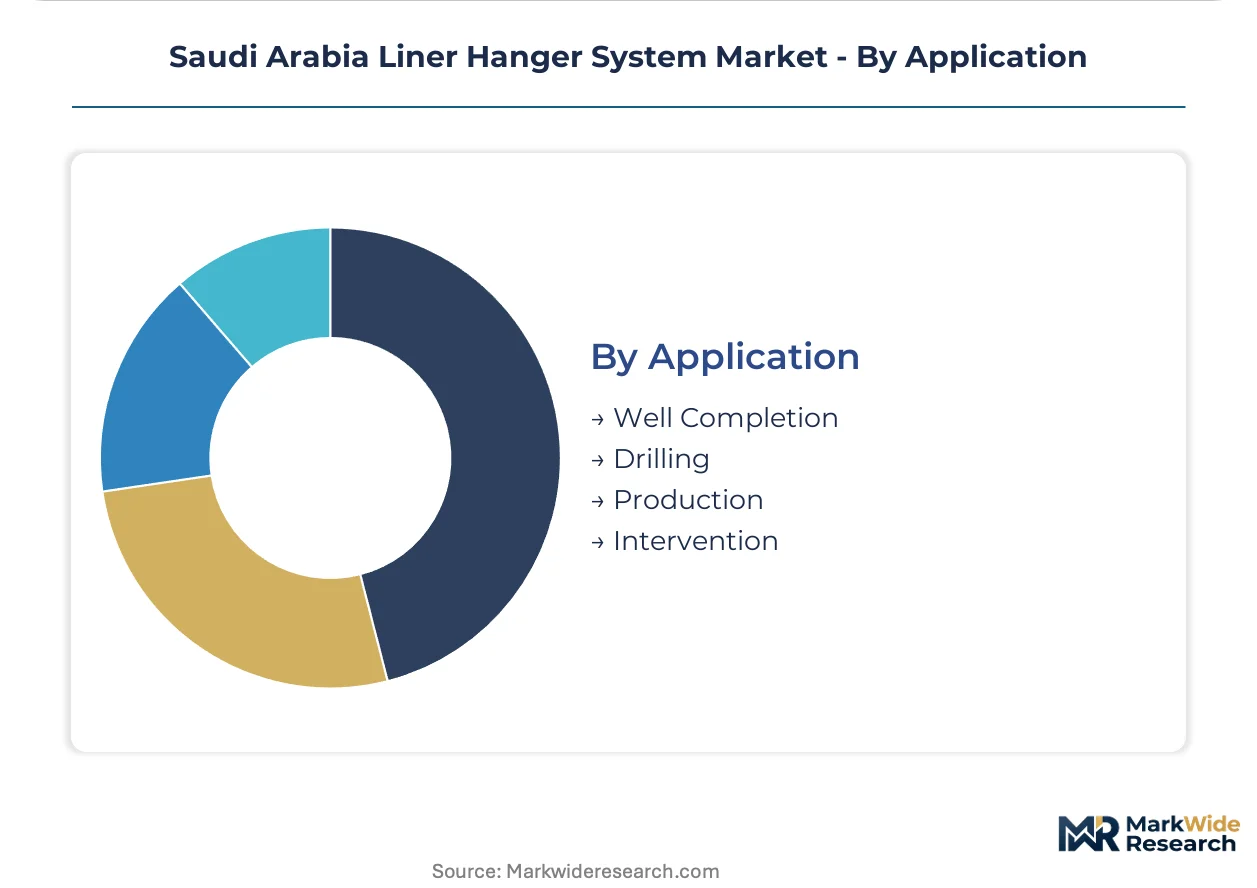
Application:
Completion-phase deployment concentrates technical specification complexity, while drilling-phase applications prioritize speed-to-depth.
- Well Completion:Final zonal isolation demands gas-tight seal integrity verified through pressure testing protocols. Sour service ratings require enhanced metallurgical certification that extends SASO conformity assessment timelines.
- Drilling:Intermediate casing suspension enables continued bit progression through unstable formations. Extended-reach laterals in offshore campaigns pull hydraulic precision-setting systems into drilling-phase deployment.
- Production:Tubing hanger integration with artificial lift equipment requires thermal cycling resistance in thermal EOR applications.
- Intervention:Through-tubing retrievable systems enable workover access without full well suspension.
Completion applications concentrate margin depth. Drilling applications drive volume velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized drilling crews and liner hanger installation technicians concentrate in the Eastern Province, where Ghawar and Safaniya field density creates sustained demand pull for downhole pressure equipment expertise.
Eastern Province
Ghawar and Safaniya reservoir complexes anchor the bulk of liner hanger installation activity, with gas-tight mechanical configurations dominating carbonate well completions. SFDA material traceability mandates filter procurement toward accredited quality management system holders. Dammam and Al-Khobar industrial zones host service company bases supporting rapid mobilization to drilling corridors.
Riyadh
Administrative headquarters of Saudi Aramco concentrate procurement decision-making and engineering standard development for SAES specifications. SASO conformity assessment bodies maintain certification facilities for pressure-equipment validation. King Salman Energy Park manufacturing investments are localizing assembly capability for in-country value compliance.
Western Region
Red Sea frontier basin appraisal programs are testing liner hanger systems in HPHT conditions distinct from Eastern Province profiles. NEOM development corridors are attracting service company infrastructure for unconventional exploration support. Yanbu industrial city hosts metallurgical processing facilities supplying specialty alloy components.
NEOM Northwest
Renewable energy diversification initiatives are piloting geothermal applications for temperature-rated elastomer and metal seal combinations. The zone's regulatory sandbox framework is streamlining equipment trial protocols for emerging energy segments. Tabuk logistics hubs are positioning for frontier basin supply chain reach.
Saudi Arabia Liner Hanger System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across mechanical and hydraulic product lines, creating a tiered structure where integrated manufacturing footprints command pricing power. The vendor base separates into three archetypes: global oilfield service conglomerates with full-spectrum portfolios, regional specialists with offshore installation expertise, and emerging domestic assemblers leveraging localization mandates. Consolidation pressures favor M&A activity targeting complementary installation capabilities, while joint venture formations address in-country value thresholds reshaping supplier qualification criteria.
Among global oilfield service conglomerates, Baker Hughes Company and Halliburton Company exemplify archetypes sustaining market presence through integrated manufacturing and procurement channel relationships. Weatherford International plc occupies a specialist position with offshore installation capabilities tailored to Arabian Gulf conditions. These three anchors represent competitive positioning vectors—manufacturing scale, channel depth, and technical specialization—through which market access concentrates.
| Leading Market Players |
|---|
| Weatherford International plc |
| NOV Inc. |
| Halliburton Company |
| SCM Daleel |
| Allamon Tool Company Inc. |
| Schlumberger Limited |
| National-Oilwell Varco, Inc |
| Tianjin Elegant Technology |
| Baker Hughes Company |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers and private-equity-rolled-up specialists dominate Saudi Arabia's liner hanger system supply base, compressing procurement timelines while enforcing disciplined pricing tiers that reward accredited quality management system holders and penalize uncertified entrants facing SASO conformity assessment delays.
Pricing Analysis
The bundled-vs-unbundled service split separates hardware procurement from precision-running contracts, with offshore Arabian Gulf campaigns commanding premium positioning for installation capabilities independent of equipment sourcing. Three-tier pricing structure across premium, standard, and economy levels stratifies by SFDA certification grade and sour service metallurgical ratings, with completion-phase applications showing least price sensitivity due to gas-tight seal integrity requirements. Cost compression in mechanical hanger tiers is intensifying because alloy steel input volatility feeds through nickel and chromium supply concentration. Drilling-phase buyers exhibit highest price sensitivity as intermediate casing suspension prioritizes speed-to-depth over precision-setting features.
Supply Chain Analysis
Saudi Aramco's in-country value mandates are reshaping sourcing toward domestic manufacturing zones at King Salman Energy Park and Dammam industrial corridors. Specialty metallurgy draws from Germany, Japan, and USA for high-temperature alloy components, while precision machining equipment feeds from South Korea and Taiwan. Single-source vulnerability concentrates in nickel-chromium smelter geographies outside GCC reach. Distribution runs through Saudi Aramco's centralized procurement channels with engineering standards SAES layering atop API specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's liner hanger system market functions as a regulatory compounder where SFDA material certification mandates and SASO pressure-equipment protocols continuously elevate technical performance thresholds, compressing supplier qualification timelines while sustaining demand pull from offshore drilling intensification.
For Market Incumbents: Extend manufacturing footprint integration into domestic assembly zones at King Salman Energy Park to satisfy localization thresholds reshaping Saudi Aramco procurement criteria. Deepen relationships with national oil company engineering standard development teams to anchor SAES specification influence ahead of Red Sea frontier basin trials. Certify additional installation crews for offshore precision-running capabilities before specialized personnel pools face capacity constraints. For New Entrants and Emerging Players: Enter via joint venture structures with established service bases in Dammam and Al-Khobar industrial zones, leveraging existing logistics chains for rapid mobilization to Eastern Province drilling corridors. Target geothermal applications in NEOM Northwest as the most penetrable segment, where renewable energy diversification initiatives pilot temperature-rated elastomer combinations with streamlined trial protocols. Pursue digital twin integration partnerships with automated well construction platforms as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with offshore installation expertise but limited manufacturing scale, offering asymmetric upside from service contract unbundling trends. Long-term viability hinges on sustained Saudi Aramco offshore campaign commitments and successful Red Sea HPHT field validation. Watch for in-country value mandate threshold adjustments as the critical inflection indicator for domestic assembly capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Joint Venture | Localization thresholds in Saudi Aramco procurement compel assembly transfer to King Salman Energy Park zones. |
| SFDA Quality Management System Certification | Accredited documentation protocols filter uncertified competitors from pressure-equipment procurement channels. |
| Offshore Installation Crew Certification | Arabian Gulf precision-running capabilities command premium positioning independent of hardware sourcing. |
| Digital Twin Integration Partnership | Predictive maintenance contracts unbundle hardware revenue from continuous wellbore integrity data streams. |
| Red Sea HPHT Field Validation | Frontier basin appraisal programs trial liner hanger systems in conditions distinct from Eastern Province carbonates. |
Research Methodology
Multiple input streams — primary interviews with drilling engineers and completion specialists, secondary validation through Saudi Aramco engineering standards documentation, and customs data on specialty alloy component imports — were reconciled to construct segment-level demand estimates. Stakeholder consultations included procurement officers at national oil company headquarters, service company base managers in Dammam industrial zones, and metallurgical certification auditors at SASO conformity assessment bodies. Secondary sources encompassed API specification databases, SFDA technical standard filings, and pressure-equipment import manifests. Bottom-up installation activity tallies from Ghawar and Safaniya field operators were cross-checked against top-down Saudi Aramco capital expenditure disclosures.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling liner hanger system demand by product type, installation environment, application phase, and end-user category. Segment-level growth trajectories derived from drilling campaign intensity projections, regulatory compliance timeline assumptions, and localization threshold evolution patterns. Industry-specific forecast inputs incorporated Saudi Aramco offshore rig deployment schedules and Red Sea unconventional testing program milestones.
Inputs from Saudi Aramco procurement channels and SASO certification registries were available through the study window; gaps in real-time alloy steel spot pricing and confidential joint venture negotiation terms introduce uncertainty bands around supplier margin estimates. Forecasts reflect documented assumptions regarding SFDA enforcement intensity and in-country value mandate progression. Geopolitical disruption to nickel-chromium supply corridors or abrupt shifts in Saudi Aramco drilling priorities could materially revise trajectory projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Chemical Enhanced Oil Recovery (EOR) Market
Oil & Gas
Floating Skimmer Market
Oil & Gas
Mud Mixers Market
Oil & Gas
APAC Oil and Gas Automation Market
Oil & Gas
Kuwait Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Corrosion Protection Market
Oil & Gas
Digital Twin in Oil and Gas Market
Oil & Gas
Intelligent Well Completion Market
Oil & Gas
Crude Oil Desalter and Electrostatic Dehydrator Market
Oil & Gas
North America Fracking Chemicals Market
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Middle East and Africa Coiled Tubing Market
Oil & Gas
Rig and Oilfield Mats Market
Oil & Gas
Brazil Oil and Gas Market
Oil & Gas
Liquefied Natural Gas Market
Oil & Gas
Rigless Intervention Systems Sales Market