
 Mud Logging Unit Market | 2026-2036
Mud Logging Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Mud Logging Unit Market Foresight
Market Context with Strategic Players
The Permian Basin is reconfiguring global mud logging capacity as US operators expand automated unit fleets. Schlumberger leverages integrated drilling-performance databases to anchor premium service contracts across North American shale plays. Baker Hughes competes through sensor-telemetry packages that extend real-time data streams from wellsite to remote command centers. Weatherford sustains aftermarket parts density through region-stocked depots in Texas and Oklahoma.
Technical Definition and Structural Segments
A mud logging unit is a mobile laboratory system installed at the drilling rig site that continuously analyzes drilling fluid returns, cuttings, and hydrocarbon gases to evaluate subsurface geology and detect formation pressures, typically operating at circulation rates up to 1,500 gallons per minute and temperatures exceeding 300°F. Its primary commercial purpose is to provide formation evaluation data that reduces drilling risks and optimizes casing-point decisions for operators. Automated units command the strongest margin pools as labor substitution and 24-hour continuity justify premium pricing over conventional manned cabins. Real-time systems are displacing batch-analysis configurations in offshore applications where satellite-linked data logging enables shore-based geoscience teams to direct downhole decisions without helicopter-transported personnel.
Regulatory Frame and Forward-Looking Close
The US Bureau of Safety and Environmental Enforcement mandates blowout-prevention monitoring that directly expands mud logging scope on federally leased offshore blocks, while EPA air-quality rules on drilling-site emissions push operators toward enclosed automated units with vapor-recovery systems. API RP 78 and ISO 13533 provide equipment-construction standards that shape procurement specifications for international drilling contractors. Stakeholders must weigh capital allocation between portable system mobility for fragmented onshore markets and fixed automated installations for long-term offshore development programs.
Market Dynamics
Automated sensor-telemetry integration is restructuring competitive advantage in mud logging services, as real-time data streams eliminate helicopter-dependent personnel rotations and compress decision cycles for offshore drilling contractors.
Growth Catalysts
- BSEE blowout-prevention mandates:Federal offshore leasing requirements in the United States expand continuous well monitoring scope, directly enlarging automated unit deployment on Gulf of Mexico platforms.
- Shale basin non-productive time reduction:Permian and Bakken operators deploy real-time formation evaluation to optimize casing-point decisions and minimize drilling interruptions.
- Sensor miniaturization:Advances in micro-gas chromatography and infrared spectroscopy enable portable automated units that match laboratory-grade detection thresholds at wellsite conditions.
Market Restraints
- Specialized sensor supply concentration:High-temperature gas detectors and telemetry transmitters rely on limited semiconductor fabrication capacity concentrated in East Asian foundries.
- API RP 78 compliance costs:Equipment-construction standards for hazardous-area certification impose capital-intensive redesign cycles on unit manufacturers.
- Direct formation evaluation substitutes:Logging-while-drilling (LWD) and measurement-while-drilling (MWD) tools capture overlapping geological data, compressing standalone mud logging value in certain hole sections.
Strategic Opportunities
- EPA vapor-recovery incentives:Air-quality enforcement on drilling-site emissions creates pull for enclosed automated units with integrated hydrocarbon containment systems.
- Geothermal drilling expansion:High-temperature geothermal projects in Nevada and Utah require formation pressure monitoring capabilities that automated mud logging units uniquely provide.
- Satellite-telemetry channel innovation:Low-earth-orbit data relay networks enable shore-based geoscience teams to direct offshore operations without personnel transport logistics.
Industry Challenges
- Petrophysicist skill scarcity:Interpretation of real-time chromatographic data streams requires cross-trained geoscientists conversant in both drilling operations and sensor diagnostics.
- Legacy SCADA integration friction:Automated units must interface with heterogeneous rig-control systems that lack standardized data protocols across drilling contractor fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mud Logging Unit Market |
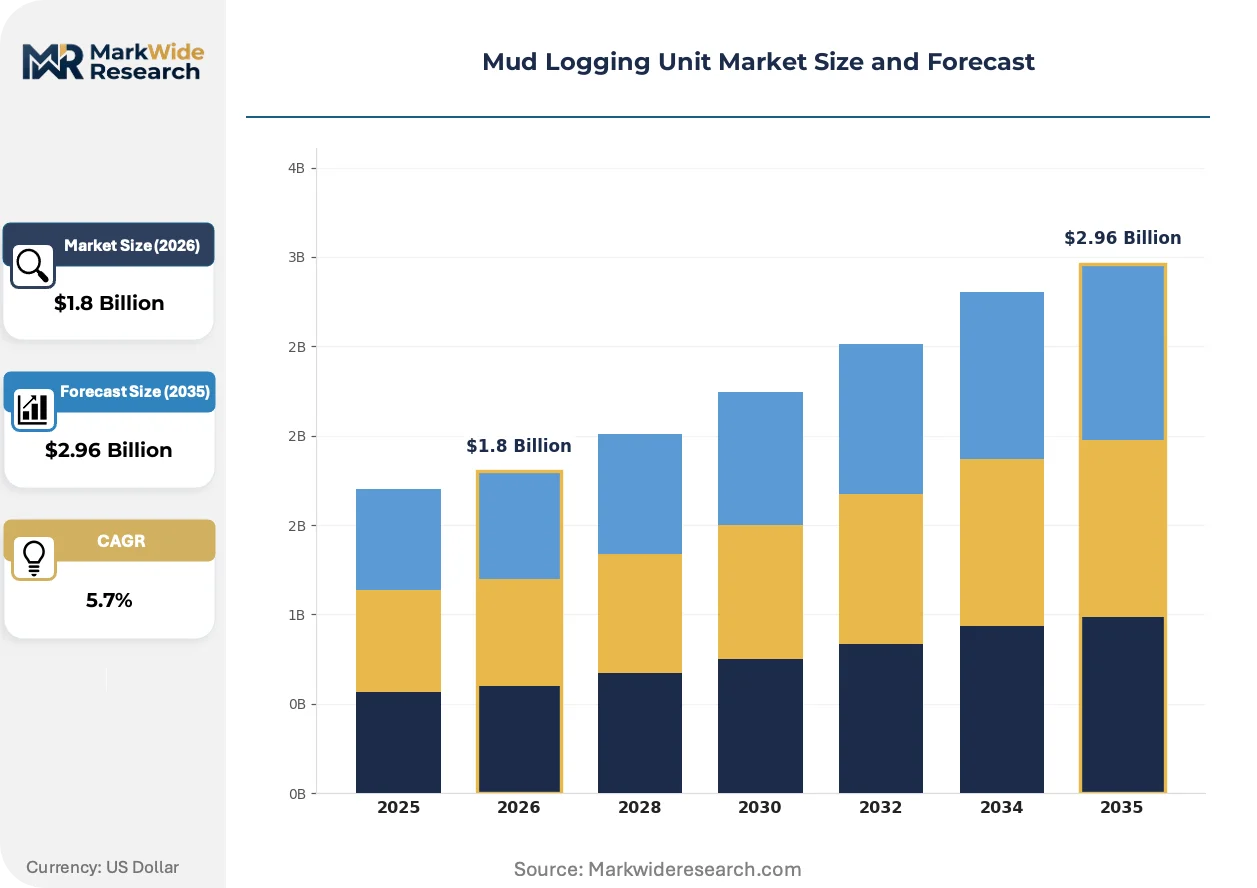
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Units, Automated Units, Portable Systems, Real-time Systems Application: Onshore Operations, Offshore Drilling, Exploration Wells, Development Wells Technology: Gas Analysis, Density Measurement, Data Logging, Geochemical Analysis End User: Oil & Gas Companies, Drilling Contractors, Service Providers, Research Institutions |
| Companies Covered | Weatherford, Rock Data Services, Schlumberger, Stratagraph, Exlog, Halliburton, Geolog International, China National Petroleum Corporation (CNPC), Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mud Logging Unit Market Shifts & Advancements
Digital thread architectures are unifying previously siloed wellsite data streams, enabling predictive formation-pressure models that anticipate kicks before conventional detection thresholds trigger alarms.
Edge-computing gas analysis is collapsing the latency between hydrocarbon detection and operator notification. Automated units now process chromatographic signatures at the wellsite rather than batch-transmitting to remote laboratories. Offshore drilling contractors in the Gulf of Mexico are adopting these configurations fastest, as satellite bandwidth constraints and personnel-reduction targets compound the value proposition. The structural consequence is collapsing reliance on helicopter-transported mud loggers for routine formation evaluation.
EPA air-quality enforcement is tightening containment requirements for drilling-site volatile organic compound emissions. The agency's New Source Performance Standards push operators toward enclosed automated units with vapor-recovery hardware. Shale operators in Texas and Oklahoma face the steepest compliance timelines, retrofitting open-air cabins or replacing them entirely with sealed systems that integrate flare-gas capture.
Service-contract unbundling is fragmenting procurement relationships that historically bundled mud logging with directional drilling and cementing services. Supermajors and large independents now source automated formation evaluation as a discrete line item, evaluating vendors on sensor-specification transparency and data-format interoperability. This pattern is most visible in the Permian Basin, where pad-drilling programs reward vendors who can standardize output across sequential wells without reconfiguration delays.
Mud Logging Unit Market Segmentation
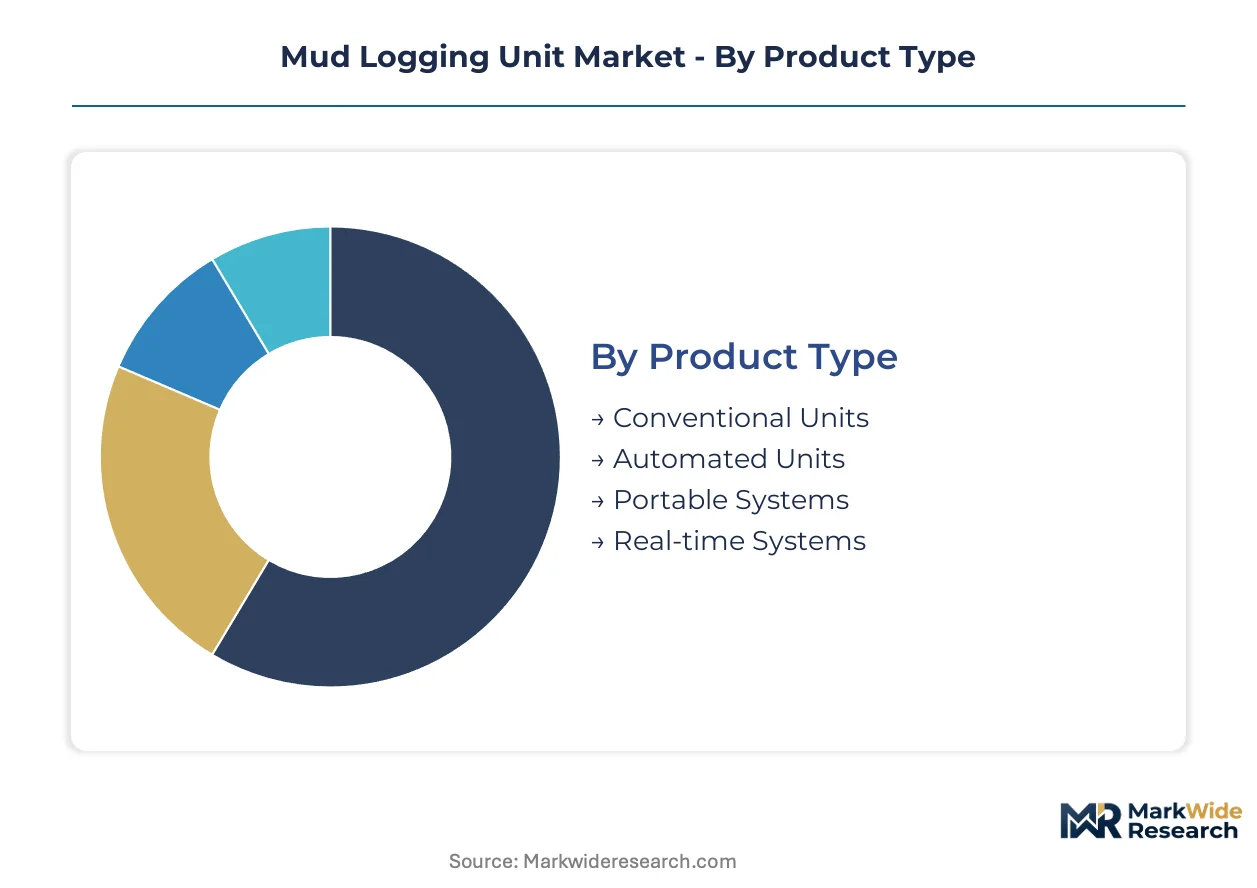
Segmentation in mud logging units reveals divergent capital intensity and replacement cycles across deployment modes. Automated configurations compress payback periods through labor substitution, while conventional manned cabins persist in marginal drilling markets with constrained capital budgets.
Product Type:
Automated units turn over fastest as sensor obsolescence drives 5-7 year replacement cycles, while conventional cabins depreciate over 12-15 years with minimal technology refresh.
- Automated Units:Enclosed laboratory systems integrate micro-gas chromatography and infrared spectroscopy for continuous hydrocarbon detection without on-site personnel. Gulf of Mexico offshore platforms deploy these configurations to satisfy BSEE blowout-prevention mandates while eliminating helicopter logistics for mud logger rotations.
- Conventional Units:Manned cabin installations rely on manual sample collection and batch chromatographic analysis by on-site geoscientists. These systems dominate legacy onshore fleets in Oklahoma and Kansas where drilling contractors prioritize capital preservation over real-time capability.
- Portable Systems:Trailer-mounted configurations enable rapid redeployment between Permian Basin pad sites without rig crane support.
- Real-time Systems:Satellite-telemetry architectures transmit formation data to shore-based command centers, collapsing decision latency for offshore drilling contractors.
Conventional units dominate installed base. Automated units are where expansion concentrates.
Application:
Development drilling absorbs equipment volume through multi-well pad programs, while exploration applications command premium pricing for specialized pressure-detection capabilities.
- Onshore Operations:Permian and Bakken shale plays drive demand for standardized automated units that sequence across sequential wells without reconfiguration delays. EPA vapor-recovery requirements in Texas and Oklahoma accelerate replacement of open-air cabins with enclosed systems.
- Offshore Drilling:Gulf of Mexico platforms require explosion-proof automated configurations with redundant gas-detection arrays and satellite telemetry for shore-based monitoring. BSEE regulations mandate continuous well monitoring that expands mud logging scope on federally leased blocks.
- Exploration Wells:Wildcat drilling in frontier basins demands portable systems with rapid mobilization for single-well campaigns.
- Development Wells:Infill drilling programs reward vendors who standardize sensor configurations across predictable geological intervals.
Onshore operations anchor equipment volume. Offshore drilling is climbing the fastest.
Technology:
Gas analysis technology commands the highest replacement frequency as detector sensitivity thresholds advance, while data logging infrastructure persists across multiple hardware generations.
- Gas Analysis:Micro-gas chromatography and infrared spectroscopy modules detect hydrocarbon species at parts-per-million thresholds under wellsite temperature extremes exceeding 300°F. Offshore contractors in the Gulf of Mexico specify these capabilities for early kick detection before conventional alarms trigger.
- Data Logging:Digital thread architectures unify chromatographic outputs with rig-control SCADA systems for predictive formation-pressure modeling. Shale operators in the Permian Basin deploy these integrations to compress non-productive time across multi-well pads.
- Density Measurement:Continuous drilling fluid density monitoring identifies formation fluid influx through annular pressure signatures.
- Geochemical Analysis:Cuttings evaluation for mineralogical composition and source-rock maturity supports exploration prospect ranking.
Data logging dominates technology deployment. Gas analysis is gaining share fastest.
End User:
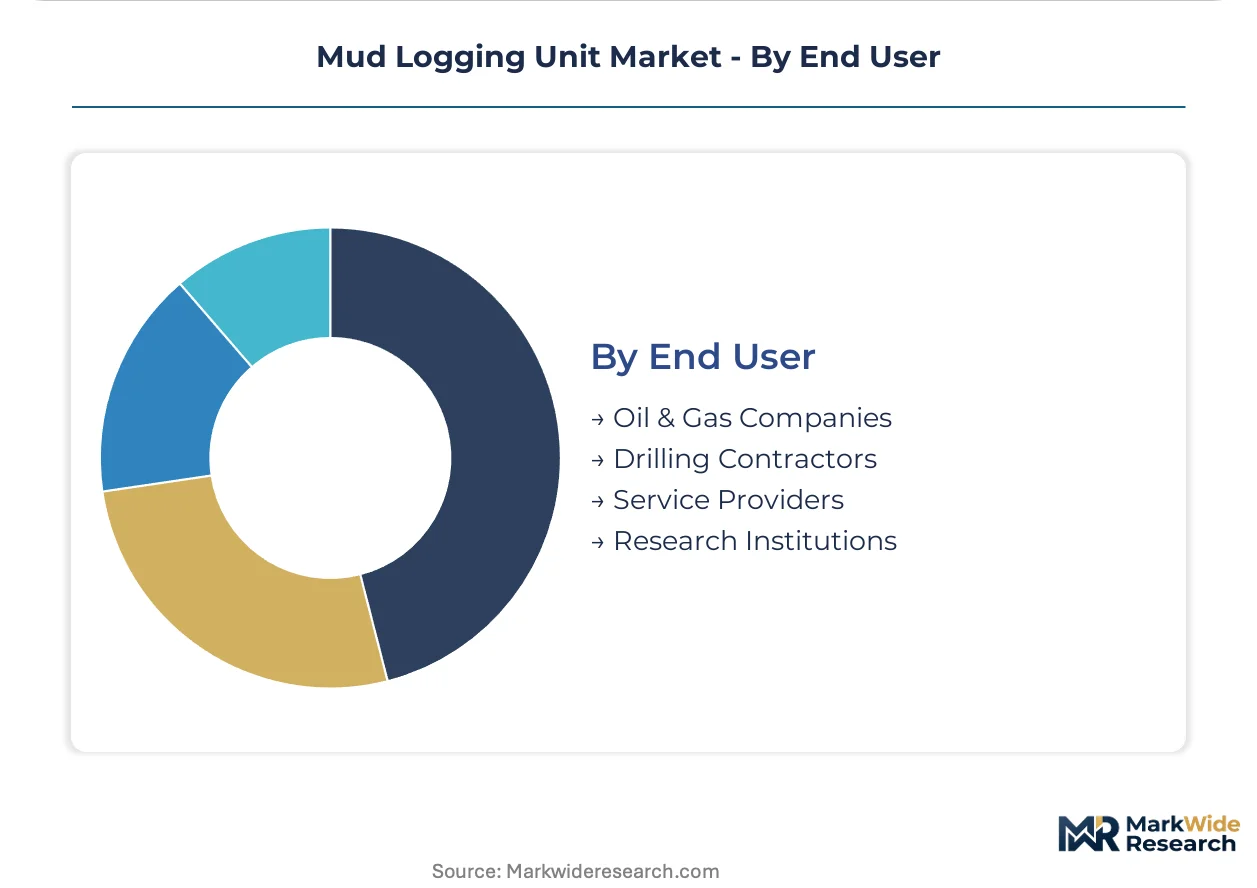
Oil and gas operators concentrate procurement authority for long-term development programs, while drilling contractors drive spot-market demand for standardized rental configurations.
- Oil & Gas Companies:Supermajors and large independents unbundle automated formation evaluation as discrete procurement line items, evaluating vendors on sensor-specification transparency and data-format interoperability. Permian Basin pad-drilling programs reward standardization across sequential wells without reconfiguration delays.
- Drilling Contractors:Nabors and Helmerich & Payne specify automated mud logging packages as bundled rig offerings to differentiate day-rate competitiveness. These contractors prioritize portable system mobility for fragmented spot-market opportunities across multiple shale basins.
- Service Providers:Schlumberger and Baker Hughes anchor premium service contracts through integrated drilling-performance databases and sensor-telemetry packages.
- Research Institutions:University geothermal programs in Nevada and Utah deploy specialized units for high-temperature formation pressure monitoring.
Oil and gas companies dominate procurement value. Drilling contractors are where rental fleet expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Offshore operators in the United States deploy automated units for regulatory compliance and personnel reduction, while onshore markets in Asia-Pacific and the Middle East retain conventional manned configurations to minimize capital outlay.
United States
Permian Basin pad-drilling programs and Gulf of Mexico offshore platforms drive divergent equipment specifications. The US Bureau of Safety and Environmental Enforcement mandates continuous blowout-prevention monitoring on federally leased blocks. Houston anchors service-provider headquarters and regional stocking depots for automated sensor-telemetry packages.
Norway
North Sea drilling contractors prioritize enclosed automated units with redundant gas-detection arrays for harsh-environment operations. The Norwegian Petroleum Safety Authority enforces well integrity standards that expand real-time formation evaluation scope. Stavanger concentrates engineering expertise for offshore automation integration.
Saudi Arabia
Onshore unconventional gas programs and Red Sea offshore exploration create dual demand streams for portable and fixed automated systems. The Ministry of Energy's In-Kingdom Total Value Add program pressures service contractors toward local manufacturing partnerships. Dhahran hosts research facilities for high-temperature sensor validation.
China
Sichuan Basin shale gas development and South China Sea deepwater projects absorb automated mud logging capacity at scale. The Ministry of Ecology and Environment enforces drilling-site emissions controls that favor enclosed vapor-recovery configurations. Tianjin manufactures telemetry hardware for domestic and export markets.
Brazil
Pre-salt offshore development programs require satellite-linked automated units for shore-based geoscience oversight. The National Petroleum Agency mandates well-control documentation that extends mud logging scope on concession blocks. Rio de Janeiro coordinates service logistics for Campos and Santos basin operations.
Mud Logging Unit Market Competitive Landscape
Capability concentration sits with integrated service conglomerates; scale advantage sits with national oil company affiliates and regional specialists. The market structures around three tiers: full-service oilfield conglomerates with bundled drilling-performance databases, pure-play mud logging specialists with sensor-telemetry expertise, and state-backed entities serving captive domestic markets. Dominant competitive moves include portfolio unbundling to capture discrete formation-evaluation contracts and geographic expansion through portable system standardization.
Within the integrated service tier, Schlumberger, Baker Hughes, and Halliburton occupy positions defined by drilling-performance data integration and sensor-telemetry scale. Schlumberger exemplifies the premium-service archetype through integrated database architectures. Baker Hughes represents the automation-forward positioning with satellite-linked command center capabilities. Halliburton anchors the diversified energy services model where mud logging sits within broader well construction portfolios.
| Leading Market Players |
|---|
| Weatherford |
| Rock Data Services |
| Schlumberger |
| Stratagraph |
| Exlog |
| Halliburton |
| Geolog International |
| China National Petroleum Corporation (CNPC) |
| Baker Hughes |
| Others |
Supply & Pricing Matrix
Houston-to-Permian Basin freight corridors transmit cost volatility from semiconductor shortages directly into automated mud logging unit pricing, while Gulf of Mexico offshore contractors absorb premium logistics expenses through long-term service contracts that lock in sensor-telemetry availability. This geographic cost architecture concentrates pricing power with integrated service providers who control regional stocking depots and captive maintenance networks.
Pricing Analysis
Long-term offtake agreements dominate offshore procurement, with Gulf of Mexico operators committing to multi-year automated unit leases that bundle sensor maintenance and satellite telemetry. Price differentiation rests on certification tier—API RP 78 hazardous-area compliance commands 15-25% premiums over standard configurations—and volume scale across multi-well pad programs. Pricing pressure stems from LWD and MWD tool substitution in certain hole sections, compressing standalone mud logging value. Drilling contractors in Oklahoma and Kansas exhibit highest price sensitivity, prioritizing capital preservation through conventional manned cabin rentals over real-time capability premiums.
Supply Chain Analysis
Export control regimes restricting high-temperature gas detector technology limit semiconductor fabrication capacity concentrated in Taiwan, South Korea, and Japan, constraining sensor module availability for automated units. Micro-gas chromatography components and infrared spectroscopy arrays draw from specialized foundries with limited alternative sourcing. Single-source vulnerability concentrates in telemetry transmitter chipsets subject to geopolitical trade restrictions. Distribution runs through Houston and Stavanger service hubs that anchor aftermarket parts density for North Sea and Gulf of Mexico operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-contract unbundling fragments procurement relationships historically bundled with directional drilling, creating discrete formation-evaluation niches for specialized vendors who standardize sensor configurations across sequential wells.
For Market Incumbents: Insulate premium positioning through integrated drilling-performance databases that anchor multi-service contracts across Permian Basin pad programs. Deepen backward integration into high-temperature sensor calibration facilities in Texas and Oklahoma to reduce East Asian foundry dependency. API RP 78 compliance investments create certification moats against regional specialists lacking hazardous-area engineering scale. For New Entrants and Emerging Players: Geothermal drilling programs in Nevada and Utah represent the most penetrable entry point, where high-temperature formation pressure monitoring requirements outstrip incumbent service density. Portable system standardization for rapid redeployment between fragmented onshore markets enables spot-market participation without fixed asset exposure. Lead with EPA vapor-recovery compliance as regulatory tailwind accelerates open-air cabin replacement timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor-telemetry specialists with satellite-linked command center capabilities over conventional manned service architectures. Long-term viability hinges on automation substitution trends that compress labor-dependent business models. Watch BSEE regulatory expansion beyond Gulf of Mexico federal leases as inflection signal for mandated monitoring scope growth.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Telemetry Integration | Edge-computing gas analysis at wellsite collapses detection-to-notification latency below satellite bandwidth constraints. |
| Vapor-Recovery Hardware Deployment | EPA New Source Performance Standards enforcement in Texas and Oklahoma accelerates enclosed unit retrofit cycles. |
| Satellite-Linked Command Centers | Low-earth-orbit data relay networks enable shore-based geoscience teams to direct offshore operations without helicopter logistics. |
| Regional Stocking Depot Expansion | Aftermarket parts density in Houston and Stavanger reduces non-productive time from sensor failure across North Sea and Gulf platforms. |
| Geothermal Formation Monitoring | High-temperature projects in Nevada and Utah require pressure detection capabilities that automated units uniquely provide. |
Research Methodology
Desk research of SEC 10-K filings from drilling contractors, API equipment certification databases, and BSEE incident reports preceded structured interviews with offshore drilling superintendents, mud logging service operations managers, and petroleum geoscientists at Permian Basin operators. Secondary validation drew from EPA enforcement actions, customs import records for gas detection equipment, and satellite telemetry provider capacity disclosures. Bottom-up unit deployment counts triangulated against top-down service revenue estimates across the analysis window.
Assumptions held fixed include BSEE regulatory scope on federally leased blocks and EPA vapor-recovery enforcement timelines in Texas and Oklahoma, while sensor miniaturization cost curves and LEO satellite bandwidth availability were varied across sensitivity scenarios. Segmentation modeling spanned product type, application, technology, and end user dimensions with regional production cluster overlays. CAGRs derived from equipment replacement cycle analysis and capital expenditure trajectories at named drilling contractors, with inputs from geothermal project development pipelines and shale basin rig counts.
Practitioners should monitor BSEE regulatory expansion to onshore federal lands and East Asian semiconductor export control tightening for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Managed Pressure Drilling Services Market
Oil & Gas
Latin America Oilfield Chemicals Market
Oil & Gas
Oil and Gas MIC Testing Market
Oil & Gas
Copper Mining Market
Oil & Gas
Global Floating LNG Terminal Market
Oil & Gas
Vacuum Gas Oil Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
Asphaltene Inhibitors Market
Oil & Gas
CO2 EOR Market
Oil & Gas
Kuwait Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Pipe Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
Swellable Packers Market
Oil & Gas
Oilfield Drilling Elevator Market