
 Southeast Asia Oil and Gas EPC Market | 2026-2036
Southeast Asia Oil and Gas EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Oil and Gas EPC Market Analytics
The premium offshore EPC tier is repositioning around subsea tieback complexity and integrated project delivery, while onshore lump-sum contracts commoditize around standardized module fabrication. Saipem leverages its subsea installation fleet to dominate deepwater assignments in Malaysian waters. Hyundai Engineering sustains cost competitiveness through captive yard capacity in Vietnam. TechnipFMC differentiates on integrated engineering-procurement interfaces for floating production systems.
The Southeast Asia Oil and Gas EPC sector encompasses the full-cycle design, material sourcing, and physical construction of hydrocarbon production, processing, and transport infrastructure, typically executed under lump-sum turnkey or cost-reimbursable contracts with performance guarantees spanning 24 to 60 months. Engineering services command margin premiums where front-end design scope includes proprietary process technology or subsea architecture. Offshore platforms represent the fastest-growing technology segment as operators push into deeper waters off Indonesia and Vietnam. LNG facilities concentrate investment in Papua New Guinea-linked developments and emerging Indonesian regasification terminals. Onshore work remains mature, with margin pools shifting toward brownfield modernization and emissions retrofit scope.
Indonesia's Ministry of Energy and Mineral Resources enforces local content thresholds that reshape contractor procurement patterns and joint-venture structures. Malaysia's PETRONAS Technical Standards and Vietnam's Ministry of Industry and Trade licensing frameworks govern platform design codes and environmental discharge limits. Thailand's Department of Mineral Fuels imposes safety audit cycles that extend project timelines. Stakeholders must weigh local partnership mandates against technology control when bidding frontier deepwater blocks.
Market Dynamics
Indonesia's tightened local content mandates are forcing contractors to restructure procurement networks and joint-venture formations, compressing margins for foreign engineering firms while creating captive demand for domestic fabrication yards.
Growth Catalysts
- Deepwater frontier expansion:Malaysian and Vietnamese operators are sanctioning subsea tieback developments in water depths exceeding 1,500 meters, requiring specialized EPC capabilities that command premium contract values.
- Upstream gas prioritization:Myanmar's Ministry of Electricity and Energy has fast-tracked offshore gas field development approvals to offset declining domestic production and reduce LNG import dependency.
- Regasification infrastructure buildout:Indonesia's state utility Perusahaan Listrik Negara is contracting multiple floating storage and regasification units to serve Java-Bali demand clusters.
Market Restraints
- Steel input cost volatility:Specialty offshore-grade plate and long-lead subsea umbilical materials face price swings tied to nickel and copper exchange fluctuations, eroding lump-sum contract margins.
- Fabrication yard concentration:Heavy structural module construction capacity clusters in Singapore and Batam, creating bottlenecks during synchronized project sanctioning waves across the region.
- Local content compliance friction:Indonesia's Ministry of Energy and Mineral Resources enforcement of TKDN thresholds adds administrative overhead and procurement restriction layers without equivalent quality certification infrastructure.
Strategic Opportunities
- Brownfield modernization scope:Thailand's Gulf of Thailand mature platforms require structural life extension and emissions retrofit work, opening recurring revenue streams distinct from greenfield project cyclicality.
- Carbon capture integration:PETRONAS has signaled pilot projects for offshore CO2 injection tied to enhanced oil recovery, creating first-mover advantage for EPCs with subsurface engineering-procurement interfaces.
- Floating LNG modularization:Standardized topsides fabrication for mid-scale FLNG units allows replication across Indonesian and Papua New Guinea developments, compressing execution timelines.
Industry Challenges
- Subsea installation vessel scarcity:Heavy-lift and pipelay asset availability constraints in Asia-Pacific waters force schedule compression and day-rate inflation during peak campaign windows.
- Cross-border certification alignment:Divergent welding procedure qualifications between Malaysia's PETRONAS Technical Standards and Indonesia's SNI codes create requalification delays for mobile fabrication teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Oil and Gas EPC Market |
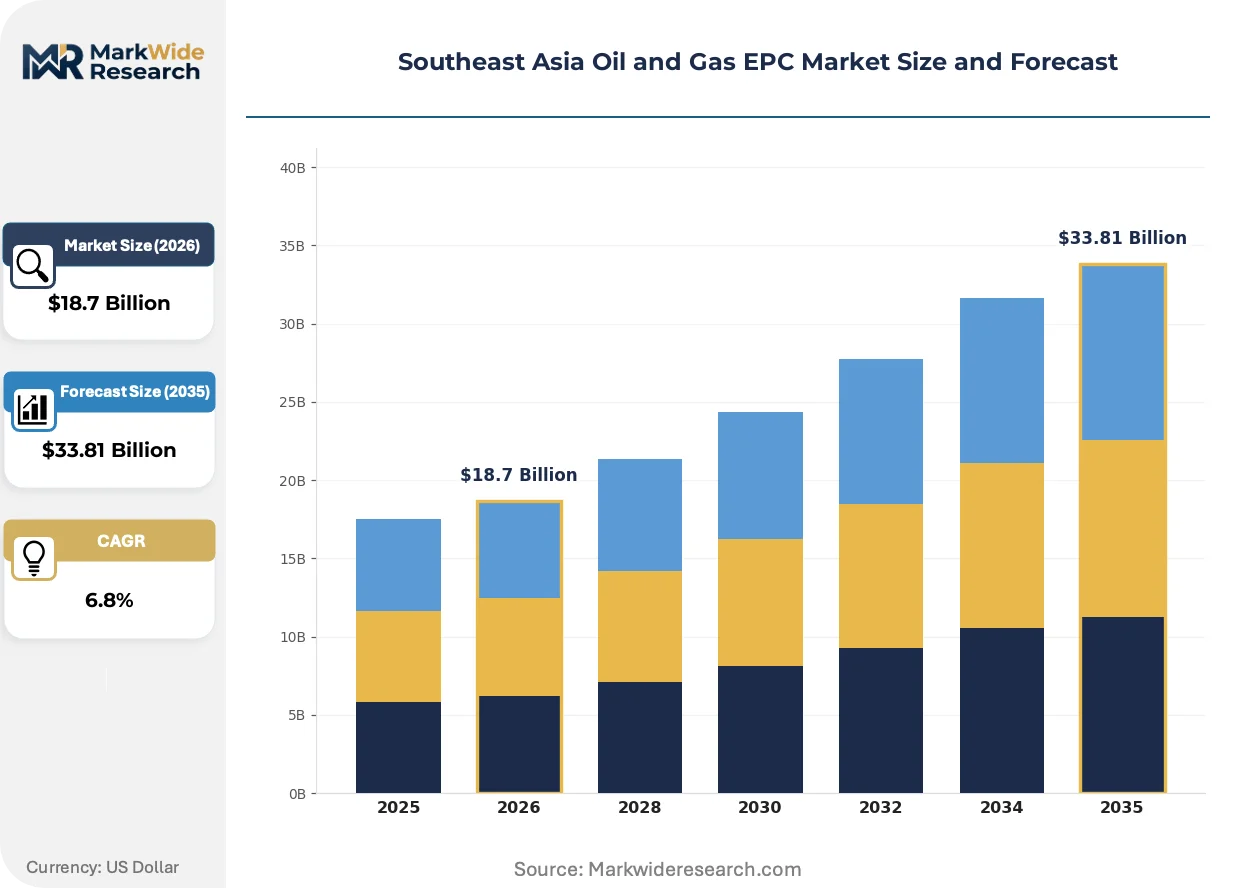
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engineering, Procurement, Construction, Project Management Technology: Pipeline, Offshore Platforms, Storage Facilities, Refineries End User: Oil Companies, Gas Producers, Contractors, Government Entities Product Type: Onshore, Offshore, Midstream, LNG Facilities |
| Companies Covered | Saipem, Petrofac Limited, TechnipFMC, Samsung Engineering, PT Barata Indonesia, Bechtel Corporation, John Wood Group, Hyundai Engineering, Fluor Corporation, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Oil and Gas EPC Market Evolving Landscape
Digital twin deployment and modular construction methods are compressing offshore project schedules while regulatory emissions frameworks reshape contracting priorities across Southeast Asian waters.
Subsea digital twin technology is integrating real-time sensor feeds with predictive maintenance algorithms for riser and flowline integrity monitoring. Malaysian deepwater operators are mandating these systems in front-end engineering designs to reduce inspection vessel callouts. The technology is integrating operational expenditure models into EPC contract structures, shifting risk allocation toward performance-based remuneration.
Indonesia's Ministry of Energy and Mineral Resources has implemented carbon intensity benchmarks for new upstream project approvals, requiring facilities to demonstrate flare minimization and electrification pathways. This policy compresses allowable project emissions profiles and favors gas over oil developments. Floating production system tenders now incorporate power-from-shore or renewable hybrid specifications, particularly for Java Sea assignments.
Buyer consolidation around integrated project delivery models is displacing fragmented engineering-procurement and construction contracting. National oil companies in Vietnam and Thailand are bundling subsea, topsides, and installation scope under single accountable contractors. This pattern concentrates risk with tier-one EPCs while marginalizing specialized subsea engineering boutiques in regional tender participation.
Southeast Asia Oil and Gas EPC Market Segmentation
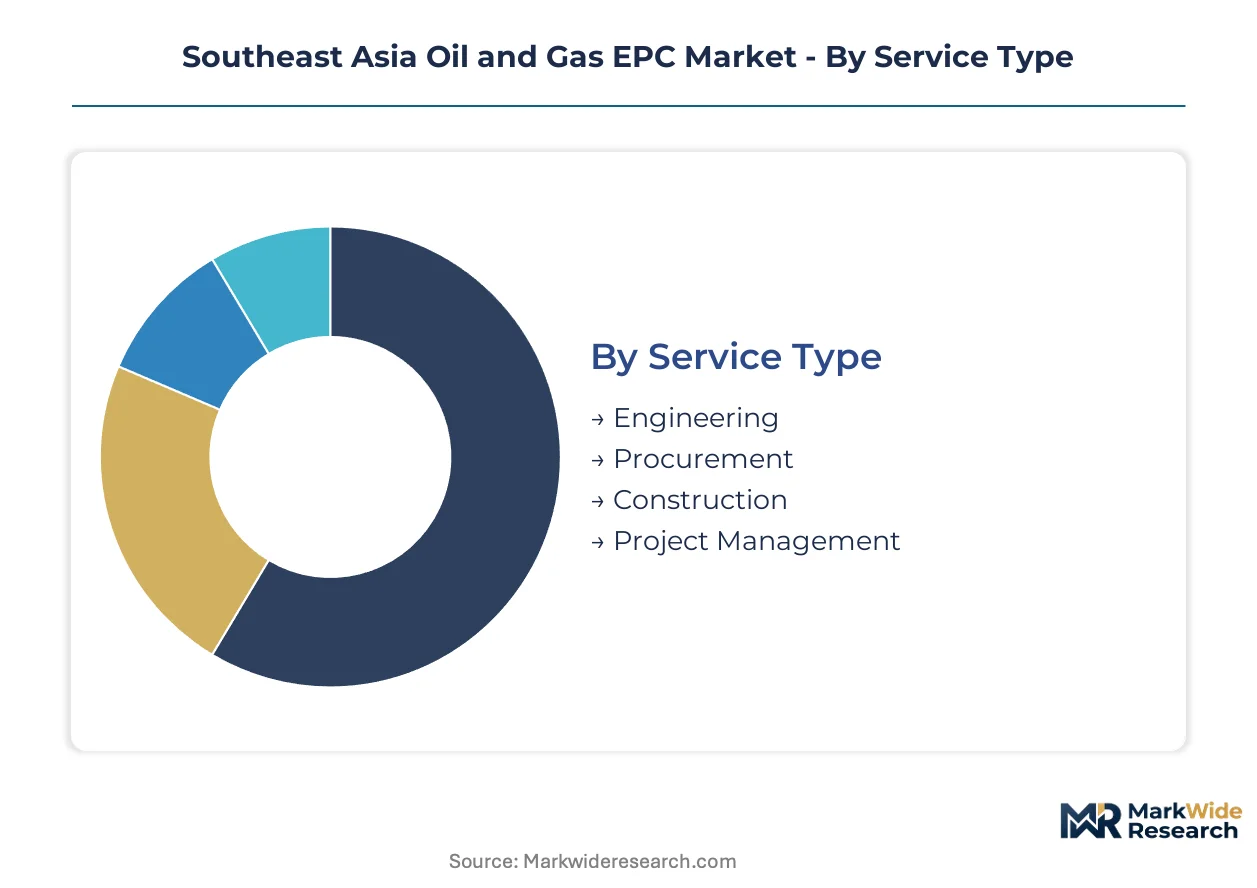
Segmentation in Southeast Asia's Oil and Gas EPC market reveals how contract structures, technology choices, and buyer types concentrate margin pools differently. Procurement patterns diverge sharply between national oil companies prioritizing local content compliance and international operators seeking integrated project delivery.
Service Type:
Contract scope decisions hinge on risk allocation preferences between lump-sum turnkey and cost-reimbursable structures.
- Engineering:Front-end design and proprietary process technology integration command premium margins where subsea architecture or floating production systems are involved. Malaysian deepwater operators mandate digital twin specifications during this phase to compress operational expenditure models into contract frameworks.
- Procurement:Long-lead subsea umbilical and specialty offshore-grade steel sourcing faces nickel and copper price volatility that erodes fixed-price contract profitability. Indonesia's TKDN thresholds force restructuring of supplier networks toward domestic fabrication yards.
- Construction:Heavy structural module fabrication clusters in Singapore and Batam, creating capacity bottlenecks during synchronized project waves across the region.
- Project Management:Integrated delivery models are displacing fragmented contracting as Vietnam and Thailand bundle subsea, topsides, and installation scope under single accountable entities.
Volume sits with Construction; growth tilts toward Engineering as front-end complexity deepens.
Technology:
Water depth and reservoir characteristics dictate technology selection, with frontier developments commanding specialized capabilities.
- Pipeline:Subsea tieback developments in Malaysian and Vietnamese waters exceeding 1,500 meters require advanced pipelay vessels and flow assurance engineering. Scarcity of heavy-lift and installation assets in Asia-Pacific waters forces schedule compression and day-rate inflation during peak campaign windows.
- Offshore Platforms:Fixed and floating production systems represent the steepest expansion trajectory as operators push into deeper waters off Indonesia and Vietnam. Carbon intensity benchmarks from Indonesia's Ministry of Energy and Mineral Resources now require flare minimization and electrification pathways in platform designs.
- Storage Facilities:Floating storage and regasification units are multiplying across Java-Bali demand clusters to offset declining domestic gas production.
- Refineries:Brownfield modernization scope in Thailand's mature downstream infrastructure focuses on emissions retrofit and structural life extension rather than greenfield construction.
Platform investments anchor current spending; pipeline infrastructure captures incremental growth from deepwater tiebacks.
End User:
Buyer consolidation around integrated delivery is reshaping how contract risk distributes across stakeholder types.
- Oil Companies:International operators in Malaysian deepwater blocks prioritize subsea installation fleet access and integrated engineering-procurement interfaces over lowest-bid procurement.
- Gas Producers:Myanmar's Ministry of Electricity and Energy has fast-tracked offshore gas field approvals to reduce LNG import dependency, creating concentrated demand for specialized EPC capabilities.
- Contractors:Tier-one EPCs are absorbing bundled scope risk while specialized subsea engineering boutiques face marginalization in regional tender participation.
- Government Entities:Indonesia's Perusahaan Listrik Negara is contracting multiple floating storage and regasification units, embedding local content mandates into utility-scale procurement.
National oil companies dominate contract value; gas producers are expanding their share through upstream prioritization policies.
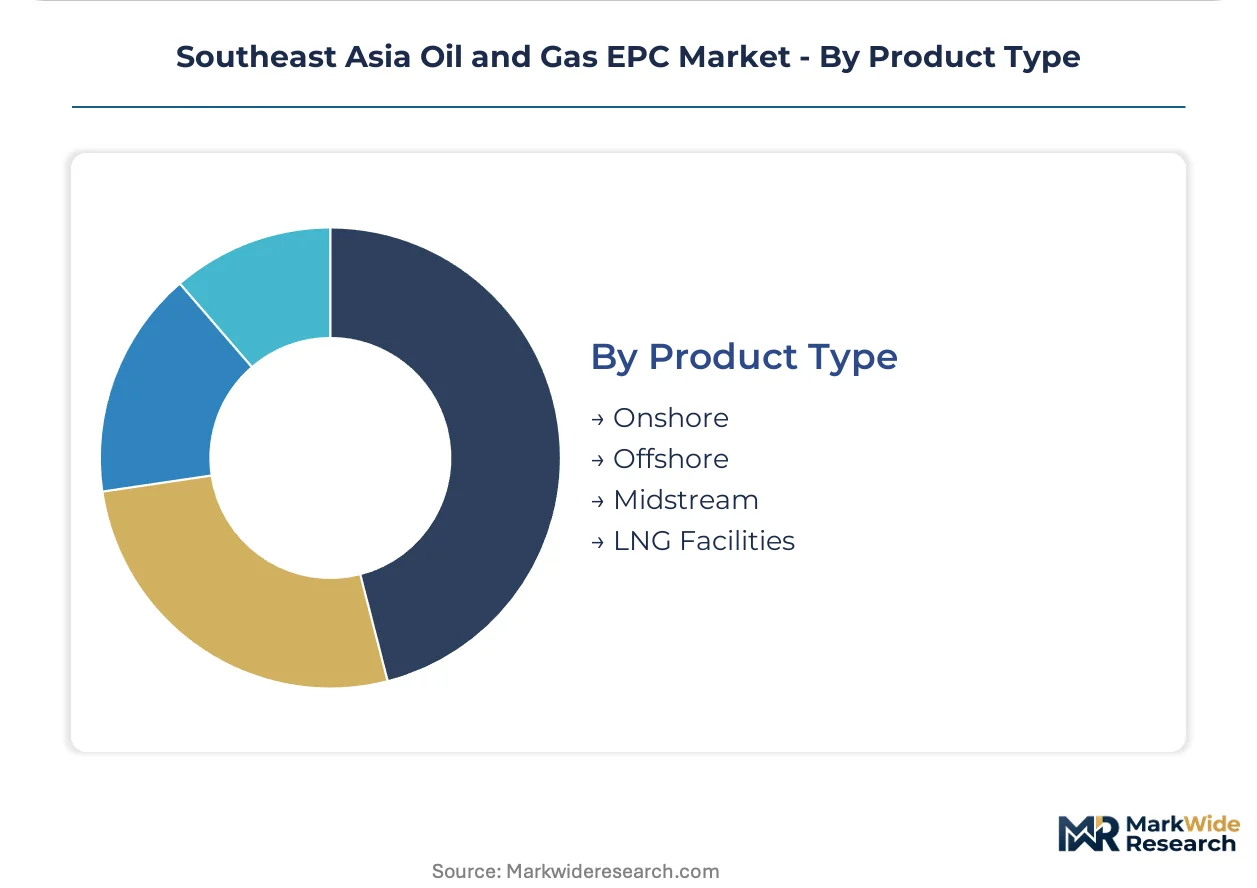
Product Type:
Physical asset location determines regulatory jurisdiction and supply chain configuration across the project lifecycle.
- Onshore:Mature margin pools have shifted toward brownfield modernization and emissions retrofit work in Thailand's Gulf of Thailand mature fields, opening recurring revenue streams distinct from greenfield cyclicality.
- Offshore:Frontier deepwater developments off Indonesia and Vietnam require subsea tieback complexity and integrated project delivery capabilities that command premium contract values. Divergent welding procedure qualifications between Malaysia's PETRONAS Technical Standards and Indonesia's SNI codes create requalification delays for mobile fabrication teams.
- Midstream:Pipeline and processing infrastructure connects production clusters to demand centers, with standardization potential across Indonesian and Papua New Guinea developments.
- LNG Facilities:Concentrated investment flows toward Papua New Guinea-linked developments and emerging Indonesian regasification terminals, with modular topsides fabrication allowing replication and timeline compression.
Offshore scope leads absolute value; LNG facilities are climbing fastest on regasification infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Jurong Island anchors fabrication capacity for the region's offshore EPC sector, hosting heavy structural module yards that supply Malaysian deepwater and Indonesian frontier developments. National oil companies across Indonesia, Vietnam, Malaysia, Thailand, and Myanmar are driving differentiated procurement patterns shaped by local content mandates and water depth requirements.
Indonesia
Deepwater frontier expansion off East Java and the Makassar Strait commands premium EPC capabilities as operators push beyond 1,500 meters. The Ministry of Energy and Mineral Resources enforces TKDN local content thresholds that restructure contractor procurement networks toward domestic fabrication yards. Batam's industrial zone captures module construction scope, though welding requalification delays persist against Malaysia's divergent technical standards.
Vietnam
Subsea tieback developments in the Cuu Long and Nam Con Son basins require specialized installation fleet access as the Ministry of Industry and Trade fast-tracks offshore gas approvals. Licensing frameworks govern platform design codes and environmental discharge limits that extend project timelines. Vung Tau's fabrication corridor concentrates heavy structural work, creating synchronized capacity bottlenecks during sanctioning waves.
Malaysia
PETRONAS Technical Standards mandate digital twin specifications in front-end engineering designs for deepwater blocks off Sabah and Sarawak. Carbon capture pilot projects for offshore CO2 injection tied to enhanced oil recovery create first-mover positioning for EPCs with subsurface engineering-procurement interfaces. Kuantan's integrated petrochemical zone anchors downstream brownfield modernization scope distinct from greenfield cyclicality.
Thailand
The Department of Mineral Fuels imposes safety audit cycles that compress allowable project timelines across the Gulf of Thailand's mature platform infrastructure. Brownfield scope dominates as structural life extension and emissions retrofit work open recurring revenue streams. Rayong's Eastern Economic Corridor clusters maintenance and modification capacity for aging offshore assets.
Myanmar
The Ministry of Electricity and Energy has prioritized offshore gas field development approvals to offset declining domestic production and reduce LNG import dependency. Shallow-water developments in the Yetagun and Yadana fields require standardized platform fabrication that competes for Singapore-Batam yard slots. Yangon's limited indigenous EPC capacity forces joint-venture structures with regional tier-one contractors.
Southeast Asia Oil and Gas EPC Market Competitive Landscape
Premium-margin players sit above commodity-margin players across subsea complexity and integrated delivery capabilities. The market structure concentrates risk with tier-one EPCs absorbing bundled scope while specialized engineering boutiques face marginalization in regional tender participation. Three archetypes dominate: subsea installation fleet operators, integrated engineering-procurement interface specialists, and cost-competitive yard-captive fabricators. Competitive moves center on joint-venture formations to satisfy local content mandates and strategic positioning for carbon capture integration scope.
Within the subsea installation tier, Saipem and TechnipFMC represent integrated delivery archetypes, while Hyundai Engineering exemplifies cost-competitive positioning through captive yard capacity. Petrofac Limited and Samsung Engineering occupy positions between premium-tier complexity and standardized module fabrication. These entities anchor the competitive dynamic as national oil companies consolidate procurement around single-accountable contractors.
| Leading Market Players |
|---|
| Saipem |
| Petrofac Limited |
| TechnipFMC |
| Samsung Engineering |
| PT Barata Indonesia |
| Bechtel Corporation |
| John Wood Group |
| Hyundai Engineering |
| Fluor Corporation |
| Others |
Value Network & Pricing Analysis
Specialized welding crews concentrated in Singapore and Batam drive labor-cost spreads between premium-tier integrated contractors and standardized module fabricators across Southeast Asian waters. Indonesian TKDN mandates amplify these differentials by forcing foreign engineering firms into joint-venture structures that layer administrative overhead onto project bids.
Pricing Analysis
Throughput-guarantee structures anchor value-based pricing for subsea installation campaigns, with day-rate premiums tied to vessel uptime performance rather than fixed mobilization fees. Three-tier pricing structure across premium, standard, and economy levels separates Saipem's integrated delivery from Hyundai Engineering's yard-captive positioning and domestic fabricators' commodity module rates. Cost compression in standard-tier lump-sum contracts is intensifying because nickel and copper volatility erodes fixed-price profitability on long-lead subsea umbilicals. National oil companies in Vietnam and Thailand show least price sensitivity for deepwater frontier developments, while Myanmar's shallow-water operators prioritize lowest-bid procurement.
Supply Chain Analysis
Heavy-lift vessel repositioning costs from West Africa and the Gulf of Mexico feed into Southeast Asian project pricing, with freight differentials widening during peak campaign windows. Structural module fabrication concentrates in Singapore, Batam, and Vung Tau, drawing from specialty offshore-grade steel mills in South Korea and Japan. Single-source vulnerability sits with the limited Asia-Pacific heavy-lift and pipelay fleet availability. Distribution runs through national oil company tender portals that bundle subsea, topsides, and installation scope under single accountable contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
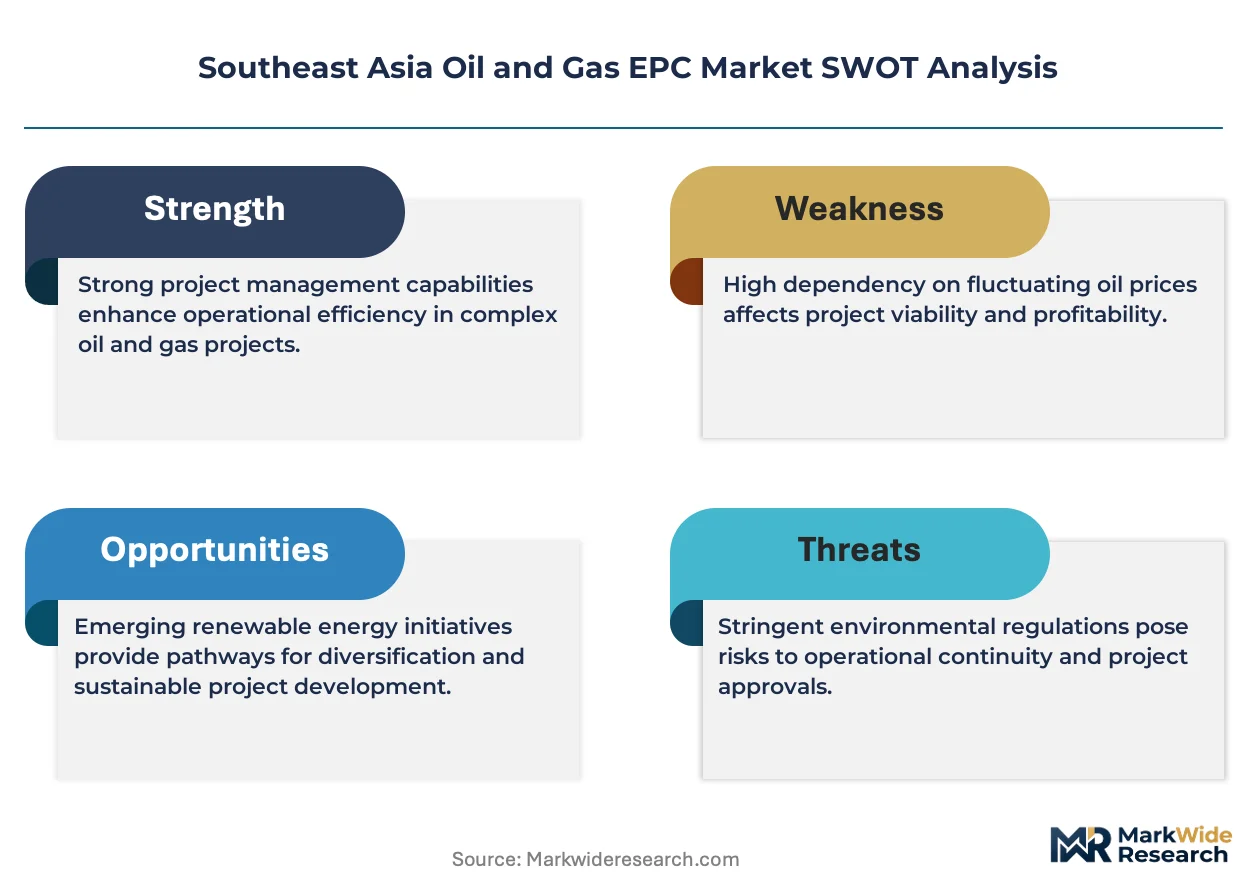
Southeast Asia's Oil and Gas EPC sector is becoming a vertical-integration race as contractors pursue captive control over fabrication yards to defend margin pools against local content mandates. Joint-venture formations with domestic partners now serve as the primary downstream lever for market access.
For Market Incumbents: Hedge against subsea installation vessel scarcity by securing multi-year charter agreements with Asian fleet operators before peak sanctioning waves compress availability. Acquire minority stakes in Batam or Vung Tau fabrication yards to satisfy Indonesia's TKDN thresholds without surrendering technology control to full joint-venture structures.
For New Entrants and Emerging Players: Launch via brownfield modernization specialization in Thailand's Gulf of Thailand, where structural life extension and emissions retrofit work escapes the cyclicality of greenfield project awards. Target Perusahaan Listrik Negara's floating storage and regasification unit procurement as the most penetrable utility-scale segment, embedding modular fabrication capabilities that replicate across Indonesian and Papua New Guinea developments.
For Investors and Strategic Acquirers: Re-rating potential sits with tier-one EPCs possessing subsurface engineering-procurement interfaces given PETRONAS's signaled carbon capture pilot projects for offshore CO2 injection. Long-term viability over the coming decade hinges on positioning for integrated project delivery consolidation as national oil companies marginalize specialized subsea engineering boutiques. Watch for welding procedure qualification harmonization between Malaysia's PETRONAS Technical Standards and Indonesia's SNI codes as the inflection indicator for cross-border fabrication mobility.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | Indonesia's TKDN mandates force foreign contractors into domestic partnerships to secure platform awards. |
| Fabrication Yard Acquisition | Captive capacity in Batam or Vung Tau insulates against synchronized project waves and capacity bottlenecks. |
| Subsea Fleet Charter | Multi-year vessel agreements lock in day-rate structures before Asia-Pacific scarcity intensifies. |
| Carbon Capture Integration | First-mover positioning for PETRONAS's offshore CO2 injection pilots requires subsurface engineering interfaces. |
| Digital Twin Deployment | Malaysian deepwater operators mandate real-time sensor integration to reduce inspection vessel callouts. |
Research Methodology
Regulatory filings from Indonesia's Ministry of Energy and Mineral Resources, Malaysia's PETRONAS Technical Standards documentation, and Vietnam's Ministry of Industry and Trade licensing frameworks formed the secondary backbone for policy impact assessment. Primary interviews with EPC contract directors, national oil company procurement leads, fabrication yard operations managers, and subsea installation vessel charter specialists combined with customs trade data and project sanctioning databases to triangulate market sizing from bottom-up project aggregation and top-down sectoral allocation.
Bottom-up modeling anchored volume estimates to disclosed contract values across lump-sum turnkey and cost-reimbursable structures, while top-down cross-checks applied energy-sector capex intensity ratios. Segmentation dimensions spanned service type, technology category, water depth tier, and buyer archetype across the projection horizon. CAGRs derived from regression against historical sanctioning cycles, with forecast inputs incorporating steel price volatility indices and fabrication yard utilization rates.
Project sanctioning delays, local content enforcement intensity, and subsea vessel availability shocks are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Polycrystalline Diamond Compact (PDC) Drill Bit Market
Oil & Gas
Global Fracking Chemicals Market
Oil & Gas
Oil and Gas Seals Market
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
Downhole Motor Market
Oil & Gas
Frac Stack Market
Oil & Gas
Sensors in Oil and Gas Market
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Wired Drill Pipe Sales Market
Oil & Gas
Turkmenistan Oil and Gas Market
Oil & Gas
Well Cementing Market
Oil & Gas
United States Natural Gas Market
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
Well Completion Market
Oil & Gas
Romania Oil and Gas Downstream Market
Oil & Gas
North America Hydraulic Fracturing Fluids Market