
 Oil and Gas Cloud Applications Market | 2026-2036
Oil and Gas Cloud Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Cloud Applications Market Intelligence
Hyperscaler data center capacity in key energy hubs like Houston and Dubai is expanding to meet specialized computational demands from the oil and gas sector. Amazon Web Services leverages its extensive infrastructure to offer scalable solutions for seismic data processing. Microsoft Corporation differentiates through its Azure platform, integrating AI and IoT services for predictive maintenance in refining facilities. Oracle Corporation specializes in enterprise resource planning and supply chain management applications tailored for the industry.
Oil and gas cloud applications are specialized software and platforms hosted on remote servers that enable the processing and analysis of large-scale operational data. These systems provide functionalities like real-time drilling optimization and subsurface modeling, connecting disparate assets through a centralized digital interface. Within service offerings, Software as a Service (SaaS) dominates due to its lower upfront cost, while hybrid cloud models are gaining traction for balancing security and scalability. Demand from pipeline operators focuses on asset monitoring and compliance tracking applications.
Data sovereignty and security standards, such as the EU's GDPR and China's Cybersecurity Law, govern cross-border data flows from offshore platforms. In the United States, EPA regulations on methane emissions monitoring create demand for cloud-based compliance tracking tools. Vendor selection will increasingly hinge on the ability to demonstrate compliance with disparate regional data localization and environmental reporting mandates.
Market Dynamics
The central structural force shaping the market is the dual mandate facing operators: maximizing hydrocarbon recovery from increasingly complex reservoirs while adhering to stringent new environmental reporting standards, such as the EU's Corporate Sustainability Reporting Directive (CSRD).
Growth Catalysts
- Emissions Reporting Mandates:The EU's CSRD and similar regulations from the US EPA compel operators to adopt cloud applications for transparent, auditable tracking of greenhouse gas emissions across their value chains, particularly methane from upstream and midstream assets.
- Advanced Reservoir Management:Demand for sophisticated subsurface modeling and real-time drilling optimization tools is a primary catalyst, especially within unconventional shale operations in the United States and deepwater exploration projects requiring intensive computational analysis.
- IoT Sensor Proliferation:The expanding deployment of IoT sensors on drilling rigs, pipelines, and refining equipment generates vast datasets that require scalable cloud infrastructure for processing, analysis, and deriving actionable insights for predictive maintenance and operational efficiency.
Market Restraints
- Data Sovereignty Laws:Regulations like the EU's GDPR and China's Cybersecurity Law impose strict rules on cross-border data transfer and localization, creating compliance complexities for multinational energy firms operating offshore platforms and globally distributed assets.
- Legacy System Integration:The high cost and technical difficulty of integrating modern cloud applications with decades-old, on-premise industrial control systems and SCADA infrastructure act as a significant barrier, especially for smaller independent operators.
- Cybersecurity Vulnerabilities:Heightened concerns over the security of hosting sensitive operational data, such as reservoir models and pipeline flow rates, on public or hybrid cloud platforms deter adoption, particularly among state-owned oil companies managing critical national infrastructure.
Strategic Opportunities
- Predictive Maintenance in Downstream:A significant opportunity exists in applying AI-driven predictive analytics for equipment failure in downstream refining and petrochemical facilities, an area with lower cloud penetration compared to the upstream exploration and production segment.
- Emerging Exploration Frontiers:Underpenetrated markets for exploration-focused cloud services include new offshore developments in regions like Guyana and West Africa, where national oil companies lack extensive legacy IT infrastructure and can adopt cloud-native solutions directly.
- Digital Twin for Asset Management:The convergence of IoT data with 3D modeling allows for the creation of comprehensive digital twins of physical assets, presenting an opportunity to offer full lifecycle management platforms from design and construction through to decommissioning.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of professionals who possess a dual expertise in both petroleum engineering and cloud-native data science creates a significant operational bottleneck, hindering the effective implementation and utilization of advanced analytical applications.
- Data Standardization:Integrating data from disparate operational technology sources, each with proprietary formats, poses a major challenge. The lack of industry-wide standards for data exchange between upstream, midstream, and downstream systems complicates the creation of unified data platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Cloud Applications Market |
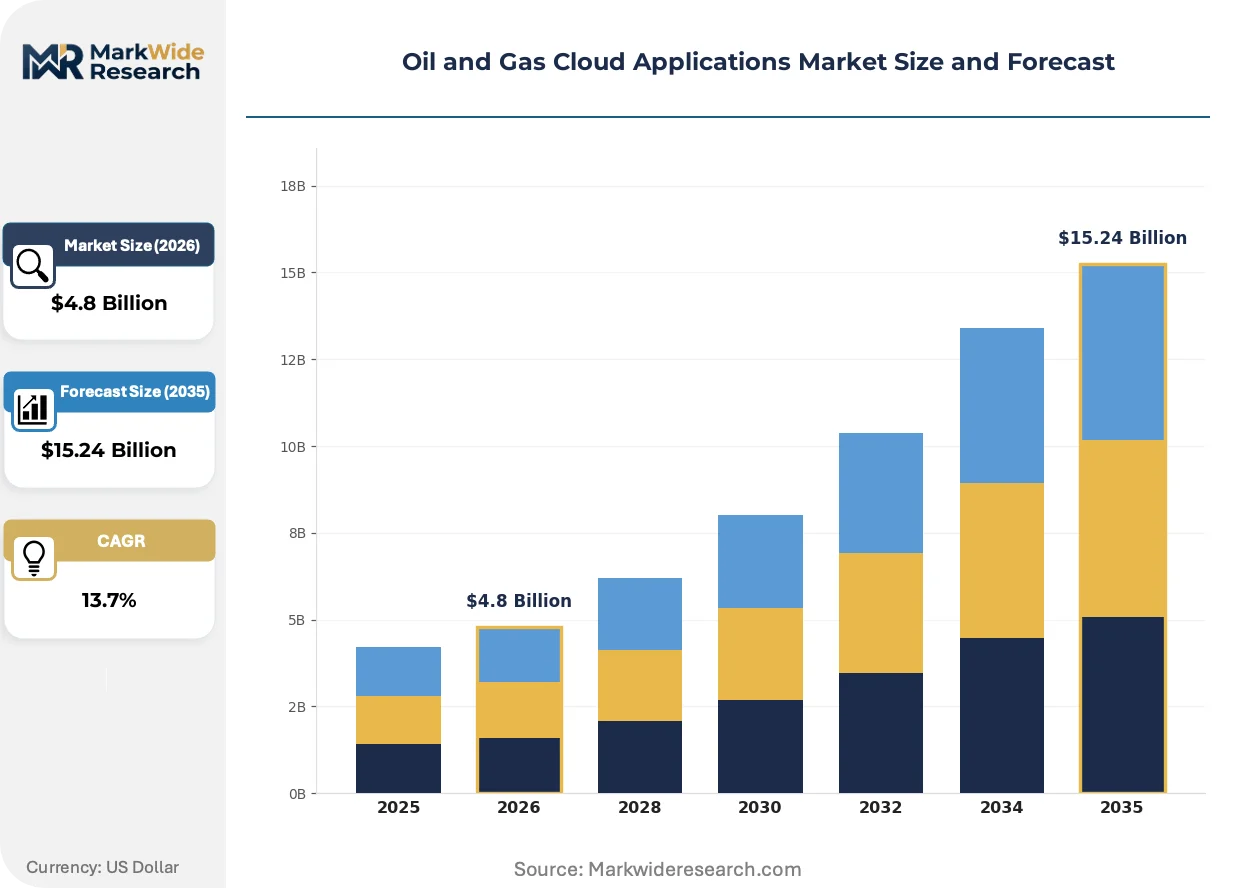
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Application Area: Reservoir Management, Drilling Optimization, Supply Chain Management, Asset Monitoring, Compliance Tracking Service Offering: Software as a Service, Platform as a Service, Infrastructure as a Service, Managed Cloud Services, Consulting End User Type: Exploration Companies, Refining Facilities, Pipeline Operators, Petrochemical Units |
| Companies Covered | Oracle Corporation, IBM Corporation, Microsoft Corporation, Hewlett Packard Enterprise, Cisco Systems, Amazon Web Services, SAP SE, TIBCO Software, Google Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Cloud Applications Market Strategic Shifts & Innovations
The convergence of operational technology (OT) from physical assets with information technology (IT) systems in the cloud is creating a new data-centric paradigm. This shift enables real-time, autonomous decision-making that optimizes performance from the reservoir to the refinery.
Digital twin technology provides a virtual, dynamic representation of a physical oil and gas asset. Upstream exploration and production firms are the primary adopters, using it to simulate drilling scenarios and optimize production strategies. This technology is converging with AI-powered analytics to enable semi-autonomous adjustments to operational parameters, moving beyond simple visualization to active process control and optimization.
Regulatory frameworks focused on environmental accountability are a major influence. The US Environmental Protection Agency's (EPA) regulations targeting methane emissions from oil and gas operations directly create demand for cloud-based monitoring and compliance reporting software. Upstream and midstream operators are most affected, accelerating their deployment of sensor networks and cloud platforms to ensure auditable compliance with federal mandates.
A notable behavioral shift involves operators moving from monolithic, single-vendor enterprise agreements to multi-cloud, best-of-breed application strategies. This unbundling disrupts the traditional dominance of large, integrated software providers, as firms select specialized applications from different vendors for distinct tasks. This trend is highly visible among national oil companies in the Middle East seeking to avoid vendor lock-in.
Oil and Gas Cloud Applications Market Segmentation
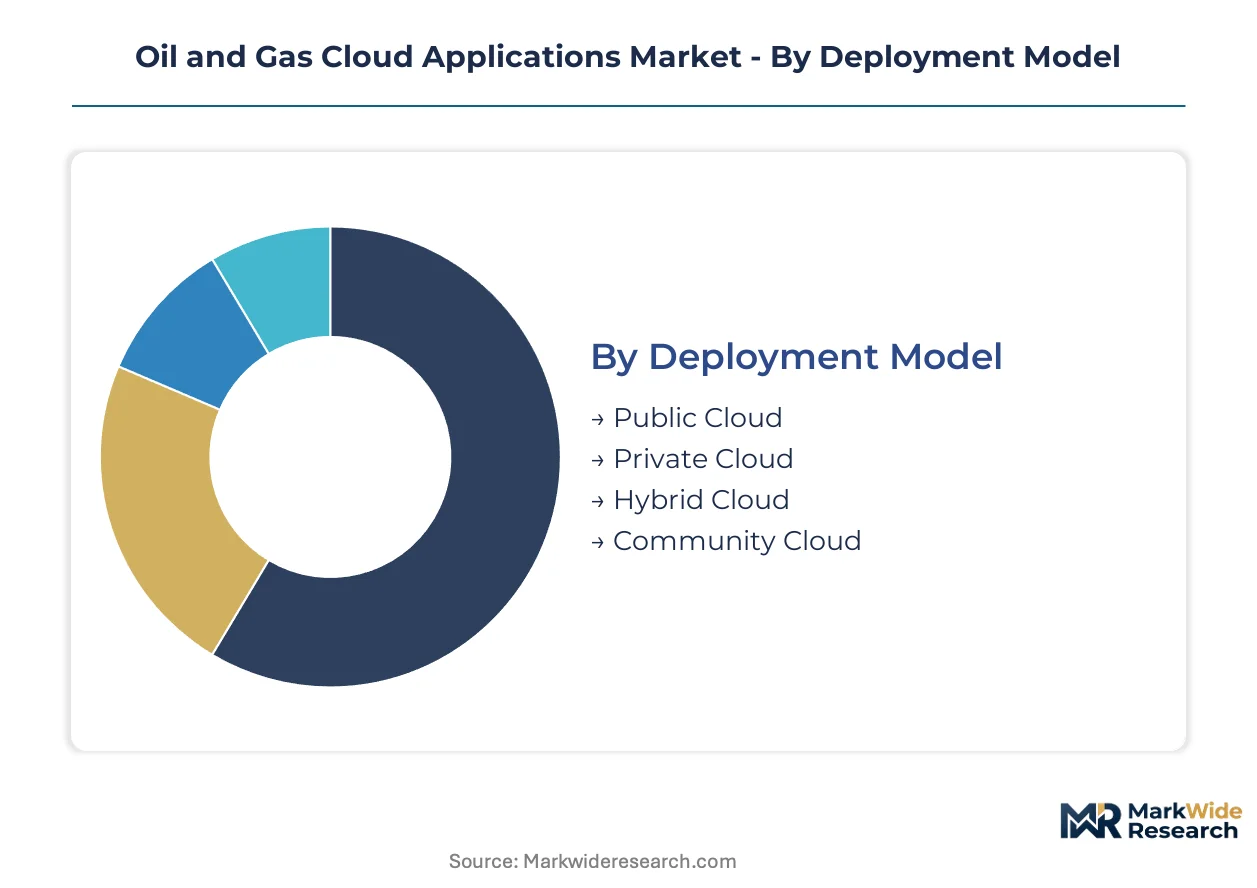
The Oil and Gas Cloud Applications market's segmentation highlights the diverse technological approaches and operational demands driving adoption. Understanding these distinct segments provides clarity on where investment and innovation are concentrating across the energy value chain.
Deployment Model:
The underlying infrastructure and hosting strategy for cloud applications define this segment.
- Hybrid Cloud:This model integrates private cloud infrastructure with public cloud services, allowing data and applications to be shared between them. Demand for hybrid models is gaining traction for balancing security requirements with scalability, particularly for sensitive operational data.
- Public Cloud:Services delivered over the public internet by third-party providers like AWS and Microsoft Azure. These platforms offer immense scalability and cost efficiencies, primarily supporting seismic data processing and large-scale computational analysis in exploration.
- Private Cloud:Dedicated cloud infrastructure operated exclusively for a single organization, either on-site or hosted by a third party. State-owned oil companies often prefer private cloud solutions for enhanced data sovereignty and control over critical national infrastructure.
- Community Cloud:Shared cloud infrastructure provisioned for a specific community of consumers from organizations with shared concerns. This model addresses niche requirements for collaborative projects among consortiums or joint ventures.
Hybrid Cloud leads on scale; Public Cloud leads on momentum.
Application Area:
Functional requirements for oil and gas operations delineate the specialized use cases for cloud applications.
- Reservoir Management:These applications utilize complex algorithms and subsurface modeling to optimize hydrocarbon recovery from geological formations. Upstream exploration and production firms, especially in unconventional shale operations, drive significant demand for these computationally intensive tools.
- Compliance Tracking:Software solutions designed to monitor, report, and ensure adherence to environmental regulations and industry standards. The EU's Corporate Sustainability Reporting Directive and US EPA methane regulations compel operators to adopt cloud-based tools for auditable emissions data.
- Drilling Optimization:Real-time data analytics and simulation tools used to improve drilling efficiency, reduce non-productive time, and enhance wellbore placement. Deepwater exploration projects and complex well designs benefit significantly from these advanced applications.
- Supply Chain Management:Cloud platforms that streamline procurement, logistics, and inventory management processes across the oil and gas value chain. These systems enhance transparency and efficiency for globally distributed operations.
- Asset Monitoring:Applications that collect and analyze data from IoT sensors on physical assets like pipelines and refining equipment. Pipeline operators rely on these tools for predictive maintenance and real-time operational oversight.
Demand for Reservoir Management remains foundational, while Compliance Tracking exhibits strong expansion.
Service Offering:
The various models for delivering cloud-based software and infrastructure characterize this segment.
- Software as a Service (SaaS):Applications hosted by a third-party provider and made available to customers over the internet. SaaS dominates the market due to its lower upfront cost and simplified management for a wide range of operational and business applications.
- Platform as a Service (PaaS):A cloud environment offering a complete development and deployment platform for building, running, and managing applications. PaaS enables specialized data science teams to develop custom AI-driven analytics for predictive maintenance and operational optimization.
- Infrastructure as a Service (IaaS):Virtualized computing resources, including servers, storage, and networking, delivered over the internet. IaaS provides the foundational scalability required for processing massive seismic datasets and supporting high-performance computing workloads.
- Managed Cloud Services:Third-party management of cloud infrastructure, operations, and security. These services allow oil and gas companies to offload the complexities of cloud management and focus on core operations.
- Consulting:Expert advisory services for cloud strategy, implementation, migration, and optimization. Consulting firms assist operators in navigating complex data sovereignty laws and integrating cloud solutions with legacy systems.
The shift towards Software as a Service reflects a preference for operational efficiency, with Platform as a Service enabling specialized development.
End User Type:
The specific operational sectors within the oil and gas industry define the distinct needs and adoption patterns.
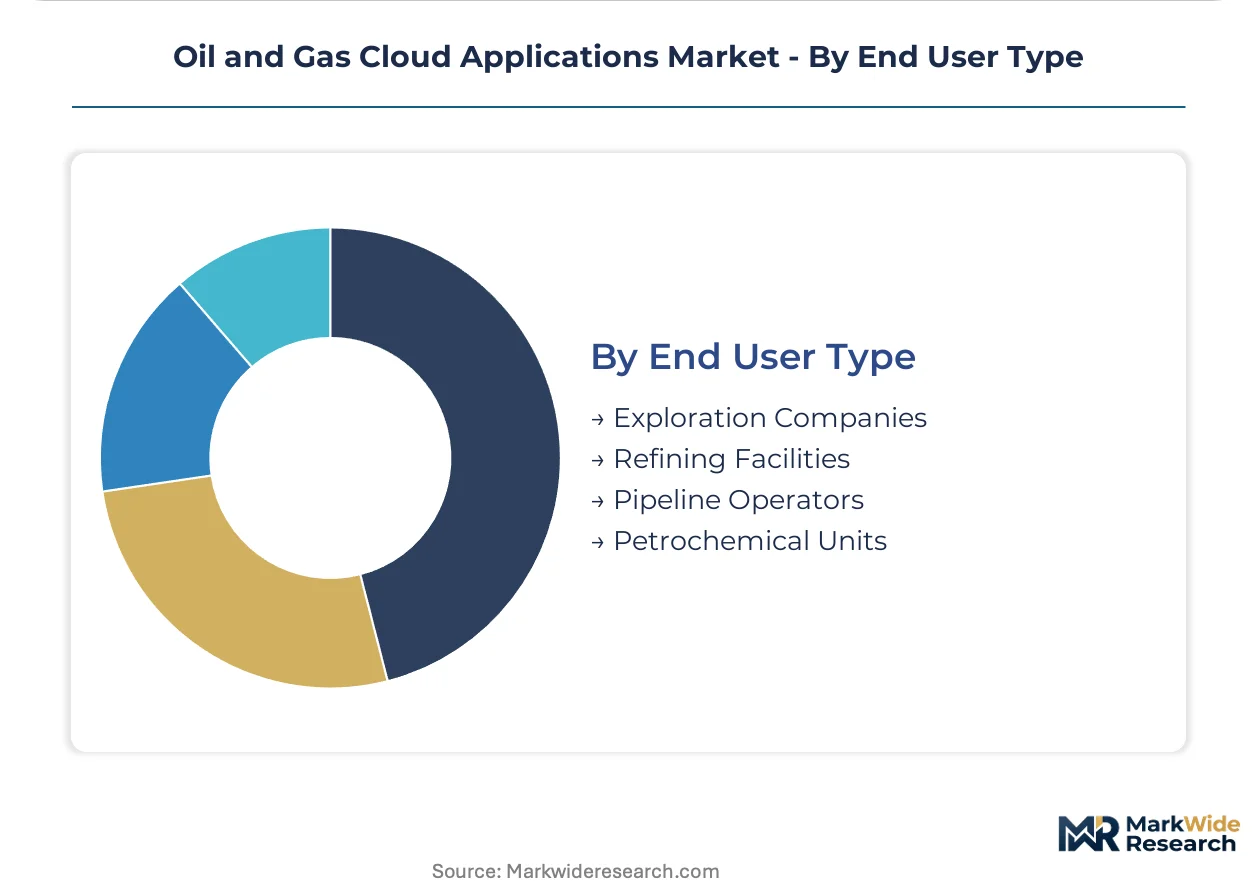
- Exploration Companies:Firms engaged in the search for new oil and gas reserves. These companies are primary adopters of cloud applications for advanced subsurface modeling, seismic data processing, and drilling optimization.
- Pipeline Operators:Entities responsible for the transportation of crude oil, natural gas, and refined products. Their demand centers on asset monitoring, integrity management, and compliance tracking applications to ensure safe and efficient operations.
- Refining Facilities:Industrial plants that process crude oil into refined products like gasoline and diesel. Cloud solutions support predictive maintenance for equipment and optimize operational workflows in these complex environments.
- Petrochemical Units:Facilities that convert petroleum products into chemicals used in various industries. Cloud applications assist with process optimization, supply chain management, and environmental reporting for these specialized operations.
Upstream operators drive significant adoption, while midstream and downstream segments show expanding requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oil and gas cloud applications adoption varies significantly due to differing regulatory environments. Stricter environmental mandates in some regions accelerate technology uptake, while less stringent oversight in others can slow adoption. This creates a complex landscape for operators managing global assets.
United States
Demand for cloud applications is intense for advanced reservoir management and real-time drilling optimization. EPA regulations on methane emissions monitoring compel operators to deploy cloud-based compliance tracking tools. Texas, particularly within its Permian Basin shale operations, sees high computational demands for subsurface modeling.
United Arab Emirates
National oil companies in the UAE prioritize cloud solutions for operational efficiency and data sovereignty. The Ministry of Energy and Infrastructure promotes digital transformation initiatives across the energy sector. Abu Dhabi, as a key energy hub, invests heavily in hyperscale data center capacity to support these advancements.
Norway
Offshore exploration and production activities in Norway drive the need for robust cloud infrastructure for seismic data processing. Strict environmental standards from the Norwegian Environment Agency necessitate advanced emissions reporting and monitoring applications. The North Sea region benefits from cloud platforms for optimizing complex deepwater projects.
China
Cloud applications support China's vast energy infrastructure, particularly for pipeline monitoring and supply chain management. China's Cybersecurity Law influences data localization requirements for energy firms operating within its borders. Major energy companies in Beijing and Shanghai leverage cloud platforms for enterprise resource planning.
Brazil
Deepwater exploration in Brazil creates significant demand for cloud-based subsurface modeling and drilling optimization tools. The Agência Nacional do Petróleo, Gás Natural e Biocombustíveis (ANP) regulates offshore operations, requiring data-intensive compliance. The pre-salt region offshore Rio de Janeiro relies on scalable cloud solutions for complex geological analysis.
Oil and Gas Cloud Applications Market Key Industry Players
United States-based technology giants anchor one tier of the market; European software specialists hold distinct positions. The market exhibits a tiered structure, with large hyperscalers offering foundational infrastructure and specialized software vendors providing niche applications. Strategic partnerships between cloud providers and industrial technology firms define competitive moves. Portfolio diversification into AI and IoT services also reshapes competitive positioning.
Within the hyperscaler and enterprise software tiers, Amazon Web Services exemplifies scalable infrastructure for seismic data processing, leveraging its extensive global network. Microsoft Corporation occupies a position as a platform provider, differentiating through its Azure platform and integrated AI/IoT services for predictive maintenance. Oracle Corporation anchors the enterprise resource planning segment, offering specialized supply chain management applications tailored for the oil and gas industry. These entities represent diverse approaches to serving the sector's computational and operational needs.
| Leading Market Players |
|---|
| Oracle Corporation |
| IBM Corporation |
| Microsoft Corporation |
| Hewlett Packard Enterprise |
| Cisco Systems |
| Amazon Web Services |
| SAP SE |
| TIBCO Software |
| Google Cloud |
| Others |
Cost & Logistics Intelligence
New environmental reporting mandates from the EU's CSRD compel oil and gas operators to adopt cloud applications, driving demand for specialized compliance tools and influencing the pricing models offered by solution providers.
Pricing Analysis
Direct-to-operator discounts often reflect the long-term contract nature of cloud application subscriptions. The dominant pricing model is SaaS-tiered, with differentiation based on volume scale for data processing and customization level for specialized analytics. Pricing pressure stems from the need for cost efficiencies in large-scale operations, particularly for smaller independent operators. State-owned oil companies, however, prioritize data sovereignty and control, making them less price-sensitive for private cloud solutions.
Supply Chain Analysis
Compliance with regional data localization and environmental reporting mandates serves as a critical qualification gate for cloud application providers. Supply concentration for foundational infrastructure centers in the United States and the United Arab Emirates, where hyperscaler data centers are expanding. The market relies on specialized data science talent and high-performance computing hardware. Data sovereignty laws, such as the EU's GDPR, pose a structural risk, requiring localized data storage. Distribution runs through direct sales channels from major hyperscalers and specialized software vendors, often supported by consulting partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Oil and Gas Cloud Applications Market functions as a stable compounder, driven by the continuous dual mandate for hydrocarbon recovery maximization and stringent environmental reporting compliance.
For Market Incumbents: Acquire niche AI/IoT firms to deepen capabilities in predictive maintenance and real-time optimization. This counters the threat of specialized software vendors unbundling services from traditional enterprise agreements. Incumbents must invest in R&D for advanced subsurface modeling and integrate consulting services to facilitate complex legacy system integrations. Securing talent with dual expertise in petroleum engineering and cloud data science remains critical.
For New Entrants and Emerging Players: The EU's Corporate Sustainability Reporting Directive (CSRD) in Europe opens a window for specialized emissions reporting and compliance tracking solutions. New entrants should target underpenetrated downstream segments, specifically refining facilities, with AI-driven predictive maintenance platforms. Focusing on cloud-native solutions for emerging exploration frontiers, like West Africa, where legacy IT infrastructure is minimal, presents another opportunity. A strong go-to-market angle involves demonstrating auditable compliance with specific environmental mandates.
For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native analytics providers addressing specific regulatory compliance needs or complex subsurface challenges. The long-term viability of this market is assured by the increasing data intensity of hydrocarbon recovery and environmental reporting. Acquisition targets should include mid-cap specialists in digital twin technology or AI-powered predictive maintenance for downstream assets. The signal to watch is the pace of multi-cloud adoption among national oil companies, indicating a shift away from monolithic vendor agreements.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-powered Emissions Monitoring Software Launch | Enables operators to meet stringent mandates like the US EPA methane regulations with auditable data. |
| OT-IT System Integration Platform | Connects disparate operational assets through a centralized digital interface, driving real-time decision-making. |
| Hyperscaler-Specialized Vendor Partnership | Combines scalable infrastructure with niche application expertise to serve diverse oil and gas needs. |
| Acquisition of Digital Twin Technology Firm | Expands capabilities for full lifecycle asset management from design through decommissioning. |
| Expansion into West African Offshore Markets | Captures demand from regions adopting cloud-native solutions without extensive legacy IT infrastructure. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a robust understanding of the Oil and Gas Cloud Applications Market. Primary insights were gathered from CTOs, reservoir engineers, compliance managers, and IT procurement officers within major energy firms. Secondary validation drew from hyperscaler financial disclosures, IEA reports on energy trends, and regulatory updates from the US EPA. This mixed-methods approach facilitated a comprehensive bottom-up and top-down triangulation of market dynamics.
Segment-level weighting, based on historical adoption rates and projected demand shifts, formed the core of the market's quantitative forecast framework. The analysis modeled growth across deployment model, application area, service offering, end user type, and key geographic regions. Compound Annual Growth Rates were derived from an assessment of new exploration licenses, anticipated environmental compliance investments, and technology adoption curves across the analysis window. This framework provides granular insights into future market trajectories.
Revisions become necessary when significant geopolitical shifts or unexpected oil price volatility materialize, impacting operator investment cycles. Forecasts reflect assumptions regarding regulatory stability and sustained digital transformation initiatives within the energy sector. Deviation in either global energy policy or major technology breakthroughs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Italy Oil and Gas Market
Oil & Gas
Malaysia Oil and Gas Midstream Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
Multi-Point Ground Flares (MPGF) Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
Qatar Oilfield Service Market
Oil & Gas
Wired Drill Pipe Sales Market
Oil & Gas
Asphaltene Inhibitors Market
Oil & Gas
Oil and Gas Electrification Market
Oil & Gas
Asia-Pacific Well Intervention Market
Oil & Gas
North America Wireline Services Market
Oil & Gas
Slickline Services Market
Oil & Gas
Sensors in Oil and Gas Market
Oil & Gas
Intelligent Well Completion Market
Oil & Gas
Small Scale LNG Terminal Market