
 Oilfield Services Market | 2026-2036
Oilfield Services Market Size, Share, and Industry Trends Forecast 2026-2036
Oilfield Services Market Intelligence
The EPA's methane emissions standards are realigning capital allocation across the oilfield services sector. Schlumberger Limited leverages its integrated drilling and evaluation portfolio to capture premium contracts in emissions-intensive basins. Halliburton Company anchors its position through pressure pumping scale and digital frac fleet optimization. Baker Hughes Company differentiates via turbomachinery and carbon capture solutions bundled into production contracts.
Oilfield services encompass the specialized equipment, technical labor, and engineered processes required to drill, complete, maintain, and optimize hydrocarbon wells, typically operating at pressures exceeding 10,000 psi and temperatures above 150°C in deep formations. These services enable exploration and production companies to extract crude oil and natural gas from conventional reservoirs, unconventional shale, and subsea fields. Drilling services commands the largest revenue share due to rig day-rate structures and extended well laterals, while well intervention is expanding fastest as mature basins require workovers and plug-and-perf refracturing to sustain output. Hydraulic fracturing technology concentrates margin pools in proppant logistics and high-horsepower pumping arrays, though cementing retains steady demand from well integrity mandates.
The EPA enforces methane leak detection and repair protocols that elevate compliance costs for service providers deploying pneumatic pumps and compressors. OSHA regulates worker exposure to hydrogen sulfide and rig-floor hazards, shaping training and equipment certification requirements. The Bureau of Land Management's venting and flaring rules on federal leases restrict operational flexibility for contractors in the Rocky Mountain states. Stakeholders must monitor how the Inflation Reduction Act's methane fee structure reshapes contract economics for emission-intensive service lines.
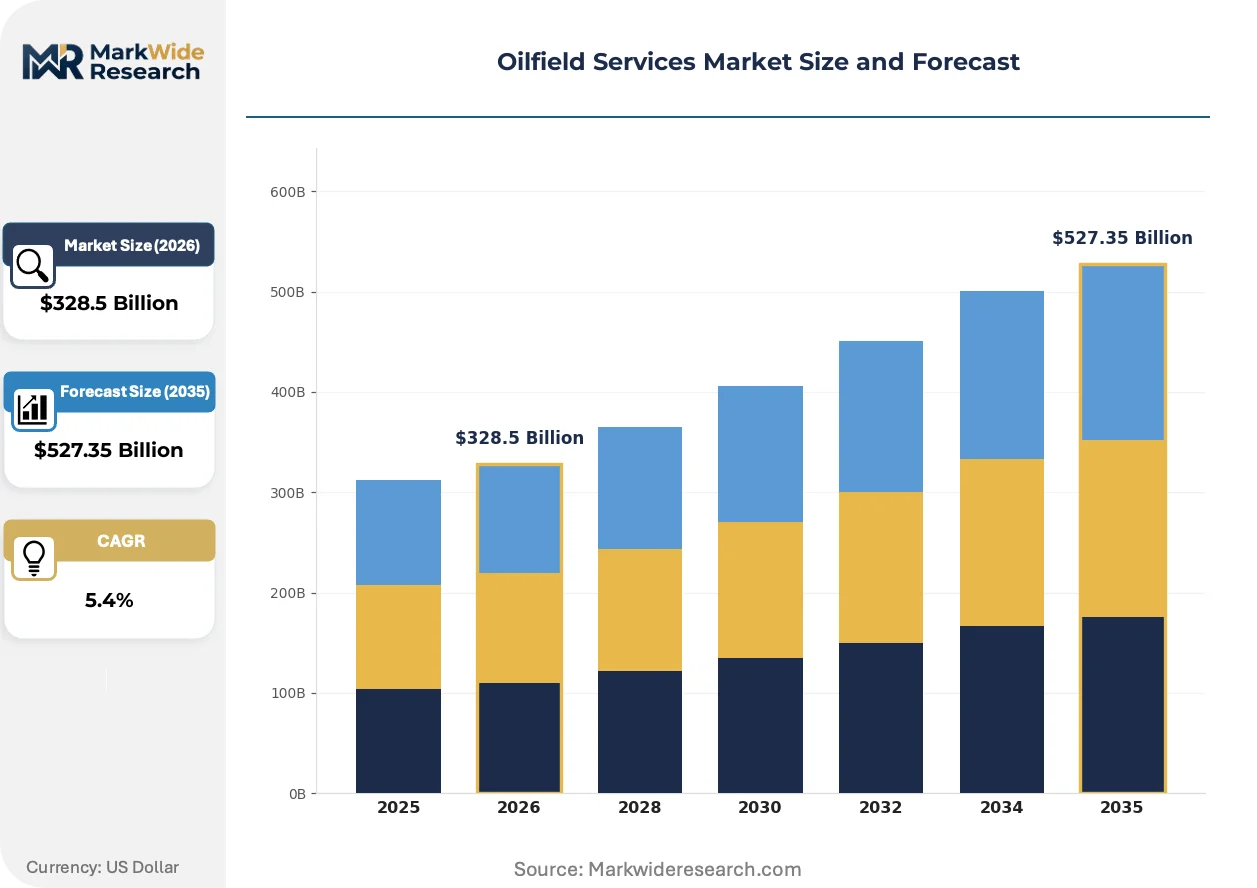
Market Dynamics
The EPA's methane emissions rules are compressing contract margins for pneumatic equipment fleets while simultaneously creating premium pricing tiers for low-emission service packages. This regulatory pressure is forcing capital redeployment toward leak detection systems and electric frac fleets.
Growth Catalysts
- Permian Basin density:Independent operators in West Texas and southeast New Mexico require continuous well intervention and rapid frac fleet redeployment to maintain production curves.
- Deepwater exploration off Brazil:Pre-salt discoveries are pulling investment toward offshore drilling contractors with subsea completion capabilities.
- Inflation Reduction Act methane fee structure:The IRA's emissions-based penalties are accelerating demand for LDAR (Leak Detection and Repair) service contracts.
Market Restraints
- High-spec rig supply concentration:Advanced AC-powered land rigs and offshore drillships cluster among a limited set of shipyards and equipment fabricators.
- Proppant logistics cost volatility:Northern White Sand from Wisconsin and regional brown sand alternatives face rail capacity constraints and fuel surcharge fluctuations.
- OSHA hydrogen sulfide protocols:Worker exposure limits and rig-floor safety mandates elevate training costs and equipment certification timelines.
Strategic Opportunities
- Guyana offshore development:ExxonMobil-led consortium activity is creating demand for subsea tieback installation and floating production hookup services.
- Carbon capture bundled contracts:Turbomachinery providers are integrating post-combustion capture equipment into gas processing and enhanced oil recovery projects.
- Digital frac fleet optimization:Real-time pump control and predictive maintenance algorithms are enabling remote operations centers to manage distributed assets.
Industry Challenges
- Specialized technician scarcity:Directional drilling engineers and subsea completion specialists command premium wages amid demographic retirements.
- Dual-certification complexity:Equipment must satisfy both API standards and emerging EPA methane performance specifications before deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oilfield Services Market |
| Market Size in 2026 | $328.5 Billion |
| Market Size in 2035 | $527.35 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling Services, Well Completion, Formation Evaluation, Well Intervention, Reservoir Engineering Technology: Hydraulic Fracturing, Well Logging, Pressure Pumping, Cementing, Coiled Tubing Application: Onshore Extraction, Offshore Exploration, Enhanced Oil Recovery, Production Optimization End User: Exploration Companies, National Oil Companies, Independent Operators, Oilfield Contractors |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Weatherford International, National Oilwell Varco, China Oilfield Services Limited, TechnipFMC plc, Expro Group, Superior Energy Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oilfield Services Market Strategic Shifts & Innovations
Digital automation and emissions compliance are converging to reshape how oilfield services are contracted, delivered, and priced. Equipment vendors and service firms are racing to embed monitoring capabilities and low-emission designs into core offerings.
Electric fracturing fleets powered by natural gas turbine generators are consolidating market share in emissions-sensitive basins. Permian and DJ Basin operators are specifying these systems to avoid EPA methane fee exposure. The technology is consolidating service margins around fuel logistics and grid interconnection capabilities rather than traditional diesel supply chains.
REACH chemical authorization requirements in Europe are restricting the import of certain drilling fluid additives and corrosion inhibitors. Formulation houses must submit full substance dossiers to ECHA or pivot to pre-registered alternatives. North Sea drilling contractors are absorbing compliance costs while Gulf of Mexico operators face parallel scrutiny under EPA TSCA rules.
Integrated service contracts are displacing discrete product purchasing across major independents. E&P companies are bundling drilling, completion, and artificial lift under single-provider agreements with performance guarantees. This pattern is most pronounced among Permian Basin independents seeking to reduce vendor management overhead and shift operational risk to service firms.
Oilfield Services Market Segmentation
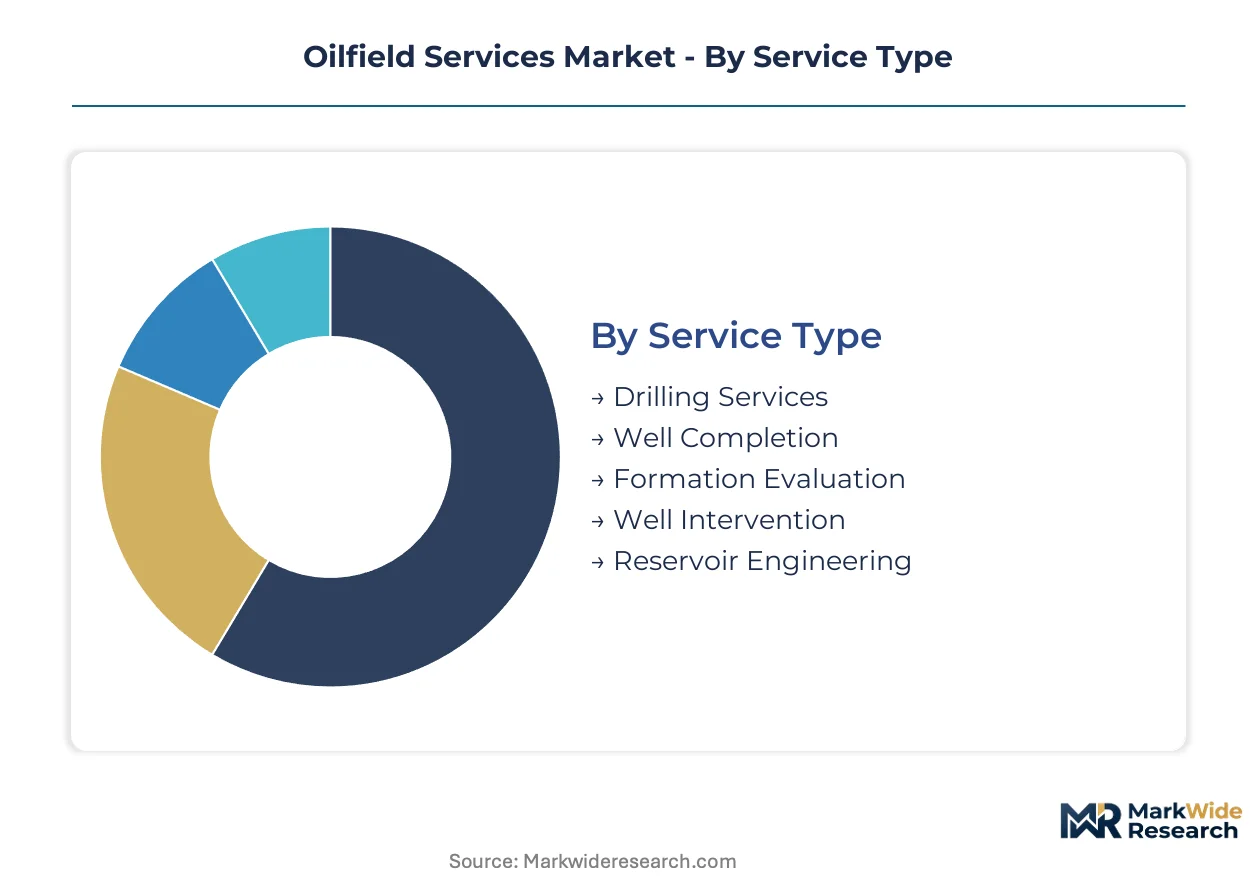
Service differentiation in oilfield operations determines contract pricing power and equipment utilization rates. Technology specialization and application-specific expertise create distinct margin pools across the value chain.
Service Type:
Supply concentration tilts toward integrated providers capable of bundling multiple service lines under single contractual frameworks.
- Drilling Services:Rig day-rate structures dominate revenue capture, with AC-powered land rigs and offshore drillships commanding premium pricing in deepwater basins. Permian Basin operators in West Texas and southeast New Mexico drive constant demand for extended lateral drilling and rapid rig mobilization.
- Well Completion:Perforating, gravel packing, and intelligent completion installations finalize well architecture for production. Deepwater pre-salt developments off Brazil pull specialized completion hardware toward subsea tieback configurations.
- Formation Evaluation:Wireline logging and core analysis characterize reservoir properties prior to completion decisions. Real-time LWD (Logging While Drilling) sensors reduce rig time and improve geosteering accuracy in unconventional shale.
- Well Intervention:Workovers, plug-and-perf refracturing, and coiled tubing operations sustain output from mature fields. EPA methane regulations are accelerating LDAR service deployment alongside traditional mechanical intervention.
- Reservoir Engineering:Simulation modeling and enhanced recovery design optimize field development strategies. Digital twin integration is reshaping how engineering consultancies contract with major independents.
Drilling Services absorbs the bulk of installed capacity; Well Intervention is expanding most quickly.
Technology:
Cost tier differentiation separates commoditized pressure pumping from proprietary digital control systems commanding performance-based pricing.
- Hydraulic Fracturing:High-horsepower pumping arrays and proppant logistics constitute the largest capital deployment in unconventional development. Electric frac fleets powered by natural gas turbine generators are consolidating share in emissions-sensitive basins to avoid EPA methane fee exposure.
- Well Logging:Gamma ray, resistivity, and acoustic measurements map formation characteristics in real time. LWD-while-drilling platforms reduce flat time and improve geosteering precision in Permian laterals.
- Pressure Pumping:Cement squeezes, acid jobs, and fracturing treatments require continuous equipment refresh cycles. Northern White Sand logistics constraints and rail capacity bottlenecks compress margins on commodity pumping services.
- Cementing:Zonal isolation and well integrity mandates sustain steady demand across all basin types. API specification testing and dual-certification complexity extend equipment certification timelines.
- Coiled Tubing:Continuous pipe deployment enables live-well intervention without killing the wellbore. Extended-reach capabilities are pushing unit specifications toward 2-inch outer diameter and 30,000-foot reach depths.
Hydraulic Fracturing anchors capital intensity across the technology stack; Well Logging is climbing the fastest on digital integration.
Application:
Volume concentration in onshore unconventional plays contrasts with margin concentration in technically complex offshore environments.
- Onshore Extraction:Horizontal drilling and multistage completions dominate activity in North American shale basins. Permian density requirements force rapid frac fleet redeployment and continuous well intervention scheduling.
- Offshore Exploration:Subsea completions and floating production systems command day-rate premiums in deepwater frontiers. Guyana's Stabroek Block developments are pulling specialized installation vessels toward South Atlantic logistics hubs.
- Enhanced Oil Recovery:CO2 flooding, steam injection, and chemical EOR extend field life in mature provinces. Carbon capture bundled contracts are integrating post-combustion capture into gas processing and EOR project economics.
- Production Optimization:Artificial lift, surface facility tuning, and real-time monitoring sustain output curves. Digital automation platforms enable remote operations centers to manage distributed asset portfolios.
Onshore Extraction captures the greatest activity volume; Offshore Exploration maintains the steepest expansion trajectory on frontier discoveries.
End User:
Customer type dictates contract structure, with national oil companies favoring long-term framework agreements and independents seeking performance-guaranteed bundles.
- Exploration Companies:Venture-backed upstream firms prioritize drilling speed and cost certainty in appraisal programs. Equity financing constraints limit their appetite for integrated service commitments.
- National Oil Companies:State-controlled entities in Brazil, Saudi Arabia, and Abu Dhabi anchor deepwater and megaproject demand. Pre-salt and offshore gas developments require multi-year contracting horizons and local content compliance.
- Independent Operators:Permian Basin pure-play producers bundle drilling, completion, and artificial lift under single-provider agreements. Vendor management overhead reduction and operational risk transfer drive integrated contract adoption.
- Oilfield Contractors:Service firms subcontract specialized capabilities—directional drilling, cementing, well testing—to fill portfolio gaps. Technician scarcity and demographic retirements elevate subcontractor wage premiums.
National Oil Companies anchor long-term capacity commitments; Independent Operators are gaining share fastest on unconventional activity concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin's federal tax incentives for enhanced oil recovery are concentrating oilfield services investment in West Texas and southeast New Mexico, with secondary demand clusters forming around deepwater frontiers and mature basin workover programs.
United States
EPA methane fee structures under the Inflation Reduction Act are accelerating LDAR service deployment across the Permian Basin. OSHA hydrogen sulfide protocols elevate certification costs for rig-floor operations in Texas and New Mexico. Midland-Odessa anchors frac fleet redeployment and continuous well intervention scheduling for independent operators.
Brazil
Pre-salt discoveries in the Santos Basin are pulling specialized offshore drilling contractors toward subsea completion projects. Petrobras-led local content mandates require foreign service firms to partner with domestic fabricators. Macaé serves as the primary logistics hub for installation vessels supporting deepwater development.
Guyana
ExxonMobil consortium activity in the Stabroek Block is generating demand for floating production hookup and subsea tieback installation services. The government's petroleum regulator enforces environmental compliance standards for offshore contractors. Georgetown functions as the supply base for South Atlantic logistics coordination.
Saudi Arabia
Aramco's gas expansion and unconventional development programs are sustaining long-term framework agreements with integrated service providers. The national oil company imposes strict local content and Saudization workforce requirements. Dhahran-Riyadh corridor concentrates engineering centers and equipment maintenance facilities.
Norway
North Sea electrification and carbon capture integration are reshaping contract specifications for turbomachinery providers. Petroleum Safety Authority regulations mandate zero-emission platform designs for new field developments. Stavanger anchors subsea technology clusters and remote operations centers.
Oilfield Services Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered contract categories. The market structures around three player clusters: integrated full-service providers bundling multiple capability lines, technology-focused equipment vendors commanding performance premiums, and regional contractors capturing localized maintenance and intervention work. Consolidation pressure favors scale-driven M&A among pressure pumping and drilling rig segments, while portfolio diversification into carbon capture and digital solutions reshapes competitive positioning.
Among North American integrated providers, Schlumberger Limited, Halliburton Company, and Baker Hughes Company exemplify the full-service archetype spanning drilling, completion, and production optimization. These entities anchor premium contract tiers through bundled performance guarantees and emissions-compliant equipment fleets. China Oilfield Services Limited represents the state-backed international competitor model, while specialized offshore contractors such as TechnipFMC plc occupy positions in subsea installation and floating production systems.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International |
| National Oilwell Varco |
| China Oilfield Services Limited |
| TechnipFMC plc |
| Expro Group |
| Superior Energy Services |
| Others |
Cost & Logistics Intelligence
Rig day-rate volatility in West Texas and the Gulf of Mexico flows through contract tiers, with AC-powered land rigs commanding premiums against legacy mechanical fleets while spot-market frac crews absorb fuel surcharge compression. EPA methane compliance costs embed into pneumatic equipment leasing rates, splitting the market between emission-certified packages and discounted conventional offerings.
Pricing Analysis
Short lead-time premiums for high-spec offshore drillships separate spot-market contracting from long-term framework agreements with Petrobras and Aramco. Three-tier pricing structure across premium, standard, and economy levels reflects API certification grade, crew experience tiers, and bundled digital monitoring capabilities. Pricing pressure stems from independent operator budget constraints in the Permian Basin, where vendor consolidation squeezes commodity pumping margins. Exploration companies exhibit highest price sensitivity due to equity financing limits, while national oil companies prioritize performance guarantees over unit economics.
Supply Chain Analysis
Rail freight costs for Northern White Sand proppant from Wisconsin and regional brown sand alternatives compress margins when diesel surcharges spike and track capacity tightens. Equipment fabrication concentrates in the United States, China, and South Korea, with advanced AC land rigs and offshore drillships clustering among specialized shipyards. Supply chains draw from high-grade steel alloys, high-horsepower diesel engines, and proprietary downhole electronics. Single-source vulnerability around subsea BOP control systems creates procurement risk for deepwater contractors. Distribution runs through Midland-Odessa supply bases for Permian operations and Macaé logistics hubs for Brazil deepwater campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oilfield services sector operates as a vertical-integration race, with incumbents pursuing captive control over electric frac fleet manufacturing and proppant mining to defend margin pools against commoditization.
For Market Incumbents: To counter electric fleet technology disruption from emerging turbomachinery specialists, Schlumberger and Halliburton should deepen backward integration into natural gas turbine generator production and secure exclusive supply agreements with Northern White Sand mining operations. Certification investment in dual EPA-API methane performance specifications creates switching costs for Permian independents. For New Entrants and Emerging Players: Independent directional drilling consultancies offer the most penetrable entry point, given demographic retirements and technician scarcity elevating wage premiums. Target Guyana offshore logistics coordination and LDAR service deployment in EPA-regulated basins as white-space opportunities. Partner with regional equipment lessors to bypass capital-intensive fleet ownership requirements. For Investors and Strategic Acquirers: Aramco's gas expansion program awarding multi-year framework agreements is the leading indicator that Saudi unconventional development will sustain premium contract tiers. Long-term viability favors vertically integrated providers with carbon capture turbomachinery portfolios. Watch for EPA methane fee enforcement intensity as the signal for electric fleet adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Frac Fleet Conversion | Natural gas turbine generators eliminate EPA methane fee exposure in Permian and DJ Basin operations. |
| Subsea Installation Vessel Capacity Buildout | Specialized assets capture day-rate premiums from ExxonMobil-led Guyana Stabroek Block developments. |
| Carbon Capture Turbomachinery Integration | Baker Hughes bundles post-combustion capture into Aramco gas processing and EOR project economics. |
| Digital Twin Platform Deployment | Remote operations centers manage distributed Permian assets through predictive maintenance algorithms. |
| Proppant Mining Backward Integration | In-house Northern White Sand production insulates margins from rail capacity bottlenecks and fuel volatility. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining structured interviews with drilling contractors, completion engineers, procurement leads at Permian independents, and regulatory compliance officers at EPA regional offices. Primary fieldwork triangulated against IHS Markit rig count databases, EIA production statistics, SEC 10-K equipment utilization disclosures, and Bureau of Land Management leasing records. Bottom-up rig fleet deployment models and top-down basin-level expenditure estimates were reconciled to validate market sizing.
Segmentation granularity modeled service type at the contract line-item level, technology tier by horsepower and emissions certification, application across onshore unconventional and offshore frontier basins, and end-user archetype from NOC framework agreements to independent spot purchasing. CAGRs were derived from equipment capacity deployment trajectories and operator capital guidance across the projection horizon. Forecast inputs incorporated EPA methane fee implementation schedules and Petrobras pre-salt development timelines.
Several conditions sit outside the modeled scope, including sudden OPEC+ production quota shifts, deepwater drilling moratoriums, and breakthrough geothermal or hydrogen substitution technologies. Forecasts reflect stated operator budgets and regulatory implementation assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
Thailand Oil and Gas Upstream Market
Oil & Gas
Well Cementing Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
Downhole Equipment Market
Oil & Gas
Digital Oilfield Market
Oil & Gas
Subsea Flowlines Market
Oil & Gas
Colombia Oil and Gas Midstream Market
Oil & Gas
North America Oil Country Tubular Goods Market
Oil & Gas
Zonal Isolation Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
Italy Oil and Gas Market
Oil & Gas
Oilfield Equipment Rental Services Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Global Hydrate Inhibitors Market