
 North America Medical Devices Market | 2026-2036
North America Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Medical Devices Market Analytics
Aftermarket service revenue is tilting toward predictive maintenance contracts and remote calibration services. Stryker Corporation leverages its orthopedic implant installed base to secure long-term service agreements. Medtronic anchors its cardiac rhythm management portfolio through proprietary remote monitoring platforms. Abbott Laboratories competes in diabetes care by integrating continuous glucose monitoring with closed-loop insulin delivery systems.
Medical devices encompass instruments, apparatus, machines, and implants intended for diagnosis, prevention, monitoring, or treatment of disease, typically requiring biocompatibility testing under ISO 10993 and electrical safety validation per IEC 60601. Diagnostic Equipment commands the largest revenue pool due to imaging modality replacement cycles in hospital systems. Minimally Invasive Techniques expand fastest as ambulatory surgical centers seek reduced recovery protocols and lower infection risk profiles. Wearable Devices concentrate margin in subscription-based data analytics rather than hardware sales alone.
The FDA's Quality System Regulation and 21 CFR Part 820 govern manufacturing controls, while Health Canada and Mexico's COFEPRIS impose parallel premarket requirements that shape cross-border product registration strategies. The EU MDR's extraterritorial influence pressures North American manufacturers to maintain dual compliance documentation for export eligibility. Stakeholders must monitor CMS reimbursement coding decisions for remote patient monitoring as these determinations dictate provider adoption velocity and device manufacturer commercialization priorities.
Market Dynamics
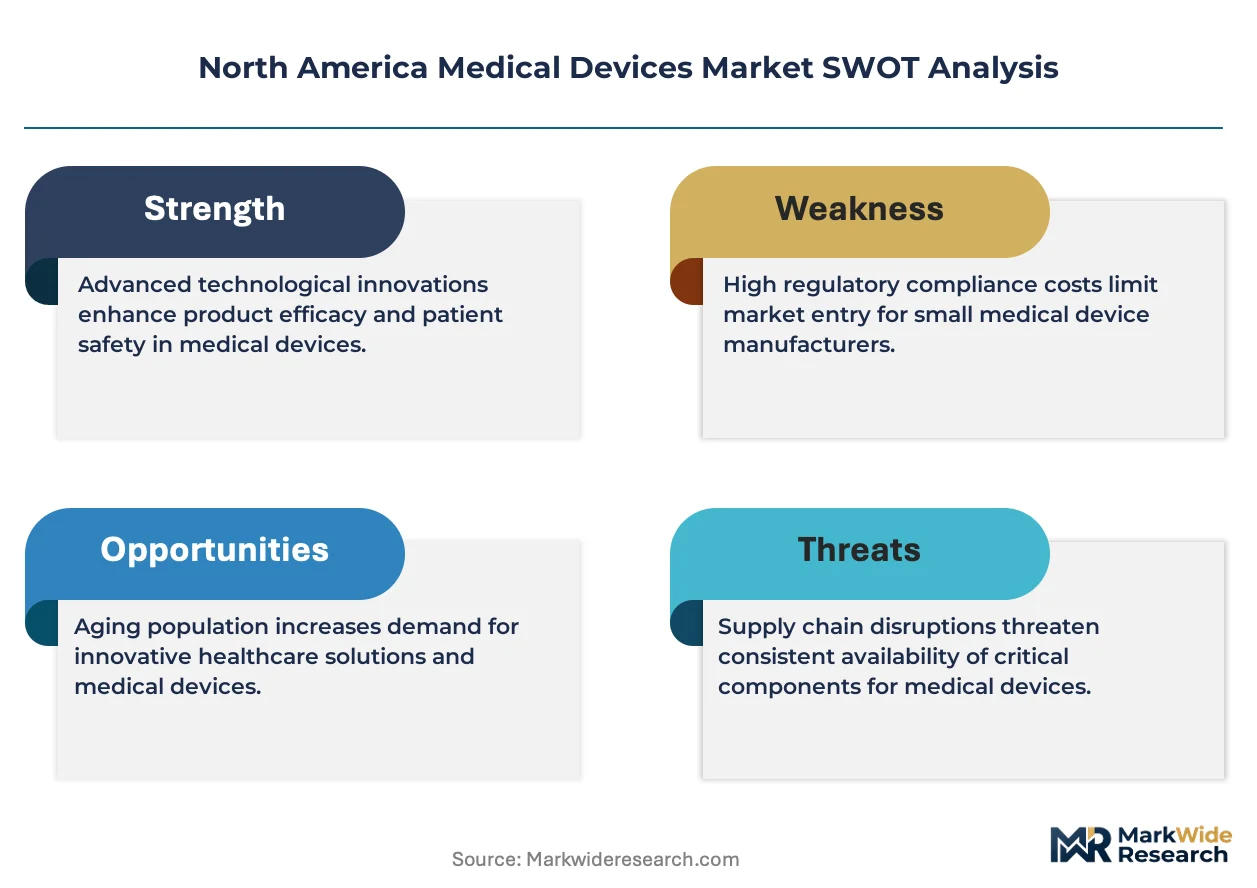
The North America medical devices market is reconfiguring around the FDA's accelerated 510(k) clearance pathway, which compresses time-to-revenue for moderate-risk diagnostics while forcing manufacturers to maintain dual documentation for Health Canada and COFEPRIS parallel submissions.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:CMS established dedicated CPT codes for continuous physiologic monitoring, triggering hospital system procurement of connected cardiac and respiratory devices across the United States.
- California Medtech Corridor Concentration:The San Diego-to-San Francisco cluster concentrates venture funding, specialized manufacturing subcontractors, and FDA-experienced regulatory consultants within a single logistics radius.
- Minimally Invasive Surgical Migration:Ambulatory surgical centers in Texas and Florida are replacing open-procedure suites with laparoscopic and robotic platforms, driving instrument and visualization equipment replacement cycles.
Market Restraints
- Semiconductor Component Volatility:Analog and sensor chip lead times from Asian foundries create production scheduling uncertainty for patient monitoring OEMs with just-in-time assembly models.
- ISO 10993 Testing Bottlenecks:Biocompatibility validation queue times at third-party laboratories extend premarket submission preparation by four to six months for implantable device categories.
- Single-Use Plastic Substitution Pressure:California's extended producer responsibility mandates and hospital sustainability procurement criteria threaten margins on disposable surgical instrument kits.
Strategic Opportunities
- Mexico Manufacturing Expansion:COFEPRIS regulatory alignment with FDA standards enables Tijuana and Guadalajara facilities to serve both domestic Mexican demand and US tariff-advantaged re-export.
- Closed-Loop Insulin Integration:Convergence of continuous glucose sensing algorithms with automated pump delivery creates new device category definitions requiring updated FDA software-as-medical-device guidance.
- Direct-to-Provider Distribution:Manufacturer-owned e-commerce platforms bypassing traditional GPO contracts capture margin from mid-size specialty clinics in the US Mountain West region.
Industry Challenges
- Embedded Systems Cybersecurity Expertise:FDA's postmarket cybersecurity guidance demands in-house penetration testing capabilities that legacy device engineering teams lack.
- EU MDR Documentation Duplication:North American manufacturers maintaining European market access must sustain parallel technical file systems, diverting regulatory affairs resources from US product line extensions.
- Legacy Hospital IT Integration:New connected devices face interoperability friction with entreained EHR systems from dominant US health information technology vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Medical Devices Market |
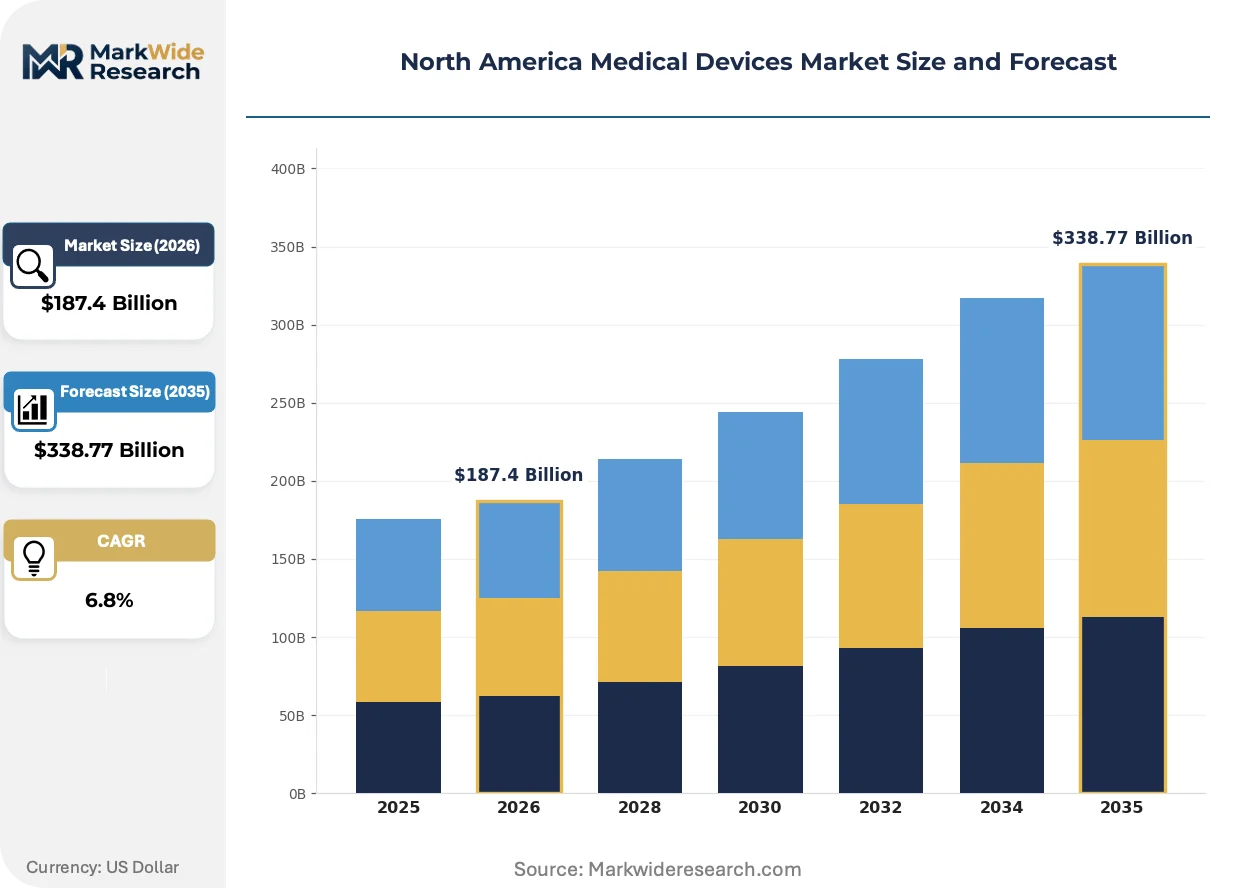
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Equipment, Surgical Instruments, Patient Monitoring Devices, Therapeutic Appliances End User: Hospitals, Clinics, Home Care Settings, Rehabilitation Centers Technology: Wearable Devices, Imaging Technology, Minimally Invasive Techniques, Telehealth Solutions Application: Cardiology, Orthopedics, Neurology, Gastroenterology |
| Companies Covered | Stryker Corporation, Zimmer Biomet, Medtronic, General Electric, Danaher Corporation, Johnson & Johnson MedTech, Boston Scientific Corporation, Cardinal Health, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Medical Devices Market Evolving Landscape
Device architectures are pivoting from hardware-centric revenue models toward software-enabled service platforms, with predictive analytics subscriptions displacing transactional equipment sales in cardiology and diabetes management segments.
Artificial intelligence-enabled diagnostic algorithms are migrating from cloud-based inference to edge-computing deployment within device hardware. Radiology departments at US academic medical centers are piloting on-device CT and MRI analysis to reduce latency and HIPAA exposure. This architecture shift is compressing data infrastructure requirements while elevating FDA software validation burdens for manufacturers.
The FDA's 2023 final guidance on predetermined change control plans for machine learning-enabled devices is altering submission strategies. Device sponsors can now lock algorithm update protocols during initial clearance rather than filing supplements for each improvement. Cardiac monitoring and sleep apnea diagnostic manufacturers are restructuring quality systems to exploit this pathway.
Hospital procurement departments are consolidating vendor relationships through single-source agreements for entire therapeutic categories. Integrated delivery networks in the US Northeast are awarding five-year sole-source contracts covering imaging, surgical instrumentation, and associated consumables. This concentration is marginalizing regional distributors and forcing mid-tier manufacturers to align with platform sponsors or exit institutional channels entirely.
North America Medical Devices Market Segmentation
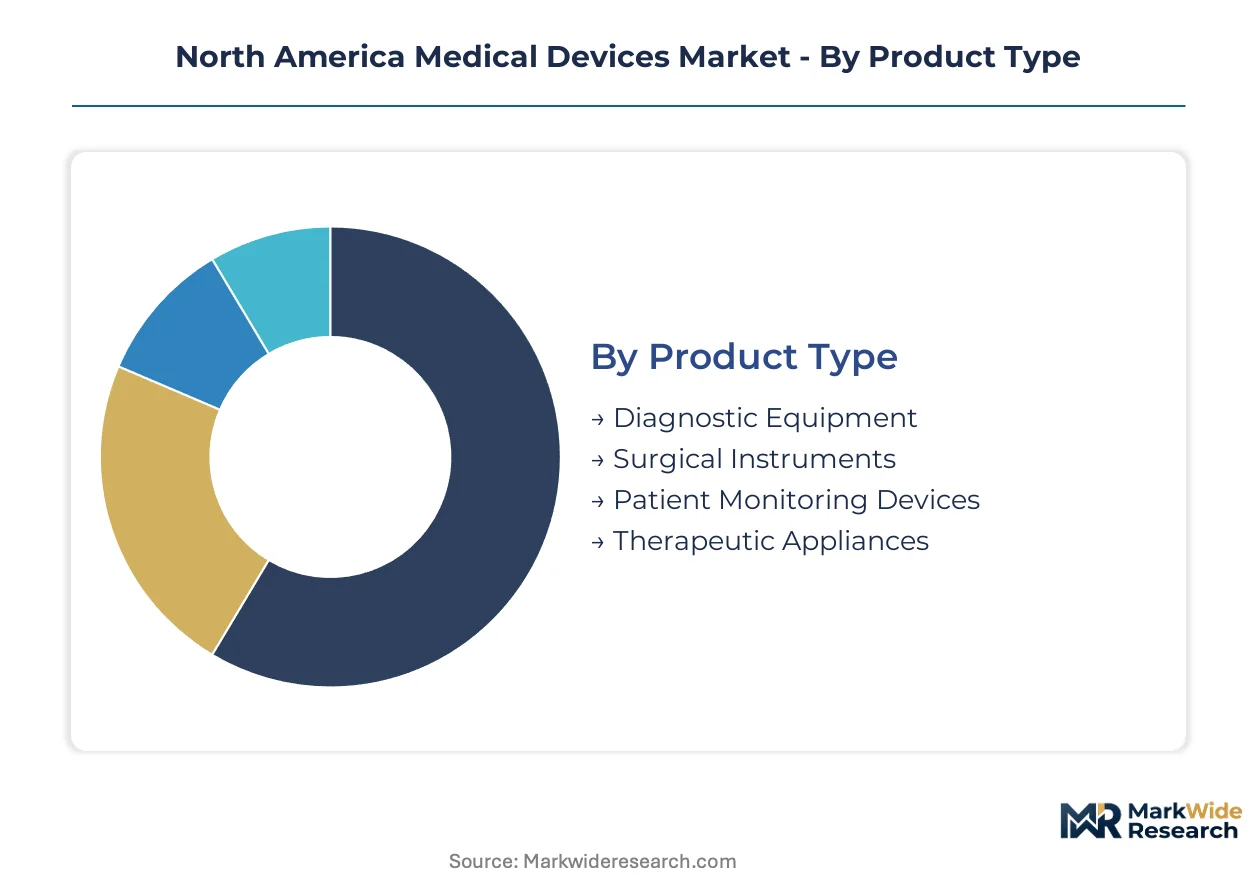
Segmentation reveals how procurement priorities diverge across North American healthcare infrastructure. Hospital capital budgets, ambulatory surgical center expansion, and home-based reimbursement codes each reshape device category performance.
Product Type:
Cost tier stratification separates capital-intensive imaging platforms from recurring consumable revenue streams.
- Diagnostic Equipment:CT, MRI, and ultrasound systems require electrical safety validation per IEC 60601 and carry replacement cycles tied to CMS technology add-on payments. Hospital systems in California's medtech corridor concentrate procurement of premium imaging suites.
- Surgical Instruments:Reusable and single-use instrument kits face margin pressure from California extended producer responsibility mandates and hospital sustainability criteria. Texas ambulatory surgical centers drive laparoscopic platform adoption.
- Patient Monitoring Devices:Connected cardiac and respiratory systems leverage dedicated CPT reimbursement codes.
- Therapeutic Appliances:Implantable and external therapeutic hardware demands ISO 10993 biocompatibility testing.
Diagnostic Equipment commands the established base. The steepest expansion runs through Patient Monitoring Devices.
End User:
Customer type determines purchasing authority, contract structure, and service integration requirements.
- Hospitals:Integrated delivery networks in the US Northeast award sole-source five-year contracts spanning imaging, surgical instrumentation, and consumables. FDA 510(k) clearance timelines directly impact capital budget allocation cycles.
- Clinics:Mid-size specialty practices in the US Mountain West region increasingly purchase through manufacturer-owned e-commerce platforms bypassing traditional GPO contracts.
- Home Care Settings:Remote patient monitoring reimbursement codes trigger demand for connected physiologic devices.
- Rehabilitation Centers:Post-acute facilities prioritize durable therapeutic appliances with predictive maintenance service agreements.
Hospitals anchor volume concentration. Home Care Settings are climbing the fastest.
Technology:
Maturity curves separate established imaging modalities from emerging software-enabled service platforms.
- Wearable Devices:Continuous glucose monitors and cardiac event recorders generate recurring subscription revenue from data analytics rather than hardware sales alone. Abbott Laboratories competes through closed-loop insulin integration.
- Imaging Technology:CT and MRI systems with on-device AI analysis reduce latency and HIPAA exposure for radiology departments at US academic medical centers.
- Minimally Invasive Techniques:Laparoscopic and robotic platforms displace open-procedure suites in Texas and Florida ambulatory surgical centers.
- Telehealth Solutions:Remote diagnostic and therapeutic delivery platforms face interoperability friction with entrenched EHR systems.
Imaging Technology holds the installed base. Wearable Devices are gaining share fastest.
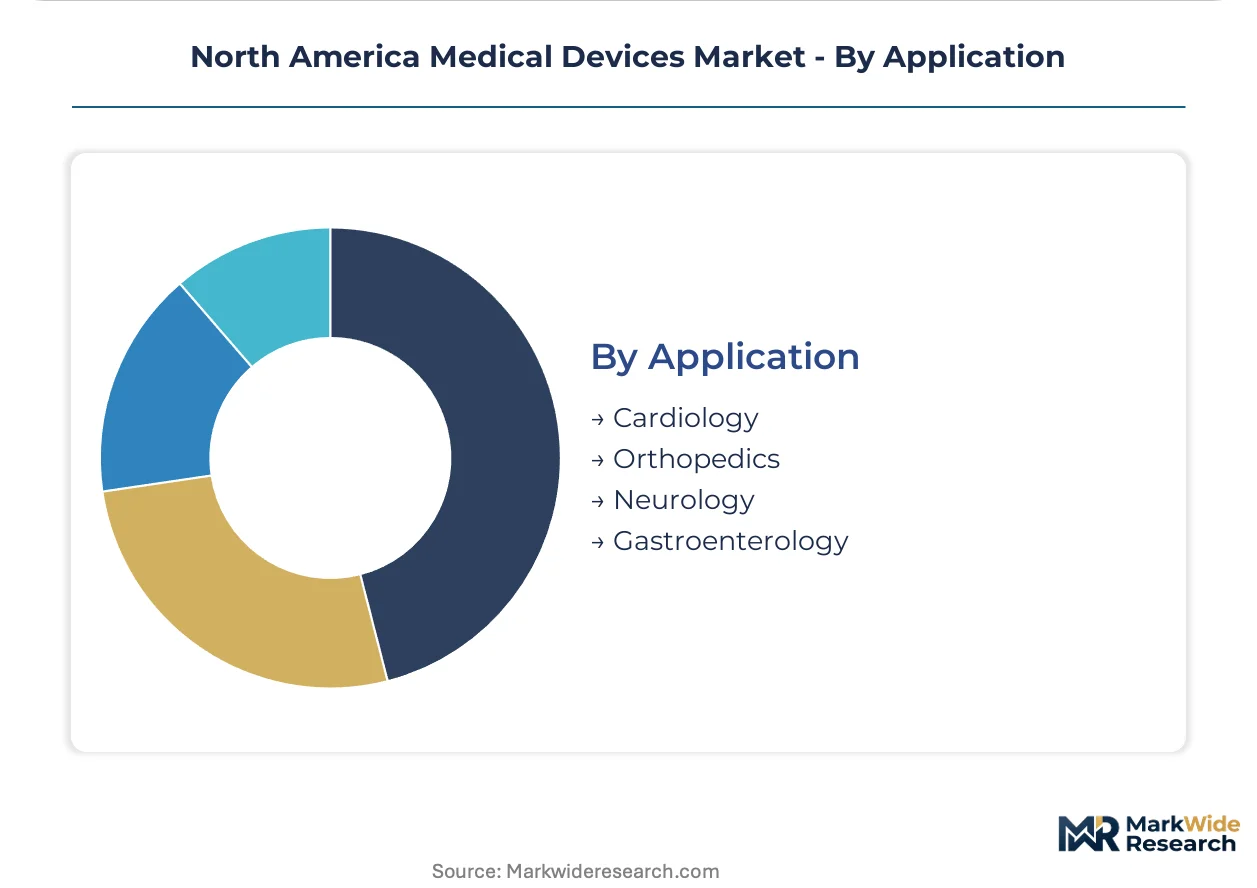
Application:
Clinical volume and reimbursement intensity concentrate demand in specific therapeutic categories.
- Cardiology:Cardiac rhythm management devices anchor proprietary remote monitoring platforms. Medtronic secures long-term service agreements through predictive analytics subscriptions.
- Orthopedics:Implantable joint reconstruction systems leverage installed base relationships for aftermarket service contracts. Stryker Corporation captures recurring revenue from predictive maintenance agreements.
- Neurology:Deep brain stimulation and neurodiagnostic devices require specialized surgical training infrastructure.
- Gastroenterology:Endoscopic systems and capsule-based diagnostics compete on disposable versus reusable instrument economics.
Cardiology dominates revenue concentration. Orthopedics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in three national jurisdictions with divergent regulatory pathways and procurement incentives. The United States dominates capital equipment demand while Canada and Mexico anchor distinct supply chain functions.
United States
Hospital systems in California's medtech corridor and Texas ambulatory surgical centers drive imaging and minimally invasive platform procurement. The FDA's 510(k) premarket notification pathway compresses clearance timelines for moderate-risk diagnostics. Boston and Minneapolis-St. Paul anchor cardiac rhythm management and neurological device development clusters.
Canada
Provincial health authorities in Ontario and Quebec consolidate procurement through group purchasing organizations for diagnostic imaging suites. Health Canada's Medical Devices Bureau maintains parallel premarket requirements that shape cross-border registration strategies. Toronto's MaRS Discovery District concentrates digital health and AI-enabled diagnostic startups.
Mexico
Tijuana and Guadalajara manufacturing facilities serve US tariff-advantaged re-export demand for disposable surgical instruments. COFEPRIS regulatory alignment with FDA standards enables dual-market production certification. Mexico City anchors domestic distribution networks for patient monitoring devices serving public hospital systems.
North America Medical Devices Market Competitive Landscape
Diversified conglomerates and specialized device manufacturers split the market across distinct capability tiers. The vendor base concentrates around three strategic archetypes: integrated orthopedic and cardiovascular platforms, diagnostic imaging and consumables systems, and hospital supply chain intermediaries. Competitive positioning depends on installed base relationships for aftermarket service revenue and regulatory submission velocity for new product categories.
Among diversified health technology conglomerates, Medtronic and Abbott Laboratories exemplify platform-centric strategies built on proprietary remote monitoring ecosystems. Stryker Corporation occupies a position within the orthopedic reconstruction tier where predictive maintenance contracts secure long-term revenue from implant installed bases. These three entities represent the dominant archetype of hardware-enabled service platforms displacing transactional equipment sales.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet |
| Medtronic |
| General Electric |
| Danaher Corporation |
| Johnson & Johnson MedTech |
| Boston Scientific Corporation |
| Cardinal Health |
| Abbott Laboratories |
| Others |
Value Network & Pricing Analysis
Undercapacity in ISO 10993-certified biocompatibility laboratories concentrates validation queue power among third-party testing providers, enabling premium pricing for expedited premarket submission support while forcing device manufacturers to absorb extended timeline costs or pay rush premiums for regulatory clearance acceleration.
Pricing Analysis
FDA's 510(k) premarket notification pathway dictates the pricing tier structure across moderate-risk device categories, separating premium-priced predicate-dependent clearances from standard de novo submissions and economy-tier exempt Class I hardware. Price differentiation rests on certification grade—ISO 13485 quality system registration commands supplier premiums—and volume scale through integrated delivery network sole-source contracts. Cost compression in single-use surgical instrument kits intensifies because California extended producer responsibility mandates layer compliance overhead onto disposable manufacturing. Mid-size specialty clinics in the US Mountain West exhibit highest price sensitivity, diverting procurement toward manufacturer-owned e-commerce platforms that bypass traditional GPO markup structures.
Supply Chain Analysis
Export control restrictions on advanced semiconductor manufacturing equipment limit analog and sensor chip flows from Taiwanese and South Korean foundries, constraining patient monitoring OEM assembly schedules. Component sourcing draws from Malaysia for precision-machined surgical instrument blanks, Mexico for tariff-advantaged disposable kit final assembly, and Germany for high-reliability imaging system subassemblies. Single-source vulnerability concentrates in Asian sensor chip suppliers with 26-week quoted lead times. Distribution runs through diversified health technology conglomerates' captive service organizations rather than independent regional distributors, compressing margin capture for mid-tier manufacturers lacking direct hospital system relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-enabled service platforms represent an active substitution threat to transactional equipment revenue models, requiring incumbent hardware manufacturers to defend recurring revenue streams against AI-native diagnostics entrants unburdened by legacy installed base transition costs.
For Market Incumbents: Build proprietary remote monitoring data moats by embedding predictive analytics subscriptions into cardiac rhythm management and orthopedic implant installed bases. Secure long-term service agreements through predictive maintenance contracts that increase customer switching costs. Counter AI-native diagnostic entrants by accelerating FDA predetermined change control plan submissions for machine learning-enabled algorithm updates, locking regulatory pathways before software-as-medical-device guidance tightens.
For New Entrants and Emerging Players: Mexico's underpenetrated public hospital systems offer white-space expansion for patient monitoring devices serving COFEPRIS-certified domestic demand with US re-export optionality. Target mid-size specialty clinics in the US Mountain West through manufacturer-owned e-commerce platforms that bypass entrenched GPO contracting structures. Lead with closed-loop insulin integration systems that exploit FDA software validation guidance gaps before incumbent diabetes care conglomerates consolidate algorithmic control.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated orthopedic and cardiovascular platform sponsors with installed base relationships convertible to predictive maintenance revenue streams. Long-term viability favors manufacturers with demonstrated FDA submission velocity and Health Canada parallel registration capabilities. Watch CMS reimbursement coding decisions for remote patient monitoring as the inflection signal—dedicated CPT code expansions would accelerate provider adoption velocity and elevate device manufacturer commercialization priorities.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Predetermined Change Control Plan Submission | Locks machine learning algorithm update protocols during initial clearance, reducing regulatory burden for cardiac monitoring manufacturers. |
| Hospital System Partnership | Secures five-year sole-source contracts spanning imaging, surgical instrumentation, and consumables in US Northeast integrated delivery networks. |
| Software Companion Development | Enables predictive analytics subscriptions that displace transactional equipment sales in cardiology and diabetes management segments. |
| Reimbursement Strategy | Aligns device commercialization priorities with CMS CPT code determinations for remote patient monitoring adoption velocity. |
| CE Marking Pathway | Maintains European market access through EU MDR technical file systems parallel to FDA documentation requirements. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with device development executives, regulatory affairs specialists, hospital purchasing committee members, and GPO contracts managers; and secondary validation against FDA 510(k) submission databases, Health Canada Medical Devices Bureau filings, CMS Medicare reimbursement code determinations, and hospital procurement system records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the North American medical devices value chain.
Forecast inputs incorporated product type stratification by capital intensity and consumable recurrence, end user differentiation across hospital system tier and ambulatory surgical center expansion velocity, technology maturity curves separating established imaging from emerging wearable platforms, and application concentration in cardiology and orthopedics. CAGRs derived from replacement cycle analysis for diagnostic equipment, reimbursement code expansion trajectories for patient monitoring, and minimally invasive surgical migration rates in Texas and Florida ambulatory settings.
The forecast holds incumbent behavior within observed patterns; aggressive platform integration moves by AI-native diagnostic entrants or accelerated FDA software guidance shifts would shift outcomes. Material changes in semiconductor component availability from Asian foundries, CMS reimbursement coding decisions for remote patient monitoring, or EU MDR documentation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Refractive Surgery Devices Market
Medical Devices
Photorejuvenation Devices Market
Medical Devices
IoT Medical Devices Market
Medical Devices
United Kingdom Neonatal and Prenatal Devices Market
Medical Devices
Europe Sternal Closure Systems Market
Medical Devices
Pharma Robots Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Retinal Surgery Devices Market
Medical Devices
High Flow Oxygen Therapy Devices Market
Medical Devices
Transabdominal Retrieval Kits Market
Medical Devices
Global Embolization Particle Market
Medical Devices
Manometry System Market
Medical Devices
Global Semiconductor in Healthcare Market
Medical Devices
Organ Preservation & Perfusion Products Market
Medical Devices
Polyether Ether Ketone (PEEK) Interbody Devices Market
Medical Devices
Absorbable Nasal Implant Market