
 Egg and Egg Products Market | 2026-2036
Egg and Egg Products Market Size, Share, and Industry Trends Forecast 2026-2036
Egg and Egg Products Market Analysis
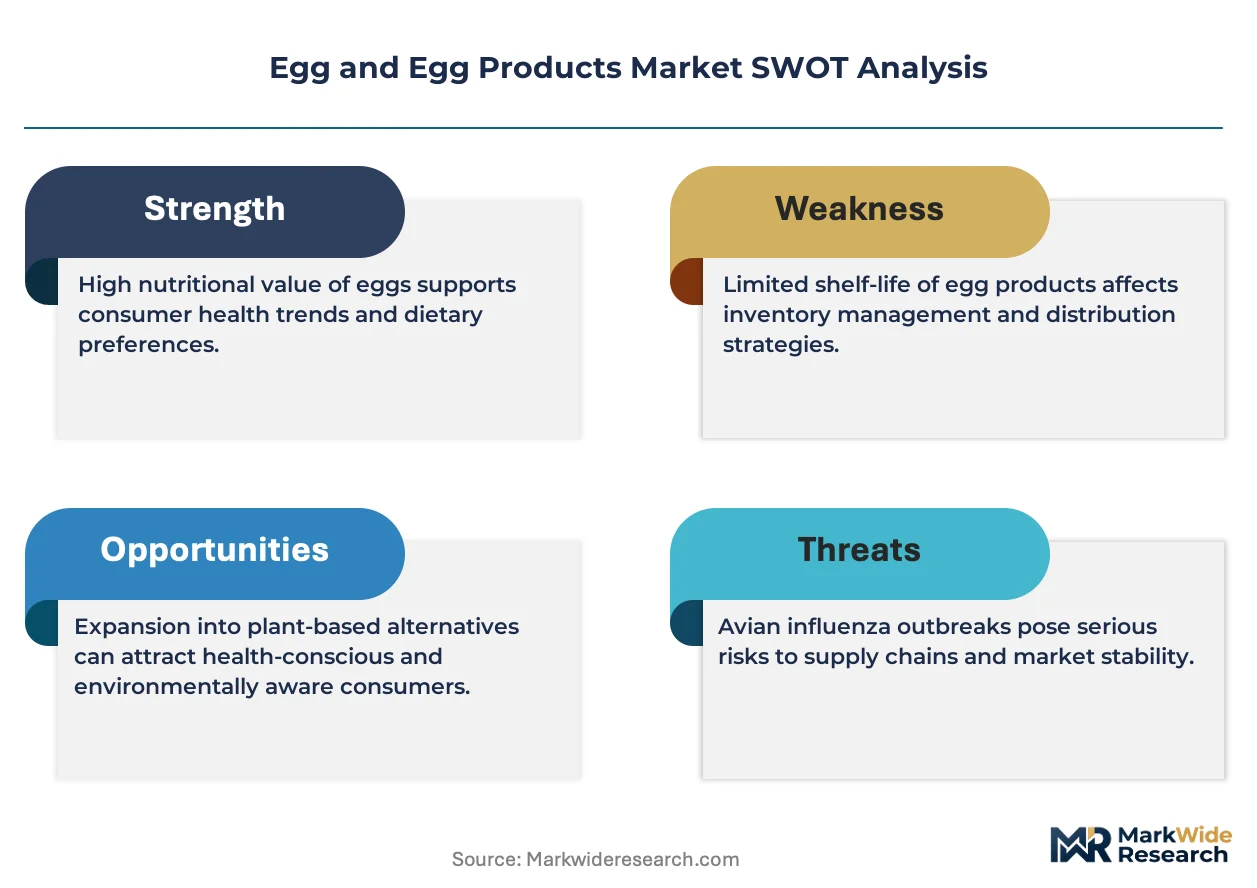
The capital-intensity divergence between automated cage-free operations and conventional barn systems is unwinding competitive parity across the industry. Cal-Maine Foods leverages vertical integration from feed mills to grading facilities to sustain margin control through volatile grain cycles. Rose Acre Farms anchors its position through geographic dominance across the Midwest and Southeast production belts. Herbruck's Poultry Ranch differentiates via specialized organic and free-range product lines that command premium channel placement.
Egg and egg products encompass shell eggs and further-processed formats including liquid, dried, frozen, and specialty preparations derived from whole eggs, whites, or yolks, with pasteurization temperatures typically reaching 60–64°C to eliminate Salmonella while preserving functional proteins for emulsification, foaming, and gelation in commercial food manufacturing. The food service end-user segment leads volume absorption through institutional kitchens and quick-service chains, while egg powder dominates export-oriented margin pools due to extended shelf stability and reduced cold-chain dependency. Liquid whole eggs remain the workhorse of industrial bakeries, though frozen specialty blends are gaining traction in premium dessert and sauce applications.
The USDA's Agricultural Marketing Service enforces grading standards that shape domestic product classification and interstate commerce, while the FDA's Egg Safety Rule mandates refrigeration and Salmonella prevention controls that dictate processing infrastructure investments. The EU Green Deal and F-Gas Regulation are accelerating cage-free transition timelines and cold-chain emission reductions across European member states. Stakeholders must monitor evolving state-level animal welfare ballot measures and carbon border adjustment mechanisms to anticipate capital reallocation requirements and market access conditions.
Market Dynamics
Cage-free transition mandates are compressing conventional barn capacity while automated aviary systems demand capital commitments that reshape producer economics across North America and Europe.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Binding cage-free deadlines through 2027 are forcing supply chain reconfiguration across German, French, and Dutch production clusters, opening premium shelf space for compliant operators.
- Quick-service restaurant procurement:Chains in India and Southeast Asia are standardizing pasteurized liquid egg specifications for kitchen safety and menu consistency, pulling volume through centralized processing facilities.
- Carbon accounting integration:Scope 3 emission tracking requirements from retail buyers are creating competitive separation for producers with verified low-carbon feed sourcing and renewable energy adoption.
Market Restraints
- Feed grain price volatility:Corn and soybean meal input costs swing with Black Sea supply disruptions and biofuel policy shifts, eroding margin predictability for non-integrated operators.
- Midwest production concentration:Iowa, Indiana, and Ohio house disproportionate shell egg capacity, creating regional disease exposure and logistics bottlenecks during extreme weather events.
- Plant-based egg substitutes:Mung bean and chickpea protein formulations are capturing bakery and food service trials where functional performance meets cost parity thresholds.
Strategic Opportunities
- India quick-service expansion:Tier-2 and Tier-3 city penetration by bakery chains and fast-food operators is outpacing domestic shell egg supply infrastructure, creating import and cold-chain investment openings.
- Egg white protein isolate:Sports nutrition and senior nutrition formulations are driving pharmaceutical-grade separation technology adoption, commanding price multiples over commodity liquid egg.
- Blockchain traceability:Retailer mandates for farm-to-fork verification are enabling premium positioning for early adopters of distributed ledger systems across European and North American channels.
Industry Challenges
- Aviary system automation expertise:Cage-free housing requires precision environmental control and bird behavior management that outstrips existing agricultural engineering talent pools.
- Dual certification timelines:Simultaneous pursuit of organic, free-range, and carbon-neutral labels creates audit complexity and extended payback periods for facility upgrades.
- Legacy processing line retrofit:Pasteurization and separation equipment from the 1990s lacks data integration capabilities needed for modern food safety compliance and yield optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg and Egg Products Market |
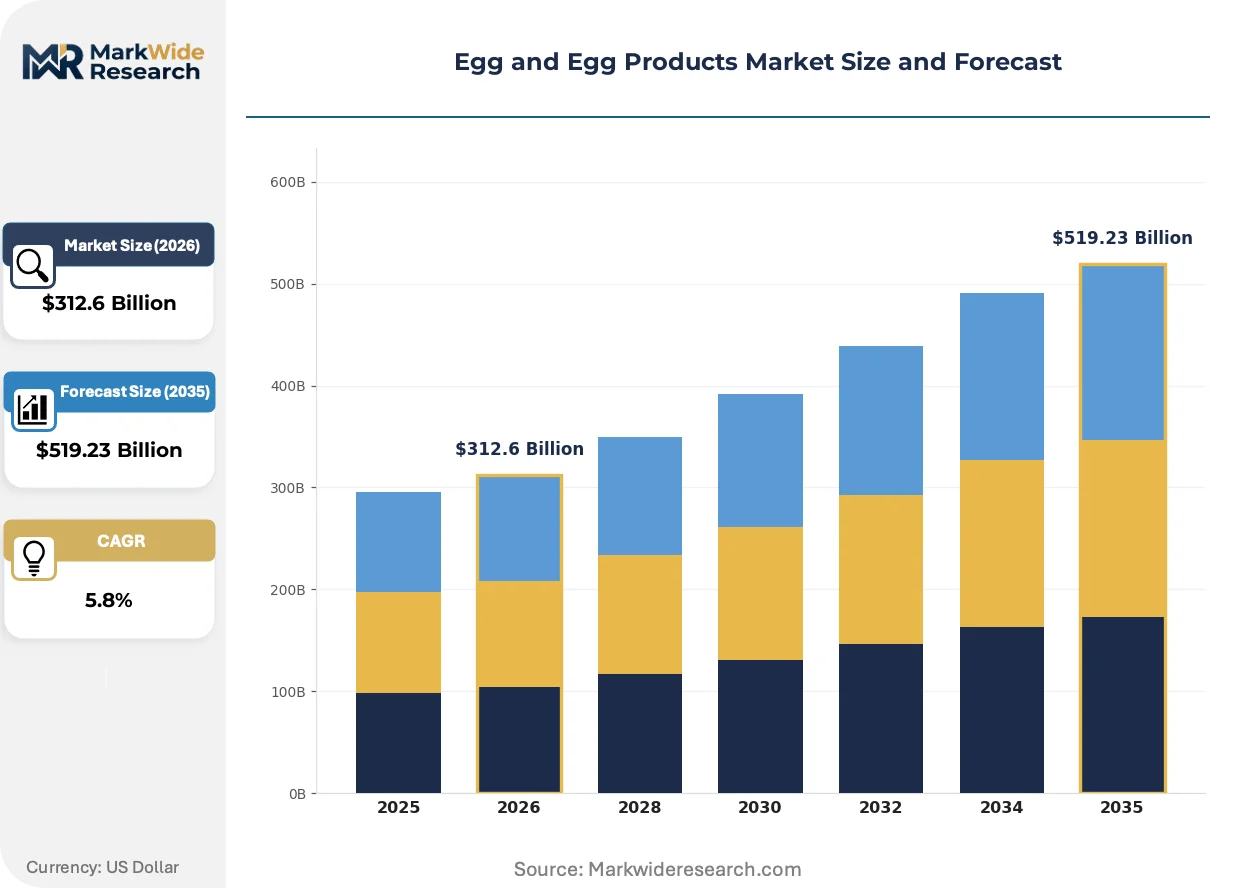
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $519.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Eggs, Egg White, Egg Yolk, Egg Powder Distribution Channel: Supermarkets, Online Stores, Convenience Stores, Wholesale End User: Food Service, Food Processing, Retail, Households Form: Liquid, Dried, Frozen, Specialty |
| Companies Covered | Fassio Egg Farms, Versova Holdings, Cal-Maine Foods, Michigan Chicken, Herbruck's Poultry Ranch, Rose Acre Farms, Daybreak Foods, Oakdell Egg Farms, Hillandale Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg and Egg Products Market Emerging Trajectories
In-line egg grading and robotic packing systems are compressing labor dependency while machine vision quality control is redefining throughput benchmarks across high-volume operations.
Machine vision defect detection is supplanting manual candling stations on grading lines. Industrial bakeries and liquid egg processors are adopting these systems at replacement cycle pace. The technology is enabling single-shift operations to match previous two-shift output while reducing Salmonella risk exposure through cracked-egg elimination.
The EU F-Gas Regulation is accelerating ammonia and CO2 refrigeration adoption in cold-chain infrastructure. Cold storage operators face retrofit deadlines that favor greenfield cage-free facilities over legacy barn conversions. German and Dutch packing stations are consolidating to capture scale efficiencies in compliant refrigeration systems.
Direct contracting between quick-service chains and integrated egg producers is fragmenting traditional distributor relationships. Food service operators in India and Southeast Asia are bypassing wholesale markets for specification-grade supply agreements. This pattern is most visible in Bangalore and Mumbai, where bakery manufacturing clusters demand consistent albumen height and yolk color metrics.
Egg and Egg Products Market Segmentation
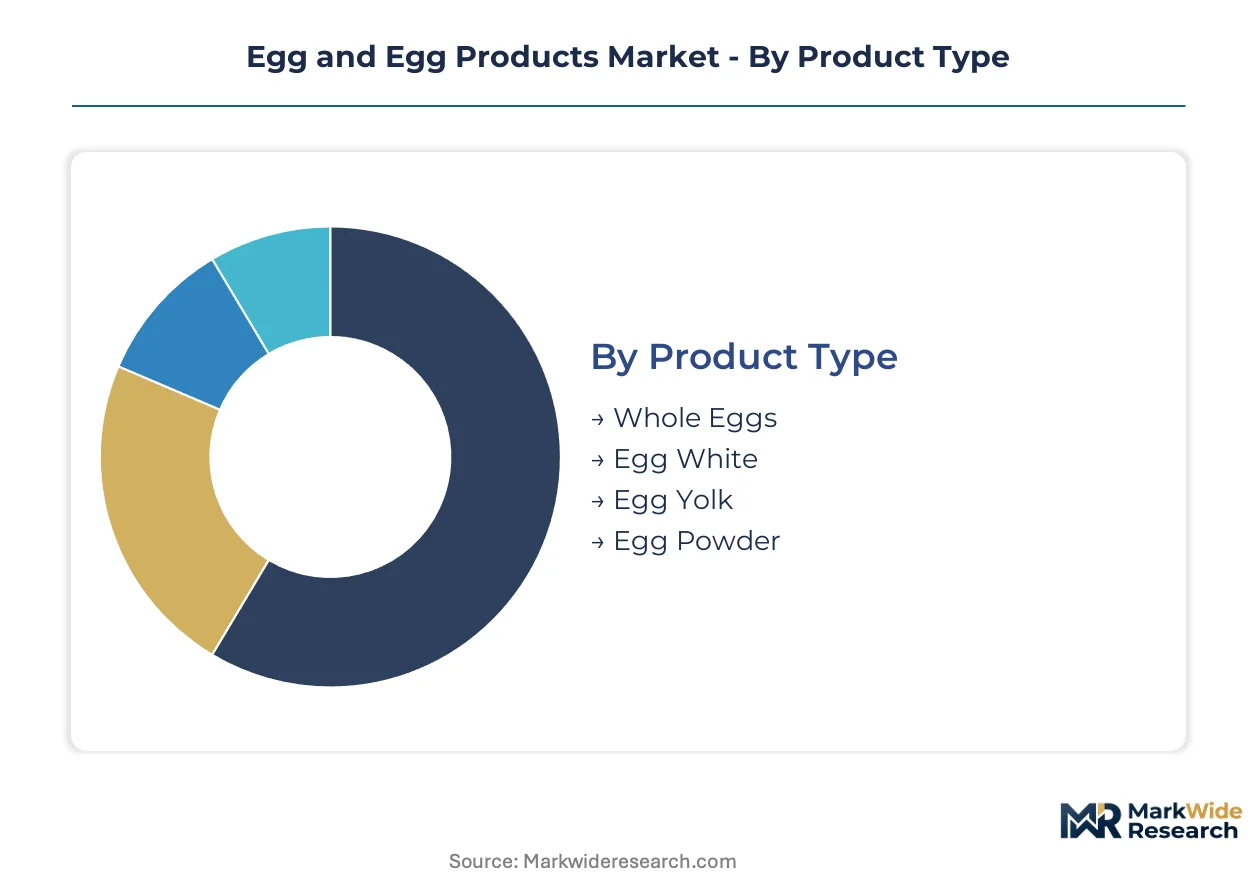
Egg and egg products fragment across four distinct category axes. Product type and form dimensions capture processing intensity and margin tier, while distribution channel and end user determine logistics configuration and specification requirements.
Product Type:
Margin pools concentrate in separated components and shelf-stable formats where functional protein extraction commands premium positioning.
- Whole Eggs:Shell eggs retain the largest volume base across retail and food service channels. Quick-service chains in India specify graded shell stock for kitchen consistency and traceability compliance.
- Egg White:Albumen separation yields pharmaceutical-grade protein isolates for sports nutrition and senior nutrition formulations. Industrial bakeries in Germany and France specify liquid egg white for macaron and meringue production where foaming stability is critical.
- Egg Yolk:High-lecithin fractions serve emulsification-heavy applications in mayonnaise and sauce manufacturing.
- Egg Powder:Spray-dried whole egg and separated powders eliminate cold-chain dependency for export markets and military procurement.
Whole eggs hold installed capacity. Egg white is rotating up the share rankings.
Distribution Channel:
Channel selection determines specification intensity, with direct contracting displacing traditional wholesale relationships in high-volume food service procurement.
- Supermarkets:Graded shell eggs and branded liquid cartons dominate shelf space. Cage-free and organic certifications drive SKU proliferation across German, French, and Dutch retail banners.
- Wholesale:Institutional volume flows through food service distributors and bakery supply cooperatives. Bangalore and Mumbai bakery manufacturing clusters bypass wholesale markets for direct processor contracts.
- Online Stores:Subscription models for specialty and organic shell eggs gain traction in urban Indian markets.
- Convenience Stores:Limited assortment focuses on commodity shell eggs for immediate consumption.
Wholesale maintains volume leadership. Online stores are climbing the fastest.
End User:
Application requirements split between specification-grade industrial buyers and price-sensitive household consumption.
- Food Processing:Pasteurized liquid egg and separated components feed industrial bakeries, pasta manufacturers, and prepared sauce producers. Albumen height and yolk color metrics are contractually specified.
- Food Service:Institutional kitchens and quick-service chains drive centralized procurement of liquid whole eggs for kitchen safety and menu standardization.
- Retail:Shell egg grading and branded packaging serve household consumers with welfare and origin labeling.
- Households:Direct farm-gate and farmers market purchases persist in rural production zones.
Food processing commands specification premiums. Food service is gaining share fastest.
Form:
Processing technology investment separates commodity liquid handlers from specialized freeze-dry and fractionation operators.
- Liquid:Pasteurized whole egg, white, and yolk remain the workhorse format for industrial bakeries. Temperature control at 60–64°C preserves functional proteins for emulsification and gelation.
- Frozen:Specialty blends with stabilizers serve premium dessert and sauce applications where extended thaw stability is required.
- Dried:Spray-dried and pan-dried formats reduce shipping weight and eliminate refrigeration for export and military supply chains.
- Specialty:Enzyme-modified and pre-gelatinized preparations target niche pharmaceutical and nutraceutical applications.
Liquid holds installed capacity. Specialty is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and the Netherlands outpaces margin capture in Indian spot markets, where fragmented supply chains compress processor returns. Regulatory divergence between EU cage-free mandates and developing-market infrastructure gaps is redrawing investment flows across production belts.
United States
Midwest grain corridors and automated grading infrastructure anchor shell egg volume. The FDA's Egg Safety Rule mandates Salmonella prevention controls that dictate cold-chain capital allocation. Iowa, Indiana, and Ohio house concentrated production capacity where extreme weather exposure creates periodic logistics bottlenecks.
Germany
Retail banner competition for cage-free shelf space accelerates processor consolidation. The EU Green Deal's farm-to-fork targets bind producers to 2027 welfare transition deadlines. Lower Saxony and Bavaria packing stations are capturing scale efficiencies through ammonia refrigeration retrofits mandated by F-Gas Regulation phase-outs.
India
Quick-service restaurant procurement standardization pulls volume toward pasteurized liquid specifications. FSSAI food safety compliance requirements shape centralized processing facility investments. Bangalore and Mumbai bakery manufacturing clusters bypass wholesale markets for direct contracting with specification-grade suppliers.
Netherlands
Export-oriented egg powder production commands premium positioning in military and humanitarian supply chains. EU carbon accounting integration creates competitive separation for verified low-carbon feed sourcing. Dutch packing cooperatives are consolidating to capture cold-chain emission reductions ahead of CSRD disclosure mandates.
China
Industrial bakery expansion drives liquid whole egg absorption in coastal manufacturing zones. SAMR food safety supervision standards enforce pasteurization infrastructure upgrades. Yangtze River Delta processing clusters are adopting machine vision grading systems to match European throughput benchmarks.
Egg and Egg Products Market Vendor Landscape
Concentration sits with vertically integrated producers controlling feed mills through grading facilities. The producer base fragments across regional cooperatives, family-owned operations, and specialty organic specialists. Strategic archetypes include scale-driven commodity handlers, premium-channel welfare certifiers, and export-focused powder processors. Competitive moves center on cage-free capacity conversion and direct quick-service restaurant contracting.
Within the integrated tier, Cal-Maine Foods exemplifies backward integration into captive feed supply, while Rose Acre Farms anchors geographic coverage across Midwest and Southeast production belts. Herbruck's Poultry Ranch occupies a position in the specialty segment through organic and free-range certification lines that command premium retail placement.
| Leading Market Players |
|---|
| Fassio Egg Farms |
| Versova Holdings |
| Cal-Maine Foods |
| Michigan Chicken |
| Herbruck's Poultry Ranch |
| Rose Acre Farms |
| Daybreak Foods |
| Oakdell Egg Farms |
| Hillandale Farms |
| Others |
Supply Flow & Price Mechanics
Long-term direct contracting between quick-service chains and integrated producers locks in volume commitments while stabilizing price visibility against spot market volatility. These agreements concentrate pricing power with vertically integrated operators who control feed sourcing through grading facilities.
Pricing Analysis
The customization-premium spread separates specification-grade liquid egg contracts from commodity shell egg spot markets. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale. Price differentiation hinges on cage-free and organic welfare credentials. Food service buyers show highest price sensitivity, while pharmaceutical-grade egg white isolates command least elasticity due to functional protein scarcity.
Supply Chain Analysis
The United States anchors shell egg volume through Midwest grain corridors, while the Netherlands concentrates export-oriented egg powder production. Raw material inputs draw from corn and soybean meal feed stocks, specialized refrigeration equipment, and automated grading machinery. Single-source vulnerability concentrates in Iowa, Indiana, and Ohio production clusters exposed to regional disease outbreaks. Distribution runs through direct processor contracts displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern this market as blockchain traceability systems create interoperability standards for farm-to-fork verification, reshaping how premium shelf access is allocated.
For Market Incumbents: Secure cage-free capacity conversion timelines ahead of EU Green Deal deadlines to preempt supply shortages. Lock in direct quick-service restaurant contracts in India before domestic infrastructure scales. Plant-based egg substitutes threaten bakery segment share; counter with pharmaceutical-grade protein isolate investments. For New Entrants and Emerging Players: Cold-chain infrastructure gaps in Tier-2 and Tier-3 Indian cities present service-layer openings where incumbents under-serve. Target Bangalore and Mumbai bakery manufacturing clusters with specification-grade supply agreements. Lead with blockchain-verified traceability as go-to-market differentiation. For Investors and Strategic Acquirers: Mid-scale organic and free-range certifiers with established retail placement represent attractive acquisition targets. Long-term viability rests on cage-free transition completion and carbon accounting integration. Watch for FSSAI enforcement intensity in India as inflection signal for centralized processing facility investments.| Strategic Initiative | Industry Significance |
|---|---|
| Cage-Free Capacity Conversion | EU Green Deal mandates force supply chain reconfiguration across German and Dutch production clusters. |
| Backward Integration into Feed Supply | Captive grain sourcing insulates margin control against Black Sea supply disruption volatility. |
| Blockchain Traceability Deployment | Retailer verification mandates enable premium positioning across European and North American channels. |
| Direct Quick-Service Contracting | Bangalore and Mumbai bakery clusters bypass wholesale markets for specification-grade supply agreements. |
| Pharmaceutical-Grade Protein Investment | Sports nutrition formulations command price multiples over commodity liquid egg products. |
Methodological Framework
Cross-validation between primary interviews with egg processing executives, feed procurement managers, and quick-service chain supply officers and secondary sources anchors the qualitative findings. USDA Agricultural Marketing Service grading standards, FDA Egg Safety Rule filings, EU F-Gas Regulation compliance databases, and FSSAI facility inspection records provide triangulation. Bottom-up facility capacity assessments and top-down consumption modeling reconcile volume estimates.
Sensitivity analysis tests forecast robustness across feed grain price volatility scenarios and cage-free transition pace assumptions. Segmentation dimensions span product type, form, distribution channel, and end user across the analysis window. CAGRs derive from trend extrapolation adjusted for regulatory mandate timing and infrastructure investment cycles. Machine vision adoption rates and ammonia refrigeration retrofit timelines inform industry-specific inputs.
Underlying assumptions cover EU Green Deal enforcement consistency and Indian quick-service expansion trajectories, with deviation risk concentrated in feed commodity shocks and animal welfare ballot measure outcomes. Recalibration cycles align with material shifts in carbon border adjustment mechanisms and FSSAI inspection intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Industrial Wearable Devices Market
Others
8K Technology Market
Others
High Frequency Vibrator Market
Others
Defense Optronics Market
Others
Global Extruded Plastics Market
Others
US Camping and Caravanning Market
Others
Video Conferencing Hardware Market
Others
Spinner Flask Market
Others
5G Devices Market
Others
Global Tobacco Market
Others
Middle East and Africa Surface Analysis Market
Others
Channel-In-A-Box (Ciab) Market
Others
Calendered Polyvinyl Chloride Flexible Films Market
Others
Spain Smart Home Market
Others
Aerospace Software Testing Market
Others
South America Halal Food and Beverages Market