
 Stand-Up Pouch Valves Market | 2026-2036
Stand-Up Pouch Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Stand-Up Pouch Valves Market Analysis
Single-source to multi-source procurement is restructuring supply relationships across the stand-up pouch valve value chain. Scholle IPN leverages its captive film and fitment manufacturing to control quality consistency for global beverage brands. Gualapack Group anchors its position through integrated spout-and-pouch systems designed for high-acid food applications. Amcor competes by extending its pre-made pouch footprint into valve-added formats for personal care and household chemical clients.
Stand-up pouch valves are mechanical fitments welded or inserted into flexible pouch structures to enable controlled dispensing, pressure equalization, or resealability, typically manufactured through injection molding of polyethylene or polypropylene resins with tolerances below 0.1 mm for seal integrity. Their primary commercial purpose is to transform passive flexible packaging into interactive consumer formats that reduce spillage and extend product freshness between uses. One-way valves now dominate food packaging applications where degassing of roasted coffee or fermented products requires outward pressure relief without oxygen ingress. Custom valves represent the fastest-growing product type as brands specify proprietary geometries for differentiation on retail shelves. Plastic remains the leading material segment, though composite constructions are gaining share where metalized barrier layers meet recyclability targets.
FDA food contact regulations in the United States and REACH chemical compliance in Europe jointly shape material approval pathways and migration testing protocols for valve components. The EU Green Deal and emerging extended producer responsibility frameworks are forcing converters to document recyclability credentials for multi-component fitments. Stakeholders must monitor how mechanical recycling infrastructure investments in Germany, Italy, and France alter design rules for valve-to-pouch compatibility before committing capital to next-generation tooling platforms.
Market Dynamics
Material substitution toward mono-polymer constructions is compressing design cycles across the stand-up pouch valve supply chain as converters race to meet recyclability mandates ahead of mechanical recycling infrastructure deployment.
Growth Catalysts
- EU Green Deal packaging requirements:Extended producer responsibility frameworks in Germany, France, and Italy are mandating recyclable valve-to-pouch compatibility, forcing converters to retool for mono-material fitments.
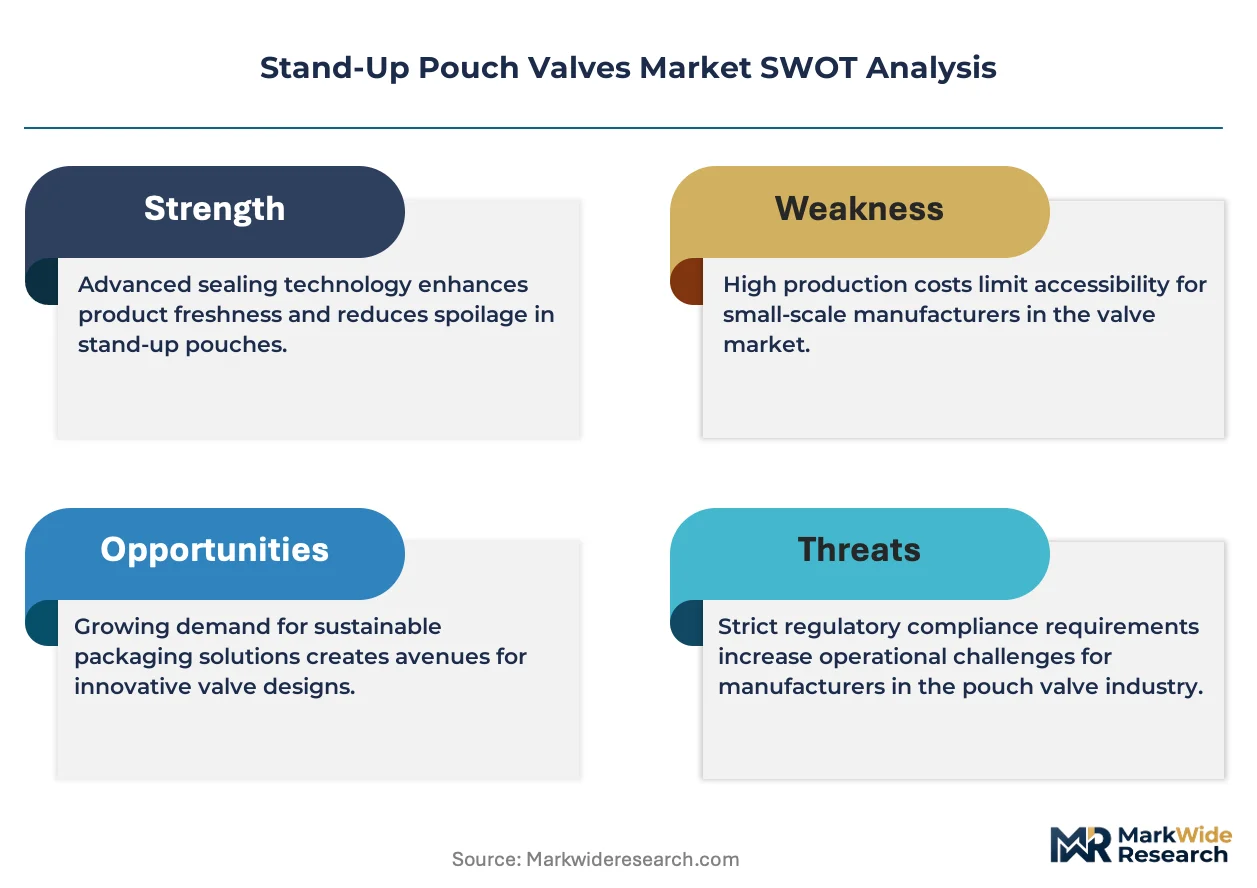
- High-acid food packaging:Fermented product manufacturers are specifying corrosion-resistant valve geometries that maintain seal integrity across pH extremes and thermal processing cycles.
- Injection molding precision advances:Tolerance control below 0.1 mm is now achievable at production scale, enabling thinner-walled valves that reduce resin consumption without compromising weld strength.
Market Restraints
- Polypropylene resin price volatility:Feedstock cost swings for copolymer grades used in flexible fitments compress converter margins and complicate long-term contract pricing.
- German converter equipment concentration:High-speed filling line investments cluster disproportionately in Bavaria and Baden-Württemberg, creating geographic supply risk for brands requiring regional redundancy.
- Multi-layer barrier incompatibility:Metalized film structures that preserve coffee freshness remain technically irreconcilable with current mechanical recycling streams, limiting circular economy claims.
Strategic Opportunities
- Italian fresh pasta packaging:Valve-equipped pouches for ambient-ready sauces and prepared meals remain underpenetrated relative to vacuum tray formats, offering white space for format conversion.
- Household chemical dispensing:Personal care brands are specifying child-resistant valve closures that integrate tamper-evidence with controlled dosing, opening premium positioning.
- REACH-compliant material certifications:Early documentation of substance safety and migration compliance is creating preferred-supplier status for converters serving pan-European brand portfolios.
Industry Challenges
- Multi-material welding expertise:Converter engineering teams lack sufficient polymer science depth to optimize ultrasonic and heat-seal parameters for novel mono-polymer combinations.
- Retrofit capex burdens:Existing pre-made pouch lines require substantial modification to handle valve insertion at speeds matching standard formats, straining mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stand-Up Pouch Valves Market |
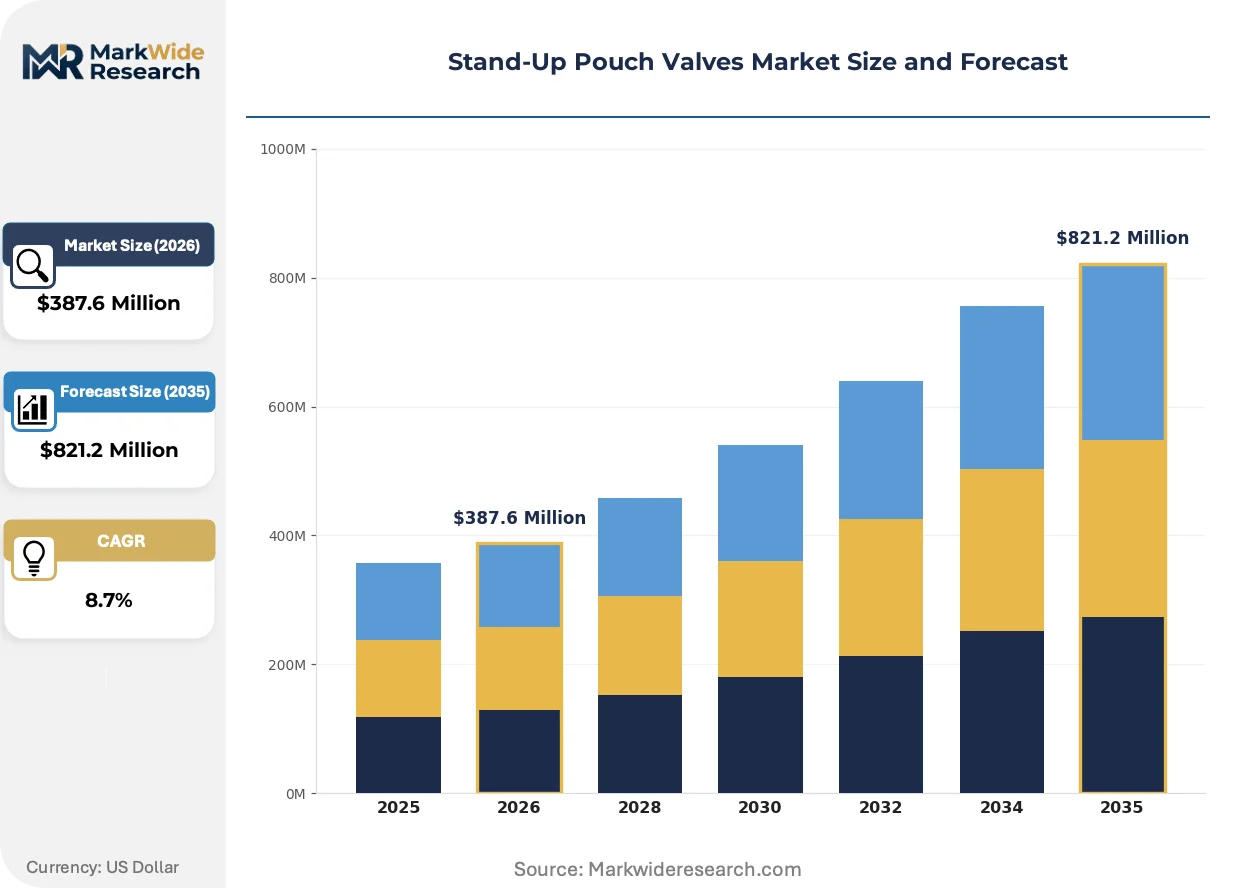
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Valves, One-Way Valves, Two-Way Valves, Custom Valves Material: Plastic, Metal, Composite, Rubber Application: Food Packaging, Beverage Packaging, Personal Care Products, Household Chemicals End User: Manufacturers, Retailers, Distributors, E-commerce |
| Companies Covered | Scholle IPN, Gualapack Group, Amcor, Smurfit Kappa, Wilk Group, Liqui-Box, Menshen, Falakpack, Edelpa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stand-Up Pouch Valves Market Emerging Trajectories
Active packaging integration and regulatory material bans are forcing simultaneous innovation across valve geometry, resin chemistry, and manufacturing equipment. Three developments are restructuring competitive positioning.
Biopolymer valve compounds derived from fermented starches and agricultural waste streams are expanding into premium organic food segments where petroleum-based plastics face explicit brand exclusions. German retailers and French organic distributors are piloting these fitments for coffee and dried fruit applications despite current cost premiums. The technology is expanding into conventional retail channels as supply scale improves and composting infrastructure clarifies end-of-life pathways.
REACH substance restriction amendments and the EU Packaging and Packaging Waste Regulation are accelerating substitution timelines for certain plasticizers and stabilizers used in valve seals. Converters must now validate alternative chemistries through migration testing protocols before existing inventory depletes. Coffee packaging applications face the most compressed compliance windows given their direct food contact and oxygen sensitivity requirements.
Direct-to-retail procurement contracts are consolidating specification authority with private-label brand owners who now dictate valve geometry, resin grade, and recyclability credentials. Traditional distributor intermediaries are losing influence as German and Dutch supermarket chains centralize packaging decisions at headquarters level. This concentration is most visible in the beverage concentrate segment, where Aldi and Lidl formats are standardizing spout dimensions across supplier bases.
Stand-Up Pouch Valves Market Segmentation
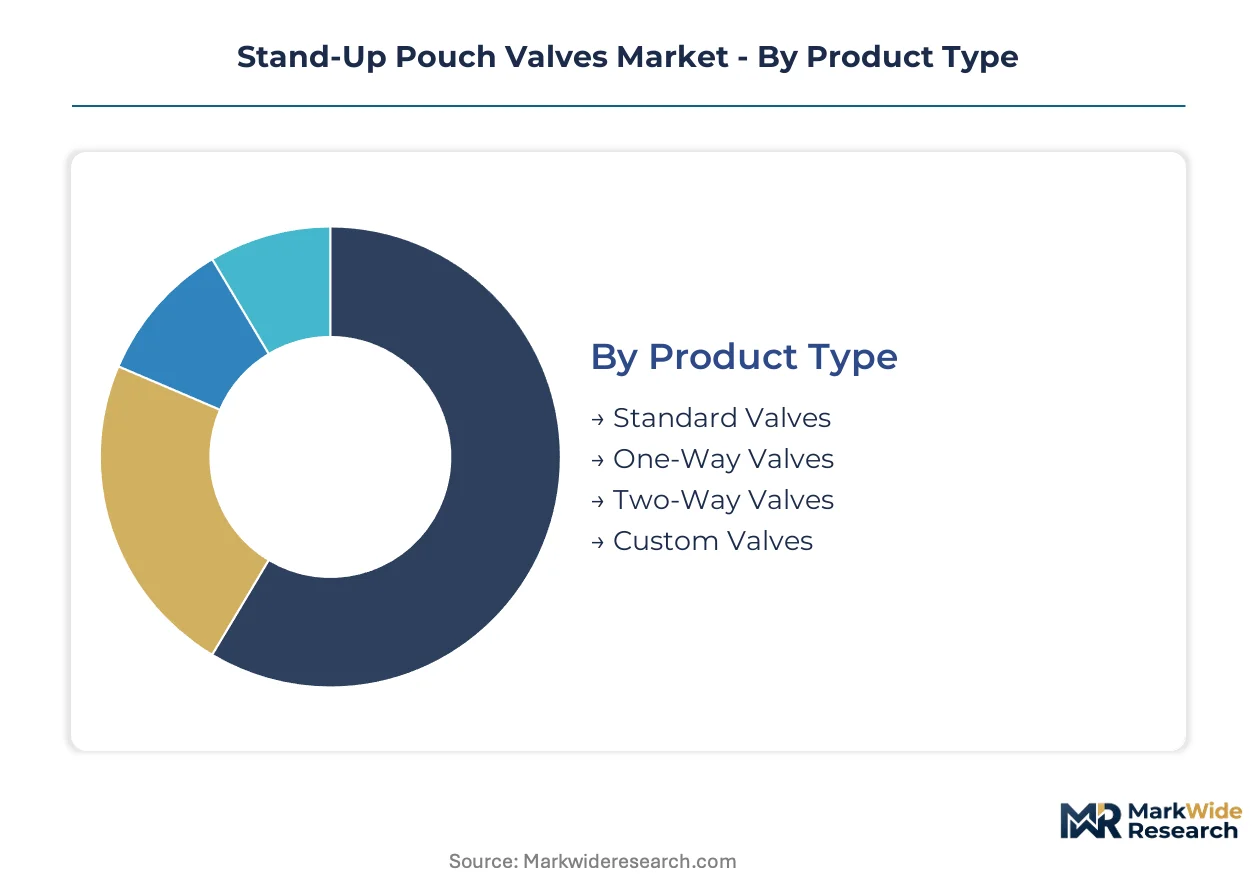
Valve specification choices determine weld compatibility, barrier performance, and end-of-life pathways for flexible packaging converters. Brand owners now segment procurement by recyclability credentials and filling-line speed requirements rather than unit cost alone.
Product Type:
Upgrade cycles favor valves that reduce resin content while maintaining seal integrity under high-speed filling conditions.
- One-Way Valves:These fitments permit outward gas release while blocking oxygen ingress through precision-molded silicone membranes. Coffee roasters in Germany and Italy specify these for degassing freshly roasted beans without vacuum sealing. REACH-compliant silicone grades are displacing older nitrile formulations as migration testing protocols tighten.
- Custom Valves:Proprietary geometries with brand-specific spout angles and tamper-evidence features command premium positioning. German private-label chains now mandate unique valve footprints to prevent supplier substitution. Biopolymer variants for organic food lines are gaining specification share despite 40-60% cost premiums over standard polyethylene fitments.
- Standard Valves:Generic polyethylene and polypropylene fitments serve commodity sauce and detergent applications where differentiation matters less than filling-line compatibility.
- Two-Way Valves:Bidirectional pressure equalization suits carbonated beverage concentrates and fermentation-active products requiring controlled gas exchange.
Volume placements concentrate in One-Way Valves; the faster expansion belongs to Custom Valves.
Material:
Cost tiers separate mono-polymer fitments eligible for mechanical recycling from multi-layer constructions requiring chemical recycling infrastructure.
- Plastic:Polyethylene and polypropylene dominate through injection molding tolerances below 0.1 mm. German converters are consolidating procurement around mono-material grades to satisfy EU Green Deal documentation requirements. Polypropylene copolymer prices swing with propylene feedstock costs, compressing margins on long-term supply contracts.
- Composite:Metalized barrier layers bonded to polymer substrates preserve coffee freshness but complicate recycling claims. Italian and French regulators are scrutinizing these constructions under emerging extended producer responsibility frameworks. Pilot programs in Bavaria are testing delamination-compatible designs.
- Metal:Aluminum valve components serve high-temperature retort applications for ready meals and sterilized sauces.
- Rubber:Silicone and EPDM seals provide compression set resistance for repeated-use dispensing closures in household chemical formats.
Plastic retains the dominant placement volume; Composite faces the steepest regulatory headwinds.
Application:
Customer type determines performance specifications—food contact migration limits versus chemical resistance versus child-resistance mechanisms.
- Food Packaging:Oxygen barrier requirements and FDA/EFSA migration compliance dominate specification sheets. Fermented product manufacturers in Italy and Germany are specifying corrosion-resistant geometries for high-acid sauces. Ambient-ready pasta sauce pouches remain underpenetrated relative to vacuum tray formats.
- Beverage Packaging:Concentrate dispensing and carbonation pressure management drive valve complexity. German supermarket chains are standardizing spout dimensions across supplier bases to simplify filling-line changeovers.
- Household Chemicals:Child-resistant closures with integrated tamper-evidence command premium positioning for bleach and detergent concentrates.
- Personal Care Products:Controlled dosing mechanisms for lotions and hair treatments emphasize aesthetic finish and ergonomic grip geometry.
Food Packaging commands the largest absolute placement base; Beverage Packaging is climbing the fastest as concentrate formats proliferate.
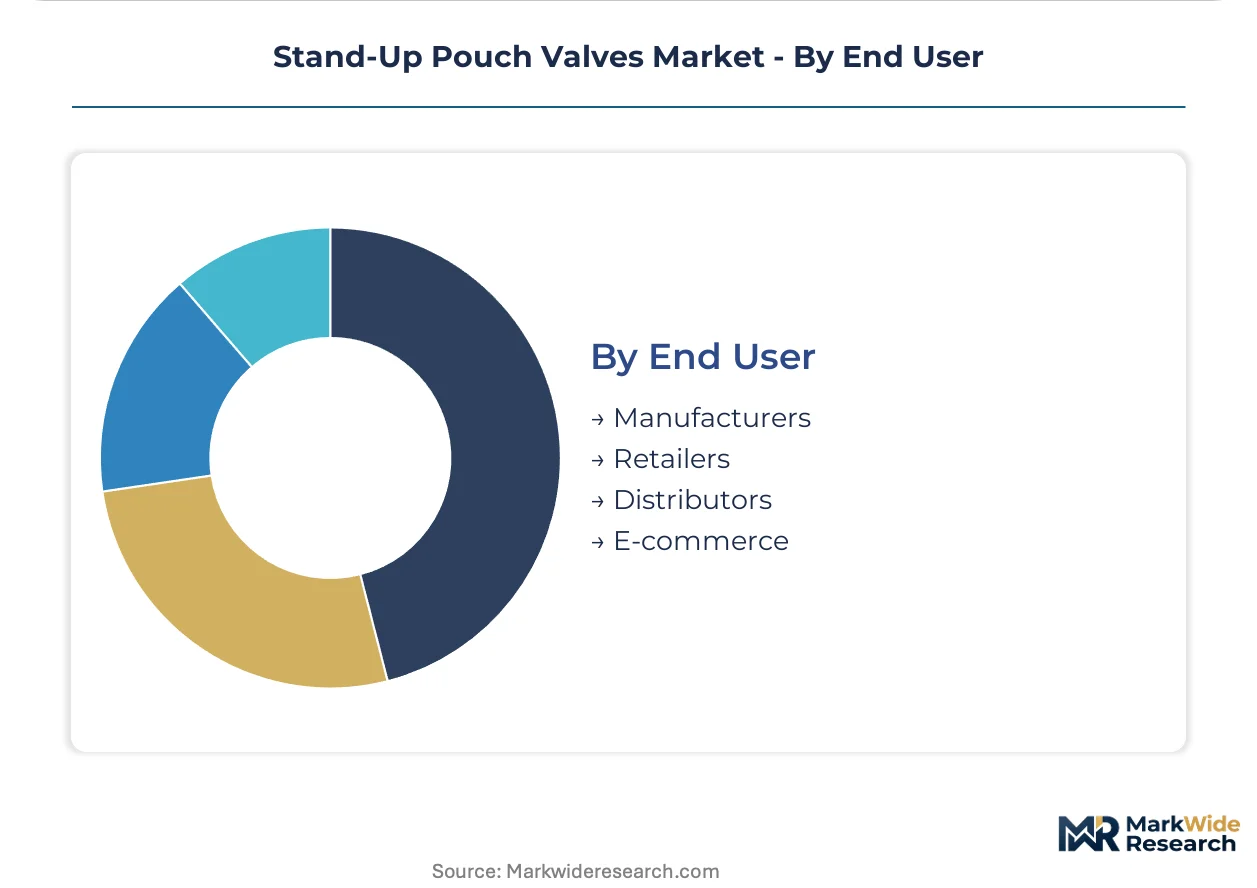
End User:
Supply concentration varies by procurement authority—direct brand ownership versus distributor intermediation versus platform retail consolidation.
- Manufacturers:Food packaging manufacturers represent the fastest-expanding buyer segment as they retool for high-speed spouted pouch lines. German converter investments in Bavaria and Baden-Württemberg outpace other European markets.
- Retailers:Aldi and Lidl formats are consolidating specification authority at headquarters level, bypassing traditional packaging distributors. Private-label brand owners now dictate valve geometry, resin grade, and recyclability credentials directly.
- Distributors:Traditional intermediaries are losing influence as procurement centralizes, though they retain relevance for mid-tier converters lacking direct retail relationships.
- E-commerce:Direct-to-consumer fulfillment requirements emphasize puncture resistance and resealability for shipping durability.
Manufacturer procurement dominates current volume; Retailer direct contracting is expanding most quickly as channel consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene resin supply from Rotterdam and Antwerp petrochemical corridors anchors European converter operations, with German mechanical engineering clusters driving filling-line automation investments.
Germany
High-acid food manufacturers in Bavaria and Baden-Württemberg are specifying corrosion-resistant valve geometries for fermented sauces and ambient-ready pasta meals. REACH compliance documentation under ECHA oversight is mandatory for all valve seal compounds entering direct food contact. Converter investments in high-speed spouted pouch lines concentrate around Stuttgart and Munich industrial corridors.
Italy
Fresh pasta and sauce producers in Emilia-Romagna represent underpenetrated demand for valve-equipped pouches relative to vacuum tray dominance. Extended producer responsibility frameworks under EU Green Deal implementation are scrutinizing multi-layer barrier constructions for recyclability claims. Bologna and Modena packaging clusters are piloting mono-polymer valve-to-pouch compatibility programs.
France
Organic food distributors are piloting biopolymer valve fitments for coffee and dried fruit despite current cost premiums over petroleum-based alternatives. ANSM and CNIL oversight extends to food contact migration testing protocols for novel resin chemistries. Paris-based private-label headquarters for Aldi and Lidl are consolidating valve geometry specifications across supplier bases.
United States
Beverage concentrate manufacturers specify carbonation pressure management valves for pouch-based dispensing formats. FDA food contact regulations govern migration testing protocols for polyethylene and polypropylene valve components. Midwest converter operations around Chicago and Milwaukee are retooling for child-resistant closure integration in household chemical applications.
China
Flexible packaging exporters in the Yangtze River Delta are scaling injection molding capacity for valve tolerances below 0.1 mm. GB standards and SAMR oversight shape material approval pathways for food contact applications. Shanghai and Suzhou manufacturing clusters are supplying European brands with REACH-compliant mono-material fitment alternatives.
Stand-Up Pouch Valves Market Vendor Landscape
Global majors compete with regional champions across material integration and filling-line compatibility dimensions. Market structure tilts toward consolidated tier-one suppliers with captive resin and fitment manufacturing alongside fragmented mid-tier converters dependent on external component sourcing. Three archetypes dominate: vertically integrated packaging multinationals controlling film-to-valve supply chains; specialized spout-and-pouch system designers serving high-acid food niches; and regional converter-engineering hybrids focused on private-label retail formats. Competitive moves concentrate on backward integration into resin compounding and strategic partnerships with high-speed filling equipment manufacturers.
Within the integrated multinational tier, Scholle IPN and Gualapack Group exemplify archetypes of captive supply chain control and specialized application focus respectively. Amcor occupies a position bridging scale-driven commodity supply and premium-format customization for personal care and household chemical segments. These three entities represent the dominant competitive anchors against which mid-tier regional converters define their differentiation strategies.
| Leading Market Players |
|---|
| Scholle IPN |
| Gualapack Group |
| Amcor |
| Smurfit Kappa |
| Wilk Group |
| Liqui-Box |
| Menshen |
| Falakpack |
| Edelpa |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between REACH-compliant mono-polymer valves and legacy multi-material fitments manifests in both pricing premiums and supply chain sourcing patterns across European converter networks. Buyers demanding ECHA-documented recyclability credentials pay 15-25% markups over standard polyethylene alternatives, while procurement teams restructure supplier bases around German and Italian compounders with captive migration testing capabilities.
Pricing Analysis
Warranty-backed compliance documentation now separates bundled from unbundled valve procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth: REACH-validated silicone membranes command top tier, generic polypropylene serves mid-market sauce applications, and spot-market resin grades supply commodity detergent pouches. Price differentiation intensifies as polypropylene feedstock volatility compresses converter margins on long-term beverage contracts. Small-scale pasta sauce manufacturers exhibit highest price sensitivity, while German private-label chains absorb premiums for proprietary valve geometries that prevent supplier substitution.
Supply Chain Analysis
End-of-life collection and mechanical recycling compatibility are reshaping valve sourcing decisions across European flexible packaging networks. Germany, Italy, and France anchor injection molding capacity for tolerances below 0.1 mm, with Bavarian converter clusters feeding high-speed filling lines for spouted pouches. Raw material flows draw from Rotterdam and Antwerp propylene corridors, while silicone membrane compounds source from specialized German chemical processors. Single-source vulnerability concentrates around Baden-Württemberg equipment engineering for ultrasonic welding stations. Distribution runs through centralized Aldi and Lidl procurement hubs that bypass traditional packaging intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over resin compounding and migration testing documentation determines pricing power and preferred-supplier status with pan-European brand portfolios.
For Market Incumbents: Anticipate biopolymer valve displacement by securing fermentation-derived starch supply agreements before cost curves flatten. Defend position through backward integration into mono-polymer compounding to meet EU Green Deal documentation requirements ahead of mechanical recycling infrastructure deployment. Lock in high-acid food converter relationships with corrosion-resistant geometry patents before Italian fresh pasta format conversion accelerates. For New Entrants and Emerging Players: Private-label retail headquarters in Paris and Düsseldorf represent the most penetrable channel partner type for specification authority. Target underpenetrated Italian ambient-ready pasta sauce pouches where vacuum tray dominance still blocks valve-equipped flexible formats. Lead with REACH-compliant material certification services that mid-tier converters lack in-house capability to generate, creating preferred-supplier status before capital-intensive tooling investments solidify incumbent positions. For Investors and Strategic Acquirers: Re-rating potential sits with specialized spout-and-pouch system designers given high-acid food packaging demand and corrosion-resistant valve specification premiums. Long-term viability hinges on recyclability credential depth as extended producer responsibility frameworks mature across the analysis window. Monitor German converter equipment concentration in Bavaria and Baden-Württemberg for geographic supply risk signals that could trigger regional redundancy investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive mono-polymer supply secures EU Green Deal documentation for German converter networks. |
| REACH-Compliant Certification Program | ECHA-validated migration testing creates preferred-supplier status with pan-European organic food distributors. |
| High-Speed Filling Equipment Partnership | Stuttgart and Munich engineering clusters demand valve-to-line compatibility guarantees for spouted pouch investments. |
| Biopolymer Valve Pilot Expansion | French organic retailers and German coffee roasters are trialing fermented starch fitments despite current cost premiums. |
| Private-Label Specification Standardization | Aldi and Lidl headquarters consolidation mandates uniform spout dimensions across supplier bases. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with flexible packaging converters, food manufacturing procurement leads, and retail category buyers. ECHA substance restriction databases, EU Packaging and Packaging Waste Regulation implementation timelines, and German mechanical engineering cluster investment disclosures provided validation benchmarks. Bottom-up valve placement estimates triangulated against top-down flexible packaging demand projections across food, beverage, and household chemical segments.
Granularity-level modeling captured product type specifications, material grade certifications, application performance requirements, and end-user procurement authority patterns across the projection horizon. Segmentation dimensions included valve geometry complexity, mono-polymer versus multi-layer barrier constructions, direct food contact migration compliance tiers, and filling-line speed compatibility. CAGRs derived from annual placement volume trajectories weighted by resin cost indices and converter capacity utilization rates in Bavaria and Baden-Württemberg.
Caveats apply where polypropylene feedstock volatility, REACH substance restriction amendments, or mechanical recycling infrastructure deployment delays could materially shift the outlook. Forecasts reflect assumptions about EU Green Deal implementation pacing and private-label procurement centralization trends. Practitioners should monitor Italian fresh pasta format conversion rates and German converter equipment geographic concentration for early signals of supply chain restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
India Home Automation Market
Others
Nonlinear Editing System Market
Others
Remanufacturing-as-a-Service (RaaS) Market
Others
Latin America Automotive HVAC Market
Others
Next Gen Video Codecs Market
Others
Spain Feed Additives Market
Others
Europe Postal Services Market
Others
Global Multi Domain Controller Market
Others
Advanced Combat Helmet Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
Aerospace Software Testing Market
Others
Edge Computing in Healthcare Market
Others
Signal Transformer Market
Others
Eye Balm Market
Others
Vegetable Carbon Market
Others
Double Card Mobile Phone Market