
 North America Machine Vision Systems Market | 2026-2036
North America Machine Vision Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Machine Vision Systems Market Foresight
The gap between premium and commodity machine vision tiers is hardening around software depth and sensor resolution. Cognex Corporation leverages proprietary vision tools to dominate high-end semiconductor inspection. Keyence Corporation sustains channel control through direct sales engineers embedded in automotive plants. Teledyne DALSA anchors its position with in-house sensor fabrication for scientific and industrial imaging.
North America machine vision systems integrate cameras, optics, lighting, and processing software to automate visual inspection, measurement, and robot guidance in production environments. These systems typically operate at frame rates from 30 to 10,000 fps with resolutions spanning 0.3 to 150 megapixels, depending on defect detection requirements. Smart cameras and 3D vision lead growth as manufacturers replace discrete component setups with integrated units that reduce cabling complexity. Deep learning within image processing commands premium margins as neural network training shifts defect classification from rule-based to adaptive models.
The US FDA enforces 21 CFR Part 11 compliance for electronic records in pharmaceutical vision applications, while OSHA machine guarding standards shape camera placement in collaborative robot cells. FCC Part 15 governs electromagnetic emissions from wireless vision sensors deployed on mobile platforms. Stakeholders must weigh validated software ecosystems against open-architecture flexibility as regulatory scope expands beyond traditional factory floors.
Market Dynamics
Deep learning defect classification is compressing inspection cycle times across automotive and pharmaceutical assembly lines, forcing hardware suppliers to bundle adaptive software or surrender margin to pure-play algorithm developers.
Growth Catalysts
- Automotive assembly expansion:Michigan and Ohio production lines are mandating inline 3D vision for weld seam inspection, creating captive demand for multi-camera synchronized systems.
- FDA 21 CFR Part 11:Pharmaceutical manufacturers in the Great Lakes corridor face validated electronic records requirements that favor machine vision over manual inspection logs.
- Collaborative robot deployment:OSHA machine guarding standards for human-robot workcells are accelerating camera-based safety perimeter monitoring in Wisconsin and Illinois plants.
Market Restraints
- Sensor supply concentration:High-resolution CMOS and sCMOS sensors for scientific imaging concentrate among three Japanese and European foundries, exposing lead time risk.
- Specialized optics cost volatility:Telecentric lenses and structured light projectors require precision-ground glass from German and Swiss suppliers with limited capacity expansion.
- Deep learning hardware requirements:GPU and edge AI accelerator shortages are extending deployment timelines for neural network-based classification systems.
Strategic Opportunities
- Underpenetrated food processing:USDA-inspected meat and poultry facilities in the US Southeast remain below 15% machine vision penetration for foreign object detection.
- Regulatory tailwind from IRA:Domestic content requirements for battery cell manufacturing are incentivizing vision-guided assembly for gigafactory construction in Tennessee and Kentucky.
- 5G private network convergence:Wireless vision sensor deployment on mobile inspection platforms is opening new channel partnerships with telecom infrastructure providers.
Industry Challenges
- Systems integration talent scarcity:Deployment of multi-vendor camera-lighting-processing pipelines requires scarce expertise in GenICam and GigE Vision protocols.
- Validation timeline compression:FDA computer system validation for pharmaceutical vision applications demands 12-18 month documentation cycles that conflict with quarterly production targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Machine Vision Systems Market |
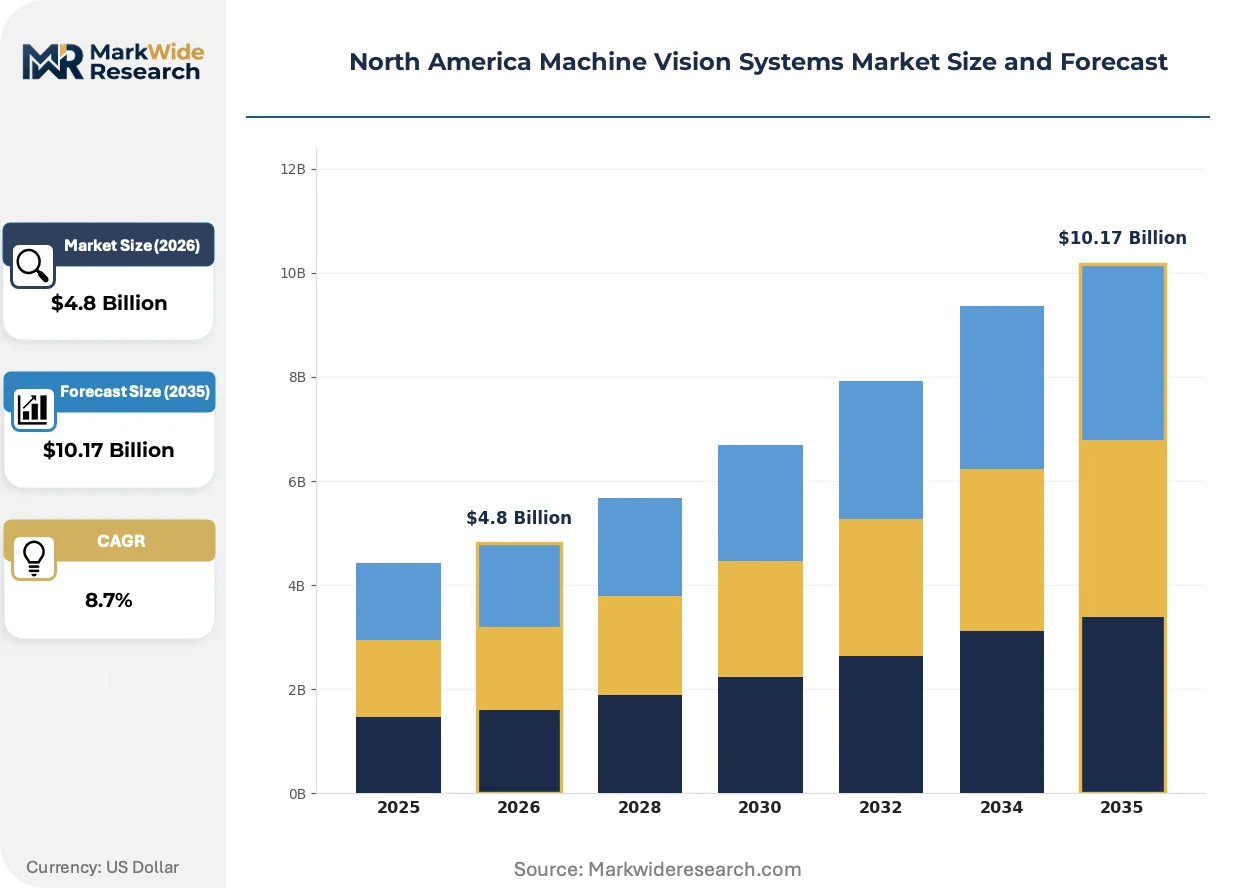
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Cameras, Vision Sensors, Frame Grabbers, Software Technology: 2D Vision, 3D Vision, Deep Learning, Image Processing End User: Manufacturing, Automotive, Electronics, Food & Beverage Application: Quality Inspection, Identifications, Guidance, Measurement |
| Companies Covered | Cognex Corporation, Keyence Corporation, Teledyne DALSA, Basler AG, National Instruments Corporation, Teledyne Technologies Inc., Omron Corporation, Zebra Technologies Corporation, FLIR Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Machine Vision Systems Market Shifts & Advancements
Edge AI inference is redistributing computational load away from centralized servers, while regulatory validation requirements and procurement centralization are rewriting vendor selection criteria across the continent.
Embedded GPU smart cameras are decentralizing defect classification from plant-floor servers to individual inspection points. Automotive tier-one suppliers in Ohio and Indiana are deploying these units at 200+ station lines to eliminate single-point-of-failure architectures. The shift is compressing infrastructure costs and enabling sub-50 millisecond response times for high-speed assembly verification.
FCC Part 15 electromagnetic emissions rules are constraining wireless vision sensor power budgets and antenna configurations on mobile platforms. Manufacturers are responding with lower-frequency sub-GHz protocols and shielded enclosures that add unit cost but enable untethered deployment. Material handling and warehouse automation in Illinois and Michigan represent the most affected application segments.
Centralized procurement through corporate engineering standards groups is displacing plant-level vendor selection. Multi-site manufacturers in the US Great Lakes corridor are consolidating approved vendor lists to three or fewer machine vision suppliers to simplify spare parts logistics and training. The pattern concentrates volume with full-stack providers capable of supporting 50+ facility deployments from a single service contract.
North America Machine Vision Systems Market Segmentation
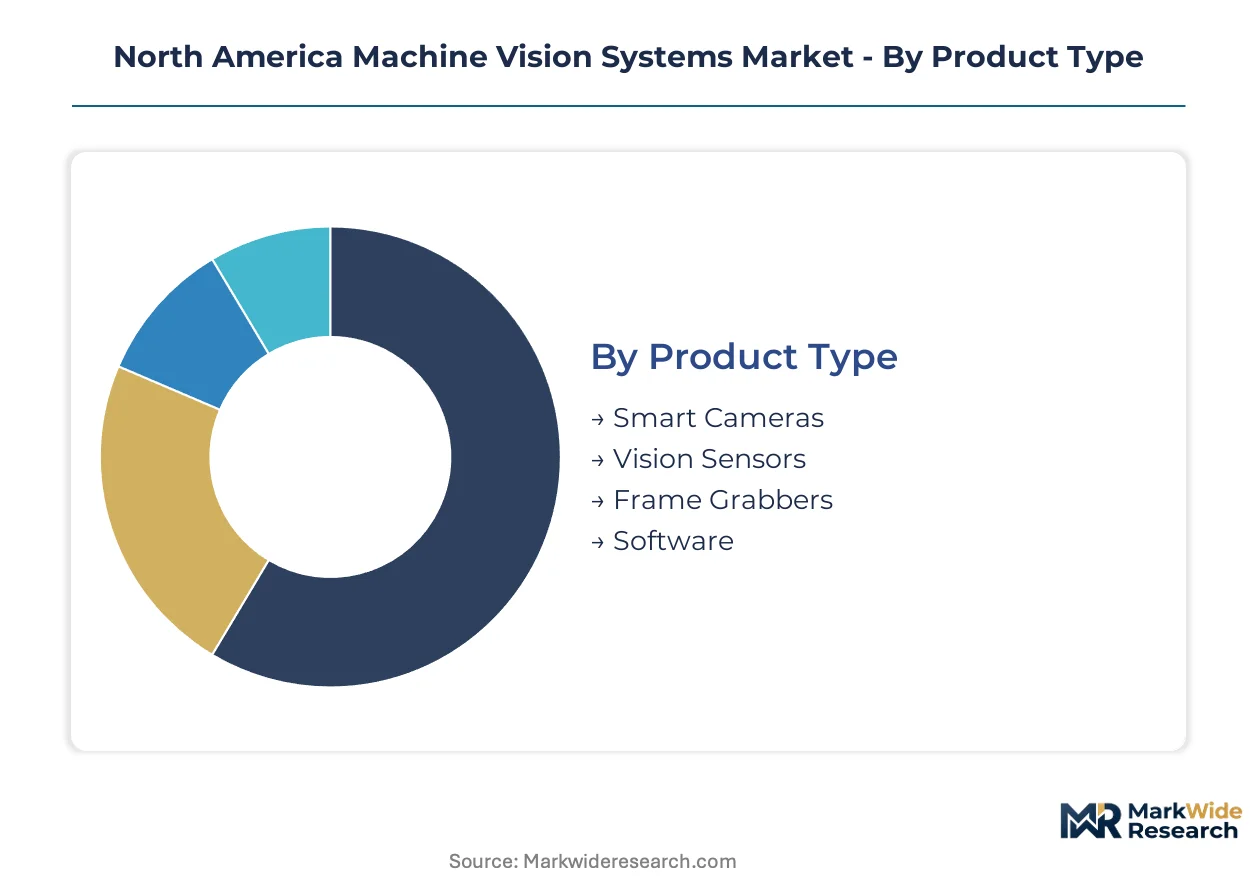
Machine vision procurement in North America stratifies sharply between integrated embedded systems and discrete component architectures. Buyers weigh cabling complexity against upgrade flexibility when selecting across product and technology categories.
Product Type:
Integration depth separates standalone smart cameras from modular frame grabber configurations requiring external processing.
- Smart Cameras:Embedded processors execute inspection algorithms without external PCs, reducing wiring footprint. Michigan automotive plants deploy these at weld stations to compress cycle times and eliminate server bottlenecks.
- Vision Sensors:Simplified devices with pre-configured tools target presence/absence detection at lower price points. Illinois food processors favor these for carton verification where complex programming would slow line changeovers.
- Frame Grabbers:Interface cards capture high-bandwidth data from specialized cameras into industrial PCs.
- Software:Licensing for image processing libraries and deep learning training environments.
Volume placements concentrate in Vision Sensors; the faster expansion belongs to Smart Cameras.
Technology:
Cost tiers separate mature 2D inspection from premium 3D and deep learning deployments demanding specialized hardware.
- 2D Vision:Established grayscale and color imaging dominates high-throughput barcode reading and surface defect detection. Ohio electronics assembly lines standardize on these systems for component placement verification.
- 3D Vision:Structured light and time-of-flight sensors capture depth data for robot guidance and volumetric measurement. Wisconsin collaborative robot cells require these for OSHA-compliant safety perimeter monitoring.
- Deep Learning:Neural network-based classification adapts to variable defect appearances without explicit rule programming.
- Image Processing:Traditional algorithmic filters and geometric pattern matching tools.
2D Vision retains the largest installed base; 3D Vision is climbing the fastest as automotive mandates spread.
End User:
Application maturity varies dramatically across verticals, with FDA-regulated pharma and USDA-inspected food plants lagging automotive adoption curves.
- Manufacturing:General industrial automation spans discrete and process industries with diverse inspection requirements.
- Automotive:Michigan and Ohio assembly lines mandate inline vision for weld seam, adhesive bead, and final assembly verification. Tier-one suppliers consolidate multi-camera synchronized systems under single service contracts.
- Electronics:Semiconductor and PCB inspection demands sub-micron resolution and validated measurement repeatability.
- Food & Beverage:USDA-inspected meat and poultry facilities in the Southeast remain below 15% penetration for foreign object detection, creating whitespace for suppliers.
Automotive captures the dominant share of new deployments; Food & Beverage presents the steepest expansion trajectory as regulatory pressure mounts.
Application:
Customer type differentiation separates high-frequency quality inspection from lower-volume guidance and measurement tasks.
- Quality Inspection:Defect detection and classification commands the majority of system deployments across all end-use verticals.
- Identifications:OCR, barcode, and DataMatrix reading for track-and-trace compliance. Pharmaceutical manufacturers in the Great Lakes corridor deploy these to satisfy FDA 21 CFR Part 11 electronic records requirements.
- Guidance:Robot path correction and pick-and-place coordination.
- Measurement:Dimensional gauging with calibrated accuracy for tolerance verification.
Quality Inspection absorbs the greatest hardware volume; Guidance is gaining share fastest alongside collaborative robot proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes manufacturing corridor spanning Michigan, Ohio, Illinois, Indiana, and Wisconsin anchors North American machine vision deployment. Automotive assembly concentration, FDA-regulated pharmaceutical production, and collaborative robot proliferation drive regional demand patterns.
United States
Michigan and Ohio automotive plants mandate inline 3D vision for weld seam inspection, creating captive demand for multi-camera synchronized systems. FDA 21 CFR Part 11 compliance requirements push pharmaceutical manufacturers toward validated electronic records systems. The Great Lakes corridor concentrates deployment across Illinois, Indiana, and Wisconsin manufacturing facilities.
Canada
Ontario automotive suppliers deploy vision-guided robotics for battery cell assembly aligned with domestic content incentives. Health Canada medical device regulations shape validation requirements for pharmaceutical vision applications in Toronto-area facilities. Quebec aerospace manufacturers in Montreal employ high-resolution inspection for precision component verification.
Mexico
Nuevo León automotive tier-one suppliers integrate machine vision for export-oriented assembly verification under USMCA compliance pressures. The country's national manufacturing regulator enforces traceability standards that favor automated inspection over manual documentation. Bajío Region electronics assembly plants deploy barcode reading systems for supply chain visibility.
North America Machine Vision Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the North American machine vision landscape. The vendor base stratifies between full-stack integrated system providers and specialized component suppliers. Three archetypes dominate: sensor fabricators with captive foundry capacity, software-centric smart camera developers, and distribution-controlled direct sales organizations. Competitive moves concentrate on strategic partnerships with automotive OEMs and vertical integration into edge AI processing hardware.
Within the full-stack integrated tier, Cognex Corporation and Keyence Corporation exemplify divergent channel strategies—one leveraging proprietary vision tools for semiconductor inspection dominance, the other sustaining embedded sales engineering in automotive plants. Teledyne DALSA occupies a position among sensor fabricators with in-house semiconductor production for scientific and industrial imaging applications.
| Leading Market Players |
|---|
| Cognex Corporation |
| Keyence Corporation |
| Teledyne DALSA |
| Basler AG |
| National Instruments Corporation |
| Teledyne Technologies Inc. |
| Omron Corporation |
| Zebra Technologies Corporation |
| FLIR Systems Inc. |
| Others |
Supply & Pricing Matrix
Precision-ground optical glass price indices from German and Swiss suppliers cascade through North American machine vision supply chains into three-tier pricing structures across premium, standard, and economy levels. Buyers in automotive and pharmaceutical verticals absorb premium markups for validated systems while food processors gravitate toward commodity tiers where sensor resolution concessions trade off against unit economics.
Pricing Analysis
Outcome-based pricing tied to defect detection throughput anchors value capture for high-end semiconductor inspection systems. Pricing stratifies across premium, standard, and economy tiers based on software depth and sensor resolution grade, with FDA-validated configurations commanding substantial premiums over uncertified alternatives. Cost compression in the economy tier intensifies because Asian sensor suppliers are expanding CMOS foundry capacity. Food and beverage processors exhibit the highest price sensitivity, while pharmaceutical manufacturers under 21 CFR Part 11 compliance pressure show minimal elasticity.
Supply Chain Analysis
Skilled optics grinding workforce availability in Germany and Switzerland constrains expansion of telecentric lens and structured light projector capacity. Component sourcing draws from Japanese and European foundries for high-resolution CMOS sensors, German suppliers for precision optics, and Taiwanese facilities for edge AI accelerators. Single-source vulnerability concentrates around sCMOS sensor fabrication, where three foundries control scientific imaging supply. Distribution runs through direct sales engineering teams embedded in automotive plants alongside authorized distributor networks serving fragmented industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American machine vision supply is capacity-constrained at the precision optics tier, where limited German and Swiss grinding capacity props pricing for validated pharmaceutical and semiconductor inspection systems.
For Market Incumbents: Extend software ecosystem lock-in by bundling deep learning training environments with hardware contracts to neutralize pure-play algorithm developers. Add captive sensor testing capacity in the US Great Lakes corridor to compress FDA validation timelines for pharmaceutical clients facing 12-18 month documentation cycles. For New Entrants and Emerging Players: IRA domestic content requirements in Tennessee and Kentucky open a window for vision-guided assembly specialists targeting battery gigafactory construction. Underpenetrated USDA-inspected meat and poultry facilities in the US Southeast offer the most penetrable vertical, with foreign object detection penetration below 15%. A channel partnership with 5G private network infrastructure providers enables untethered mobile inspection platform deployment without direct competition against entrenched direct sales organizations. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-centric smart camera developers with embedded GPU architectures in Michigan and Ohio automotive corridors. Long-term viability hinges on edge AI inference decentralization trends compressing server-dependent system architectures. Watch for GPU and edge AI accelerator availability inflection as the signal triggering accelerated deployment timelines for neural network-based classification systems.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Hardware Integration | Embedded GPU smart cameras eliminate server bottlenecks at Ohio automotive weld stations. |
| Regulatory Validation Investment | FDA 21 CFR Part 11 compliance documentation accelerates pharmaceutical procurement decisions. |
| Direct Sales Engineering Expansion | Embedded technical staff in Michigan plants sustain channel control against distributor competitors. |
| 5G Private Network Partnership | Wireless sensor deployment on Illinois mobile platforms opens telecom infrastructure alliances. |
| Optics Supply Backward Integration | In-house telecentric lens production insulates against German and Swiss capacity constraints. |
Research Methodology
Independent corroboration across plant engineers at Michigan automotive tier-one suppliers, pharmaceutical validation specialists in the Great Lakes corridor, and vision systems integration firms underwrites the qualitative findings. Primary interviews with OEM procurement teams, aftermarket service heads, and FDA compliance officers combined with secondary validation from SEC 10-K filings, customs/trade data, and OSHA machine guarding interpretation documents. Bottom-up deployment tallies triangulate against top-down market sizing from component shipment data.
Comparable historical reference periods anchored the forecast window to pre-pandemic baseline capacity utilization and post-2021 supply normalization patterns. The analytical framework models segmentation across product integration depth, vision technology tier, end-use vertical maturity, and application frequency throughout the forecast period. CAGRs derive from installed base replacement cycles, regulatory mandate implementation timelines, and collaborative robot penetration curves in OSHA-governed workcells.
Caveats apply where GPU and edge AI accelerator availability constraints, precision optics capacity expansion decisions, or FDA validation timeline compression could materially shift the outlook. Forecasts reflect assumptions about semiconductor foundry capacity allocation and German optics supplier investment intentions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
South America Orange Market
Others
Coconut Activated Carbon Market
Others
Cloud-Based Streaming Services Market
Others
US Mobile MRI Services Market
Others
Australia Content Services Platform Market
Others
Refractometer Market
Others
Europe Digital Experience Platform Market
Others
Global Active Speaker Market
Others
Latin America 3D Printing Construction Market
Others
Ceramic Machinery Market
Others
Level Measuring Instrument Market
Others
Global Recruitment and Staffing Market
Others
Digital Education Projector Market
Others
Global Smart Home Installation Service Market
Others
Trusted Platform Module (TPM) Market
Others
Military Image Intensifier Market