
 Europe Medical Simulation Market | 2026-2036
Europe Medical Simulation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Simulation Market Foresight
Subscription-based software licensing for simulation platforms is expanding how vendors monetize hardware deployments. Surgical Science Sweden AB leverages its haptic feedback engine to dominate laparoscopic training modules. Laerdal Medical sustains brand strength across emergency response mannequins through direct hospital channel control. Mentice AB specializes in endovascular simulation, anchoring its position within interventional cardiology training networks.
Europe medical simulation encompasses anatomically accurate physical models, computer-generated virtual environments, and haptic-enabled procedural trainers designed to replicate clinical scenarios without patient risk. High-fidelity simulators incorporate physiologic modeling software that generates real-time cardiac, respiratory, and neurological responses to learner interventions. Virtual reality simulators are capturing the fastest expansion as hardware costs decline and graphics processing enables photorealistic tissue deformation. Hardware-based solutions remain the mature revenue base, though margin pools are migrating toward software-defined feature upgrades and cloud-hosted scenario libraries.
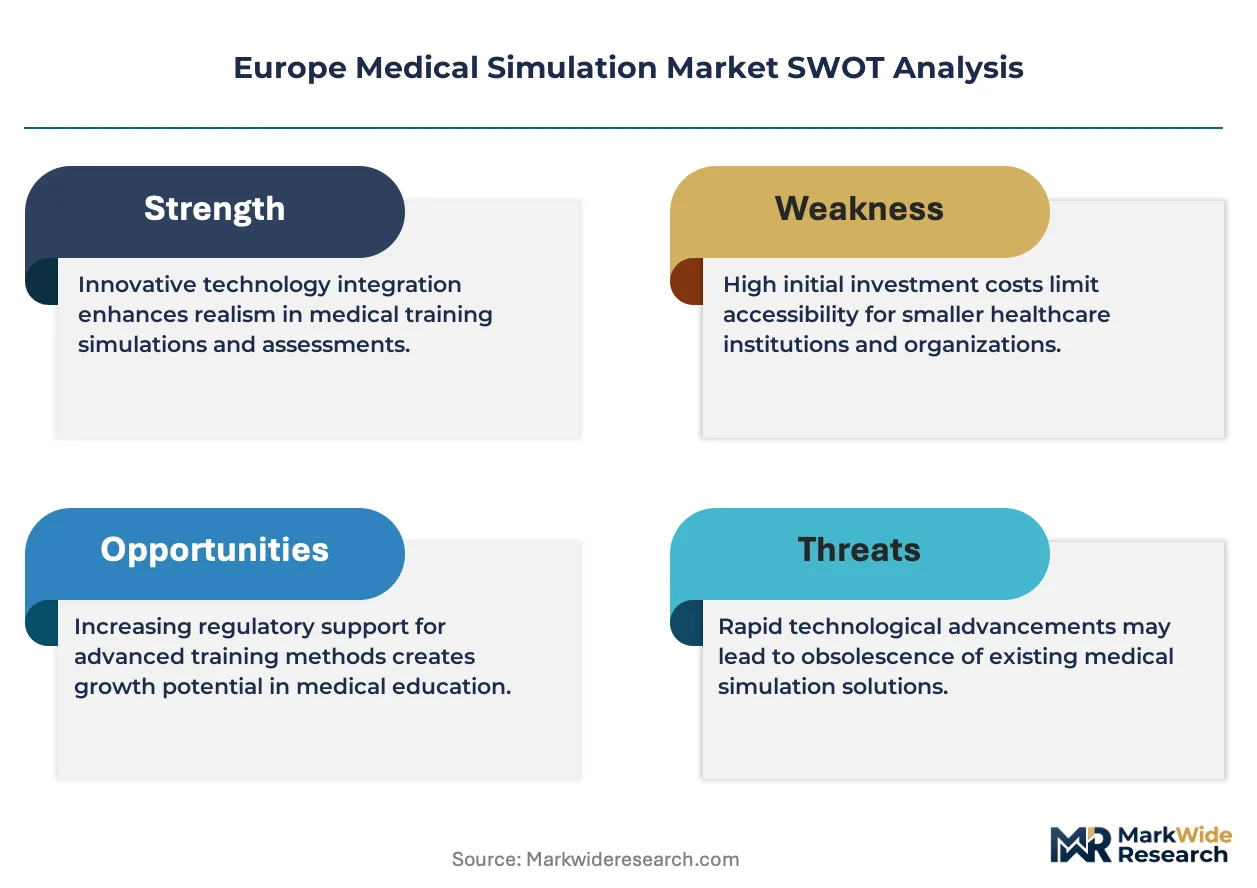
The EU Medical Device Regulation (MDR) and CE marking framework administered by notified bodies in Germany, France, and the Netherlands are elevating clinical validation standards for simulation products marketed as training replacements for live patient exposure. EMA guidance on Good Clinical Practice increasingly references simulation-based competency assessment for investigator training in multi-center trials. Stakeholders must monitor how national health technology assessment bodies in France, Germany, and Italy incorporate simulation efficacy data into reimbursement and procurement criteria for teaching hospitals.
Market Dynamics
The EU Medical Device Regulation is compressing validation timelines for simulation platforms while university hospital clusters in Germany and the UK accelerate procurement of high-fidelity virtual reality trainers, creating a structural tension between compliance burden and demand velocity.
Growth Catalysts
- MDR Compliance Mandate:The EU Medical Device Regulation now classifies advanced simulators as training-equivalent to live patient exposure, forcing teaching hospitals to upgrade legacy equipment to maintain accreditation.
- Haptic Feedback Maturation:Force-feedback engines now replicate tissue resistance with sub-millimeter precision, enabling procedural transfer to live surgery that paper-based training cannot achieve.
- German University Hospital Procurement:Charité Berlin and Heidelberg University Hospital have established dedicated simulation center budgets, creating reference-site demand that radiates to mid-tier institutions.
Market Restraints
- Notified Body Bottleneck:CE marking capacity concentrates among German and Dutch notified bodies, creating 12-18 month validation queues that delay product launches.
- Graphics Processing Unit Dependency:Photorealistic tissue deformation requires NVIDIA and AMD chips subject to supply allocation volatility and export control friction.
- Physical Mannequin Obsolescence:Low-fidelity task trainers face substitution pressure from software-defined platforms, stranding inventory at distributors and compressing hardware margins.
Strategic Opportunities
- Poland and Czech Republic Expansion:Medical faculties in Warsaw and Prague lack simulation infrastructure relative to Western European peers, creating first-mover whitespace for platform vendors.
- Cloud-Hosted Scenario Libraries:Subscription access to procedurally diverse case archives enables recurring revenue from hardware installations previously monetized once.
- EMA Investigator Training Alignment:European Medicines Agency guidance on Good Clinical Practice now references simulation-based competency verification, opening investigator certification as an adjacent revenue stream.
Industry Challenges
- Clinical Educator Shortage:Simulation centers require faculty with dual expertise in clinical practice and debriefing methodology, a skill combination scarce in nursing and medical school pipelines.
- Legacy LMS Integration:Hospital learning management systems from SAP and Oracle lack native interoperability with simulation data formats, forcing costly middleware development.
- Biometric Data Governance:GDPR compliance for learner performance analytics stored on cloud platforms creates legal review cycles that extend sales timelines by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Simulation Market |
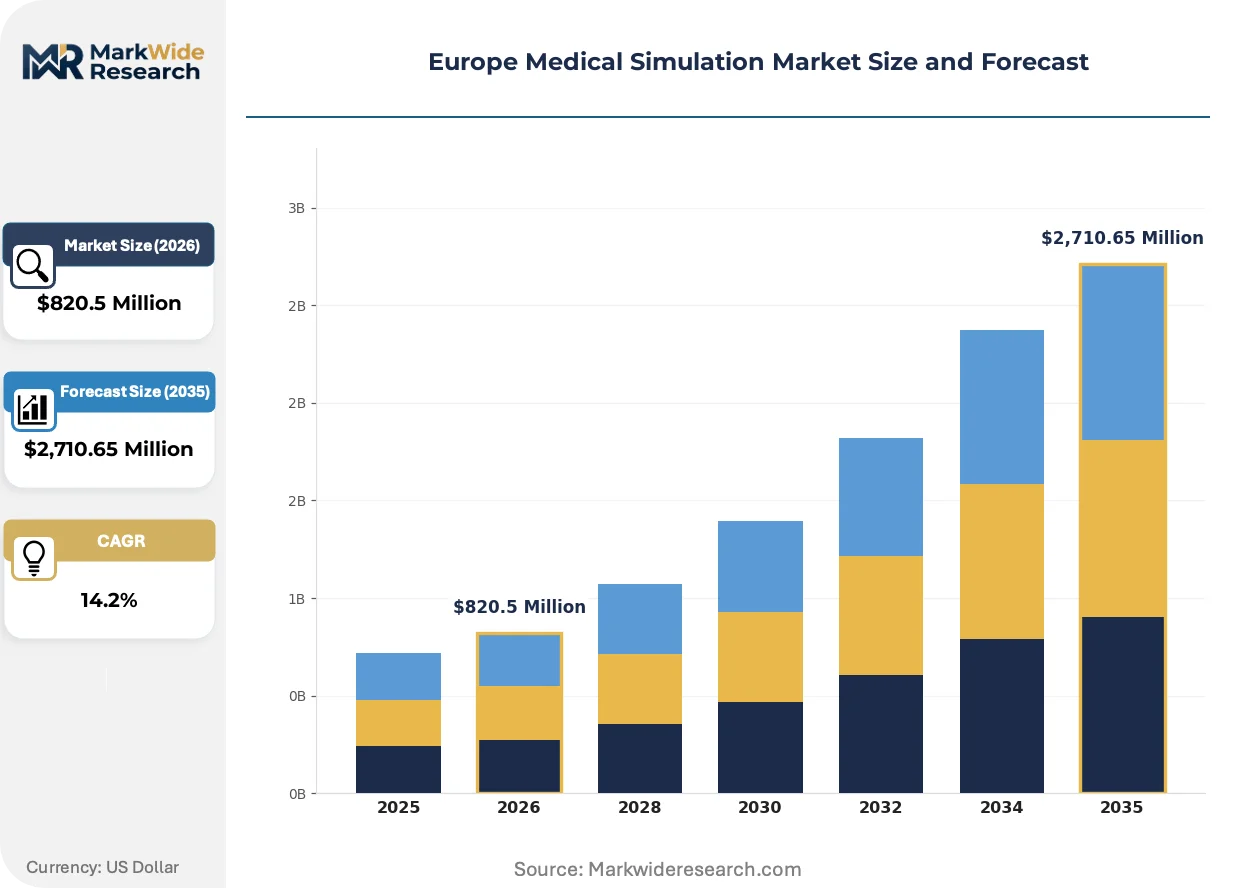
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $2,710.65 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Fidelity Simulators, Low-Fidelity Simulators, Virtual Reality Simulators, Mannequins End User: Hospitals, Medical Schools, Nursing Institutions, Defense Organizations Application: Surgical Training, Medical Education, Pediatric Care, Emergency Response Technology: Software-Based Solutions, Hardware-Based Solutions, Simulation Platforms, Mixed Reality |
| Companies Covered | Surgical Science Sweden AB, Laerdal Medical, 3B Scientific, Mentice AB, Limbs & Things, CAE Inc., Gaumard Scientific, 3D Systems Corp, VirtaMed AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Simulation Market Shifts & Advancements
Artificial intelligence is embedding into simulation platforms to generate adaptive patient responses, while regulatory frameworks force convergence between training efficacy data and formal competency credentials.
Photorealistic volumetric rendering is integrating real-time tissue deformation physics with patient-specific anatomical models derived from CT and MRI datasets. Teaching hospitals in France and the UK are adopting these platforms for pre-procedural rehearsal at rates exceeding hardware replacement cycles. The technology is integrating surgical planning workflows with training environments, compressing the boundary between diagnostic imaging and skills acquisition.
The EU Medical Device Regulation's Annex XVI expansion now captures software-only simulation products previously exempt from clinical validation. Manufacturers must submit performance data demonstrating transfer of training to live procedures, elevating R&D spend for scenario fidelity. Interventional cardiology modules face the steepest compliance burden given the high-stakes nature of endovascular error.
Buying committees at NHS trusts and German university hospitals now require outcome metrics linking simulation hours to reduced complication rates before capital approval. Traditional equipment vendors with direct sales relationships are adding clinical education consultants to justify ROI. This behavioral shift is most visible in the UK, where NHS England's patient safety mandates explicitly reference simulation-based competency verification for high-risk procedures.
Europe Medical Simulation Market Segmentation
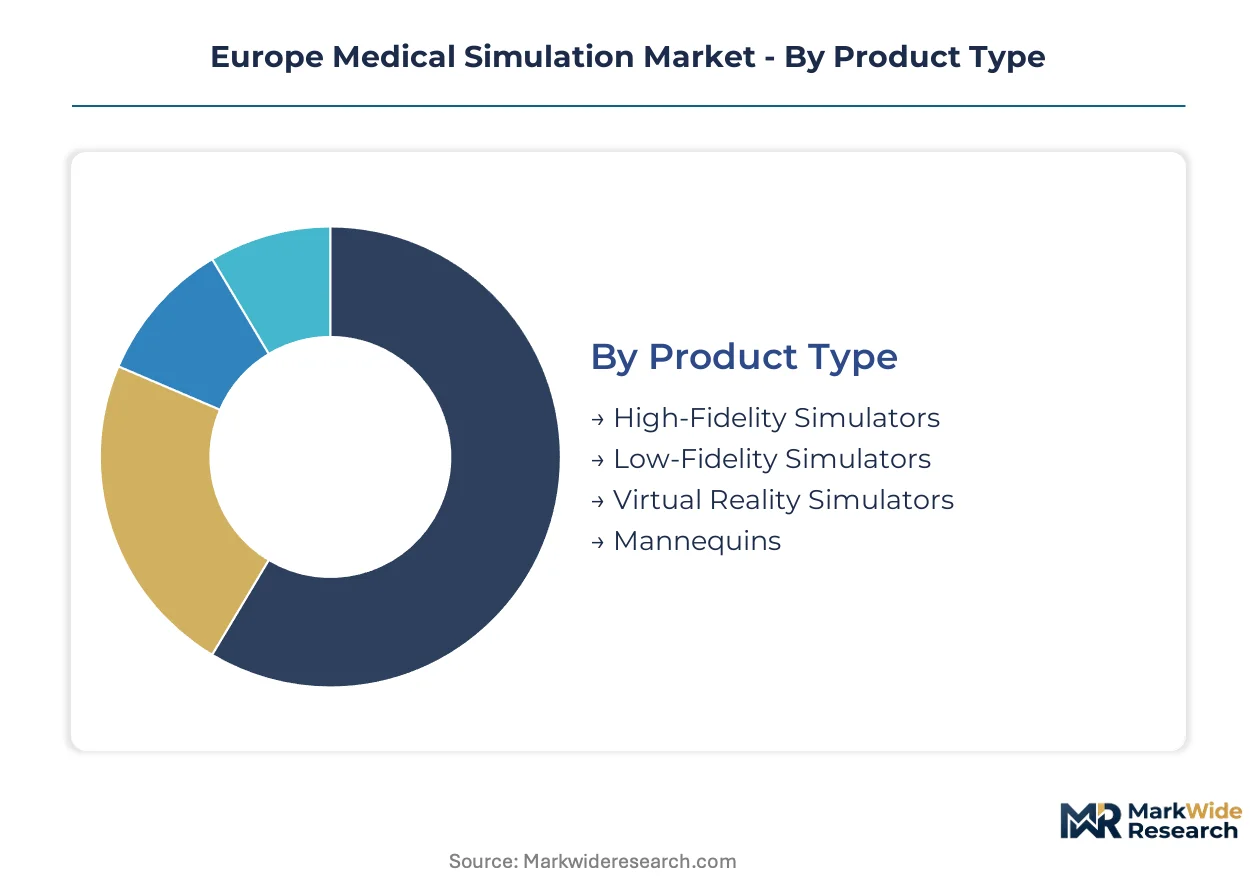
Medical simulation procurement in Europe fragments across hardware maturity curves and software upgrade cycles. Teaching hospitals prioritize high-fidelity systems for accreditation compliance while nursing institutions seek cost-effective task trainers. Understanding segment-level demand concentration reveals where margin pools are migrating.
Product Type:
Volume concentrates in entry-level mannequins, but premium capture belongs to immersive platforms with haptic feedback engines and photorealistic rendering.
- High-Fidelity Simulators:Physiologic modeling software generates real-time cardiac, respiratory, and neurological responses to learner interventions. Charité Berlin and Heidelberg University Hospital anchor demand in Germany's university hospital clusters, driven by MDR mandates classifying advanced simulators as training-equivalent to live patient exposure.
- Virtual Reality Simulators:Photorealistic tissue deformation enabled by declining hardware costs and advanced graphics processing. NHS trusts in the UK accelerate procurement for pre-procedural rehearsal, compressing replacement cycles for legacy equipment.
- Low-Fidelity Simulators:Basic task trainers for repetitive skill acquisition in resource-constrained nursing programs across Poland and Czech Republic.
- Mannequins:Physical patient models for emergency response training, with Laerdal Medical dominating through direct hospital channel control.
Today's leader: High-Fidelity Simulators. Tomorrow's challenger: Virtual Reality Simulators.
End User:
Procurement authority concentrates in teaching hospitals with dedicated simulation center budgets, while medical schools represent volume expansion at lower per-unit spend.
- Hospitals:German university hospital clusters and UK NHS simulation centers drive premium demand. Buying committees now require outcome metrics linking simulation hours to reduced complication rates before capital approval.
- Medical Schools:Warsaw and Prague medical faculties lack simulation infrastructure relative to Western European peers, creating first-mover whitespace for platform vendors.
- Nursing Institutions:Cost-sensitive procurement of low-fidelity task trainers for basic competency verification.
- Defense Organizations:Combat casualty care simulation for field medic training, with specialized trauma scenario requirements.
Demand anchors in hospitals. Volume expansion sits with medical schools.
Application:
Surgical training commands premium pricing, while emergency response applications face substitution pressure from software-defined platforms.
- Surgical Training:Laparoscopic and endovascular modules with force-feedback engines replicating tissue resistance at sub-millimeter precision. Surgical Science Sweden AB leverages haptic technology to dominate this segment.
- Medical Education:Core curriculum integration across European medical faculties, with EMA guidance on Good Clinical Practice referencing simulation-based competency verification.
- Emergency Response:Mannequin-based training for cardiac arrest and trauma protocols.
- Pediatric Care:Specialized neonatal and pediatric simulation for rare procedure exposure.
Premium capture: Surgical Training. Steepest expansion trajectory: Medical Education.
Technology:
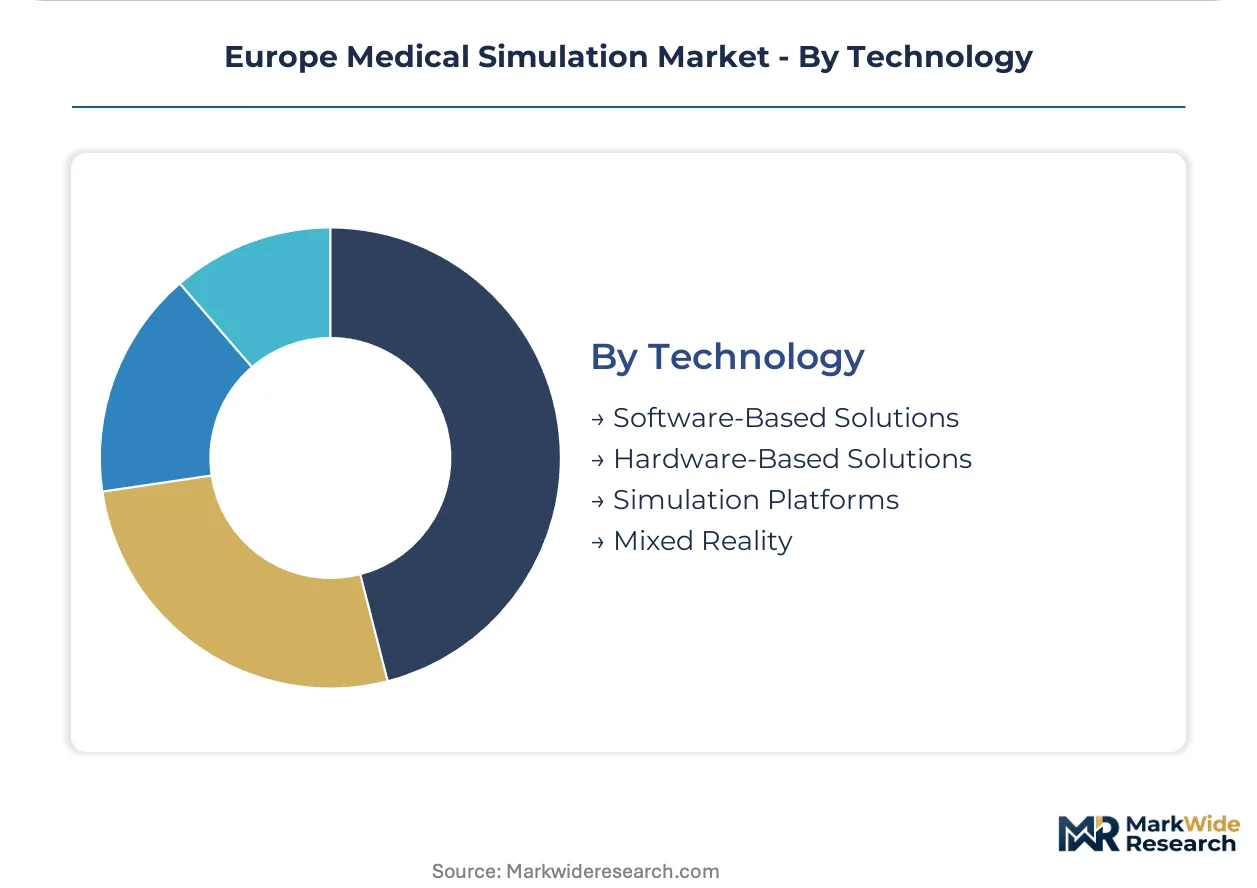
Margin pools are migrating from hardware installations toward software-defined feature upgrades and cloud-hosted scenario libraries.
- Software-Based Solutions:Subscription licensing for adaptive patient responses and AI-generated scenario variation. GDPR compliance for learner performance analytics creates legal review cycles extending sales timelines.
- Hardware-Based Solutions:Mature revenue base with stranded inventory risk as low-fidelity platforms face obsolescence.
- Simulation Platforms:Integrated hardware-software systems with cloud-hosted case archives enabling recurring revenue.
- Mixed Reality:Emerging convergence of physical mannequins with virtual environment overlays.
Current margin concentration: Software-Based Solutions. Emerging architecture: Mixed Reality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in high-fidelity simulator procurement, while the UK accelerates VR adoption for NHS surgical training programs.
Germany
Charité Berlin and Heidelberg University Hospital anchor demand through dedicated simulation center budgets. The EU MDR classification of advanced simulators as training-equivalent to live patient exposure forces teaching hospitals to upgrade legacy equipment. Bavaria's university hospital clusters radiate procurement standards to mid-tier institutions across southern Germany.
United Kingdom
NHS England's patient safety mandates explicitly reference simulation-based competency verification for high-risk procedures. NHS trusts now require outcome metrics linking simulation hours to reduced complication rates before capital approval. London and the Southeast concentrate procurement authority for premium VR systems.
France
ANSM oversight tightens clinical validation requirements for simulation products marketed as training replacements. The country's health technology assessment bodies incorporate simulation efficacy data into teaching hospital reimbursement criteria. Parisian university hospitals lead adoption of photorealistic volumetric rendering platforms.
Sweden
Swedish medical device developers leverage domestic haptic feedback expertise to supply laparoscopic training modules across Nordic markets. CE marking alignment with MDR Annex XVI elevates R&D spend for scenario fidelity. Gothenburg's medical technology corridor concentrates simulation platform engineering talent.
Poland
Medical faculties in Warsaw lack simulation infrastructure relative to Western European peers, creating first-mover whitespace for platform vendors. EU structural funds support healthcare modernization programs that include simulation center development. Krakow emerges as a secondary hub for nursing institution procurement of entry-level task trainers.
Europe Medical Simulation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors commanding premium positioning in high-fidelity systems while component suppliers serve cost-sensitive nursing programs. The vendor landscape organizes around three archetypes: haptic technology specialists, emergency response mannequin incumbents, and endovascular simulation pure-plays. M&A activity concentrates on software-defined feature acquisitions, while geographic expansion targets underpenetrated Central European medical faculties.
Among Nordic-origin platform developers, Surgical Science Sweden AB and Mentice AB exemplify the haptic specialization archetype, with the former occupying a dominant position in laparoscopic training modules and the latter anchoring endovascular simulation networks. Laerdal Medical represents the emergency response incumbent tier through sustained channel control across hospital systems. These three entities illustrate how technology differentiation and direct sales relationships shape competitive positioning within MDR-compliant procurement environments.
| Leading Market Players |
|---|
| Surgical Science Sweden AB |
| Laerdal Medical |
| 3B Scientific |
| Mentice AB |
| Limbs & Things |
| CAE Inc. |
| Gaumard Scientific |
| 3D Systems Corp |
| VirtaMed AG |
| Others |
Supply & Pricing Matrix
Graphics processing unit spot pricing volatility cascades through European medical simulation manufacturing, compressing margins on VR-enabled platforms while amplifying pricing power for haptic engine vendors with captive semiconductor sourcing. German university hospital clusters absorb premium tier increases through dedicated simulation center budgets, whereas Polish and Czech nursing institutions face procurement delays from component cost pass-through.
Pricing Analysis
Capacity additions in Swedish haptic technology production are reshaping price floors for force-feedback surgical trainers, yet NVIDIA chip allocation constraints sustain premium capture for photorealistic VR systems. Three-tier pricing structure across MDR-validated premium, CE-marked standard, and non-validated economy levels separates German teaching hospitals from Polish medical faculties. Cost compression in low-fidelity mannequins is intensifying because software-defined platforms displace physical inventory. Nursing institutions in Central Europe exhibit highest price sensitivity; NHS trusts with patient safety mandates show lowest.
Supply Chain Analysis
Photorealistic rendering hardware rests on Taiwanese semiconductor foundries, German precision motion control manufacturers, and Swedish haptic feedback engineering clusters. Supply chains draw from NVIDIA and AMD GPUs, force-feedback actuators, and medical-grade silicone polymers. Single-source vulnerability concentrates in advanced graphics processing allocation. Distribution runs through direct hospital channel relationships for high-fidelity systems and medical equipment distributors for entry-level trainers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European medical simulation has entered a late-cycle quality phase where MDR compliance separates sustainable premium capture from stranded hardware inventory. German university hospital procurement shifts toward outcome-linked VR platforms validate this specification upgrade trajectory.
For Market Incumbents: Hedge against software-defined substitution by deepening haptic engine IP control and securing direct NHS channel relationships before cloud-hosted scenario libraries commoditize hardware margins. CE marking bottlenecks at German and Dutch notified bodies threaten launch timelines for legacy equipment refreshes. Prioritize MDR Annex XVI validation investment over capacity expansion in saturated Western European clusters. For New Entrants and Emerging Players: Capture whitespace in Warsaw and Prague medical faculties where simulation infrastructure lags Western European accreditation standards by 5-7 years. Polish nursing institutions present the most penetrable volume tier for entry-level task trainers. Lead with EU structural fund eligibility positioning to accelerate procurement cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with Nordic-origin platform developers possessing integrated haptic-software architectures and established CE marking pathways. Five-to-ten-year viability hinges on recurring revenue transition from perpetual hardware sales. Watch for EMA guidance expansion linking simulation hours to investigator certification as inflection signal for adjacent revenue stream monetization.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Annex XVI Validation Investment | CE marking alignment with EU Medical Device Regulation secures teaching hospital procurement eligibility. |
| Cloud-Hosted Scenario Library Development | Subscription revenue models transform one-time hardware deployments into recurring monetization streams. |
| Haptic Engine IP Acquisition | Force-feedback technology control defends margin position against software-only simulation entrants. |
| Central European Medical Faculty Partnership | Warsaw and Prague infrastructure gaps create first-mover reference sites for platform standardization. |
| NHS Trust Direct Channel Expansion | Patient safety mandate alignment accelerates capital approval for outcome-linked VR system procurement. |
Research Methodology
Direct dialogue with hospital simulation center directors, biomedical engineering procurement leads, GPO contracts managers, and MDR regulatory affairs specialists grounded qualitative insights. Secondary validation drew from EMA guidance documents, NHS England patient safety mandates, EU Medical Device Regulation Annex XVI texts, and German university hospital procurement databases. Bottom-up demand modeling triangulated against top-down market sizing across hardware and software revenue streams.
Top-down macroeconomic framing anchored growth assumptions while bottom-up segment builds validated penetration rates across the projection horizon. Segmentation dimensions spanned product fidelity tier, end-user institution type, application specialty, and technology architecture. CAGRs emerged from installed base replacement cycles, MDR compliance-driven upgrade mandates, and software subscription attach rate trajectories. Haptic engine cost curves and GPU supply allocation forecasts informed hardware margin projections.
Notified body capacity constraints, graphics processing export control friction, and GDPR compliance timeline extensions are the dominant revision risks to modeled outcomes. Forecasts embed assumptions about MDR enforcement consistency and NHS funding continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Military Lighting Market
Others
Global Compact Wheel Loaders Market
Others
One-Way Degassing Valve Market
Others
Europe Military 4D Printing Market
Others
Global Digital Market
Others
Air Separation Plant Market
Others
Solid White Films Market
Others
Global Electroshock Weapons Market
Others
Motor Grader Market
Others
Underwater Light Market
Others
Brazil Lime Market
Others
United States Air Furnaces Market
Others
Germany Smart Home Market
Others
Idaas Market
Others
Calcined Petroleum Coke Market
Others
Indoor LBS Market