
 North America Cashew Market | 2026-2036
North America Cashew Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cashew Market Analytics
Food manufacturers is rebalancing toward higher cashew inclusion as plant-based cheese and dairy analog formulations gain shelf space across North American retail channels. John B. Sanfilippo & Son Inc. anchors its position through extensive roasting and flavoring infrastructure in the Midwest. Diamond Foods LLC competes via branded snack portfolios distributed through mainstream grocery networks. Emerald Nuts LLC differentiates through seasoned and value-added product lines targeting convenience-oriented consumers.
Cashews comprise the curved, kidney-shaped seeds of Anacardium occidentale, typically containing 46-48% oil and 18-20% protein by weight, with commercial grades determined by wholeness, scorching, and coloration after roasting or dry-processing. The nuts serve as critical inputs across confectionery, nut butter, vegan dairy alternatives, and premium snack applications where mouthfeel and neutral flavor profiles matter. Raw cashews occupy the largest volume share among product type segments, though roasted and spiced variants command stronger unit economics through flavor premiumization. Specialty stores and online retail channels are expanding fastest within distribution channel segmentation, reflecting direct-to-consumer subscription models and health-focused curation that bypasses conventional grocery slotting fees.
The FDA governs allergen labeling and nutrition fact panel standards that directly influence cashew product packaging claims and cross-contamination protocols for manufacturers selling in the United States. USDA organic certification and state-level agricultural inspection regimes in California and Texas shape premium positioning and import verification requirements for roasted and raw product lines. Stakeholders must monitor evolving plant-based protein classification debates and traceability mandates that could alter sourcing documentation burdens across the value chain.
Market Dynamics
Plant-based dairy alternatives are absorbing larger cashew volumes as FDA nutrition labeling updates and clean-label ingredient trends steer processor formulations across the United States and Mexico.
Growth Catalysts
- Clean-label mandates:FDA nutrition fact panel revisions are compelling manufacturers to reformulate with recognizable cashew ingredients rather than synthetic additives.
- California snack food cluster:Concentrated demand from roasted and flavored nut processors creates dedicated offtake agreements with regional distributors.
- Steam-based pasteurization:This non-chemical pathogen reduction method is expanding raw cashew eligibility for organic certification and premium positioning.
Market Restraints
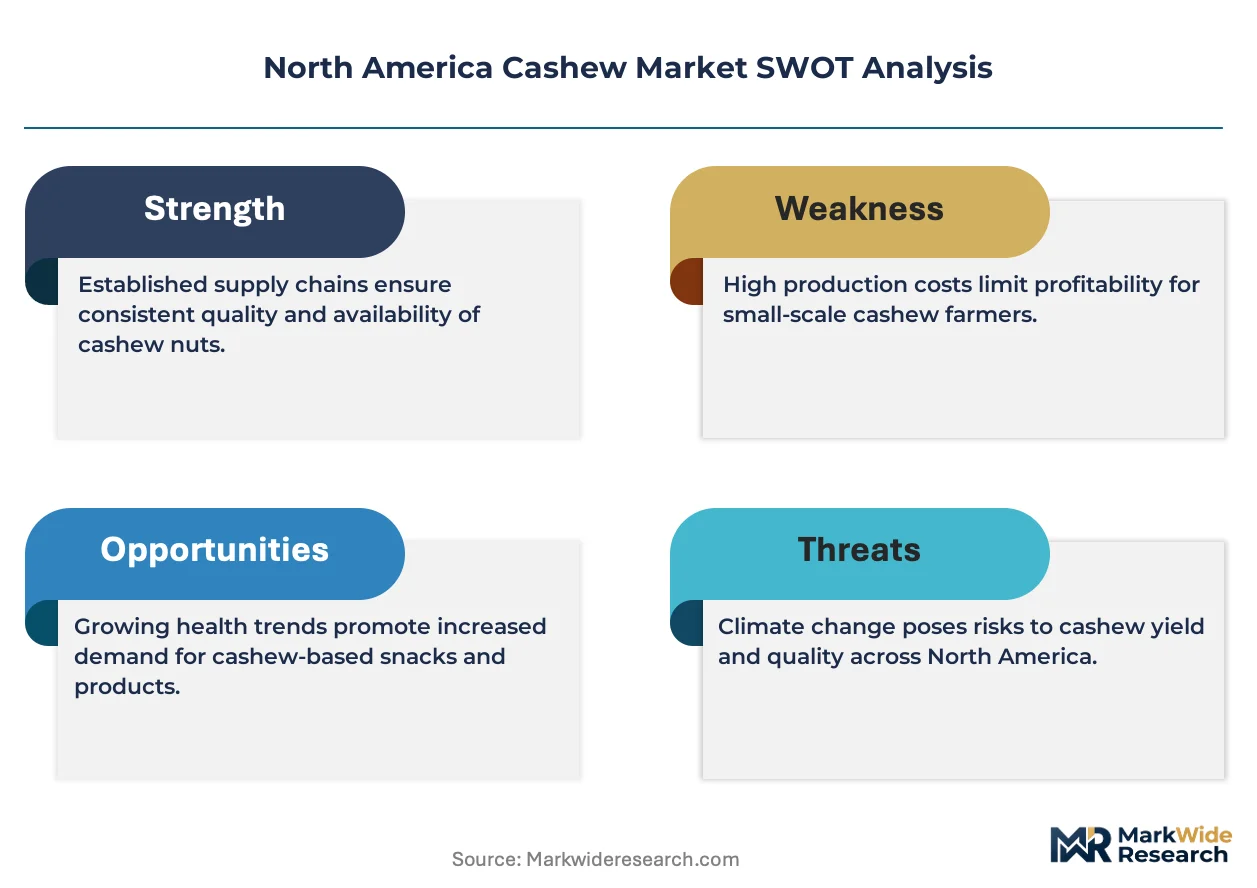
- African supply concentration:Ivory Coast and Ghana processing dominance exposes buyers to port congestion and currency volatility in West African franc zones.
- Allergen labeling friction:FDA tree nut classification requirements impose cross-contamination protocols that inflate packaging and facility segregation costs.
- Oat and almond substitution:Lower-cost plant-based bases are capturing shelf space in mass-market dairy alternatives, compressing cashew inclusion rates in economy-tier products.
Strategic Opportunities
- Mexico processing corridor:Emerging roasting and flavoring infrastructure near Manzanillo port offers tariff-advantaged supply to US Southwest distribution networks.
- Direct-to-consumer subscriptions:Specialty online channels bypass conventional grocery slotting fees and capture margin through health-focused curation.
- USDA organic tailwind:Premium certification demand is outpacing certified acreage expansion, creating first-mover advantages for verified supply chain documentation.
Industry Challenges
- Roasting technician scarcity:Specialized flavor development and moisture-control expertise is concentrated among legacy Midwest processors, constraining new facility staffing.
- Traceability system integration:Lot-level farm-to-fork documentation requirements are forcing mid-tier processors to retrofit legacy ERP systems or face exclusion from major retailer supply programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cashew Market |
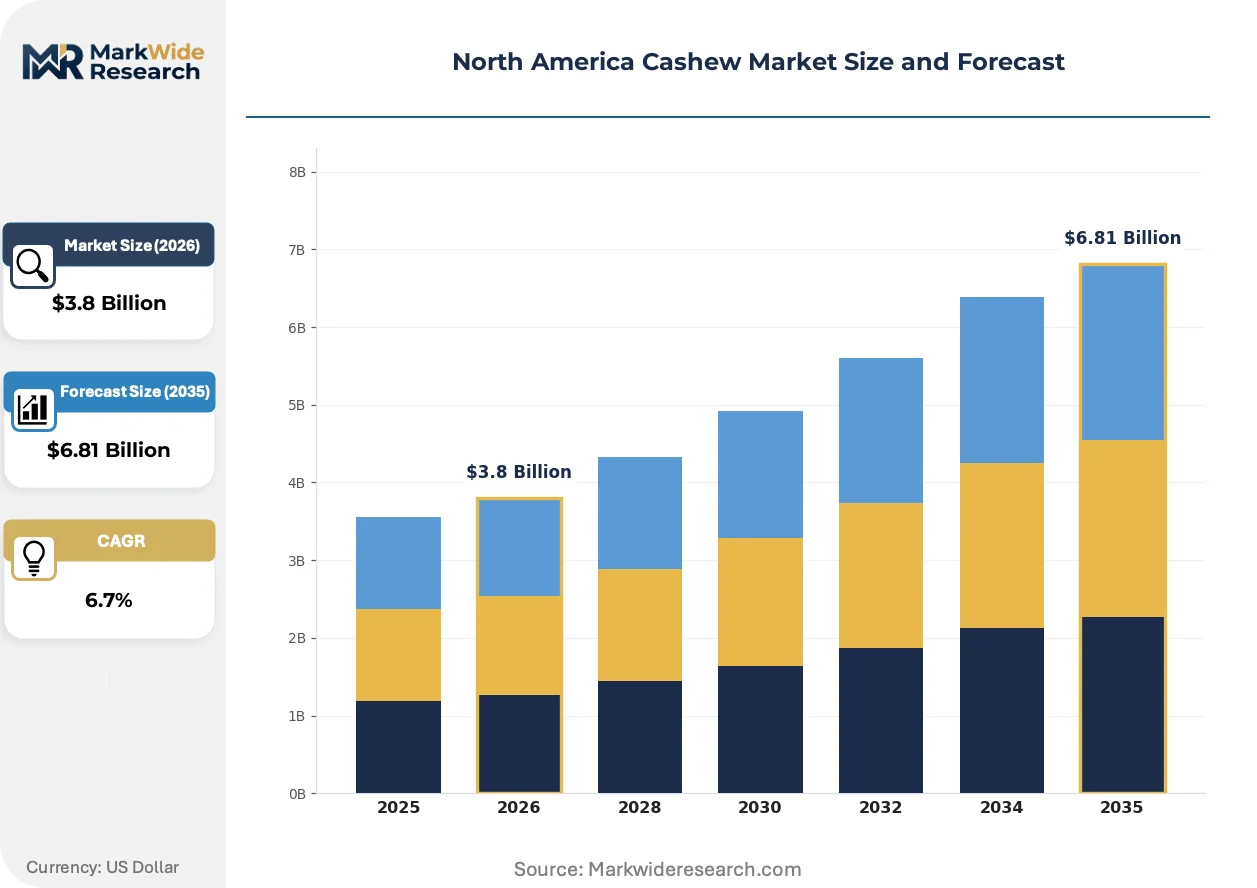
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Cashews, Roasted Cashews, Salted Cashews, Spiced Cashews Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Stores End User: Households, Restaurants, Bakeries, Food Manufacturers Packaging Type: Bags, Pouches, Tins, Bulk Packaging |
| Companies Covered | Aurora Products Inc., Braga Organic Farms, Diamond Foods LLC, Flanigan Farms Natural Foods, Bates Nut Farm, John B. Sanfilippo & Son Inc., Nutsco Inc., D&S Ranches, Emerald Nuts LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cashew Market Evolving Landscape
Processing technology and distribution models are restructuring how cashews move from raw commodity to finished consumer products across North American channels.
Steam pasteurization systems are overtaking propylene oxide fumigation as the dominant pathogen control method for raw cashew imports. Organic-certified processors in California and Texas are adopting steam-based systems to maintain label integrity for premium retail segments. This shift is compressing the addressable market for chemical treatment equipment while expanding cold-chain infrastructure requirements at port-of-entry facilities.
The FDA's updated nutrition labeling rules for added sugars and serving sizes are forcing reformulation across nut butter and dairy alternative categories. Manufacturers are reducing sugar content and adjusting portion claims to align with revised daily value percentages. Snack food producers targeting California's health-conscious consumer base are accelerating package redesign timelines to meet compliance deadlines.
Subscription-based procurement is displacing traditional wholesale purchasing among specialty retailers and direct-to-consumer brands. Health-focused curation services are aggregating demand for small-batch roasted and seasoned varieties outside conventional grocery distribution. This pattern is most visible in urban coastal markets where consumers prioritize traceability claims and limited-edition flavor releases over mass-market price points.
North America Cashew Market Segmentation
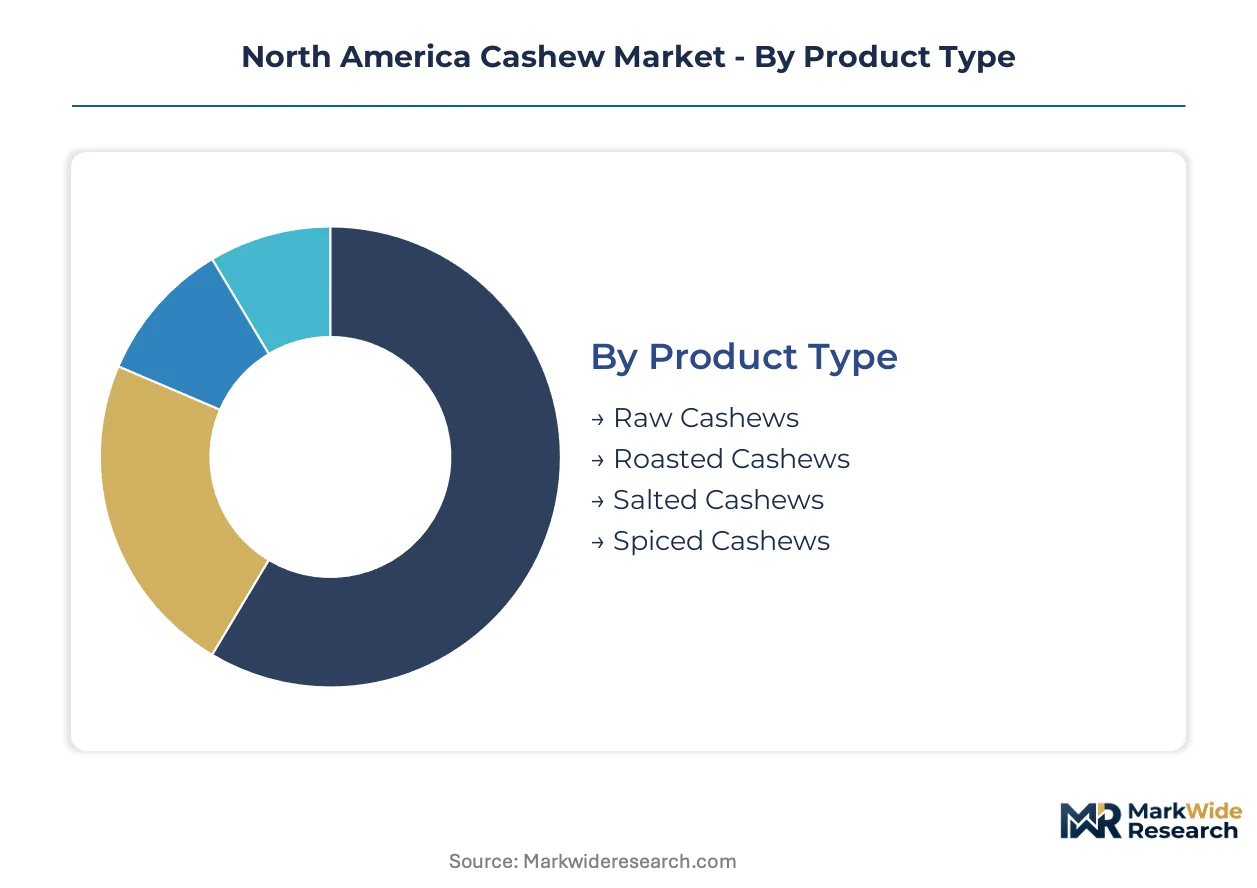
Cashew segmentation across North America tracks distinct value capture patterns between commodity-grade raw inputs and premium-positioned finished goods. Product form and channel selection determine margin architecture, with organic certification and steam-pasteurization status acting as critical price-tier differentiators.
Product Type:
Integration depth varies sharply across this category, with raw cashews serving as standalone commodity inputs while roasted and flavored variants embed into branded consumer portfolios.
- Raw Cashews:These unprocessed kernels retain 46-48% oil content and 18-20% protein by weight, forming the foundational input for food manufacturers producing vegan dairy alternatives and nut butters. Demand concentrates most visibly in California's snack food cluster, where processors seek steam-pasteurized organic grades for clean-label formulations.
- Roasted Cashews:Dry-heat processing develops Maillard-reaction flavor compounds and extends shelf stability for direct consumption. Food manufacturers in the Midwest—anchored by John B. Sanfilippo & Son's infrastructure—absorb the largest volumes for private-label and branded snack portfolios.
- Salted Cashews:Sodium-enhanced variants target mainstream retail channels with familiar flavor profiles and lower price elasticity.
- Spiced Cashews:Seasoned offerings from Emerald Nuts and similar players capture convenience-oriented consumers through limited-edition and ethnic-flavor rotations.
Volume placements concentrate in Raw Cashews; the faster expansion belongs to Spiced Cashews.
Distribution Channel:
Channel selection maps directly to customer acquisition cost and margin retention, with digital-native routes bypassing traditional grocery slotting-fee structures.
- Online Retail:Direct-to-consumer subscriptions and health-focused curation services aggregate demand for small-batch and traceable varieties. Urban coastal markets—particularly in California and the Pacific Northwest—drive the steepest expansion trajectory here as consumers prioritize farm-to-fork documentation over mass-market price points.
- Supermarkets:Conventional grocery networks remain the dominant volume channel, with Diamond Foods LLC and similar players competing for shelf space through branded snack portfolios.
- Convenience Stores:Grab-and-go formats favor single-serve pouches and value-priced salted variants.
- Specialty Stores:Premium retailers curate organic-certified and small-roaster lines for health-conscious segments.
Revenue weight rests with Supermarkets; margin expansion is concentrating fastest in Online Retail.
End User:
End-use segmentation reveals a bifurcation between household consumption and industrial-scale ingredient absorption across foodservice and manufacturing.
- Households:Direct consumers purchase across all product types, with purchasing decisions influenced by FDA nutrition labeling visibility and allergen warnings. California's health-conscious demographic drives disproportionate demand for organic-certified and low-sodium options.
- Restaurants:Foodservice operators incorporate cashews into plant-based menu items and premium salad toppings.
- Bakeries:Confectionery and pastry applications utilize chopped and paste forms for texture and binding.
- Food Manufacturers:Industrial buyers absorb raw and bulk-roasted volumes for vegan cheese, dairy alternatives, and nut butter production.
Absolute volume flows to Food Manufacturers; the most rapid demand growth is appearing in Restaurants.
Packaging Type:
Packaging configuration signals price-tier positioning and supply-chain efficiency requirements from bulk commodity handling to single-serve convenience.
- Bags:Flexible paper and plastic bag formats dominate mainstream retail with cost-efficient barrier properties. Supermarket and convenience channels in the US Southwest—served by Mexico's emerging processing corridor—favor this format for economy-tier positioning.
- Pouches:Resealable stand-up pouches with high-definition printing support premium branding and portion-control claims.
- Tins:Rigid metal packaging preserves freshness for gift-oriented and ultra-premium segments.
- Bulk Packaging:Industrial totes and supersacks serve food manufacturers and bakery operations with minimal handling overhead.
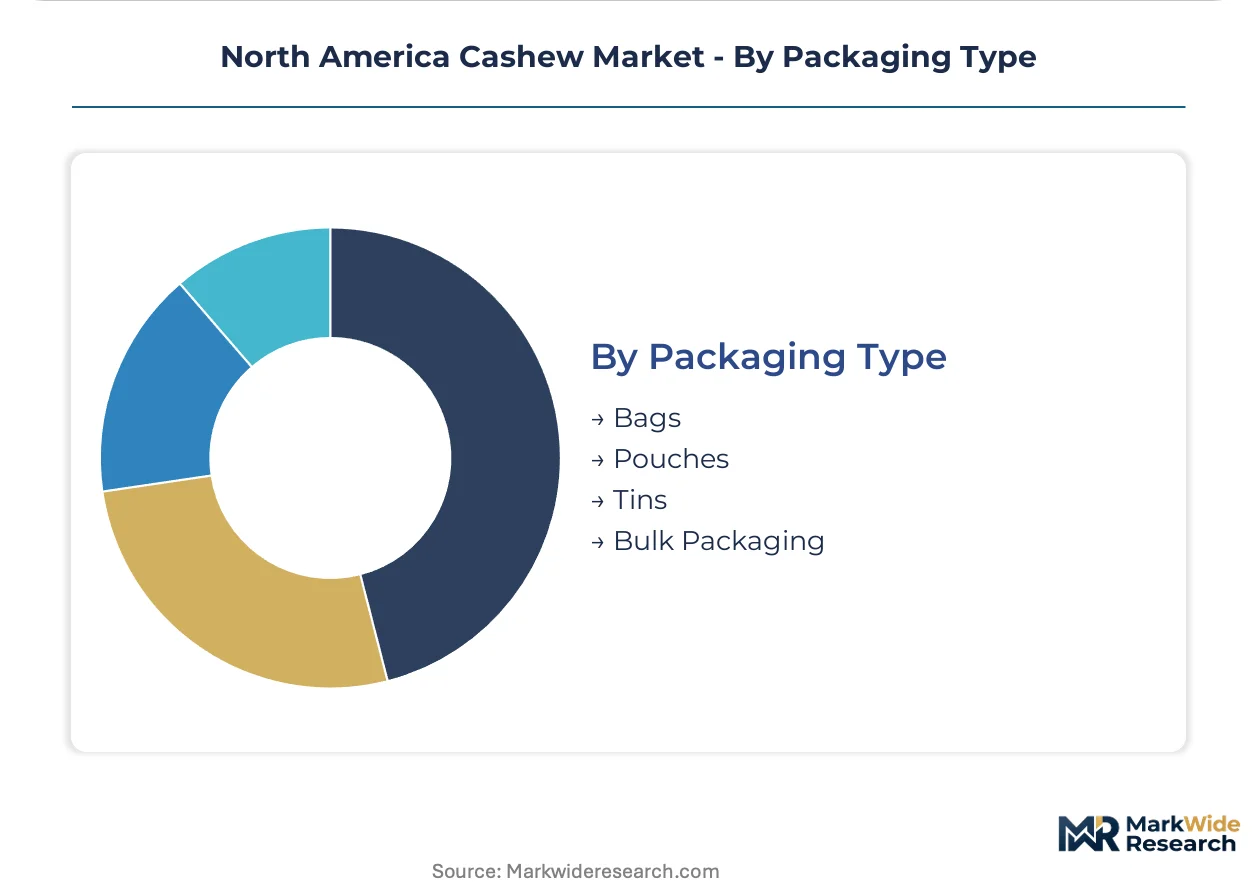
Shipment volumes cluster in Bulk Packaging; brand-margin capture is migrating fastest toward Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American cashew consumption outstrips regional production by substantial margins, forcing reliance on West African and Asian import corridors. The United States absorbs the majority of volume, while Mexico develops processing capacity and Canada channels demand through health-specialty import channels.
United States
California's snack food cluster generates concentrated demand for steam-pasteurized organic grades, with processors in the Central Valley seeking clean-label inputs for plant-based dairy formulations. FDA nutrition labeling revisions compel reformulation across nut butter and dairy alternative categories, tightening compliance timelines for packaged goods manufacturers. Midwest roasting infrastructure anchored by Illinois-based operations supplies branded and private-label portfolios to mainstream grocery networks nationwide.
Mexico
Manzanillo port corridors are attracting roasting and flavoring investments to serve US Southwest distribution networks with tariff-advantaged supply positioning. Mexico's national agricultural inspection regime coordinates with USDA organic verification protocols to streamline cross-border shipment clearance. Jalisco and Nuevo León processing zones are expanding cold-chain infrastructure to handle rising raw cashew import volumes from Ivory Coast and Ghana.
Canada
Health Canada and PMRA allergen labeling requirements parallel FDA tree nut classification standards, imposing cross-contamination protocols that elevate packaging costs for imported finished goods. Ontario and Quebec distribution hubs channel premium organic cashews through specialty retail and direct-to-consumer subscription services. Vancouver and Toronto urban markets demonstrate disproportionate appetite for traceable small-batch roasted varieties.
North America Cashew Market Competitive Landscape
Top-tier vendors anchor branded snack and ingredient supply, while mid-tier processors compete on private-label roasting capacity and organic certification speed. The competitive structure stratifies across three functional tiers: legacy Midwest roasters with established flavor development expertise, coastal importers prioritizing traceability documentation, and emerging Mexican processors exploiting tariff and logistics advantages. Dominant competitive moves include backward integration into sourcing relationships and technology licensing for steam-pasteurization systems.
Within the legacy roasting tier, John B. Sanfilippo & Son Inc. and Diamond Foods LLC occupy positions exemplifying scale-driven Midwest infrastructure, while Emerald Nuts LLC represents the seasoned-product differentiation archetype targeting convenience-oriented consumers. Aurora Products Inc. and Braga Organic Farms sit within the organic-certified and specialty-import segments respectively, reflecting the market's bifurcation between mass-market volume and premium-positioned curation.
| Leading Market Players |
|---|
| Aurora Products Inc. |
| Braga Organic Farms |
| Diamond Foods LLC |
| Flanigan Farms Natural Foods |
| Bates Nut Farm |
| John B. Sanfilippo & Son Inc. |
| Nutsco Inc. |
| D&S Ranches |
| Emerald Nuts LLC |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap processors in California and Texas exercise pricing discipline through captive organic acreage relationships and direct-to-consumer channel control, insulating premium grades from commodity volatility while economy-tier raw kernels face compression from West African oversupply.
Pricing Analysis
Margin tightening in economy-tier raw cashews reflects oat and almond substitution in mass-market dairy alternatives, while premium-mid-economy pricing differentiation separates steam-pasteurized organic grades from chemically treated commodity lots. Brand premiums and USDA organic certification status drive price spreads, with California health-conscious consumers showing lowest price sensitivity and convenience-store salted variants facing highest elasticity. Cost-down pressure on standard-grade processors accelerates because Ivory Coast port congestion extends inventory carrying costs.
Supply Chain Analysis
USDA organic verification protocols and FDA allergen labeling requirements are reshaping sourcing documentation burdens, forcing mid-tier processors to upgrade ERP traceability systems. Supply concentrates in Ivory Coast, Ghana, and Vietnam for raw kernel imports, with roasting and flavoring capacity clustering in California, Illinois, and Mexico's Jalisco corridor. The chain draws from West African franc zone currency volatility, single-source vulnerability at Abidjan and Tema ports, and propylene oxide regulatory phase-out. Distribution runs through Midwest roasting hubs to national grocery networks, with direct-to-consumer subscriptions bypassing conventional slotting fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Roasting technician scarcity across legacy Midwest facilities props pricing for flavor-development capabilities, constraining new entrant scale-up and preserving incumbent margin pools.
For Market Incumbents: Lock in long-term offtake agreements with Ivory Coast and Ghana processing cooperatives before currency hedging costs escalate. Acquire steam-pasteurization technology licenses to defend organic certification speed against Mexican processing corridor entrants. Channel control through direct-to-consumer subscription platforms offers the strongest defensive lever against oat-milk substitution in dairy alternatives. For New Entrants and Emerging Players: Specialty online retailers represent the most penetrable channel partner type for traceable small-batch roasted varieties targeting urban coastal markets. White-space exists in USDA organic-certified spiced cashew subscriptions and Manzanillo-port-advantaged supply to US Southwest distribution networks. A health-focused curation go-to-market angle bypasses conventional grocery slotting-fee barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier processors with incomplete traceability system upgrades in California and Texas, where retrofit costs have strained working capital. Long-term viability hinges on verified supply chain documentation and organic certification backlog clearance. Watch for FDA plant-based protein classification rulings as the inflection signal for ingredient demand restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into West African Sourcing | Long-term offtake agreements with Ivory Coast cooperatives secure organic kernel supply against currency volatility. |
| Steam Pasteurization Technology Licensing | Non-chemical pathogen control maintains FDA label integrity for premium retail segments in California. |
| Direct-to-Consumer Subscription Launch | Health-focused curation models bypass conventional grocery slotting fees and capture margin in urban coastal markets. |
| Mexico Processing Corridor Expansion | Manzanillo port infrastructure offers tariff-advantaged supply positioning to US Southwest distribution networks. |
| USDA Organic Certification Acceleration | Premium certification demand outpaces certified acreage expansion, creating first-mover advantages in traceable supply chains. |
Research Methodology
Trade databases, FDA filing records, and USDA organic certification registries formed the secondary backbone, cross-referenced with primary interviews involving roasting facility managers, California snack food cluster procurement leads, organic certification auditors, and Midwest distribution channel partners. Bottom-up volume triangulation from processor capacity utilization combined with top-down retail audit data to establish market sizing boundaries.
Historical trendline analysis tracked kernel import volumes, organic acreage expansion rates, and plant-based dairy alternative formulation shifts across the projection horizon. Segmentation dimensions modeled include product form, distribution channel, end-use application, and steam-pasteurization certification status. CAGRs derived from weighted average of demand drivers and supply constraints, with West African port capacity and FDA labeling compliance timelines serving as industry-specific forecast inputs.
Caveats apply where Ivory Coast political instability, CFA franc devaluation, or FDA tree nut reclassification could materially shift the outlook. Forecasts reflect documented assumptions about organic certification speed and Mexican processing corridor buildout pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Communication Base Station Body Market
Others
Augmented Shopping Market
Others
Global Military Wearable Sensors Market
Others
Aluminium Clad Printed Circuit Board Market
Others
Global Multi Domain Controller Market
Others
Solid White Films Market
Others
Telecom Transformers Market
Others
Digital LUX Meter Market
Others
North America Commercial Vehicles Lubricants Market
Others
Finished Leather Market
Others
Light Meter Market
Others
Durian Market
Others
Global Tobacco Market
Others
Thermal Energy Flow Metering Solutions Market
Others
Ceramic Machinery Market
Others
Fluid Dispensing Systems Market