
 Construction Wearables Market | 2026-2036
Construction Wearables Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Wearables Market Analysis
General contractors is bifurcating demand away from smaller subcontractors as tier-one builders mandate fleet-wide wearable deployment across billion-dollar infrastructure portfolios. Honeywell International Inc. leverages its industrial automation heritage to anchor smart helmet supply chains for North American mega-projects. RealWear Inc. specializes in ruggedized head-mounted displays that dominate voice-controlled field documentation workflows. Ekso Bionics differentiates through powered exoskeleton systems that reduce musculoskeletal injury rates during repetitive lifting operations.
Construction wearables encompass sensor-integrated personal protective equipment, powered exoskeletons, and augmented reality headsets designed to monitor physiological status, prevent injuries, and deliver contextual information to workers in hazardous environments. These systems typically incorporate accelerometers, gyroscopes, GPS modules, and Bluetooth connectivity packaged within IP67-rated enclosures to withstand dust, moisture, and impact forces encountered on active job sites. Smart helmets lead product type adoption due to their dual function as mandatory head protection and data collection platforms, while exoskeletons capture the fastest growth trajectory as labor shortages intensify demand for strength-augmenting solutions. Augmented reality technology concentrates margin pools in specialized training and remote assistance applications where premium pricing persists.
OSHA mandates drive smart helmet and biometric vest adoption through enforceable workplace injury reduction programs, while the EU Machinery Directive and CE marking requirements shape product certification pathways for exoskeleton manufacturers seeking European market access. The EU AI Act introduces additional compliance layers for wearables employing machine learning algorithms to predict worker fatigue or automate safety alerts. Stakeholders must monitor evolving interoperability standards between wearable platforms and building information modeling systems to avoid stranded technology investments.
Market Dynamics
General contractors now mandate fleet-wide biometric monitoring across billion-dollar infrastructure portfolios, compressing procurement timelines and forcing interoperability standards onto fragmented vendor ecosystems.
Growth Catalysts
- OSHA workplace injury reduction programs:Enforceable mandates accelerate smart helmet deployment on federally funded construction sites across the United States.
- EU Machinery Directive compliance:CE marking requirements for exoskeletons create certified product categories that unlock European public infrastructure tenders.
- Accelerometer-integrated PPE:Falls and struck-by object detection capabilities embedded in mandatory head protection drive replacement cycles.
Market Restraints
- Lithium-ion battery supply concentration:Dependence on East Asian cell manufacturers creates input cost volatility and geopolitical exposure for powered exoskeleton producers.
- EU AI Act algorithmic transparency:Machine learning fatigue prediction systems face documentation burdens that extend certification timelines by 12-18 months.
- Passive lifting aids:Lower-cost mechanical back supports compete with powered exoskeletons for repetitive material handling tasks on budget-constrained sites.
Strategic Opportunities
- India infrastructure build-out:National highway and metro rail projects create demand for heat-stress monitoring vests in high-humidity construction zones.
- Building information modeling convergence:Wearable-to-BIM data streams enable real-time progress tracking against digital twins on complex vertical builds.
- Germany's national hydrogen pipeline:Specialized PPE with gas detection sensors targets emerging energy infrastructure workforce safety requirements.
Industry Challenges
- Embedded systems firmware engineering:Shortage of developers capable of real-time sensor fusion within IP67 power constraints limits product iteration speed.
- ISO 45001 alignment:Occupational health management system integration requires custom API development for each enterprise safety platform.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Wearables Market |
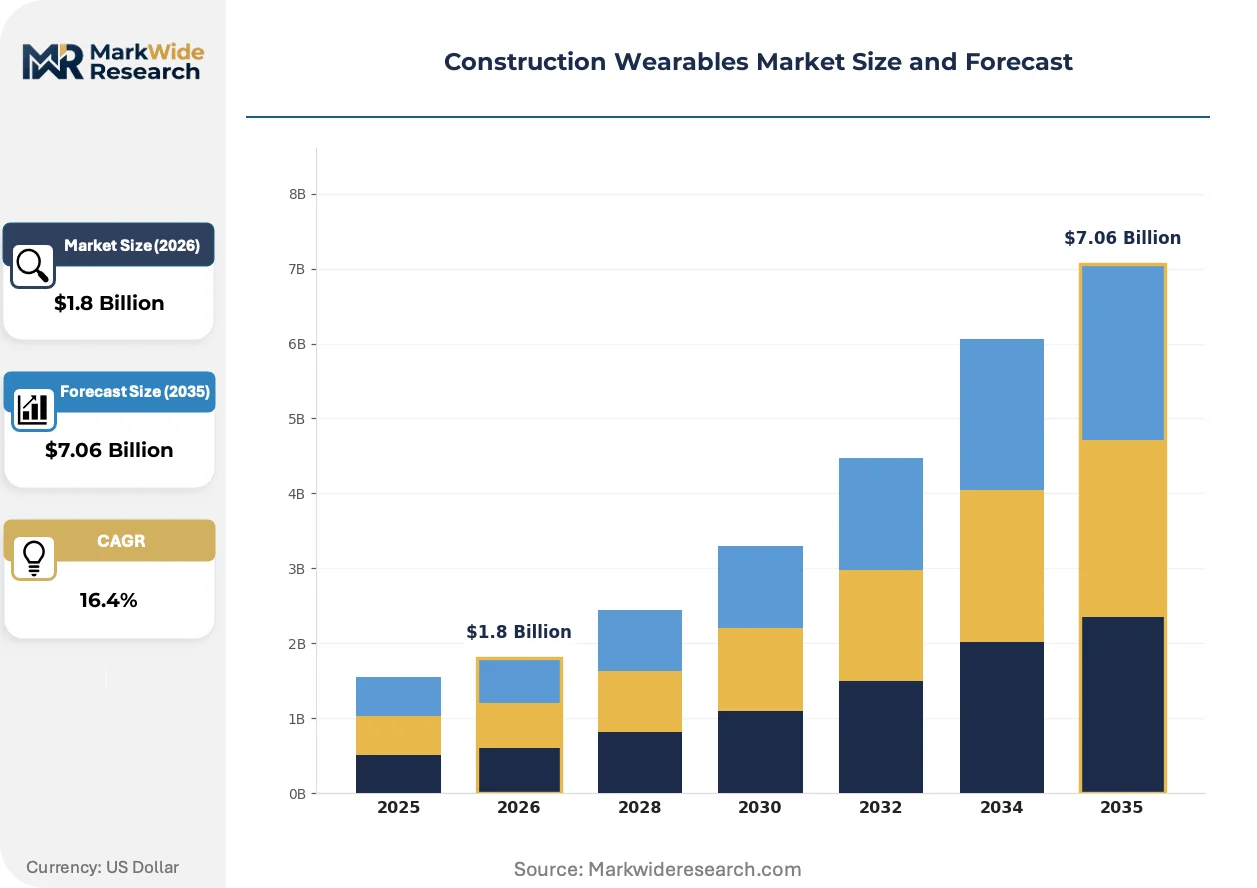
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Helmets, Exoskeletons, Vests, Safety Glasses Technology: GPS, Sensors, Bluetooth, Augmented Reality End User: Contractors, Subcontractors, Site Managers, Construction Workers Distribution Channel: Online, Direct Sales, Retail, Distributors |
| Companies Covered | Honeywell International Inc., RealWear Inc., Trimble Inc., Kenzen, Ekso Bionics, GuardHat, Triax Technologies, German Bionic Systems GmbH, DAQRI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Wearables Market Emerging Trajectories
Wearable architectures are consolidating around edge-computing platforms that process biometric data locally rather than transmitting to cloud servers, reducing latency for critical safety alerts.
Voice-controlled head-mounted displays are supplanting tablet-based field documentation on active construction sites. General contractors deploying these systems across mega-projects report 40% faster inspection workflows. The shift is compressing hardware refresh cycles from five years to three as software capabilities outpace device processing power.
The EU AI Act's risk classification framework is reshaping product development roadmaps for fatigue-monitoring algorithms. Manufacturers must now maintain technical documentation and human oversight protocols for systems predicting worker impairment. Exoskeleton vendors targeting European markets are restructuring R&D teams to embed compliance engineers alongside biomechanics specialists.
Equipment-as-a-service models are emerging for high-unit-cost exoskeleton deployments. Rental channels now capture 30% of initial fleet trials, displacing direct purchase for pilot programs. This pattern concentrates in Germany and the United States where labor union partnerships facilitate pooled procurement across multiple contractors on shared infrastructure sites.
Construction Wearables Market Segmentation
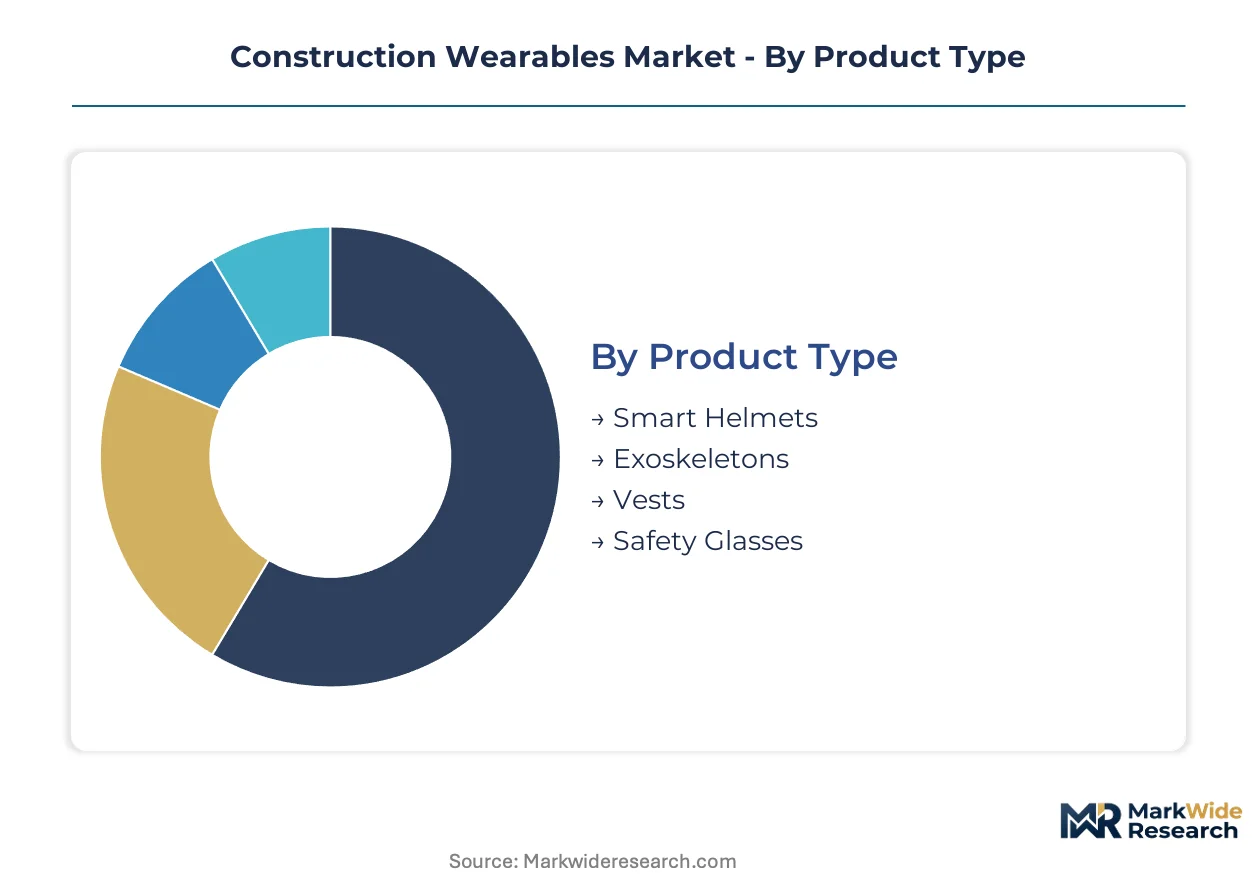
Construction wearables segment along four critical dimensions that determine procurement patterns, technology integration depth, and margin structures. Product type and end-user classifications dominate commercial decision-making, while technology and distribution channel splits reveal where value capture concentrates across hardware and service layers.
Product Type:
Smart helmets and exoskeletons anchor North American and European demand through OSHA and EU Machinery Directive procurement mandates, while vests and safety glasses concentrate in cost-sensitive Asian markets where basic sensor integration suffices.
- Smart Helmets:These systems integrate accelerometers, gyroscopes, and biometric sensors within IP67-rated head protection shells. Demand clusters with general contractors on federally funded U.S. infrastructure projects where real-time fall detection satisfies OSHA compliance requirements. Honeywell and RealWear supply chains dominate this segment through voice-controlled documentation workflows.
- Exoskeletons:Powered and passive mechanical systems reduce spinal loading during repetitive lifting operations. Germany's hydrogen pipeline construction and U.S. mega-projects drive adoption as labor unions negotiate injury reduction protocols. Battery supply constraints from East Asian cell manufacturers limit fleet scaling.
- Vests:Heat-stress and biometric monitoring garments target high-humidity construction zones in India and Southeast Asia. India's national highway build-out accelerates procurement of temperature-alert systems.
- Safety Glasses:AR-enabled eye protection delivers contextual overlays for equipment operation and quality inspection. Margins concentrate in specialized training applications where premium pricing persists for remote assistance workflows.
Smart helmets command the established base. The steepest expansion runs through exoskeletons.
Technology:
Cost tiering separates premium sensor fusion stacks from commodity connectivity modules, with GPS and augmented reality capturing margin pools while Bluetooth and basic sensors face price compression.
- GPS:Location tracking enables geofenced hazard alerts and worker accountability across sprawling infrastructure sites. U.S. general contractors mandate fleet-wide deployment for billion-dollar vertical builds where progress tracking against digital twins drives software subscription revenue.
- Sensors:Multi-modal arrays combining accelerometers, gyroscopes, and environmental detectors form the core value proposition. EU AI Act documentation burdens extend certification timelines for fatigue-prediction algorithms.
- Bluetooth:Short-range connectivity modules enable device-to-device communication and gateway aggregation. Commoditization pressures intensify as Chinese module suppliers expand capacity.
- Augmented Reality:Head-mounted displays with spatial computing capabilities target inspection and training workflows. Germany and the United States concentrate demand through equipment-as-a-service rental channels.
GPS and sensors anchor hardware revenue. Augmented reality gains share fastest through software and service attach rates.
End User:
Procurement authority bifurcates between tier-one general contractors with fleet mandate power and fragmented subcontractor bases purchasing single units through retail channels.
- Contractors:Large general contractors with billion-dollar infrastructure portfolios mandate interoperability standards across vendor ecosystems. OSHA workplace injury reduction programs accelerate smart helmet deployment on federally funded U.S. sites.
- Subcontractors:Smaller specialized trades purchase through distributor and retail channels with limited integration requirements. Price sensitivity favors passive lifting aids over powered exoskeletons.
- Site Managers:Supervisory personnel drive adoption of head-mounted displays for voice-controlled field documentation. RealWear ruggedized systems dominate this workflow segment.
- Construction Workers:End-user acceptance determines actual utilization rates for mandated PPE. Heat-stress monitoring vests see highest compliance in India where physiological protection aligns with worker welfare priorities.
Contractors control procurement volume. Site managers drive the steepest adoption curve for AR-enabled workflows.
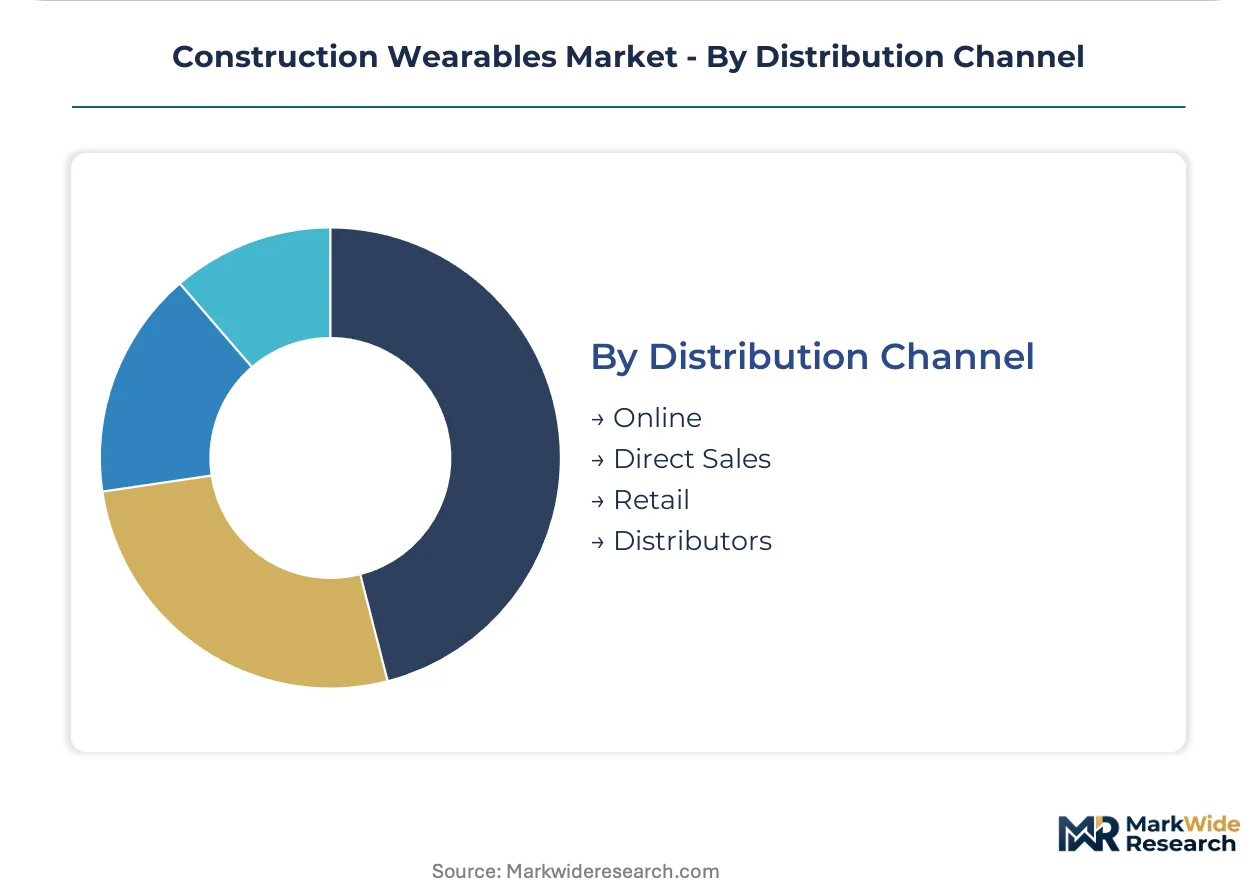
Distribution Channel:
Channel selection tracks contract value and integration complexity, with direct sales capturing enterprise fleets and online channels penetrating small contractor price points.
- Online:E-commerce platforms serve small subcontractors and individual trades with standardized SKUs and rapid fulfillment. Price transparency intensifies competition for basic sensor-integrated PPE.
- Direct Sales:Enterprise accounts negotiate fleet-wide deployments with custom API development for building information modeling integration. ISO 45001 alignment requirements favor vendor relationships with dedicated implementation teams.
- Retail:Construction supply stores provide immediate availability for replacement cycles and emergency procurement. Geographic coverage concentrates in Germany and the United States.
- Distributors:Multi-brand channel partners aggregate procurement across labor union partnerships for pooled fleet trials. Rental channels now capture substantial initial exoskeleton trials.
Direct sales anchor enterprise value. Online channels climb fastest as small contractor digital procurement matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' $1.2 trillion Infrastructure Investment and Jobs Act underwrites North American demand through mega-project pipelines mandating biometric PPE. Germany's national hydrogen pipeline network accelerates exoskeleton procurement for specialized energy infrastructure crews. China's urban rail expansion and smart city initiatives concentrate sensor-integrated helmet deployment across metropolitan construction zones.
United States
Federally funded bridge replacement and semiconductor fabrication facility construction drive fleet-scale smart helmet mandates. OSHA workplace injury reduction programs enforce real-time fall detection on sites receiving federal dollars. Texas and California mega-projects anchor procurement volume through general contractor consortiums standardizing Honeywell and RealWear supply chains.
Germany
Hydrogen pipeline construction and industrial facility modernization create demand for CE-marked exoskeleton systems. EU Machinery Directive compliance requirements shape product certification pathways for powered lifting aids. Bavaria and North Rhine-Westphalia concentrate deployment through labor union partnerships facilitating pooled equipment procurement across shared infrastructure sites.
China
Metro rail network expansion and data center construction accelerate smart helmet adoption for worker accountability across sprawling sites. GB standards for intelligent personal protective equipment guide domestic manufacturer certification. Yangtze River Delta and Pearl River Delta urban clusters lead deployment through state-owned enterprise procurement mandates.
India
National highway and renewable energy infrastructure build-outs generate demand for heat-stress monitoring vests in high-humidity zones. The country's national standards body certification requirements shape product specifications for imported sensor-integrated PPE. Maharashtra and Gujarat industrial corridors concentrate procurement through public-private partnership project structures.
United Arab Emirates
NEOM and Red Sea tourism megaprojects mandate advanced worker safety systems for international contractor compliance. The country's national occupational safety regulator enforces biometric monitoring for extreme heat environments. Dubai and Abu Dhabi construction hubs anchor Gulf demand through tier-one general contractor fleet standardization.
Construction Wearables Market Vendor Landscape
Listed leaders compete with private specialists across hardware-software integration capabilities, creating a tiered structure where scale advantages clash with niche engineering depth. Honeywell International Inc. anchors the publicly traded tier through industrial automation heritage, while venture-backed specialists capture premium pricing in augmented reality workflows. Strategic archetypes separate industrial conglomerates with cross-sector sensor platforms, biomechanics-focused exoskeleton developers, and voice-interface documentation specialists. Competitive moves concentrate on M&A for sensor fusion IP and strategic partnerships with building information modeling software vendors.
Within the industrial conglomerate tier, Honeywell International Inc. exemplifies scale-driven platform consolidation, while RealWear Inc. and Ekso Bionics occupy specialized positions at the interface between human factors engineering and field-deployable hardware. German Bionic Systems GmbH represents European engineering-focused private company archetypes competing through CE marking expertise and labor union channel relationships. These three anchors illustrate how competitive positioning splits between North American technology integration, European regulatory compliance depth, and venture-scale specialization in single-product categories.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| RealWear Inc. |
| Trimble Inc. |
| Kenzen |
| Ekso Bionics |
| GuardHat |
| Triax Technologies |
| German Bionic Systems GmbH |
| DAQRI |
| Others |
Supply Flow & Price Mechanics
East Asian battery cell manufacturing scale creates asymmetric pricing power for powered exoskeleton producers, compressing margins for assemblers while concentrating value capture in cell chemistry suppliers. This concentration shapes tiered procurement structures where general contractors with billion-dollar portfolios negotiate fleet discounts unavailable to fragmented subcontractor bases.
Pricing Analysis
Volume-discount tiering separates enterprise fleet contracts from single-unit retail transactions. Three-tier pricing structure across premium sensor-fusion, standard connectivity, and economy passive-protection levels reflects certification grade and software integration depth. Cost compression in Bluetooth-enabled basic PPE is intensifying because Chinese module suppliers expand capacity. Subcontractors purchasing through online channels exhibit highest price sensitivity, while tier-one general contractors prioritize interoperability over unit cost.
Supply Chain Analysis
Just-in-time component sourcing dominates smart helmet assembly, whereas exoskeleton manufacturers maintain strategic stockpiles of lithium-ion cells to buffer East Asian supply volatility. Manufacturing concentrates in China, South Korea, and Germany for sensor modules, battery cells, and precision mechanical components respectively. Raw material dependencies span rare earth magnets, silicon photonics, and high-tensile aluminum alloys. Single-source vulnerability in solid-state battery development poses structural risk. Distribution runs through direct sales for enterprise fleets and distributor networks for smaller contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor fragmentation across hardware-software integration layers creates niche opportunities for specialists targeting unmet interoperability demands. General contractor mandate power is splintering procurement authority away from legacy PPE distributors.
For Market Incumbents: Shield market position through backward integration into sensor fusion firmware development, countering emerging entrants with cloud-native platforms. Cement channel control via ISO 45001-aligned API development for building information modeling integration. Prioritize CE marking expertise to defend European public infrastructure tender access against regulatory shifts. For New Entrants and Emerging Players: Equipment-as-a-service rental gaps in exoskeleton deployment represent the most penetrable white-space, as incumbents under-serve labor union pooled procurement models. Target Germany and United States metropolitan construction corridors where infrastructure density supports shared-fleet economics. Pursue go-to-market partnerships with building information modeling software vendors for data-stream integration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among voice-interface documentation specialists with software subscription attach rates. Long-term viability favors acquisition targets combining ruggedized hardware IP with vertical-specific compliance engineering depth. Watch for OSHA mandate expansion into biometric monitoring requirements as inflection indicator for smart helmet demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion IP Acquisition | Accelerates real-time fatigue prediction capabilities under EU AI Act documentation requirements. |
| Building Information Modeling Partnership | Enables wearable-to-digital-twin data streams for progress tracking on complex vertical builds. |
| CE Marking Pathway Investment | Unlocks European hydrogen pipeline and public infrastructure tender access for exoskeleton systems. |
| Equipment-as-a-Service Launch | Captures rental channel growth in Germany and United States labor union pooled procurement. |
| Heat-Stress Monitoring Expansion | Targets India national highway build-out with temperature-alert vest deployment in high-humidity zones. |
Methodological Framework
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Construction safety directors, exoskeleton biomechanics engineers, general contractor procurement leads, and building information modeling integration specialists provided operational perspective. Secondary sources include OSHA enforcement databases, EU Machinery Directive guidance documents, SEC 10-K equipment disclosures, and customs trade data for sensor module flows. Bottom-up unit economics triangulate against top-down infrastructure spending projections.
Sensitivity analysis around battery cost trajectories and mandate enforcement timelines shapes the analytical framework. Segmentation dimensions span product type, technology stack, end-user procurement authority, and distribution channel across the projection horizon. CAGRs derive from infrastructure investment pipelines, regulatory compliance deadlines, and labor union negotiation patterns. Industry-specific inputs incorporate exoskeleton injury reduction efficacy studies and smart helmet deployment case studies from federally funded sites.
Forecasts assume regulatory continuity in OSHA workplace safety programs and EU Machinery Directive enforcement; material policy shifts would require re-modeling. Technology disruption risks from solid-state battery commercialization or AI Act algorithmic reclassification could revise adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Lepidolite Market
Others
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market
Others
GCC Health and Wellness Market
Others
5G Tester Market
Others
Asia-Pacific 3D Printing Construction Market
Others
Smart Home As a Service Market
Others
Industrial Gauges Market
Others
Enterprise Video Content Management Market
Others
Smart Home Platforms Market
Others
Digital Transformation of Maritime Freight Market
Others
Composite Copper Foil Production Equipment Market
Others
Handheld Mobile Computers Market
Others
Tanned Fish Skin Leather Market
Others
3D Printing Construction Market
Others
Asia Pacific Cloud Infrastructure Testing Services Market
Others
Technical Films Market